
 Europe Sugar Confectionery Market | 2026-2036
Europe Sugar Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sugar Confectionery Market Insights
Foodservice procurement across European hotels, airlines, and corporate catering is consolidating toward fewer, larger contract buyers with national coverage requirements. Nestlé SA leverages its pan-European distribution infrastructure to secure these consolidated accounts. Haribo Holding GmbH & Co. KG differentiates through its specialized gummy production expertise and heritage positioning. Lindt & Sprüngli AG anchors the premium chocolate-coated confectionery niche with controlled retail channel presence.
Europe sugar confectionery comprises sweet, shelf-stable products formulated primarily from sucrose or glucose syrups, often incorporating flavoring agents, colorants, and acidulants, with moisture content typically below 5% for hard candies to ensure extended ambient stability. These products serve impulse purchase occasions, gift-giving rituals, and portion-controlled indulgence across retail and foodservice channels. Hard candy and lollipops occupy mature volume positions with stable household penetration, while sour flavor profiles represent the fastest-growing segment as younger consumers seek intense taste experiences. Supermarkets dominate the sales channel landscape, though online retail is expanding fastest as direct-to-consumer subscription models gain traction among specialty and gifting segments.
ECHA enforces REACH compliance on food-contact packaging and colorant additives, while EFSA evaluates novel ingredient safety claims that determine reformulation pathways. The EU Green Deal's packaging waste directives are mandating recyclable or reusable formats, forcing shifts from multi-layer films toward mono-material pouches and paper-based boxes. Stakeholders must monitor how the EU AI Act's transparency requirements intersect with automated quality control systems deployed in confectionery manufacturing lines.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing format choices across European confectionery supply chains, forcing rapid transitions from multi-layer films toward mono-material pouches and paper-based boxes that satisfy extended producer responsibility frameworks.
Growth Catalysts
- Hospitality Sector Rebound:Hotels and airlines are rebuilding in-room and onboard snack offerings, creating replenishment demand for portion-controlled formats. Contract specifications increasingly require national coverage capabilities.
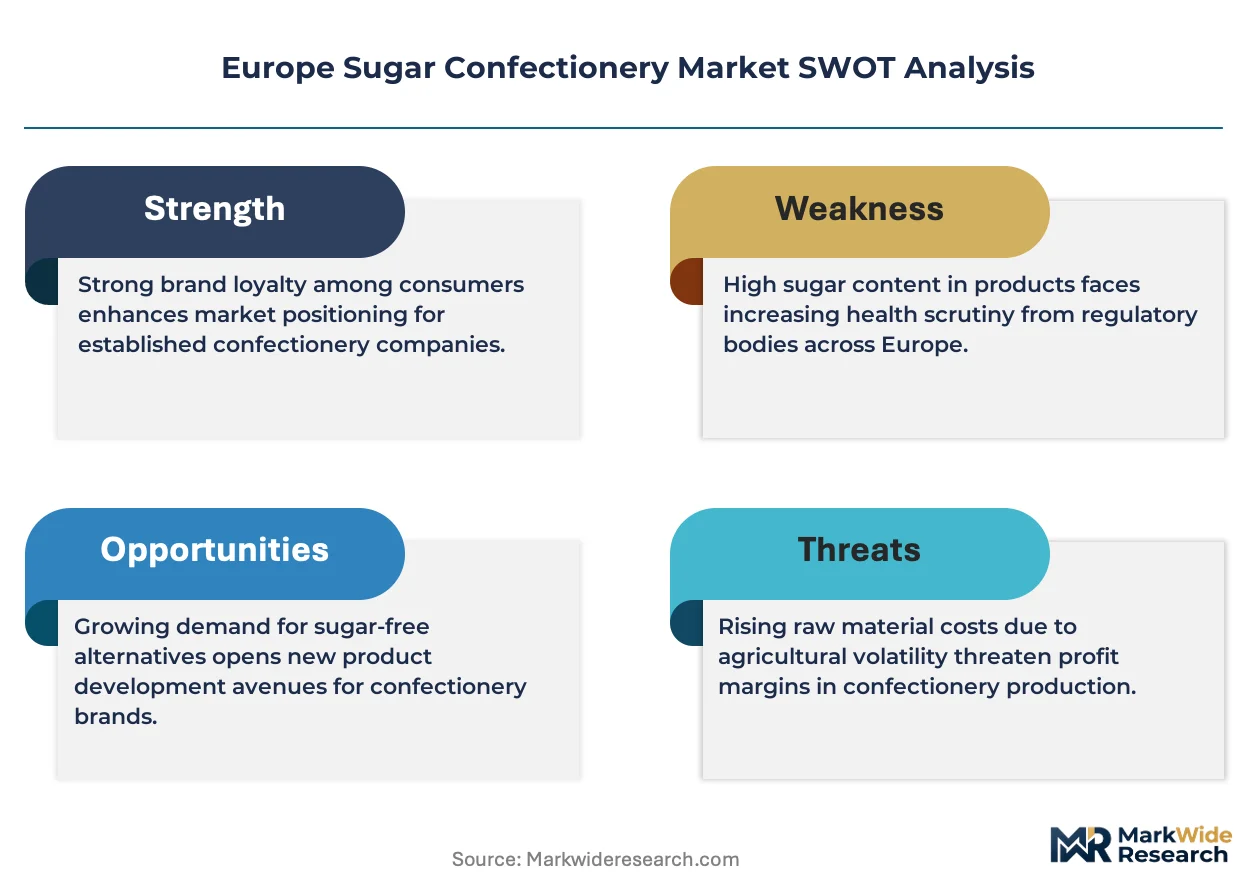
- Farm to Fork Strategy:The EU's sugar reduction targets are accelerating reformulation investments, opening functional ingredient substitution pathways. EFSA novel ingredient approvals determine viable product pipelines.
- Sour Flavor Profile Expansion:Younger consumer cohorts in France and Germany are seeking intense taste experiences, pulling production capacity toward acidulant-intensive formulations and specialized gummy textures.
Market Restraints
- Beet Sugar Input Volatility:European sugar beet harvest fluctuations create raw material cost instability. Processing margins compress when weather events hit key growing regions in northern France and eastern Germany.
- Colorant Additive Restrictions:ECHA REACH compliance on food-contact packaging and colorant additives limits formulation flexibility. Titanium dioxide exclusions force expensive natural pigment substitutions.
- Direct-to-Consumer Substitution:Artisanal confectionery subscription services in the United Kingdom are capturing gifting occasions previously held by mass-market brands, eroding volume in traditional retail.
Strategic Opportunities
- Eastern European Underpenetration:Poland and Romania show lower per-capita sugar confectionery consumption than Western European benchmarks. Modern trade expansion in Warsaw and Bucharest creates shelf-space availability.
- EU AI Act Alignment:Automated quality control systems deployed on manufacturing lines can capture compliance documentation advantages. Early adopters gain inspection speed benefits.
- Corporate Catering Channel Innovation:Workplace snack programs are consolidating procurement toward wellness-positioned portion packs. Direct B2B platforms bypass traditional wholesale intermediaries.
Industry Challenges
- Reformulation Technical Talent Scarcity:Food scientists capable of balancing sugar reduction targets with texture and shelf stability are concentrated in Switzerland and southern Germany, creating recruitment competition.
- Packaging Line Capex Requirements:Mono-material pouch conversion demands new forming and sealing equipment. Smaller producers face financing constraints for machinery upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sugar Confectionery Market |
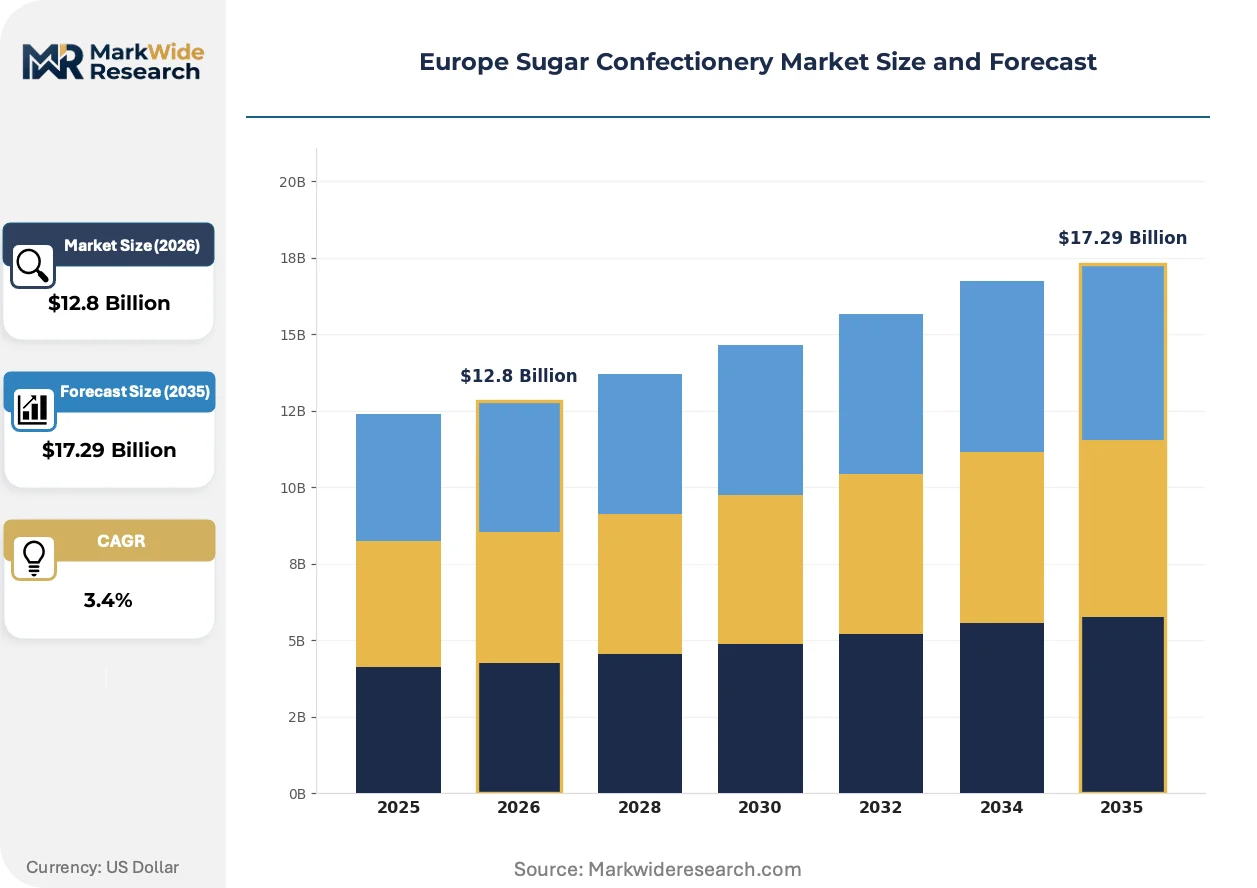
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $17.29 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candy, Jelly Beans, Cotton Candy, Lollipops Sales Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Packaging Type: Bags, Boxes, Tins, Pouches Flavor Profile: Fruit, Mint, Chocolate, Sour |
| Companies Covered | Nestlé SA, Lindt & Sprüngli AG, Ferrero Group, Pladis Global, August Storck KG, Haribo Holding GmbH & Co. KG, Perfetti Van Melle, Ricola AG, Mondelēz International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sugar Confectionery Market Trends and Innovations
Digital traceability systems and automated manufacturing controls are reshaping how European confectionery producers manage compliance documentation and quality assurance across dispersed production networks.
Continuous glucose monitoring-inspired formulation analytics is electrifying precision in sugar replacement ratios. Mid-sized producers in Belgium and the Netherlands are adopting sensor-guided batch consistency tools. This technology is compressing the reformulation cycle from months to weeks.
EFSA's evolving stance on novel sweetener safety claims is tightening the evidentiary burden for reformulated products. Manufacturers must commission extended toxicology studies before market authorization. The premium chocolate-coated segment faces the steepest compliance costs as consumers demand clean-label positioning.
Foodservice buyers are consolidating contract specifications toward outcome-based quality metrics rather than ingredient-grade specifications. Hotel chains in Spain and Italy now require shelf-life guarantees and traceability documentation as standard procurement terms. This pattern is most visible in Mediterranean markets where tourism recovery drives volume concentration.
Europe Sugar Confectionery Market Segmentation
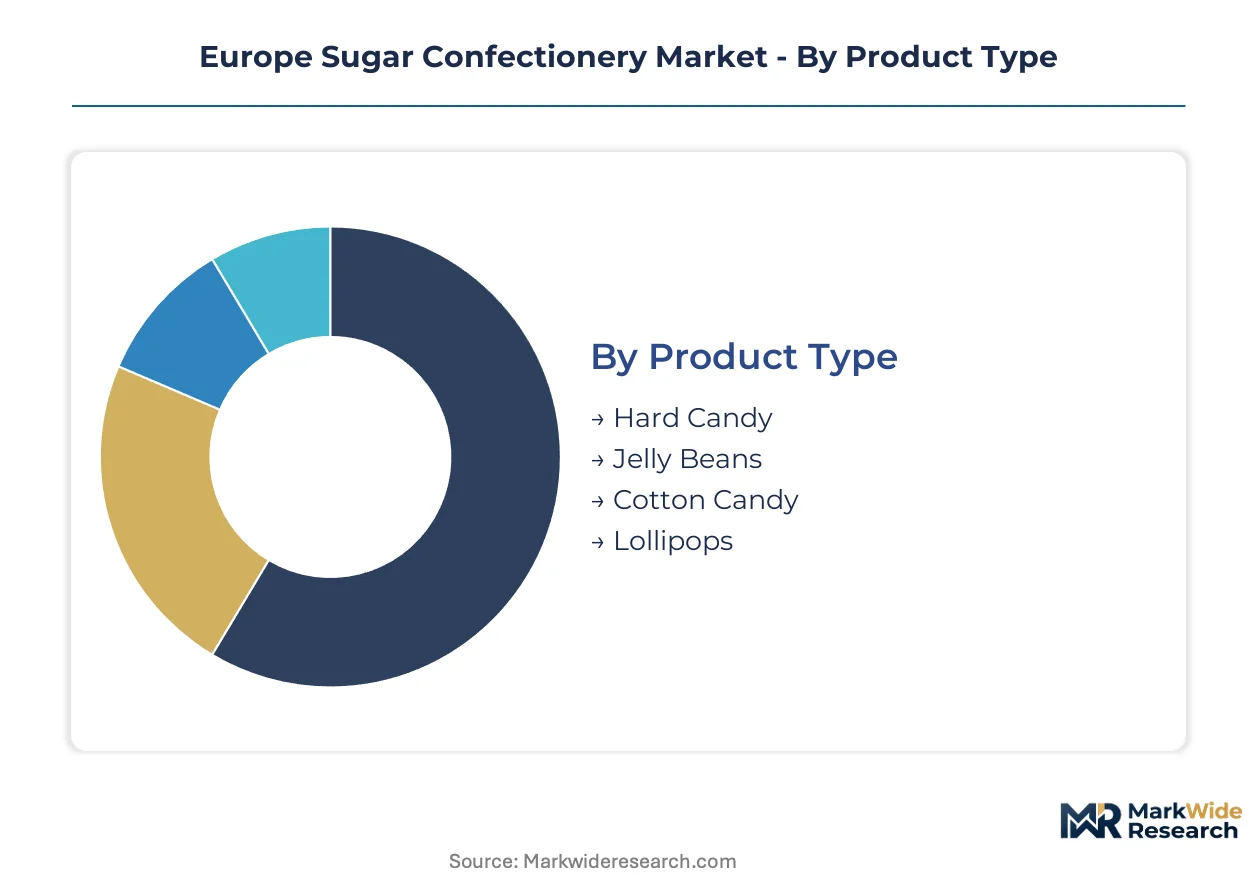
Segmentation in European sugar confectionery reveals distinct upgrade cycles across product formats and channel infrastructure. Reformulation investments and packaging compliance deadlines are forcing category-by-category renewal timelines that reshape procurement patterns.
Product Type:
Replacement cycles in European confectionery manufacturing equipment are accelerating format-specific capacity shifts, with acidulant-intensive lines commanding premium retrofit investments.
- Hard Candy:Formulated from sucrose-glucose syrups cooked to low moisture content below 5%, hard candy delivers extended ambient stability without refrigeration. German and French households maintain steady replenishment rates for traditional boiled sweet varieties, though sugar reduction targets under the EU Farm to Fork Strategy are compressing permissible formulation ranges.
- Lollipops:These mounted confections incorporate molded sugar matrices on paper or plastic sticks, with portion control appealing to parental purchase decisions. Airlines rebuilding onboard snack programs in Spain and Italy are specifying individually wrapped lollipop formats for hygiene compliance, pulling capacity toward single-serve packaging lines.
- Jelly Beans:Panned sugar shells surrounding soft centers rely on specialized starch mogul equipment concentrated in Belgian and Dutch production clusters.
- Cotton Candy:Spun sugar floss requires immediate consumption and limited retail shelf presence, constraining distribution to event-based and impulse channels.
Volume placements concentrate in Hard Candy; the faster expansion belongs to Lollipops.
Sales Channel:
Channel cost tiers in European confectionery separate high-volume grocery contracts from premium-margin specialty placements, with digital infrastructure investments determining competitive access.
- Supermarkets:These mass-market retailers dominate European sugar confectionery volume through centralized distribution and promotional calendar control. German chains like REWE and EDEKA leverage pan-national procurement specifications that favor suppliers with REACH-compliant packaging documentation and mono-material format capabilities.
- Online Retail:Direct-to-consumer platforms and subscription services are capturing gifting occasions previously held by traditional retail, with UK-based artisanal operators leading specialty segment migration. EFSA novel ingredient approval timelines determine which reformulated products qualify for cross-border e-commerce fulfillment.
- Convenience Stores:Urban impulse purchase patterns in Warsaw and Bucharest are expanding modern trade shelf space for portion-controlled formats.
- Specialty Shops:Heritage positioning and controlled retail presence anchor premium chocolate-coated and gift-boxed segments in Swiss and Belgian urban centers.
Supermarkets retain the dominant volume position; Online Retail is climbing the fastest as subscription models gain traction.
Packaging Type:
Margin structures across European confectionery packaging separate commodity flexible formats from rigid premium presentations, with EU Green Deal compliance costs reshaping supplier economics.
- Pouches:Flexible mono-material pouches are displacing multi-layer films under extended producer responsibility frameworks, requiring new forming and sealing equipment investments. Smaller producers in Eastern Europe face financing constraints for machinery upgrades that larger pan-European suppliers have already deployed.
- Boxes:Paper-based rigid formats satisfy corporate gifting specifications and hotel chain procurement terms in Mediterranean markets, with traceability documentation now standard requirement.
- Bags:Conventional polyethylene formats face accelerating substitution pressure as recyclability mandates tighten across the bloc.
- Tins:Metal containers retain collectible and premium positioning despite higher material costs and shipping weight penalties.
Pouches command the steepest compliance-driven upgrade cycle; Boxes maintain premium positioning in corporate and hospitality channels.
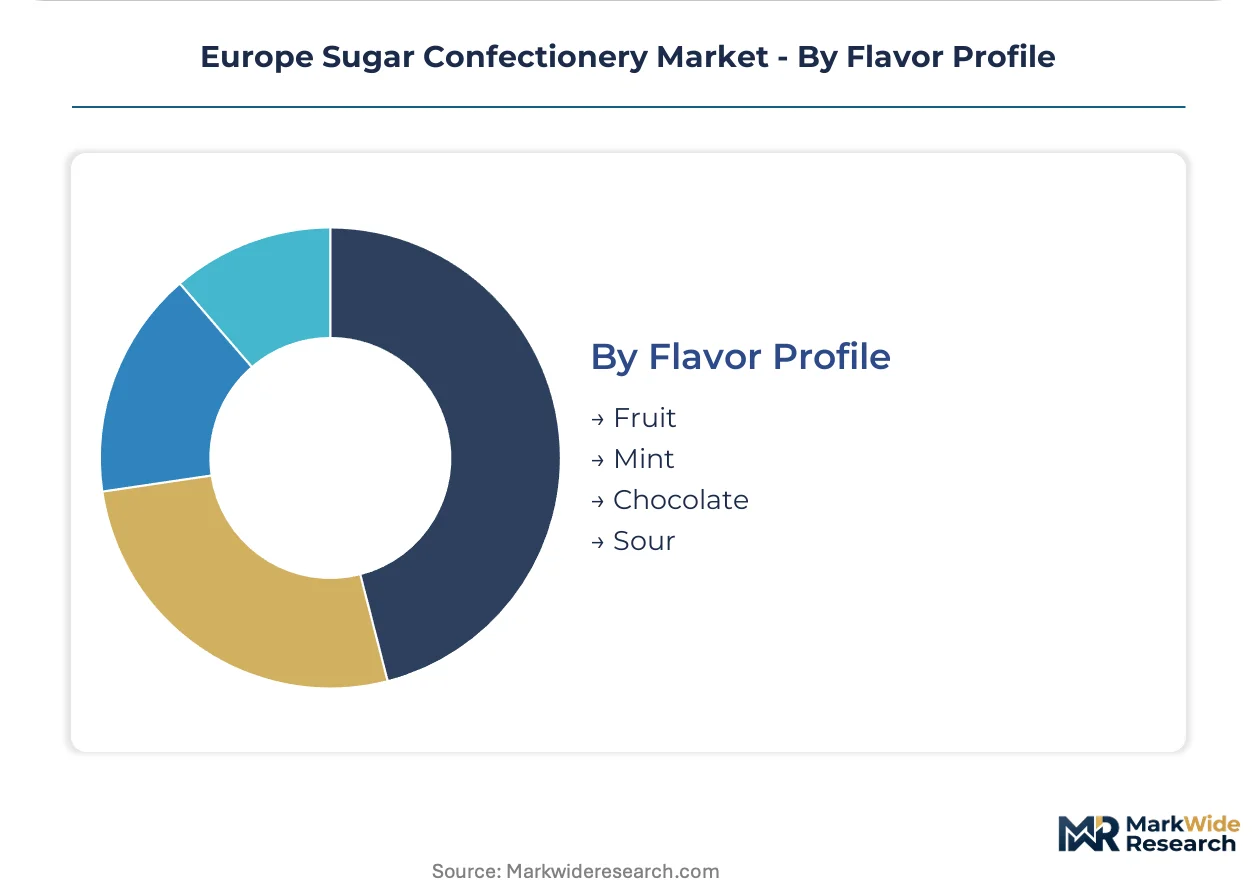
Flavor Profile:
Application-driven segmentation in European confectionery separates everyday consumption occasions from intense taste experiences sought by younger demographic cohorts.
- Sour:Acidulant-intensive formulations incorporating citric, malic, and tartaric acids are pulling production capacity toward specialized gummy textures. French and German consumers under 35 are driving fastest segment expansion, with Haribo and regional specialists investing in dedicated sour production lines.
- Fruit:Traditional flavoring systems using natural and nature-identical compounds maintain stable household penetration across all age demographics.
- Mint:Breath-freshening functional positioning sustains consistent demand in workplace and travel consumption contexts.
- Chocolate:Chocolate-coated and enrobed varieties face the steepest EFSA compliance costs as clean-label positioning demands drive extended toxicology study requirements for reformulated products.
Fruit flavors hold the broadest volume base; Sour profiles are gaining share fastest among younger consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentration across European sugar confectionery gravitates toward Germany, France, and the United Kingdom, where hospitality procurement consolidation and reformulation investments under EU Farm to Fork targets are reshaping national market trajectories.
Germany
Hard candy household replenishment and sour gummy demand from consumers under 35 drive volume. ECHA REACH compliance on colorant additives constrains formulation flexibility for domestic producers. The Bonn-Cologne corridor hosts specialized gummy production clusters where acidulant-intensive line retrofits are accelerating capacity shifts.
France
Intense taste preferences among younger cohorts pull production toward specialized sour formulations, while sugar beet harvest volatility in northern growing regions creates raw material cost instability. EU Green Deal packaging waste directives mandate transitions from multi-layer films toward mono-material pouches. Paris-based procurement teams for hotel chains are consolidating contract specifications toward outcome-based quality metrics.
United Kingdom
Artisanal subscription services capture gifting occasions previously held by mass-market brands, eroding traditional retail volume. EFSA novel ingredient approval timelines determine which reformulated products qualify for cross-border e-commerce fulfillment. London and Birmingham urban centers show expanding modern trade shelf space for portion-controlled formats targeting workplace snack programs.
Spain
Tourism recovery drives volume concentration in Mediterranean markets where hotel chains require shelf-life guarantees and traceability documentation as standard procurement terms. Extended producer responsibility frameworks under EU packaging directives compress format choices toward recyclable mono-material solutions. Barcelona and Madrid production facilities face machinery upgrade financing constraints for compliant pouch conversion equipment.
Poland
Lower per-capita consumption than Western European benchmarks creates underpenetration opportunity as modern trade expands in Warsaw. EFSA evaluations of novel sweetener safety claims tighten evidentiary burdens for reformulated product pipelines. Bucharest corridor distributors are capturing emerging convenience store shelf space for impulse purchase patterns in urban centers.
Europe Sugar Confectionery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription and wellness-positioned portion pack niches. The market structure reflects consolidated pan-European distribution capabilities alongside specialized heritage positioning in premium segments. Three archetypes dominate: scale-driven multinationals with national coverage infrastructure, family-owned specialists leveraging production expertise, and premium chocolate-coating operators with controlled retail presence. Competitive moves center on reformulation technical talent acquisition and mono-material packaging line capital deployment.
Within the heritage-specialist tier, Haribo Holding GmbH & Co. KG and August Storck KG exemplify family-owned German producers with concentrated gummy and hard candy expertise. Lindt & Sprüngli AG anchors premium chocolate-coated confectionery positioning through Swiss-controlled retail channel strategies. Nestlé SA occupies the scale-driven multinational archetype with pan-European distribution infrastructure securing consolidated hospitality and foodservice accounts.
| Leading Market Players |
|---|
| Nestlé SA |
| Lindt & Sprüngli AG |
| Ferrero Group |
| Pladis Global |
| August Storck KG |
| Haribo Holding GmbH & Co. KG |
| Perfetti Van Melle |
| Ricola AG |
| Mondelēz International |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-caps concentrated in the Bonn-Cologne corridor and Swiss chocolate specialists anchor supply discipline through long-term beet sugar contracts and captive distribution networks, insulating premium tiers from commodity volatility while compressing standard-tier margins through pan-European procurement consolidation.
Pricing Analysis
Volume placements in hard candy and traditional boiled sweets operate on thin margins driven by German supermarket chain consolidation, while premium chocolate-coated and sour gummy segments capture pricing power through heritage positioning and controlled retail presence. Price differentiation rests on EFSA novel ingredient approval status and REACH-compliant packaging certification, with clean-label reformulated products commanding shelf-space premiums. Cost compression in standard-tier flexible packaging is intensifying because mono-material pouch conversion demands new capital equipment. Foodservice buyers with national coverage requirements show least price sensitivity, while Eastern European modern trade entrants exhibit highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Dual-sourcing mandates from consolidated hotel chain procurement teams in Spain and Italy require manufacturers to qualify secondary acidulant suppliers alongside primary citric acid providers. Geographic supply concentration centers on Belgium and the Netherlands for starch mogul equipment and specialized gummy production, northern France and eastern Germany for sugar beet processing, and Switzerland for premium chocolate enrobing. Raw material dependencies include European sugar beet harvests, natural colorant substitutes replacing titanium dioxide, and acidulant-intensive formulations for sour profiles. Single-source vulnerability in specialized gummy texture equipment creates bottleneck risk. Distribution runs through pan-European logistics hubs serving consolidated retail and hospitality accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material pouch conversion technology is displacing legacy multi-layer film lines, forcing capital allocation decisions that separate compliant producers from stranded asset risks across the analysis window.
For Market Incumbents: To counter artisanal subscription services eroding gifting occasion volume in the United Kingdom, Nestlé SA and Haribo Holding should secure reformulation technical talent in Switzerland and southern Germany through targeted acquisition of specialized food science teams, while deploying backward integration into natural colorant supply chains to offset titanium dioxide substitution costs. For New Entrants and Emerging Players: Capture underpenetrated modern trade shelf space in Warsaw and Bucharest by positioning wellness-oriented portion packs for corporate catering programs, leveraging direct B2B platform distribution to bypass wholesale intermediaries, and qualifying EFSA novel sweetener approvals ahead of incumbent reformulation cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor Eastern European packaging line operators in Poland and Romania facing machinery upgrade financing constraints, with long-term viability hinging on EU Green Deal extended producer responsibility compliance. The signal to watch is EFSA approval velocity for functional ingredient substitutions, which determines which reformulated product pipelines achieve cross-border e-commerce eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pouch Conversion | EU Green Deal packaging directives in France and Germany mandate recyclable format transitions by extended producer responsibility deadlines. |
| Reformulation Technical Talent Acquisition | Food scientists capable of balancing sugar reduction with shelf stability in Switzerland command recruitment premiums from multiple competitors. |
| Direct B2B Platform Launch | Workplace snack programs in London and Birmingham consolidate procurement toward wellness-positioned portion pack suppliers. |
| Natural Colorant Backward Integration | ECHA REACH titanium dioxide exclusions force expensive pigment substitutions in German and French production facilities. |
| EFSA Novel Ingredient Pre-Approval | Extended toxicology study investments determine which reformulated products qualify for cross-border e-commerce fulfillment. |
Research Methodology
Multi-period observation of sugar beet harvest volatility, EFSA novel ingredient approval timelines, and hospitality procurement consolidation anchored the trend analysis, supplemented by interviews with category buyers at German supermarket chains, procurement directors for Mediterranean hotel groups, plant managers at Belgian starch mogul facilities, and regulatory affairs leads navigating REACH compliance. Secondary validation drew from EU customs trade data, EFSA safety opinion databases, national sugar beet yield statistics, and hospitality sector contract documentation. Bottom-up capacity assessments across production clusters triangulated against top-down expenditure flows from foodservice and retail channels.
Input-output matrices modeled volume and value trajectories across product type, flavor profile, packaging format, and sales channel dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory deadline impacts. Industry-specific forecast inputs included EFSA approval pipeline velocity for functional sweeteners and EU Green Deal packaging compliance cost curves for machinery conversion.
The model holds under stable EFSA evaluation timelines and moderate sugar beet harvest conditions; deviation in northern French weather patterns or accelerated titanium dioxide restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Germany Chocolate Market
Confectionery
Chocolate Couverture Market
Confectionery
Low-Fat Sweets Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Black Treacle Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Middle East Chocolate Market
Confectionery
United States and Europe Macarons Market
Confectionery
Global Mochi Market
Confectionery
India Industrial Chocolate Market
Confectionery
Coffee Gummy Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Chocolate Spread Market
Confectionery
Low Calorie Treats Market
Confectionery
Green Tea Chocolate Market
Confectionery
Sugar Free Mints Market