
 Low-Fat Candy Market | 2026-2036
Low-Fat Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Candy Market Analytics
Convenience store and online direct-to-consumer routes is fragmenting as low-fat candy brands bypass traditional grocery wholesalers. Mars, Inc. leverages its global manufacturing footprint to secure shelf placement across fragmented retail formats. Nestlé sustains R&D intensity in sugar alcohol formulations that reduce fat without compromising texture. Ferrero SpA differentiates through premium positioning in the chocolate candies segment where ingredient sourcing commands price premiums.
Low-fat candy denotes confectionery products manufactured with reduced fat content, typically achieved through substitution of cocoa butter or dairy fats with modified starch emulsifiers, protein-based fat mimetics, or aeration processes that maintain mouthfeel while delivering fewer than three grams of fat per standard serving. The primary commercial purpose centers on satisfying indulgence-oriented purchase occasions among consumers managing caloric intake or specific dietary regimens. Chocolate candies anchor the value pool due to higher per-unit pricing and established brand equity, while gummies represent the fastest-expanding product type driven by gelatin-free and plant-based ingredient innovations. Sugar alcohols as an ingredient category concentrate margin capture because manufacturers command technical premiums for erythritol and maltitol blends that preserve sweetness intensity with reduced laxative effect.
FDA nutrition labeling rules and EU health claims regulations under EFSA guidance constrain permissible fat reduction claims and mandate substantiated compositional disclosures. ISO 22000 food safety management standards and CODEX Alimentarius confectionery specifications further shape cross-border market access and reformulation requirements. Stakeholders must monitor evolving sweetener approval pathways and front-of-pack labeling mandates that will determine which ingredient technologies retain commercial viability.
Market Dynamics
Reformulation chemistry now dictates competitive positioning as manufacturers race to replace cocoa butter and dairy fats with protein-based fat mimetics and aeration systems that preserve mouthfeel under tightening FDA and EFSA compositional thresholds.
Growth Catalysts
- EFSA Nutritional Claims Standards:Tightened fat-content declaration rules in Europe are accelerating clean-label reformulation investments among premium chocolate producers seeking permissible health claims.
- Sugar Alcohol Blending:Technical advances in erythritol-maltitol combinations are reducing laxative effects while maintaining sweetness intensity, unlocking repeat purchase frequency in weight-management segments.
- Japan:METI-backed functional food certifications and aging demographics are concentrating demand for portion-controlled, reduced-fat confectionery in convenience retail formats.
Market Restraints
- Modified Starch Input Costs:Volatility in tapioca and potato starch supply from Southeast Asian processors is compressing margins on emulsifier-dependent formulations.
- Technical Ceiling on Fat Reduction:Below 2.5 grams per serving, texture degradation accelerates, limiting claim differentiation without proprietary aeration patents.
- FDA Enforcement Variance:Inconsistent state-level interpretation of reduced-fat labeling thresholds creates compliance fragmentation for nationally distributed brands.
Strategic Opportunities
- Gelatin-Free Gummies:Pectin and agar-agar substitutions in plant-based formulations are opening shelf space in vegan-specialty retail channels across Germany and the United States.
- Direct-to-Consumer Subscriptions:Recurring delivery models bypass slotting fee barriers in consolidated grocery, capturing lifetime value through personalized portion sizing.
- ISO 22000 Certification:Third-party food safety validation is becoming a procurement prerequisite for private-label contracts with European discounters.
Industry Challenges
- Flavor Chemist Scarcity:Reformulation teams capable of balancing fat reduction with taste intensity are concentrated among legacy chocolate houses, driving compensation inflation.
- Clean-Label Certification Timelines:Non-GMO Project and USDA Organic verification cycles extend 14-18 months, delaying product launches behind competitor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Candy Market |
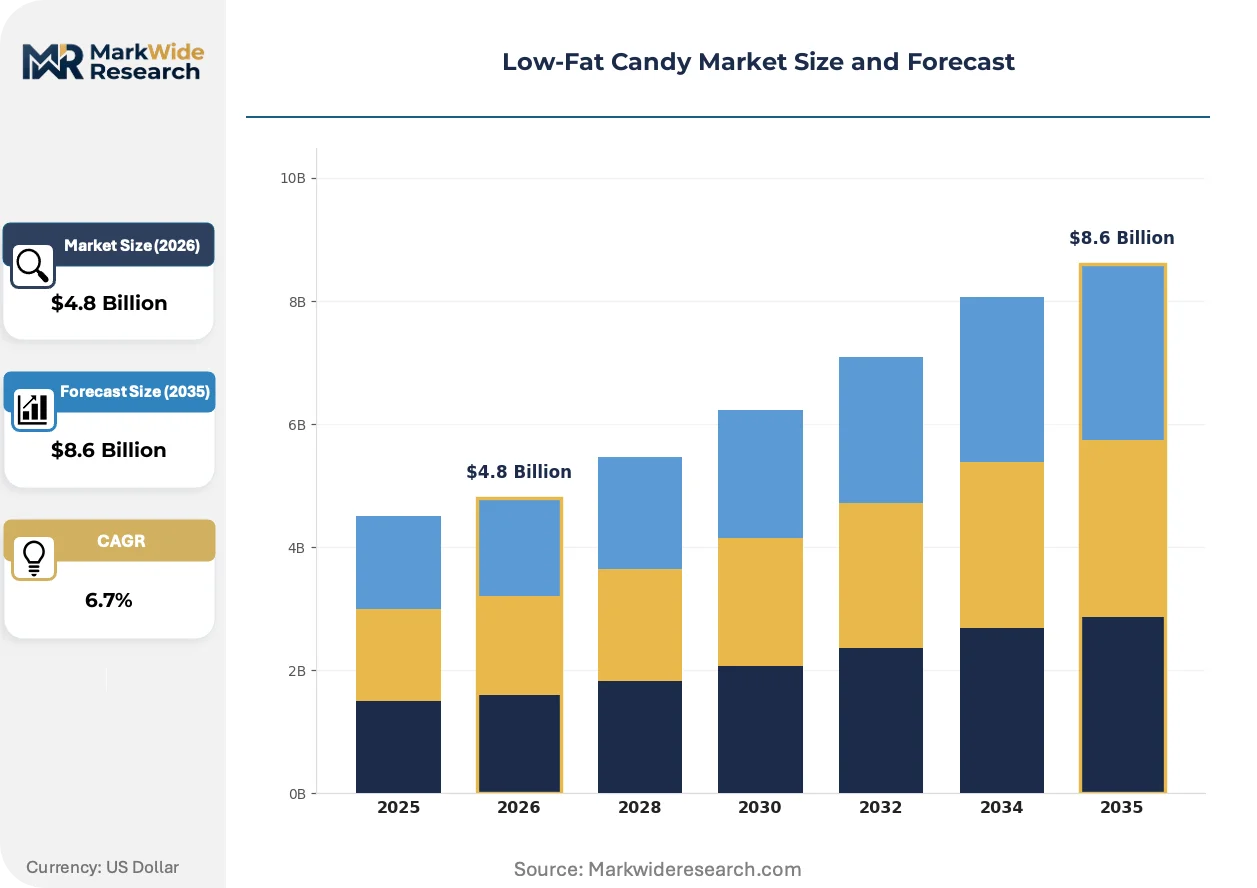
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Candies, Gummies, Hard Candies, Chewy Candies Ingredient Type: Natural Sweeteners, Sugar Alcohols, Plant-Based Ingredients, Others Packaging Type: Bags, Boxes, Bulk Packaging, Single-Serve Packs End User: Health-Conscious Consumers, Children, Fitness Enthusiasts, Snackers |
| Companies Covered | Nestlé, Mars, Inc., The Hershey Company, Mondelez International, PepsiCo, General Mills, Ferrero SpA, Danone S.A., Unilever plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Candy Market Evolving Landscape
Aeration technology and protein-based fat mimetics are redrawing technical boundaries between indulgence and health-positioned confectionery, while regulatory convergence on front-of-pack labeling is compressing formulation flexibility.
Micro-encapsulated protein-fat systems are migrating from sports nutrition applications into mainstream chocolate manufacturing. Mid-tier confectioners in the United States are adopting these systems at accelerated pilot scales. The technology is migrating from niche functional foods into mass-market candy by enabling 40% fat reduction without viscosity loss in enrobing processes.
EFSA's 2024 guidance on nutrient profiles restricts fat-reduction claims for products exceeding threshold sugar levels, forcing simultaneous reformulation across two dimensions. Chocolate bar manufacturers targeting German and French retail must now optimize both macronutrients to retain shelf positioning. Premium segment players are responding with dual-claim products that synchronize reduced-fat and no-added-sugar positioning.
Buyers are consolidating purchase authority through retailer-owned brand development teams rather than relying on national brand assortments. Discounters in Japan and Germany are building captive low-fat candy capabilities, displacing traditional supplier relationships. This concentration is most visible in Aldi and Lidl's European private-label expansion, where direct sourcing from reformulation houses bypasses established confectionery intermediaries.
Low-Fat Candy Market Segmentation
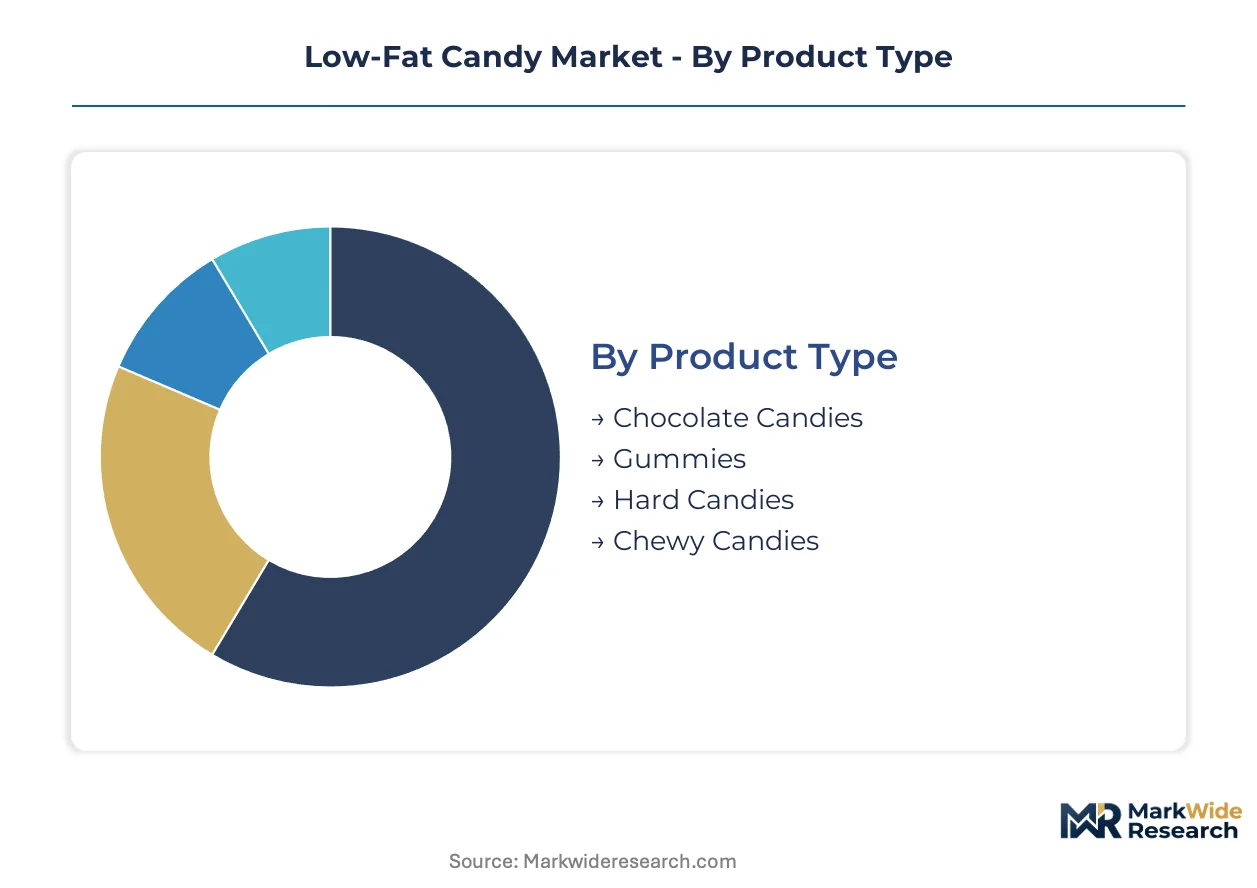
Low-fat candy manufacturers engineer distinct product architectures to match divergent consumption rituals across retail channels. Each segmentation dimension reveals where technical investment concentrates and which buyer profiles command premium positioning.
Product Type:
After-sales intensity varies sharply across product categories, with chocolate candies demanding sophisticated reformulation support while gummies require rapid flavor innovation cycles to maintain shelf relevance.
- Chocolate Candies:Cocoa butter replacement with protein-based fat mimetics and micro-encapsulated aeration systems preserves enrobing viscosity at 40% fat reduction. Demand concentrates in premium retail across Germany and Japan where dual-claim positioning (reduced-fat plus no-added-sugar) commands price premiums under tightening EFSA nutrient profile rules.
- Gummies:Pectin and agar-agar substitutions displace gelatin in plant-based formulations targeting vegan-specialty channels. Portion-controlled formats in Japanese convenience retail are expanding fastest among aging demographics seeking functional food certifications from METI.
- Hard Candies:Long shelf stability reduces reformulation frequency, with sugar alcohol blends from erythritol-maltitol combinations dominating clean-label production.
- Chewy Candies:Modified starch emulsifiers from Southeast Asian tapioca processors face input cost volatility, compressing margins on texture-preserving formulations.
Chocolate candies hold the largest share; momentum sits with gummies.
Ingredient Type:
Cost tier stratification separates premium-positioned natural extracts from commodity sugar alcohol volumes, with plant-based inputs capturing expanding shelf space in ethical retail channels.
- Natural Sweeteners:Stevia and monk fruit extracts command technical premiums for clean-label formulations, though supply concentration among specialized extractors limits volume scaling.
- Sugar Alcohols:Erythritol-maltitol blending advances reduce laxative effects while maintaining sweetness intensity, unlocking repeat purchase frequency in weight-management segments across United States retail.
- Plant-Based Ingredients:Pectin, agar-agar, and protein isolates from pea and rice sources enable vegan certification, with German and United States specialty retailers expanding dedicated shelf sections.
- Others:Modified starches and synthetic emulsifiers serve cost-sensitive private-label contracts, though clean-label migration is displacing volumes in premium channels.
Sugar alcohols anchor current volume; plant-based ingredients are climbing the fastest.
Packaging Type:
Volume concentration in bulk formats for foodservice contrasts with margin capture in single-serve units, where portion-control claims align with functional positioning strategies.
- Bags:Flexible film structures dominate family-size retail, with resealability features reducing per-ounce packaging cost for frequent-purchase households.
- Boxes:Rigid formats support premium gifting occasions, with seasonal assortments in Japan and Germany requiring specialized barrier properties for extended shelf life.
- Bulk Packaging:Foodservice and private-label manufacturing inputs concentrate volume, with ISO 22000 certification becoming a procurement prerequisite for European discounters.
- Single-Serve Packs:Portion-controlled units align with FDA and EFSA labeling thresholds for reduced-fat claims, expanding in vending and convenience channels where impulse purchase dominates.
Bags hold the largest share; single-serve packs show steepest expansion trajectory.
End User:
Customer type determines reformulation priority, with health-conscious buyers demanding dual-claim products while fitness enthusiasts drive protein-fortified hybrid formats.
- Health-Conscious Consumers:Dual-claim seekers simultaneously optimizing fat and sugar intake, with German and French retail requiring EFSA-compliant nutrient profile synchronization for permissible shelf positioning.
- Children:Clean-label pressure from parental buyers is accelerating natural sweetener adoption, though texture fidelity requirements limit aggressive fat reduction below 2.5 grams per serving.
- Fitness Enthusiasts:Protein-fortified and electrolyte-enhanced variants bridge confectionery and sports nutrition, with micro-encapsulated protein-fat systems migrating from niche to mainstream applications.
- Snackers:Indulgence-oriented occasional buyers prioritize taste intensity over health claims, representing a retention challenge for reduced-fat formulations.
Health-conscious consumers command the largest share; fitness enthusiasts are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German premium retail channels while United States mass-market volumes operate on thinner margin structures. Japanese convenience formats command portion-control premiums unavailable elsewhere. Regulatory divergence between FDA and EFSA thresholds is fragmenting reformulation strategies across Atlantic markets.
United States
Health-conscious households drive dual-claim purchases through direct-to-consumer subscriptions and convenience retail. FDA reduced-fat labeling thresholds create state-level compliance fragmentation for nationally distributed brands. Chicago and Minneapolis anchor reformulation R&D clusters where Mars, Inc. and The Hershey Company maintain technical facilities.
Germany
EFSA nutrient profile rules force simultaneous fat and sugar optimization for permissible shelf positioning. Aldi and Lidl private-label expansion displaces traditional supplier relationships through direct sourcing from reformulation houses. Cologne and Hamburg concentrate clean-label certification expertise for European discounter procurement.
Japan
METI functional food certifications and aging demographics concentrate demand in portion-controlled convenience formats. Tokyo and Osaka metropolitan areas host the densest vending machine networks for single-serve reduced-fat products. Nagoya manufacturing clusters specialize in pectin-based gummy formulations for aging consumer segments.
United Kingdom
Clean-label pressure from parental buyers accelerates natural sweetener adoption in children's confectionery segments. Trading standards enforcement of nutritional claims varies between England and Scotland, creating regional labeling complexity. Birmingham and Manchester distribution hubs handle reformulated product flows for British grocery multiples.
France
Premium chocolate heritage sustains price premiums for reduced-fat variants meeting EFSA compositional thresholds. ANSM monitoring of health claim substantiation raises compliance costs for imported formulations. Paris and Lyon retail clusters demand dual-claim synchronization that smaller exporters struggle to satisfy.
Low-Fat Candy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient technology and aeration patents. The vendor base separates into three functional tiers: multinational confectionery houses with global manufacturing footprints, regional reformulation specialists licensing fat-mimetic technologies, and private-label contractors serving discounter procurement teams. Two dominant competitive moves are reshaping positioning: backward integration into captive sugar alcohol supply and strategic patent licensing of micro-encapsulated protein-fat systems.
Within the multinational tier, Nestlé, Mars, Inc., and Ferrero SpA exemplify divergent strategic postures. Nestlé occupies a position emphasizing R&D intensity in sugar alcohol formulation science. Mars, Inc. anchors scale-driven manufacturing coordination across fragmented retail formats. Ferrero SpA sits within premium-segment positioning where ingredient sourcing commands price premiums in chocolate candies. These three represent the archetypal spectrum from technology-led to sourcing-led to scale-led competitive advantage.
| Leading Market Players |
|---|
| Nestlé |
| Mars, Inc. |
| The Hershey Company |
| Mondelez International |
| PepsiCo |
| General Mills |
| Ferrero SpA |
| Danone S.A. |
| Unilever plc |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southeast Asian modified starch processing is forcing tapioca emulsifier suppliers toward extended payment terms and volume discounts, compressing margins for reformulation houses while creating procurement leverage for large confectionery buyers negotiating long-term offtake contracts.
Pricing Analysis
The customization-premium spread in low-fat candy separates standard sugar-alcohol formulations from proprietary aeration-patent products. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard formulations is intensifying because of input volatility from Southeast Asian starch processors. Private-label contractors at European discounters exhibit highest price sensitivity, while premium chocolate houses in Germany and Japan command lowest sensitivity due to dual-claim positioning premiums.
Supply Chain Analysis
Supplier-financing facilities from Thai and Vietnamese tapioca processors are extending payment terms to 90 days for qualified buyers, reshaping working capital requirements across the ingredient tier. Geographic supply concentration centers on Thailand, Vietnam, and Indonesia for modified starches; China and Germany for sugar alcohol refining; and Japan for pectin extraction. Raw material dependencies include tapioca starch, erythritol-maltitol blends, and cocoa butter alternatives. Single-source vulnerability in Southeast Asian starch supply creates exposure to climate-driven crop failures. Distribution runs through consolidated grocery wholesalers in developed markets and direct-to-consumer subscriptions in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as dual-claim positioning accelerates adoption among health-conscious households seeking simultaneous fat and sugar reduction without taste compromise.
For Market Incumbents: Build formulation-patent moats around micro-encapsulated protein-fat systems to defend against mid-tier confectioners adopting aeration technology at pilot scale. Secure captive supply of erythritol-maltitol blends through backward integration or long-term offtake agreements with Chinese and German refiners. Prioritize ISO 22000 certification investment to maintain shelf positioning as European discounters consolidate procurement authority. For New Entrants and Emerging Players: Establish a beachhead in gelatin-free gummy segments where pectin and agar-agar substitutions command vegan-certification premiums in German and United States specialty retail. Target Japanese convenience formats with portion-controlled single-serve packs aligned with METI functional food certifications. Pursue direct-to-consumer subscription models to bypass slotting fee barriers in consolidated grocery channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aeration-patent development and captive sugar alcohol supply, favoring scaled players with balance-sheet capacity. Long-term viability across the analysis window rests on reformulation chemistry capabilities and regulatory compliance infrastructure rather than brand equity alone. Target acquisition archetypes include regional reformulation specialists with EFSA-compliant clean-label pipelines. Monitor FDA enforcement variance on reduced-fat labeling thresholds as an inflection signal for compliance cost fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugar Alcohol Supply | Captive erythritol-maltitol production secures margin control against Chinese and German refiner pricing volatility. |
| Direct-to-Consumer Subscription Launch | Recurring delivery models capture lifetime value through personalized portion sizing while bypassing Aldi and Lidl slotting fees. |
| Gelatin-Free Gummy Line Extension | Pectin and agar-agar formulations unlock vegan-specialty shelf space across German and United States ethical retail channels. |
| ISO 22000 Certification Program | Third-party food safety validation becomes procurement prerequisite for European discounter private-label contracts. |
| Dual-Claim Product Development | Synchronized reduced-fat and no-added-sugar positioning satisfies tightening EFSA nutrient profile rules in French and German retail. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Primary fieldwork engaged R&D directors at multinational confectionery houses, procurement leads at European discounters, flavor chemists at reformulation specialists, and category buyers at United States grocery multiples. Secondary sources included FDA labeling guidance documents, EFSA nutrient profile rulings, CODEX Alimentarius confectionery specifications, customs records for tapioca starch trade flows, and Nielsen retail audit data for reduced-fat candy shelf velocity. Bottom-up and top-down triangulation cross-validated volume estimates against ingredient consumption patterns and end-user demand signals.
Forecast inputs considered product type segmentation across chocolate candies, gummies, hard candies, and chewy candies; ingredient type stratification including sugar alcohols, plant-based inputs, and natural sweeteners; packaging format differentiation from bulk to single-serve; and end-user archetypes spanning health-conscious consumers, fitness enthusiasts, and parental buyers for children's segments. CAGRs were derived from trend extrapolation of reformulation investment cycles, regulatory compliance timelines, and channel shift velocities. Industry-specific forecast inputs incorporated METI functional food certification adoption rates in Japan and EFSA enforcement patterns on dual-claim permissibility.
Stress conditions across Southeast Asian starch supply disruptions, FDA state-level enforcement variance, and EFSA nutrient profile threshold revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clean-label migration speed and discounter private-label expansion trajectories. Macroeconomic contraction, regulatory timeline acceleration, or breakthrough aeration technology licensing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Green Tea Chocolate Market
Confectionery
US Confectionery Market
Confectionery
India Industrial Chocolate Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Dark Chocolate Market
Confectionery
Global Compound Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Truffle Chocolate Market
Confectionery
North America Premium Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
North America Chocolate Market
Confectionery
Chocolate Spread Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
South America Confectionery Market