
 Fruit Pectin Market | 2026-2036
Fruit Pectin Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Pectin Market Foresight
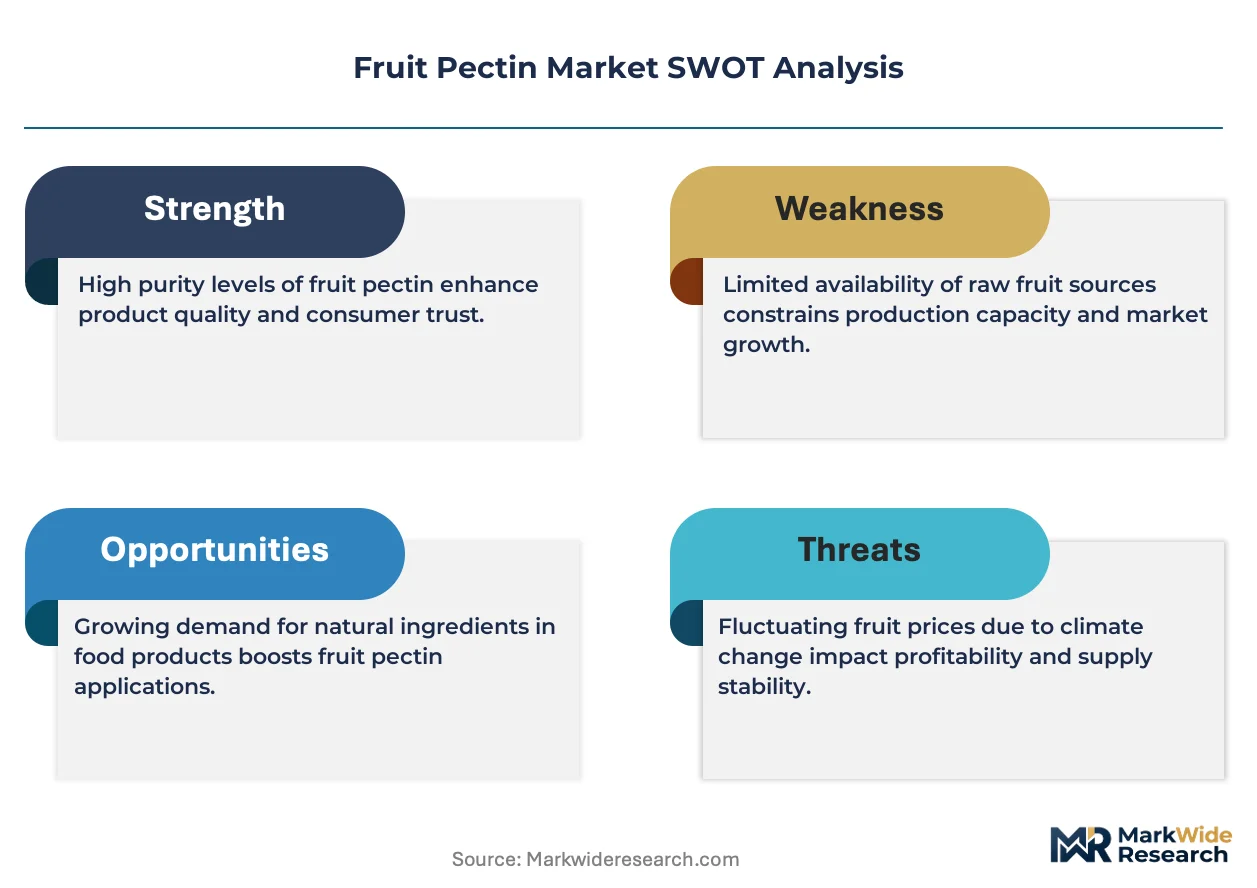
ISO 22000 certification is bifurcating the supplier base into qualified industrial suppliers and regional traders lacking hazard-control documentation. CP Kelco leverages its captive citrus peel supply network across Brazil and Mexico to sustain cost-advantaged high-methoxyl output. Herbstreith & Fox anchors European pharmaceutical-grade pectin through its Swabian manufacturing complex, while Yantai Andre Pectin competes on amidated pectin specialization for Asian dairy processors.
Fruit pectin denotes a complex polysaccharide rich in galacturonic acid units, extracted via acid hydrolysis of citrus peel or apple pomace at pH 1.5-3.0 and temperatures between 60-90°C, functioning primarily as a gelling agent, stabilizer, or thickener in food systems. High methoxyl pectin dominates confectionery and bakery fillings where rapid-set gels with soluble solids above 55% remain standard, while low methoxyl pectin captures faster growth in dairy alternatives and reduced-sugar beverages where calcium-reactive gelling enables clean-label formulation without excess sucrose. Amidated pectin occupies a narrower but higher-margin niche in pharmaceutical coating and controlled-release matrices where modified degree of amidation dictates dissolution profiles.
The FDA's GRAS self-affirmation pathway governs US food-grade pectin entry, while EFSA's re-evaluation of food additives under Regulation 1333/2008 tightens purity thresholds for European pharmaceutical applications, and China's NMPA and GB standards impose additional heavy-metal limits on imports. These layered compliance requirements raise capital barriers for new entrants and concentrate formulation partnerships among established certificated suppliers. Stakeholders must monitor evolving clean-label definitions and regional extraction-origin disclosure rules to anticipate which pectin grades will command premium positioning.
Market Dynamics
Clean-label formulation mandates from the EU Green Deal's Farm-to-Fork strategy are restructuring procurement patterns, forcing compounders to abandon synthetic stabilizers and source certified-sustainable citrus peel derivatives with verified extraction documentation.
Growth Catalysts
- EU Green Deal Farm-to-Fork Strategy:Binding additive disclosure rules in Western Europe compel bakery and dairy formulators to replace modified starches with high-methoxyl citrus pectin, absorbing premium-grade volumes from verified sustainable extraction networks.
- Calcium-reactive gelling technology:Low methoxyl pectin enables reduced-sugar beverage formulations without excess sucrose, capturing faster adoption in Asian dairy alternatives where clean-label positioning commands shelf space.
- Germany's processing corridor:Confectionery and dairy compounders cluster around Hamburg and Cologne, creating concentrated demand nodes that reward suppliers with ISO 22000 certification and captive peel supply.
Market Restraints
- Citrus peel supply volatility:Weather-driven fluctuations in Florida and São Paulo orange harvests constrain raw material predictability, forcing processors to maintain multi-origin sourcing premiums.
- High-methoxyl production concentration:Cost-advantaged output depends on captive citrus peel networks concentrated in Brazil and Mexico, creating geographic single-source exposure for European buyers.
- Amidated pectin substitution ceiling:Pharmaceutical coating applications face competition from cellulose derivatives and alginates where dissolution profile precision matches modified degree of amidation at lower regulatory burden.
Strategic Opportunities
- Asian dairy processor expansion:Amidated pectin specialization for calcium-reactive applications remains underpenetrated in South Korean and Vietnamese beverage markets, offering first-mover positioning for certified exporters.
- EFSA purity threshold elevation:Tightened pharmaceutical-grade standards under Regulation 1333/2008 create margin expansion for existing certificated suppliers capable of heavy-metal documentation beyond food-grade baselines.
- Enzymatic extraction convergence:Combining cellulase pre-treatment with conventional acid hydrolysis is miniaturizing energy inputs and expanding yield from apple pomace waste streams in Polish and Chinese processing facilities.
Industry Challenges
- ISO 22000 certification timeline:Hazard-control documentation requirements bifurcate the supplier base, excluding regional traders from German and French compounder procurement lists and compressing qualified vendor pools.
- Galacturonic acid assay standardization:Inconsistent degree of esterification measurement protocols between USP and European Pharmacopoeia methods create batch rejection risk and inventory stranding for cross-border shipments.
- Legacy synthetic stabilizer integration:Bakery filling reformulation from modified starch to pectin requires retooling hydration and shear protocols, extending technical service commitments and diluting gross margins for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Pectin Market |
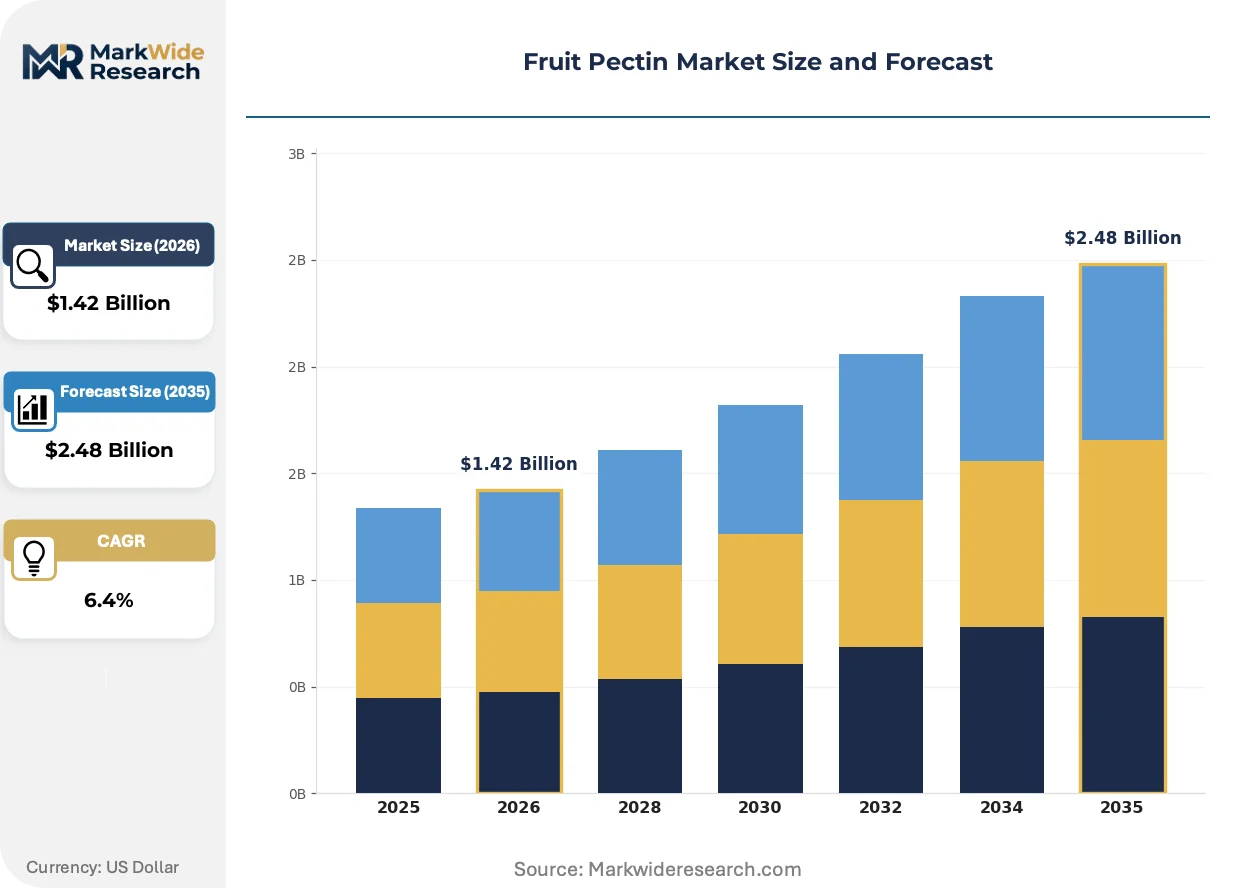
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Methoxyl Pectin, Low Methoxyl Pectin, Amidated Pectin, Modified Pectin, Citrus Pectin, Apple Pectin Application: Confectionery, Dairy & Frozen Desserts, Beverages, Bakery Fillings, Pharmaceuticals, Cosmetics End User: Food & Beverage Manufacturers, Pharmaceutical Companies, Cosmetic Manufacturers, Nutraceutical Firms Packaging Type: Bulk Bags, Powder Cans, Sachets, Drums, Boxed Packs |
| Companies Covered | CP Kelco, Cargill, Herbstreith & Fox, DuPont, Ingredion, Tate & Lyle, International Flavors & Fragrances, Yantai Andre Pectin, Naturex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Pectin Market Shifts & Advancements
Extraction technology advances and regulatory disclosure mandates are compressing the viable supplier base while opening premium positioning for documented sustainable sourcing. Formulators now prioritize traceable origin claims over commodity pricing.
Enzymatic pre-treatment of citrus peel using cellulase and pectinase cocktails is miniaturizing acid consumption and thermal energy inputs in extraction protocols. Brazilian processors adopting this hybrid approach report yield improvements from previously discarded flavedo layers. The technology is compressing unit economics for high-methoxyl output and enabling smaller-scale regional processors to achieve cost parity with integrated multinationals.
EFSA's re-evaluation of food additives under Regulation 1333/2008 is tightening purity thresholds for European pharmaceutical applications, particularly heavy-metal limits and methanol residue caps. Industrial consequence includes mandatory third-party assay documentation for every production lot. Pharmaceutical coating compounders in Germany and Switzerland are consolidating supplier relationships to three certificated vendors capable of sustained compliance investment.
Buyer concentration among multinational dairy and confectionery groups is compressing switching cycles and unbundling technical service from material supply. Category managers now demand origin-disclosure down to specific citrus cooperative or apple pressing facility. This pattern is most visible in Western European clean-label procurement, where sustainability scorecards determine vendor qualification before price negotiation begins.
Fruit Pectin Market Segmentation
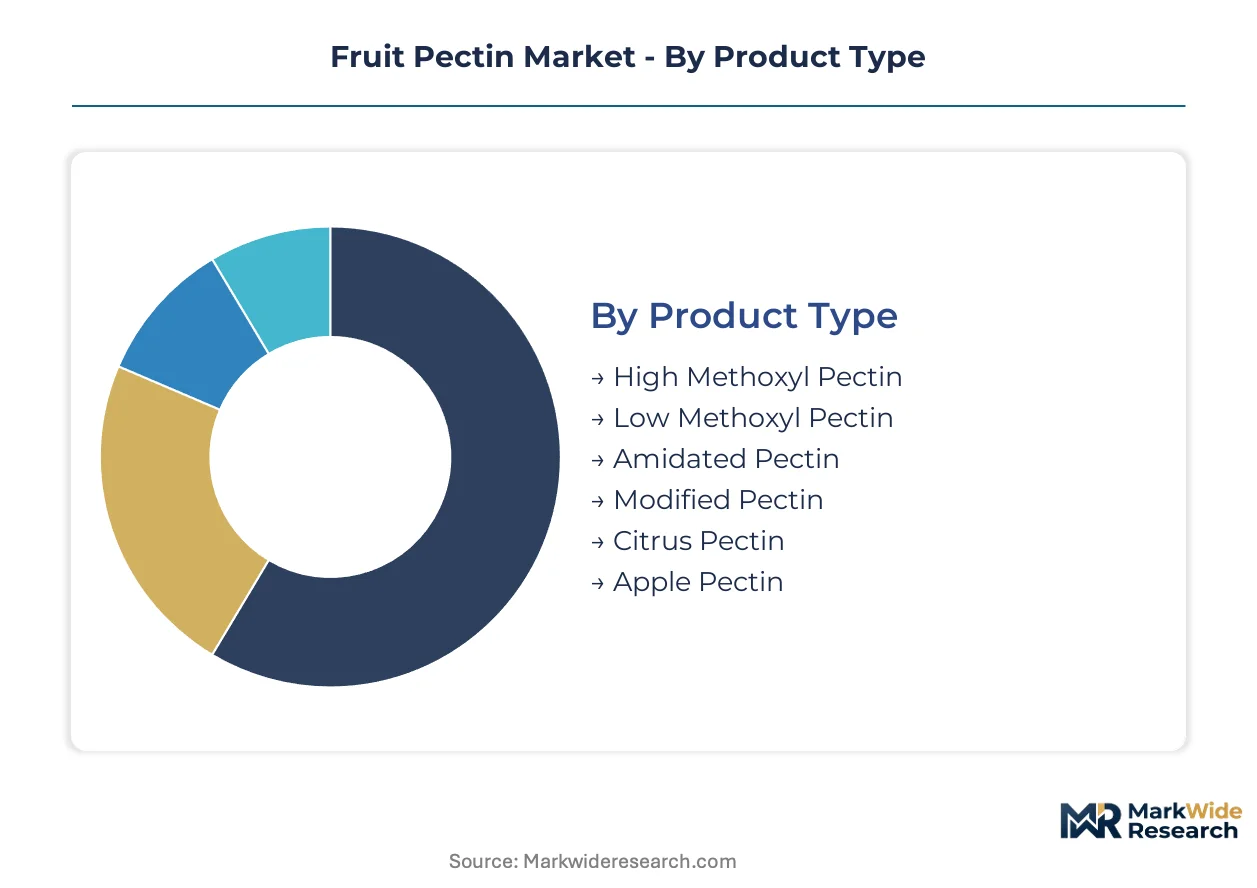
Pectin grade differentiation determines regulatory pathway complexity and pricing tier access. Manufacturers align product portfolios to end-use certification requirements rather than commodity volume plays.
Product Type:
EFSA's re-evaluation under Regulation 1333/2008 and FDA GRAS pathways create divergent compliance burdens across extraction methods and methoxylation degrees.
- High Methoxyl Pectin:Rapid-set gelling requires soluble solids above 55% and degree of esterification exceeding 50%. Confectionery compounders in Germany's Hamburg-Cologne corridor absorb premium volumes for clean-label candy centers as EU Green Deal disclosure rules displace modified starches.
- Low Methoxyl Pectin:Calcium-reactive gelling enables reduced-sugar beverage formulations without sucrose dependence. Asian dairy alternative processors in South Korea and Vietnam are expanding procurement of this grade for clean-label positioning.
- Amidated Pectin:Modified degree of amidation controls dissolution profiles for pharmaceutical coating matrices.
- Modified Pectin:Enzymatically or chemically altered for targeted functional properties in nutraceutical delivery.
- Citrus Pectin:Extracted from orange and lemon peel via acid hydrolysis at pH 1.5-3.0.
- Apple Pectin:Sourced from pomace waste streams in Polish and Chinese pressing facilities.
High methoxyl pectin handles the majority of throughput; low methoxyl pectin is gaining share fastest on reduced-sugar formulation demand.
Application:
Customer technical service intensity and reformulation complexity separate margin tiers across end-use categories.
- Confectionery:Gummy and jelly centers require rapid-set gel strength with standardized soluble solids. German and Swiss compounders dominate procurement, demanding ISO 22000 certification and origin documentation down to specific citrus cooperative.
- Pharmaceuticals:Coating and controlled-release matrices mandate heavy-metal assays and methanol residue documentation per European Pharmacopoeia methods. EFSA's tightened purity thresholds under Regulation 1333/2008 have compressed qualified supplier pools to three certificated vendors.
- Dairy & Frozen Desserts:Stabilization of yogurt and ice cream formulations.
- Beverages:Mouthfeel modification in reduced-sugar and plant-based drinks.
- Bakery Fillings:Viscosity control and bake stability in fruit preparations.
- Cosmetics:Emulsion stabilization and rheology modification.
Confectionery absorbs the largest volume share; pharmaceuticals command the steepest price premiums on compliance documentation.
End User:
Scale concentration and formulation expertise determine procurement power and vendor qualification requirements.
- Food & Beverage Manufacturers:Multinational dairy and confectionery groups compress switching cycles and unbundle technical service from material supply. Category managers demand sustainability scorecards before price negotiation.
- Pharmaceutical Companies:Coating compounders in Germany and Switzerland consolidate to certificated suppliers capable of sustained compliance investment.
- Cosmetic Manufacturers:Smaller batch requirements with flexible specification tolerances.
- Nutraceutical Firms:Emerging demand for modified pectin in targeted delivery applications.
Food and beverage manufacturers drive baseline volume; pharmaceutical companies anchor margin expansion through purity-grade premiums.
Packaging Type:
Handling economics and contamination risk separate industrial from specialty distribution channels.
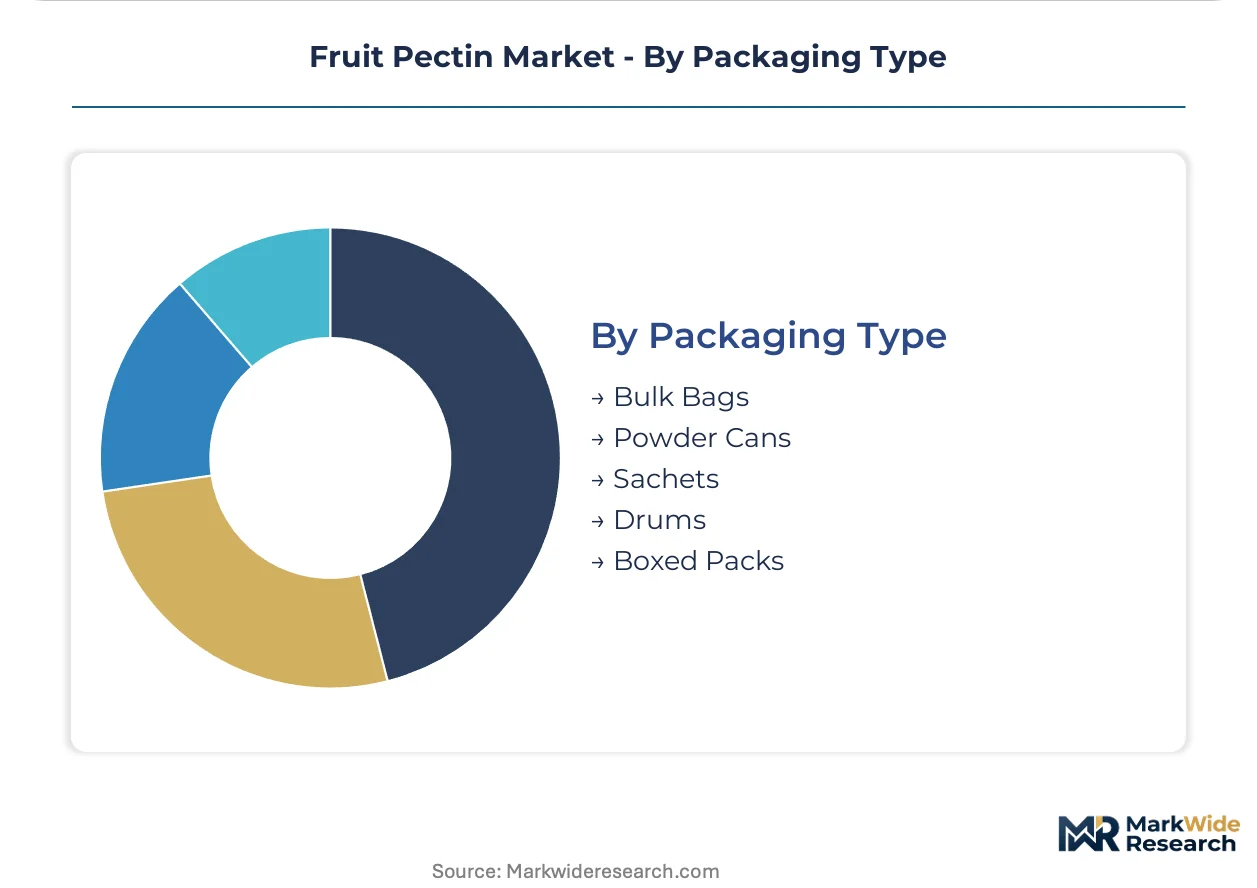
- Bulk Bags:500-1000 kg flexible intermediate bulk containers serve high-volume compounders in Germany's processing corridor. Reduced per-kilogram handling cost offsets capital requirements for pneumatic conveying systems.
- Drums:25-50 kg steel or fiber containers dominate pharmaceutical-grade shipments requiring lot segregation and contamination control.
- Powder Cans:Retail and small-batch food service distribution.
- Sachets:Single-use portions for artisanal and test-batch applications.
- Boxed Packs:Intermediate quantities for mid-tier processors.
Bulk bags carry the highest tonnage; drums capture the fastest expansion on pharmaceutical certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement from multinational confectionery and dairy compounders concentrates in Germany's Hamburg-Cologne corridor, while Asian dairy alternative processors in South Korea and Vietnam are expanding calcium-reactive pectin sourcing. Regulatory disclosure mandates under the EU Green Deal and China's NMPA standards are reshaping supplier qualification requirements across these demand centers.
Germany
Confectionery compounders in Hamburg and Cologne absorb premium-grade high-methoxyl citrus pectin volumes as the EU Green Deal's Farm-to-Fork strategy tightens additive sourcing rules. EFSA's re-evaluation under Regulation 1333/2008 mandates third-party assay documentation for every production lot. Herbstreith & Fox anchors European pharmaceutical-grade supply through its Swabian manufacturing complex.
China
Yantai Andre Pectin competes on amidated pectin specialization for Asian dairy processors seeking calcium-reactive gelling in reduced-sugar beverages. NMPA and GB standards impose additional heavy-metal limits on imports, raising capital barriers for new entrants. Enzymatic extraction convergence is expanding yield from apple pomace waste streams in Chinese processing facilities.
Brazil
CP Kelco leverages its captive citrus peel supply network across São Paulo state to sustain cost-advantaged high-methoxyl output. Weather-driven fluctuations in orange harvests constrain raw material predictability, forcing multi-origin sourcing premiums. Brazilian processors adopting cellulase pre-treatment report yield improvements from previously discarded flavedo layers.
South Korea
Amidated pectin specialization for calcium-reactive applications remains underpenetrated in South Korean beverage markets, offering first-mover positioning for certified exporters. MFDS pharmaceutical standards create compliance documentation requirements that favor established ISO 22000-certified suppliers. Dairy alternative processors in the Seoul Capital Area are expanding procurement of low methoxyl grades for clean-label positioning.
United States
The FDA's GRAS self-affirmation pathway governs food-grade pectin entry, with Florida citrus peel supply volatility affecting raw material predictability for domestic compounders. Confectionery manufacturers in the Midwest and Southeast are reformulating from modified starches to high-methoxyl pectin under clean-label pressure. CP Kelco and Cargill maintain integrated supply positions serving these regional demand clusters.
Fruit Pectin Market Competitive Landscape
Player mix skews toward integrated multinationals with captive raw material networks and specialized regional processors with certification advantages. The supplier base bifurcates into ISO 22000-qualified industrial suppliers and regional traders lacking hazard-control documentation. Three archetypes dominate: citrus peel-integrated multinationals, pharmaceutical-grade specialists with European Pharmacopoeia compliance, and amidated pectin specialists serving Asian dairy processors. Competitive moves center on enzymatic extraction technology licensing and backward integration into citrus cooperative supply contracts.
Among North American and European integrated players, CP Kelco, Cargill, and Herbstreith & Fox occupy positions representing distinct strategic archetypes. CP Kelco exemplifies the citrus peel-captive multinational with hemispheric supply network coverage. Cargill represents the diversified agricultural processor leveraging commodity sourcing scale across multiple hydrocolloid categories. Herbstreith & Fox anchors the pharmaceutical-grade specialist tier with European manufacturing concentration and sustained compliance investment under EFSA frameworks. These three sit within a vendor pool that procurement managers in Germany and Switzerland have compressed to certificated suppliers capable of origin-disclosure down to specific citrus cooperative or apple pressing facility.
| Leading Market Players |
|---|
| CP Kelco |
| Cargill |
| Herbstreith & Fox |
| DuPont |
| Ingredion |
| Tate & Lyle |
| International Flavors & Fragrances |
| Yantai Andre Pectin |
| Naturex |
| Others |
Supply & Pricing Matrix
Captive citrus peel networks in Brazil and Mexico generate scale economies that compress unit costs for high-methoxyl output while establishing price floors European buyers cannot match without multi-origin sourcing premiums. This geographic concentration of raw material control simultaneously tightens supplier margins in Asia and elevates procurement leverage for ISO 22000-certified compounders in Germany's Hamburg-Cologne corridor.
Pricing Analysis
Cost-plus contracts with citrus peel indexation dominate long-term offtake agreements between Brazilian processors and European confectionery compounders. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels separates EFSA-certified heavy-metal documentation from commodity citrus pectin. Cost compression in standard food-grade tiers is intensifying as enzymatic extraction yield improvements expand supply. Dairy alternative processors in South Korea demonstrate highest price sensitivity; pharmaceutical coating compounders in Switzerland show least.
Supply Chain Analysis
Brazil and Mexico anchor global high-methoxyl pectin production through captive citrus peel supply networks concentrated in São Paulo state and Veracruz. Acid hydrolysis inputs draw from sulfuric acid and thermal energy feedstocks; enzymatic pre-treatment rests on cellulase and pectinase cocktails. Single-source vulnerability runs through Florida orange harvest volatility affecting North American compounders. Distribution runs through flexible intermediate bulk containers for industrial compounders and steel drums for pharmaceutical-grade lot segregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label formulation standardization is shifting Fruit Pectin Market economics toward platform interoperability, where EFSA certification documentation and origin-disclosure scorecards function as ecosystem gatekeepers determining vendor qualification before price negotiation.
For Market Incumbents: Shield market position by deepening captive citrus cooperative supply contracts in Brazil and accelerating pharmaceutical-grade heavy-metal assay capacity expansion in Swabian manufacturing clusters. Cellulose derivative substitution in pharmaceutical coating applications threatens amidated pectin margins; vertical integration into enzymatic extraction technology licensing defends cost position against yield-improving regional processors. For New Entrants and Emerging Players: Lead with amidated pectin specialization for calcium-reactive dairy applications in South Korean and Vietnamese beverage markets, where clean-label positioning commands shelf space and ISO 22000 certification gaps exclude regional traders. White-space concentration in Asian reduced-sugar formulation offers first-mover positioning for certified exporters with documented sustainable extraction credentials. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic extraction specialists with hybrid acid-cellulase protocols and apple pomace waste stream integration. Long-term viability across the projection horizon hinges on backward integration into citrus cooperative supply contracts and sustained EFSA compliance investment capability. The signal to watch is EFSA purity threshold elevation under Regulation 1333/2008 compressing qualified supplier pools to certificated vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Technology Licensing | Yield improvements from cellulase pre-treatment expand cost parity for regional processors against multinationals. |
| Backward Integration into Citrus Cooperative Contracts | Captive peel supply networks in São Paulo state secure raw material predictability against weather-driven harvest volatility. |
| Pharmaceutical-Grade Heavy-Metal Assay Capacity Expansion | EFSA's tightened purity thresholds under Regulation 1333/2008 compress qualified supplier pools to certificated vendors. |
| Asian Dairy Processor Technical Service Partnerships | Calcium-reactive gelling expertise in South Korean and Vietnamese markets captures clean-label shelf space expansion. |
| Apple Pomace Waste Stream Integration | Polish and Chinese pressing facility yield improvements diversify raw material base beyond citrus peel dependence. |
Research Methodology
A standing panel of citrus processing plant managers, dairy compounder procurement leads, pharmaceutical coating technical directors, and enzymatic extraction R&D specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA additive re-evaluation filings, FDA GRAS self-affirmation pathways, NMPA heavy-metal standard disclosures, customs trade data for citrus peel derivatives, and SEC 10-K filings for integrated multinationals. Bottom-up volume triangulation against top-down demand aggregation ensured consistency.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated pectin grade tier, end-use application intensity, regional regulatory cluster, and extraction method technology level. CAGRs were derived from normalized growth trajectory fitting against historical volume patterns and projected clean-label formulation penetration curves. Forecast inputs included EU Green Deal Farm-to-Fork disclosure mandate implementation pace and enzymatic extraction technology adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained EFSA compliance investment capability or severe citrus harvest disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding regulatory disclosure mandate enforcement and clean-label procurement scorecard weighting. Recalibration cycles align with material shifts in EFSA purity threshold revisions and enzymatic extraction yield improvement trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fresh Yeast Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Fluid Lecithin Market
Ingredients
Corn Oil Cake Market
Ingredients
Organic Edible Oil Market
Ingredients
Cheese Powder Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Precision Fermentation Ingredient Supplier Market
Ingredients
Tapioca Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Specialty Feed Additives Market
Ingredients
Stock Cubes Market
Ingredients
Microparticulated Egg White Protein Market
Ingredients
Ximenia Oil Market