
 E-Commerce Liquor Market | 2026-2036
E-Commerce Liquor Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Liquor Market Analysis
AI-powered demand forecasting and dynamic routing algorithms is reconfiguring last-mile delivery economics for alcohol e-commerce. Drizly leverages its marketplace aggregation model to sustain liquidity across fragmented local retailer networks. ReserveBar specializes in luxury and limited-edition spirits, occupying a defensible premium niche. Total Wine controls extensive physical infrastructure that anchors its hybrid click-and-collect strategy.
E-commerce liquor encompasses the digital sale and fulfillment of alcoholic beverages through online platforms, requiring age-verification protocols, temperature-controlled logistics, and compliance with varying jurisdictional licensing regimes. The primary commercial purpose is to connect producers and retailers with end consumers through direct or intermediary digital channels while navigating regulatory constraints. Spirits commands the highest margin pool among product type segments due to per-unit value density and collector-driven scarcity economics. Subscription services within distribution channel segments represent the fastest-growing structural category, locking in recurring revenue and reducing customer acquisition costs. Retail consumers dominate customer type segments by volume, though bars and restaurants generate higher average order values with more predictable replenishment cycles.
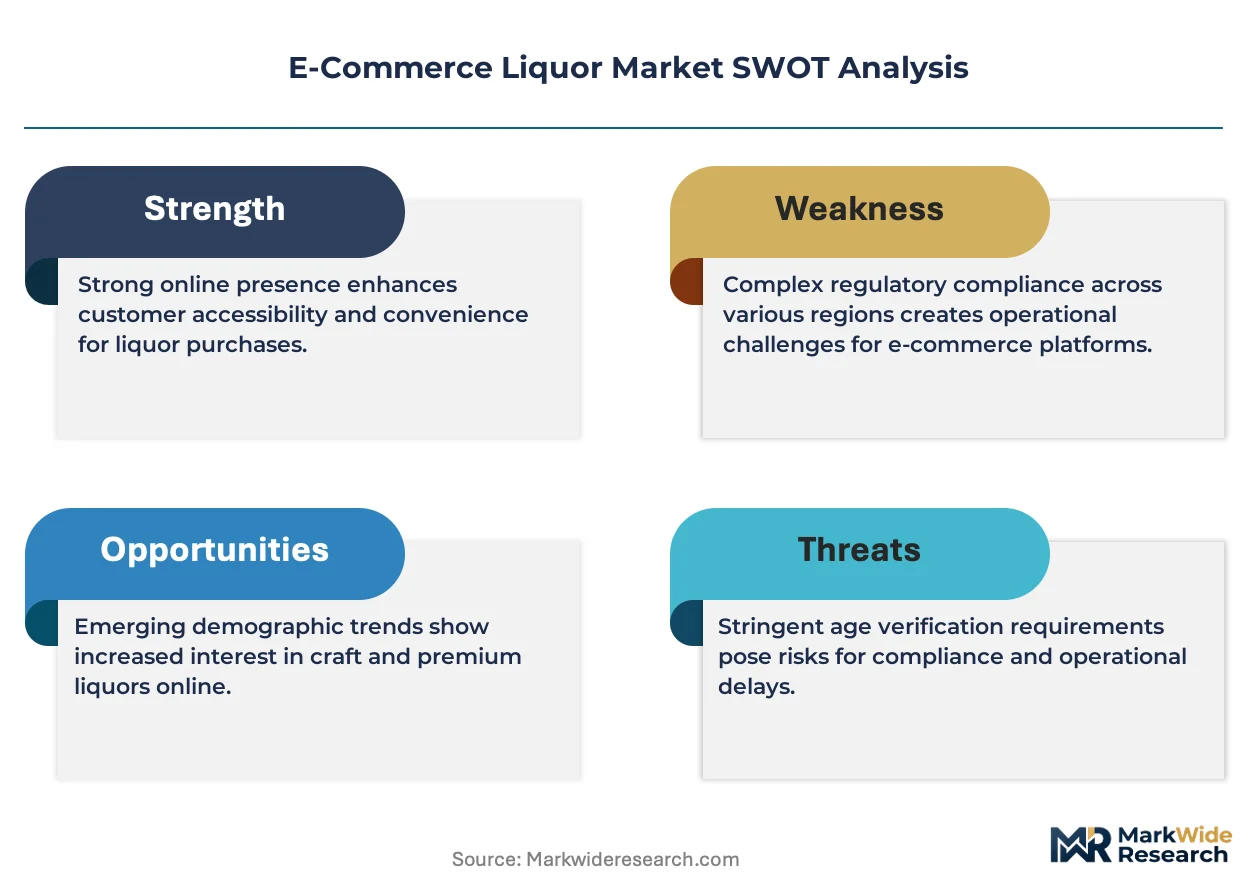
FDA guidelines on labeling and advertising intersect with state-level ABC (Alcoholic Beverage Control) licensing requirements and the three-tier system legacy constraints in the United States. The 21st Amendment's delegation of alcohol regulation to states creates a compliance mosaic that elevates platform technology costs and favors scaled operators with legal infrastructure. TTB (Alcohol and Tobacco Tax and Trade Bureau) certificate of label approvals and interstate shipping reciprocity agreements determine which SKUs can legally cross state lines. Stakeholders must monitor the patchwork evolution of direct-to-consumer shipping permissions and third-party delivery service liability frameworks as the primary variables shaping addressable market expansion.
Market Dynamics
State-level direct-to-shipper law liberalization is fragmenting the regulatory perimeter and forcing platforms to build jurisdiction-specific compliance stacks rather than uniform national operations.
Growth Catalysts
- Interstate shipping reciprocity:TTB certificate streamlining and state reciprocity agreements in the United States are dissolving historical three-tier system barriers. California, Texas, and New York now permit cross-border fulfillment from out-of-state licensed retailers.
- AI-powered logistics:Dynamic routing algorithms compress last-mile delivery costs for temperature-sensitive spirits. Machine learning demand forecasting reduces inventory holding costs for urban fulfillment centers.
- Subscription lock-in:Recurring revenue models among millennial and Gen Z retail consumers reduce customer acquisition costs. Premium subscription services capture predictable replenishment cycles.
Market Restraints
- ABC licensing mosaic:The 21st Amendment's state delegation creates compliance cost escalation. Each jurisdiction demands separate age-verification protocols and label approvals.
- Three-tier legacy architecture:Producer-wholesaler-retailer separation prevents direct platform relationships with distilleries. This structural constraint limits margin capture for pure-play e-commerce operators.
- Temperature-controlled logistics:Cold-chain requirements for wine and craft beer elevate fulfillment costs versus ambient e-commerce categories. Last-mile refrigeration infrastructure concentrates in metropolitan clusters.
Strategic Opportunities
- Direct-to-consumer spirits:Kentucky and Tennessee craft distilleries exploit DTC shipping permissions to bypass wholesale markups. Limited-edition releases command scarcity premiums through digital channels.
- Hybrid click-and-collect:Physical retail networks anchor same-day pickup for immediate consumption occasions. Urban stores function as micro-fulfillment nodes.
- Blockchain provenance:Distributed ledger technology converges with NFC-enabled bottles to authenticate luxury spirits. Collector-driven secondary markets demand verification infrastructure.
Industry Challenges
- Age-verification engineering:Real-time identity confirmation at delivery creates friction in conversion funnels. Biometric integration with state ID databases demands API standardization.
- Third-party delivery liability:Platform versus retailer versus driver responsibility allocation remains unsettled in tort frameworks. Insurance underwriting struggles to price alcohol-specific risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Liquor Market |
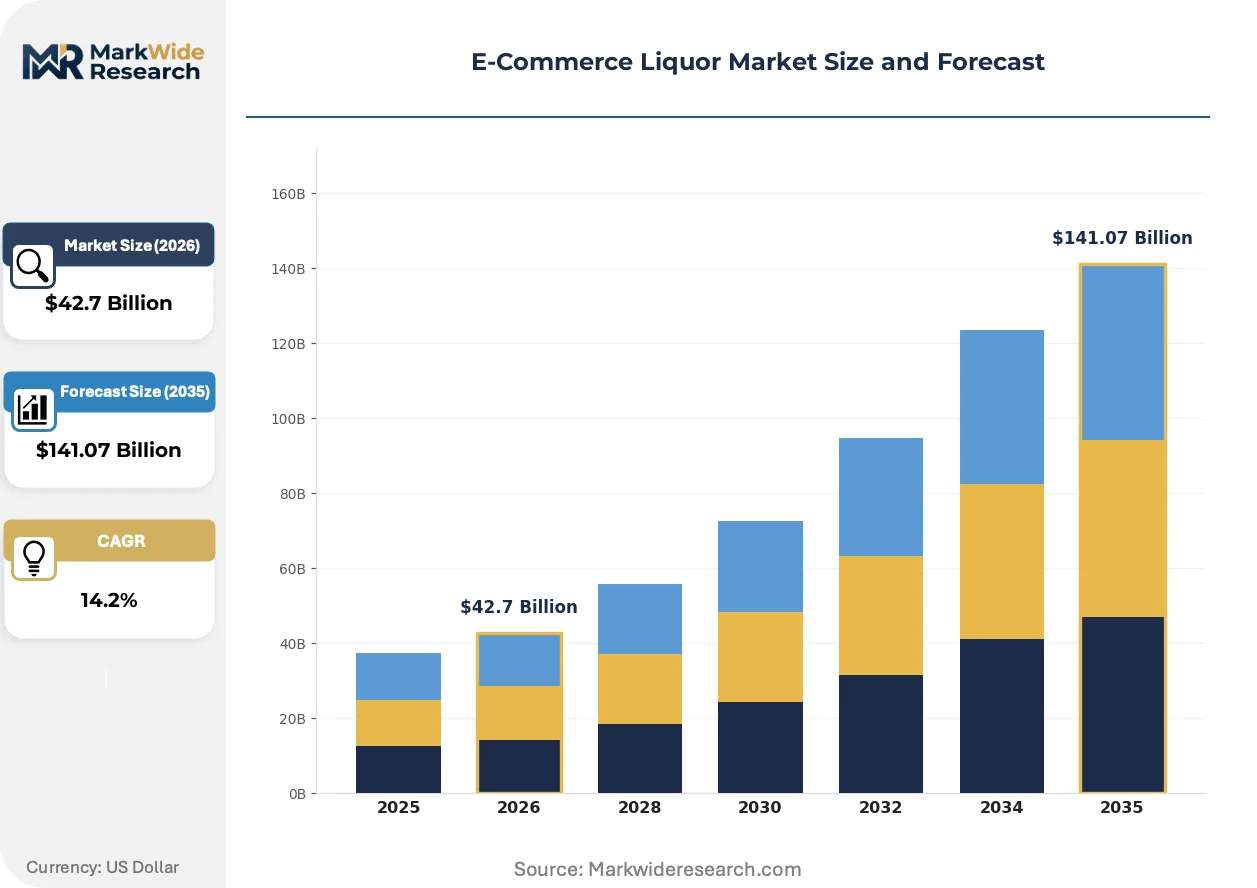
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $141.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirits, Wine, Beer, Liqueurs Customer Type: Retail Consumers, Bars, Restaurants, Event Planners Distribution Channel: Direct Sales, Third-Party Platforms, Subscription Services, Wholesale Price Tier: Premium, Mid-range, Budget, Exclusive |
| Companies Covered | Drizly, Total Wine, Wine.com, Minibar, ReserveBar, Vivino, BevMo!, Flaviar, Saucey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Liquor Market Emerging Trajectories
Digital infrastructure is compressing the distance between producer and consumer while regulatory technology absorbs compliance complexity previously handled by legal departments.
Blockchain-enabled provenance tracking is digitizing authentication workflows for luxury and limited-edition spirits. High-net-worth collectors and auction platforms adopt distributed ledger verification to eliminate counterfeits. This technology is digitizing trust mechanisms that previously required physical inspection and paper documentation.
TTB label approval modernization is accelerating certificate processing timelines for e-commerce SKUs. The Bureau's digital submission portal reduces administrative lag for cross-state product launches. Spirits producers with national distribution ambitions now prioritize TTB compliance automation.
Curated subscription boxes are displacing transactional replenishment among urban professional segments. Discovery-driven procurement replaces brand loyalty for wine and craft spirits categories. This behavioral shift concentrates in California metropolitan clusters where platform density enables rapid fulfillment experimentation.
E-Commerce Liquor Market Segmentation
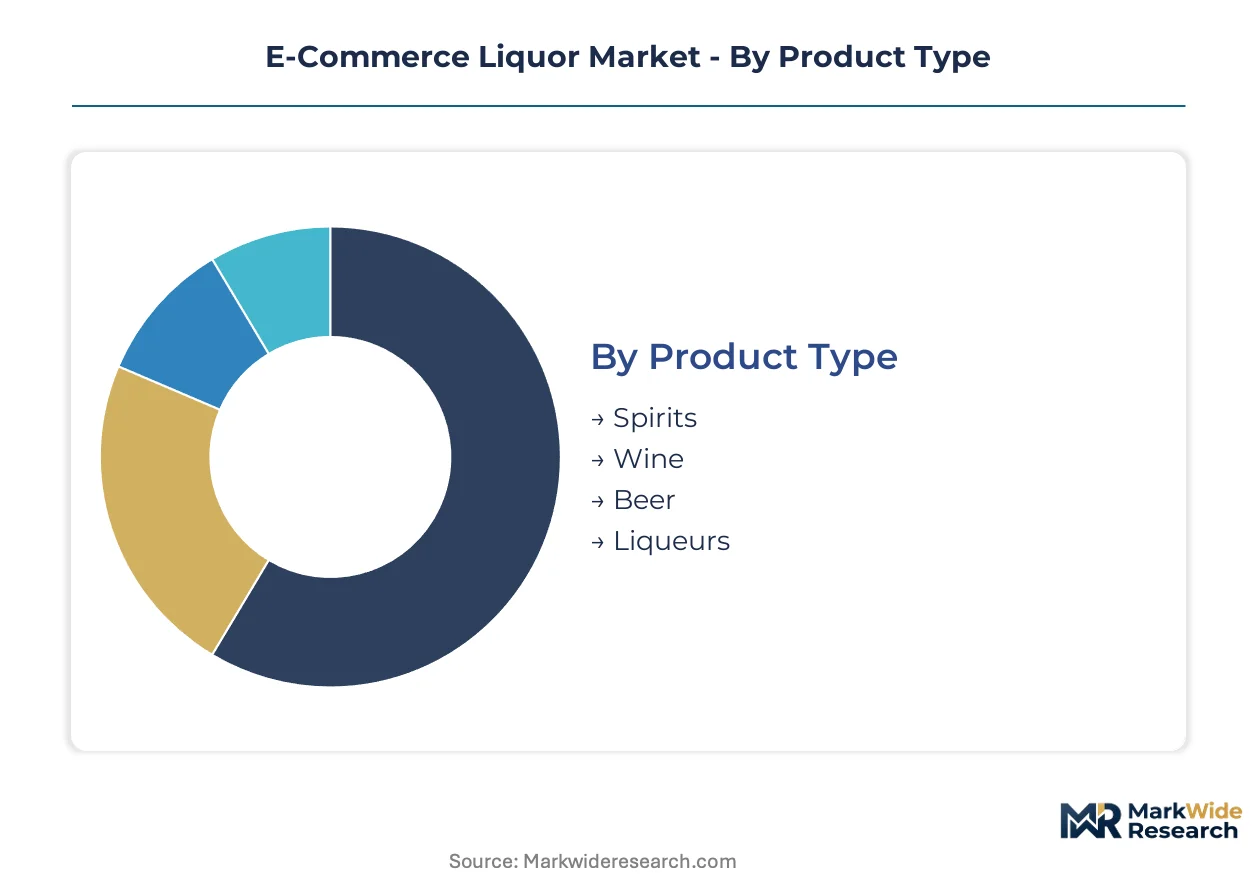
E-commerce liquor segmentation reveals how compliance costs, fulfillment complexity, and customer lifetime value distribute unevenly across product and channel configurations. Distinct segments carry radically different margin profiles and regulatory exposure, forcing platform operators to prioritize infrastructure investments selectively.
Product Type:
After-sales service intensity varies sharply across alcohol categories, with high-value spirits requiring authentication support and temperature-sensitive wine demanding cold-chain incident management.
- Spirits:High-proof distilled beverages with extended shelf stability and collector-driven scarcity economics. Demand concentrates in urban metropolitan clusters across California, Texas, and New York, driven by millennial and Gen Z interest in craft and limited-edition releases. Per-unit value density supports premium logistics spend and age-verification engineering investments.
- Wine:Fermented grape products requiring continuous cold-chain integrity from warehouse to doorstep. Temperature excursions destroy product value, elevating customer service costs and insurance complexity. Subscription services capture recurring revenue from discovery-seeking urban professionals.
- Beer:Perishable fermented beverages with compressed consumption windows and lower per-unit margins. Volume concentrates in immediate-consumption occasions, favoring hybrid click-and-collect fulfillment over pure home delivery.
- Liqueurs:Sweetened spirit-based products occupying niche mixology and gifting use cases. Seasonal demand spikes around holidays strain inventory forecasting algorithms.
By volume, Beer leads. By growth pace, Spirits is ahead.
Customer Type:
Cost tier stratification separates high-frequency low-margin replenishment from episodic high-value procurement, reshaping platform acquisition economics.
- Retail Consumers:Individual purchasers seeking convenience, discovery, or price transparency. Millennial and Gen Z segments drive subscription adoption and curated box experimentation. Urban density enables same-day fulfillment economics.
- Bars:Licensed on-premise establishments with predictable high-volume replenishment cycles and stringent delivery timing requirements. Average order values exceed retail thresholds, justifying dedicated account management.
- Restaurants:Food-service operators balancing wine list curation with cost control. Sommelier-driven procurement favors platform relationships offering portfolio breadth and vintage depth.
- Event Planners:Occasion-based bulk purchasers with compressed fulfillment windows and specialized packaging needs. Liability exposure around service-to-minors elevates compliance verification intensity.
By transaction count, Retail Consumers dominate. By revenue per order, Bars command the premium position.
Distribution Channel:
Application logic determines whether platforms optimize for margin capture, reach extension, or customer lock-in through recurring revenue architecture.
- Direct Sales:Producer-controlled digital storefronts bypassing intermediary markups. Kentucky and Tennessee craft distilleries exploit DTC shipping permissions to capture scarcity premiums on limited releases.
- Third-Party Platforms:Marketplace aggregators connecting fragmented local retailer networks with national demand. Liquidity depends on density of participating licensed merchants within delivery zones.
- Subscription Services:Recurring revenue models reducing customer acquisition costs and locking in predictable replenishment cycles. Discovery-driven curation displaces brand loyalty among wine and craft spirits categories.
- Wholesale:B2B bulk distribution anchoring bar and restaurant supply relationships. Three-tier system constraints limit direct platform participation in this channel.
By revenue concentration, Third-Party Platforms lead. By expansion trajectory, Subscription Services is climbing the fastest.
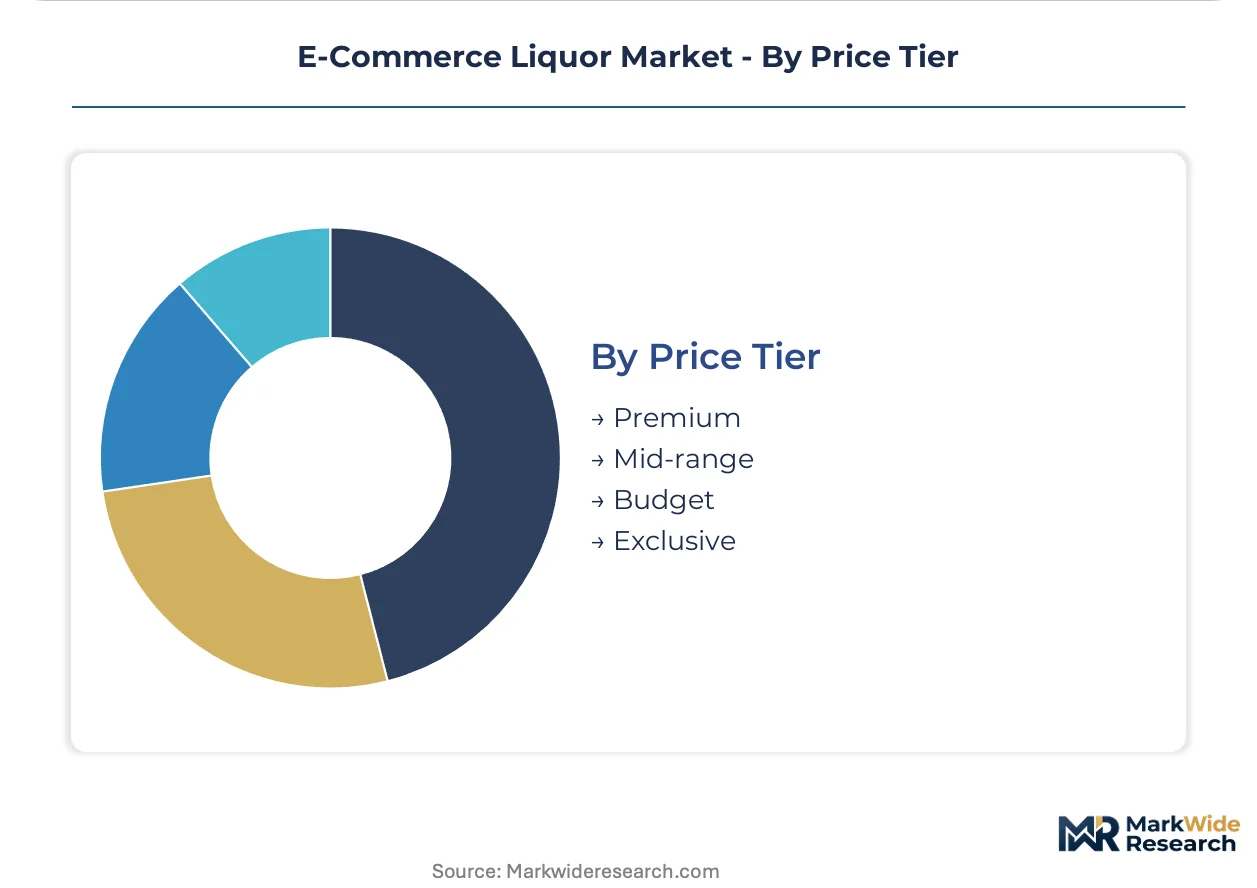
Price Tier:
Margin structure stratifies across authentication requirements, packaging investment, and customer service intensity, with luxury segments justifying proprietary technology spend.
- Premium:Established brands commanding price premiums through reputation and consistent quality. Urban professional demand supports subscription curation and same-day fulfillment economics.
- Mid-range:Volume-driving category balancing accessibility with perceived quality. Price transparency pressures favor platform comparison shopping.
- Budget:Value-oriented segments with thin margins and high volume velocity. Logistics cost compression determines platform viability.
- Exclusive:Ultra-limited releases and allocated products requiring blockchain provenance verification and collector-market infrastructure. NFC-enabled bottles and distributed ledger authentication justify technology investment.
By unit volume, Mid-range leads. By margin per transaction, Exclusive commands the premium position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z retail consumers concentrate in urban metropolitan clusters across California, Texas, and New York, driving subscription adoption and same-day fulfillment economics. Bars and restaurants in these density centers generate higher average order values with predictable replenishment cycles.
United States
Urban metropolitan clusters across California, Texas, and New York dominate transaction volume. The TTB certificate of label approvals and interstate shipping reciprocity agreements determine SKU portability across state lines. Kentucky and Tennessee craft distilleries exploit direct-to-consumer shipping permissions to capture scarcity premiums on limited releases.
United Kingdom
London and Southeast England anchor premium spirits discovery through curated subscription services. The country's national alcohol regulator enforces licensing requirements that elevate platform compliance costs. Manchester and Birmingham function as micro-fulfillment nodes for hybrid click-and-collect operations.
Germany
Bavaria and North Rhine-Westphalia concentrate wine subscription demand among urban professionals. ECHA chemical safety standards intersect with national beverage control frameworks for labeling compliance. The Frankfurt-Rhine-Main corridor hosts temperature-controlled logistics infrastructure for cold-chain wine fulfillment.
France
Île-de-France and Provence-Alpes-Côte d'Azur drive luxury spirits authentication demand. ANSM labeling requirements converge with EU-wide food safety regulations for cross-border digital sales. Bordeaux and Champagne-Ardenne function as provenance-verification hubs for blockchain-enabled collector markets.
Australia
New South Wales and Victoria concentrate craft spirits discovery through digital channels. TGA guidelines on therapeutic claims intersect with state-level liquor licensing for functional beverage categories. Sydney and Melbourne anchor same-day delivery infrastructure for immediate-consumption occasions.
E-Commerce Liquor Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a fragmented market structure where no single operator commands dominant share. Marketplace aggregators, hybrid physical-digital retailers, and curated subscription platforms represent three distinct strategic archetypes. Competitive moves concentrate on geographic expansion through local retailer network aggregation and technology licensing for age-verification engineering.
Within the marketplace aggregation tier, Drizly and Saucey exemplify liquidity-sustaining models that connect fragmented local retailer networks with national demand. Total Wine anchors the hybrid physical-digital archetype, leveraging extensive brick-and-mortar infrastructure as micro-fulfillment nodes for click-and-collect operations. ReserveBar occupies a defensible position in the luxury and limited-edition spirits niche, where scarcity economics and collector-driven authentication requirements justify specialized platform investment.
| Leading Market Players |
|---|
| Drizly |
| Total Wine |
| Wine.com |
| Minibar |
| ReserveBar |
| Vivino |
| BevMo! |
| Flaviar |
| Saucey |
| Others |
Supply Flow & Price Mechanics
Kentucky and Tennessee craft distillery concentration upstream funnels scarcity premiums into exclusive-tier margin pools downstream, while temperature-controlled logistics costs compress mid-range pricing flexibility. Subscription lock-in mechanisms redistribute pricing power toward platforms with recurring revenue architecture.
Pricing Analysis
Cost-plus contracts with TTB certificate indexation dominate producer-platform arrangements, though subscription SaaS-tiered pricing is displacing per-unit transactional models among urban professionals. Price differentiation rests on authentication grade and cold-chain certification tier, with exclusive releases commanding scarcity premiums. Pricing pressure stems from last-mile refrigeration infrastructure costs in metropolitan clusters. Budget-tier retail consumers exhibit highest price sensitivity; collector-driven exclusive buyers show lowest.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchor distributor-retailer relationships, compressing working capital cycles for fragmented local merchants. Geographic supply concentration centers on the United States, France, and Australia for provenance-authenticated spirits. Raw material dependencies include aged whiskey stock, temperature-sensitive wine inventory, and NFC-enabled packaging components. Single-source vulnerability runs through specialized cold-chain logistics providers. Distribution runs through hybrid third-party platform and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where subscription curation layers expand faster than transactional fulfillment hardware, justifying platform investment in recurring-revenue infrastructure.
For Market Incumbents: Insulate core liquidity positions by deepening exclusive-tier authentication capabilities and securing TTB compliance automation ahead of interstate reciprocity expansion. Platform aggregators face margin compression from direct-to-consumer distillery entrants; vertical integration into proprietary age-verification engineering defends customer acquisition economics. For New Entrants and Emerging Players: Pursue white-space in blockchain-enabled provenance services for luxury spirits collectors, where authentication infrastructure remains underdeveloped. Kentucky and Tennessee craft distillery direct-to-consumer segments offer the most penetrable entry point. A licensing-based go-to-market angle with established retailers accelerates regulatory compliance without captive infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid physical-digital operators with micro-fulfillment node density in California, Texas, and New York metropolitan clusters. Long-term viability over a multi-year horizon favors platforms combining subscription lock-in with temperature-controlled logistics capabilities. The signal to monitor is state-level ABC licensing liberalization momentum as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| TTB Compliance Automation | Accelerates cross-state SKU launches by compressing certificate approval timelines for e-commerce inventory. |
| Cold-Chain Infrastructure Partnership | Secures metropolitan last-mile refrigeration capacity for temperature-sensitive wine and craft beer fulfillment. |
| Blockchain Provenance Integration | Authenticates luxury spirits for collector markets through NFC-enabled bottle verification systems. |
| Subscription Curation Platform | Locks in millennial and Gen Z recurring revenue through discovery-driven wine and craft spirits procurement. |
| Hybrid Click-and-Collect Expansion | Converts physical retail locations into same-day pickup nodes for immediate-consumption occasions. |
Methodological Framework
Desk research of regulatory filings, customs records, and platform transaction datasets preceded structured interviews with e-commerce platform executives, ABC compliance officers, cold-chain logistics operators, and craft distillery founders. Primary fieldwork combined with secondary validation against TTB certificate databases, state-level shipping reciprocity agreements, and subscription service financial disclosures. Bottom-up SKU-level demand modeling triangulated against top-down market sizing.
Assumptions held state-level direct-to-shipper law trajectories and TTB processing timelines within observed patterns while varying subscription adoption curves and interstate shipping reciprocity expansion scenarios across the analysis window. Segmentation dimensions modeled include product type, customer archetype, distribution channel configuration, and urban metropolitan cluster density. CAGRs derived from logistic diffusion curves fitted to subscription penetration data and platform transaction velocity benchmarks.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by craft distilleries or platform acquisitions by beverage conglomerates would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Luzhou-Flavor Liquor Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Spirits Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Cooking Wine Market