
 Gummy Candy Market | 2026-2036
Gummy Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Gummy Candy Market Analysis
Subscription-based replenishment for personalized vitamin gummies is hardening into a core revenue layer for manufacturers seeking recurring consumer relationships. Haribo leverages its century-old brand equity and dense European retail footprint to sustain dominance in traditional jelly confectionery. Mondelēz International anchors its position through global distribution scale and cross-category snacking synergies. Meiji Co. Ltd. differentiates via precision-controlled Japanese manufacturing standards and Asia-Pacific channel control.
Gummy candy comprises gelatin or pectin-based chewy confections formed through starch molding or depositing processes, typically containing glucose syrup, sucrose, and flavoring agents at moisture levels of 15-20 percent, serving purposes from indulgent snacking to nutrient delivery. Fruit-flavored gummies occupy the largest share of flavor profile demand while sour variants capture premium positioning among teen and young adult segments. Gummy vitamins within product type classification represent the fastest-expanding margin pool as functional claims attract adult and senior customer types. Online retailers as a distribution channel are displacing traditional supermarket dominance through direct-to-consumer personalization and subscription mechanics.
FDA oversight of dietary supplement labeling and Good Manufacturing Practice requirements directly shapes formulation transparency and market access for gummy vitamin producers in the United States. EFSA health claim regulations and ECHA food additive assessments constrain permissible fortification messaging and colorant selections across European markets. China's SAMR food safety standards and GB additive specifications govern import compliance and domestic production licensing. Stakeholders must monitor evolving clean-label certification requirements and adapt formulation strategies as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
Clean-label gelatin alternatives and plant-based pectin formulations are forcing wholesale reformulation across conventional gummy manufacturing, compressing legacy supply chains while opening margin pools for certified ingredient suppliers.
Growth Catalysts
- EFSA Health Claim Regulations:Fortification messaging clarity in European markets accelerates adult-targeted functional gummy adoption, particularly for vitamin D and probiotic claims.
- Starch Molding Automation:Precision depositing technology cuts production cycle times by half while enabling complex multi-layer geometries for premium positioning.
- United States:FDA dietary supplement GMP enforcement drives transparency investments that differentiate compliant producers in direct-to-consumer channels.
Market Restraints
- Pork-Derived Gelatin Sourcing:Religious dietary restrictions and clean-label demands constrain formulation flexibility across Middle Eastern and Southeast Asian markets.
- Glucose Syrup Price Volatility:Corn and wheat feedstock fluctuations transmit directly to margin pressure for mid-tier producers lacking forward-contract coverage.
- SAMR Import Licensing:China's extended approval timelines for novel food additives delay product launches by 18-24 months versus domestic competitors.
Strategic Opportunities
- Germany:Underpenetrated senior nutrition segment offers white space for collagen-fortified and joint-health gummy formats with pharmacy channel access.
- Subscription Personalization:Algorithm-driven vitamin stacking based on biomarker data is expanding into wellness-as-a-service business models.
- EU Green Deal Packaging Mandates:Compostable film and bulk refill formats create first-mover advantage for sustainability-certified brands.
Industry Challenges
- Moisture Migration Control:Achieving 15-20% moisture stability in pectin-based formulations without synthetic humectants demands specialized process engineering talent scarce outside Japanese and Swiss technical centers.
- Dual Certification Burden:Simultaneous pursuit of FDA GRAS self-affirmation and EFSA novel food opinions stretches regulatory affairs capacity at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gummy Candy Market |
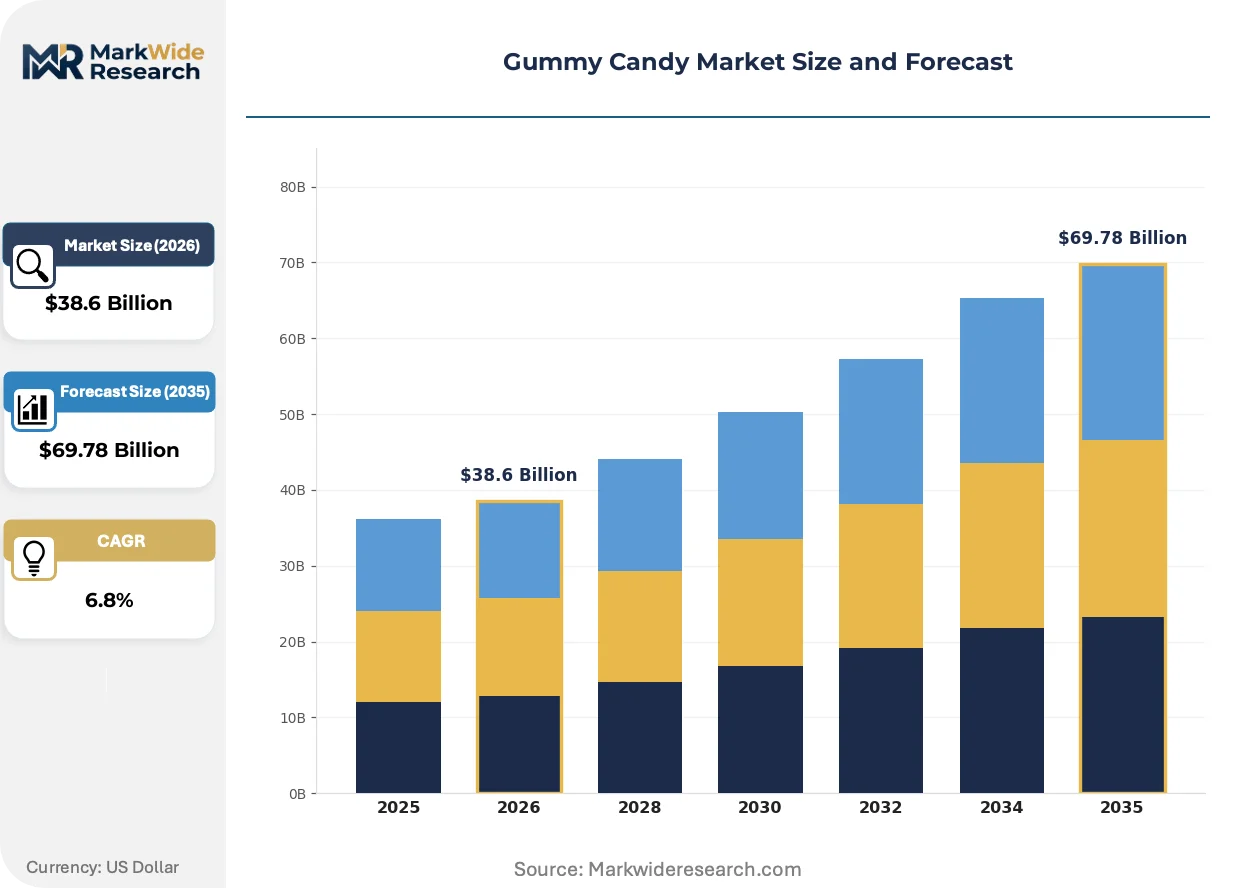
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jelly Bears, Sour Worms, Fruit Snacks, Gummy Vitamins Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops Customer Type: Children, Teens, Adults, Seniors Flavor Profile: Fruit, Sour, Chocolate, Herbal |
| Companies Covered | Ferrero Group, Albanese, Haribo, Jelly Belly, Katjes, Mondelēz International, Nestlé SA, Meiji Co. Ltd., Mars Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gummy Candy Market Emerging Trajectories
Functional claims are migrating from niche vitamin positioning toward mainstream indulgence formats, blurring category boundaries while reshaping ingredient sourcing priorities and manufacturing asset configurations.
Encapsulation technology for heat-sensitive actives is expanding into gummy production lines previously limited to ambient-stable ingredients. Probiotic and omega-3 fortification now reaches mass-market price points as microencapsulation costs fall. Adult wellness buyers accept texture trade-offs that teen segments reject, segmenting formulation strategies by demographic.
REACH restrictions on titanium dioxide and select azo dyes force European producers toward natural colorant portfolios. Reformulation timelines compress as ECHA updates its approved additives list. German and French manufacturers lead substitution efforts, transferring technical knowledge to Asian contract manufacturers facing parallel regulatory pressure.
Direct-to-consumer subscription mechanics are displacing conventional retail replenishment for personalized vitamin stacks. Millennial and Gen Z buyers in the United States and China favor algorithm-curated monthly shipments over pharmacy aisle selection. Customer lifetime value metrics now dominate brand valuation models, rewarding retention engineering over single-transaction marketing efficiency.
Gummy Candy Market Segmentation
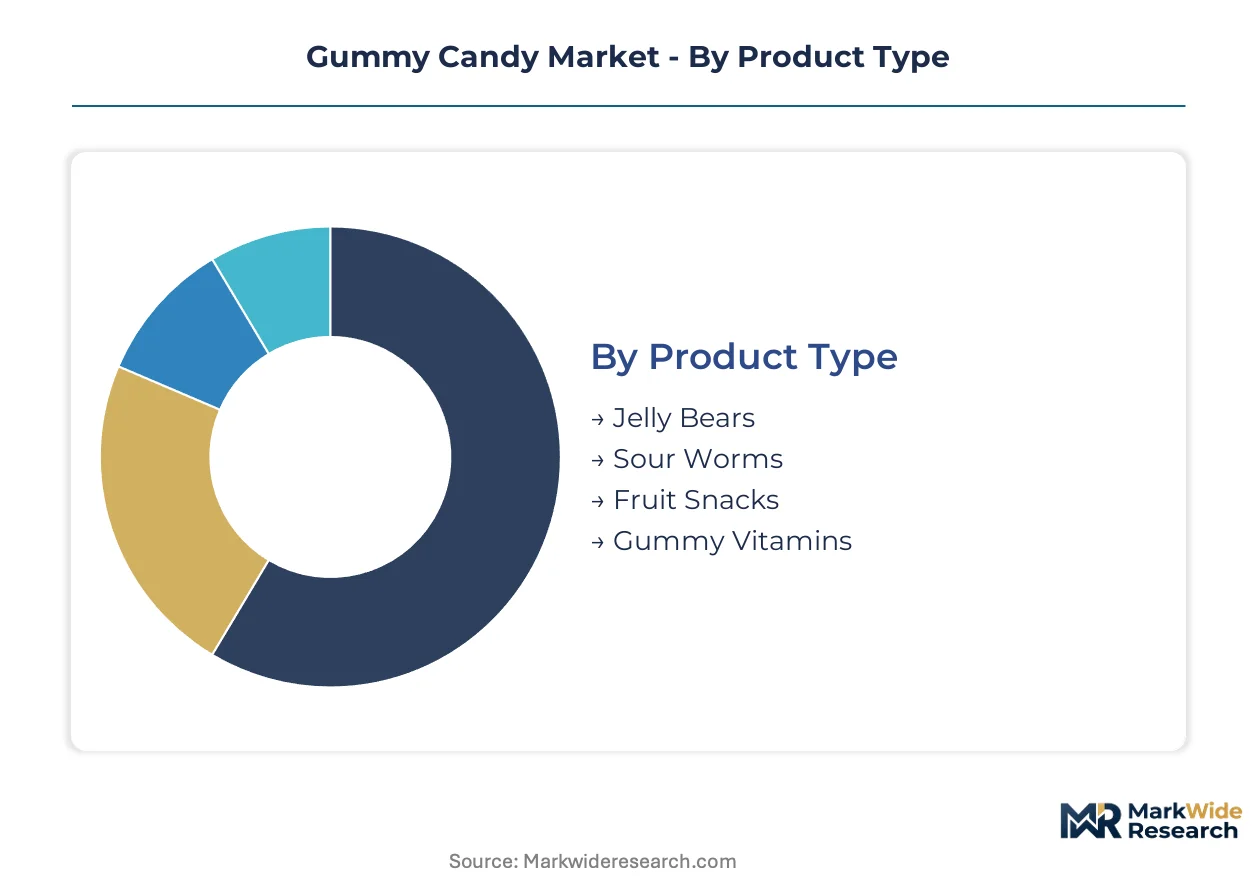
Gummy candy manufacturers align production assets and formulation expertise against distinct demand profiles. Segmentation reveals where margin pools concentrate and which technical capabilities command premium positioning.
Product Type:
Gelatin and pectin base specifications differentiate manufacturing complexity and shelf stability requirements across formats.
- Jelly Bears:Starch-molded gelatin matrices at 15-20% moisture define the traditional benchmark. Haribo's century-old equity and dense German retail penetration sustain volume leadership in classic bear geometries.
- Gummy Vitamins:Pectin-based functional matrices accommodate heat-sensitive actives through microencapsulation. Adult wellness consumers in the United States and China drive subscription replenishment models with the steepest expansion trajectory.
- Sour Worms:Citric acid surface application creates pH-sensitive tartness layers. Teen segments in convenience channels favor this format for impulse purchase occasions.
- Fruit Snacks:Reduced-sugar pectin formulations target parental purchase decisions. Clean-label positioning competes with conventional confectionery in lunchbox and on-the-go snacking.
Jelly Bears lead on scale; Gummy Vitamins lead on momentum.
Distribution Channel:
Channel selection determines margin capture, customer data access, and replenishment mechanics.
- Online Retailers:Direct-to-consumer platforms enable algorithm-driven personalization and subscription bundling. Millennial buyers in the United States favor curated monthly vitamin stacks over pharmacy aisle selection.
- Supermarkets:Mass-market volume flows through controlled-temperature shelf networks with slotting fee structures. German and Chinese hypermarket chains anchor traditional jelly candy placement.
- Convenience Stores:Impulse-oriented single-serve formats dominate checkout adjacencies. Sour variants capture unplanned teen purchases in urban locations.
- Specialty Shops:Premium positioning through artisanal small-batch claims and regional flavor novelty. Pharmacy channel access in Germany supports senior-targeted functional formats.
Supermarkets lead on scale; Online Retailers lead on momentum.
Customer Type:
Demographic targeting shapes texture acceptance, fortification tolerance, and price elasticity.
- Adults:Wellness-motivated purchasers accept texture trade-offs for functional claims. Vitamin D and probiotic fortification concentrates demand among United States and Chinese subscription adopters.
- Teens:Sour flavor intensity and novel shape geometries drive social sharing behaviors. Convenience channel impulse mechanics capture discretionary spending.
- Children:Parental gatekeeping favors reduced-sugar and natural colorant formulations. Fruit-flavored pectin options compete for lunchbox inclusion.
- Seniors:Joint-health and collagen claims gain traction through pharmacy channel credibility. German market underpenetration offers white space for targeted formats.
Adults lead on scale; Seniors lead on momentum.
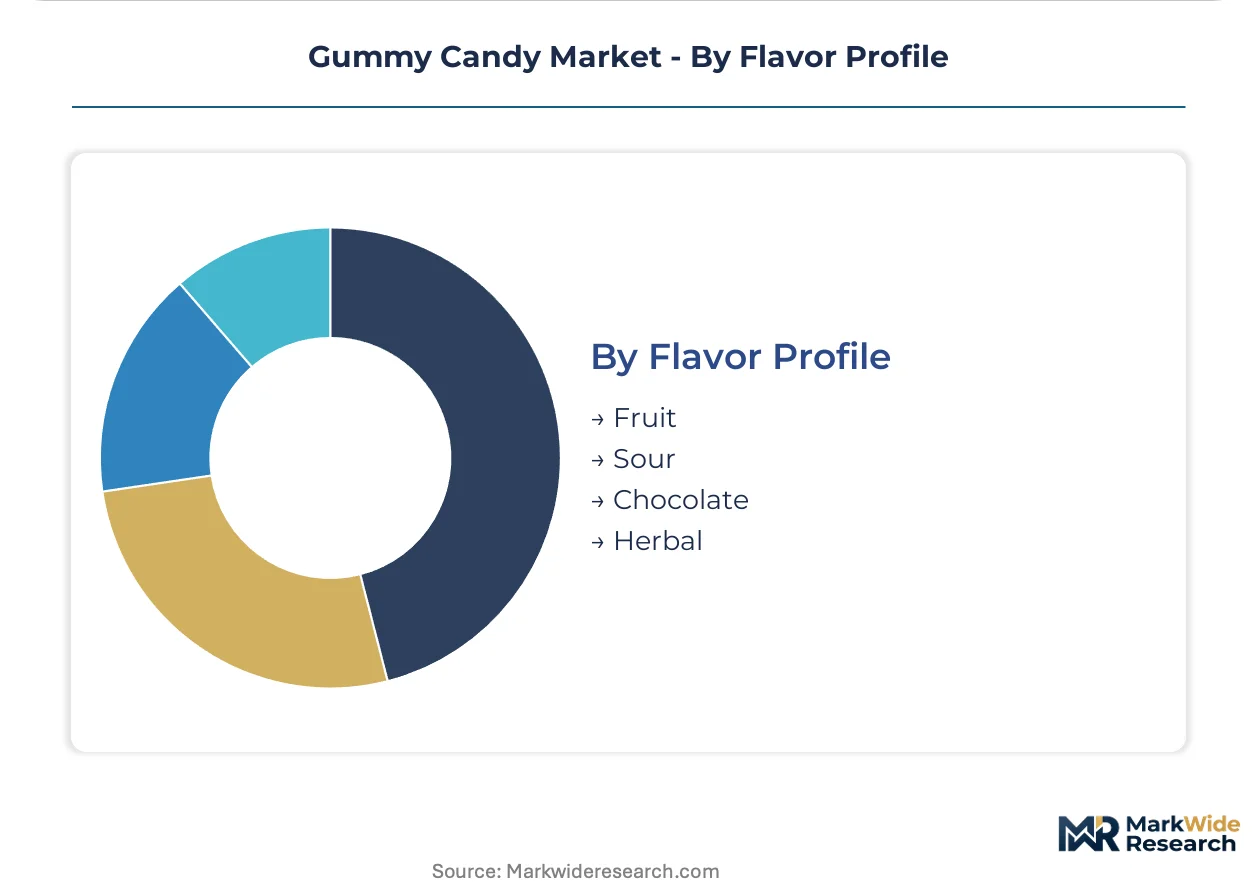
Flavor Profile:
Flavor chemistry and colorant sourcing requirements vary sharply by profile, affecting regulatory compliance burden.
- Fruit:Natural and nature-identical ester compounds dominate volume production. EFSA and FDA colorant approvals constrain European and United States formulation flexibility.
- Sour:Citric and malic acid surface applications create pH-driven tartness. Teen and young adult segments in convenience channels pay premium positioning for intensity.
- Chocolate:Fat-compatible flavor systems require modified starch or gum arabic suspensions. Niche positioning competes against conventional chocolate confectionery.
- Herbal:Botanical extracts and adaptogen claims attract functional positioning. EFSA health claim regulations limit permissible messaging in European markets.
Fruit leads on scale; Sour leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States functional gummy adoption outpaces German traditional confectionery volume, while Chinese premium positioning accelerates fastest among the three demand centers.
United States
FDA dietary supplement GMP enforcement drives transparency investments among vitamin gummy producers. Direct-to-consumer subscription channels capture wellness-motivated millennials seeking personalized nutrient stacks. Chicago and New Jersey corridor manufacturers expand pectin-based clean-label capacity to serve pharmacy and online retail channels.
Germany
Haribo's century-old brand equity sustains jelly bear dominance through dense retail penetration. EFSA health claim regulations constrain fortification messaging while REACH colorant restrictions force natural pigment reformulation. Cologne-Bonn manufacturing cluster leads starch molding automation adoption for complex multi-layer geometries.
China
SAMR food safety standards and GB additive specifications govern import compliance timelines stretching 18-24 months for novel ingredients. Domestic producers leverage shorter approval pathways to capture functional gummy growth. Yangtze River Delta contract manufacturers scale pectin formulation expertise for export markets.
Japan
Precision-controlled manufacturing standards differentiate domestic producers in Asia-Pacific quality-sensitive segments. PMDA and METI guidance shapes functional claim substantiation requirements for joint-health and collagen formats. Kansai/Osaka technical centers develop moisture migration control expertise scarce outside Swiss counterparts.
United Kingdom
Post-Brexit divergence from EFSA frameworks creates dual compliance burden for exporters serving EU and domestic markets. London-based direct-to-consumer brands pioneer algorithm-driven vitamin personalization. Midlands manufacturing corridor adapts to UK-specific novel food consultation timelines.
Gummy Candy Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage confectioners defending traditional formats while functional entrants capture wellness premiums. The vendor base organizes around three archetypes: century-old European jelly candy houses, multinational snacking conglomerates with cross-category scale, and Asia-Pacific precision manufacturers. Consolidation pressure intensifies as mid-tier producers face dual certification burdens and ingredient sourcing reformulation costs.
Within the heritage branded tier, Haribo and Ferrero Group exemplify century-old equity translation into sustained retail shelf dominance. Meiji Co. Ltd. occupies a position representing Japanese manufacturing precision standards. Mondelēz International anchors the multinational scale archetype through global distribution infrastructure. These three company types collectively illustrate how competitive positioning stratifies between brand heritage, technical capability, and network scale rather than converging on a single winning formula.
| Leading Market Players |
|---|
| Ferrero Group |
| Albanese |
| Haribo |
| Jelly Belly |
| Katjes |
| Mondelēz International |
| Nestlé SA |
| Meiji Co. Ltd. |
| Mars Inc. |
| Others |
Supply Flow & Price Mechanics
Specialized moisture migration control engineers concentrated in Swiss and Japanese technical centers command wage premiums that propagate through pectin-based gummy manufacturing costs, widening spreads between premium functional tiers and conventional gelatin formats.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for clean-label pectin formulations as domestic producers exploit shorter SAMR approval pathways. Three-tier pricing structure across premium functional, standard confectionery, and economy bulk segments separates subscription vitamin stacks from impulse-checkout jelly bears. Cost compression in mid-tier gelatin formats intensifies as glucose syrup feedstock volatility transmits directly from corn and wheat markets. Teen convenience-channel buyers exhibit highest price elasticity, while adult wellness subscribers in the United States accept sustained premiums for algorithm-curated fortification.
Supply Chain Analysis
Direct-to-consumer platforms handle personalized vitamin stack demand while supermarket controlled-temperature networks anchor traditional jelly candy volume. Raw material sourcing draws from German starch molding equipment, Chinese pectin refinement capacity, and Southeast Asian natural colorant cultivation. Pork-derived gelatin dependencies create single-source vulnerability for Middle Eastern market access, forcing parallel plant-based formulation investments. Distribution runs through pharmacy channels for senior-targeted functional formats in Germany, online subscription mechanics for millennial wellness buyers in the United States, and hypermarket chains for family-oriented fruit snacks in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EFSA health claim clarity and FDA dietary supplement GMP enforcement simultaneously expand addressable demand and raise compliance barriers to entry.
For Market Incumbents: Anchor brand equity in heritage jelly formats through dense European retail penetration while accelerating pectin-based clean-label capacity in Chicago-New Jersey and Yangtze River Delta corridors. Defend against functional entrants by securing pharmacy channel access for senior-targeted collagen and joint-health formats. Invest in dual FDA-EFSA certification capacity to outrun mid-tier producers facing stretched regulatory affairs resources.
For New Entrants and Emerging Players: Capture algorithm-driven subscription personalization white space among United States millennial wellness buyers seeking biomarker-curated vitamin stacks. Target underpenetrated German senior nutrition segments through pharmacy channel partnerships for collagen-fortified formats. Pursue EU Green Deal packaging mandates as first-mover sustainability positioning with compostable film and bulk refill mechanics.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale producers facing simultaneous dual certification burdens and ingredient reformulation costs. Long-term viability favors contract manufacturers with pectin formulation expertise and moisture migration control capabilities transferable across pharmaceutical and confectionery applications. Watch ECHA additive list updates as inflection signal for natural colorant substitution demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Pectin Capacity Expansion | Yangtze River Delta producers exploit shorter SAMR pathways versus import competitors. |
| Subscription Personalization Platform Launch | Algorithm-curated vitamin stacks capture millennial lifetime value in United States direct-to-consumer channels. |
| Pharmacy Channel Partnership Development | German senior nutrition access differentiates functional formats from supermarket confectionery placement. |
| Dual Certification Investment | Parallel FDA GRAS and EFSA novel food opinions stretch mid-tier regulatory capacity. |
| Sustainable Packaging Transition | EU Green Deal compostable film mandates create first-mover advantage for certified brands. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at heritage confectioners, category buyers at German and Chinese hypermarket chains, pectin formulation specialists at contract manufacturers, and regulatory affairs leads navigating EFSA and SAMR pathways. Secondary validation drew from FDA dietary supplement enforcement actions, EFSA health claim register updates, SAMR food safety standard releases, and Nielsen retail audit data across United States pharmacy and convenience channels. Bottom-up segment sizing and top-down macro constraint checks provided cross-verification.
Historical reference periods anchored volume and value trajectories across the analysis window, with segmentation modeling spanning product type matrices, distribution channel economics, customer demographic elasticity, and flavor profile regulatory burden. CAGRs derived from trend extrapolation against capacity expansion announcements and approval timeline patterns. Forecast inputs incorporated encapsulation technology cost curves for heat-sensitive actives and starch molding automation adoption rates in European manufacturing clusters.
Underlying measurement precision varies by segment; online retailer subscription data carries tighter precision than specialty shop artisanal volume estimates. Forecasts reflect assumptions around regulatory approval velocity and clean-label ingredient substitution timelines. Periodic stress-testing of base assumptions is recommended given ECHA additive list volatility and glucose syrup feedstock fluctuation exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Fat Sweets Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Fat Free Candy Market
Confectionery
Macarons Market
Confectionery
Low-Fat Candy Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
Vegan Candies Market
Confectionery
Fruit Jellies Market
Confectionery
Dietary Chocolate Products Market
Confectionery
UK Confectionery Market
Confectionery
North America Compound Chocolate Market
Confectionery
Caramel Market
Confectionery
Black Treacle Market
Confectionery
Low-Calorie Candy Market
Confectionery
Sugar-Free Gummy Market