
 India Chocolate Market | 2026-2036
India Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
India Chocolate Market Outlook
Confectionery craftsmanship talent is bifurcating the India chocolate landscape into artisanal premium producers and scaled mass-market operators. Mondelez India anchors its dominance through deep rural distribution networks and localized flavor portfolios. Amul leverages its cooperative dairy infrastructure to control milk chocolate input costs across Gujarat and neighboring states. Nestlé India competes on manufacturing scale, operating one of the largest cocoa processing facilities serving the domestic market.
Chocolate comprises roasted and ground cacao seeds combined with cocoa butter, sugar, and emulsifiers such as lecithin, typically refined through conching and tempering processes to achieve defined viscosity and snap characteristics for confectionery consumption. Milk chocolate remains the volume leader, though dark chocolate is gaining fastest among health-positioned urban consumers seeking elevated cocoa solids content. Specialty shops and online retail channels capture disproportionate margin pools as premium shoppers migrate toward bean-to-bar and single-origin offerings with transparent sourcing credentials.
FSSAI mandates govern chocolate product standards, cocoa content thresholds, and labeling disclosures across India, while BIS certification requirements apply to packaging materials in direct food contact. The PLI scheme for food processing incentivizes domestic cocoa bean processing capacity expansion, reducing import dependency for key intermediates. Stakeholders must monitor evolving FSSAI fortification guidelines and state-level cold-chain infrastructure investments that will determine premium chocolate penetration into secondary cities.
Market Dynamics
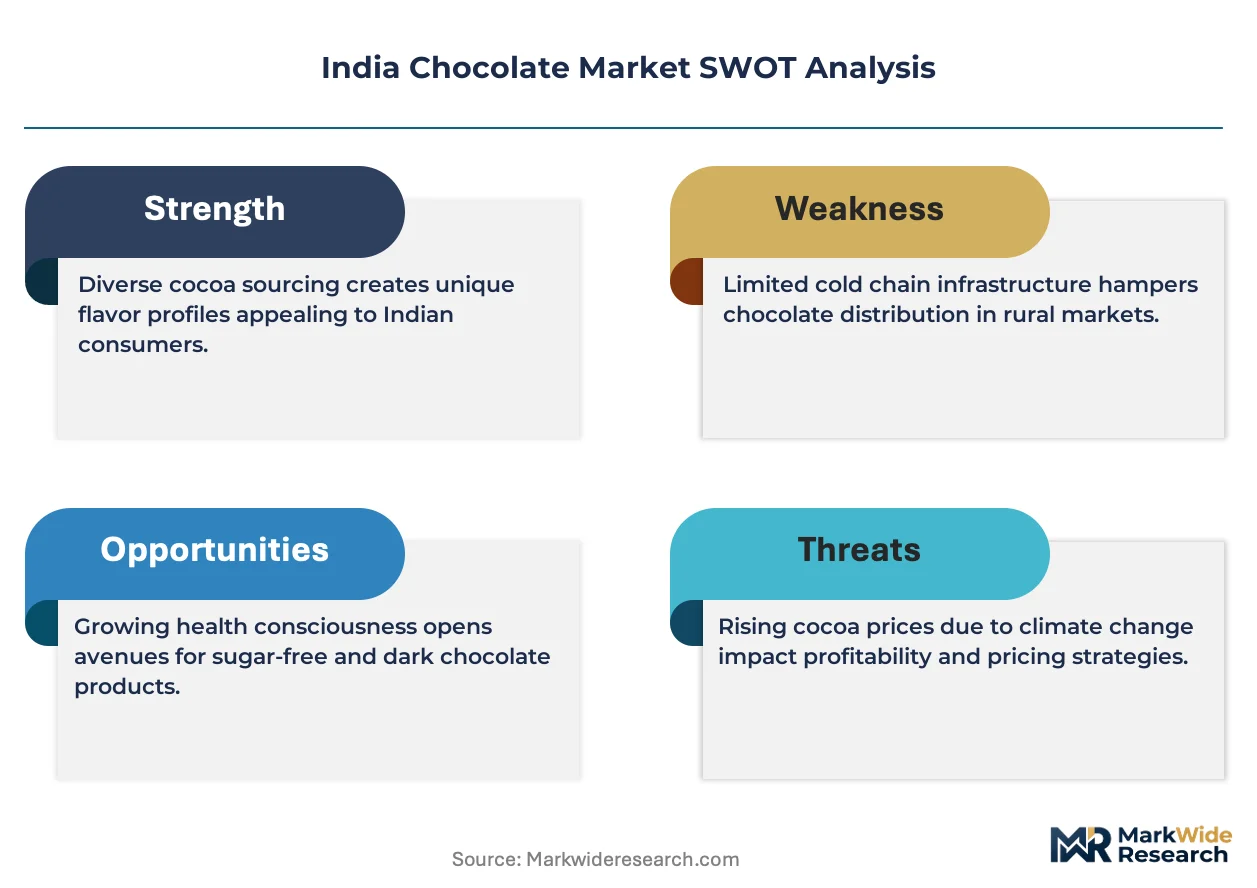
FSSAI fortification mandates and cold-chain infrastructure gaps are creating a bifurcated market where premium chocolate penetration stalls beyond Maharashtra and Karnataka while mass-market operators absorb compliance costs.
Growth Catalysts
- PLI scheme for food processing:Domestic cocoa bean processing capacity receives capital subsidies, reducing import dependency for cocoa butter and cocoa powder intermediates.
- Tier-1 urban retail infrastructure:Maharashtra and Karnataka host concentrated specialty retail and e-commerce fulfillment nodes that enable premium chocolate distribution with intact tempering.
- Bean-to-bar craftsmanship:Artisanal producers leverage transparent sourcing credentials to capture margin pools from health-positioned consumers seeking elevated cocoa solids content.
Market Restraints
- Cocoa butter price volatility:Input costs fluctuate with Ivory Coast and Ghana supply disruptions, compressing gross margins for milk chocolate manufacturers.
- Cold-chain concentration risk:Temperature-controlled logistics capacity clusters in western and southern states, limiting premium product reach into eastern and northern markets.
- FSSAI labeling friction:Stringent disclosure requirements for cocoa content thresholds and allergen warnings extend product development timelines and increase compliance expenditure.
Strategic Opportunities
- Secondary city penetration:Uttar Pradesh and Bihar present underdeveloped chocolate consumption per capita with expanding modern trade presence.
- Single-origin dark chocolate:Health-conscious urban consumers in Bengaluru and Mumbai drive demand for 70%+ cocoa solids products with traceable plantation sourcing.
- E-commerce direct-to-consumer channels:Specialty brands bypass traditional distributor networks to capture full retail margin through temperature-controlled last-mile partnerships.
Industry Challenges
- Conching and tempering technician scarcity:Artisanal producers compete with mass-market operators for skilled confectionery craftsmen capable of achieving defined viscosity and snap characteristics.
- BIS certification timelines:Packaging material compliance for direct food contact extends procurement cycles and creates inventory mismatches with seasonal demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Chocolate Market |
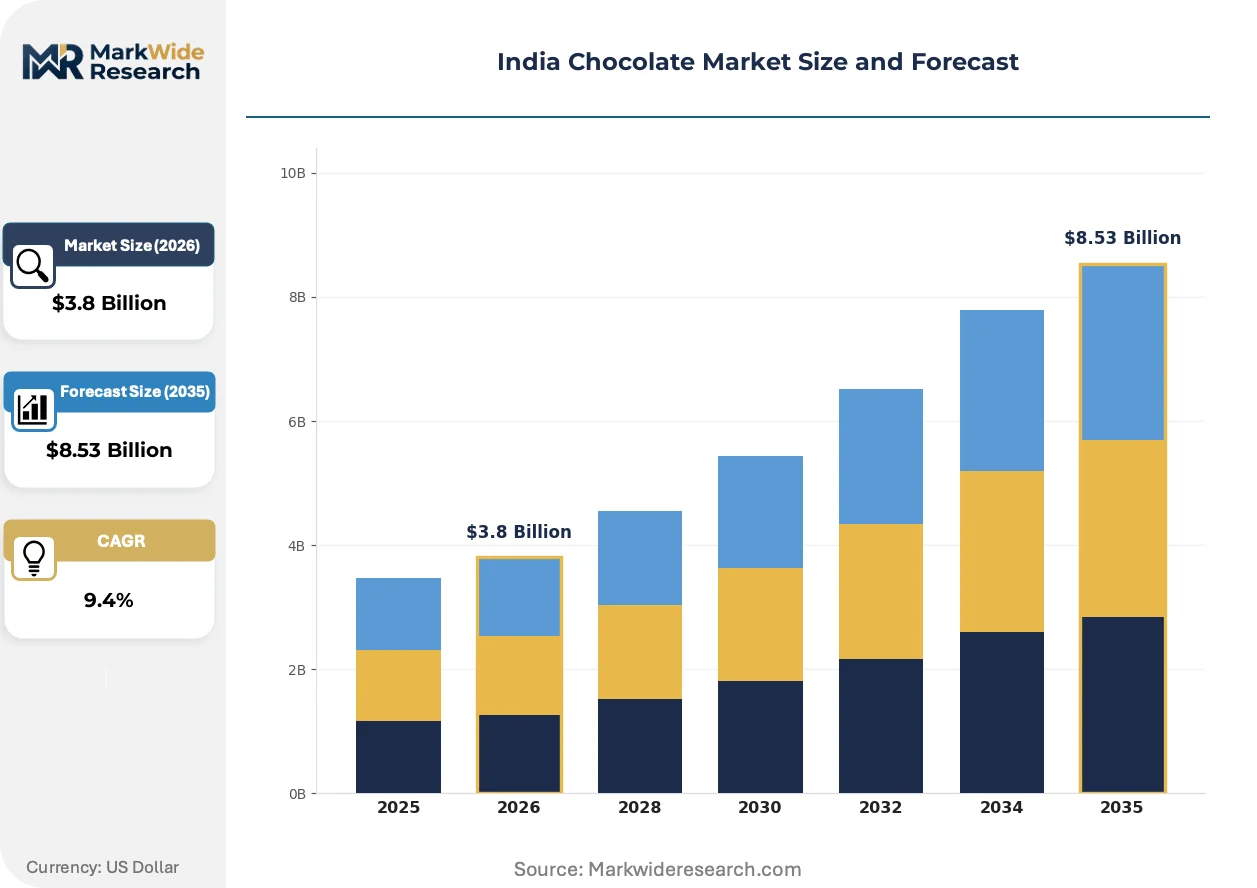
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Customer Type: Retail Consumers, B2B Buyers, Distributors, Premium Shoppers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Packaging Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Gift Packaging |
| Companies Covered | Ferrero India, ITC Limited, Mondelez India, Campco, Amul, Nestlé India, Hershey India, Lindt, Mars International India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Chocolate Market Strategic Shifts
Confectionery production technology and regulatory disclosure requirements are reshaping how chocolate manufacturers configure their supply chains and communicate product composition to consumers.
Precision tempering automation is decomposing traditional batch-based chocolate production into continuous-flow systems with real-time viscosity monitoring. Mid-scale manufacturers in Gujarat and Tamil Nadu adopt these systems to reduce cocoa butter waste and achieve consistent snap characteristics. The technology is decomposing cost barriers between artisanal quality and mass-market scale.
FSSAI fortification guidelines for micronutrient enrichment in chocolate products are mandating reformulation investments across domestic manufacturers. The standards require documented testing protocols and supply chain traceability for added vitamins and minerals. Milk chocolate producers targeting school and institutional channels face the steepest compliance ramps.
Consumer verification behavior is shifting purchase decisions toward packaging with QR-linked sourcing transparency and third-party ethical certification logos. Specialty retailers in Hyderabad and Pune report higher conversion rates for products displaying plantation coordinates and farmer cooperative identifiers. This pattern concentrates among dark chocolate buyers seeking differentiation from mass-market alternatives.
India Chocolate Market Segmentation
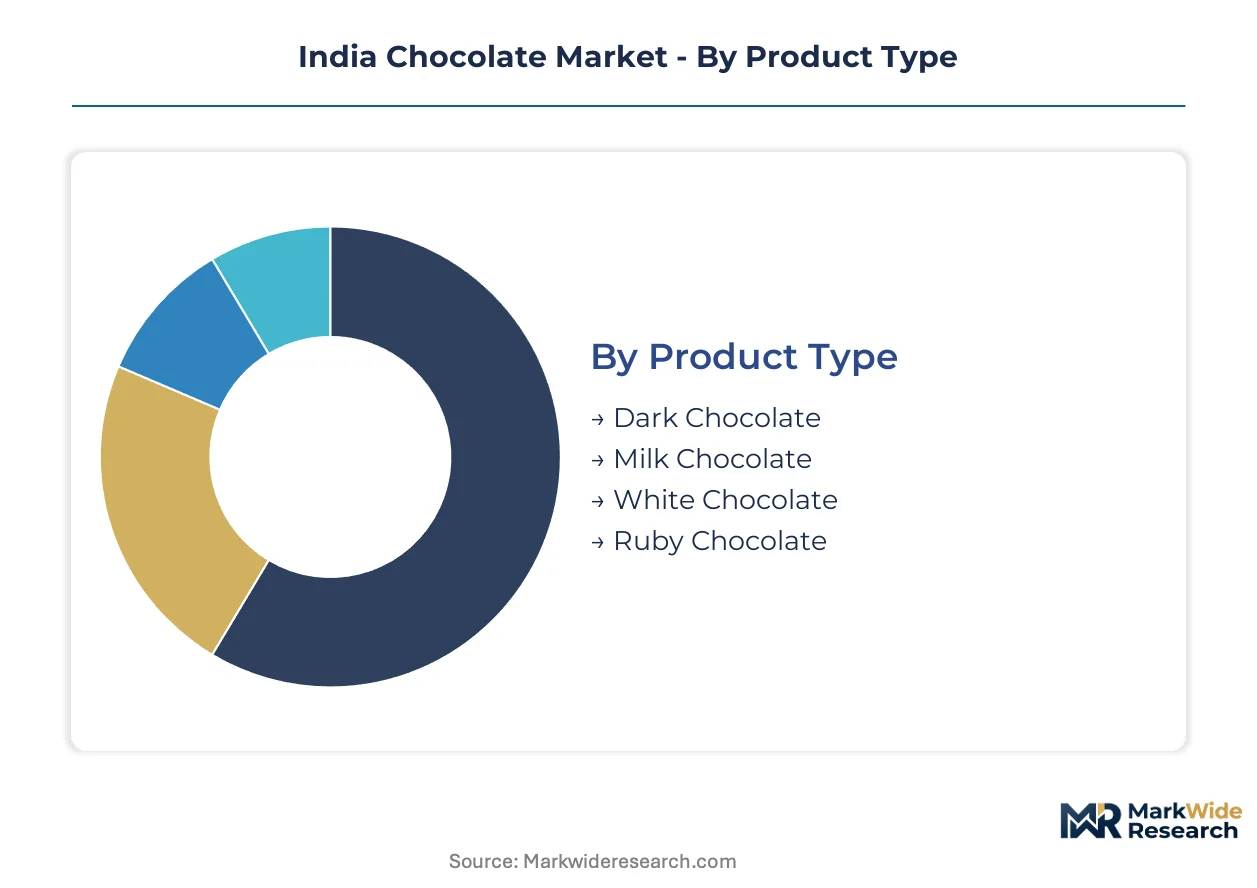
Chocolate segmentation in India reflects the tension between FSSAI-mandated cocoa content thresholds and divergent consumer willingness to pay for craftsmanship credentials. Regulatory compliance costs and cold-chain logistics constraints reshape which product formats and channels can profitably serve distinct buyer categories across tier-1 and tier-2 city clusters.
Product Type:
FSSAI standards differentiate chocolate categories by minimum cocoa solids and milk fat content, creating distinct compliance burdens that manufacturers internalize into pricing architecture.
- Milk Chocolate:Formulated with cocoa solids, cocoa butter, sugar, and milk solids exceeding 12% milk fat content per FSSAI standards. Maharashtra and Karnataka households drive volume through modern trade penetration, though cocoa butter price volatility from Ivory Coast supply disruptions compresses manufacturer margins.
- Dark Chocolate:Contains elevated cocoa solids above 35% with minimal milk content, positioning for health-conscious urban consumers seeking antioxidant claims. Bengaluru and Mumbai specialty retailers report accelerating adoption of 70%+ cocoa variants with single-origin sourcing credentials.
- White Chocolate:Cocoa butter-based confection without cocoa solids, regulated by FSSAI milk fat minimums. Premium shoppers in tier-1 cities favor this segment for gifting occasions.
- Ruby Chocolate:Pink-hued variant derived from specific cacao bean varieties, offering berry notes without added flavoring. Limited domestic processing capacity constrains widespread availability.
Established volume favors milk chocolate; emerging adoption favors dark chocolate.
Customer Type:
Margin capture varies sharply across buyer categories, with premium shoppers extracting transparency requirements that reshape supplier certification investments.
- Retail Consumers:Individual purchasers selecting packaged chocolate for personal consumption or household gifting. Tier-1 urban clusters concentrate demand for bean-to-bar products with QR-linked plantation traceability.
- B2B Buyers:Foodservice operators, institutional caterers, and bakery chains procuring chocolate for ingredient applications. Cold-chain reliability determines supplier selection for temperature-sensitive couverture requirements.
- Distributors:Wholesale intermediaries managing inventory across modern trade and traditional retail networks. Mondelez India and Nestlé India dominate their supplier relationships through exclusive territory allocations.
- Premium Shoppers:Affluent consumers prioritizing ethical certification, single-origin credentials, and artisanal craftsmanship. Hyderabad and Pune specialty retailers convert these buyers through farmer cooperative identifiers on packaging.
Mass-market profitability depends on distributor relationships; premium expansion hinges on direct engagement with affluent urban shoppers.
Distribution Channel:
Channel selection determines tempering integrity and margin retention, with temperature-controlled infrastructure concentrating in western and southern states.
- Supermarkets:Organized retail chains with refrigerated display capacity enabling year-round premium chocolate merchandising. Maharashtra and Karnataka host the densest network of compliant retail infrastructure.
- Online Retail:E-commerce platforms and direct-to-consumer brand websites leveraging temperature-controlled last-mile partnerships. Specialty producers bypass traditional distributor margins through this channel.
- Convenience Stores:Small-format neighborhood retailers with limited cold-chain equipment, favoring ambient-stable mass-market formulations. Gujarat and Tamil Nadu contain extensive networks.
- Specialty Shops:Curated retail environments emphasizing bean-to-bar provenance and craftsmanship narrative. Bengaluru's Indiranagar and Mumbai's Bandra clusters concentrate these outlets.
Volume flows through supermarkets; margin expansion concentrates in online and specialty channels.
Packaging Type:
BIS certification requirements for direct food contact materials extend procurement cycles and create inventory mismatches with seasonal demand spikes.
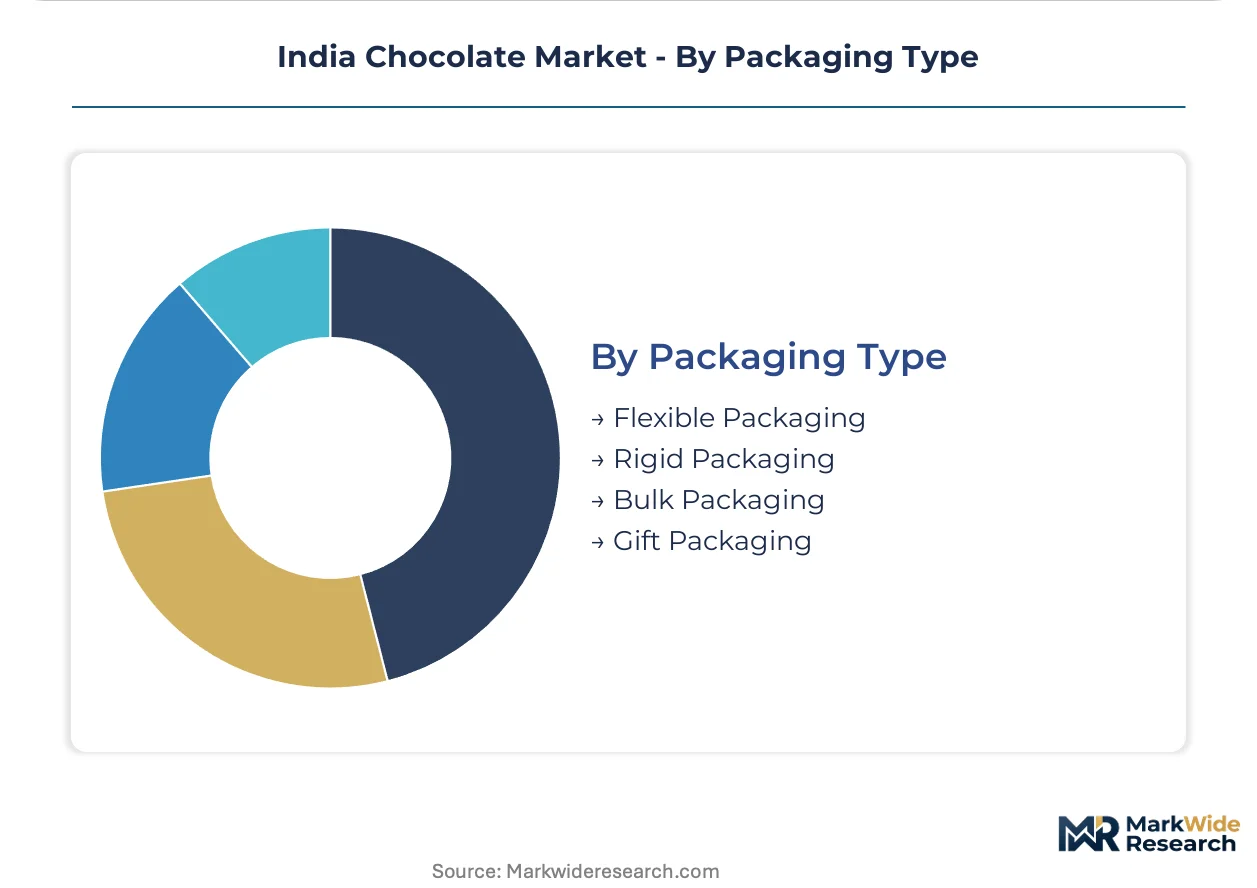
- Flexible Packaging:Films, wrappers, and pouches offering cost efficiency for high-volume milk chocolate SKUs. Amul leverages cooperative scale to negotiate favorable flexible packaging contracts.
- Rigid Packaging:Molded plastics, metal tins, and glass containers protecting premium products through distribution. Gift-oriented dark chocolate variants favor this format for shelf differentiation.
- Bulk Packaging:Industrial containers serving B2B bakery and confectionery manufacturing channels. Cocoa butter stability requirements limit supplier options.
- Gift Packaging:Elaborate boxed assortments targeting festive and corporate gifting occasions. Premium shoppers in tier-1 cities drive seasonal demand concentration.
Operational efficiency favors flexible packaging; brand premiumization requires rigid and gift format investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI standards anchor Maharashtra's dominance in premium chocolate distribution, with cold-chain infrastructure and urban retail density creating geographic concentration that other states struggle to replicate.
Maharashtra
Mumbai and Pune metropolitan clusters drive premium chocolate volume through specialty retail networks and e-commerce fulfillment nodes. FSSAI fortification mandates for micronutrient enrichment reshape product portfolios targeting institutional channels. The Bandra-Kurla commercial district concentrates corporate gifting demand, while Indiranagar-adjacent logistics parks enable temperature-controlled last-mile delivery.
Karnataka
Bengaluru's Indiranagar and Koramangala neighborhoods host India's densest concentration of bean-to-bar specialty shops. PLI scheme subsidies for food processing attract domestic cocoa grinding capacity to the state. Whitefield industrial corridors support chocolate manufacturing scale with reliable cold-chain connectivity to southern retail markets.
Gujarat
Amul's cooperative dairy infrastructure controls milk chocolate input costs across Anand and surrounding districts. BIS certification requirements for packaging materials extend procurement cycles for manufacturers in Ahmedabad industrial zones. The state's ambient-stable logistics networks favor mass-market chocolate distribution over premium tempering-dependent formats.
Tamil Nadu
Chennai's organized retail chains provide refrigerated display capacity for year-round premium chocolate merchandising. Precision tempering automation adoption accelerates among mid-scale manufacturers seeking to reduce cocoa butter waste. Coimbatore's industrial corridors host emerging confectionery production clusters with proximity to Kerala cocoa processing inputs.
Delhi-NCR
Gurgaon and Noida corporate campuses generate concentrated corporate gifting demand during festive quarters. Cold-chain infrastructure gaps limit premium chocolate penetration compared to western and southern counterparts. The region's distributor networks remain dominated by mass-market operators with exclusive territory allocations from national brands.
India Chocolate Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the India chocolate market. Mondelez India and Nestlé India anchor a consolidated tier through manufacturing scale and deep rural distribution networks, while artisanal producers compete on craftsmanship credentials and transparent sourcing. Three strategic archetypes define competitive positioning: cooperative-backed dairy-integrated players, multinational scale operators, and bean-to-bar craft specialists. Dominant competitive moves include portfolio diversification toward dark chocolate variants and strategic partnerships with temperature-controlled logistics providers.
Among multinational scale operators, Mondelez India and Nestlé India exemplify manufacturing dominance through extensive cocoa processing infrastructure and nationwide distributor relationships. Amul occupies a distinct position within the cooperative-integrated tier, leveraging its dairy cooperative structure to control milk chocolate input costs. Ferrero India represents the premium-import archetype, sitting within a positioning tier that emphasizes gifting-oriented packaging and European brand heritage. Mars International India and Hershey India anchor the confectionery-diversified segment, with product portfolios extending beyond chocolate into broader sweet snacking categories.
| Leading Market Players |
|---|
| Ferrero India |
| ITC Limited |
| Mondelez India |
| Campco |
| Amul |
| Nestlé India |
| Hershey India |
| Lindt |
| Mars International India |
| Others |
Value Chain & Pricing Dynamics
FSSAI certification requirements for cocoa content thresholds and allergen labeling simultaneously gate supplier qualification and enable price stratification between compliant mass-market operators and artisanal producers. This dual-gating mechanism concentrates margin capture among manufacturers with documented tempering protocols and BIS-certified packaging partnerships.
Pricing Analysis
Maharashtra and Karnataka command 15-20% price premiums over eastern and northern markets due to cold-chain reliability and specialty retail density. Three-tier pricing structure across premium, standard, and economy levels separates bean-to-bar artisanal products from Mondelez and Nestlé mass-market SKUs and Amul's cooperative-priced milk chocolate lines. Cost compression in the standard tier is intensifying because cocoa butter price volatility from Ivory Coast supply disruptions compresses manufacturer margins. Distributors and B2B bakery channels exhibit highest price sensitivity, while premium shoppers in Bengaluru and Mumbai demonstrate inelastic demand for single-origin dark chocolate with traceable sourcing credentials.
Supply Chain Analysis
Inventory cycles for BIS-certified packaging materials extend procurement lead times by 3-4 weeks, creating seasonal demand mismatches ahead of festive quarters. Cocoa bean processing capacity concentrates in Kerala, Karnataka, and Tamil Nadu, with domestic grinding operations drawing from Ivory Coast and Ghana raw bean imports. The supply chain rests on cocoa butter, cocoa powder, and lecithin emulsifier inputs. Single-source vulnerability from West African supply disruptions poses structural risk. Distribution runs through Mondelez and Nestlé's exclusive territory allocations to wholesale intermediaries, with specialty brands bypassing this layer through direct-to-consumer e-commerce partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled conching and tempering technician scarcity constrains artisanal scale-up and mass-market premium migration simultaneously. This capability gap rewards early movers who lock in vocational training pipelines and precision automation investments.
For Market Incumbents: Secure exclusive partnerships with temperature-controlled logistics providers in Uttar Pradesh and Bihar before secondary city modern trade expansion accelerates. Anchor manufacturing scale advantages through backward integration into domestic cocoa grinding capacity under PLI scheme subsidies, while defending against artisanal encroachment by acquiring bean-to-bar craft specialists with established transparency credentials. For New Entrants and Emerging Players: Anchor in Delhi-NCR's corporate gifting corridor where cold-chain gaps have suppressed premium penetration and mass-market operators dominate with undifferentiated assortments. Target health-positioned urban consumers in tier-1 cities seeking 70%+ cocoa solids dark chocolate with plantation traceability. Launch through direct-to-consumer e-commerce channels with QR-linked sourcing transparency to bypass entrenched distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational confectionery parents seeking portfolio rationalization away from non-core geographies. Mid-scale domestic manufacturers with PLI scheme approvals and existing BIS certification infrastructure represent attractive acquisition archetypes over a 5-10 year viability window. Monitor FSSAI fortification guideline enforcement intensity as the signal indicating whether micronutrient compliance investments will consolidate smaller players or create margin expansion for prepared incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Tempering Automation Adoption | Mid-scale Gujarat and Tamil Nadu manufacturers reduce cocoa butter waste while achieving artisanal-quality snap characteristics. |
| Direct-to-Consumer Channel Launch | Specialty brands bypass Mondelez and Nestlé distributor margins through temperature-controlled last-mile partnerships. |
| Single-Origin Dark Chocolate Extension | Bengaluru and Mumbai health-conscious consumers drive adoption of 70%+ cocoa solids products with traceable plantation sourcing. |
| Secondary City Distribution Expansion | Uttar Pradesh and Bihar present underdeveloped per capita consumption with expanding modern trade cold-chain infrastructure. |
| FSSAI Fortification Compliance Investment | Milk chocolate producers targeting institutional channels face steepest reformulation ramps for micronutrient enrichment mandates. |
Study Parameters
A spread of perspectives from chocolate manufacturing executives, specialty retail buyers, cold-chain logistics operators, and FSSAI regulatory consultants converged on the working assumptions driving this analysis. Primary interviews with Mondelez India and Nestlé India distribution heads, Amul cooperative procurement managers, and Bengaluru bean-to-bar founders combined with secondary validation from FSSAI product standards notifications, BIS packaging certification registries, PLI scheme disbursement records, and Maharashtra and Karnataka state-level cold-chain infrastructure investment disclosures. Bottom-up SKU-level demand modeling and top-down macro consumption trend analysis provided triangulation.
Segmentation dimensions modeled across the analysis window include product type by FSSAI cocoa solids thresholds, customer archetype by margin capture potential, distribution channel by tempering integrity requirements, and packaging format by BIS certification compliance burden. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory enforcement intensity and infrastructure rollout timelines. Cocoa butter price volatility indices and specialty retail square footage expansion in tier-1 cities served as industry-specific forecast inputs.
Material uncertainties — cocoa supply disruptions from Ivory Coast and Ghana, FSSAI fortification guideline finalization, and state-level cold-chain subsidy allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and infrastructure investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Chocolate Spread Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Licorice Candy Market
Confectionery
Low Calorie Sweets Market
Confectionery
Green Tea Chocolate Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Confectionery Coating Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Ruby Chocolate Market
Confectionery
Gummy Candy Market
Confectionery
Xylitol Lollipops Market
Confectionery
Confectionery Fillings Market
Confectionery
North America Dark Chocolate Market