
 Aquatic Feed Supplement Market | 2026-2036
Aquatic Feed Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Aquatic Feed Supplement Market Analysis
Aquatic feed supplement distribution through regional cooperatives and farm-gate networks is fragmenting as aquaculture intensifies across coastal zones. Cargill leverages its integrated aquaculture nutrition platform to secure bulk supply agreements with large-scale shrimp operators in Latin America and Southeast Asia. Evonik Industries anchors its position through precision amino acid formulations tailored to species-specific metabolic requirements. Nutriad differentiates via mycotoxin management and gut health solutions that reduce mortality in high-density pond systems.
Aquatic feed supplements comprise biologically active compounds including vitamins, amino acids, lipids, and minerals formulated to enhance growth performance, disease resistance, and feed conversion ratios in farmed fish and shellfish. These formulations typically incorporate fish meal or algae-derived proteins processed through extrusion or cold-pelleting to preserve thermolabile nutrients such as ascorbic acid and certain B-vitamins. Amino acid supplementation commands the largest value share within product type segmentation due to its direct impact on protein synthesis efficiency in carnivorous species like salmon and sea bass. Pellet form dominates volume flows because of mechanical durability requirements in automated feeding systems, though liquid delivery formats gain traction in larval rearing applications where precise dosing proves critical. Algae-based raw materials represent the fastest-expanding input category as manufacturers seek alternatives to finite fish meal supplies and respond to buyer pressure for reduced marine dependency.
Regulatory oversight from EMA feed additive guidelines, FDA Center for Veterinary Medicine approvals, and FAO Code of Conduct for Responsible Fisheries collectively shape product registration pathways and residue monitoring protocols across export-oriented supply chains. REACH compliance and EU Green Deal sustainability criteria increasingly determine market access for suppliers targeting European retail-linked aquaculture producers. Stakeholders must monitor evolving maximum residue limits for heavy metals and persistent organic pollutants in supplement raw materials, as tightening standards in destination markets will force reformulation investments ahead of certification deadlines.
Market Dynamics
The EU Green Deal's sustainability mandates are forcing ingredient reformulation across marine and freshwater production systems, as European retail-linked buyers demand supply chain documentation that traces raw materials to certified sources.
Growth Catalysts
- Intensive shrimp farming in Southeast Asia:High-density pond operations in Indonesia and Vietnam require functional additives to manage disease pressure and optimize feed conversion ratios in black tiger and whiteleg shrimp species.
- REACH compliance requirements:European aquaculture producers must source supplements meeting ECHA chemical safety standards, creating certified-supplier premiums for compliant amino acid and probiotic manufacturers.
- Algae-derived protein processing:Thermostable extraction methods now preserve bioactive compounds through extrusion, enabling substitution of finite fish meal with sustainable marine biomass inputs.
Market Restraints
- Fish meal price volatility:Peruvian anchovy catch fluctuations and El Niño events create input cost instability for traditional marine protein-based supplement formulations.
- Heavy metal residue limits:Tightening FAO Code of Conduct standards for cadmium and mercury in raw materials force costly pre-treatment investments ahead of certification deadlines.
- Probiotic strain stability:Thermolabile bacterial cultures degrade during pelleting above 85°C, limiting viable cell delivery in standard extruded feeds for carnivorous species.
Strategic Opportunities
- Larval rearing liquid formats:Precision dosing systems for hatchery-stage fish and shellfish create premium positioning above commodity pellet volumes in Vietnam and India.
- EU Green Deal farm-to-fork traceability:Blockchain-enabled ingredient documentation commands price premiums from European retailers sourcing ASC-certified farmed salmon and sea bass.
- Integrated nutrition platforms:Full-service contracts combining feed formulation, diagnostic testing, and mortality insurance displace transactional additive sales in Latin American shrimp operations.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning marine biology, thermoprocessing, and regulatory compliance remains concentrated among senior specialists at established nutrition houses.
- Multi-jurisdiction registration timelines:Separate FDA Center for Veterinary Medicine, EMA feed additive, and national veterinary drug approvals extend product launch cycles by 18-36 months for novel functional ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquatic Feed Supplement Market |
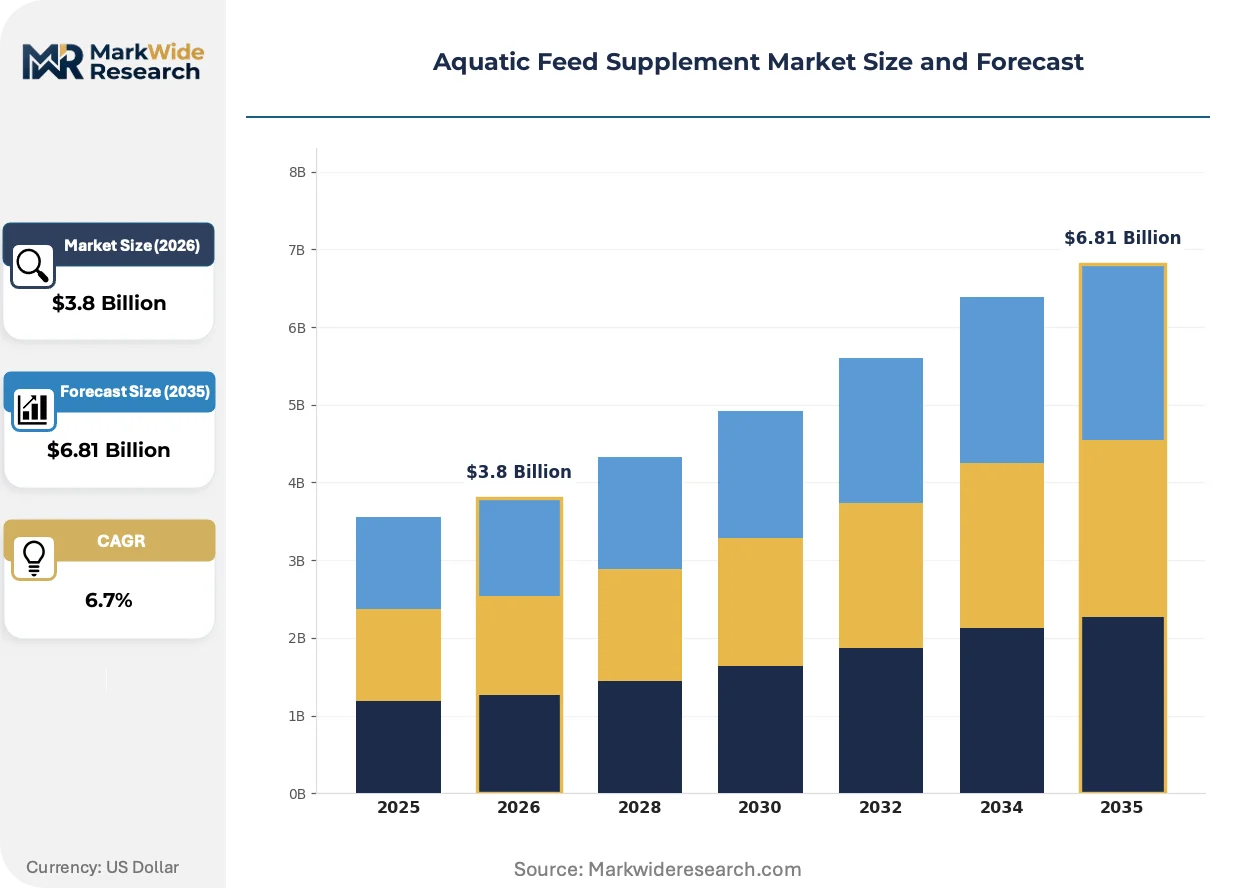
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Amino Acids, Lipids, Minerals Raw Material: Fish Meal, Soybean Meal, Corn Gluten Meal, Algae Form: Pellets, Powder, Granules, Liquid End User: Aquaculture Farms, Research Institutions, Feed Manufacturers, Others |
| Companies Covered | Alltech, Cargill, Kemin Industries, DSM Animal Nutrition, Evonik Industries, Olmix Group, Nutriad, Lallemand, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquatic Feed Supplement Market Emerging Trajectories
Formulation science is pivoting toward species-specific metabolic modeling, while digital tools penetrate farm-level decision systems. Sustainability certification now functions as a market access filter rather than a premium differentiator.
Microencapsulation technology for thermosensitive nutrients is migrating from pharmaceutical applications into aquaculture feed supplements. Hatchery operators in Norway and Chile now specify lipid-coated ascorbic acid and B-vitamin matrices that withstand extrusion temperatures above 120°C. This protection chemistry is compressing mortality differentials between larval-rearing liquid systems and grow-out pellet feeds, enabling single-formulation strategies across production stages.
REACH authorization requirements for novel feed additives are tightening substance documentation obligations across European supply chains. Manufacturers must now submit full toxicological dossiers to ECHA for enzymes and probiotic strains previously grandfathered under transitional provisions. Salmon feed producers in Scotland and Norway are consolidating supplier bases to partners with established registration portfolios, squeezing mid-tier additive houses without dedicated regulatory affairs capacity.
Buyer concentration among integrated shrimp operators is restructuring distribution economics for functional additives. Large-scale Latin American producers now negotiate direct supply agreements with amino acid and probiotic manufacturers, bypassing traditional distributor margins. This disintermediation is most visible in Ecuador and Brazil, where farm-gate networks previously captured 15-20 percent of additive value through technical service bundling that buyers now source separately.
Aquatic Feed Supplement Market Segmentation
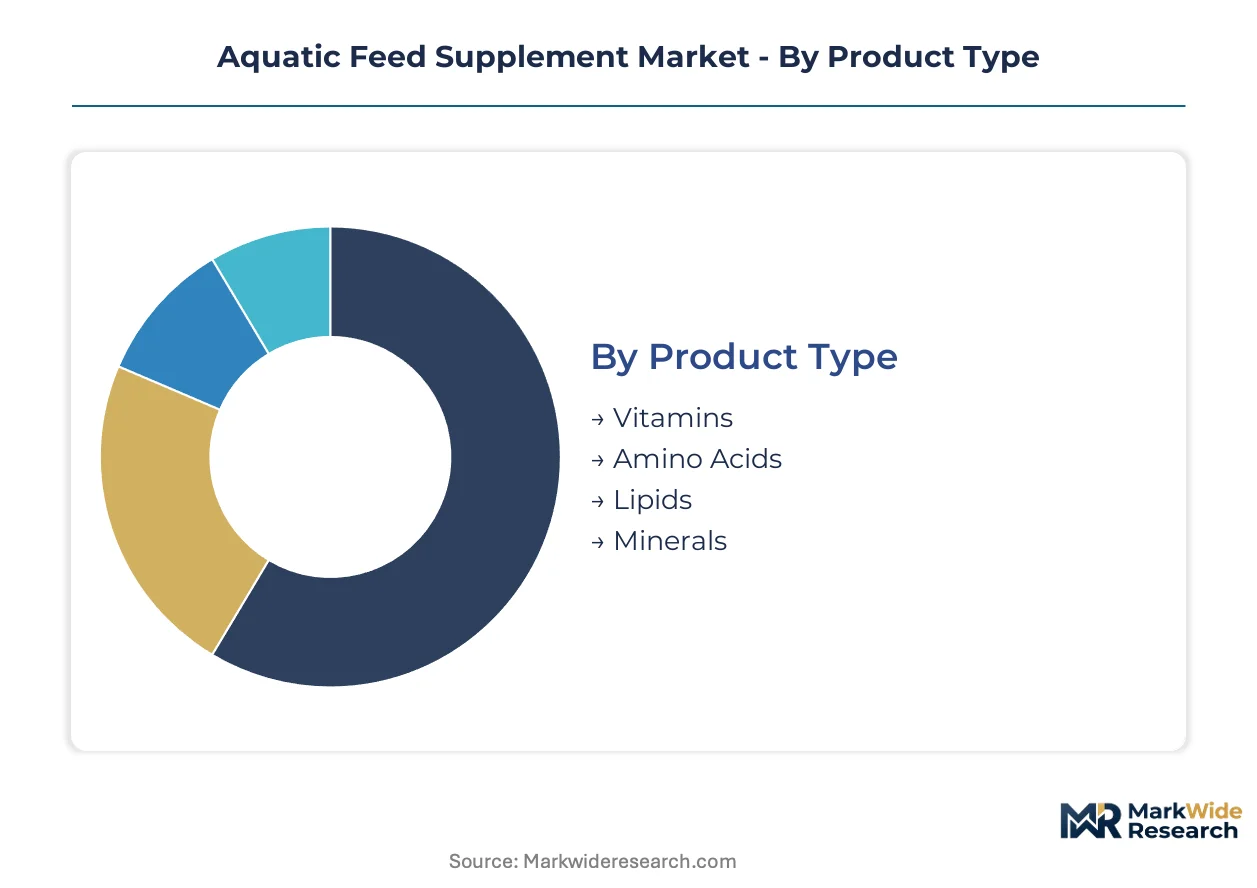
Aquatic feed supplement segmentation reflects divergent technical requirements across production stages, from thermolabile larval nutrients to durable grow-out formulations. Manufacturers configure service intensity around form-factor complexity and species-specific metabolic modeling.
Product Type:
After-sales technical support concentrates disproportionately in amino acid and probiotic categories, where precision dosing and metabolic optimization demand ongoing farm-level consultation.
- Amino Acids:Precision-formulated lysine, methionine, and taurine blends address species-specific protein synthesis gaps in carnivorous finfish. Demand clusters in Norwegian salmon operations and Vietnamese shrimp ponds where feed conversion ratios determine margin survival.
- Vitamins:Thermostable ascorbic acid derivatives and fat-soluble matrices prevent deficiency syndromes in high-density systems. Indonesian black tiger shrimp farms drive volume for water-stable C-vitamin formulations that withstand pond leaching.
- Lipids:Omega-3 enrichment through algae-derived DHA supports neurological development in larval stages.
- Minerals:Chelated trace elements address bioavailability constraints in plant-based diet transitions.
By volume, amino acids lead. By growth pace, vitamin stabilization technologies are ahead.
Raw Material:
Cost tier stratification separates marine-derived inputs from plant and microbial alternatives, with certification premiums widening spreads between commodity and specialty grades.
- Algae:Thermostable extraction methods now preserve bioactive compounds through extrusion temperatures exceeding 120°C. Scottish and Chilean salmon feed producers source algae proteins to satisfy ASC certification requirements and reduce marine dependency.
- Fish Meal:Peruvian anchovy supply fluctuations force formulation hedging strategies across Southeast Asian shrimp operations. Premium grades command supplier loyalty programs from integrated Latin American producers.
- Soybean Meal:Defatted and enzyme-treated variants address anti-nutritional factor concerns in omnivorous species diets.
- Corn Gluten Meal:High-protein byproduct streams from ethanol production supply cost-sensitive freshwater carp operations.
By volume, fish meal leads. By growth pace, algae-derived inputs are expanding most quickly.
Form:
Application context dictates durability requirements, with automated feeding systems demanding mechanical integrity that hatchery precision dosing sacrifices for nutrient preservation.
- Pellets:Extruded and cold-pelleted formats dominate grow-out operations for mechanical durability in pneumatic feeding systems. Vietnamese and Ecuadorian shrimp farms specify sinking pellets with 95%+ water stability over four hours.
- Liquid:Precision micro-dispersion systems enable exact nutrient delivery in larval rearing tanks. Norwegian hatchery operators specify lipid-coated emulsions for first-feeding Atlantic salmon fry.
- Powder:Top-dressing applications for broodstock conditioning and emergency supplementation.
- Granules:Intermediate durability for semi-intensive pond systems with manual feeding protocols.
By volume, pellets lead. By growth pace, liquid formats for hatchery applications are climbing the fastest.
End User:
Customer type determines procurement sophistication, with integrated operations bypassing distributor networks for direct manufacturer relationships.
- Aquaculture Farms:Large-scale shrimp and salmon operators negotiate full-service contracts combining nutrition, diagnostics, and mortality coverage. Indonesian and Indian farm cooperatives consolidate purchasing to extract technical service bundling.
- Feed Manufacturers:Compound feed mills source amino acids and vitamin premixes for in-house formulation. Brazilian and Thai mills specify just-in-time delivery to minimize working capital tied in thermolabile inventories.
- Research Institutions:Universities and government aquaculture stations procure experimental-grade nutrients for controlled trials.
- Others:Ornamental fish breeders and public aquarium facilities represent fragmented specialty demand.
By volume, aquaculture farms lead. By growth pace, integrated feed manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites European import flows of thermolabile amino acid premixes, while Singapore's Tuas Mega Port anchors Southeast Asian distribution networks for Indonesian and Vietnamese shrimp operations.
Indonesia
Black tiger shrimp farms in East Java and Sulawesi drive concentrated demand for water-stable vitamin C formulations and probiotic gut health additives. The country's national feed safety regulator enforces maximum residue limits for heavy metals in imported raw materials under FAO-aligned standards. Surabaya's industrial corridor hosts blending facilities that compound amino acid premixes for distribution through farm-gate cooperatives.
Vietnam
Whiteleg shrimp intensive pond systems in the Mekong Delta require functional additives managing disease pressure in high-density stocking configurations. Ministry of Agriculture and Rural Development protocols mandate veterinary drug residue monitoring across export-oriented supply chains. Can Tho and Bac Lieu provinces concentrate feed mill capacity serving integrated operators negotiating direct manufacturer contracts.
Norway
Atlantic salmon grow-out operations in fjord systems specify algae-derived proteins meeting ASC certification requirements for reduced marine dependency. The Norwegian Food Safety Authority enforces strict documentation obligations for novel feed additives under EEA-aligned REACH implementation. Bergen and Trondheim harbor clusters coordinate cold-chain logistics for thermolabile larval nutrient imports from specialized European suppliers.
Ecuador
Large-scale shrimp producers in Guayas and El Oro provinces negotiate full-service nutrition contracts combining feed formulation with diagnostic testing and mortality coverage. The national aquaculture chamber coordinates compliance documentation for EU retail-linked buyers demanding supply chain traceability. Manta's port infrastructure supports direct bulk amino acid imports that bypass traditional distributor networks.
India
Farm cooperatives in Andhra Pradesh and Gujarat consolidate purchasing power to extract technical service bundling from amino acid and probiotic suppliers. FSSAI feed additive regulations govern import registration and residue monitoring for export-oriented marine and freshwater production. Chennai's industrial zone hosts formulation facilities serving both domestic shrimp operations and Bangladesh cross-border demand.
Aquatic Feed Supplement Market Vendor Landscape
On the supply side, the industry is consolidating around integrated nutrition platforms that displace transactional additive sales through full-service contracts. Tiered competitive dynamics separate multinational compounders with regulatory affairs capacity from regional blenders dependent on licensed formulations. Three archetypes dominate: precision amino acid specialists, mycotoxin management and gut health solution providers, and algae-derived protein processors. Strategic moves center on backward integration into raw material sourcing and geographic expansion through direct supply agreements with large-scale farm operators.
Within the integrated nutrition tier, Cargill and Evonik Industries exemplify divergent positioning strategies. Cargill leverages its Minneapolis-based global supply chain infrastructure to secure bulk agreements with Latin American shrimp operators, while Evonik Industries anchors its Darmstadt-rooted operations through precision amino acid formulations. DSM Animal Nutrition occupies a position bridging specialty and commodity segments, reflecting the Dutch cooperative heritage in feed ingredient consolidation. Kemin Industries represents the Des Moines-based mid-tier archetype focused on functional additive specialization rather than full-platform integration.
| Leading Market Players |
|---|
| Alltech |
| Cargill |
| Kemin Industries |
| DSM Animal Nutrition |
| Evonik Industries |
| Olmix Group |
| Nutriad |
| Lallemand |
| DuPont de Nemours |
| Others |
Supply Flow & Price Mechanics
Peruvian anchovy catch volatility and El Niño disruption cycles determine both pricing tier spreads and supply chain shape across marine protein-dependent supplement formulations. Buyers hedging finite fish meal exposure now stratify procurement across algae-derived alternatives, with certification-grade premiums widening spreads between commodity and specialty raw material tiers.
Pricing Analysis
Volume-discount tiering structures dominate amino acid and probiotic procurement, with integrated Latin American shrimp operators extracting double-digit percentage concessions through direct manufacturer contracts. Three-tier pricing stratification separates ASC-certified algae proteins from standard-grade fish meal and economy-tier plant-based alternatives. Cost compression in commodity marine proteins is intensifying because Peruvian catch variability forces hedging premiums. Feed manufacturers exhibit highest price sensitivity due to working capital constraints on thermolabile inventories, while research institutions show least sensitivity given experimental-grade tolerance.
Supply Chain Analysis
Supplier-financing facilities now extend payment terms to 90-120 days for Indonesian and Vietnamese farm cooperatives, compressing working capital cycles for amino acid premix distributors. Raw material sourcing concentrates in Peru for fish meal, Indonesia for tropical algae biomass, and India for enzyme-treated plant proteins. Formulation chemistry rests on thermostable extraction methods, chelated trace element precursors, and microencapsulation matrices. Single-source vulnerability in Peruvian anchovy supply creates systemic exposure during El Niño events. Distribution runs through Rotterdam's cold-chain infrastructure for European thermolabile imports and Singapore's Tuas Mega Port for Southeast Asian farm-gate networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as algae-derived proteins displace marine-dependent formulations and integrated nutrition platforms displace transactional additive sales.
For Market Incumbents: Harden supply security through backward integration into algae cultivation capacity in Indonesia and Vietnam, while consolidating regulatory affairs capacity to navigate ECHA REACH authorization timelines. Probiotic strain thermostability represents a critical R&D lever against mortality differentials in high-density shrimp systems. Certification investment in ASC and EU Green Deal traceability documentation defends margin position against commodity-grade competitors. For New Entrants and Emerging Players: Mid-tier feed manufacturers in India and Brazil represent the most penetrable entry point, given their working capital constraints and appetite for just-in-time technical service bundling. Larval rearing liquid formats in Norwegian and Chilean hatcheries offer premium positioning above commodity pellet volumes. Go-to-market execution should center on precision micro-dispersion systems with diagnostic testing partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory affairs-capable mid-tier specialists with established EMA and FDA registration portfolios. Long-term viability hinges on backward integration into sustainable raw material sourcing and platform-style service bundling. Watch for inflection signals in EU Green Deal certification adoption rates among Scottish and Norwegian salmon producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algae Cultivation | Captures ASC certification premiums and reduces Peruvian anchovy dependency. |
| REACH Authorization Portfolio Expansion | Secures market access for novel enzymes and probiotic strains across EEA-aligned markets. |
| Integrated Nutrition Platform Launch | Combines feed formulation, diagnostic testing, and mortality coverage to displace transactional sales. |
| Larval Liquid Format Capacity Buildout | Targets Norwegian and Chilean hatchery demand for precision-dosed thermolabile nutrients. |
| Blockchain Traceability Implementation | Commands EU retail-linked premiums through farm-to-fork documentation for ASC-certified salmon. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aquaculture farm managers, compound feed mill procurement leads, regulatory affairs directors at nutrition houses, and hatchery operations specialists. Secondary validation drew from EMA feed additive guidelines, FDA Center for Veterinary Medicine approvals, FAO Code of Conduct documentation, customs trade data on amino acid premix flows, and SEC filings of listed nutrition companies. Bottom-up volume modeling across species-specific consumption rates triangulated with top-down value estimates from regional production data.
Calibration against historical price series for fish meal and algae protein inputs anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, raw material source, form factor, and end-user procurement sophistication, with species-specific metabolic requirements as an industry-specific overlay. CAGRs were derived from regression analysis of input cost trajectories and elasticity-adjusted demand responses. Forecast inputs incorporated El Niño frequency patterns and EU Green Deal implementation timelines.
Stress conditions across Peruvian anchovy supply disruption, REACH authorization delays, and probiotic strain thermostability thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on certification adoption rates and integrated platform penetration. Macroeconomic volatility, regulatory acceleration, or breakthroughs in microbial protein cultivation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Krill Oil Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Australia Protein Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Spain Whey Protein Market