
 Spicy Sticks (Chinese Snack) Market | 2026-2036
Spicy Sticks (Chinese Snack) Market Size, Share, and Industry Trends Forecast 2026-2036
Spicy Sticks (Chinese Snack) Market Insights
Young urban professionals are rotating into the core buyer base for spicy sticks as traditional school-age consumers face demographic headwinds. Weilong Food leverages its vertically integrated production base in Henan to control raw material costs across chili and wheat supply chains. Dali Foods Group sustains national distribution density through its established beverage and snack logistics network that reaches county-level retail. Want Want China Holdings Limited anchors shelf presence with brand recognition built through decades of packaged snack marketing.
Spicy sticks are extruded or pressed wheat, rice, or starch-based snacks coated with chili oil, Sichuan pepper extract, and flavoring agents, typically shelf-stable for six to twelve months and consumed as impulse purchases or social sharing items. The product type dimension shows noodle sticks occupying the largest volume share due to texture familiarity, while rice sticks are gaining traction among consumers seeking cleaner ingredient labels. Within flavor profile, spicy and sweet & spicy variants command the widest distribution, though garlic-positioned products are carving out premium placement in convenience channels. Stand-up pouches dominate packaging type as resealable formats extend consumption occasions beyond single-serve impulse buys.
China's SAMR enforces GB standards on food additive limits and labeling accuracy that directly shape formulation decisions and packaging claims for domestic spicy stick producers. The country's MEE guidelines on wastewater and emissions from food manufacturing facilities are raising compliance costs for mid-sized extrusion operations. Stakeholders must monitor how evolving FSSAI-equivalent import standards in target export markets will reshape product certification requirements for Chinese manufacturers seeking overseas distribution.
Market Dynamics
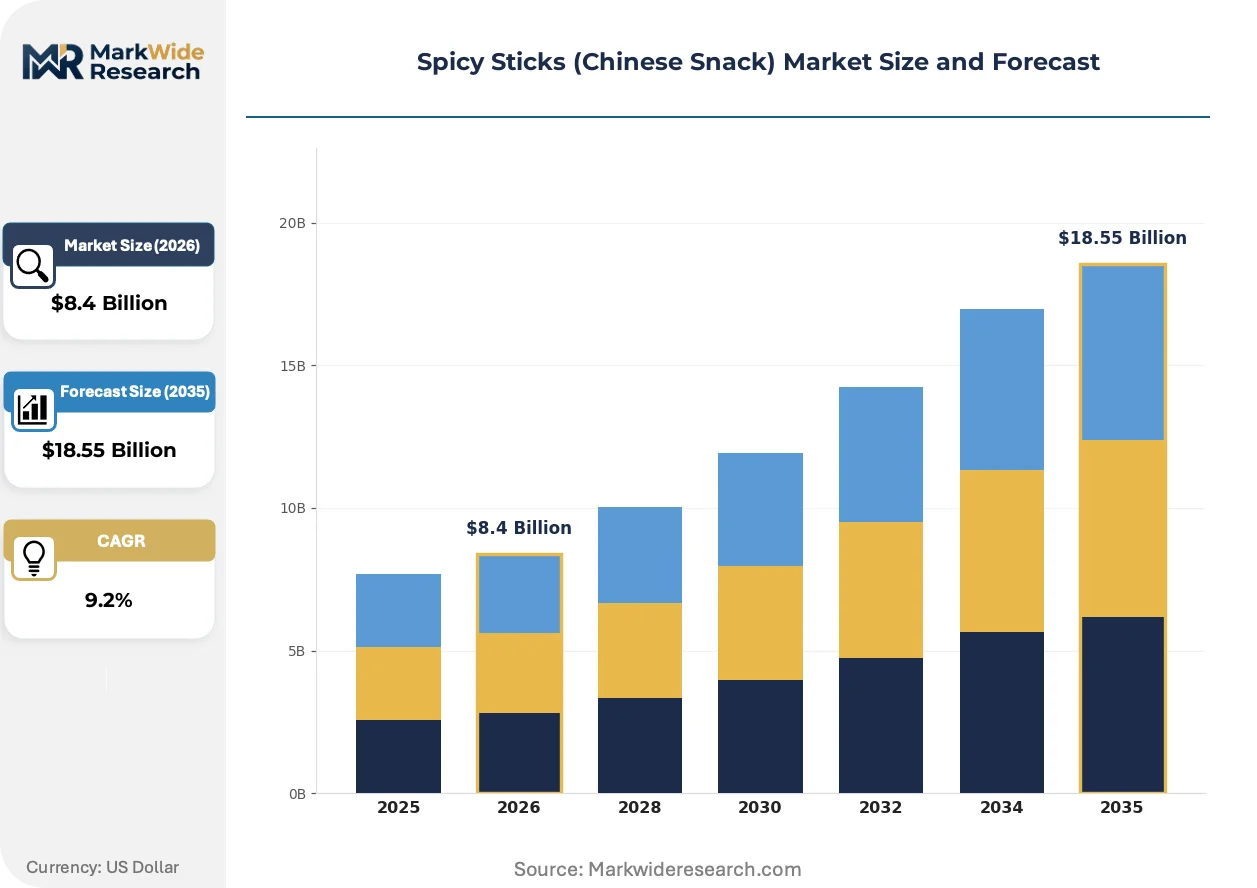
China's SAMR enforcement of GB standards on food additive transparency and labeling accuracy is compressing formulation flexibility while forcing mid-sized extrusion operations toward consolidated production bases. This regulatory tightening intersects with convenience store chains expanding shelf space for resealable pouch formats.
Growth Catalysts
- Henan Province production clustering:Vertically integrated wheat and chili supply chains in this central China hub reduce raw material cost volatility for extrusion-based snack manufacturing.
- GB standard compliance infrastructure:China's SAMR labeling mandates are accelerating shelf-space consolidation toward producers with in-house certification capabilities.
- Extrusion technology advancement:Twin-screw extrusion systems enable texture precision that supports rice-stick variants targeting cleaner-label consumer segments.
Market Restraints
- Chili oil input cost volatility:Sichuan pepper and chili commodity prices fluctuate with regional harvest conditions, squeezing margin structures for non-integrated producers.
- Wastewater compliance burden:China's MEE emissions guidelines raise capital requirements for extrusion facility upgrades, disproportionately affecting mid-cap operations.
- Demographic headwinds in core segment:Declining school-age population in tier-three cities threatens volume foundation of traditional impulse-buy channels.
Strategic Opportunities
- County-level convenience penetration:Offline retail networks in China's tier-two and tier-three cities remain underdeveloped for premium-positioned spicy stick assortments.
- Export certification alignment:FSSAI-equivalent standards in target South Asian markets create first-mover advantages for Chinese manufacturers achieving dual compliance.
- Social sharing format innovation:Resealable stand-up pouches extend consumption occasions beyond single-serve impulse purchases into home pantry rotation.
Industry Challenges
- Formulation talent scarcity:Food science expertise in Sichuan pepper extract stabilization and shelf-life extension concentrates among established producers.
- Legacy distribution integration:Beverage-and-snack logistics networks require SKU complexity management that conflicts with spicy stick seasonal demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spicy Sticks (Chinese Snack) Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seasame Sticks, Chili Sticks, Noodle Sticks, Rice Sticks Flavor Profile: Spicy, Sweet & Spicy, Savory, Garlic Ingredient Type: Vegetarian, Non-Vegetarian, Gluten-Free, Organic Packaging Type: Stand-Up Pouches, Tins, Boxes, Plastic Bags |
| Companies Covered | Weilong Food, Dali Foods Group, Want Want China Holdings Limited, Qiushi Group, Tong Garden, Baixiang Food Group, Laiyifen, Qiaqia, Three Squirrels, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spicy Sticks (Chinese Snack) Market Trends and Innovations
Extrusion precision technology and regulatory transparency mandates are converging to reshape competitive positioning in China's spicy stick segment. These forces are compressing the viable producer base while opening white space for certified clean-label entrants.
High-pressure extrusion systems with real-time moisture control are miniaturizing production footprints for regional manufacturers. Tier-two city processors adopt these compact lines to achieve texture consistency previously requiring large-scale Henan-based facilities. This technology diffusion is fragmenting supply concentration while raising quality baselines across county-level production.
China's SAMR is tightening GB 2760 food additive limits and mandating front-of-pack disclosure for chili oil content. The industrial consequence is reformulation toward natural Sichuan pepper extracts and compressed ingredient decks. Premium-positioned rice-stick variants face the steepest compliance timelines due to cleaner-label consumer expectations.
Young urban professionals are displacing school-age consumers as the core buyer cohort through social-media-driven discovery and pantry-stocking behavior. Convenience store chains respond by expanding resealable pouch facings and cross-merchandising with beverage sets. This demand rotation concentrates in Chengdu and Chongqing where spicy flavor preference anchors category trial rates.
Spicy Sticks (Chinese Snack) Market Segmentation
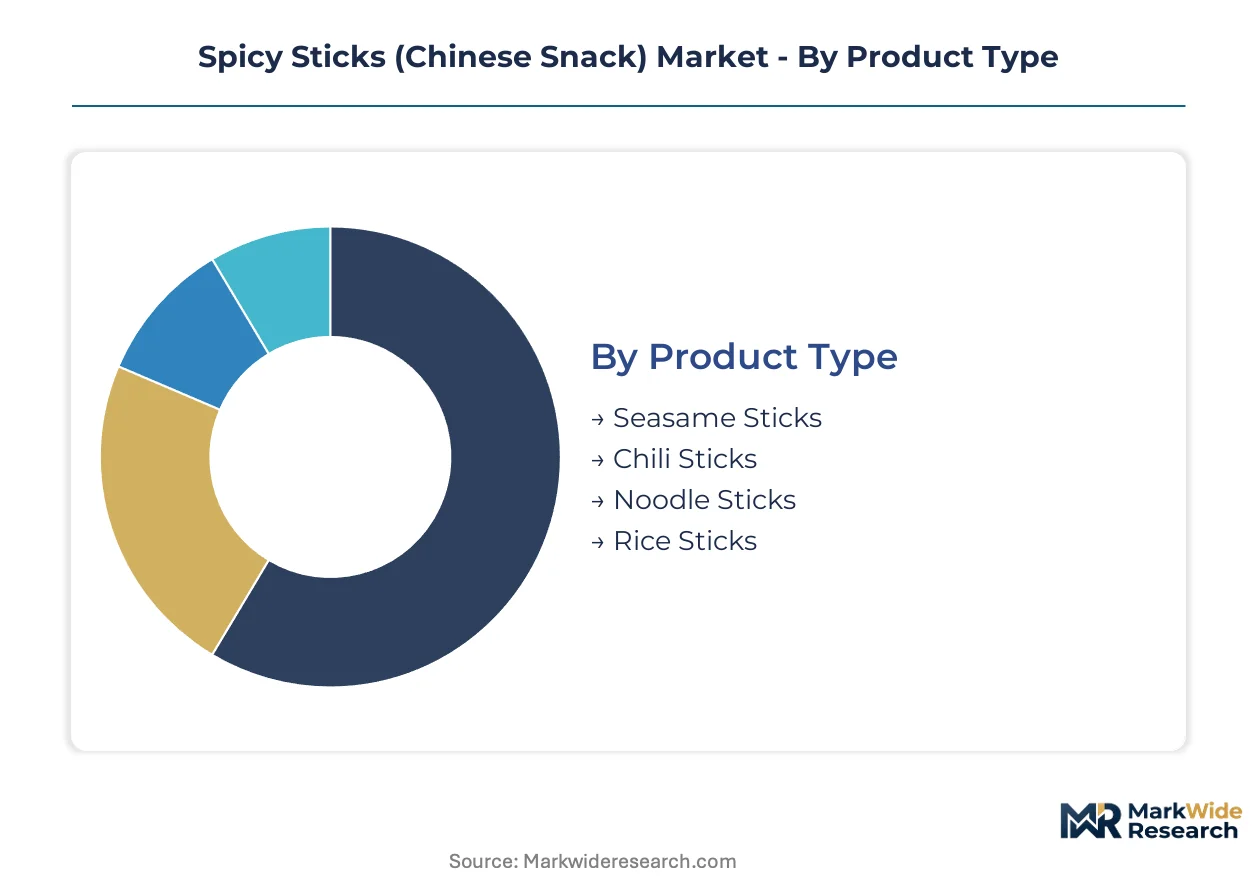
Spicy stick producers allocate R&D and shelf-space investments based on texture format and flavor positioning. Segment boundaries are blurring as extrusion technology enables hybrid products combining multiple ingredient bases.
Product Type:
Noodle sticks command the deepest margin pools due to established wheat supply contracts and automation amortization across high-volume lines.
- Noodle Sticks:Extruded wheat-based strips with alkaline processing create the chewy texture consumers associate with traditional latiao. Demand concentrates in Henan and Shandong province convenience networks where wheat supply chain density supports cost-competitive production.
- Rice Sticks:Milled rice flour extrusion yields a lighter, crisper bite profile that appeals to label-conscious buyers in Chengdu and Chongqing urban convenience channels. Cleaner ingredient decks attract young professional pantry-stocking behavior despite 15-20% raw material premiums over wheat.
- Chili Sticks:Chili powder-infused dough extrusion creates intense heat concentration in smaller formats popular in Sichuan province impulse channels.
- Seasame Sticks:Sesame seed coating adds fat content and nutty flavor modulation for premium-positioned gift assortments in tier-one city supermarkets.
Noodle sticks hold installed capacity. Rice sticks are rotating up the share rankings.
Flavor Profile:
Flavor innovation drives shelf rotation velocity and commands disproportionate trade marketing spend from manufacturers seeking trial conversion.
- Spicy:Chili oil and Sichuan peppercorn extract formulations dominate volume through familiarity and physiological craving mechanisms. Chengdu and Chongqing convenience stores allocate double facings to classic spicy variants versus other flavor positions.
- Sweet & Spicy:Sugar-chili balance broadens appeal to younger demographics and non-traditional markets where pure heat tolerance is lower. This profile is gaining fastest in eastern coastal city convenience chains cross-merchandised with milk tea sets.
- Savory:Reduced sugar, umami-forward formulations target health-positioned snacking occasions in tier-two city supermarkets.
- Garlic:Pungent aromatic positioning creates distinctiveness for premium private label programs in high-traffic convenience locations.
Spicy flavor holds installed capacity. Sweet & Spicy is rotating up the share rankings.
Ingredient Type:
Certification costs and ingredient sourcing complexity create tiered margin structures that separate integrated producers from contract manufacturers.
- Vegetarian:Wheat and starch-based formulations without animal-derived flavor enhancers satisfy the largest addressable base. SAMR GB standard compliance is straightforward, keeping certification overhead minimal for mass-market positioning.
- Gluten-Free:Rice, corn, and alternative starch extrusion requires dedicated production lines and allergen segregation protocols. Demand concentrates in Shanghai and Beijing premium supermarket channels where dietary restriction awareness is highest.
- Organic:Certified organic wheat and chili sourcing limits supplier pools and extends procurement lead times. Tier-one city gift box channels absorb the 40-60% cost premium for clean-label positioning.
- Non-Vegetarian:Chicken or pork extract flavoring creates regional taste differentiation in specific provincial markets with strong meat-forward culinary traditions.
Vegetarian formulations hold installed capacity. Gluten-Free is rotating up the share rankings.
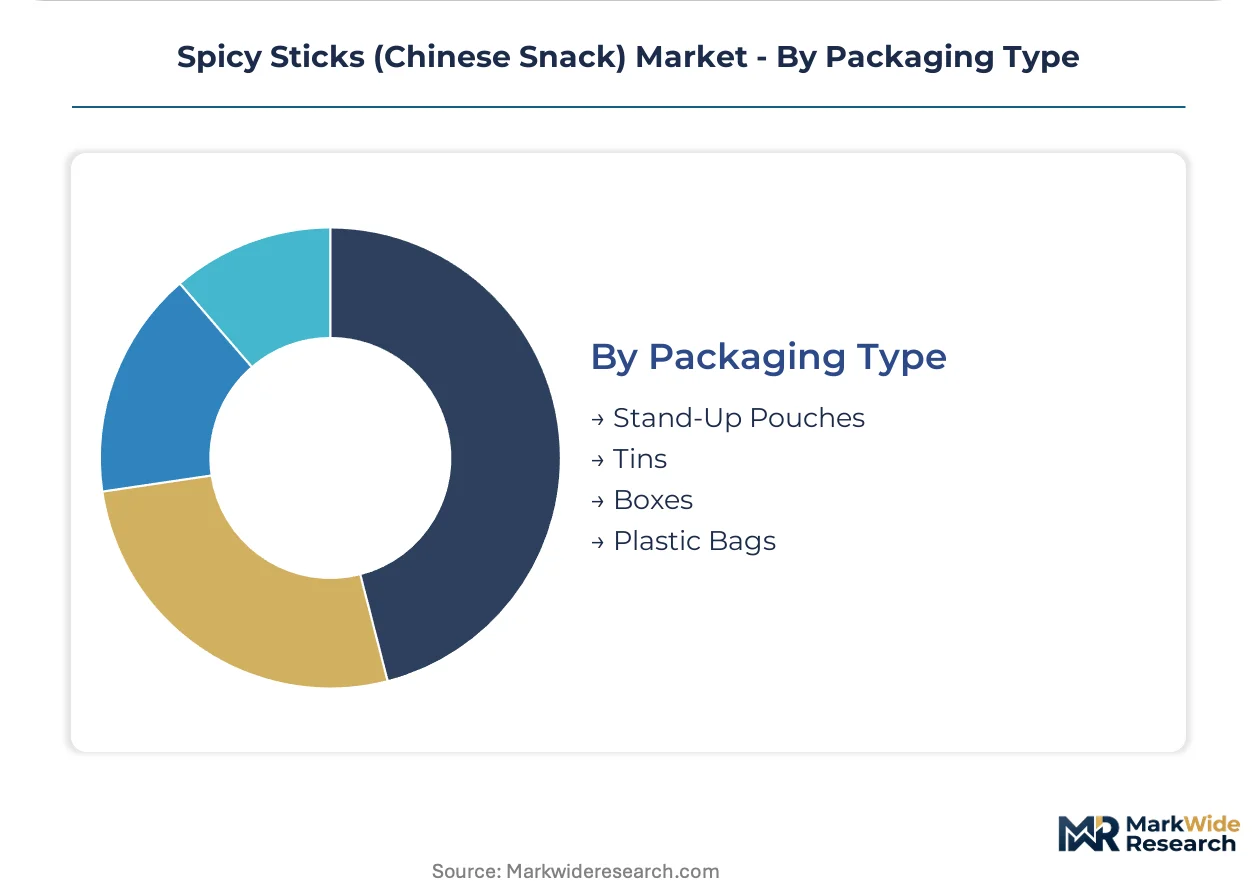
Packaging Type:
Packaging format selection directly determines distribution channel compatibility and consumption occasion expansion potential.
- Stand-Up Pouches:Resealable zipper and high-barrier film structures extend shelf life and enable multi-serve pantry stocking. Convenience store chains are expanding facings for this format as young professionals replace single-serve impulse buying with planned repeat consumption.
- Plastic Bags:Simple polyethylene or laminated structures dominate traditional school-proximate retail and price-sensitive county-level distribution. Volume remains substantial but trade marketing support is shifting toward resealable alternatives.
- Boxes:Rigid paperboard formats support gift set positioning and e-commerce shipping durability for premium assortments.
- Tins:Metal canister packaging creates collectible and premium gifting presence in festival-season retail programs.
Plastic bags hold installed capacity. Stand-Up Pouches are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese spicy stick exports flow primarily to Southeast Asian diaspora communities and North American Asian grocery channels, with secondary volumes reaching European specialty retailers and Middle Eastern convenience distributors.
China
Henan Province hosts the densest concentration of extrusion facilities, with Zhengzhou and Luohe city clusters integrating wheat milling, chili processing, and packaging operations under single ownership. SAMR's GB 2760 additive limits are forcing reformulation investments among mid-sized producers. Chengdu and Chongqing anchor premium flavor innovation, where Sichuan pepper extract specialists supply concentrated extracts to national brands.
Vietnam
Border province retailers in Lang Son and Quang Ninh stock Chinese-origin spicy sticks through informal cross-border trade channels, with Hanoi and Ho Chi Minh City convenience chains testing formal import arrangements. The country's national food safety regulator maintains vigilance on chili oil additive declarations. Da Nang's emerging snack distribution hub is consolidating regional procurement for central province retail networks.
United States
California and New York metropolitan area Asian grocery chains allocate expanding shelf space to resealable pouch formats targeting young professional pantry stocking. FDA enforcement of allergen labeling and facility registration shapes import compliance costs for Chinese manufacturers. Los Angeles County's San Gabriel Valley retail corridor concentrates the highest per-capita spicy stick consumption outside Asia.
South Korea
Seoul Capital Area convenience stores stock Chinese spicy sticks as cross-category traffic drivers alongside domestic tteokbokki snacks, with Busan-Ulsan port facilities handling bulk import consolidation. MFDS maintains strict caps on capsaicin extract concentrations and synthetic color additive usage. Incheon's free economic zone warehouses are developing dedicated ambient snack storage capacity for Chinese import distributors.
Thailand
Bangkok metropolitan convenience chains are trialing Chinese spicy stick placements in university-proximate locations, with Chiang Mai and Phuket tourist retail channels absorbing gift-format volumes. The Thai Food and Drug Administration aligns additive standards with ASEAN harmonization protocols. Rayong Province's eastern seaboard logistics parks are attracting Chinese snack distributors seeking regional ASEAN distribution hubs.
Spicy Sticks (Chinese Snack) Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and county-level distribution density. The market structure shows moderate consolidation, with three to five national brands commanding convenience store shelf space while dozens of regional extrusion operations serve price-sensitive county markets. Strategic archetypes include vertically integrated agribusiness conglomerates, regional extrusion specialists with captive wheat supply, and snack-platform brands leveraging e-commerce discovery. Dominant competitive moves involve backward integration into chili and wheat supply chains, plus format innovation in resealable packaging.
Within the listed-company tier, Want Want China Holdings Limited and Dali Foods Group exemplify scale-driven positioning through diversified snack-and-beverage portfolios that share logistics infrastructure. Weilong Food occupies a position as a private specialist archetype, with geographic naming suggesting Henan-based production clustering. These three entities represent the competitive spectrum from conglomerate diversification to focused category depth.
| Leading Market Players |
|---|
| Weilong Food |
| Dali Foods Group |
| Want Want China Holdings Limited |
| Qiushi Group |
| Tong Garden |
| Baixiang Food Group |
| Laiyifen |
| Qiaqia |
| Three Squirrels |
| Others |
Pricing and Supply Chain Analysis
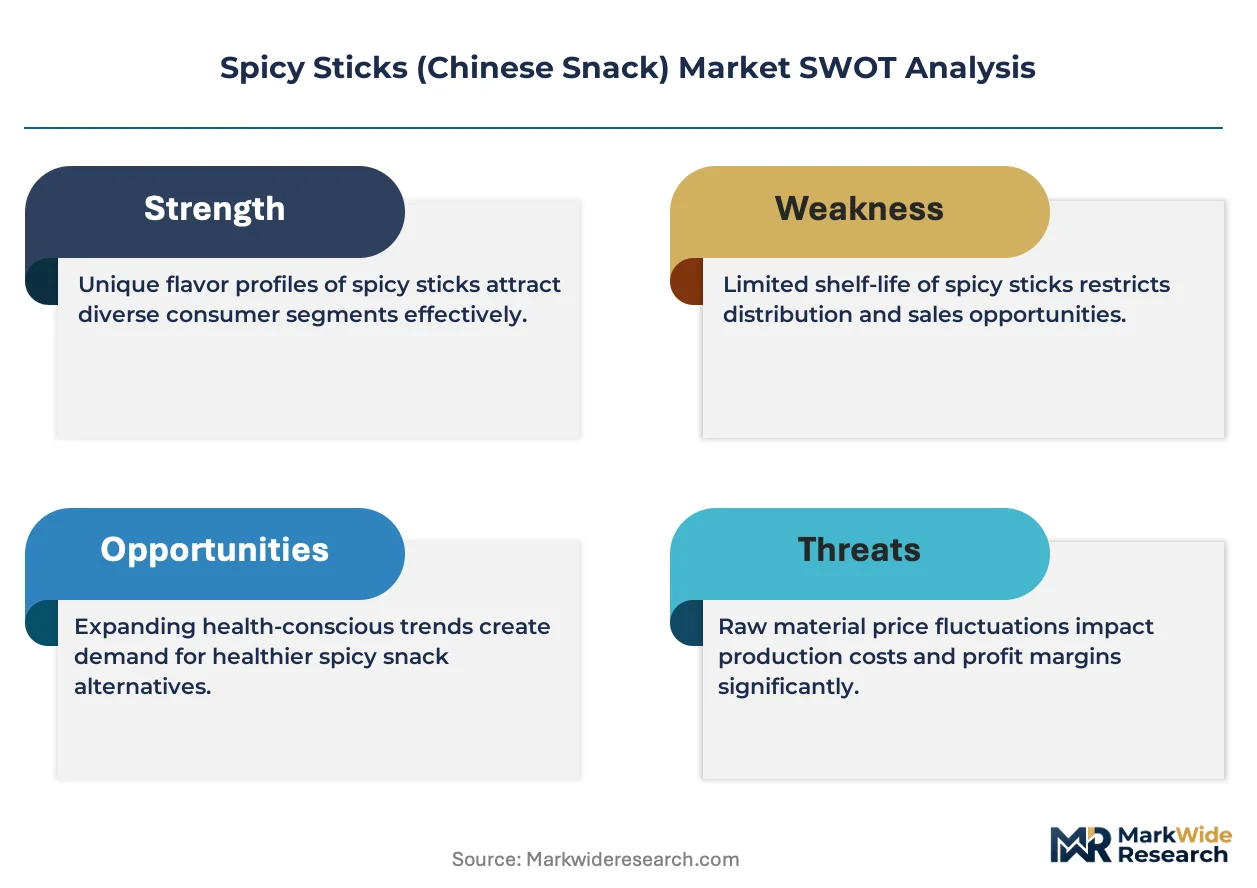
Ninety-day chili oil procurement cycles concentrate pricing power among Henan-based producers with captive wheat milling operations, while non-integrated extruders absorb raw material volatility that compresses margin structures at the county distribution tier. SAMR's GB 2760 compliance timelines add certification cost layers that widen spreads between certified clean-label SKUs and conventional plastic-bag formats in tier-three retail channels.
Pricing Analysis
Single-screw versus twin-screw extrusion technology gaps create three-tier pricing structure across premium, standard, and economy levels, with rice-stick variants commanding 15-20% raw material premiums over wheat-based noodle sticks due to cleaner-label positioning. Price differentiation hinges on SAMR certification tier and volume scale, with integrated Henan producers least exposed to chili commodity swings. Pricing pressure stems from Sichuan pepper extract cost volatility that squeezes mid-cap operations lacking backward integration into upstream supply. School-proximate retail channels show highest price sensitivity, while young professional pantry-stocking segments absorb resealable pouch premiums.
Supply Chain Analysis
Strategic stockpiling of chili powder and Sichuan peppercorn dominates inventory strategy among Henan extrusion clusters, insulating against harvest-season price spikes that disrupt just-in-time procurement at smaller regional facilities. Supply concentrates in China, with secondary sourcing from Vietnam and Thailand for specialty chili varietals. Raw material dependencies center on wheat flour, chili oil, and Sichuan pepper extract, with distribution running through beverage-and-snack logistics networks that reach county-level retail. Single-source vulnerability to Henan production clustering creates geographic concentration risk if MEE wastewater compliance forces facility consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market cycles with school-age demographic troughs and recoveries tied to young professional cohort expansion into pantry-stocking behavior, creating demand rotation rather than net contraction across the analysis window.
For Market Incumbents: Shield installed convenience store shelf space by accelerating SAMR GB 2760 certification coverage ahead of mid-cap competitor compliance timelines, and anchor county-level distribution density through exclusive supply agreements with beverage logistics networks that resist SKU complexity from seasonal demand spikes. For New Entrants and Emerging Players: Lead with rice-stick format innovation targeting Chengdu and Chongqing urban convenience channels where cleaner-label premiums absorb raw material cost structures, and penetrate county-level tier-two cities through compact twin-screw extrusion lines that bypass Henan production clustering barriers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because SAMR regulatory tightening and MEE compliance costs will compress the viable producer base toward integrated agribusiness conglomerates with captive wheat and chili supply chains; watch for inflection when county-level distribution networks show accelerating shelf-space consolidation toward three to five national brands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chili Supply | Captive Sichuan peppercorn sourcing insulates margin structures from harvest volatility. |
| SAMR GB 2760 Certification Investment | Accelerated compliance timelines capture shelf space from lagging mid-cap competitors. |
| Resealable Pouch Format Expansion | Stand-up pouch facings extend consumption occasions into young professional pantry rotation. |
| County-Level Distribution Partnership | Beverage logistics network access penetrates underdeveloped tier-two and tier-three retail channels. |
| Rice-Stick Production Line Addition | Twin-screw extrusion capability captures cleaner-label premium positioning in Chengdu and Chongqing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, customs trade records, and retail audit data from Nielsen and Circana, drawing from interviews with extrusion plant managers, convenience chain category buyers, chili supply procurement leads, and food science formulation directors. Bottom-up facility capacity assessments triangulate against top-down consumption pattern analysis across the projection horizon.
Segmentation dimensions modeled include product type, flavor profile, ingredient certification tier, and packaging format, with analytical frameworks projecting volume and value outputs across the modeling period. CAGRs derive from historical trajectory analysis adjusted for regulatory compliance cost absorption and demographic cohort rotation effects, incorporating chili commodity price cycle assumptions and extrusion technology diffusion rates.
Forecasts assume regulatory continuity in China's SAMR enforcement of GB standards and MEE emissions guidelines; material policy shifts would require re-modeling. Revision becomes warranted when school-age population decline rates or young professional pantry-stocking adoption crosses thresholds that alter channel mix assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Qatar Potato Chips Market
Snacks
Energy Balls Market
Snacks
Corn Chips Market
Snacks
Packaged Rice Snacks Market
Snacks
Kids Snacks Market
Snacks
North America Snack Food Market
Snacks
Organic Snack Food Market
Snacks
Baked Chips Market
Snacks
Fried Potato Chips Market
Snacks
Meat Protein Chips Market
Snacks
UAE Snack Bar Market
Snacks
South America Frozen Snacks Market
Snacks
Low-Calorie Sweet Treats Market
Snacks
Middle East and Africa Snack Food Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
North America Baked Chips Market