
 Low Calorie Nutella Market | 2026-2036
Low Calorie Nutella Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Nutella Market Analytics
The low calorie spread category is pivoting between artisan hazelnut recipes and mass-market cocoa-flavored lines. Ferrero Group leverages its Italian sourcing network to sustain premium positioning. Mondelēz International competes through manufacturing scale across European retail. J.M. Smucker Company anchors North American distribution with health-focused branding.
Low calorie Nutella denotes a reduced-sugar chocolate-hazelnut spread typically containing 30-50% less sucrose than standard formulations, achieved through polyol sweeteners or fiber enrichment. The product serves weight-management and glycemic-control use cases in household and foodservice settings. Spread formats dominate volume while dairy-free formulations capture the fastest margin expansion. Health food stores and specialty shops concentrate premium pricing power for gluten-free variants.
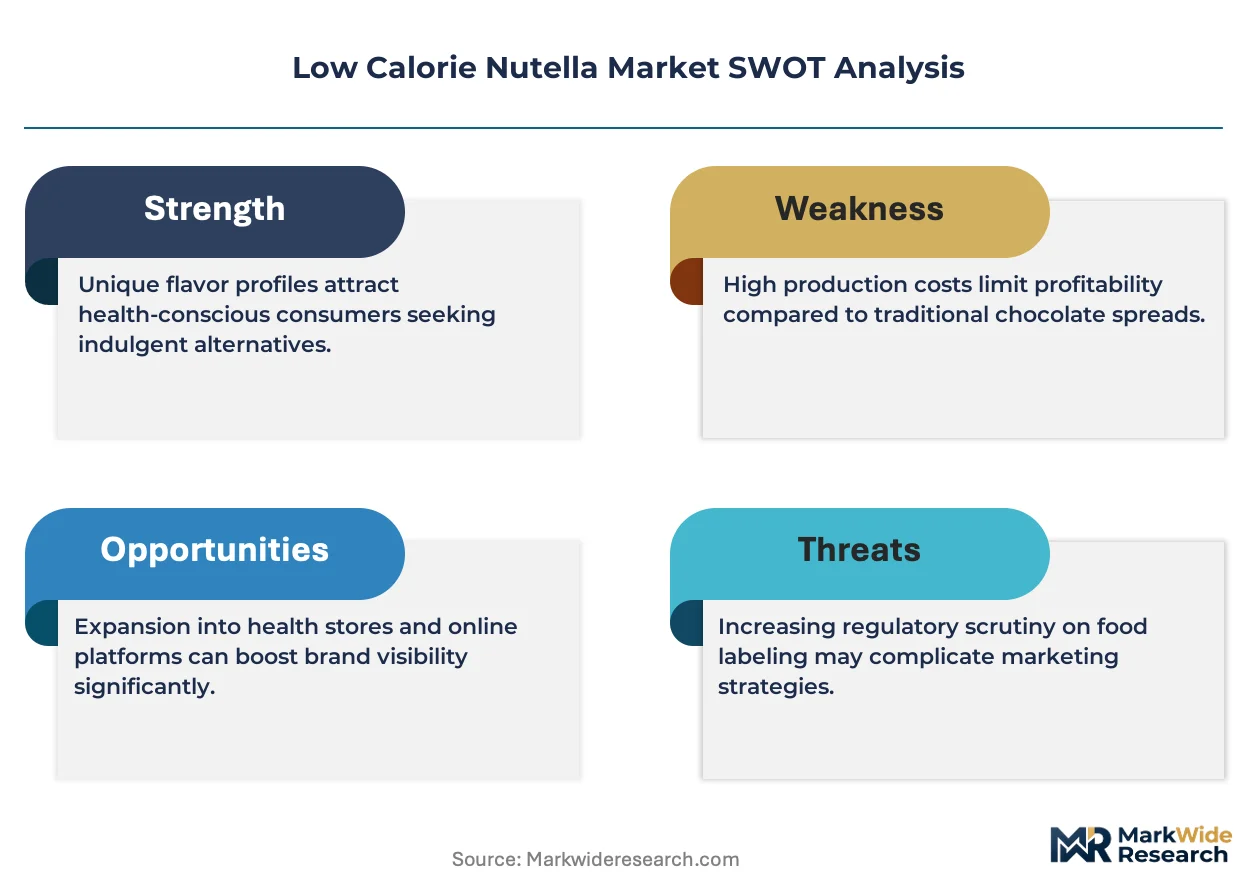
EFSA front-of-pack nutrition labeling and EU sugar-reduction targets reshape formulation requirements across member states. FDA serving-size rules and added-sugar disclosure in the US force label transparency that redirects R&D spending. Stakeholders must monitor evolving sweetener approvals and clean-label certification thresholds to align portfolio decisions with regulatory trajectories.
Market Dynamics
EU sugar-reduction mandates and EFSA front-of-pack labeling rules are forcing reformulation across the chocolate-hazelnut spread category, compressing R&D timelines and redirecting capital toward clean-label polyol systems and fiber enrichment technologies.
Growth Catalysts
- EFSA Nutrition Labeling:Front-of-pack color-coded schemes accelerate consumer shift toward reduced-sugar variants in German and French retail channels.
- Hazelnut Sourcing Concentration:Italian and Turkish cultivation clusters enable premium positioning through provenance storytelling and supply traceability.
- Polyol Sweetener Approvals:Erythritol and allulose regulatory clearances expand formulation flexibility for glycemic-control product lines.
Market Restraints
- Raw Material Volatility:Hazelnut price swings in Turkey's Black Sea region compress margin stability for spread manufacturers.
- Supply Concentration Risk:Overreliance on Italian confectionery equipment suppliers creates bottleneck vulnerability for new market entrants.
- Technical Limitation:Polyol-induced cooling aftertaste caps consumer acceptance at 40-50% sugar reduction thresholds.
Strategic Opportunities
- Underpenetrated Markets:Poland and Czech Republic specialty retail channels show latent demand for premium reduced-sugar spreads.
- Regulatory Tailwind:EU Green Deal farm-to-fork targets incentivize clean-label certification investments across member states.
- Channel Innovation:Direct-to-subscription models bypass traditional retail slotting fees and capture recurring revenue pools.
Industry Challenges
- Reformulation Expertise Gap:Shortage of food technologists skilled in polyol-hazelnut emulsion stability slows product pipeline velocity.
- Clean-Label Certification Timelines:Organic and non-GMO verification processes extend time-to-market by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Nutella Market |
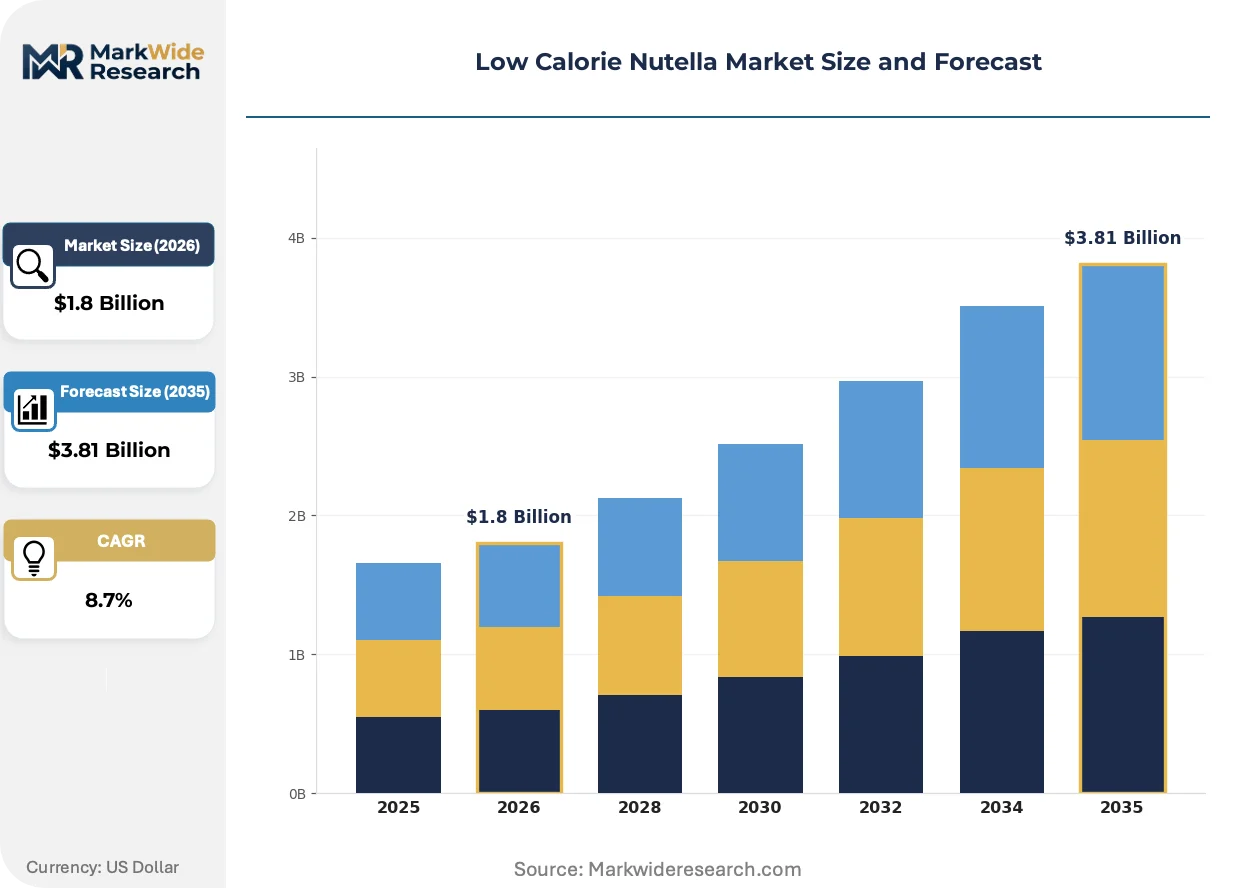
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syrup, Spread, Snack, Dessert Formulation: Hazelnut-Based, Cocoa-Flavored, Dairy-Free, Gluten-Free Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Consumer Type: Health-Conscious Consumers, Diabetics, Fitness Enthusiasts, Parents |
| Companies Covered | Mondelēz International, Hormel Foods Corporation, Ferrero Group, Rigoni di Asiago, Andros Group, The Hershey Company, Dr. Oetker, Barefoot & Chocolate, J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Nutella Market Evolving Landscape
Reformulation chemistry and packaging transparency are converging to redefine competitive advantage in reduced-sugar spreads, with sensory science and regulatory compliance emerging as the twin pillars of product development.
Allulose-based sweetening systems are overtaking traditional maltitol formulations in premium spread applications. Health-conscious households in Germany and the Netherlands are adopting these variants at accelerating rates. This shift is compressing shelf space allocation for legacy polyol products in continental European supermarkets.
EFSA's evolving guidance on novel food ingredients is tightening approval pathways for emerging sweeteners across EU member states. Manufacturers face extended safety dossier requirements and toxicology study obligations. Smaller brands without dedicated regulatory affairs teams are retreating to established ingredient portfolios.
Subscription-based replenishment models are disrupting conventional grocery purchasing for household spread categories. Direct-to-consumer channels in urban UK and French markets are capturing repeat purchase loyalty through personalized flavor profiles. This behavioral pivot is fragmenting volume concentration away from hypermarket dominance toward curated delivery ecosystems.
Low Calorie Nutella Market Segmentation
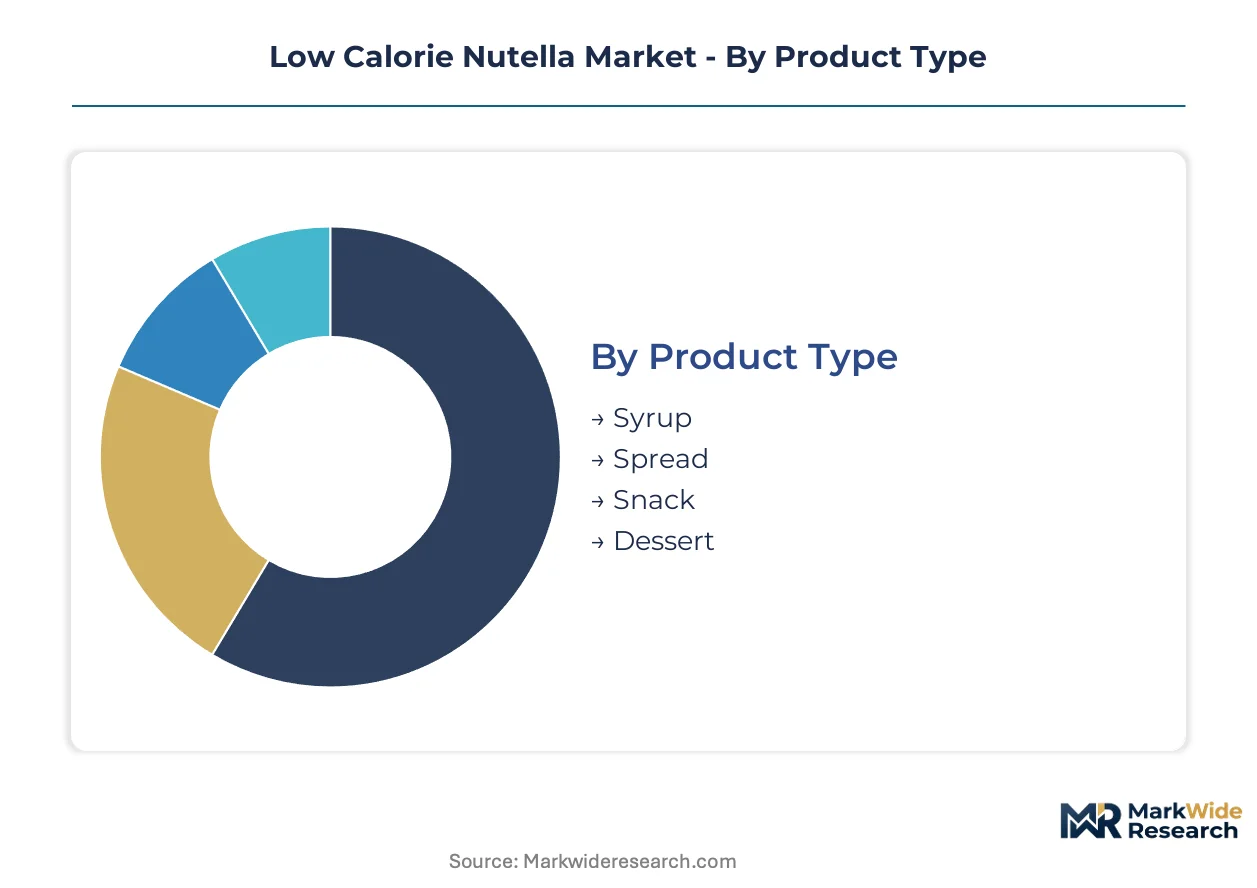
Segmentation in reduced-sugar chocolate-hazelnut spreads reveals how formulation chemistry and channel strategy fragment commercial opportunity. Manufacturers must align product architecture with distinct glycemic-control needs and retail format economics.
Product Type:
Standardization dominates commodity formats while premium tiers demand bespoke viscosity and mouthfeel engineering.
- Spread:Viscous emulsion of roasted hazelnuts, defatted cocoa, and erythritol syrup achieving spoonable texture at 30-40% sugar reduction. German and French supermarket chains allocate expanding shelf facings to polyol-stabilized variants as EFSA color-coded labels redirect basket composition. Technical limitation: polyol crystallization above 50% sugar replacement degrades spreadability.
- Syrup:Pourable reduced-sugar formulation optimized for beverage and dessert topping applications. Coffee shop chains in urban UK markets are standardizing allulose-sweetened hazelnut syrups for glycemic-conscious menu engineering. Supply constraint: allulose import quotas limit European formulation scale.
- Snack:Portion-controlled single-serve sachets or squeeze tubes for on-premise consumption. Travel retail and convenience store channels in Netherlands prioritize this format.
- Dessert:Refrigerated mousse or pudding applications with extended stabilizer systems. Foodservice accounts in Belgian hospitality sector drive trial.
Leading the category by volume: Spread. Expanding most quickly: Syrup.
Formulation:
Ingredient cost tiers separate mass-market polyol blends from premium clean-label positioning.
- Hazelnut-Based:Core formulation leveraging Turkish Black Sea or Italian Piemonte hazelnut paste as primary solids source. Premium provenance claims command 40-60% price premiums in specialty retail. Ferrero's captive Italian sourcing network constrains competitive replication.
- Dairy-Free:Plant-based emulsion systems replacing skim milk powder with oat or pea protein isolates. Fastest margin expansion as vegan certification unlocks health food store distribution in Germany and Austria. Technical barrier: protein-hazelnut fat emulsion stability requires specialized homogenization equipment.
- Cocoa-Flavored:Reduced cocoa butter content with alkalized powder for cost-optimized mass market. Dominates private-label supermarket lines.
- Gluten-Free:Certified production protocols preventing cross-contamination for celiac positioning. Celiac society endorsements concentrate pricing power in Scandinavian markets.
Dominating revenue concentration: Hazelnut-Based. Steepest expansion trajectory: Dairy-Free.
Distribution Channel:
Channel selection dictates margin structure through slotting fee exposure versus direct relationship economics.
- Supermarkets:Hypermarket and grocery multiples commanding 60-70% of volume throughput. Edeka, Carrefour, and Tesco buyer consolidation forces promotional dependency and compresses net realized price. EFSA front-of-pack labeling is accelerating shelf reset toward reduced-sugar facings.
- Online Retail:Direct-to-consumer and marketplace platforms capturing subscription replenishment loyalty. UK and French urban markets show strongest repeat purchase velocity for personalized flavor bundles. Amazon and Ocado algorithms favor products with clean-label certification badges.
- Health Food Stores:Independent and chain specialty retailers with trained staff recommendation influence. Bio-certificate requirements filter assortment.
- Specialty Shops:Gourmet food halls and confectionery boutiques emphasizing provenance storytelling. Italian and Belgian chocolate retailers anchor this channel.
Capturing majority volume: Supermarkets. Gaining share fastest: Online Retail.
Consumer Type:
Usage occasion and medical necessity create distinct willingness-to-pay thresholds across user profiles.
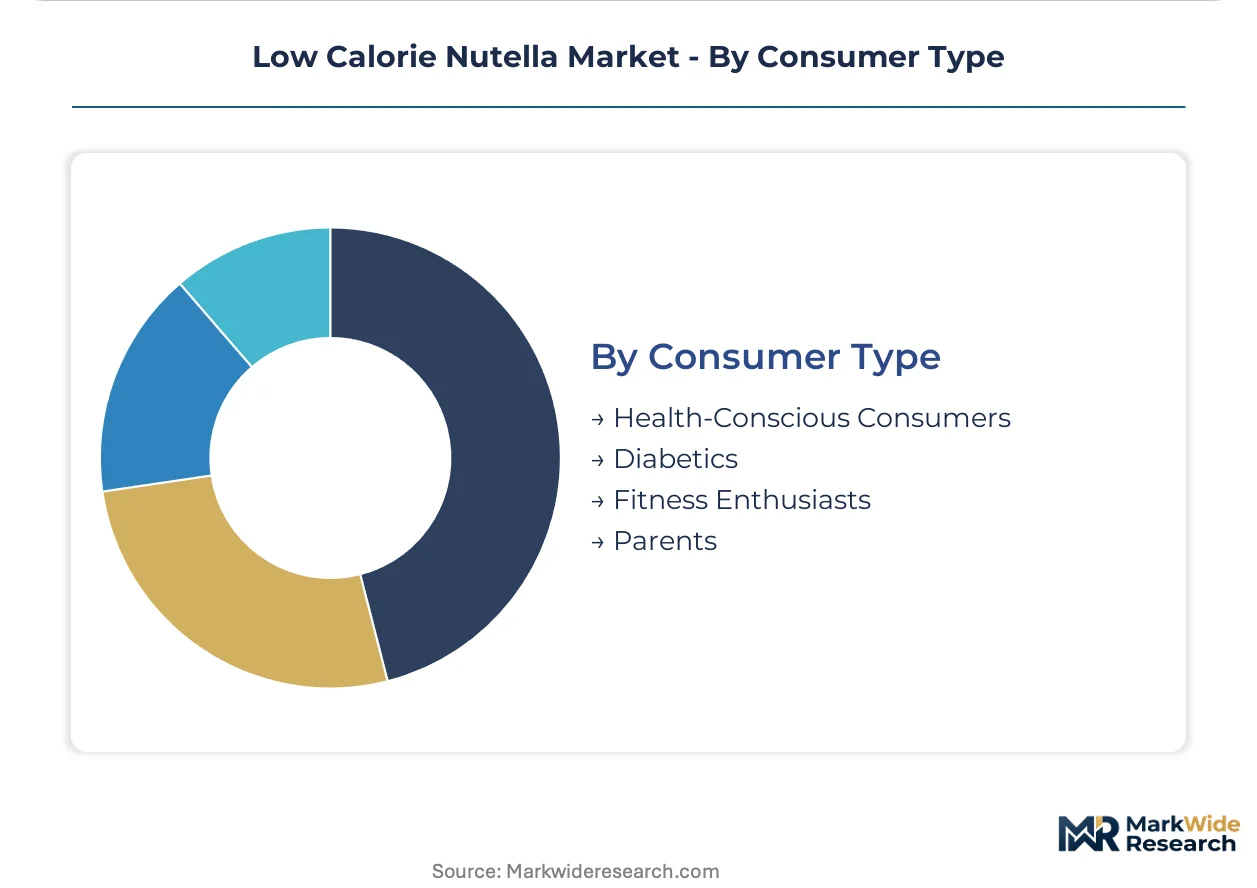
- Health-Conscious Consumers:Wellness-motivated purchasers prioritizing sugar reduction without diagnosed medical need. German households demonstrate highest per-capita trial rates as EFSA nutrition labeling simplifies comparative choice. Marketing resonance: clean-label ingredient transparency outperforms calorie claims.
- Diabetics:Medically indicated glycemic control requiring verified low-glycemic index certification. Endocrinologist recommendation and diabetic association endorsement drive prescription-adjacent purchasing in French and Italian pharmacy channels. Regulatory sensitivity: unauthorized therapeutic claims trigger national health authority enforcement.
- Fitness Enthusiasts:Macro-tracking consumers integrating spreads into high-protein meal prep. Sports nutrition retail and gym adjacent commerce concentrate this segment.
- Parents:Household gatekeepers seeking reduced-sugar options for children's lunchbox occasions. Back-to-school seasonal purchasing patterns concentrate volume.
Representing largest addressable base: Health-Conscious Consumers. Climbing the fastest: Diabetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turin's confectionery corridor anchors European spread innovation, with Piemonte hazelnut cultivation supplying premium formulations across German and French retail networks. Supply chain traceability from Turkish Black Sea orchards to Italian processing facilities underpins regional competitive advantage.
Germany
Health-conscious households in Bavaria and North Rhine-Westphalia drive sugar-reduced spread adoption through Edeka and REWE supermarket channels. EFSA front-of-pack Nutri-Score labeling accelerates consumer migration toward polyol-sweetened variants. Cologne-based food technology clusters specialize in erythritol-hazelnut emulsion stability for clean-label formulations.
France
Parisian specialty food halls and pharmacy-adjacent retail concentrate diabetic-positioned spread demand. ANSM enforcement of unauthorized therapeutic claims shapes marketing compliance frameworks. Auvergne-Rhône-Alpes packaging innovation hubs develop portion-controlled formats for foodservice accounts.
United Kingdom
London's subscription-commerce ecosystem captures recurring replenishment loyalty through personalized flavor bundles. FSA sugar-reduction targets align with Ocado and Amazon algorithm preferences for clean-label certification badges. Midlands manufacturing corridors supply private-label spreads to Tesco and Sainsbury's buyer networks.
Italy
Piemonte hazelnut cultivation clusters enable Ferrero's captive sourcing network and provenance storytelling. Italian Piemonte IGP certification requirements filter premium assortment in specialty retail. Lombardy food technology institutes advance allulose formulation research for glycemic-control applications.
Netherlands
Amsterdam-Rotterdam logistics corridors distribute reduced-sugar spreads across Benelux supermarket networks. Dutch retail consolidation through Albert Heijn buyer power forces promotional dependency and compresses net realized price. Wageningen food research institutes specialize in protein-hazelnut emulsion stability for dairy-free variants.
Low Calorie Nutella Market Competitive Landscape
Premium-margin players sit above commodity-margin players across provenance certification and clean-label formulation dimensions. The vendor base concentrates around three strategic archetypes: Italian heritage houses with captive hazelnut sourcing, North American scale manufacturers with health-focused branding, and European private-label specialists with reformulation agility. Dominant competitive moves include backward integration into Turkish hazelnut orchards and direct-to-consumer channel bypass of traditional retail slotting fees.
Among Italian heritage conglomerates, Ferrero Group exemplifies premium-tier positioning through Piemonte provenance control. Mondelēz International and J.M. Smucker Company occupy scale-driven positions across European and North American retail respectively. These three anchors represent divergent strategic vectors: captive sourcing, manufacturing scale, and health-focused distribution anchoring.
| Leading Market Players |
|---|
| Mondelēz International |
| Hormel Foods Corporation |
| Ferrero Group |
| Rigoni di Asiago |
| Andros Group |
| The Hershey Company |
| Dr. Oetker |
| Barefoot & Chocolate |
| J.M. Smucker Company |
| Others |
Value Network & Pricing Analysis
Family-owned Italian confectionery houses with multi-generational orchard holdings anchor supply discipline through captive Piemonte hazelnut sourcing, translating vertical control into premium pricing power that resists commodity volatility. Their financing independence from quarterly earnings pressure enables patient capacity planning and selective customer allocation that reinforces margin stability across reformulation cycles.
Pricing Analysis
Value-based pricing anchored to glycemic-control outcomes commands sustained premiums in pharmacy-adjacent retail and diabetic-specialist channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity: organic and non-GMO badges separate top tiers, while private-label cocoa-flavored lines compress toward cost-plus mechanics. Pricing pressure stems from Turkish hazelnut price volatility and REWE buyer consolidation, with promotional dependency intensifying in hypermarket channels. Diabetic-positioned consumers demonstrate lowest price sensitivity due to medical necessity, while health-conscious households without diagnosed conditions exhibit elastic response to shelf-price differentials.
Supply Chain Analysis
Refrigerated freight costs from Turkish Black Sea orchards to Italian processing facilities concentrate margin exposure in temperature-controlled logistics lanes. Raw material flows draw from Turkey, Italy, and emerging Georgian cultivation zones, with roasted hazelnut paste and erythritol syrup constituting primary cost stack components. Single-source vulnerability in Italian confectionery equipment suppliers creates bottleneck risk for new formulation scale-up. Distribution runs through Albert Heijn and Edeka buyer networks in continental Europe, with direct-to-subscription channels fragmenting volume toward curated delivery ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low calorie spread category is transitioning from maltitol-based legacy formulations toward allulose and erythritol clean-label systems, with polyol-hazelnut emulsion stability emerging as the critical technical differentiator. This technology pivot rewards manufacturers with dedicated food technology capabilities and regulatory affairs infrastructure.
For Market Incumbents: To counter private-label erosion in German supermarket channels, Ferrero and Mondelēz should deepen backward integration into Turkish hazelnut orchards and accelerate proprietary allulose formulation patent filings. Channel control through direct-to-consumer subscription platforms offers defensive margin protection against slotting-fee compression. For New Entrants and Emerging Players: Diabetic-specialist households in French pharmacy channels represent an underserved buyer archetype with prescription-adjacent purchasing patterns and endocrinologist endorsement pathways. Poland and Czech Republic specialty retail show penetrable white space for premium reduced-sugar positioning. A go-to-market angle anchored to diabetic association certification and portion-controlled single-serve formats bypasses incumbent shelf dominance. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap reformulation specialists with captive Italian sourcing networks and EFSA regulatory dossier expertise. Long-term viability across the analysis window hinges on clean-label certification depth and polyol-sweetener approval velocity. The signal to watch is EFSA novel food ingredient guidance tightening, which would strand smaller brands without dedicated toxicology study capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hazelnut Orchards | Turkish Black Sea cultivation control secures supply traceability for Piemonte provenance claims. |
| Allulose Formulation Patent Filing | First-mover regulatory dossiers lock in glycemic-control positioning ahead of EFSA pathway tightening. |
| Direct-to-Consumer Subscription Launch | Urban UK and French replenishment models bypass Albert Heijn promotional dependency. |
| Diabetic Association Certification | ANSM-compliant endorsement unlocks pharmacy-adjacent retail in Paris and Lyon. |
| Dairy-Free Production Line Expansion | Vegan certification captures health food store distribution in German Bio-certificate channels. |
Research Methodology
EFSA guidance documents, EU customs trade records, and Nielsen retail audit data formed the secondary backbone, cross-referenced against primary interviews with category buyers at Edeka and Carrefour, food technology directors at Lombardy research institutes, and regulatory affairs leads at Italian heritage manufacturers. Bottom-up volume modeling from SKU-level retail velocity and top-down macroeconomic calibration triangulated market sizing across the projection horizon.
Historical trendline analysis of hazelnut price volatility and polyol sweetener adoption curves informed the analytical framework. Segmentation dimensions modeled include product format viscosity, formulation certification tier, channel slotting-fee exposure, and consumer glycemic-control need intensity. CAGRs derived from regression-adjusted growth trajectories incorporate EFSA labeling policy implementation pace and allulose import quota expansion as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Turkish agricultural policy shifts and EFSA novel food safety dossier requirements. Forecasts reflect documented assumptions about regulatory approval timelines and consumer acceptance thresholds for polyol-induced sensory profiles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Vegan Candies Market
Confectionery
Chocolate Couverture Market
Confectionery
India Chocolate Market
Confectionery
Durian Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
Milk Chocolate Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
UK Chocolate Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Fruit Jellies Market
Confectionery
Global Mochi Market
Confectionery
Brain Mint Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Mooncake Market