
 Buttercream Frosting Market | 2026-2036
Buttercream Frosting Market Size, Share, and Industry Trends Forecast 2026-2036
Buttercream Frosting Market Analytics
European dairy processors is realigning butterfat sourcing for industrial frosting production. Rich Products Corporation leverages its frozen bakery platform to anchor North American foodservice supply. CSM Bakery Solutions sustains European market presence through specialized fat technologies. Wilton Brands competes in the home baking channel through craft-focused distribution.
Buttercream frosting is an emulsified sugar-fat confection made from butter or shortening, powdered sugar, and liquid binders, typically containing 35-50% sugar by weight and whipped to aerated densities of 0.6-0.8 g/ml for spreadable cake coating and decorative piping. Classic formulations retain dominant volume share in commercial bakeries due to cost efficiency and neutral flavor compatibility. Chocolate buttercream is gaining fastest in premium retail channels where cocoa butter content differentiates positioning. Cream cheese variants command higher margin pools in specialty store distribution despite narrower application scope.
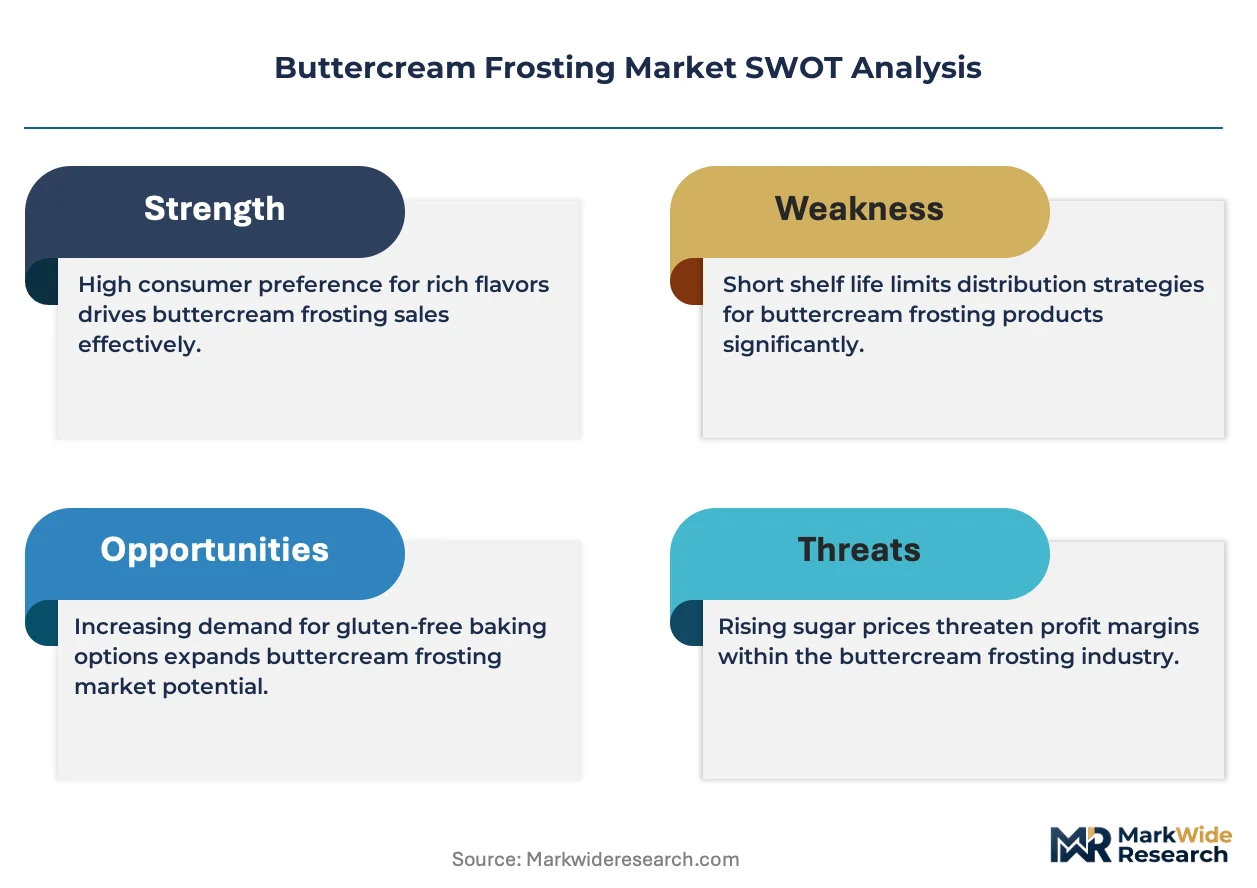
The FDA governs standardized identity and added sugar disclosure for U.S. frosting products, while the EFSA evaluates novel fat replacers entering European formulations, and ISO 22000 frameworks shape hazard control across export-oriented manufacturing. These regulatory layers determine permissible ingredient claims and cross-border market access for reformulated low-sugar alternatives. Stakeholders must monitor evolving clean-label thresholds and fat-standard enforcement to align R&D portfolios with compliance-bound demand shifts.
Market Dynamics
Artisanal cake decoration in retail bakeries is expanding as consumer preference for visual customization drives ingredient specification upgrades across commercial and home baking channels.
Growth Catalysts
- FDA Added Sugar Disclosure:Reformulated low-sugar buttercream variants are capturing shelf space in U.S. retail as manufacturers align with updated labeling requirements for transparency.
- Premium Home Baking:Hobbyist decorators in the United States are sustaining demand for high-butterfat formulations through specialized craft retailers and e-commerce platforms.
- European Fat Technology:EFSA evaluations of novel fat replacers are accelerating clean-label product development pipelines for industrial frosting applications.
Market Restraints
- Butterfat Input Volatility:European dairy processors face margin compression from fluctuating cream commodity prices tied to seasonal milk production cycles.
- Supply Concentration Risk:Industrial shortening supply for North American foodservice channels clusters among a limited base of hydrogenated oil refiners.
- Technical Shelf-Life Ceiling:Aerated buttercream density thresholds of 0.6-0.8 g/ml constrain ambient distribution reach without refrigeration infrastructure.
Strategic Opportunities
- Clean-Label Tailwinds:ISO 22000 hazard control frameworks are enabling export-oriented manufacturers to access premium retail channels with certified production credentials.
- Chocolate Buttercream Premiumization:Cocoa butter content differentiation is opening margin expansion in specialty store distribution where consumers pay for ingredient provenance.
- Frozen Bakery Platform Integration:Pre-finished buttercream layers for foodservice thaw-and-apply applications are reducing labor costs in commercial kitchen operations.
Industry Challenges
- Reformulation Expertise Gap:Food technologists capable of balancing sugar reduction with emulsion stability remain scarce in mid-tier manufacturing facilities.
- Cross-Border Compliance Friction:Divergent fat-standard enforcement between U.S. FDA identity requirements and EFSA novel ingredient protocols delays multi-market product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buttercream Frosting Market |
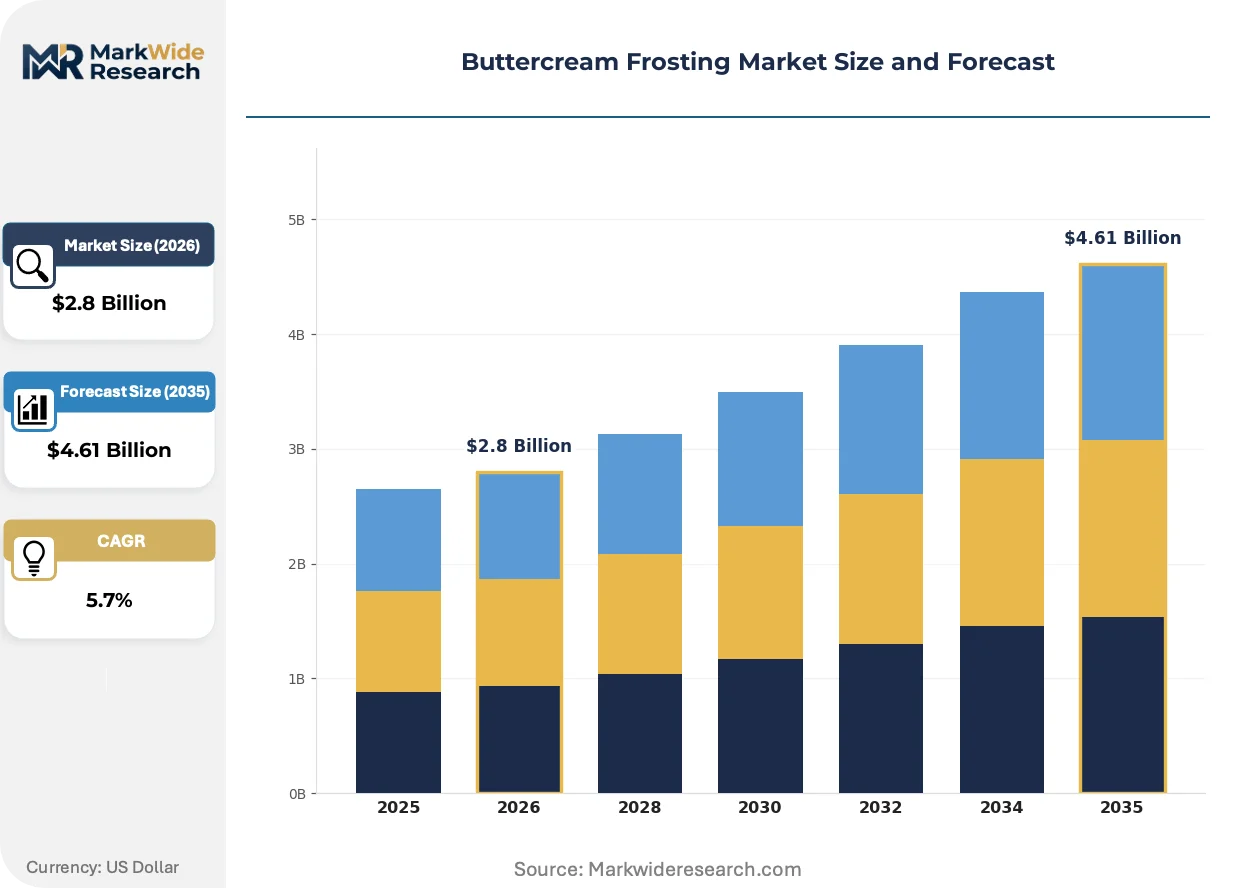
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Classic, Chocolate, Vanilla, Cream Cheese Application: Cakes, Cupcakes, Cookies, Pastries Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers End User: Bakers, Restaurants, Retail Bakeries, Home Bakers |
| Companies Covered | Rich Products Corporation, Betty Crocker, CSM Bakery Solutions, Wilton Brands, Pinnacle Foods, Dawn Food Products, Dr. Oetker, General Mills, Nestle SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buttercream Frosting Market Evolving Landscape
Reformulation science and regulatory transparency mandates are converging to reshape how buttercream products are developed, labeled, and distributed across commercial and retail channels.
Enzymatic fat structuring is rewriting the technical possibilities for reduced-sugar buttercream without sacrificing spreadability or mouthfeel. U.S. retail bakeries are piloting these modified lipid systems at accelerated trial frequencies. The technology is compressing the traditional trade-off between clean-label positioning and functional performance in cake coating applications.
EFSA novel food assessments for plant-derived fat replacers are tightening ingredient approval timelines for European manufacturers seeking clean-label positioning. Industrial formulators must now front-load toxicology documentation before commercial scale-up. Chocolate buttercream variants with elevated cocoa butter content face heightened scrutiny but also premium pricing authorization in specialty retail channels.
Direct-to-consumer craft channels are fragmenting traditional distributor control over home baking ingredient supply. Wilton Brands and comparable craft-focused suppliers are building proprietary digital platforms that bypass wholesale intermediaries. This disintermediation is most visible in the United States where premium decorating supply e-commerce has captured significant share from brick-and-mortart specialty retailers.
Buttercream Frosting Market Segmentation
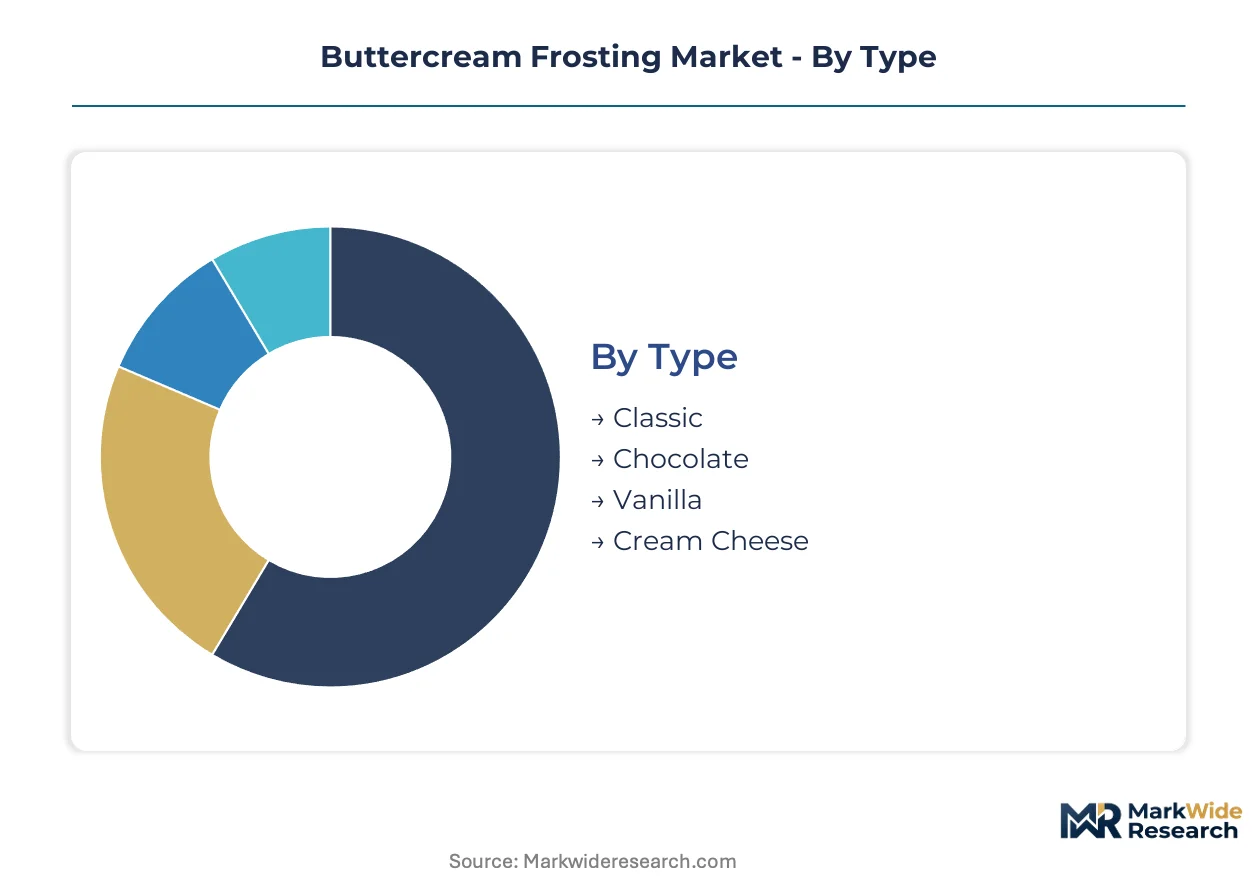
Segmentation in buttercream frosting reveals how formulation chemistry, use-case requirements, and channel economics partition value capture across the supply chain. Each dimension carries distinct regulatory burdens and margin profiles that shape manufacturer portfolio priorities.
Type:
Classic buttercream formulations require only FDA standardized identity compliance, while chocolate and cream cheese variants trigger additional cocoa butter content verification and dairy-derived ingredient disclosure protocols.
- Classic:Comprising butter or shortening emulsified with powdered sugar at 35-50% sugar by weight and aerated to 0.6-0.8 g/ml density. Commercial bakeries in the United States specify this type for cost-efficient cake coating where neutral flavor compatibility supports decoration versatility.
- Chocolate:Incorporating cocoa butter solids that elevate fat content and require EFSA novel food assessments when plant-derived replacers substitute traditional lipids. Specialty retailers in premium channels are concentrating demand here as ingredient provenance justifies pricing premiums.
- Vanilla:Standard extract-flavored variant with minimal regulatory overhead beyond basic FDA labeling.
- Cream Cheese:Acidified dairy base commanding narrow application scope but higher margin pools in specialty distribution.
Classic formulations sit at the top of the volume ranking, with chocolate climbing the fastest.
Application:
Volume concentration varies sharply by finished product complexity, with multi-layer cake assembly demanding stable emulsion performance that constrains formulation flexibility.
- Cakes:Tiered and sheet cake applications requiring structural integrity in frosting layers under refrigeration stress. U.S. retail bakeries drive specification upgrades here as visual customization trends intensify ingredient performance demands.
- Cupcakes:Single-serve format with shorter decoration exposure time and more forgiving aerated density requirements. Foodservice channels in North America are expanding portion-controlled cupcake programs that reduce per-unit frosting waste.
- Cookies:Sandwich and topped applications with lower fat stability thresholds.
- Pastries:Laminated and filled products where moisture migration control dominates formulation priorities.
Cakes anchor volume leadership across the analysis window, while cupcakes gain share fastest in foodservice contract manufacturing.
Distribution Channel:
Channel selection determines refrigeration infrastructure requirements and clean-label certification thresholds that segment manufacturers by operational capability.
- Online Retail:Direct-to-consumer platforms bypassing wholesale intermediaries. Wilton Brands and craft-focused suppliers are building proprietary digital channels in the United States where premium decorating supply e-commerce has displaced brick-and-mortar specialty retailers.
- Supermarkets:Mass retail requiring ISO 22000 credentials for shelf placement and extended ambient distribution reach without refrigeration infrastructure.
- Specialty Stores:Curated assortments with elevated cocoa butter content authorization.
- Wholesalers:Industrial foodservice supply with frozen bakery platform integration for thaw-and-apply applications.
Supermarkets maintain volume dominance, with online retail expanding most quickly through craft channel disintermediation.
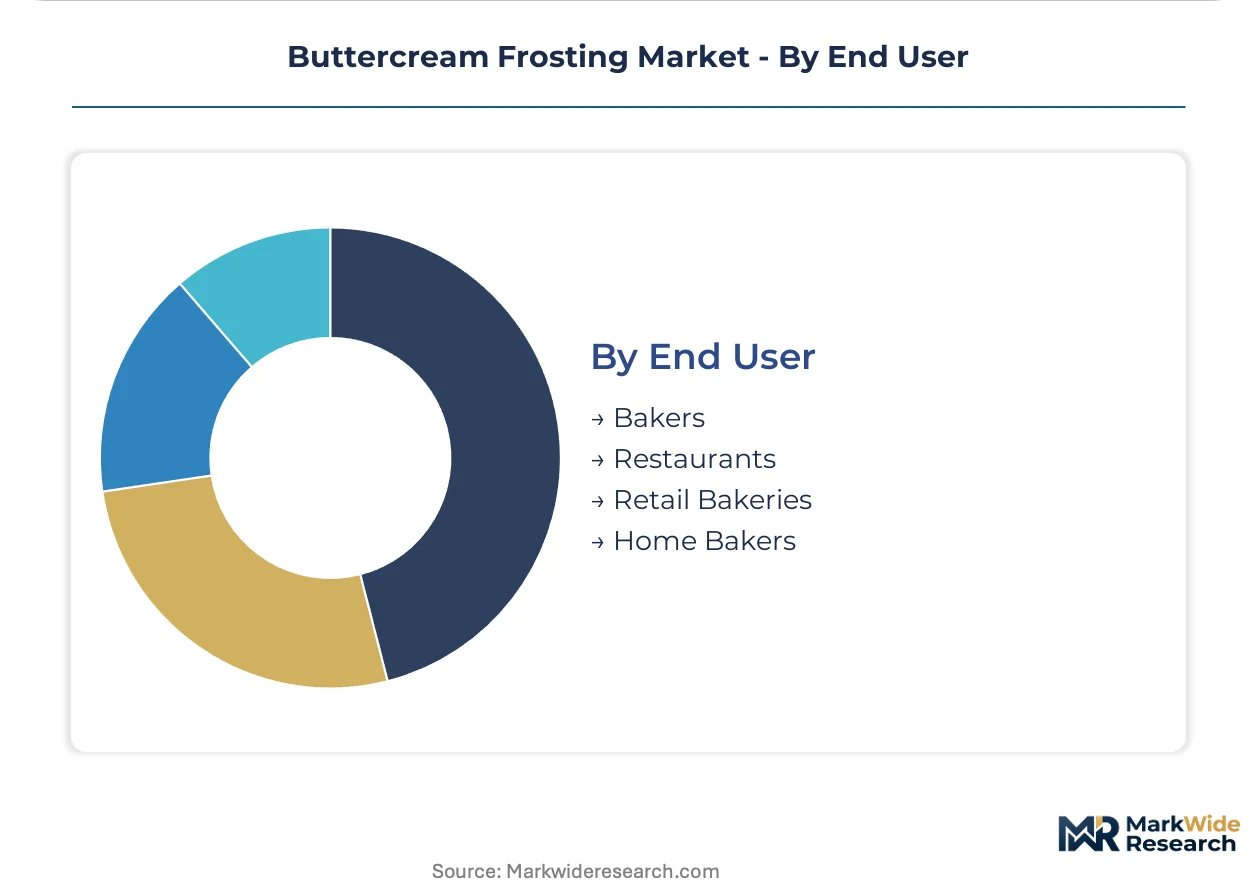
End User:
Technical expertise and batch scale create diverging procurement patterns that favor either pre-finished convenience or raw ingredient control.
- Bakers:Industrial and artisanal production facilities with in-house formulation capability and volume purchasing leverage. European dairy processors are realigning butterfat sourcing specifically for this segment's industrial frosting production.
- Restaurants:Commercial kitchens prioritizing labor reduction through frozen pre-finished buttercream layers.
- Retail Bakeries:Mid-tier operators driving artisanal cake decoration expansion with ingredient specification upgrades.
- Home Bakers:Hobbyist decorators sustaining demand for high-butterfat formulations through specialized craft retailers.
Bakers command the highest volume position, while home bakers show the steepest expansion trajectory through premium home baking trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between FDA sugar-disclosure mandates and EFSA fat-replacer assessment timelines is redirecting reformulation investment toward jurisdictions with faster novel-ingredient pathways. Manufacturers are migrating pilot-scale production to countries where clean-label certification accelerates premium channel access.
United States
Premium home baking trends in the United States sustain demand for high-butterfat formulations through specialized craft retailers and direct-to-consumer platforms. FDA updated labeling requirements for added sugars are forcing rapid product reformulation across domestic manufacturing facilities. Chicago and Minneapolis anchor industrial frosting production where frozen bakery platform integration supports foodservice thaw-and-apply applications.
Germany
Artisanal cake decoration expansion in retail bakeries drives specification upgrades for emulsion-stable frosting formulations across German commercial channels. EFSA evaluations of novel fat replacers are tightening approval timelines for plant-derived lipid systems entering European formulations. The Baden-Württemberg region concentrates dairy processor realignment efforts as butterfat sourcing pivots toward industrial frosting production.
United Kingdom
Specialty store distribution channels in the United Kingdom command elevated margin pools for cream cheese buttercream variants despite narrower application scope. ISO 22000 hazard control frameworks shape export-oriented manufacturing credentials for premium retail placement. Greater London and the Midlands cluster craft-focused supplier activity where disintermediation through proprietary digital platforms is displacing traditional wholesale intermediaries.
France
Chocolate buttercream premiumization in French specialty retail channels leverages cocoa butter content differentiation to justify pricing premiums. REACH compliance obligations for industrial shortening supply chains constrain hydrogenated oil refiner concentration in North Atlantic trade corridors. The Île-de-France region hosts formulation R&D facilities where enzymatic fat structuring trials are compressing the trade-off between clean-label positioning and functional performance.
Canada
Cross-border compliance friction between FDA identity requirements and Health Canada fat-standard enforcement delays multi-market product launches for reformulated low-sugar alternatives. PMRA oversight of novel food ingredients parallels EFSA assessment rigor while maintaining distinct documentation protocols. Ontario and Quebec industrial bakeries are piloting reduced-sugar buttercream variants for ambient distribution reach without full refrigeration infrastructure.
Buttercream Frosting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label specialization and direct-to-consumer craft channels. The vendor base stratifies across three maturity tiers: multinational frozen bakery platforms with foodservice scale, European fat-technology specialists with EFSA-aligned R&D pipelines, and craft-focused suppliers building proprietary digital distribution. Strategic archetypes include integrated dairy processors controlling butterfat input costs, industrial shortening refiners with hydrogenated oil supply concentration, and enzymatic fat-structuring technology licensors. Dominant competitive moves center on backward integration into dairy sourcing and geographic expansion through ISO 22000-certified export manufacturing.
Within the multinational frozen bakery tier, Rich Products Corporation and CSM Bakery Solutions exemplify divergent regional anchoring strategies. Rich Products Corporation occupies a position tied to North American foodservice supply through frozen platform integration. CSM Bakery Solutions represents European market presence sustained through specialized fat technologies and EFSA-aligned novel ingredient pipelines. Wilton Brands sits within the craft-channel disintermediation archetype, building direct-to-consumer digital platforms that bypass wholesale intermediaries in United States premium decorating supply.
| Leading Market Players |
|---|
| Rich Products Corporation |
| Betty Crocker |
| CSM Bakery Solutions |
| Wilton Brands |
| Pinnacle Foods |
| Dawn Food Products |
| Dr. Oetker |
| General Mills |
| Nestle SA |
| Others |
Value Network & Pricing Analysis
Food technologists capable of enzymatic fat structuring command wage premiums in the Baden-Württemberg and Chicago manufacturing clusters, compressing labor-cost differentials between premium clean-label tiers and standard industrial formulations. This workforce concentration shapes pricing-tier spreads as manufacturers pass specialized R&D overhead into cocoa butter-differentiated chocolate buttercream positioning.
Pricing Analysis
Distributor margin layers in craft retail channels absorb 25-35 point markups before reaching home bakers, while direct-to-consumer platforms compress this spread. Three-tier pricing structure across premium, standard, and economy levels stratifies by butterfat content and ISO 22000 certification status. Pricing pressure stems from European cream commodity volatility forcing reformulation toward plant-derived fat replacers. Industrial foodservice buyers exhibit highest price sensitivity due to frozen bakery platform volume contracts, while specialty store channels tolerate premium positioning for provenance-verified cocoa butter formulations.
Supply Chain Analysis
Workforce availability for enzymatic fat structuring trials concentrates in Île-de-France and Minneapolis-St. Paul R&D corridors, constraining pilot-scale capacity expansion. Raw material flows draw from New Zealand and German dairy processors for butterfat, Malaysian and Indonesian palm oil refiners for shortening fractions, and West African sourcing corridors for cocoa butter solids. Single-source vulnerability clusters in hydrogenated oil refiner concentration for North American foodservice shortening supply. Distribution runs through frozen bakery platform integration for foodservice thaw-and-apply applications, with ambient-refrigerated hybrid logistics for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in buttercream frosting rests on enzymatic fat structuring cost curves flattening and chocolate buttercream premiumization capturing specialty store pricing authorization.
For Market Incumbents: Cement backward integration into dairy sourcing to buffer European cream commodity volatility threatening industrial frosting margin pools. Lock ISO 22000 certification across export-oriented manufacturing to defend shelf placement against clean-label specialist entrants. Prioritize captive supply of high-butterfat cream inputs in Baden-Württemberg and Midwest dairy corridors. For New Entrants and Emerging Players: Direct-to-consumer craft platforms offer the lowest customer acquisition cost route into United States premium home baking demand. Target cupcake foodservice contract manufacturing in North America where portion-controlled programs reduce per-unit frosting waste and specification barriers are lower than tiered cake applications. Lead with enzymatic fat structuring technology licensing to bypass capital-intensive production scale requirements. For Investors and Strategic Acquirers: Frozen bakery platform operators are the most active acquirer in this space, consolidating foodservice thaw-and-apply capabilities. The five-to-ten year viability window favors targets with EFSA-aligned novel ingredient pipelines and established European fat technology relationships. Watch EFSA approval velocity for plant-derived fat replacers as the inflection signal for clean-label tier margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Sourcing | Captive butterfat supply from New Zealand and German processors insulates margin pools from cream commodity cycles. |
| Enzymatic Fat Structuring Licensing | Technology transfer agreements compress R&D timelines for reduced-sugar clean-label reformulation in U.S. retail. |
| ISO 22000 Certification Investment | Hazard control credentials unlock supermarket shelf placement and cross-border premium channel access. |
| Direct-to-Consumer Platform Buildout | Proprietary digital channels bypass distributor markups in United States craft decorating supply. |
| Frozen Bakery Platform Integration | Pre-finished buttercream layers reduce labor costs in North American foodservice commercial kitchen operations. |
Research Methodology
Multiple input streams — executive interviews with industrial bakery procurement directors, regulatory affairs specialists at EFSA-aligned manufacturers, and craft channel category managers — were reconciled against trade flow databases, FDA labeling guidance documents, and dairy commodity exchange records. Secondary validation drew from customs data on cocoa butter imports, frozen bakery platform utilization reports, and ISO certification registry filings. Bottom-up segment sizing triangulated against top-down value chain expenditure estimates.
Historical volume trajectories were cross-referenced against panel input from foodservice contract manufacturers and specialty store buyers to anchor projection assumptions across the analysis window. Segmentation modeling captured formulation type, application complexity, distribution channel infrastructure requirements, and end-user technical capability tiers. CAGRs were derived from elasticity-adjusted demand curves incorporating FDA sugar-disclosure compliance timelines and EFSA novel food assessment velocity.
The model assumes a particular technology adoption path; alternative pathways for enzymatic fat structuring scale-up would alter the outlook for clean-label tier penetration. Forecasts reflect documented assumptions on butterfat input cost trajectories and craft channel disintermediation velocity. Material deviation in EFSA approval timelines or European dairy processor realignment decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Candy Market
Confectionery
Brain Mint Market
Confectionery
Liquorice Shellac Market
Confectionery
South Africa Confectionery Market
Confectionery
Chocolate Confectionery Market
Confectionery
UK Chocolate Market
Confectionery
Canada Chocolate Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Global Candy Market
Confectionery
Chocolate Spread Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Citrus Gummies Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Fruit Jellies Market