
 North America Sugar-Free Chewing Gum Market | 2026-2036
North America Sugar-Free Chewing Gum Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sugar-Free Chewing Gum Market Insights
The FDA's updated nutrition labeling requirements is decoupling sugar-free gum formulations from legacy sweetener systems across North American manufacturing. Mars Incorporated leverages its integrated supply chain to sustain cost advantages in mint and fruit flavor production. Mondelēz International anchors its position through specialized distribution networks spanning convenience and mass retail channels. Perfetti Van Melle competes aggressively on spearmint and cinnamon variants, while The Hershey Company differentiates through premium resealable pouch formats targeting adult wellness segments.
North America sugar-free chewing gum comprises elastomer-based chewable products formulated with non-cariogenic sweeteners such as xylitol, sorbitol, or aspartame, manufactured through sequential mixing, rolling, and coating processes to achieve specified chew texture and flavor release profiles. The primary commercial purpose centers on delivering oral hygiene benefits, breath freshening, and functional claims including stress relief or dental caries prevention without contributing to sugar intake. Functional gum leads product type segmentation by margin contribution, driven by added-value claims around cognitive performance and oral care. Adults dominate end user demand, though teens represent the fastest-growing cohort as school-based wellness programs expand. Single-serve packaging commands premium pricing in transit retail locations, while bulk pack formats occupy mainstream grocery and club store channels.
The FDA governs sweetener safety and labeling claims, while the USDA's organic certification program shapes premium positioning for natural-positioned entrants. State-level sugar tax legislation in California and New York indirectly stimulates sugar-free alternatives through relative price advantages. Health Canada maintains parallel but distinct additive approval pathways that Canadian manufacturers must navigate for cross-border distribution. Stakeholders should monitor evolving FDA guidance on novel sweeteners and anticipate how provincial labeling harmonization efforts may reshape North American supply chain configuration.
Market Dynamics
FDA nutrition labeling revisions and state-level sugar tax legislation are forcing North American manufacturers to abandon legacy sweetener systems and accelerate xylitol and allulose adoption across production lines.
Growth Catalysts
- FDA Sweetener Guidance:Updated approval pathways for novel non-nutritive sweeteners are compressing time-to-market for functional gum formulations targeting dental caries prevention claims.
- California Sugar Tax:State-level excise duties on sugar-sweetened beverages create relative price advantages for sugar-free alternatives in West Coast retail channels.
- Oral Care Integration:Dental professional endorsement programs in metropolitan New York and Los Angeles are legitimizing therapeutic gum positioning among adult wellness consumers.
Market Restraints
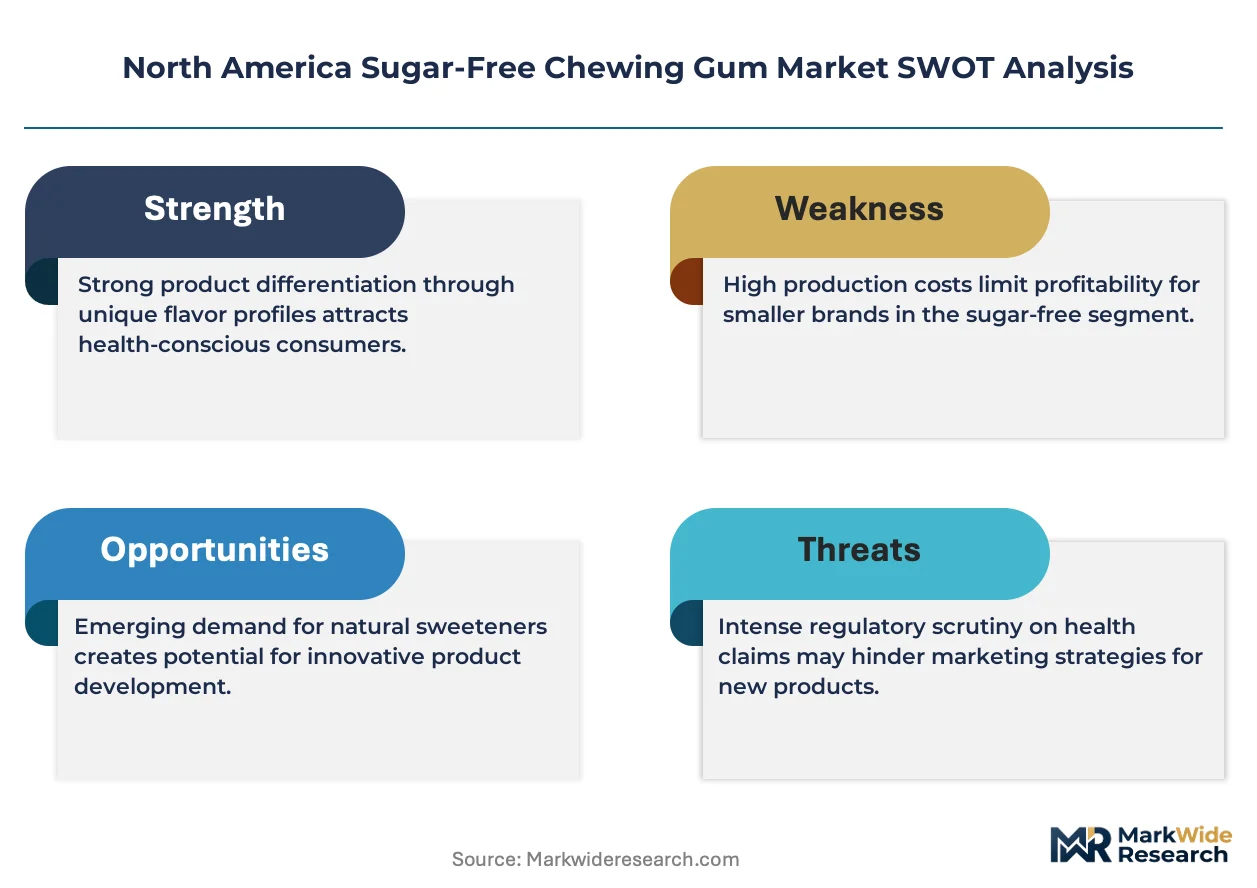
- Xylitol Supply Concentration:Finnish and Chinese producers control over 70% of global xylitol feedstock, exposing North American formulators to input cost volatility and currency risk.
- Health Canada Additive Divergence:Parallel but non-harmonized approval pathways for novel sweeteners create regulatory friction for cross-border product standardization.
- Nicotine Gum Substitution:Smoking cessation products and CBD-infused alternatives capture overlapping functional positioning in stress-relief and oral fixation segments.
Strategic Opportunities
- USDA Organic Certification:Premium natural-positioned entrants leverage the USDA organic seal to command shelf space in Whole Foods and Sprouts distribution networks.
- Cognitive Performance Claims:Nootropic ingredient integration targets Silicon Valley and Austin tech worker cohorts seeking productivity-enhancing consumables.
- Transit Retail Expansion:Single-serve resealable formats penetrate airport convenience and urban metro vending channels previously dominated by mint and candy competitors.
Industry Challenges
- Flavor Chemist Scarcity:Specialized expertise in sustained-release flavor encapsulation for polyol-based matrices commands premium compensation and extends R&D timelines.
- Coating Equipment Capex:Conversion to aqueous coating systems for clean-label positioning requires seven-figure capital outlays that mid-tier manufacturers struggle to finance.
- Patent Thicket Navigation:Dense intellectual property landscape around specific xylitol-to-sorbitol ratios and texture modifiers complicates new entrant formulation freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sugar-Free Chewing Gum Market |
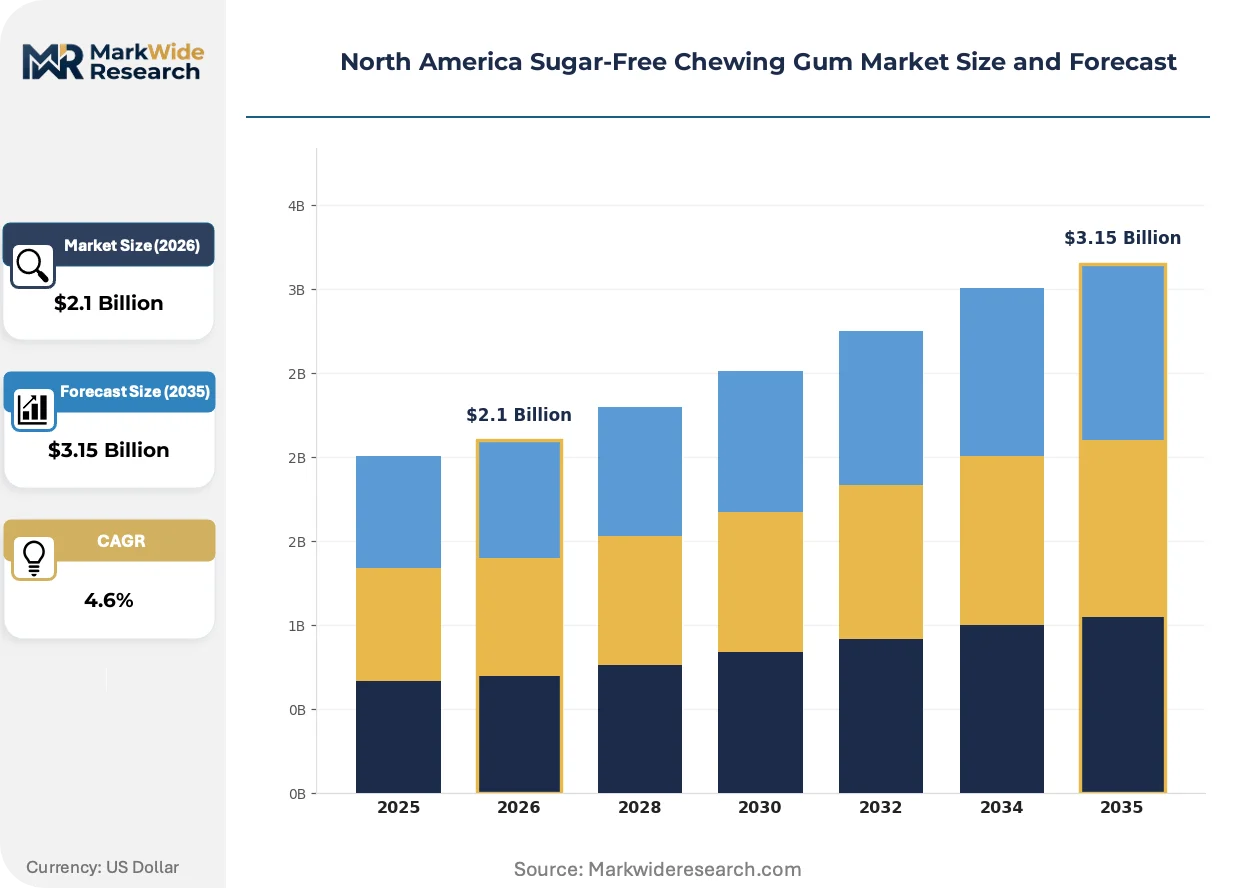
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Gum, Mints, Chewy Candy, Functional Gum End User: Adults, Children, Teens, Seniors Flavor: Mint, Fruit, Cinnamon, Spearmint Packaging Type: Bulk Pack, Single-Serve, Resealable Pouch, Tins |
| Companies Covered | Mars Incorporated, Mondelēz International Inc., Perfetti Van Melle BV, The Hershey Company, Ford Gum & Machine Company Inc., Simply Gum Inc., The Bazooka Companies Inc., Tootsie Roll Industries Inc., The PUR Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sugar-Free Chewing Gum Market Trends and Innovations
Microbiome-targeted delivery systems and blockchain-enabled ingredient provenance are redefining competitive differentiation in North American sugar-free gum manufacturing. These developments intersect with evolving retail channel structures and regulatory disclosure requirements.
Precision fermentation-derived rare sugars are decentralizing sweetener sourcing away from traditional agricultural supply chains. Adult wellness brands in Colorado and Massachusetts are adopting these inputs at pilot scale. The technology is decentralizing procurement power from incumbent corn and birch processors toward biotechnology startups with modular production capacity.
FDA guidance on dietary fiber labeling is reshaping how manufacturers position polydextrose and resistant dextrin in functional gum formulations. The agency's 2023 enforcement discretion memo creates compliance uncertainty for products making satiety claims. Prebiotic-positioned variants in the Pacific Northwest are reformulating to meet the new analytical standards ahead of formal rulemaking.
Subscription-direct models are capturing recurring revenue from habitual gum consumers previously served by impulse retail. Wellness-focused cohorts in Chicago and Toronto are migrating toward auto-replenishment platforms that bundle oral care diagnostics with product delivery. This channel shift concentrates customer data ownership with brands and compresses traditional distributor margins in the convenience store segment.
North America Sugar-Free Chewing Gum Market Segmentation
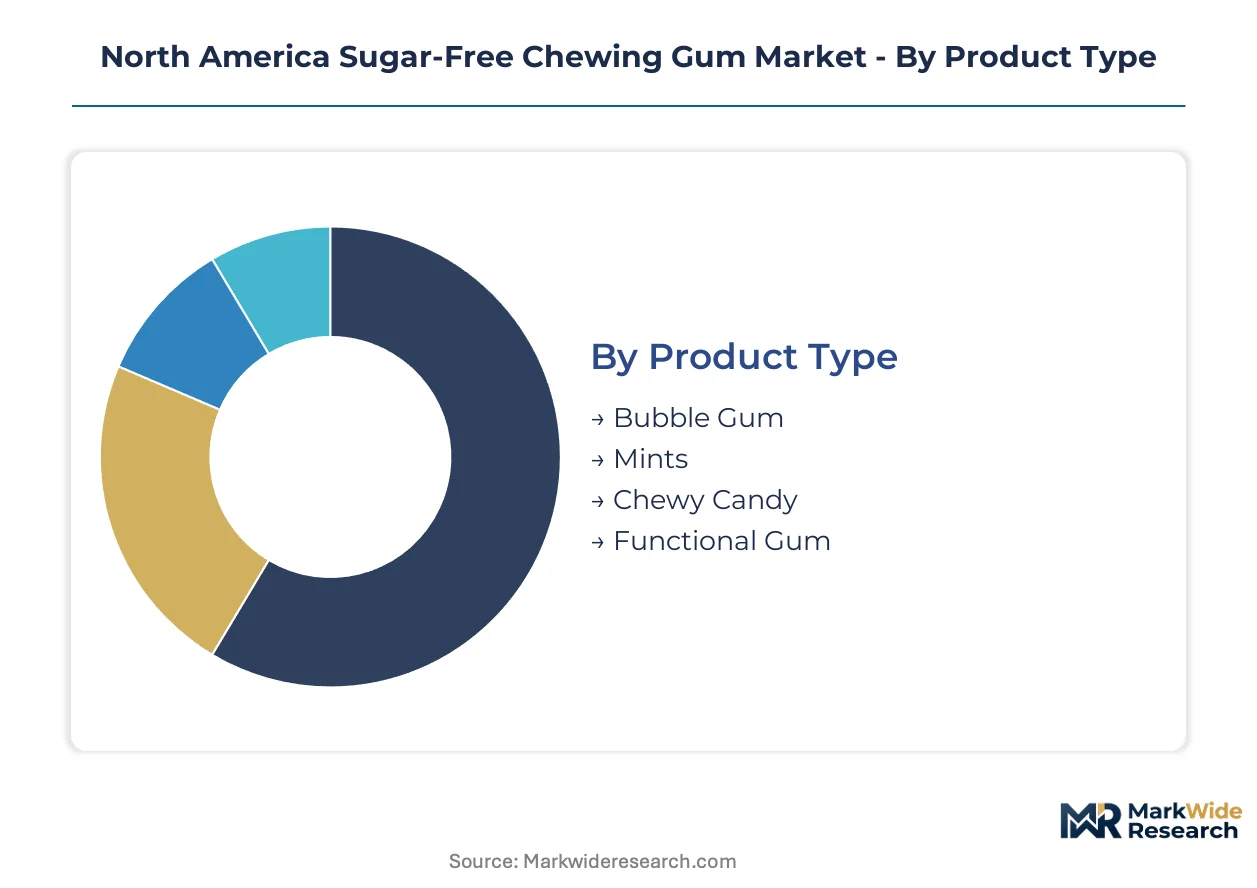
Consumer upgrade cycles in North American sugar-free gum vary sharply by life stage and consumption context. Manufacturers calibrate formulation complexity, packaging convenience, and functional positioning to capture replacement demand across distinct usage occasions.
Product Type:
Replacement frequency and functional claims drive divergent upgrade cycles across product categories, with therapeutic positioning commanding premium shelf space.
- Functional Gum:Elastomer matrices integrate xylitol, nootropic compounds, or microbiome-targeted actives for dental caries prevention and cognitive performance claims. Demand concentrates in California and New York metropolitan wellness corridors, propelled by dental professional endorsement programs and employer wellness subsidies.
- Bubble Gum:Traditional polyol-sweetened formulations emphasize chew texture and flavor longevity for recreational consumption. Teens in Texas and Florida school districts represent the fastest-expanding cohort as district-level sugar reduction policies displace conventional candy alternatives.
- Mints:Compressed tablet formats deliver rapid breath freshening through intense flavor dosing. Transit retail locations in Chicago O'Hare and Atlanta Hartsfield-Jackson anchor volume.
- Chewy Candy:Soft-texture variants bridge gum and confectionery positioning with extended dissolve profiles. Convenience store distributors in the Midwest stock these for impulse conversion.
Volume placements concentrate in Functional Gum; the faster expansion belongs to Bubble Gum.
End User:
Life-stage-specific oral health priorities and purchasing autonomy reshape channel access and price tolerance across consumer cohorts.
- Adults:Primary decision-makers seeking functional benefits including stress modulation, dental caries prevention, and breath management. Metropolitan professionals in Los Angeles and Toronto drive premium pouch format adoption.
- Teens:School-based consumption with high social visibility and flavor experimentation. District wellness program expansion in Colorado and Massachusetts accelerates sugar-free substitution fastest.
- Children:Parent-controlled purchasing with safety-focused sweetener preferences. Pediatric dentist recommendations in suburban Texas and Florida influence household trial.
- Seniors:Dry mouth symptom management and denture-compatible texture requirements. Medicare Advantage plan partnerships in Arizona and Florida create covered benefit access.
Adults dominate absolute volume; teens gain share most rapidly through institutional channel penetration.
Flavor:
Flavor preference stability varies by demographic persistence, with mint variants showing highest loyalty and fruit profiles capturing experimentation cycles.
- Mint:Peppermint and wintergreen oil formulations with sustained-release encapsulation for breath-freshening efficacy. Corporate procurement programs in Manhattan and downtown Chicago standardize on mint for workplace distribution.
- Spearmint:Milder terpene profile appealing to consumers avoiding intensity. Pacific Northwest natural-positioned retailers favor spearmint for clean-label alignment.
- Fruit:Berry and citrus flavor systems using encapsulated acid for tartness persistence. Teens in Sun Belt states drive seasonal velocity spikes.
- Cinnamon:Cinnamaldehyde-based warming sensation with limited but loyal following. Convenience store distributors in the Southwest maintain consistent facings.
Mint variants anchor baseline volume; fruit flavor rotation programs capture the steepest expansion trajectory among younger cohorts.
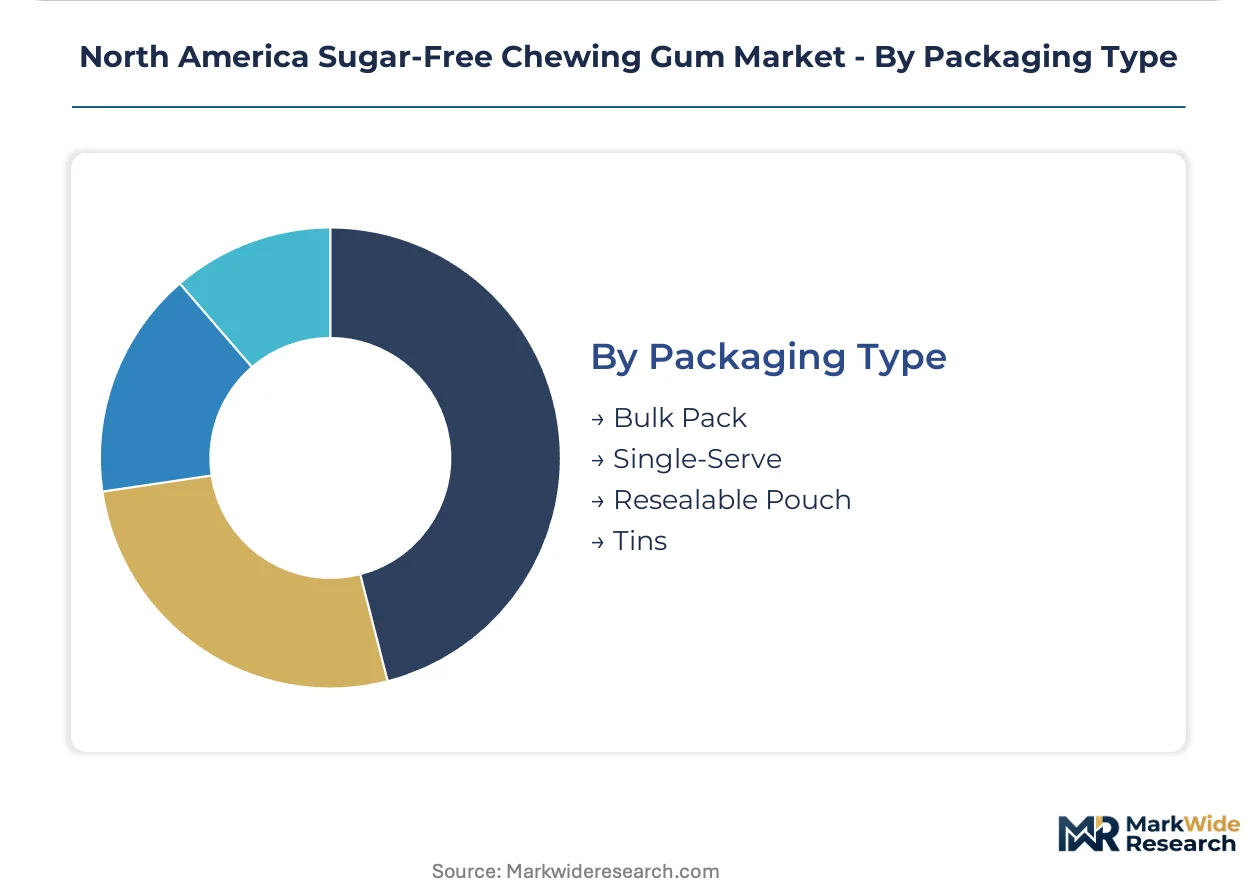
Packaging Type:
Consumption occasion and portability requirements segment packaging investment, with resealable innovations capturing commuter and travel contexts.
- Resealable Pouch:Multi-layer barrier films with zip-lock closure for freshness preservation across intermittent use. Premium natural retailers in Colorado and Massachusetts stock these for wellness-positioned brands.
- Single-Serve:Individual blister or flow-wrap units for portion control and vending compatibility. Airport convenience and urban metro channels in New York and Los Angeles generate highest throughput.
- Bulk Pack:Multi-stick trays or bags for household replenishment and cost efficiency. Club store distributors in Texas and Ohio move volume through palletized display.
- Tins:Rigid metal or plastic containers for pocket portability and crush protection. Traditional mint brands maintain presence in pharmacy checkout lanes.
Bulk Pack formats dominate household penetration; Resealable Pouch configurations climb fastest through specialty retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States and Canada, while Mexican operations supply cost-optimized base formulations for cross-border distribution. California and New York metropolitan corridors absorb premium functional gum volumes. State-level sugar tax legislation and FDA sweetener guidance create divergent compliance burdens across the three markets.
United States
California sugar taxes and New York wellness subsidies accelerate functional gum adoption in coastal metropolitan markets. FDA updated nutrition labeling requirements force reformulation away from legacy sweetener systems. Los Angeles and Manhattan dental professional endorsement programs legitimize therapeutic positioning among adult consumers.
Canada
Health Canada maintains parallel additive approval pathways that complicate cross-border product standardization for US manufacturers. Provincial labeling harmonization efforts in Ontario and Quebec reshape supply chain configuration. Toronto wellness retailers drive demand for USDA-certified organic pouch formats.
Mexico
Cost-optimized base gum production serves US private-label distributors through maquiladora operations near the border. Mexican regulators align sweetener safety standards with FDA guidance to facilitate export compliance. Baja California manufacturing clusters supply bulk polyol-sweetened formulations for North American retail channels.
California
State excise duties on sugar-sweetened beverages create relative price advantages for sugar-free alternatives in West Coast retail. Silicon Valley tech worker cohorts pilot nootropic ingredient integration for cognitive performance claims. San Francisco Bay Area subscription-direct platforms capture recurring revenue from habitual consumers.
New York
Metropolitan employer wellness subsidies and dental professional endorsement programs concentrate premium functional gum demand. State-level procurement policies favor sugar-free alternatives in workplace distribution channels. Manhattan corporate programs standardize on mint variants for breath-freshening efficacy in professional settings.
North America Sugar-Free Chewing Gum Market Competitive Landscape
The competitive structure tilts toward diversified confectionery conglomerates with integrated supply chains and specialized distribution networks. Mars Incorporated and Mondelēz International anchor the consolidated tier through captive sweetener sourcing and mass retail penetration. Mid-tier natural-positioned entrants compete on USDA organic certification and clean-label positioning. Dominant competitive moves include strategic partnerships with dental professional endorsement programs and portfolio diversification into functional claims.
Within the diversified conglomerate tier, Mars Incorporated and Mondelēz International exemplify scale-driven manufacturing and distribution integration. Mars leverages upstream control over mint and fruit flavor production. Mondelēz anchors position through specialized networks spanning convenience and mass retail channels. Among mid-tier wellness specialists, The Hershey Company occupies a premium positioning through resealable pouch formats targeting adult segments. Simply Gum Inc. represents the natural-positioned archetype competing on ingredient transparency and subscription-direct channel capture.
| Leading Market Players |
|---|
| Mars Incorporated |
| Mondelēz International Inc. |
| Perfetti Van Melle BV |
| The Hershey Company |
| Ford Gum & Machine Company Inc. |
| Simply Gum Inc. |
| The Bazooka Companies Inc. |
| Tootsie Roll Industries Inc. |
| The PUR Company Inc. |
| Others |
Pricing and Supply Chain Analysis
Flavor chemist scarcity in New Jersey and Illinois manufacturing corridors widens labor-cost differentials between premium functional formulations and commodity polyol-sweetened base products, compressing margin spreads at the standard tier.
Pricing Analysis
Margin tightening in standard-tier bubble gum traces to xylitol feedstock volatility and coating equipment capex burdens. Three-tier pricing structure across premium functional, standard polyol, and economy private-label levels separates USDA-certified organic pouch formats from mass-market stick packs. Certification grade and volume scale drive price differentiation, with bulk club store contracts showing highest buyer price sensitivity versus subscription-direct wellness platforms.
Supply Chain Analysis
Freight cost escalation from Finnish and Chinese xylitol ports to North American manufacturing hubs compresses landed cost advantages for domestic formulators. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on birch-derived and corn-derived polyol feedstocks plus specialty nootropic actives. Single-source vulnerability around Finnish xylitol producers creates structural risk. Distribution runs through mass retail, convenience, and subscription-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America sugar-free chewing gum market sits in a sweetener-transition phase, with precision fermentation-derived rare sugars displacing legacy agricultural polyol supply chains.
For Market Incumbents: Anchor market position through captive supply agreements with precision fermentation startups in Colorado and Massachusetts, while accelerating aqueous coating system conversion to defend margin structure against clean-label private-label entrants. FDA novel sweetener guidance creates regulatory moat opportunities for first-mover formulation approvals.
For New Entrants and Emerging Players: California sugar tax legislation opens a window for premium functional gum positioning in West Coast metropolitan wellness corridors, with employer wellness subsidy programs representing the most penetrable buyer segment. USDA organic certification investment unlocks Whole Foods and Sprouts distribution access.
For Investors and Strategic Acquirers: The window for entry favors mid-tier natural-positioned brands with subscription-direct channel infrastructure and dental professional endorsement relationships. Watch Health Canada-PMRA harmonization progress as inflection signal for cross-border supply chain consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Secures rare sugar supply independent of Finnish and Chinese xylitol concentration. |
| USDA Organic Certification Investment | Unlocks premium shelf placement in Sprouts and Whole Foods distribution networks. |
| Dental Professional Endorsement Program | Legitimizes therapeutic positioning among Los Angeles and Manhattan wellness consumers. |
| Subscription-Direct Platform Buildout | Captures recurring revenue and customer data ownership from habitual gum purchasers. |
| Aqueous Coating System Conversion | Meets clean-label demands while extending R&D timelines for mid-tier manufacturers. |
Research Methodology
Multi-period observation of FDA sweetener approval timelines, state sugar tax legislative trajectories, and dental professional endorsement program expansion anchored the trend analysis, supplemented by interviews with brand managers at diversified confectionery conglomerates, category buyers at mass retail and club store channels, flavor chemists specializing in sustained-release encapsulation, supply planners at polyol distributors, and regulatory affairs leads navigating Health Canada additive pathways. Secondary validation drew from FDA guidance documents, USDA organic certification databases, Nielsen retail audit data, and customs import records for xylitol and sorbitol feedstocks. Bottom-up volume modeling and top-down value reconciliation ensured triangulation integrity.
Input-output matrices mapped elastomer raw material flows through mixing, rolling, and coating processes to finished product value across functional gum, bubble gum, mint, and chewy candy categories, segmented by product type, end user life stage, flavor profile, and packaging format. CAGRs derived from regression analysis of historical replacement frequency data and projected wellness program penetration rates. Forecast inputs included employer wellness subsidy adoption curves and precision fermentation capacity buildout timelines.
The model assumes a particular technology adoption path for precision fermentation-derived sweeteners; alternative pathways for biotechnology scale-up would alter the outlook. Forecasts reflect assumptions about regulatory harmonization progress and raw material cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Liquorice Shellac Market
Confectionery
Cookie Dough Market
Confectionery
Milk Chocolate Market
Confectionery
Low-Calorie Candy Market
Confectionery
Chocolate Couverture Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Global Chocolate Market
Confectionery
Sugar Free Candy Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Xylitol Lollipops Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Europe Premium Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
Fruit Jellies Market