
 Asia Pacific Chocolate Market | 2026-2036
Asia Pacific Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Chocolate Market Analysis
The cocoa-processing capability gap between integrated grinders and brand-only confectioners is rotating competitive advantage toward companies with upstream supply control. Barry Callebaut leverages its bean-to-bar infrastructure to secure industrial contracts across Southeast Asia. Meiji Holdings anchors its position through deep R&D intensity in functional chocolate formulations. Nestlé competes via brand strength and shelf-space dominance in modern retail channels.
Asia Pacific chocolate comprises cocoa mass, cocoa butter, sugar, and milk solids formulated through conching, tempering, and molding processes into solid or filled confectionery products for direct consumption or industrial ingredient use. Milk chocolate occupies the largest volume share due to mass-market familiarity, while dark chocolate commands the fastest value expansion as consumers prioritize higher cocoa percentages and reduced sugar content. The food service segment differentiates through premium couverture demand from bakery and dessert chains, whereas confectionery manufacturers concentrate procurement on bulk compound coatings to manage input costs.
Japan's Ministry of Health, Labour and Welfare and Food and Drug Administration standards, alongside China's National Health Commission food safety frameworks, shape product formulation, additive allowances, and import clearance protocols across the region. FSSAI labeling mandates in India and Australia's Food Standards Code further fragment compliance requirements for multinational suppliers. Stakeholders must monitor evolving sugar taxation regimes and cocoa sustainability certification thresholds to anticipate margin compression and sourcing qualification barriers.
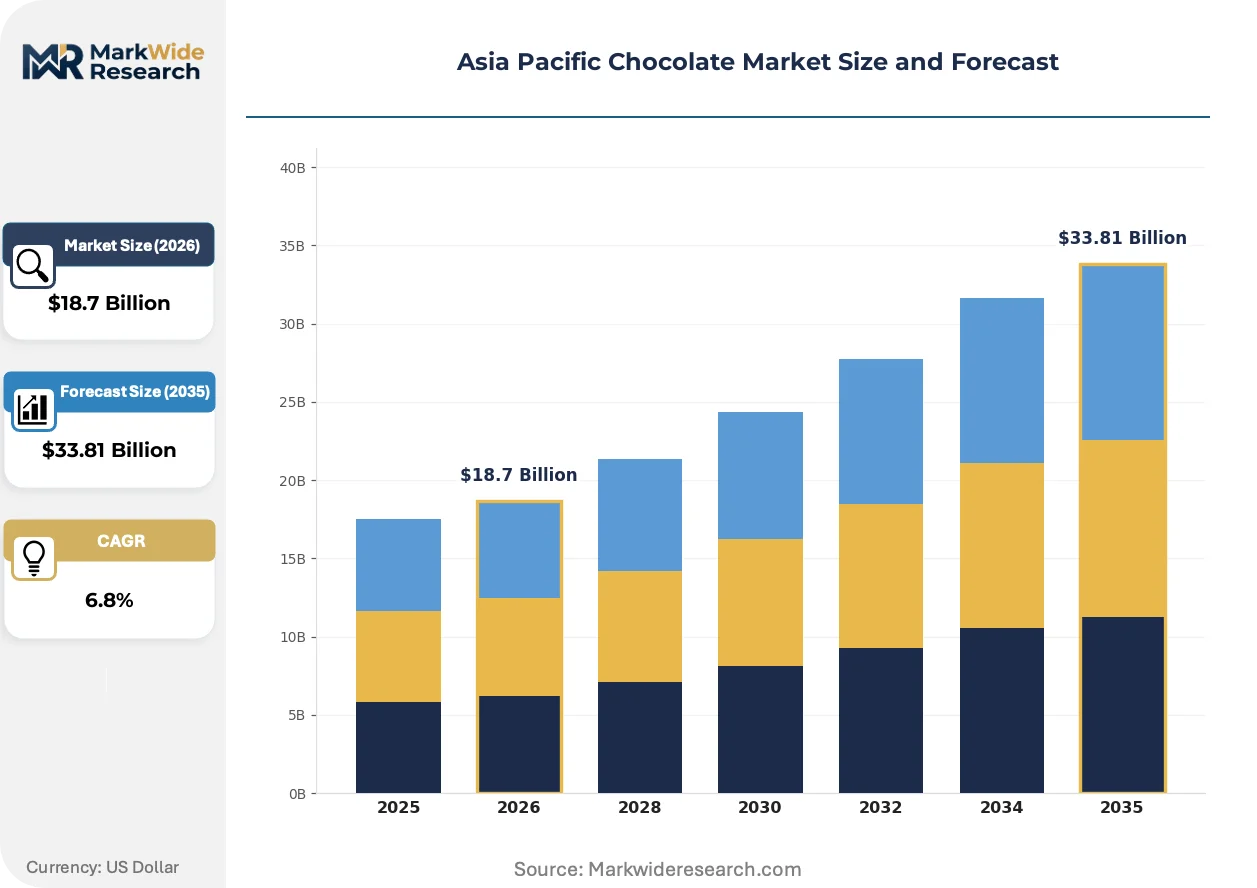
Market Dynamics
Japan's Ministry of Health, Labour and Welfare labeling mandates and China's National Health Commission food safety frameworks are forcing reformulation investments across the Asia Pacific chocolate supply chain. The tension between premium positioning and compliance costs is redrawing competitive boundaries between integrated processors and brand-only confectioners.
Growth Catalysts
- Urban Middle-Class Expansion:China's tier-one and tier-two cities are generating concentrated demand for premium chocolate gifting occasions. This consumer segment prioritizes cocoa percentage transparency and origin traceability in purchase decisions.
- FSSAI Streamlining:India's Food Safety and Standards Authority is harmonizing import clearance protocols for cocoa derivatives, reducing time-to-market for multinational suppliers entering the subcontinent.
- Functional Formulation R&D:Probiotic and reduced-sugar chocolate variants are capturing shelf space in Japanese convenience retail channels. Meiji Holdings and domestic competitors are accelerating clinical validation partnerships with regional research institutes.
Market Restraints
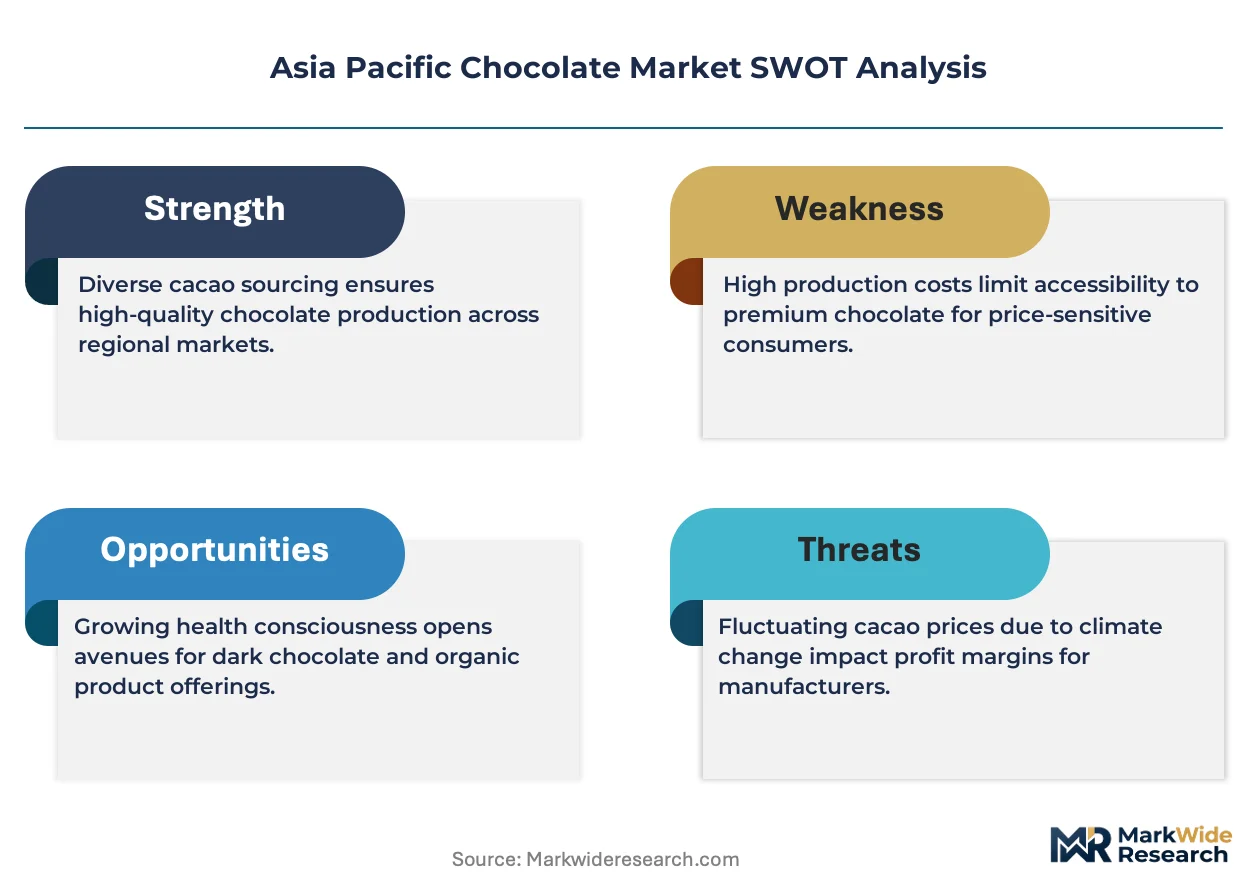
- Cocoa Butter Price Volatility:West African supply interruptions transmit directly to Asia Pacific manufacturing cost structures. Grinders with captive bean sourcing maintain margin stability that brand-only players cannot replicate.
- Fragmented Regulatory Compliance:Australia's Food Standards Code, India's FSSAI mandates, and Japan's MHLW requirements create overlapping certification burdens. Multinational suppliers face redundant testing expenditures across national boundaries.
- Sugar Taxation Escalation:Thailand and Philippines fiscal measures on sugar-sweetened confectionery are compressing volume demand in mass-market milk chocolate segments. Reformulation to alternative sweeteners requires capital-intensive process reconfiguration.
Strategic Opportunities
- Vietnam and Indonesia Underpenetration:Modern retail infrastructure expansion in secondary Vietnamese cities and Indonesian provincial centers is creating first-mover positioning for premium chocolate entrants. Local distribution partnerships remain underdeveloped relative to China saturation.
- E-Commerce Gifting Platforms:Tmall, Lazada, and Shopee festival-specific chocolate assortments are displacing traditional brick-and-mortar seasonal purchasing. Direct-to-consumer data capture enables precision flavor localization.
- Sustainability Certification Tailwinds:Rainforest Alliance and Fairtrade label recognition is accelerating among South Korean and Australian ethical consumption segments. Retailers are mandating certified sourcing as private-label entry conditions.
Industry Challenges
- Confectionery Technologist Scarcity:Tempering and couverture formulation expertise concentrates in Japan and Australia, creating recruitment bottlenecks for Southeast Asian production facility expansions. Technical training institute capacity lags industry demand.
- Cold Chain Integrity:Chocolate bloom and fat migration risks during tropical climate distribution require refrigerated logistics investments that erode margin in price-sensitive compound coating segments. Last-mile temperature monitoring remains inconsistent across Indonesian archipelago shipping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Chocolate Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Form: Bar, Box, Chip, Spread End User: Retail Consumers, Food Service, Industrial, Confectionery Manufacturers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Mondelez International, Nestlé, Mars Incorporated, Ferrero International, Meiji Holdings, Morinaga & Co., Lotte Confectionery, Chocoladefabriken Lindt & Sprüngli, Barry Callebaut, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Chocolate Market Emerging Trajectories
Bean-to-bar traceability systems and alternative protein integration are redefining product architecture across the Asia Pacific chocolate value chain. These developments are compressing traditional manufacturing advantages while opening white space for technology-enabled entrants.
Precision fermentation-derived cocoa butter alternatives are fragmenting raw material sourcing strategies for mid-tier confectionery manufacturers. Singapore and South Korean food-tech startups are scaling microbial lipid production facilities targeting price parity with conventional cocoa butter by 2027. This technology is fragmenting the historical grinder-supplier relationship that has governed industrial chocolate procurement for decades.
China's National Health Commission is tightening maximum residue limits for pesticide contaminants in imported cocoa beans, effective across all SAMR-registered food imports. This regulatory tightening is accelerating laboratory testing infrastructure investments at major entry ports including Shanghai and Shenzhen. European and West African exporters with established quality management systems are capturing preferential clearance timelines versus smaller origin suppliers.
Gifting assortments are displacing individual bar purchasing as the dominant transaction format in Chinese and South Korean premium chocolate. Department store confectionery counters and brand flagship stores are ceding volume to curated subscription boxes and limited-edition collaborative releases. This behavioral shift is most visible in Shanghai and Seoul, where social media-driven unboxing content generates organic marketing velocity that traditional advertising cannot replicate.
Asia Pacific Chocolate Market Segmentation
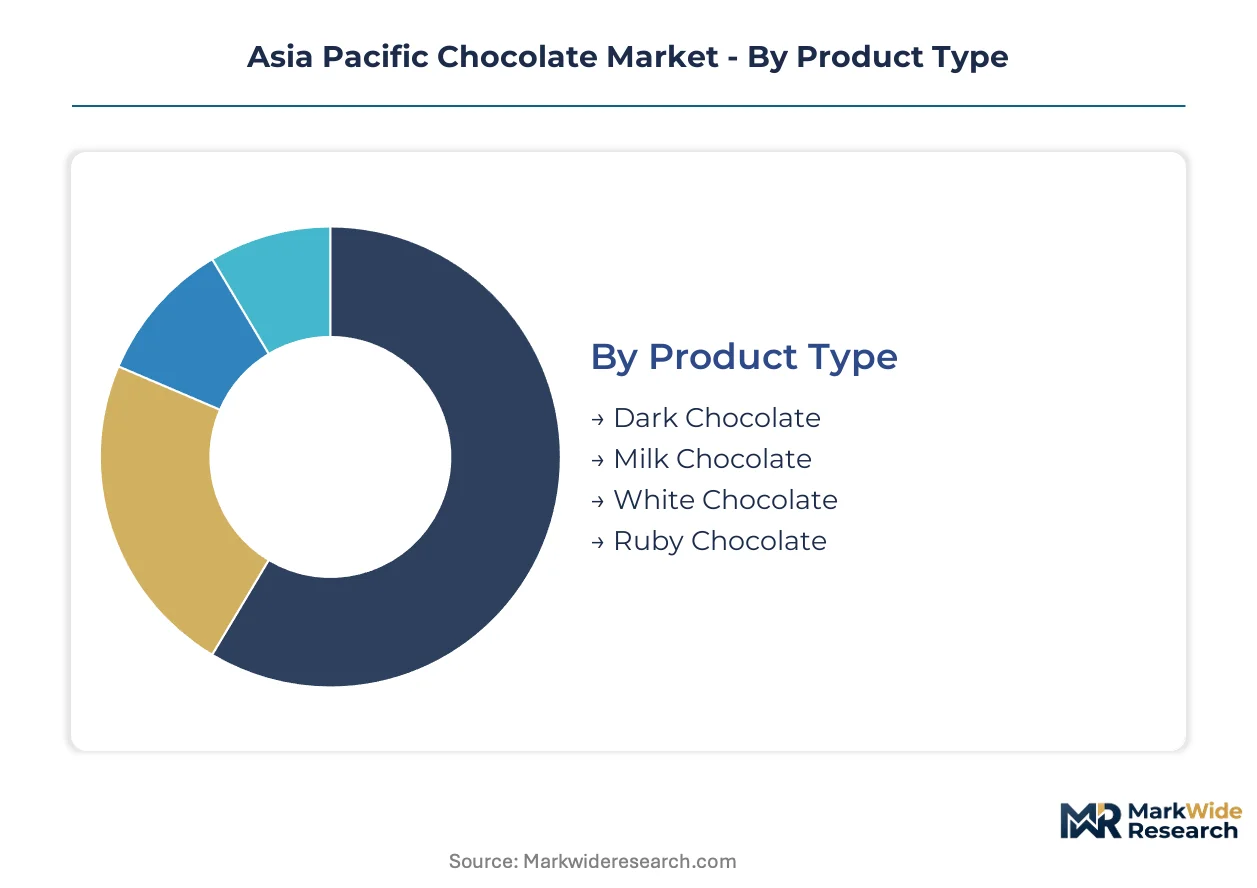
Segmentation in Asia Pacific chocolate reveals how product architecture, channel access, and end-use specifications fragment procurement requirements across the value chain. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Channel mix varies sharply by cocoa content and positioning tier, with premium variants concentrating in specialty retail and gifting platforms while mass formulations dominate modern trade.
- Dark Chocolate:Higher cocoa percentage formulations (70%+) command shelf space in Japanese department store confectionery counters and South Korean premium gifting platforms. Chinese tier-one cities drive the steepest expansion trajectory as consumers prioritize reduced sugar content and origin traceability.
- Milk Chocolate:Standard cocoa-sugar-milk solid formulations anchor volume across Southeast Asian supermarkets and convenience retail. Thailand and Philippines sugar taxation regimes compress margin in this segment, forcing reformulation to alternative sweeteners.
- White Chocolate:Cocoa butter-dominant recipes without cocoa solids serve bakery and dessert chain industrial demand across Vietnam and Indonesia.
- Ruby Chocolate:Barry Callebaut's proprietary cultivar-derived variant captures limited-edition releases in Australian and Japanese premium channels.
Milk chocolate dominates installed base. Dark chocolate is where expansion concentrates.
Form:
Cost tier stratification separates artisan production from industrial scale, with labor-intensive formats commanding premium positioning and commodity forms serving ingredient procurement.
- Bar:Standard molded and wrapped single-serve or sharing formats constitute the baseline transaction unit across all retail channels. Individual bar purchasing is ceding volume to gifting assortments in Chinese and South Korean premium segments.
- Box:Curated assortments with partitioned packaging dominate festival-specific purchasing on Tmall, Lazada, and Shopee platforms. Social media unboxing content generates organic marketing velocity in Shanghai and Seoul.
- Chip:Industrial-scale drops and callets serve confectionery manufacturer compound coating requirements and bakery chain couverture demand across Southeast Asia.
- Spread:Cocoa butter and sugar-based pastes capture breakfast and bakery application demand in Australian and Indian retail channels.
Bar formats dominate installed base. Box assortments are where expansion concentrates.
End User:
Application-specific formulation requirements fragment procurement, with food service demanding tempering-stable couverture and industrial buyers prioritizing cost-managed compound coatings.
- Retail Consumers:Direct consumption purchasing concentrates in urban middle-class households across Chinese tier-one and tier-two cities. Gifting occasions and self-treat behaviors drive premium chocolate demand with cocoa percentage transparency requirements.
- Food Service:Bakery and dessert chains in Japan, South Korea, and Australia demand premium couverture with defined viscosity and tempering characteristics. Cold chain integrity requirements erode margin in tropical climate distribution.
- Industrial:Ingredient procurement for processed food manufacturing concentrates on bulk compound coatings with managed input costs.
- Confectionery Manufacturers:Regional chocolate product producers source cocoa mass and butter through grinder relationships or bean-to-bar integrated suppliers.
Retail consumers dominate installed base. Food service is where expansion concentrates.
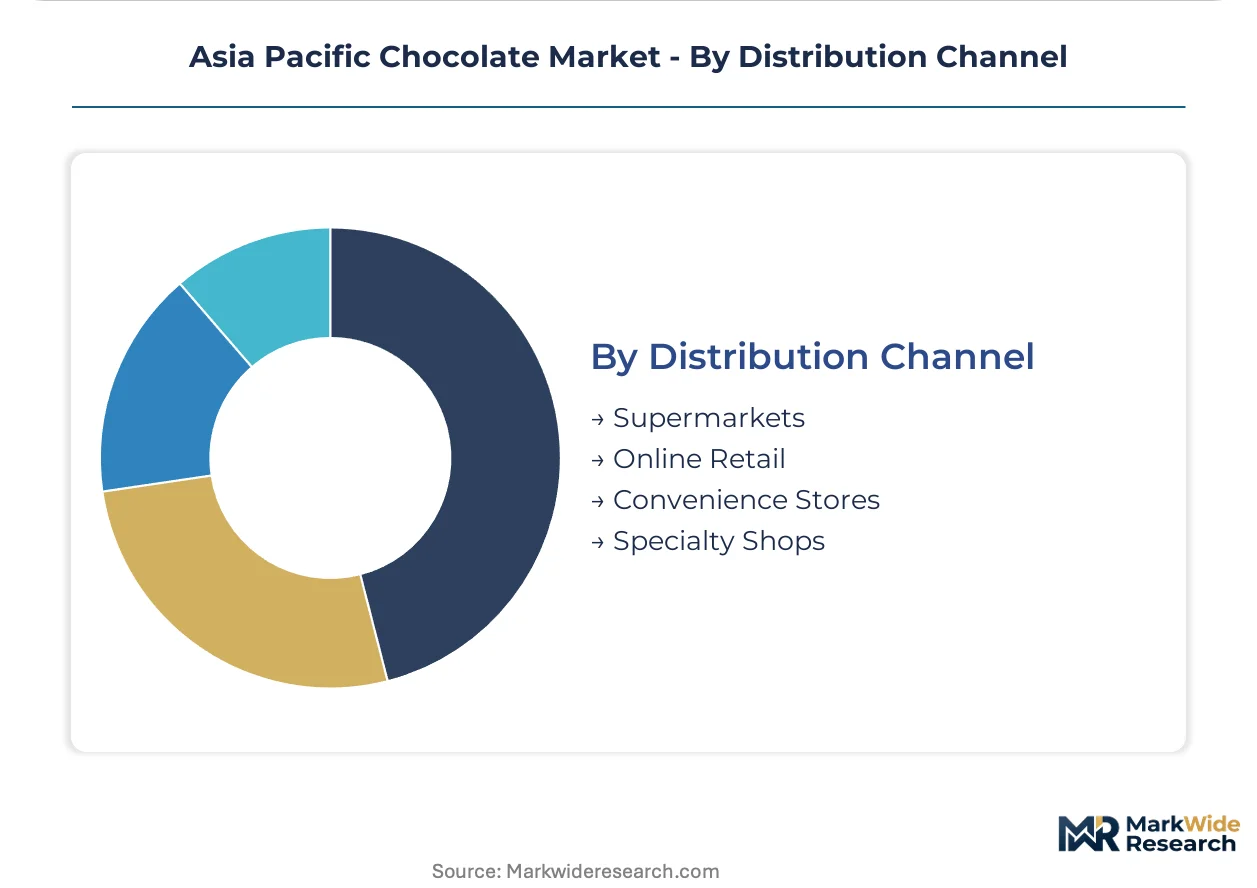
Distribution Channel:
Geographic penetration depth separates mature urban infrastructure from emerging provincial center development, with e-commerce platforms displacing traditional seasonal purchasing patterns.
- Supermarkets:Modern trade chains anchor mass-market milk chocolate volume across established urban retail infrastructure. Shelf-space dominance by multinational brands shapes competitive access.
- Online Retail:Tmall, Lazada, and Shopee festival-specific assortments enable direct-to-consumer data capture for precision flavor localization. Subscription box models capture gifting demand in Chinese and South Korean markets.
- Convenience Stores:Japanese konbini chains and Southeast Asian 7-Eleven networks distribute functional formulation variants including probiotic and reduced-sugar options.
- Specialty Shops:Department store confectionery counters and brand flagship stores in Tokyo, Seoul, and Shanghai serve premium positioning with origin storytelling and limited-edition releases.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands premium pricing power that Southeast Asian markets cannot replicate, while Japan's functional chocolate segment sustains margin premiums unavailable elsewhere in the region. This geographic asymmetry shapes capital allocation and portfolio prioritization for multinational suppliers.
China
Urban middle-class households in Shanghai, Beijing, and Shenzhen drive concentrated demand for high-cocoa-percentage gifting assortments. SAMR-registered food imports face tightened maximum residue limits for pesticide contaminants, favoring established exporters with quality management systems. Tier-one and tier-two cities generate the steepest expansion trajectory as consumers prioritize origin traceability.
Japan
Convenience retail channels distribute probiotic and reduced-sugar functional variants to aging urban populations. MHLW labeling mandates force reformulation investments that raise compliance barriers for import-dependent suppliers. Tokyo and Osaka anchor R&D partnerships between domestic manufacturers and regional research institutes.
India
FSSAI harmonization of import clearance protocols is reducing time-to-market for cocoa derivatives entering Mumbai and Delhi distribution networks. Sugar taxation pressures remain lighter than Southeast Asian peers, preserving volume elasticity in mass-market milk chocolate. Maharashtra and Gujarat concentrate emerging production facility investments.
South Korea
Premium gifting platforms and subscription box models displace traditional department store purchasing in Seoul. MFDS standards align with international frameworks, reducing redundant certification burdens relative to multi-regulatory environments. Ethical consumption segments accelerate Rainforest Alliance and Fairtrade label recognition.
Australia
Food Standards Code requirements fragment compliance architecture for multinational suppliers serving Sydney and Melbourne retail channels. Premium couverture demand from bakery and dessert chains supports higher-margin positioning than commodity compound coatings. Cold chain infrastructure exceeds Southeast Asian reliability standards.
Asia Pacific Chocolate Market Vendor Landscape
Concentration sits with integrated cocoa processors and diversified confectionery conglomerates that span multiple price tiers. The competitive structure rewards backward integration into bean sourcing and grinding capacity, while brand-only players face margin compression from input cost volatility. Strategic archetypes include bean-to-bar integrated suppliers, functional formulation specialists, and mass-market brand owners. Dominant competitive moves encompass geographic expansion into underpenetrated Southeast Asian markets and portfolio diversification toward reduced-sugar and certified-sustainable variants.
Within the integrated processing tier, Barry Callebaut exemplifies upstream supply control through captive grinding infrastructure. Meiji Holdings occupies a position within the functional formulation specialist archetype, anchoring clinical validation partnerships for probiotic and health-positioned variants. Nestlé sits within the diversified conglomerate tier, leveraging shelf-space dominance across modern retail channels in China and Southeast Asia.
| Leading Market Players |
|---|
| Mondelez International |
| Nestlé |
| Mars Incorporated |
| Ferrero International |
| Meiji Holdings |
| Morinaga & Co. |
| Lotte Confectionery |
| Chocoladefabriken Lindt & Sprüngli |
| Barry Callebaut |
| Others |
Supply Flow & Price Mechanics
Precision fermentation-derived cocoa butter alternatives are displacing conventional bean-sourced inputs across Southeast Asian manufacturing, simultaneously shifting procurement geography toward Singapore and South Korean food-tech clusters while compressing historical grinder premiums. This substitution dynamic is redrawing margin structures between integrated processors and brand-only confectioners who lack captive supply control.
Pricing Analysis
The customization-premium spread separates artisan bean-to-bar formulations from mass-market compound coatings across the Asia Pacific chocolate value chain. Three-tier pricing structure across premium, standard, and economy levels reflects cocoa percentage transparency, origin traceability certification, and tempering-stable couverture specifications as primary differentiation drivers. Cost compression in mass-market milk chocolate segments intensifies as Thailand and Philippines sugar taxation regimes force reformulation investments. Industrial buyers sourcing bulk compound coatings exhibit highest price sensitivity, while Japanese department store confectionery counters and South Korean gifting platforms absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Côte d'Ivoire and Ghana anchor global cocoa bean production that feeds Asia Pacific grinding infrastructure, with Indonesia and Malaysia hosting regional processing capacity for cocoa mass and butter derivatives. Manufacturing draws from West African bean supply, Southeast Asian palm oil derivatives for compound coatings, and emerging microbial lipid production from Singaporean biotech facilities. Single-source vulnerability concentrates in West African origin dependence where climate disruption and political instability transmit directly to input cost volatility. Distribution runs through refrigerated logistics networks serving tropical climate markets, with cold chain integrity requirements eroding margin in price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific chocolate market rewards specialized formulation expertise that remains scarce outside Japan and Australia, creating defensive moats for incumbent players with established technical training pipelines and R&D partnerships.
For Market Incumbents: Fortify upstream supply control through grinder relationship deepening or captive bean sourcing investments to insulate margin from cocoa butter price volatility. Prioritize clinical validation partnerships for functional chocolate variants in Japanese convenience retail channels, defending shelf position against emerging probiotic-focused entrants. For New Entrants and Emerging Players: Rainforest Alliance and Fairtrade certification fast-tracks unlock private-label entry conditions at Australian and South Korean retailers mandating ethical sourcing standards. Target Vietnam and Indonesia provincial centers where modern retail infrastructure expansion outpaces local distribution partnership development, leveraging e-commerce platform direct-to-consumer models to bypass established channel gatekeepers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated processors with backward supply control over brand-only confectioners facing persistent input cost volatility. Acquisition targets should demonstrate established quality management systems qualifying for preferential SAMR clearance timelines at Chinese entry ports. The signal to watch is precision fermentation scale-up achieving price parity with conventional cocoa butter, which would fragment historical grinder-supplier relationships and reset valuation multiples across mid-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Bean-to-Bar Traceability Investment | Origin storytelling commands premium positioning in Chinese tier-one gifting assortments. |
| Functional Formulation R&D Partnership | Clinical validation with Japanese research institutes secures probiotic shelf space in konbini chains. |
| E-Commerce Platform Direct Launch | Tmall and Shopee festival-specific assortments enable precision flavor localization through data capture. |
| Sustainability Certification Acquisition | Rainforest Alliance labeling satisfies South Korean retailer private-label entry mandates. |
| Cold Chain Infrastructure Expansion | Refrigerated logistics investments protect couverture integrity across Indonesian archipelago distribution. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at multinational confectionery conglomerates, category buyers at Chinese and Japanese retail chains, cocoa procurement leads at integrated grinders, and technical R&D directors specializing in tempering and couverture formulation. Secondary validation drew from FSSAI import clearance databases, Japan MHLW labeling mandate filings, SAMR-registered food import quality management records, and customs trade data for cocoa derivative flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the analysis window, the analytical framework modeled volume and value outputs through segmentation across product type, form, end user, and distribution channel dimensions, with additional granularity on cocoa percentage tiers and certification status. CAGRs were derived from trend extrapolation adjusted for regulatory intervention impacts including sugar taxation escalation and pesticide residue limit tightening. Forecast inputs incorporated urban middle-class household formation rates in Chinese tier-one and tier-two cities, modern retail infrastructure expansion trajectories in Vietnamese and Indonesian provincial centers, and precision fermentation scale-up timelines from Singaporean and South Korean food-tech startups.
Decision-makers should treat outputs as directional under assumptions of continued West African bean supply availability and stable regulatory enforcement intensity across Japan MHLW, China SAMR, and India FSSAI jurisdictions; material deviation in cocoa price volatility or accelerated sustainability mandate adoption would warrant model refresh. Recalibration cycles align with material shifts in sugar taxation regime expansion, cold chain infrastructure investment patterns, and alternative protein integration scale-up milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low Calorie Sweets Market
Confectionery
Durian Chocolate Market
Confectionery
Low-Fat Candy Market
Confectionery
UK Chocolate Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
North America Marshmallow Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Sugar-Free Sweets Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Caramel Market
Confectionery
Global Confectionery Market
Confectionery
North America Dark Chocolate Market