
 Nutraceutical Gummies Market | 2026-2036
Nutraceutical Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Gummies Market Outlook
Clean-label and organic certification tiers is redrawing competitive boundaries in the Nutraceutical Gummies Market. Bayer AG leverages its pharmaceutical heritage to anchor credibility in clinical-grade formulations. Nestlé sustains broad retail penetration through shelf-stable distribution infrastructure. Church & Dwight Co., Inc. differentiates via specialized probiotic gummy lines targeting digestive wellness segments.
Nutraceutical gummies are chewable confectionery-delivery vehicles containing bioactive compounds such as vitamins, minerals, or botanical extracts, typically formulated with gelatin or pectin matrices and standardized to specific potency thresholds per serving unit. Their primary commercial purpose is to improve supplement adherence among consumers who resist traditional tablets or capsules. Vitamins dominates current volume as the most mature product type with established supply chains and retail placement. Probiotics represents the fastest-expanding segment due to rising gut-health awareness and refrigerated distribution innovations that preserve colony-forming unit stability. Online Retail channels capture disproportionate margin pools through subscription models and direct-to-consumer personalization.
FDA oversees dietary supplement labeling and good manufacturing practice compliance in the United States, while EFSA sets novel food and health claims standards across European markets, and China's SAMR enforces registration requirements for imported nutraceutical products under food and health food classifications. These frameworks elevate barrier costs for new entrants but simultaneously validate premium pricing for compliant manufacturers. Stakeholders must monitor evolving pectin supply constraints and shifting clean-label certification requirements to secure formulation continuity and market access.
Market Dynamics
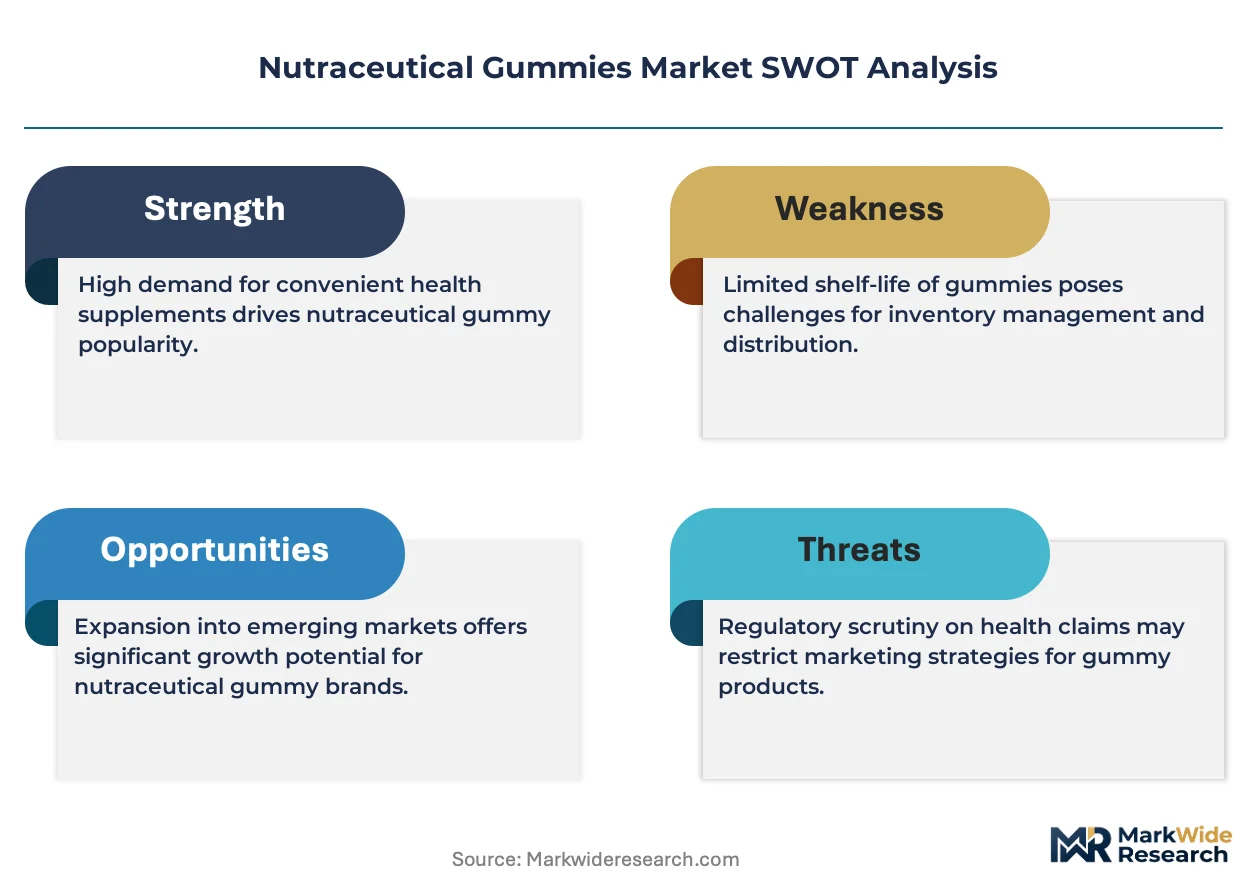
Pectin supply concentration and clean-label certification requirements are restructuring competitive boundaries, forcing manufacturers to secure alternative gelling agents and transparent sourcing documentation to maintain market access.
Growth Catalysts
- Pediatric wellness demand:Households with children are adopting multivitamin gummies as gateway products, creating spillover demand for adult formulations across Germany and the United States.
- REACH compliance elevation:EFSA's tightening novel food assessments validate premium positioning for European manufacturers with documented supply chain traceability.
- Refrigerated distribution innovation:Cold-chain logistics investments preserve probiotic colony-forming unit stability, unlocking pharmacy and clinical channel placement previously reserved for capsules.
Market Restraints
- Pectin cost volatility:Citrus peel supply disruptions from climate stress in Spain and Mexico are compressing margins for clean-label formulators.
- SAMR registration timelines:China's 18-24 month health food approval process creates working capital strain for importers targeting pharmacy shelves.
- Tablet substitution resilience:Medicare and private insurers maintain broader reimbursement for traditional supplement formats, limiting gummy penetration in senior segments.
Strategic Opportunities
- India's FSSAI pathway:Functional food regulations are clarifying, opening pharmacy and modern trade channels for clinically positioned entrants.
- Sports nutrition convergence:Electrolyte and amino acid gummies are displacing powder formats among recreational athletes in Australia and Brazil.
- Subscription direct-to-consumer:Personalized vitamin stacks delivered on 30-day cycles capture recurring revenue with higher lifetime value than retail.
Industry Challenges
- Formulation scientist scarcity:Cross-functional expertise in confectionery science and bioactive stability is concentrated among a narrow talent pool in Switzerland and the Netherlands.
- ISO 22000 certification backlog:Third-party audit capacity constraints are extending food safety management system timelines by 4-6 months for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Gummies Market |
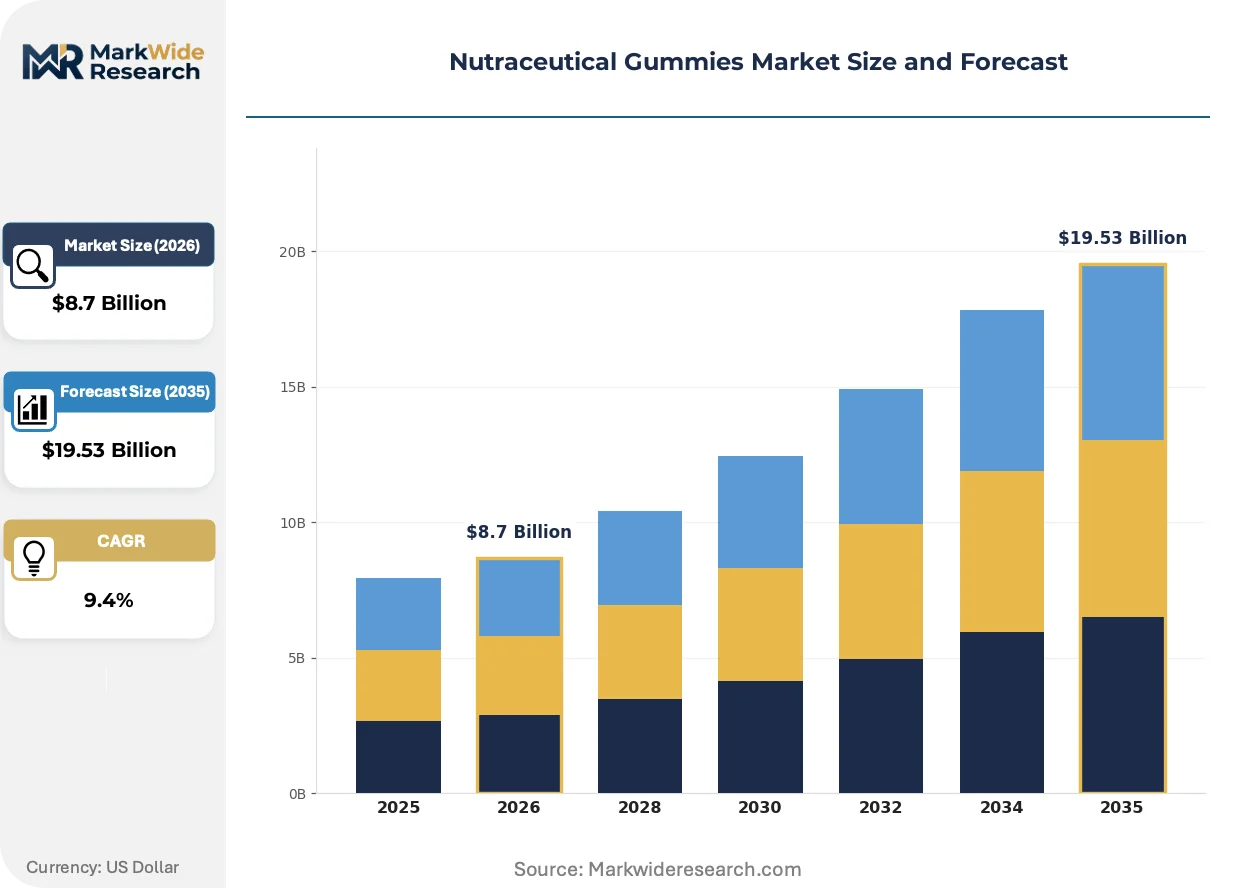
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Probiotics Target Consumer: Children, Adults, Seniors, Fitness Enthusiasts Flavor Profile: Fruit, Berry, Citrus, Herbal Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Church & Dwight Co., Inc., H&H Group, Bayer AG, Haleon, Nestlé, Unilever, Pharmavite, Amway, Hero Nutritionals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Gummies Market Strategic Shifts
Delivery format innovation and regulatory transparency requirements are compressing development cycles while fragmenting competitive positioning between clinical-grade and lifestyle-oriented product tiers.
Microencapsulation technology for heat-sensitive actives is bifurcating the contract manufacturing landscape. Brands targeting pharmacy placement in Germany and the United States are adopting lipid-based shell systems to protect probiotics during ambient distribution. This capability divide is separating full-service manufacturers with in-house R&D from commodity gummy producers confined to vitamin-only portfolios.
EFSA's 2023 guidance on botanical health claims is tightening evidentiary standards for European market entry. Manufacturers must now commission human intervention studies for immune and cognitive positioning statements. French and Italian brands with legacy herbal portfolios are reformulating toward structure-function claims or withdrawing SKUs rather than absorbing clinical trial costs.
Pharmacy buyers in the United States are consolidating supplier relationships around vendors with dual FDA cGMP and NSF Certified for Sport credentials. This certification-driven procurement compression favors manufacturers with existing quality infrastructure, squeezing regional players dependent on undifferentiated contract manufacturing. Independent retailers and practitioner channels represent the remaining accessible entry points for emerging brands lacking enterprise-scale compliance investment.
Nutraceutical Gummies Market Segmentation
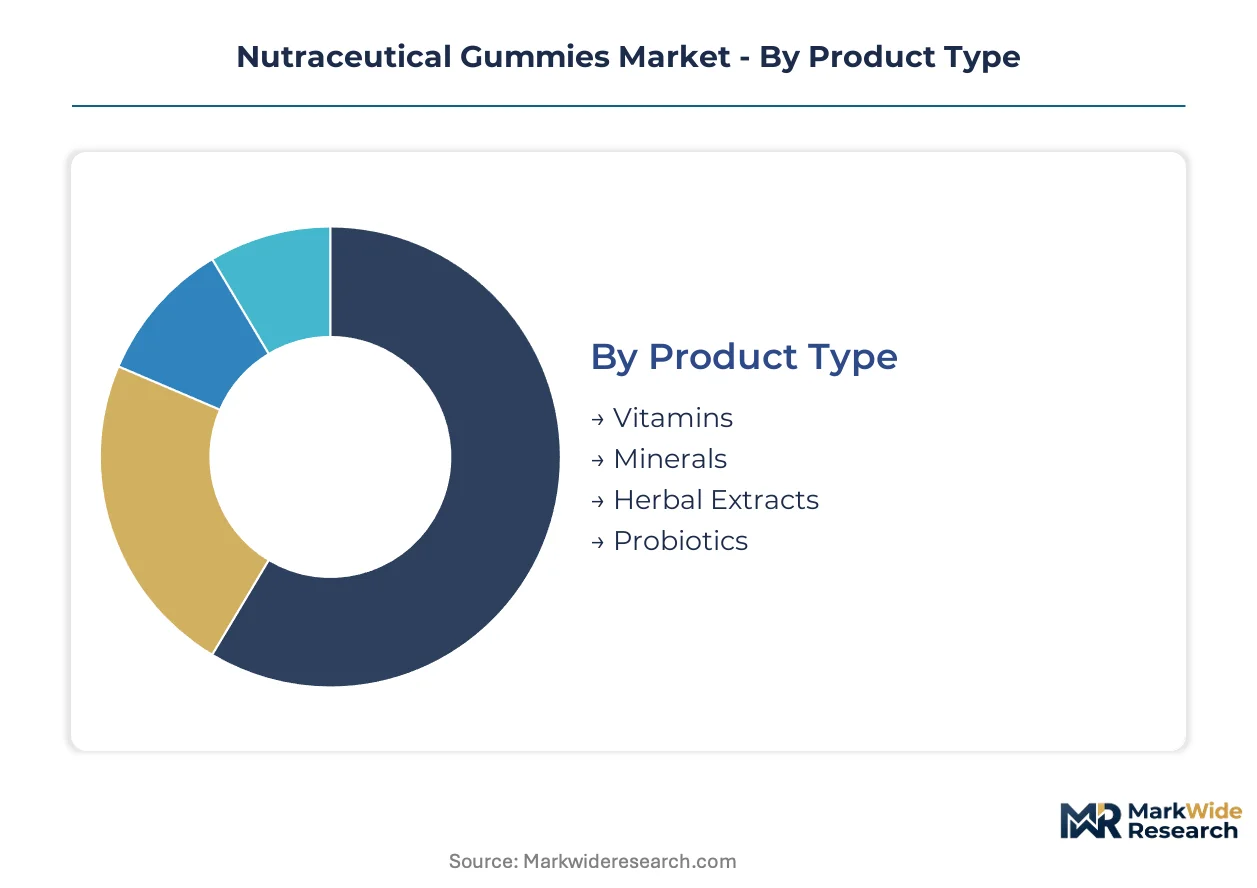
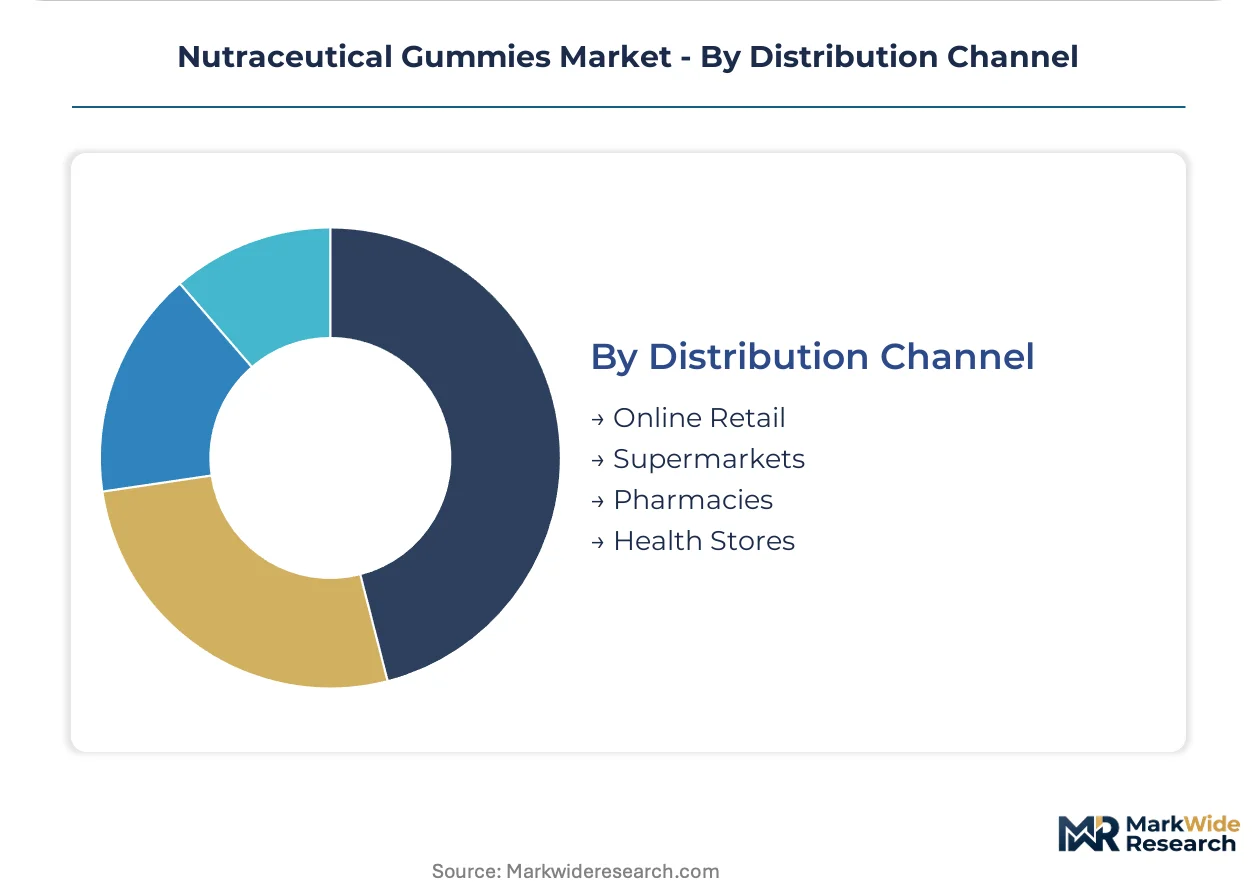
Nutraceutical gummies segment along four distinct axes that determine formulation complexity, regulatory pathway, and margin capture. Product type and distribution channel exert the strongest influence on pricing power, while target consumer shapes clinical positioning requirements.
Product Type:
Vitamins command the deepest margin pools through established retail placement and minimal stability engineering, while probiotics extract premium pricing from cold-chain infrastructure investments.
- Vitamins:Multivitamin and single-nutrient matrices dominate current volume through standardized potency testing and ambient distribution compatibility. Demand concentrates in pediatric and adult preventive wellness segments across Germany and the United States, driven by household gateway purchasing behavior that expands to full-family coverage.
- Probiotics:Live colony-forming units require microencapsulation or refrigerated logistics to maintain viability through shelf life. Pharmacy channel placement in Switzerland and the Netherlands is accelerating as lipid-shell technologies mature, displacing capsule formats among gut-health-focused consumers.
- Minerals:Chelated iron and calcium formulations address absorption bioavailability challenges through organic salt complexes.
- Herbal Extracts:Botanical actives face EFSA evidentiary tightening for immune and cognitive claims, forcing reformulation toward structure-function positioning.
Vitamins holds installed capacity. Probiotics is rotating up the share rankings.
Target Consumer:
Volume concentrates in adult maintenance segments, though pediatric positioning generates household spillover effects that reshape adult purchasing patterns.
- Children:Palatable delivery formats overcome compliance resistance in households with nutritional gaps, creating brand loyalty transfer to parental purchasing. Germany's pharmacy channels prioritize child-specific SKUs with documented safety profiles.
- Adults:Preventive wellness and stress-management positioning capture recurring subscription revenue through direct-to-consumer platforms.
- Seniors:Medicare reimbursement gaps for gummy formats limit penetration despite swallowing-difficulty advantages among aging populations.
- Fitness Enthusiasts:Electrolyte and branched-chain amino acid gummies displace powder formats in Australia and Brazil recreational sports segments.
Adults anchor current revenue. Children is climbing the fastest as household entry point.
Flavor Profile:
Flavor selection determines clean-label certification viability and masks off-notes from botanical or mineral actives without synthetic masking agents.
- Fruit:Apple and tropical profiles dominate mass-market positioning with broad demographic acceptance.
- Berry:Antioxidant association and natural color stability from anthocyanins support premium tier placement.
- Citrus:Vitamin C correlation and pectin compatibility from citrus peel sourcing create formulation synergy.
- Herbal:Ginger and elderberry profiles align with immune-positioned SKUs requiring sophisticated bitterness management.
Berry commands formulation investment. Citrus gains traction through supply chain verticality.
Distribution Channel:
Channel selection dictates regulatory burden, margin retention, and consumer relationship depth more than any other segmentation axis.
- Online Retail:Subscription models and personalized stack configurations capture lifetime value multiples above retail through direct consumer data ownership. Cold-chain capabilities unlock probiotic pharmacy-equivalent placement without brick-and-mortar infrastructure.
- Supermarkets:Shelf-stable vitamin portfolios achieve velocity through impulse placement and promotional pricing, though margin compression from slotting fees challenges smaller manufacturers.
- Pharmacies:Clinical-grade formulations with dual FDA cGMP and NSF Certified for Sport credentials consolidate supplier relationships around quality-verified vendors.
- Health Stores:Independent retailers and practitioner channels represent accessible entry points for emerging brands lacking enterprise-scale compliance investment.
Supermarkets maintains volume leadership. Online Retail is expanding most quickly through recurring revenue mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in nutraceutical gummies concentrate in advanced manufacturing economies with established pharmaceutical infrastructure. Germany and the United States maintain trade surpluses in clinical-grade formulations, while China absorbs substantial pectin and gelatin raw material imports to feed domestic production expansion.
United States
Pediatric wellness demand and pharmacy channel consolidation drive volume concentration on the coasts. FDA cGMP enforcement and NSF Certified for Sport procurement standards elevate compliance costs for entrants. New Jersey and California host contract manufacturing clusters where lipid-shell microencapsulation capabilities are scaling to serve probiotic stability requirements.
Germany
Pharmacy-first distribution and preventive wellness culture sustain premium positioning for multivitamin and mineral matrices. EFSA novel food assessments and REACH compliance documentation requirements validate supply chain traceability investments. Bavaria and Baden-Württemberg concentrate formulation R&D facilities alongside confectionery science talent pools.
China
Domestic consumption of palatable supplement formats accelerates as middle-class households shift from traditional medicine. SAMR health food registration timelines and dual carbon goals reshape ingredient sourcing toward plant-based gelling agents. Shanghai and Guangdong province anchor manufacturing capacity for both domestic pharmacy shelves and Southeast Asian export markets.
Switzerland
Precision positioning in clinical-grade probiotics and botanical extracts commands price premiums across European pharmacy networks. Swissmedic enforcement of pharmaceutical-grade manufacturing standards and bilateral mutual recognition agreements facilitate EU market access. Basel and Zurich host concentrated expertise in live culture stability engineering and clean-label certification consulting.
India
FSSAI functional food regulation clarification unlocks modern trade and pharmacy channel entry for clinically positioned brands. Pediatric multivitamin adoption in urban households creates brand loyalty transfer effects toward adult formulations. Maharashtra and Karnataka concentrate contract manufacturing investment as pectin-based formulation capabilities expand to serve Middle East export demand.
Nutraceutical Gummies Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base stratifies between enterprise-scale pharmaceutical heritage players with dual FDA-EFSA compliance infrastructure and mid-scale specialists concentrating on single-category dominance. Three archetypes define positioning: pharmaceutical-confectionery hybrids leveraging clinical credibility, pure-play gummy specialists optimizing palatability engineering, and diversified FMCG groups exploiting retail shelf leverage. Competitive moves concentrate on M&A for formulation talent acquisition and backward integration into pectin supply security.
Within the pharmaceutical-confectionery hybrid tier, Bayer AG and Church & Dwight Co., Inc. exemplify divergent strategic anchors. Bayer's AG structure reflects European pharmaceutical heritage positioning, while Church & Dwight's Inc. designation signals US-based diversified consumer health orientation. Nestlé represents the FMCG conglomerate archetype, exploiting global retail infrastructure to achieve shelf-stable distribution velocity that specialist competitors cannot replicate. These three entities occupy positions spanning clinical-grade credibility, digestive wellness specialization, and mass-market penetration respectively.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| H&H Group |
| Bayer AG |
| Haleon |
| Nestlé |
| Unilever |
| Pharmavite |
| Amway |
| Hero Nutritionals |
| Others |
Value Chain & Pricing Dynamics
FDA cGMP and NSF Certified for Sport credentials simultaneously gate supplier qualification and enable price premiums for compliant nutraceutical gummy manufacturers, compressing procurement options for pharmacy buyers while stratifying tiered pricing across certification levels.
Pricing Analysis
Pharmacy buyers anchor tiered pricing across premium, standard, and economy levels. Price differentiation hinges on dual certification status and cold-chain capability for probiotic stability. Cost compression in clean-label pectin formulations is intensifying because citrus peel supply disruptions in Spain and Mexico squeeze margin pools. Private-label supermarket SKUs exhibit highest price sensitivity, while clinical-grade pharmacy channels absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Spain and Mexico anchor citrus peel sourcing for pectin extraction, while Germany and Switzerland concentrate gelatin alternative R&D and lipid-shell microencapsulation expertise. Formulation draws from chelated mineral complexes, heat-sensitive botanical extracts, and live colony-forming units requiring refrigerated logistics. Single-source vulnerability in Iberian citrus agriculture exposes clean-label formulators to raw material interruption. Distribution runs through pharmacy networks in Germany and the United States, direct-to-consumer subscription platforms, and mass-market supermarket channels with divergent margin retention profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric wellness demand cyclically recovers household supplement purchasing as multivitamin gummies reactivate full-family coverage patterns across Germany and the United States.
For Market Incumbents: Secure pectin supply contracts with documented provenance to preempt clean-label certification disruption. Expand lipid-shell microencapsulation capacity in New Jersey and California contract manufacturing clusters to defend probiotic pharmacy placement against capsule format substitution. For New Entrants and Emerging Players: Lead with India's FSSAI-compliant functional food positioning to capture modern trade and pharmacy channel whitespace before regulatory clarity attracts pharmaceutical-confectionery hybrid competition. Target sports nutrition convergence in Australia and Brazil with electrolyte gummy formulations displacing powder formats among recreational athletes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refrigerated probiotic distribution infrastructure and dual FDA-EFSA compliance systems. Five-to-ten-year viability favors acquisition targets with captive pectin sourcing or backward integration into citrus peel processing. Monitor EFSA botanical health claims enforcement as signal for reformulation cost inflection across European immune-positioned portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Pectin Supply Security | Backward integration into Spanish and Mexican citrus peel sourcing insulates clean-label formulators from climate-driven margin compression. |
| Cold-Chain Infrastructure Expansion | Refrigerated distribution investments unlock pharmacy channel placement for probiotic gummies in Switzerland and the Netherlands. |
| Dual Certification Achievement | Simultaneous FDA cGMP and NSF Certified for Sport credentials consolidate procurement relationships with US pharmacy buyers. |
| Direct-to-Consumer Platform Launch | Subscription models capture recurring revenue with superior lifetime value mechanics versus slotting-fee-burdened supermarket placement. |
| Microencapsulation Capability Acquisition | Lipid-shell technology purchases separate clinical-grade manufacturers from commodity vitamin-only contract producers. |
Study Parameters
The analysis maps vitamin, probiotic, mineral, and herbal extract sub-sectors, each validated through formulation scientists, pharmacy procurement managers, contract manufacturing executives, and retail category buyers. Primary interviews with confectionery R&D directors and cold-chain logistics specialists combined with secondary validation from FDA warning letters, EFSA novel food opinions, SAMR registration databases, and customs trade flow records. Bottom-up capacity assessments and top-down consumption estimates triangulate volume figures.
Consistency checks validated outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, target consumer demographic, flavor profile, and distribution channel with regulatory pathway overlay. CAGRs derive from installed capacity expansion schedules, household penetration trajectory analysis, and channel shift elasticity coefficients. Probiotic stability engineering adoption curves and pectin price volatility indices feed industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained pediatric wellness demand recovery, EFSA enforcement continuity, or pectin supply stabilization would require recalibration. Forecasts reflect assumptions on clean-label certification retention, refrigerated distribution cost curves, and pharmacy channel consolidation velocity. Recalibration cycles align with material shifts in SAMR registration timelines, climate stress patterns in citrus-growing regions, and microencapsulation technology cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Pregnenolone Supplements Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Australia Protein Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
South America Nutraceuticals Market