
 Premium Chocolate Market | 2026-2036
Premium Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Chocolate Market Intelligence
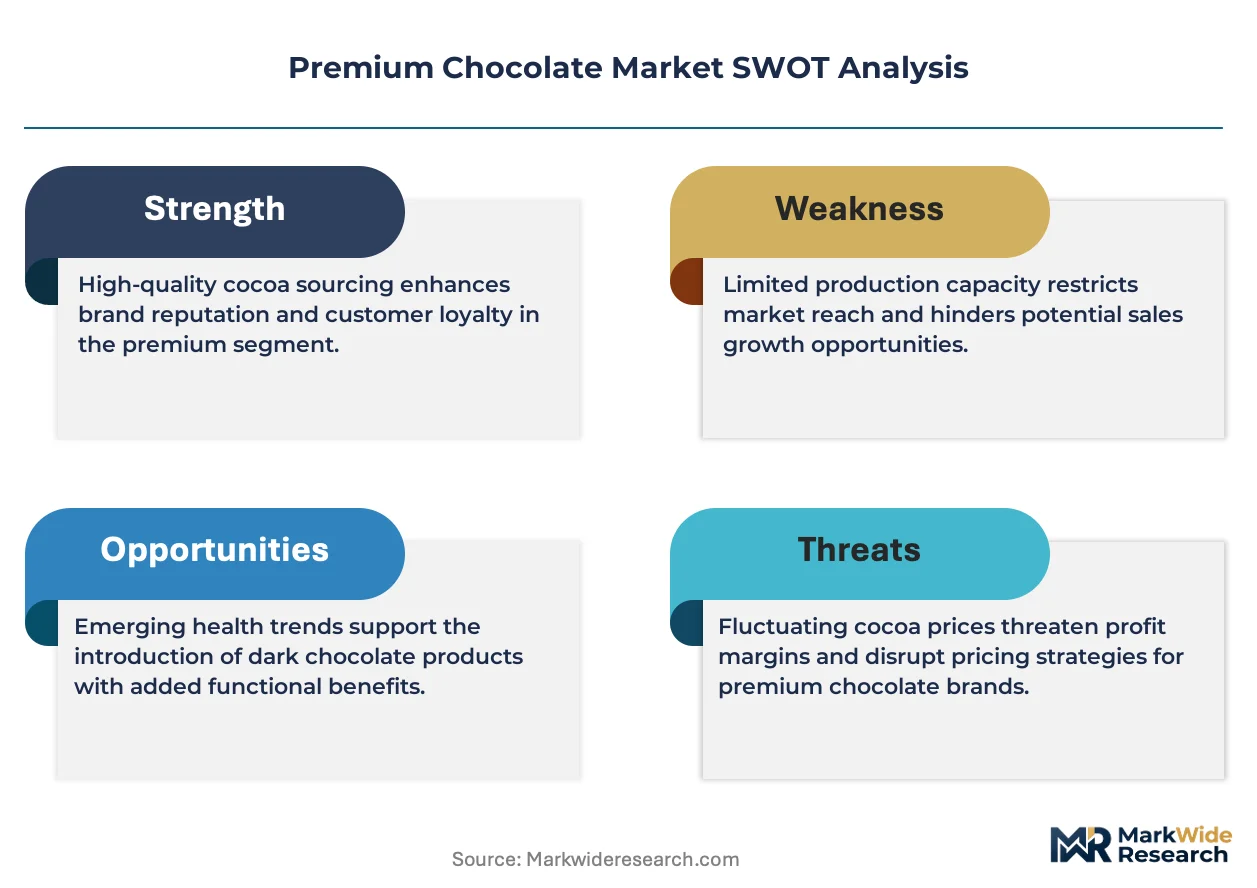
Fair Trade certification, once a clear differentiator in ethical sourcing, is collapsing the distinction between mass-market and premium segments. This shift forces brands to communicate value beyond a single label. Chocoladefabriken Lindt & Sprüngli AG leverages its control over the bean-to-bar process to guarantee quality. The Hershey Company competes by acquiring artisanal brands to build a premium portfolio. Godiva Chocolatier sustains its luxury status through exclusive retail boutiques and premium packaging.
Premium chocolate is defined by its high percentage of cocoa solids, often sourced from a single origin or estate, and a minimal use of additives. The production process involves longer conching times, which develops complex flavor profiles. Its primary purpose is to serve the high-end consumer market and professional chocolatiers. The dark chocolate product type continues to lead, associated with health benefits and sophisticated taste. In terms of channels, online retail is creating new pathways to consumers, challenging the dominance of specialty stores.
The regulatory environment is shaped by food safety and labeling standards. In the United States, the FDA enforces strict rules on cocoa content percentages and allergen declarations. The EU’s Corporate Sustainability Reporting Directive (CSRD) pressures companies to provide transparent reporting on cocoa sourcing and labor practices. These regulations elevate the barrier to entry and reinforce consumer trust in verified premium claims. Success for brands now hinges on effectively communicating provenance and quality beyond basic compliance.
Market Dynamics
The central force shaping the premium chocolate market is the increasing consumer and regulatory demand for supply chain transparency. This pressure, exemplified by frameworks like the EU's CSRD, forces brands to prove ethical and quality claims beyond packaging.
Growth Catalysts
- Regulatory Transparency:The EU's Corporate Sustainability Reporting Directive (CSRD) compels companies to provide detailed sourcing data, which in turn validates premium claims and builds consumer trust.
- Food Service Demand:High-end restaurants and luxury hotels increasingly require superior, traceable chocolate for desserts and confections, creating a stable B2B growth channel for premium producers.
- Artisanal Product Interest:Consumer appetite for single-origin and estate-specific chocolates is intensifying in developed markets like Japan and Switzerland, supporting niche brands with unique flavor profiles.
Market Restraints
- Input Cost Volatility:Prices for fine flavor cocoa beans, such as Criollo and Nacional, are subject to significant fluctuation due to climate events and crop diseases, creating margin pressure.
- Supply Concentration:Over-reliance on a few countries in West Africa and Latin America for high-quality cocoa creates vulnerability to geopolitical instability and logistical disruptions.
- Attribute Mimicry:Mass-market brands are launching products with high cocoa percentages and single-origin claims, blurring segment lines and challenging the price premium of authentic artisanal products.
Strategic Opportunities
- Geographic Expansion:Untapped demand exists in affluent urban centers within the Middle East and Southeast Asia, where a growing middle class seeks luxury consumer goods.
- Functional Ingredients:Incorporating wellness-oriented ingredients like botanicals or nootropics into premium dark chocolate creates a new product category targeting health-conscious consumers.
- Subscription Models:Direct-to-consumer services offering curated selections of rare or small-batch chocolates provide a channel to bypass traditional retail and build brand loyalty.
Industry Challenges
- Talent Scarcity:A shortage of master chocolatiers and sensory experts capable of developing complex flavor profiles and ensuring bean-to-bar quality consistency limits scalable production.
- Certification Overhead:Managing the costs and administrative burden of multiple, distinct certifications for organic, Fair Trade, and single-origin status across various export markets is a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Chocolate Market |
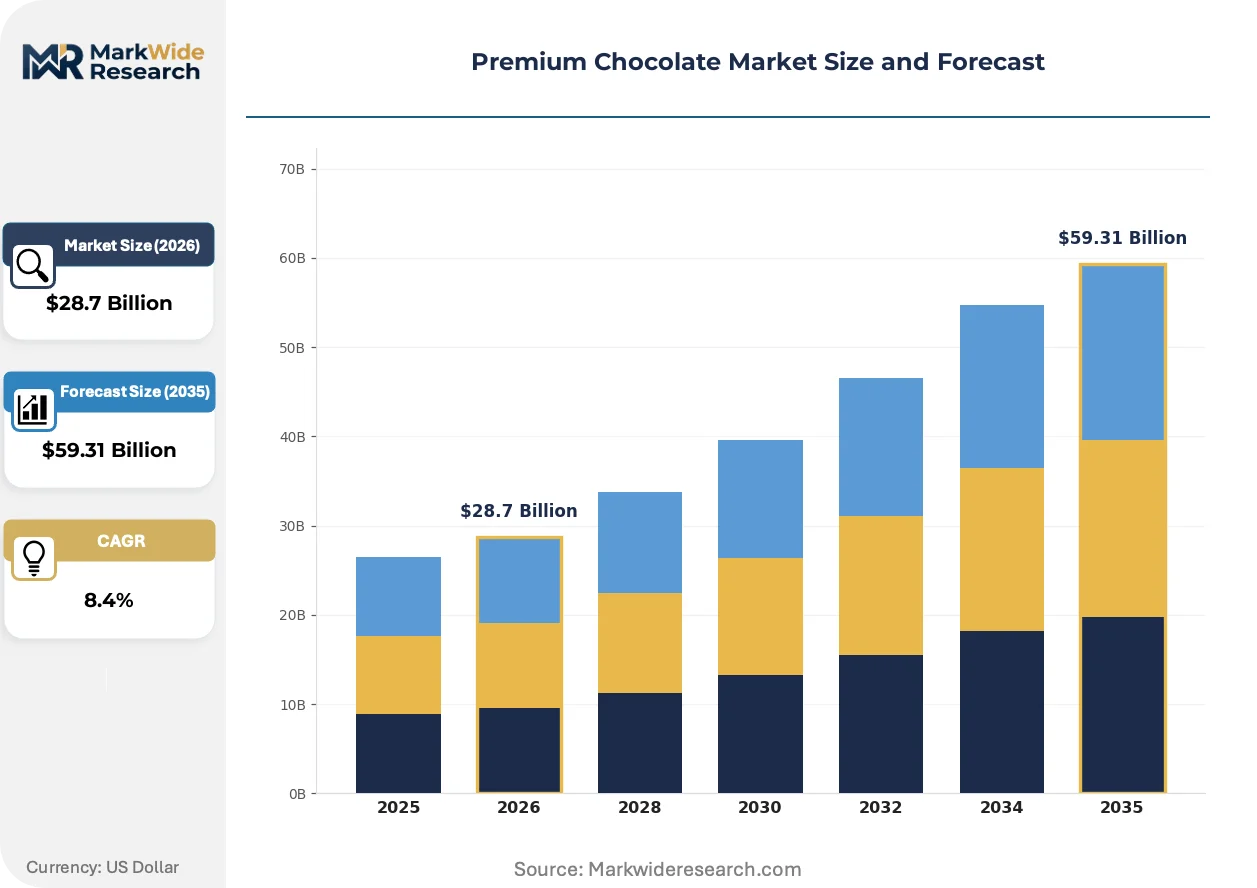
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Couverture Chocolate Packaging Type: Boxes, Bars, Pouches, Gift Sets Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Gourmet Shops End User: Food Service, Retail Consumers, Bakeries, Confectioneries |
| Companies Covered | Mondelez International, Endangered Species Chocolate, Chocoladefabriken Lindt & Sprüngli AG, CEMOI Group, Godiva Chocolatier, Ferrero International S.A., The Hershey Company, Lake Champlain Chocolate Co., Mars, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Chocolate Market Strategic Shifts & Innovations
An evolution in the definition of "premium" is underway, moving beyond cocoa content to include technological verification and consumer ethics. This change pressures brands to communicate value through transparent processes and authentic stories, not just product attributes.
Blockchain-based traceability platforms are providing an immutable ledger for cocoa bean provenance. Ethically focused consumers and niche brands are adopting the technology to validate sourcing claims from farm to bar. This adoption is bifurcating the market between radically transparent producers and incumbents relying on traditional brand marketing.
The European Union's Corporate Sustainability Reporting Directive (CSRD) requires extensive disclosure on supply chain impacts, including labor and environmental standards. This elevates compliance costs and forces manufacturers to invest in robust due diligence systems for their cocoa sourcing. The dark chocolate segment, frequently marketed on ethical provenance, is most affected.
Consumer preference is migrating from trust in a single certification label to a holistic assessment of a brand's ethical and quality narrative. This shift reduces the gatekeeping power of specialty retailers and elevates direct-to-consumer channels where brands can fully articulate their story. This trend is most visible in North American and European markets.
Premium Chocolate Market Segmentation
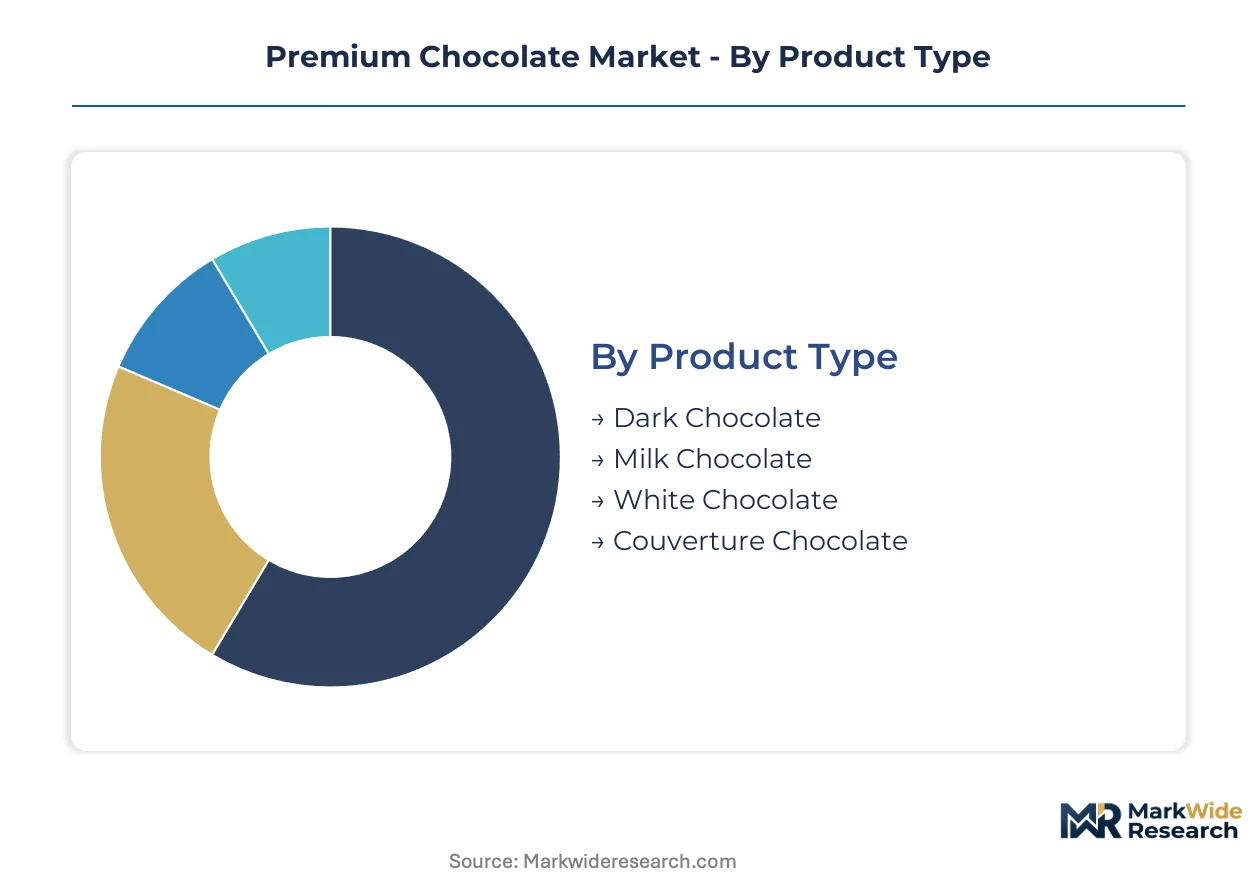
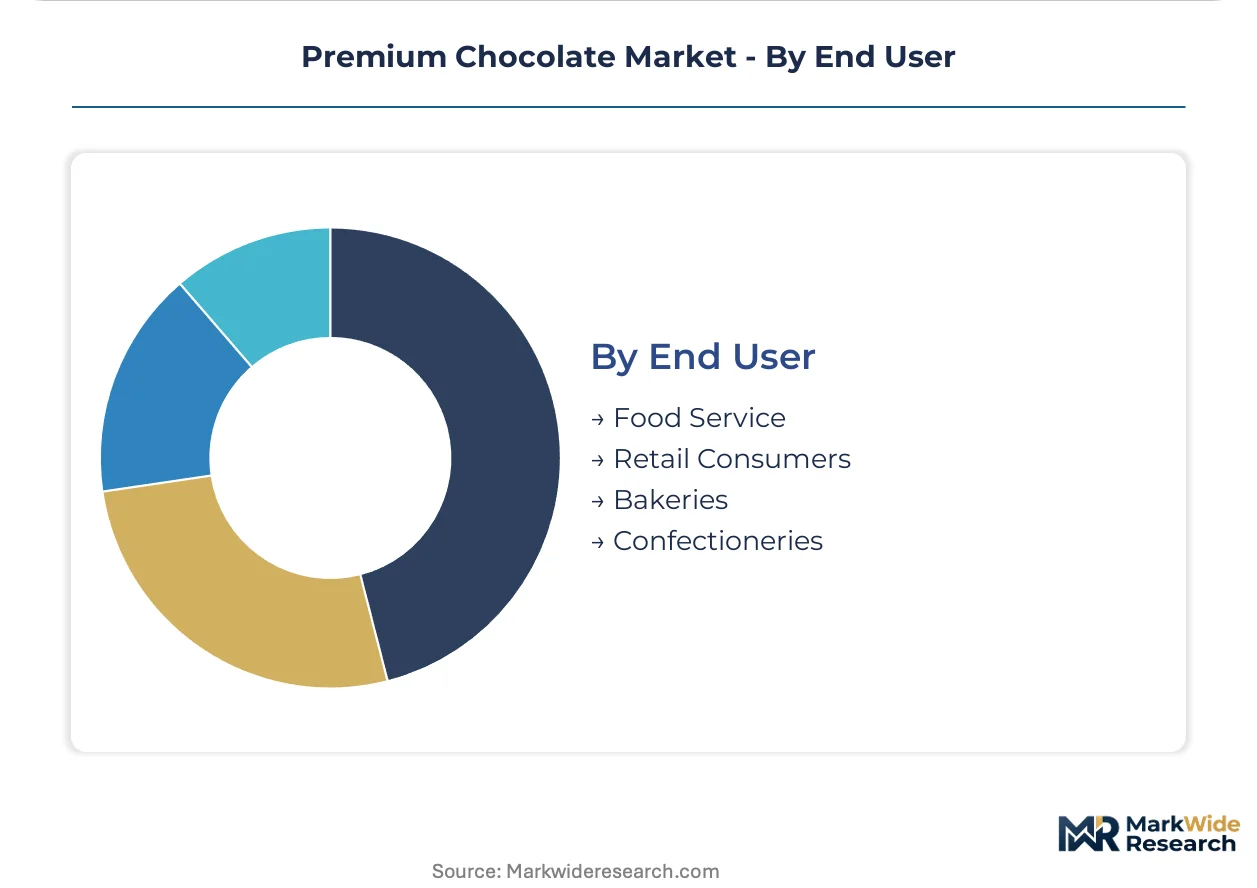
The premium chocolate market segments reveal distinct consumer behaviors and operational requirements. Understanding these divisions helps brands tailor product offerings and communication strategies for targeted consumer engagement and sustained market presence.
Product Type:
Segments within premium chocolate product types face varying degrees of substitution pressure from mass-market alternatives.
- Dark Chocolate:High cocoa solids content and minimal additives define this product type. Its association with health benefits and sophisticated taste drives consumer preference in developed markets like Japan and Switzerland.
- Couverture Chocolate:This professional-grade chocolate contains a higher percentage of cocoa butter, ensuring superior melt and gloss. Professional chocolatiers and high-end bakeries demand its specific tempering properties for fine confections.
- Milk Chocolate:This variant balances cocoa solids with milk and sugar, appealing to a broader consumer base seeking a sweeter profile.
- White Chocolate:Composed of cocoa butter, sugar, and milk solids, it offers a distinct, creamy flavor profile without cocoa solids.
Dark Chocolate retains volume leadership; Couverture Chocolate holds the steepest expansion curve.
Packaging Type:
Packaging types reflect distinct cost tiers, influencing both consumer perception and brand positioning.
- Gift Sets:These curated collections often feature premium assortments and elegant designs, targeting seasonal and celebratory purchases. Luxury hotels and corporate clients drive consistent demand for these high-value presentations.
- Boxes:Offering a sophisticated presentation, boxes typically contain individual pralines or bonbons. Specialty stores and gourmet shops feature these for discerning consumers seeking variety and elegance.
- Bars:Standard bar formats offer convenience and direct consumption, making them a staple for individual indulgence.
- Pouches:Resealable pouches provide convenience for bite-sized premium chocolates, suitable for sharing or portion control.
Bars dominate everyday consumption; Gift Sets capture seasonal and luxury spending.
Distribution Channel:
Distribution channels serve distinct application needs, from broad market access to exclusive consumer engagement.
- Online Retail:E-commerce platforms provide direct-to-consumer access, bypassing traditional intermediaries. This channel allows niche brands to reach a global audience and articulate their provenance stories effectively.
- Specialty Stores:These dedicated outlets offer a curated selection and expert advice, enhancing the premium shopping experience. They serve as critical touchpoints for brands to showcase limited editions and artisanal products.
- Supermarkets:Mass-market supermarkets carry premium chocolate brands, making them accessible to a wider consumer base.
- Gourmet Shops:Focused on high-end food products, gourmet shops offer a specialized retail environment for premium chocolate consumers.
Online Retail exhibits the most dynamic expansion; Specialty Stores maintain crucial brand equity.
End User:
End users represent diverse customer types, each with specific purchasing criteria and volume requirements.
- Food Service:High-end restaurants, luxury hotels, and caterers demand superior, traceable chocolate for desserts and confections. This B2B segment values consistent quality and specific flavor profiles for culinary applications.
- Retail Consumers:Individual consumers purchase premium chocolate for personal indulgence, gifting, and home consumption. This segment responds to brand narratives, ethical sourcing, and perceived health benefits.
- Bakeries:Professional bakeries utilize premium chocolate as an ingredient for high-quality cakes, pastries, and other baked goods.
- Confectioneries:Artisan confectioners and chocolate makers use premium chocolate as their primary raw material for crafting specialty items.
Retail Consumers drive the largest volume; Food Service demonstrates consistent B2B growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Policy frameworks like the EU's Corporate Sustainability Reporting Directive are compelling greater transparency in cocoa sourcing globally. This regulatory push validates premium claims, reinforcing consumer trust in ethical products. Developed markets show strong demand for high-quality, traceable chocolate.
United States
Demand for premium chocolate in the United States is driven by health-conscious consumers and the robust food service sector. The FDA enforces strict rules on cocoa content percentages and allergen declarations, ensuring product integrity. Major metropolitan areas like New York City and Los Angeles see high concentrations of specialty chocolate boutiques and artisan producers.
Germany
Germany's premium chocolate market benefits from strong consumer preference for organic and ethically sourced products. The EU's CSRD impacts German manufacturers, requiring extensive disclosure on supply chain practices. Cologne and Hamburg feature significant confectionery industry clusters, fostering innovation in premium chocolate development.
Japan
Japanese consumers exhibit a refined palate, driving demand for artisanal and single-origin premium chocolates. METI initiatives support innovation and quality standards for food products, including confectionery. Tokyo's high-end retail districts are central to the display and sale of luxury chocolate brands and limited-edition items.
Switzerland
Swiss consumers prioritize high-quality ingredients and traditional chocolate-making techniques, sustaining strong demand for premium offerings. Swissmedic ensures rigorous food safety and quality controls for all chocolate products. Zurich and Bern remain key centers for master chocolatiers, known for their precision and complex flavor profiles.
United Arab Emirates
Expanding demand for luxury consumer goods in the United Arab Emirates fuels the premium chocolate market. The UAE's food safety authorities implement stringent import regulations, maintaining high product standards. Dubai's luxury hotels and high-end retail sector are critical distribution points for exclusive chocolate brands.
Premium Chocolate Market Key Industry Players
Player mix skews toward established confectionary giants alongside specialized artisanal producers, creating a dynamic competitive environment. The market structure exhibits a tiered consolidation, with large corporations actively acquiring smaller premium brands to expand their high-end offerings. Strategic archetypes include global brand consolidators, ethical sourcing specialists, and luxury experience providers. Companies are actively pursuing portfolio diversification, geographic expansion into affluent urban centers, and strategic partnerships to strengthen their market positions.
Within the premium tier, Chocoladefabriken Lindt & Sprüngli AG exemplifies brands with strong bean-to-bar control and a focus on consistent quality. The Hershey Company occupies a position among global consolidators, actively integrating artisanal brands into its broader portfolio. Godiva Chocolatier anchors the luxury segment, maintaining its status through exclusive retail boutiques and premium packaging strategies. These entities collectively demonstrate diverse approaches to sustaining competitive advantage in the premium chocolate market. Their strategies reflect a broader industry trend of balancing scale with specialized offerings.
| Leading Market Players |
|---|
| Mondelez International |
| Endangered Species Chocolate |
| Chocoladefabriken Lindt & Sprüngli AG |
| CEMOI Group |
| Godiva Chocolatier |
| Ferrero International S.A. |
| The Hershey Company |
| Lake Champlain Chocolate Co. |
| Mars, Inc. |
| Others |
Cost & Logistics Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) gates both supply qualification and price differentiation simultaneously in the premium chocolate market. This regulation compels companies to provide transparent reporting on cocoa sourcing, validating premium claims and influencing consumer purchasing decisions. Supply chain transparency therefore directly impacts a brand's ability to command higher prices.
Pricing Analysis
Provenance verification, driven by certifications like Fair Trade or single-origin claims, creates the primary spread in premium chocolate pricing. The market operates on a tiered structure, with ultra-premium offerings commanding the highest prices due to rare cocoa varieties and intricate craftsmanship. Brand premium and the cost of specialized packaging also drive price differentiation. Pricing pressure stems from mass-market brands launching products with high cocoa percentages, blurring segment lines. Retail consumers purchasing for personal indulgence exhibit higher price sensitivity compared to food service establishments requiring specific quality for culinary applications.
Supply Chain Analysis
The concentrated sourcing of fine flavor cocoa beans from specific regions in West Africa and Latin America underwrites the premium chocolate supply chain. Key raw material dependencies include Criollo and Nacional cocoa beans, alongside high-quality cocoa butter. Climate events and crop diseases in these limited geographic areas pose a significant structural risk to supply consistency and bean quality. Distribution runs primarily through online retail, specialty stores, and direct channels to high-end food service establishments, ensuring product integrity and controlled access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The premium chocolate market demands a strong substitution defense against mass-market brands increasingly mimicking high cocoa percentages and single-origin claims. Incumbents must navigate this blurring of segment lines to preserve perceived value and pricing power.
For Market Incumbents: Secure direct control over the bean-to-bar process to guarantee quality and provenance, counteracting mass-market attribute mimicry. Consolidate smaller artisanal brands to expand premium portfolios, leveraging established distribution and marketing capabilities. Invest in blockchain-based traceability platforms to validate sourcing claims, reinforcing consumer trust and ethical positioning.
For New Entrants and Emerging Players: Anchor in niche segments by focusing on unique flavor profiles from single-origin beans or incorporating functional ingredients like botanicals. Target affluent urban centers in the Middle East and Southeast Asia, where luxury consumer goods demand is expanding. Utilize direct-to-consumer subscription models to build brand loyalty and articulate authentic provenance stories to health-conscious consumers.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger confectionery groups seeking to divest non-core premium assets or from family-owned artisanal producers requiring capital for expansion. The long-term viability of the premium chocolate market hinges on sustained consumer demand for ethically sourced, high-quality products over the next five to ten years. Watch the adoption rate of blockchain-based traceability platforms as a signal for authentic provenance validation and market bifurcation.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension | Introduce new flavor profiles or product formats to capture evolving consumer preferences. |
| Direct-to-Consumer Launch | Establish online channels to bypass intermediaries and build direct customer relationships. |
| Premium Tier Introduction | Launch ultra-premium lines with rare cocoa beans and exclusive packaging. |
| Distribution Channel Expansion | Penetrate new affluent urban centers in the Middle East and Southeast Asia. |
| Sustainability Repositioning | Certify sourcing practices to align with EU CSRD and ethical consumer demands. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to gather qualitative insights and validate quantitative data. Engagements included master chocolatiers, cocoa farmers' cooperative representatives, food service procurement managers, and specialty retail buyers. Secondary validation drew from FDA filings, EU CSRD reports, global customs data, and confectionery industry association publications. This approach ensured bottom-up and top-down triangulation for robust market sizing.
The market analysis delineates projections across the analysis window, integrating a robust analytical framework. Modeling considered segmentation by product type, packaging type, distribution channel, end-user, and regional demand patterns. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Key forecast inputs included cocoa bean price volatility and evolving consumer preference for ethical sourcing.
Material uncertainties — including severe climate change impacts on cocoa crops and unforeseen geopolitical events — sit outside the modeled envelope. Forecasts reflect assumptions regarding current regulatory trajectories and consumer behavior. Practitioners should keep alternative scenarios live as global climate patterns and trade policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Europe Confectionery Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Functional Confectionery Market
Confectionery
Gum Base Candy Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Brain Mint Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
Gummy Candy Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
White Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Confectionery Coating Market
Confectionery
Canada Chocolate Market