
 Japan Dry Eye Syndrome Market | 2026-2036
Japan Dry Eye Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Dry Eye Syndrome Market Intelligence
Ophthalmologist workforce shortages in rural prefectures is rotating treatment capacity toward urban centers and telemedicine platforms. Santen Pharmaceutical Co Ltd leverages its domestic manufacturing base to sustain supply chain responsiveness across Japan's islands. Novartis AG anchors its position through R&D intensity in novel delivery systems. Alcon competes on brand strength in the premium preservative-free segment.
Dry eye syndrome constitutes a multifactorial ocular surface disorder characterized by tear film instability, hyperosmolarity, and inflammation, with diagnostic criteria incorporating tear break-up time below 10 seconds and Schirmer test measurements under 5 mm. Its primary purpose is restoring homeostasis to the corneal and conjunctival epithelium to prevent progressive visual impairment. Artificial Tears dominate volume due to broad accessibility, while Lipid-Based Formulations capture expanding margin pools as meibomian gland dysfunction recognition grows. Preservative-Free Formulations lead technology preference where chronic use drives safety concerns.
PMDA approval pathways and Japan's MHLW reimbursement schedules shape product commercialization timelines and physician prescribing incentives. JIS standards for medical device classification influence punctal plug market access requirements. Stakeholders must monitor evolving MHLW pricing reviews and PMDA guidance on novel biologic eye drops to anticipate portfolio repositioning needs.
Market Dynamics
Japan's MHLW reimbursement schedules for preservative-free formulations are restructuring prescribing incentives across ophthalmology clinics, redirecting volume toward premium therapeutic categories while compressing margins on conventional artificial tears.
Growth Catalysts
- PMDA Fast-Track Designation:Japan's pharmaceutical regulator accelerates approval timelines for novel biologic eye drops, compressing commercialization cycles for domestic manufacturers.
- Meibomian Gland Dysfunction Recognition:Diagnostic protocol updates in Tokyo and Osaka academic medical centers are expanding the addressable patient pool for lipid-based therapeutics.
- Telemedicine Infrastructure:Rural prefectures lacking ophthalmologist density are routing patients to urban specialty clinics through remote diagnostic platforms.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Import dependence on Chinese and Indian API suppliers exposes formulation costs to currency volatility and shipping disruptions.
- Punctal Plug Technical Limitations:Device migration and epiphora complications limit patient retention rates for mechanical tear conservation therapies.
- MHLW Pricing Compression:Biennial reimbursement reviews systematically reduce listed prices for mature artificial tear categories, squeezing manufacturer margins.
Strategic Opportunities
- Hokkaido and Tohoku Underpenetration:Northern prefectures with aging demographics and limited specialist access represent expansion targets for mobile screening units.
- Novel Delivery System Convergence:Integration of nanotechnology carriers with preservative-free formulations enables extended ocular surface residence time.
- Direct-to-Patient Channels:Pharmacy-based diagnostic kiosks in metropolitan convenience retail are bypassing traditional clinic gatekeepers for mild-to-moderate cases.
Industry Challenges
- Ophthalmologist Workforce Scarcity:Rural Japan faces critical shortages of cornea specialists capable of performing advanced diagnostic workups.
- PMDA Biologic Guidance Uncertainty:Evolving evidentiary requirements for cytokine-targeting eye drops extend preclinical development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Dry Eye Syndrome Market |
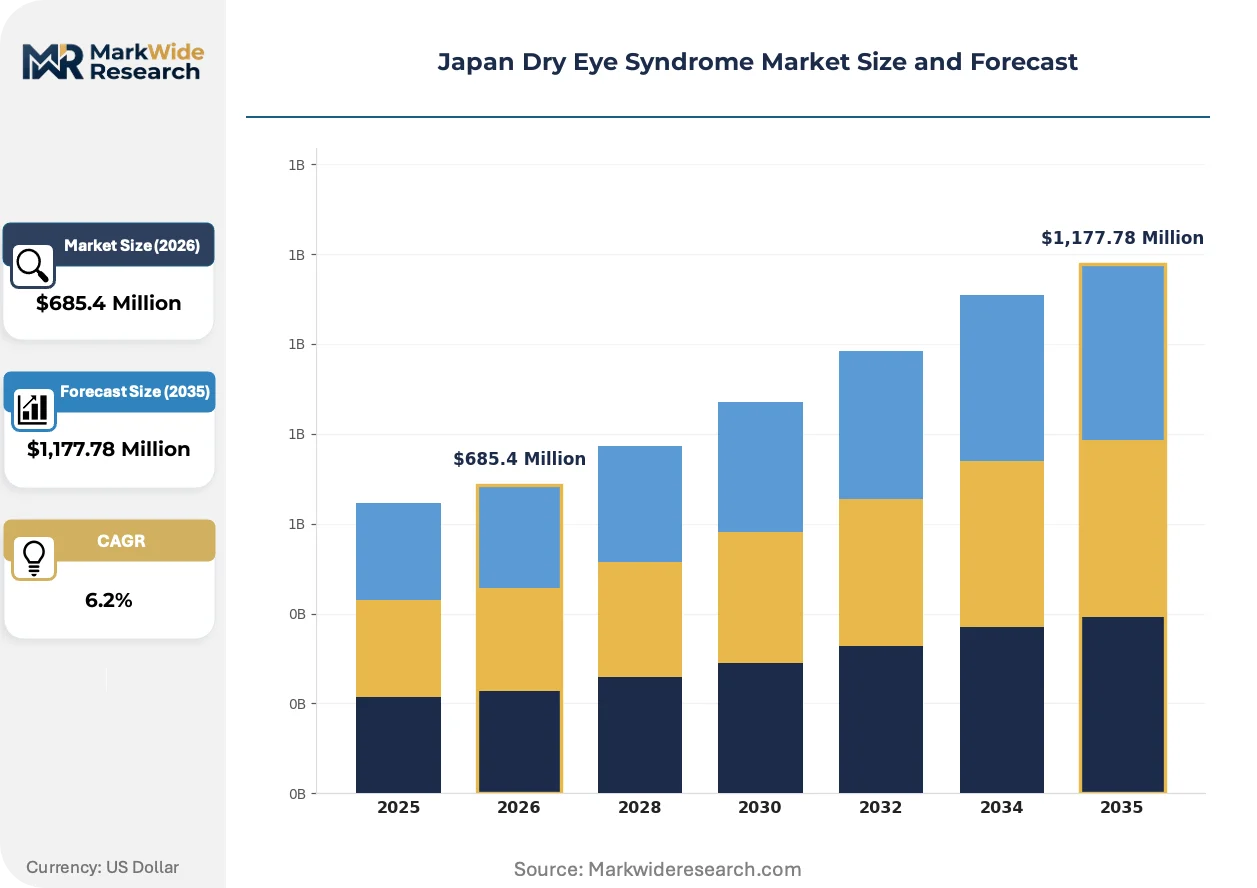
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Anti-Inflammatory Drops, Punctal Plugs, Lipid-Based Formulations End User: Ophthalmology Clinics, Hospitals, Retail Pharmacies, Home Care Technology: Preservative-Free Formulations, Liposomal Technology, Novel Delivery Systems, Hyperosmolarity Solutions Application: Symptomatic Relief, Post-Surgery Care, Visual Fatigue, Medication-Induced Dryness |
| Companies Covered | Allergan plc, Novartis AG, Santen Pharmaceutical Co Ltd, Alcon, Johnson & Johnson, Otsuka Pharmaceutical Co Ltd, Bausch Health Companies Inc, Takeda Pharmaceutical Company Limited, Senju Pharmaceutical Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Dry Eye Syndrome Market Strategic Shifts & Innovations
Preservative-free formulation technology is advancing rapidly while reimbursement policy and patient acquisition channels undergo parallel restructuring. These intersecting developments are compressing traditional competitive advantages.
Lipid-based nanoemulsion delivery systems are displacing conventional aqueous artificial tears in chronic dry eye management. Cornea specialists in Tokyo's academic medical centers are adopting these formulations for moderate-to-severe meibomian gland dysfunction cases. The technology is displacing volume share from polyvinyl alcohol and carboxymethylcellulose segments previously dominant in first-line therapy.
PMDA's 2023 guidance on real-world evidence submissions for ophthalmic biologics is shortening post-market study requirements. Domestic manufacturers are repositioning pipeline assets to capture accelerated approval pathways. Novel cytokine inhibitors targeting the IL-1 and TNF-alpha pathways are most affected, with sponsors restructuring Phase IV commitments.
Patient acquisition through pharmacy-based screening is fragmenting traditional clinic referral networks. Major drugstore chains in Osaka and Nagoya are deploying automated tear film analyzers to identify symptomatic consumers. This channel shift is most visible among working-age screen-intensive professionals seeking convenience access before specialist escalation.
Japan Dry Eye Syndrome Market Segmentation
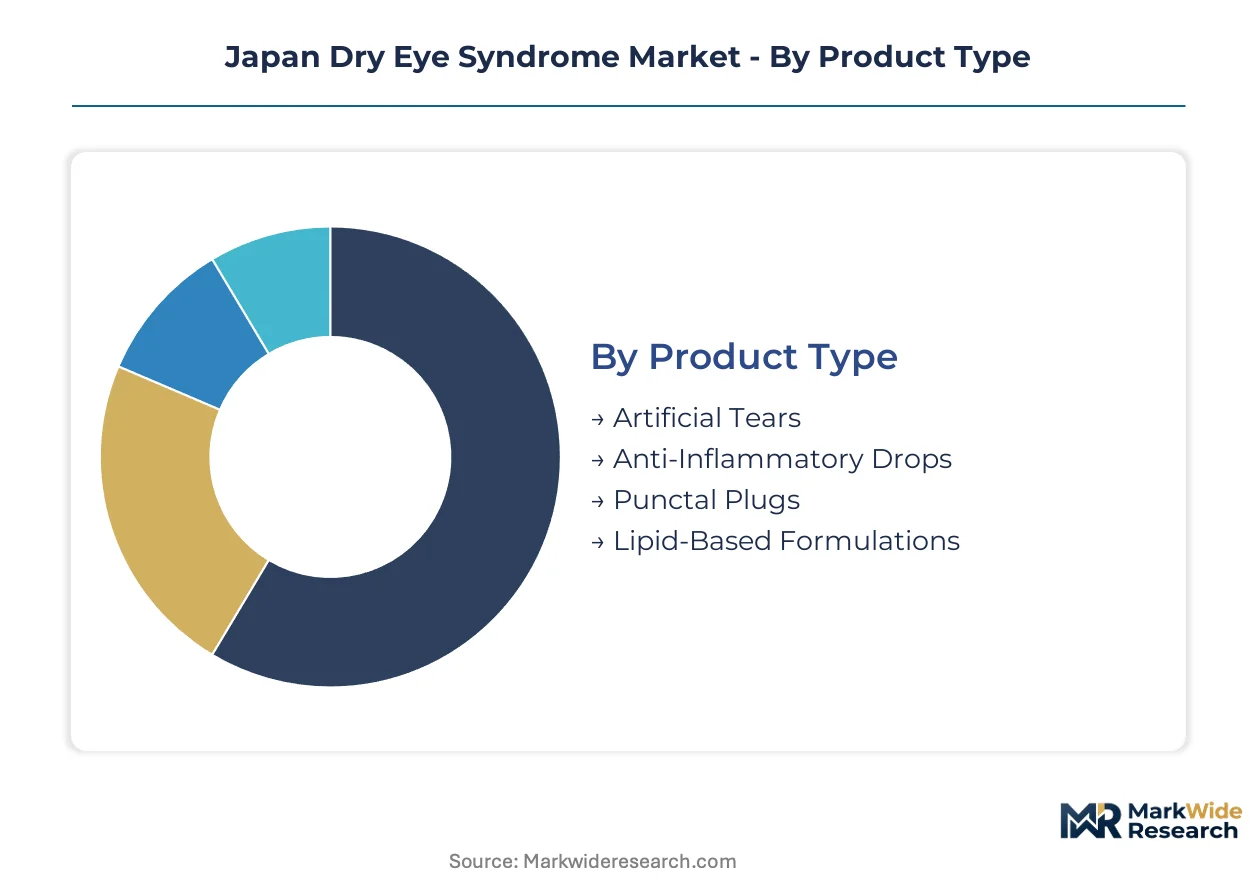
Product differentiation in Japan's dry eye market concentrates around preservative safety profiles and delivery mechanism sophistication. Segment boundaries blur as lipid-based technologies displace conventional aqueous formulations and clinic-based diagnostic protocols reshape prescribing hierarchies.
Product Type:
Substitution pressure intensifies as lipid-based formulations and anti-inflammatory drops encroach on territory once held by commodity artificial tears, with reimbursement differentials accelerating the shift.
- Artificial Tears:Polyvinyl alcohol and carboxymethylcellulose-based solutions constitute first-line therapy for mild cases. Volume concentrates in metropolitan Tokyo and Osaka retail pharmacies where MHLW reimbursement compressions squeeze margins on mature formulations.
- Lipid-Based Formulations:Nanoemulsion delivery systems targeting meibomian gland dysfunction command premium positioning. Demand clusters in academic medical centers with advanced diagnostic capability, driven by recognition of evaporative dry eye subtypes.
- Anti-Inflammatory Drops:Cyclosporine and corticosteroid formulations address underlying ocular surface inflammation.
- Punctal Plugs:Silicone and collagen-based devices for tear conservation face retention challenges from migration complications.
Artificial Tears retains volume leadership; Lipid-Based Formulations holds the steepest expansion curve.
End User:
Cost tier stratification separates premium clinic-based care from convenience-driven retail acquisition, with telemedicine platforms eroding traditional channel boundaries.
- Ophthalmology Clinics:Specialized diagnostic workups including tear break-up time and Schirmer testing guide therapeutic selection. Patient flows concentrate in Tokyo, Osaka, and Nagoya where cornea specialist density supports advanced care pathways.
- Retail Pharmacies:Automated tear film analyzers in major drugstore chains now capture working-age professionals seeking rapid symptomatic relief. Osaka and Nagoya deployments fragment traditional clinic referral networks for mild-to-moderate cases.
- Hospitals:Integrated care settings manage post-surgical dry eye and complex comorbidities.
- Home Care:Self-administered regimens dominate chronic maintenance therapy.
Ophthalmology Clinics anchors premium revenue; Retail Pharmacies is expanding most quickly through diagnostic kiosk deployment.
Technology:
Application specificity determines technology adoption, with chronic use safety requirements driving preservative-free migration across all patient segments.
- Preservative-Free Formulations:Single-use vials and multidose preservative-free systems eliminate benzalkonium chloride exposure risks. MHLW reimbursement schedules explicitly favor these formulations, redirecting physician prescribing behavior across all prefectures.
- Novel Delivery Systems:Nanotechnology carriers and sustained-release platforms extend ocular surface residence time. Development pipelines concentrate in domestic manufacturers leveraging PMDA fast-track designations for cytokine-targeting biologics.
- Liposomal Technology:Phospholipid bilayer encapsulation improves drug bioavailability.
- Hyperosmolarity Solutions:Osmoprotective agents address tear film instability in severe cases.
Preservative-Free Formulations dominates current prescribing; Novel Delivery Systems shows the strongest pipeline momentum.
Application:
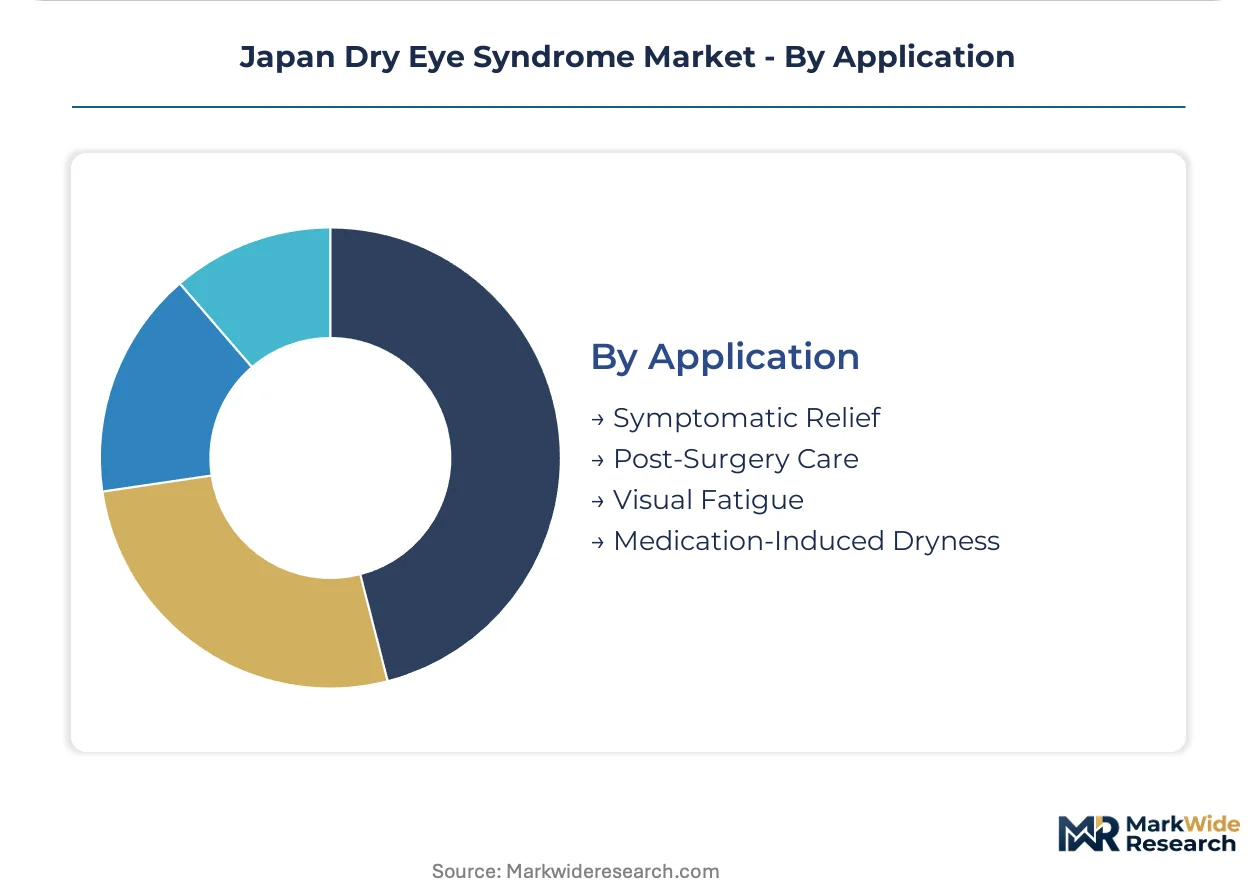
Volume concentration varies sharply by patient demographic, with screen-intensive professionals and post-surgical populations presenting distinct therapeutic requirements.
- Symptomatic Relief:Broad indication covering mild-to-moderate discomfort from environmental and occupational factors. Demand concentrates among Tokyo and Osaka office workers with prolonged digital device exposure.
- Post-Surgery Care:LASIK, cataract, and refractive procedures generate acute dry eye episodes requiring intensive management. Academic medical centers in Tokyo coordinate specialized perioperative protocols.
- Visual Fatigue:Computer vision syndrome drives recurring purchase cycles.
- Medication-Induced Dryness:Antihistamine, antidepressant, and hormone therapy side effects create iatrogenic demand.
Symptomatic Relief captures the widest patient base; Post-Surgery Care generates the highest per-patient therapeutic intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's regulatory framework and MHLW reimbursement schedules anchor market development across Japan's prefectural landscape. Regional disparities in specialist density and aging demographics concentrate demand in specific metropolitan corridors while creating access gaps elsewhere.
Kanto/Tokyo
Tokyo's screen-intensive professional workforce and dense ophthalmologist concentration drive premium therapeutic demand. MHLW reimbursement schedules for preservative-free formulations redirect prescribing toward higher-margin categories in academic medical centers. Cornea specialists at Keio University and University of Tokyo Hospitals coordinate advanced diagnostic protocols for meibomian gland dysfunction.
Kansai/Osaka
Osaka's manufacturing base and aging industrial workforce generate substantial symptomatic relief demand. PMDA fast-track designations for novel biologics accelerate clinical trial recruitment at Osaka University Hospital. Major drugstore chains deploy automated tear film analyzers in convenience retail locations, fragmenting traditional clinic referral networks.
Chubu/Nagoya
Nagoya's automotive and aerospace engineering clusters produce concentrated computer vision syndrome cases among precision manufacturing workers. JIS standards for medical device classification influence punctal plug market access requirements for regional distributors. Telemedicine platforms route rural Aichi and Gifu prefecture patients to Nagoya specialty clinics.
Kyushu
Fukuoka's emerging biotech corridor attracts domestic manufacturers seeking PMDA proximity for regulatory consultation. Aging demographics in Saga and Nagasaki prefectures expand the addressable patient pool for chronic dry eye management. Regional hospitals coordinate with Tokyo academic centers for complex post-surgical dry eye protocols.
Hokkaido and Tohoku
Northern prefectures exhibit critical ophthalmologist workforce scarcity alongside pronounced aging demographics. MHLW mobile screening unit deployments target Sapporo and Sendai metropolitan areas. Limited specialist access positions these regions for telemedicine expansion and pharmacy-based diagnostic kiosk penetration.
Japan Dry Eye Syndrome Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Japan's dry eye syndrome market. Domestic pharmaceutical manufacturers leverage PMDA proximity and manufacturing responsiveness, while multinational subsidiaries compete through brand equity in premium segments. Three archetypes dominate: domestic integrated manufacturers with regulatory agility, multinational specialty ophthalmology divisions with R&D scale, and diversified health conglomerates with distribution breadth. Competitive moves concentrate on novel delivery system development and strategic partnerships with academic medical centers for real-world evidence generation.
Among domestic pharmaceutical specialists, Santen Pharmaceutical Co Ltd exemplifies the integrated manufacturer archetype with domestic production capabilities spanning Japan's island geography. Novartis AG occupies a position representing multinational R&D intensity in novel biologic development. Alcon anchors the premium device-and-formulation portfolio segment. These three entities collectively illustrate the competitive structure: domestic regulatory responsiveness, multinational innovation scale, and premium brand positioning operate as distinct competitive vectors rather than consolidated dominance.
| Leading Market Players |
|---|
| Allergan plc |
| Novartis AG |
| Santen Pharmaceutical Co Ltd |
| Alcon |
| Johnson & Johnson |
| Otsuka Pharmaceutical Co Ltd |
| Bausch Health Companies Inc |
| Takeda Pharmaceutical Company Limited |
| Senju Pharmaceutical Co Ltd |
| Others |
Cost & Logistics Intelligence
Domestic manufacturing scale economies at Santen Pharmaceutical's Osaka and Noto facilities create cost floors that shape competitive positioning across preservative-free and lipid-based formulation tiers. Capacity utilization rates at these plants influence MHLW pricing negotiations and determine which competitors can sustain margin pressure from biennial reimbursement reviews.
Pricing Analysis
Metropolitan Tokyo commands 15-20% price premiums over Hokkaido and Tohoku for identical preservative-free formulations, reflecting specialist density and faster MHLW reimbursement processing. Three-tier pricing structure across premium lipid-based nanoemulsions, standard preservative-free artificial tears, and economy generic polyvinyl alcohol segments dominates the market. Cost compression in the standard tier intensifies as MHLW reimbursement reviews systematically reduce listed prices. Retail pharmacy buyers exhibit highest price sensitivity for first-line artificial tears, while academic medical centers prioritize clinical outcomes over unit cost for advanced meibomian gland dysfunction therapies.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient production for benzalkonium chloride alternatives and cyclosporine raw materials, with domestic Japanese facilities handling final formulation and sterile filling. Key inputs include phospholipid excipients for nanoemulsion systems, hyaluronic acid grades for viscosity modulation, and single-use vial polymers. Single-source vulnerability concentrates in Indian API suppliers for anti-inflammatory active ingredients, exposing formulation costs to shipping disruptions. Distribution runs through wholesaler consignment to ophthalmology clinics, with direct-to-pharmacy channels expanding for automated diagnostic kiosk networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cornea specialist workforce gaps in northern prefectures limit treatment capacity expansion, creating structural bottlenecks that constrain market penetration regardless of product availability or pricing.
For Market Incumbents: Consolidate diagnostic protocol influence by embedding tear film analyzer placements in Tokyo and Osaka academic medical centers, securing real-world evidence generation partnerships that shape PMDA guidance. Deepen backward integration into phospholipid excipient supply through captive production or long-term offtake agreements, reducing exposure to Chinese import volatility. Defend against pharmacy kiosk channel fragmentation by deploying proprietary screening algorithms that require specialist interpretation. For New Entrants and Emerging Players: Differentiate on novel delivery system convergence, specifically nanotechnology carriers with extended ocular residence time that bypass incumbent patent thickets around existing lipid-based formulations. Target Hokkaido and Tohoku mobile screening unit contracts, where MHLW deployment schedules create procurement windows for equipment-and-formulation bundles. Pursue direct-to-patient channel partnerships with major drugstore chains in Nagoya and Fukuoka, leveraging automated diagnostic kiosks as patient acquisition infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic manufacturers with PMDA fast-track designation experience and preservative-free formulation pipelines over multinational subsidiaries dependent on imported API supply. Long-term viability hinges on regulatory agility and reimbursement navigation capability rather than R&D scale alone. Acquisition target archetype: mid-cap ophthalmology specialists with novel cytokine inhibitor pipelines and established MHLW pricing relationships. Watch PMDA guidance evolution on biologic eye drops as inflection indicator for portfolio repositioning timelines.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Fast-Track Designation Pursuit | Accelerates commercialization timelines for domestic manufacturers developing IL-1 pathway inhibitors. |
| Academic Medical Center Partnership | Secures real-world evidence generation channels at Keio University and University of Tokyo Hospitals. |
| Preservative-Free Manufacturing Scale-Up | Captures MHLW reimbursement preference shifts away from benzalkonium chloride formulations. |
| Mobile Screening Unit Deployment | Penetrates Hokkaido and Tohoku markets where ophthalmologist density falls below treatment demand. |
| Pharmacy Diagnostic Kiosk Integration | Fragments traditional clinic referral networks in Osaka and Nagoya convenience retail locations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of PMDA approval databases, MHLW reimbursement schedules, and JIS medical device classification standards. Interviews with cornea specialists, formulary directors at academic medical centers, pharmaceutical regulatory affairs leads, and pharmacy chain procurement managers informed demand and pricing assumptions. Secondary validation drew from hospital procurement databases, GPO contracts, and pharmaceutical trade flow records. Bottom-up patient volume estimates and top-down manufacturer revenue analysis were cross-referenced for triangulation.
Segmentation dimensions modeled include product type, end user channel, technology platform, and application severity across the projection horizon. CAGRs were derived from patient demographic projections, reimbursement schedule evolution, and technology substitution curves. Forecast inputs incorporated MHLW pricing review cycles, PMDA guidance timelines for novel biologics, and meibomian gland dysfunction diagnostic protocol adoption rates.
Material uncertainties — PMDA biologic guidance revisions, API supply disruptions, and ophthalmologist workforce migration patterns — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and reimbursement continuity that may require adjustment. Recalibration cycles align with material shifts in MHLW pricing reviews and PMDA novel therapy designations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Global Vitreous Tamponades Market