
 Neurotrophic Keratitis Market | 2026-2036
Neurotrophic Keratitis Market Size, Share, and Industry Trends Forecast 2026-2036
Neurotrophic Keratitis Market Outlook
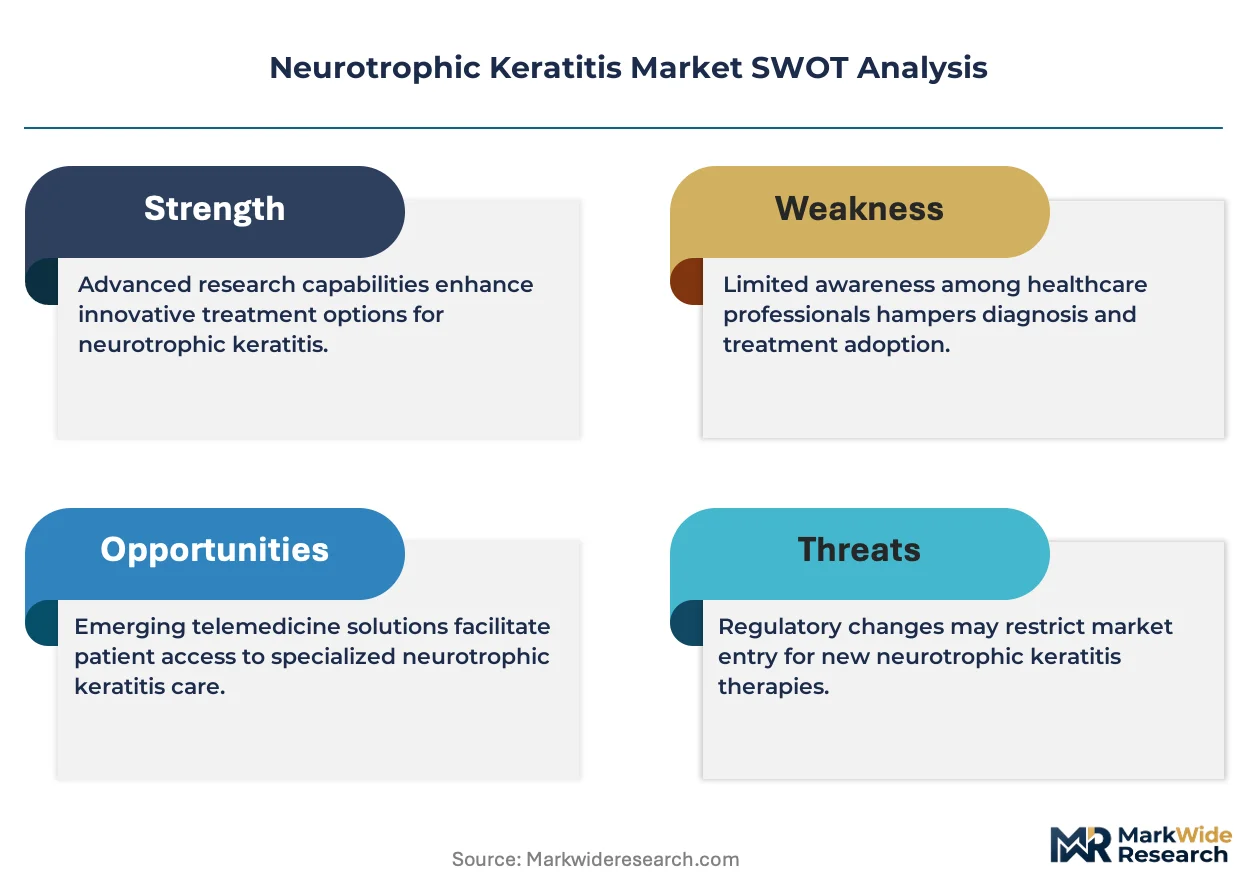
Modular bundling of diagnostic workup with therapeutic intervention is rebalancing how corneal specialists procure neurotrophic keratitis care. Dompé Farmaceutici sustains its position through vertical integration from recombinant nerve growth factor production to direct hospital channel control. AbbVie leverages its immunology infrastructure to compete in adjacent ocular surface disease portfolios. Santen Pharmaceutical anchors its presence across Asia-Pacific through specialized ophthalmology sales forces that dominate hospital formulary access.
Neurotrophic keratitis constitutes a rare degenerative corneal disorder characterized by impaired trigeminal innervation leading to epithelial breakdown, ulceration, and potential perforation, with diagnostic criteria requiring corneal sensation testing below 30 millimeters using a Cochet-Bonnet esthesiometer alongside persistent epithelial defects. Pharmacological treatment encompasses recombinant human nerve growth factor formulations, autologous serum eye drops, and preservative-free artificial tears designed to restore epithelial integrity and prevent stromal melting. The regenerative therapy segment leads margin pools due to orphan pricing dynamics and limited competition, while hospital pharmacies control the dominant distribution channel through restricted biologic handling requirements. Online pharmacies represent the fastest-growing distribution vector as specialty pharmacies build cold-chain capabilities for temperature-sensitive biologics.
FDA orphan drug designation and EMA PRIME eligibility frameworks shape clinical trial incentives and accelerated market access pathways for novel neurotrophic keratitis therapies. The EU MDR and ISO 14155 standards govern device-drug combination products such as contact lens inserts delivering sustained-release formulations. Stakeholders must monitor how payer evidence requirements for corneal nerve regeneration biomarkers evolve alongside competitive entries in the regenerative therapy space.
Market Dynamics
Hospital-based corneal specialists are consolidating procurement around bundled diagnostic-therapeutic protocols, compressing vendor selection cycles and favoring suppliers with integrated nerve growth factor manufacturing and cold-chain distribution capabilities.
Growth Catalysts
- EMA PRIME Eligibility:Accelerated assessment pathways for regenerative therapies reduce time-to-market for novel biologics targeting rare corneal disorders.
- Tertiary Ophthalmology Centers:Concentration of surgical volume in specialized hospitals creates anchor demand for high-complexity neurotrophic keratitis interventions.
- Recombinant Protein Engineering:Advances in stable nerve growth factor formulations enable extended shelf-life and expanded pharmacy distribution.
Market Restraints
- Biologic Cold-Chain Costs:Temperature-sensitive recombinant therapies require specialized logistics infrastructure that limits rural and community hospital access.
- Diagnostic Equipment Concentration:Cochet-Bonnet esthesiometers and confocal microscopes cluster in academic medical centers, creating geographic access disparities.
- Orphan Drug Pricing Scrutiny:Payer resistance to premium regenerative therapy reimbursement compresses margin expansion potential in volume markets.
Strategic Opportunities
- Specialty Pharmacy Networks:Independent specialty pharmacies with biologic handling certification represent underdeveloped distribution capacity for temperature-controlled corneal therapies.
- Autologous Serum Standardization:Protocol harmonization for patient-derived eye drops creates white space for GMP-compliant processing services.
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions attract development investment in next-generation neurotrophic agents.
Industry Challenges
- Corneal Specialist Training Pipeline:Fellowship programs produce insufficient numbers of surgeons trained in advanced ocular surface reconstruction techniques.
- Biomarker Validation Timelines:Regulatory acceptance of corneal nerve density imaging as surrogate endpoints remains unresolved, extending pivotal trial durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurotrophic Keratitis Market |
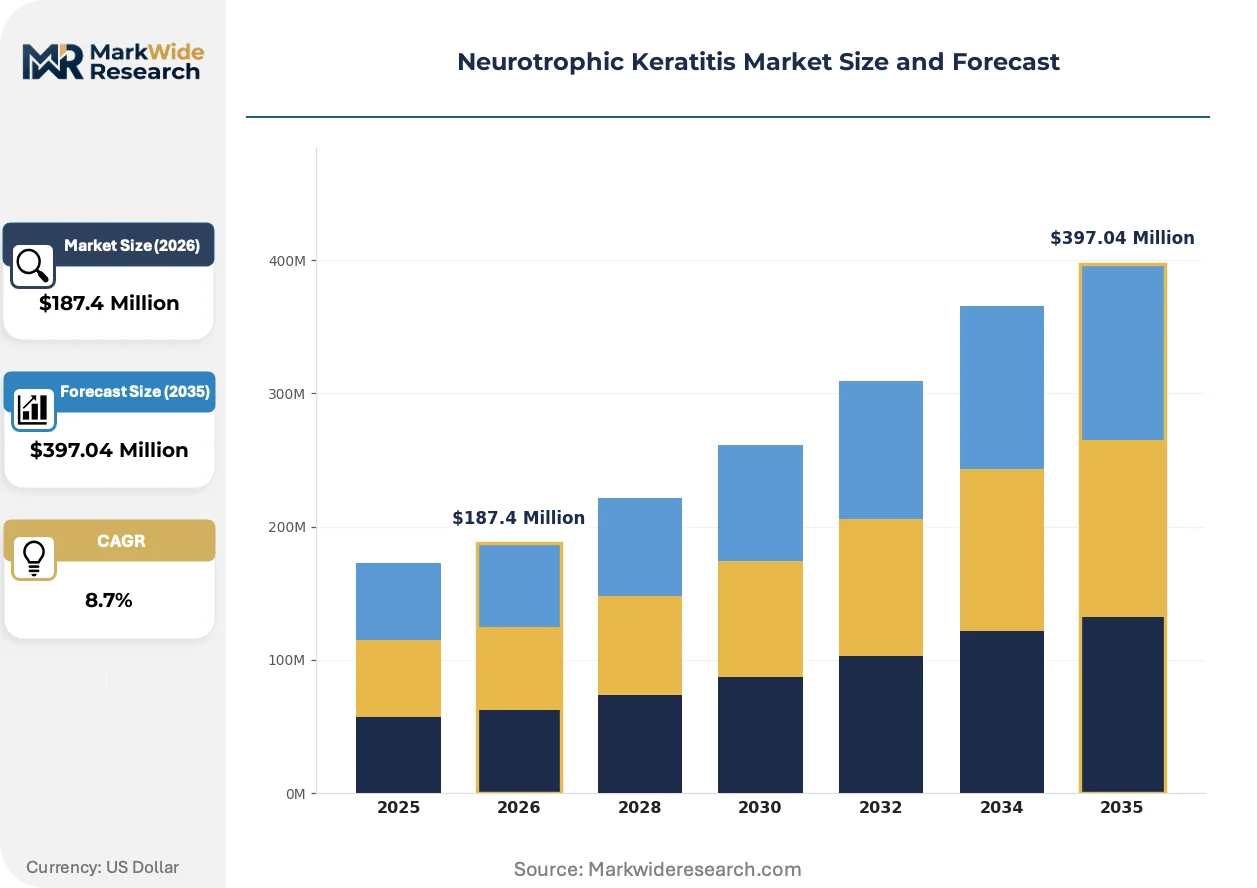
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Tears, Ophthalmic Solutions, Contact Lens Inserts, Eye Drops End User: Clinics, Hospitals, Home Care Settings, Research Institutions Treatment Method: Pharmacological, Surgical Intervention, Regenerative Therapy, Palliative Care Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Dompé Farmaceutici S.p.A., AbbVie Inc., Bausch Health Companies Inc., ReGenTree, LLC, Santen Pharmaceutical Co., Ltd., Johnson & Johnson, Novartis AG, Allergan, Ocular Therapeutix, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurotrophic Keratitis Market Strategic Shifts
Neurotrophic keratitis care is reconfiguring around regenerative modalities that restore innervation rather than manage symptoms, with diagnostic protocols and reimbursement frameworks adapting to biologic-first treatment sequences.
Sustained-release contact lens inserts delivering recombinant human nerve growth factor are absorbing market interest from conventional drop formulations. Corneal specialists in tertiary referral networks are piloting these devices for patients with persistent epithelial defects. The technology is absorbing development investment that previously flowed toward preservative-free artificial tear line extensions.
EU MDR device-drug combination product classifications are tightening quality management system requirements for lens-based delivery platforms. Manufacturers must demonstrate biocompatibility and drug stability across extended wear periods. German notified bodies are processing the bulk of conformity assessments, creating regulatory queue congestion for smaller developers.
Hospital pharmacy directors are consolidating vendor relationships around suppliers offering bundled diagnostic workup and therapeutic procurement. Single-source contracting for nerve growth factor biologics and companion esthesiometry equipment is displacing fragmented purchasing across separate capital and pharmacy budgets. This concentration is most visible in United States academic medical centers where value-based care contracts incentivize total episode cost management.
Neurotrophic Keratitis Market Segmentation
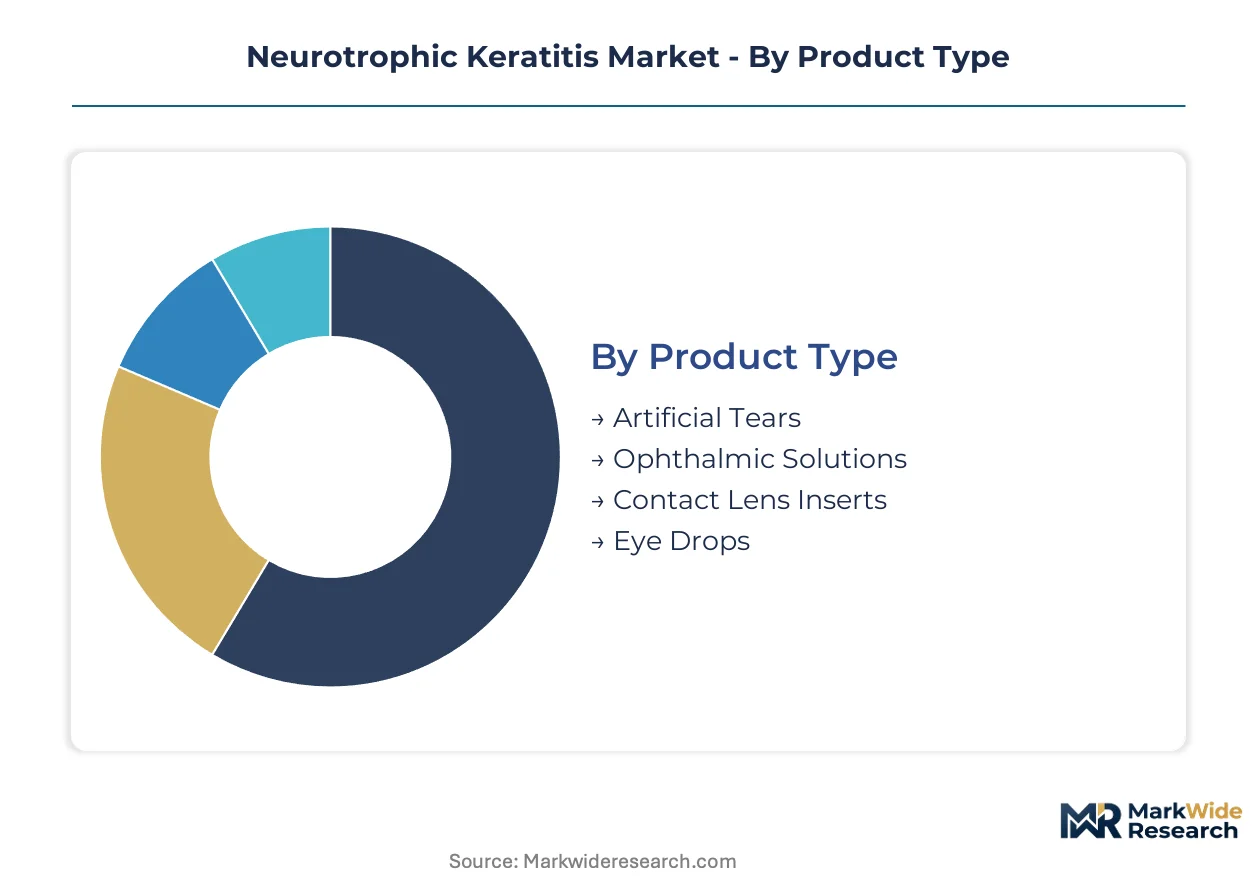
Segmentation in neurotrophic keratitis reveals how procurement authority, treatment complexity, and cold-chain requirements reshape vendor relationships. Understanding these divisions exposes where margin pools concentrate and which access pathways face friction.
Product Type:
Cost tier separates acute intervention from chronic maintenance, with biologic pricing commanding premium positioning against commodity lubricants.
- Artificial Tears:Preservative-free formulations serve as first-line maintenance therapy for early-stage epithelial irregularity. Demand clusters in United States retail pharmacies where patients self-manage between specialist visits, constrained by formulary exclusion from orphan drug reimbursement tiers.
- Ophthalmic Solutions:Recombinant human nerve growth factor solutions target persistent epithelial defects with disease-modifying mechanism. United States tertiary centers anchor procurement volume, driven by FDA orphan drug exclusivity and bundled diagnostic-therapeutic protocols that favor high-efficacy biologics.
- Contact Lens Inserts:Sustained-release drug-device combinations extend therapeutic residence time on compromised corneal surfaces.
- Eye Drops:Autologous serum preparations require patient-specific processing and cold-chain handling.
Ophthalmic solutions lead volumes today; contact lens inserts are gaining share fastest.
End User:
Patient acuity and procedural capability determine where complex regenerative therapies concentrate versus where palliative management suffices.
- Hospitals:Academic medical centers with corneal fellowship programs control access to surgical intervention and biologic prescribing. Germany's university hospitals anchor European volume through EMA PRIME-eligible therapy administration and confocal microscopy diagnostics.
- Clinics:Private ophthalmology practices manage stable patients with artificial tears and monitoring protocols. Japan's specialized eye clinics concentrate follow-up volume, supported by PMDA reimbursement pathways for maintenance therapy.
- Home Care Settings:Patient-administered regimens require simplified cold-chain logistics and caregiver training.
- Research Institutions:Clinical trial sites generate demand for investigational regenerative agents and biomarker validation.
Hospitals dominate biologic revenue; clinics are expanding fastest as diagnostic equipment decentralizes.
Treatment Method:
Margin structure inverts between symptom management and disease modification, with regenerative modalities capturing orphan pricing premiums.
- Regenerative Therapy:Recombinant nerve growth factor and gene therapy approaches target trigeminal nerve restoration rather than epithelial patching. United States academic centers concentrate adoption, propelled by FDA tax credits for rare disease development and seven-year market exclusivity provisions.
- Pharmacological:Topical immunosuppressants and growth factor formulations manage inflammation and promote healing. German hospital pharmacies anchor procurement, shaped by EMA accelerated assessment pathways for novel biologics.
- Surgical Intervention:Tarsorrhaphy and amniotic membrane transplantation address advanced ulceration.
- Palliative Care:Pain management and visual rehabilitation for end-stage disease.
Regenerative therapy commands highest revenue per patient; pharmacological treatment retains widest patient reach.
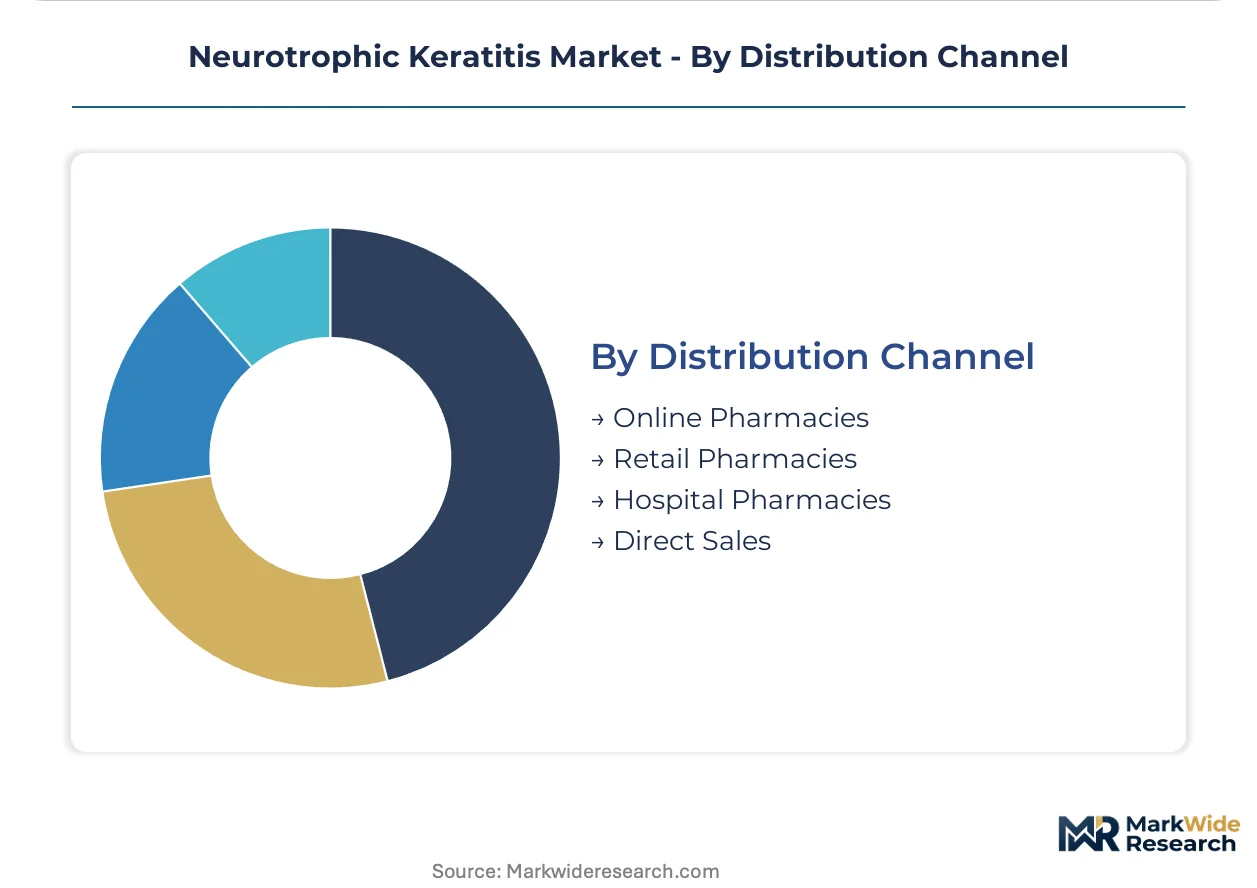
Distribution Channel:
Cold-chain certification and biologic handling credentials fragment access between institutional and patient-direct pathways.
- Hospital Pharmacies:Restricted distribution networks control temperature-sensitive recombinant therapies through specialized storage infrastructure. United States health systems consolidate purchasing through single-source contracts that bundle diagnostics and therapeutics.
- Online Pharmacies:Specialty pharmacy platforms build cold-chain capabilities for direct-to-patient biologic delivery. Japanese digital health infrastructure supports this channel expansion through METI-backed logistics standardization.
- Retail Pharmacies:Community outlets handle artificial tears and non-biologic maintenance therapies.
- Direct Sales:Manufacturer-to-provider contracting for device-drug combination products.
Hospital pharmacies control biologic volume; online pharmacies are climbing the fastest as specialty certification spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurotrophic keratitis therapeutic development originated in Italian pharmaceutical research centers during the early recombinant protein era, with subsequent commercial scaling concentrated in United States academic medical centers and German university hospital networks.
United States
Academic medical centers in Boston, Baltimore, and San Francisco anchor biologic prescribing volume for recombinant nerve growth factor therapies. FDA orphan drug tax credits and seven-year market exclusivity provisions attract development investment from domestic and foreign sponsors. The Cleveland Clinic and Johns Hopkins corneal fellowship programs train specialists who concentrate surgical intervention capacity in the Northeast and Midwest corridors.
Germany
University hospitals in Heidelberg, Tübingen, and Munich control European access to EMA PRIME-eligible regenerative therapies through centralized biologic pharmacy infrastructure. The EU MDR device-drug combination framework governs sustained-release contact lens insert development, with German notified bodies processing the majority of conformity assessments for ophthalmic delivery platforms. Baden-Württemberg's medical technology cluster hosts confocal microscopy manufacturers that supply diagnostic equipment across the continent.
Japan
Specialized eye clinics in Tokyo and Osaka concentrate maintenance therapy volume for stable neurotrophic keratitis patients. METI-backed logistics standardization supports cold-chain infrastructure expansion for direct-to-patient biologic delivery. PMDA reimbursement pathways for autologous serum preparations create demand for GMP-compliant processing services in the Kanto region.
Italy
Milan and Rome anchor Mediterranean demand for orphan-designated corneal therapies through tertiary ophthalmology referral networks. The country's national pharmaceutical regulator oversees accelerated assessment pathways for rare disease biologics manufactured in Lombardy-based production facilities. Italian corneal specialists pioneered nerve growth factor formulation science that now supplies hospital pharmacies across Southern Europe.
United Kingdom
London's Moorfields Eye Hospital and Manchester Royal Eye Hospital concentrate NHS-funded regenerative therapy administration for complex ocular surface disease. The Medicines and Healthcare products Regulatory Agency processes UK-specific marketing authorizations for biologics already cleared through centralized EMA procedures. Southeast England's pharmaceutical services sector provides cold-chain distribution capacity that reaches Northern England and Scotland.
Neurotrophic Keratitis Market Competitive Environment
The competitive structure tilts toward vertically integrated biologic manufacturers with captive recombinant protein production and direct hospital channel control. Two strategic archetypes dominate: multinational ophthalmology portfolios leveraging immunology infrastructure, and specialized rare disease players with orphan drug manufacturing expertise. Competitive moves concentrate on single-source hospital contracting that bundles diagnostics with therapeutic procurement, and specialty pharmacy network certification for direct-to-patient cold-chain delivery.
Among Italy-based pharmaceutical developers, Dompé Farmaceutici S.p.A. exemplifies the vertically integrated archetype spanning recombinant nerve growth factor production through hospital formulary access. Japanese specialists Santen Pharmaceutical Co., Ltd. occupy a position representing Asia-Pacific ophthalmology sales force concentration. AbbVie Inc. sits within the diversified immunology portfolio tier, leveraging existing infrastructure to compete in adjacent ocular surface disease segments.
| Leading Market Players |
|---|
| Dompé Farmaceutici S.p.A. |
| AbbVie Inc. |
| Bausch Health Companies Inc. |
| ReGenTree, LLC |
| Santen Pharmaceutical Co., Ltd. |
| Johnson & Johnson |
| Novartis AG |
| Allergan |
| Ocular Therapeutix, Inc. |
| Others |
Value Chain & Pricing Dynamics
Hospital formulary consolidation around bundled diagnostic-therapeutic protocols in the United States and Germany is forcing recombinant nerve growth factor suppliers to absorb cold-chain infrastructure costs and accept longer payment cycles, compressing margin structures for manufacturers lacking captive production capacity.
Pricing Analysis
Three-tier pricing structure across premium biologic, standard processed serum, and economy artificial tear levels dominates procurement. FDA orphan drug exclusivity and EMA PRIME eligibility command premium positioning for recombinant therapies, while autologous serum occupies mid-tier positioning shaped by GMP processing certification. Cost compression in the artificial tear segment intensifies as retail pharmacy formularies exclude non-preserved formulations from reimbursement tiers. Clinic-based buyers in Japan exhibit highest price sensitivity due to PMDA maintenance therapy reimbursement caps.
Supply Chain Analysis
Dual-sourcing mandates from United States academic medical centers and German university hospitals require recombinant protein manufacturers to qualify secondary production facilities in Italy and Switzerland. Active pharmaceutical ingredient supply draws from Lombardy-based bioreactor facilities and Basel-region contract manufacturing organizations. Single-source vulnerability concentrates around recombinant nerve growth factor cell line banks held by Italian developers. Distribution runs through hospital pharmacy restricted networks with temperature-monitored logistics, supplemented by METI-certified specialty pharmacy platforms in Japan for direct-to-patient delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA orphan drug tax credits and EMA accelerated assessment pathways create demand acceleration for developers with rare disease infrastructure.
For Market Incumbents: Deepen backward integration into recombinant protein production to defend against emerging gene therapy entrants and secure margin protection from cold-chain cost inflation. Expand hospital formulary control through bundled esthesiometry equipment contracts that lock out competing biologic suppliers. Prioritize EU MDR conformity assessment queue positioning with German notified bodies to sustain device-drug combination product leadership. For New Entrants and Emerging Players: Capture specialty pharmacy certification white space in Japan's Kanto region where METI logistics standardization creates infrastructure leverage for temperature-controlled direct delivery. Target autologous serum processing services as the most penetrable segment, exploiting GMP compliance gaps among existing hospital compounding operations. Lead with reimbursement strategy expertise to navigate PMDA maintenance therapy pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated rare disease specialists possessing captive recombinant manufacturing and established hospital channel relationships. Long-term viability favors developers with corneal nerve regeneration biomarker platforms that could shorten pivotal trial durations. Watch for EMA PRIME eligibility announcements as inflection indicators for accelerated market access valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| EMA PRIME Pathway Pursuit | Accelerated assessment reduces time-to-market for novel biologics targeting rare corneal disorders. |
| Hospital System Partnership | Bundled diagnostic-therapeutic contracting with academic medical centers locks out competing suppliers. |
| Specialty Pharmacy Certification | Cold-chain credentialing enables direct-to-patient biologic delivery outside institutional pharmacy control. |
| Biomarker Validation Investment | Corneal nerve density imaging endpoints could compress regulatory trial timelines and accelerate approval. |
| EU MDR Conformity Assessment | German notified body queue positioning secures device-drug combination product market access. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded the qualitative assessment. Secondary validation drew from FDA orphan drug designations, EMA PRIME eligibility decisions, ClinicalTrials.gov neurotrophic keratitis protocols, and Japanese PMDA reimbursement bulletins. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs across the analysis window.
Top-down modeling anchored regional projections to tertiary ophthalmology center capacity and corneal specialist fellowship pipeline outputs. Segmentation dimensions spanned product type, end user acuity, treatment method mechanism, and distribution channel certification. CAGRs emerged from therapy adoption curves shaped by FDA exclusivity periods and EMA accelerated assessment completion timelines. Forecast inputs incorporated orphan drug pricing dynamics and cold-chain logistics cost trajectories without year-specific assumptions.
Regulatory pathway delays, biomarker validation setbacks, and payer resistance to premium biologic reimbursement are the dominant revision risks to the outlook. Deviation in FDA orphan drug tax credit policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Lazy Eye Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Vision Care Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market