
 Retinal Detachment Market | 2026-2036
Retinal Detachment Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Detachment Market Outlook
The ophthalmology clinic segment is pivoting toward same-day surgical models, reducing hospital dependency for routine retinal interventions. Alcon Inc. leverages its integrated vitrectomy platform to sustain high-margin recurring revenue from consumables. IRIDEX Corporation specializes in laser photocoagulation systems, occupying a defensible niche in outpatient settings. Carl Zeiss Meditec AG dominates optical coherence tomography diagnostics, extending its influence into preoperative planning workflows.
Retinal detachment describes the separation of the neurosensory retina from the underlying retinal pigment epithelium, typically requiring intervention when subretinal fluid accumulation exceeds the rate of natural resorption; pneumatic retinopexy achieves reattachment through intravitreal gas bubble injection combined with cryotherapy or laser photocoagulation to seal retinal breaks. Reparative surgery commands the largest revenue pool due to instrument and consumable intensity, while laser therapy segments gain traction from office-based procedure migration and reduced recovery protocols. Vitrectomy technology leads in complex cases involving proliferative vitreoretinopathy, whereas scleral buckling retains cost advantages in phakic patients with anterior breaks.
The FDA governs premarket notification and approval pathways for retinal surgery devices, while the Centers for Medicare & Medicaid Services shapes procedure economics through physician fee schedule and ambulatory surgical center payment updates. ISO 13485 quality management standards and the EU Medical Device Regulation impose design control and post-market surveillance obligations on manufacturers selling into European markets. Stakeholders must monitor reimbursement parity shifts between facility types and anticipate how real-world evidence requirements will reshape clinical trial investment priorities.
Market Dynamics
Same-day surgical protocols are compressing care pathways for retinal detachment, forcing ophthalmology clinics to reconfigure physical infrastructure and staffing models around rapid patient turnover rather than overnight observation.
Growth Catalysts
- Office-based laser systems:IRIDEX photocoagulation platforms enable outpatient retinopexy without surgical suite overhead, expanding addressable procedure volume in ambulatory settings.
- CMS ASC payment updates:The Centers for Medicare & Medicaid Services reimbursement parity between hospital outpatient departments and ambulatory surgical centers accelerates facility migration for pneumatic retinopexy.
- Aging phakic populations:United States demographic shifts toward patients retaining natural lenses sustain scleral buckling demand as a cost-effective alternative to vitrectomy in appropriate anatomical presentations.
Market Restraints
- Silicone oil supply concentration:Vitrectomy-dependent tamponade agents face raw material sourcing bottlenecks concentrated among specialized chemical manufacturers, creating instrument-to-consumable dependency risk.
- Proliferative vitreoretinopathy recurrence:Complex detachment cases involving epiretinal membrane formation exhibit technical limitation rates that compress reimbursement confidence for high-acuity surgical intervention.
- EU MDR transition friction:The European Union Medical Device Regulation imposes extended conformity assessment timelines for optical coherence tomography diagnostic platforms, delaying platform refresh cycles.
Strategic Opportunities
- Tele-ophthalmology screening networks:Rural United States health systems deploy remote diagnostic hubs to identify macula-off detachments earlier, compressing time-to-intervention windows.
- AI-assisted surgical planning:Machine learning segmentation of preoperative OCT volumes converges with intraoperative heads-up display systems to reduce surgeon cognitive load during membrane peeling.
- Direct-to-employer contracting:Self-insured corporations in high-deductible plan structures negotiate bundled rates for retinal procedures, bypassing traditional payer intermediaries.
Industry Challenges
- Vitreoretinal fellowship pipeline constraints:The specialized microsurgical skill required for complex detachment repair faces training program capacity limitations, restricting qualified surgeon supply.
- ISO 13485 audit burden:Quality management recertification timelines for multi-site manufacturers create compliance friction that diverts engineering resources from product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Detachment Market |
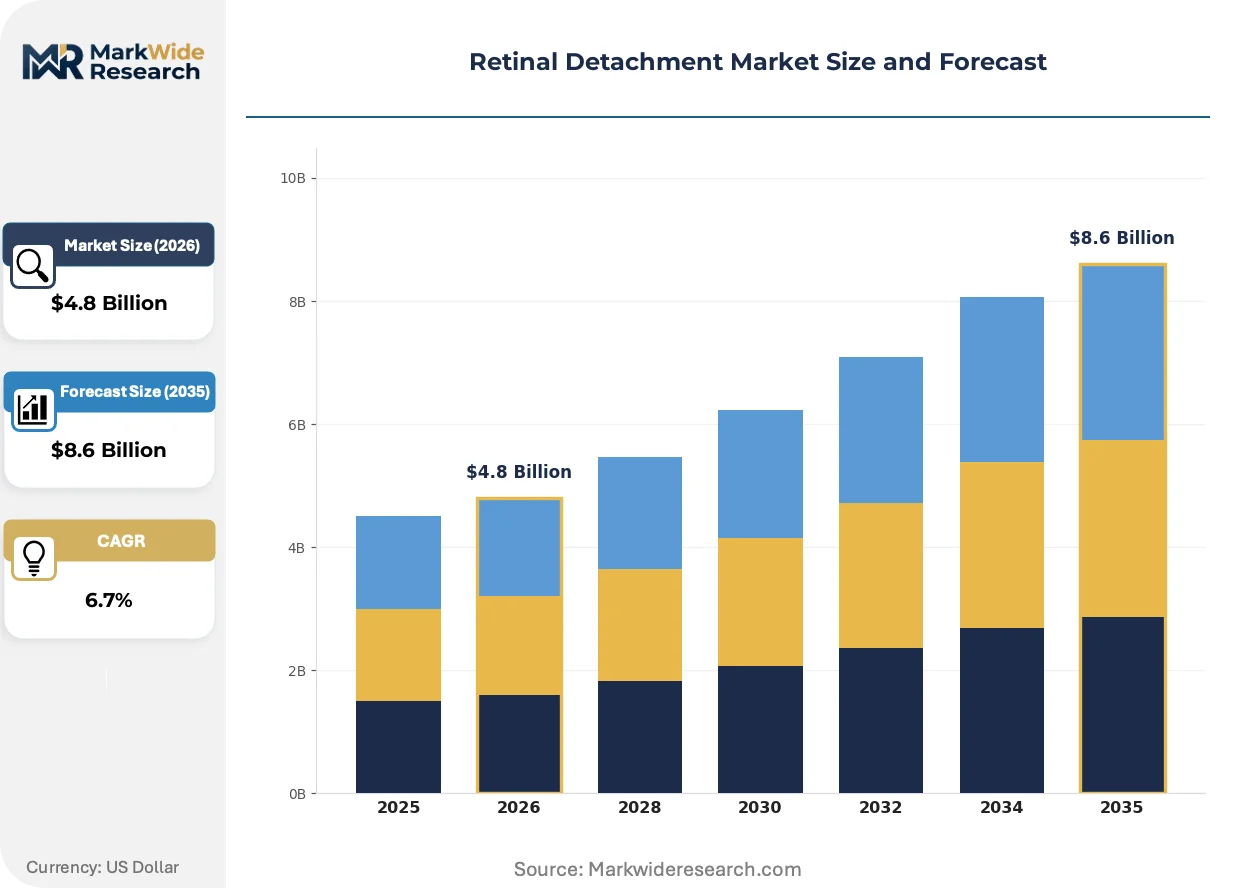
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reparative Surgery, Laser Therapy, Cryotherapy, Drug Therapy Technology: Vitrectomy, Pneumatic Retinopexy, Scleral Buckling, Circumferential Buckling End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Application: Retinal Repair, Vision Restoration, Diagnostic Procedures, Post-surgical Monitoring |
| Companies Covered | IRIDEX Corporation, Alcon Inc., Inami & Co., Ltd., Geuder AG, Dutch Ophthalmic Research Center International B.V., FCI Ophthalmics, Bausch & Lomb Incorporated, Ellex Medical Lasers Ltd, Carl Zeiss Meditec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Detachment Market Strategic Shifts
Digital surgical visualization is collapsing the distinction between diagnostic imaging and operative field guidance, creating integrated workflow ecosystems that reduce instrument exchange friction and shorten procedure duration.
Heads-up three-dimensional display systems are unifying preoperative OCT segmentation with real-time intraoperative visualization. Vitreoretinal surgeons at high-volume academic medical centers adopt these platforms to reduce neck strain and improve depth perception during membrane dissection. The technology is unifying diagnostic and therapeutic workflows into single-environment procedures, compressing facility time requirements.
The FDA's evolving premarket review pathways for breakthrough ophthalmic devices compress 510(k) clearance timelines for instruments demonstrating substantial equivalence to predicate technologies. Manufacturers responding to this regulatory tailwind accelerate iterative platform development rather than pursuing de novo classification. Vitrectomy console upgrades constitute the segment most affected, with firms prioritizing modular hardware architectures that accommodate software-driven feature expansion.
Patients with high-deductible health plans increasingly demand transparent procedure pricing prior to scheduling, disrupting traditional opaque hospital charge-master structures. Ambulatory surgical centers capture this behavioral shift through published bundled rates that include facility, physician, and anesthesia components. This pattern concentrates in United States metropolitan markets where employer-sponsored consumer-directed health plans predominate.
Retinal Detachment Market Segmentation
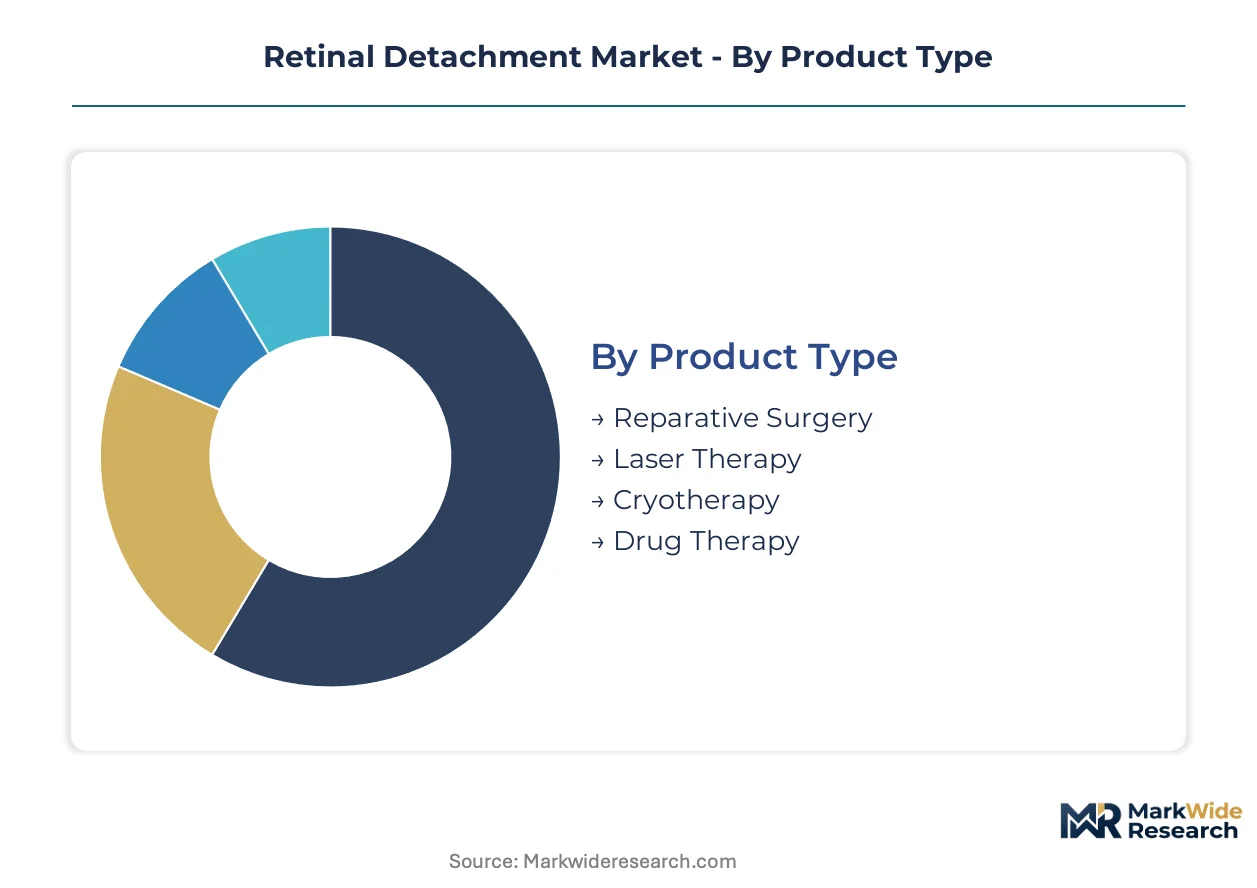
Retinal detachment interventions fragment across four distinct axes that shape procurement patterns and facility investment priorities. Surgical technique selection drives capital equipment allocation, while care setting migration reconfigures reimbursement capture across provider types.
Product Type:
Technology specifications determine consumable intensity and facility infrastructure requirements across intervention modalities.
- Reparative Surgery:Vitrectomy and scleral buckling procedures demand specialized instrumentation including high-speed cutters, endoillumination systems, and scleral bands. United States ambulatory surgical centers capture disproportionate volume as CMS payment parity accelerates outpatient migration for routine detachments.
- Laser Therapy:Photocoagulation systems deliver targeted thermal energy to seal retinal breaks through office-based delivery platforms. IRIDEX Corporation and comparable vendors supply portable units that eliminate surgical suite overhead, expanding addressable procedure volume in ophthalmology clinic settings.
- Cryotherapy:Trans-scleral freezing probes achieve chorioretinal adhesion through controlled tissue necrosis at break margins. The modality retains cost advantages in resource-constrained environments lacking laser infrastructure.
- Drug Therapy:Adjunctive pharmacologic agents including anti-VEGF compounds and corticosteroids address proliferative vitreoretinopathy and macular edema complicating surgical repair.
Reparative surgery leads on scale; laser therapy leads on momentum.
Technology:
Procedure selection hinges on break location, lens status, and proliferative vitreoretinopathy presence.
- Vitrectomy:Pars plana approaches remove vitreous gel and address epiretinal membranes through 23- and 25-gauge instrument platforms. Complex posterior segment pathology in the United States academic medical centers sustains demand for advanced console systems with integrated fluidics management.
- Pneumatic Retinopexy:Gas tamponade combined with cryotherapy or laser delivers reattachment without scleral manipulation. Office-based delivery in United States metropolitan markets captures patients seeking minimal recovery protocols.
- Scleral Buckling:External silicone elements indent sclera to relieve vitreoretinal traction. Phakic patient populations sustain demand as a lens-preserving alternative to vitrectomy.
- Circumferential Buckling:360-degree encircling elements address multiple breaks and dialysis configurations. The technique retains relevance in high-myopia presentations with extensive peripheral pathology.
Vitrectomy dominates complex case revenue; pneumatic retinopexy climbs the fastest through office-based expansion.
End User:
Facility type determines reimbursement capture and capital equipment amortization schedules.
- Ophthalmology Clinics:Same-day surgical models reduce hospital dependency for routine interventions. United States private practice networks invest in laser platforms and minor procedure suites to retain patient volume.
- Hospitals:Tertiary centers manage complex detachments requiring overnight observation and multidisciplinary coordination. Academic medical centers concentrate fellowship training and research protocol enrollment.
- Ambulatory Surgical Centers:Specialized ophthalmology facilities achieve cost efficiency through high-volume scheduling and standardized supply chains.
- Research Institutions:Clinical trial sites evaluate novel surgical adjuncts and device platforms under FDA investigational device exemption protocols.
Ophthalmology clinics lead on momentum; hospitals retain complex case concentration.
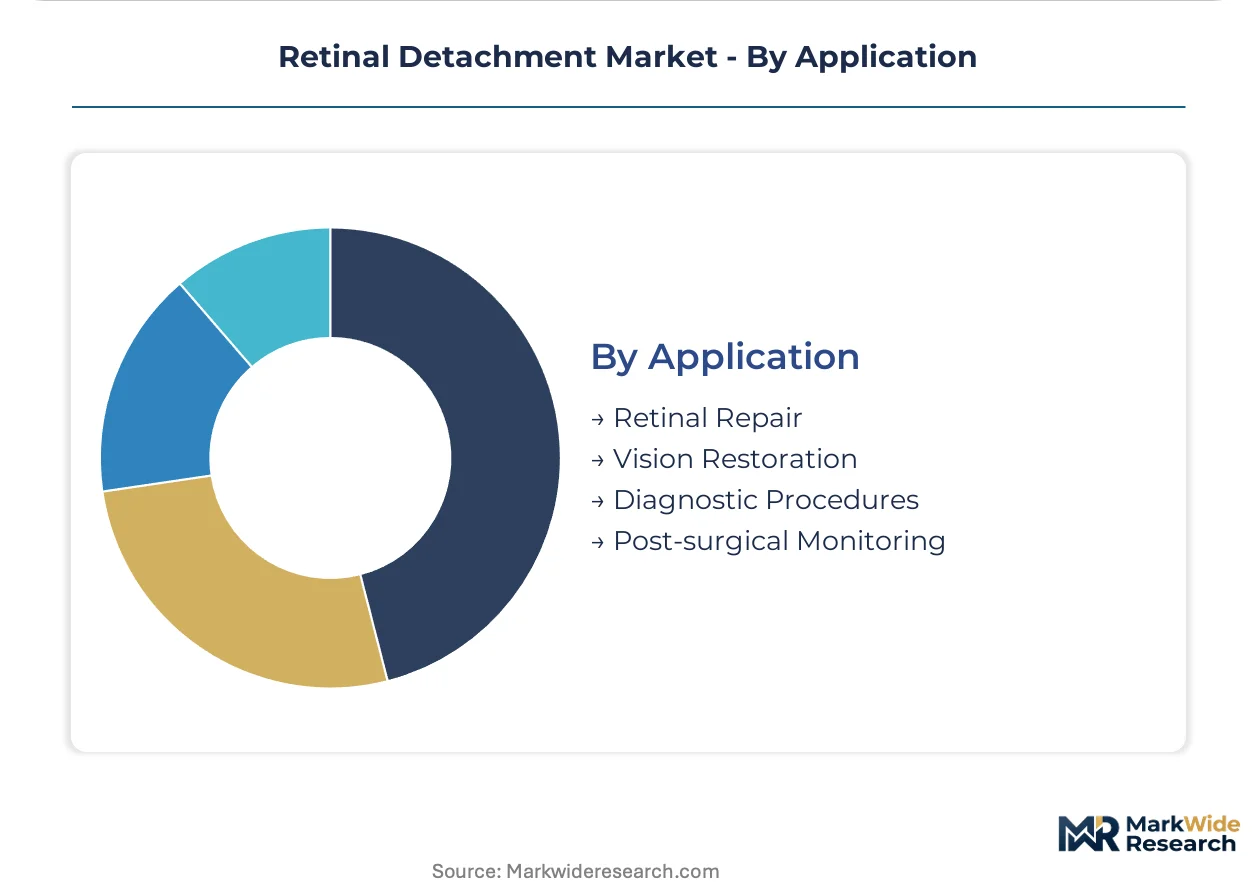
Application:
Clinical purpose shapes diagnostic and therapeutic workflow integration.
- Retinal Repair:Primary reattachment procedures address rhegmatogenous and tractional detachments through surgical or laser modalities.
- Vision Restoration:Secondary interventions address macular pathology including epiretinal membrane peeling and subretinal fluid drainage.
- Diagnostic Procedures:Optical coherence tomography and ultrasonography localize detachments and guide surgical planning.
- Post-surgical Monitoring:Surveillance protocols detect recurrence and silicone oil emulsification requiring secondary intervention.
Retinal repair leads on scale; diagnostic procedures gain share fastest through AI-assisted screening expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping device manufacturing footprints as manufacturers relocate assembly operations toward jurisdictions with streamlined quality management certification timelines and favorable premarket review pathways.
United States
Aging demographics and employer-sponsored high-deductible plans concentrate procedure demand in metropolitan ambulatory surgical centers. The FDA's breakthrough device designation streamlines 510(k) pathways for vitrectomy console upgrades. The Boston-Cambridge corridor anchors ophthalmic laser R&D clusters alongside academic medical center training pipelines.
Germany
Precision optics manufacturing heritage sustains diagnostic device production for preoperative planning workflows. The EU Medical Device Regulation imposes extended conformity assessment timelines that compress platform refresh cycles. Baden-Württemberg hosts vertically integrated surgical instrument fabricators serving European hospital networks.
Japan
Super-aging society dynamics sustain phakic patient populations preferring lens-preserving scleral buckling interventions. PMDA premarket approval pathways emphasize clinical evidence standards for novel tamponade agents. The Nagoya-Chubu corridor concentrates vitreoretinal surgical instrument manufacturing for Asia-Pacific distribution.
China
Domestic NMPA regulatory harmonization accelerates local production of office-based laser photocoagulation platforms. Provincial healthcare procurement reforms favor cost-effective pneumatic retinopexy delivery in tier-two city ophthalmology clinics. The Yangtze River Delta hosts contract manufacturers supplying global OEM brands with ISO 13485-certified components.
India
Expanding vitreoretinal fellowship programs address surgeon supply constraints for complex detachment repair. CDSCO medical device rules impose import licensing requirements that incentivize local assembly of diagnostic platforms. Maharashtra's Mumbai-Pune corridor attracts multinational contract research organizations conducting clinical trials for surgical adjuncts.
Retinal Detachment Market Competitive Environment
Strategic partnerships dominate the current landscape as device manufacturers align with diagnostic imaging platforms to create integrated surgical workflow ecosystems. The vendor base concentrates around three tiers: diversified ophthalmic conglomerates with full-spectrum portfolios, specialized laser and visualization equipment vendors, and regional contract manufacturers supplying consumable components. Archetypes include integrated platform providers, niche laser specialists, and private-label instrument fabricators. Technology licensing agreements and backward integration into optical component supply represent the dominant competitive vectors.
Among diversified ophthalmic conglomerates, Alcon Inc. and Carl Zeiss Meditec AG exemplify integrated platform strategies spanning diagnostics through surgical intervention. IRIDEX Corporation occupies a specialist position within office-based laser delivery systems. These three entities represent distinct strategic archetypes: full-spectrum integration, precision optics dominance, and ambulatory-care-focused equipment specialization.
| Leading Market Players |
|---|
| IRIDEX Corporation |
| Alcon Inc. |
| Inami & Co., Ltd. |
| Geuder AG |
| Dutch Ophthalmic Research Center International B.V. |
| FCI Ophthalmics |
| Bausch & Lomb Incorporated |
| Ellex Medical Lasers Ltd |
| Carl Zeiss Meditec AG |
| Others |
Value Chain & Pricing Dynamics
Office-based laser photocoagulation platform adoption is simultaneously compressing per-procedure facility costs and concentrating procurement power among ophthalmology clinic networks that negotiate multi-unit instrument bundles. This technology shift redirects margin capture from hospital surgical suites toward ambulatory settings while amplifying volume-based pricing leverage for high-throughput buyers.
Pricing Analysis
Distributor margins on vitrectomy consoles typically run 15-22 percent before value-added services, while direct-to-OEM procurement by academic medical center consortia secures 8-12 point discounts for multi-system commitments. Pricing stratifies across premium, standard, and economy tiers differentiated by console fluidics sophistication and bundled software modules. Cost compression in economy-tier laser systems is intensifying because Chinese contract manufacturers are scaling ISO 13485-certified production for private-label brands. Ambulatory surgical centers exhibit the highest price sensitivity due to thin facility fee structures, whereas tertiary academic centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for vitrectomy consoles, while specialized distributors serve mid-tier ophthalmology clinics with financing and training wraparounds. Component sourcing concentrates in Germany for precision optical assemblies, Japan for high-speed pneumatic cutters, and China for laser diode modules and consumable packaging. Silicone oil tamponade agents draw from specialized chemical manufacturers in the United States and Japan, creating instrument-to-consumable dependency chains. Single-source vulnerability persists for 25-gauge micro-instrument tips where patent-protected designs limit qualified suppliers. Distribution runs through regional ophthalmic equipment specialists that maintain field service engineer networks for console maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retinal detachment market reads as a late-cycle quality story where outcomes-based contracting and AI-assisted surgical planning are elevating specifications for integrated diagnostic-therapeutic platforms. Premium-tier demand is concentrating among high-volume academic centers that prioritize workflow efficiency over per-unit instrument cost.
For Market Incumbents: Cement platform stickiness through backward integration into optical coherence tomography software ecosystems that lock in preoperative planning workflows. Expand captive supply of high-margin consumables including silicone oil tamponades and disposable instrument packs to defend against private-label entrants. The FDA's breakthrough device designation pathway for AI-enabled surgical guidance presents a certification moat against unvalidated software competitors. For New Entrants and Emerging Players: Ambulatory surgical center group purchasing organizations represent the most penetrable channel for portable laser photocoagulation platforms that eliminate surgical suite overhead. Target rural United States health systems deploying tele-ophthalmology screening networks where capital constraints favor lease-based equipment models over outright purchase. A software-as-a-service pricing model for AI-assisted surgical planning modules reduces upfront adoption barriers against integrated console incumbents. For Investors and Strategic Acquirers: Roll-up economics work for specialized vitreoretinal instrument fabricators because surgeon training program capacity constraints limit qualified supply and sustain pricing power for complex surgical tools. Five-to-ten year viability hinges on consolidation of mid-tier laser platform vendors into full-spectrum portfolios. The signal to watch is CMS reimbursement parity expansion for office-based pneumatic retinopexy, which would accelerate ambulatory setting migration and revalue clinic-focused equipment suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated 510(k) pathways compress time-to-revenue for AI-enabled vitrectomy consoles. |
| CE Marking Pathway Expansion | EU MDR conformity assessment timelines shape European platform refresh cycles for OCT diagnostics. |
| Hospital System Partnership | Integrated delivery networks negotiate bundled rates spanning diagnostics through surgical intervention. |
| Software Companion Development | Machine learning segmentation of preoperative OCT volumes reduces surgeon cognitive load during membrane peeling. |
| Reimbursement Strategy | CMS ASC payment parity shifts procedure economics toward ambulatory surgical centers. |
Study Parameters
Multiple input streams — vitreoretinal surgeon interviews, ophthalmology clinic administrator surveys, and regulatory filing analysis — were reconciled to construct demand estimates across the analysis window. Primary fieldwork engaged fellowship-trained surgeons, ambulatory surgical center medical directors, biomedical equipment procurement managers, and GPO contracts specialists. Secondary validation drew from FDA 510(k) clearances, CMS physician fee schedule updates, hospital procurement databases, and ISO 13485 certification registries. Bottom-up procedure volume estimates triangulated against top-down equipment shipment data from precision optics manufacturers.
Data-stream reconciliation applied segment-specific growth assumptions across surgical technique, care setting, and patient acuity dimensions. Modeled projections incorporated pars plana vitrectomy adoption curves, pneumatic retinopexy office-based migration rates, and scleral buckling persistence in phakic populations. CAGRs were derived from instrument replacement cycles, consumable attach rates, and reimbursement trajectory modeling. Industry-specific inputs included vitreoretinal fellowship graduation counts, silicone oil tamponade pricing indices, and laser platform utilization rates per clinic.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR transition friction, vitreoretinal surgeon supply constraints, and real-world evidence requirements reshaping clinical trial investment priorities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Fungal Eye Infection Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
North America Vision Care Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Eye Allergy Treatment Market
Ophthalmology
Orthokeratology Market