
 Trachoma Treatment Market | 2026-2036
Trachoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Trachoma Treatment Market Outlook
Community health programs is reorganizing demand in the trachoma treatment landscape, displacing traditional clinic-centric procurement with population-wide distribution models. Pfizer Inc. leverages its azithromycin donation program to sustain channel dominance across endemic regions. Novartis AG anchors its position through integrated access initiatives that combine drug supply with surveillance infrastructure. Merck & Co., Inc. competes on manufacturing scale for alternative antibiotic formulations used in targeted outbreak response.
Trachoma treatment encompasses medical and surgical interventions for Chlamydia trachomatis infection, with azithromycin single-dose oral therapy representing the primary pharmacological standard and tarsal rotation surgery reserved for trichiasis cases. Antibiotics dominate product type revenue due to mass drug administration scale, while surgical tools command premium pricing in advanced trachoma management. Community health programs represent the fastest-growing end user segment as national elimination programs shift delivery from facility-based to door-to-door models, concentrating margin pools in high-volume procurement contracts.
WHO prequalification requirements and national regulatory authorities in endemic countries shape product standards and market access for trachoma therapeutics, with stringent cold-chain and quality verification protocols governing azithromycin distribution. The FDA and EMA maintain oversight of innovator drug specifications that cascade into WHO procurement guidelines through reference standard alignment. Stakeholders must monitor evolving national elimination timelines and corresponding shifts from preventive mass treatment to reactive case management as disease prevalence thresholds change.
Market Dynamics
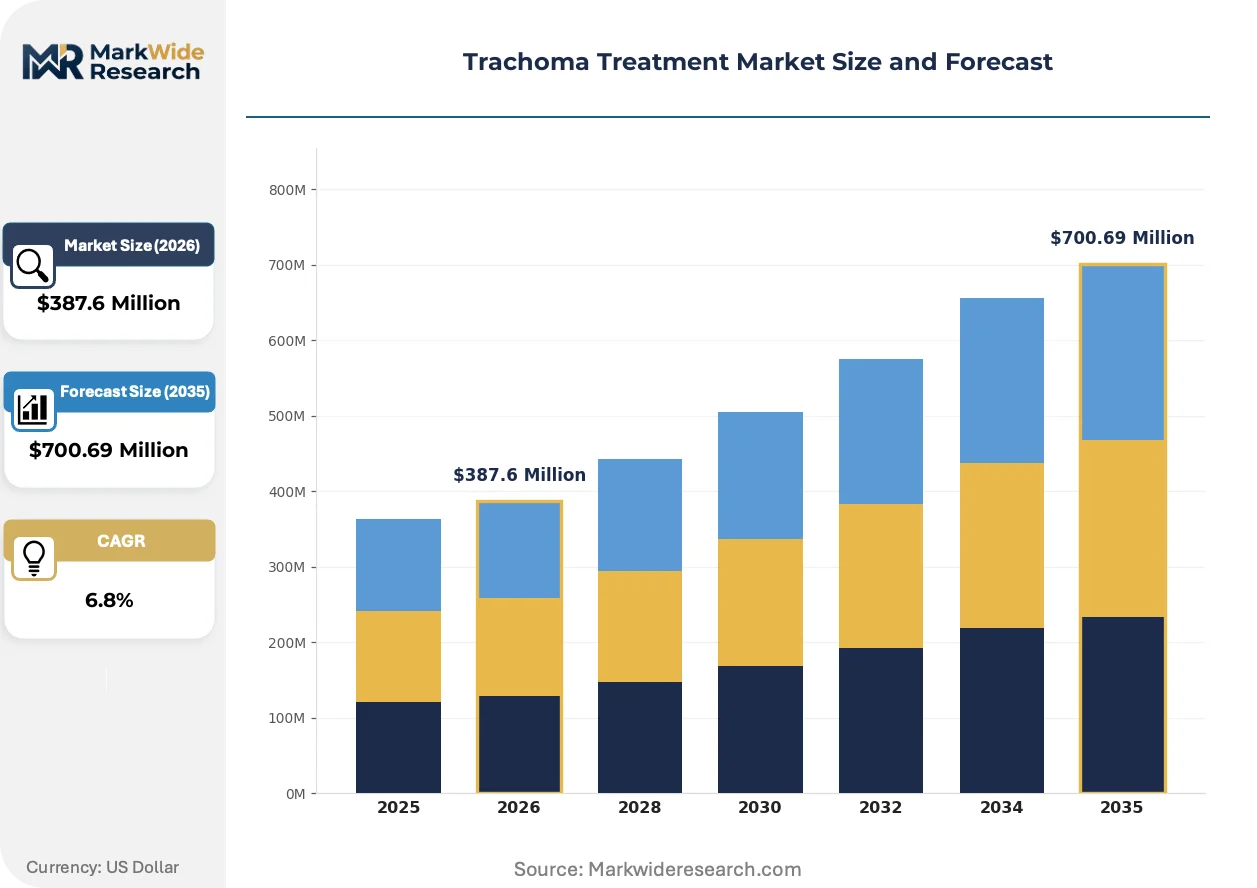
Mass drug administration campaigns by national elimination programs are reorganizing procurement flows, displacing clinic-centric distribution with population-wide delivery models that concentrate contract volumes in community health networks.
Growth Catalysts
- WHO SAFE Strategy:The WHO's integrated prevention framework mandates azithromycin distribution at scale across endemic regions, creating institutional demand pull for single-dose oral therapy procurement.
- Sub-Saharan Africa Disease Burden:Concentrated infection prevalence in Ethiopia, Nigeria, and Tanzania generates sustained procurement volumes for preventive chemotherapy programs.
- Azithromycin Donation Mechanisms:Pharmaceutical access programs reduce cost barriers for national health systems, enabling expanded treatment coverage in resource-limited settings.
Market Restraints
- Cold-Chain Infrastructure Gaps:Temperature-controlled storage requirements for antibiotic stability limit distribution reach in remote endemic areas with unreliable electricity.
- Surveillance System Fragmentation:Inconsistent trachoma mapping and prevalence data across district health systems complicates targeted resource allocation for elimination programs.
- Antimicrobial Resistance Pressures:Emerging macrolide resistance patterns in Chlamydia trachomatis strains threaten long-term efficacy of standard pharmacological protocols.
Strategic Opportunities
- Point-of-Care Diagnostic Convergence:Integration of rapid nucleic acid testing with mobile health platforms enables precision targeting of antibiotic distribution, reducing waste and resistance selection pressure.
- Ethiopia Elimination Timeline:Accelerated national targets for trachoma-free certification by 2030 are expanding surgical capacity-building contracts for trichiasis management.
- Community Health Worker Networks:Door-to-door distribution channels bypass traditional facility-based procurement, opening direct-to-community supply relationships for drug manufacturers.
Industry Challenges
- Ophthalmic Surgical Specialist Scarcity:Limited trained surgeons for tarsal rotation procedures creates bottlenecks in advanced trachoma management, particularly in rural district hospitals.
- Regulatory Harmonization Delays:Divergent national pharmaceutical registration requirements across endemic countries fragment procurement standardization and delay product market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trachoma Treatment Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Surgical Tools, Eye Ointments, Supportive Devices Therapy Area: Infectious Diseases, Ophthalmology, Preventive Care, Public Health Delivery Mode: Topical Applications, Oral Administration, Injectable Solutions, Surgical Procedures End User: Hospitals, Clinics, Home Care Settings, Community Health Programs |
| Companies Covered | Pfizer Inc., Novartis AG, GlaxoSmithKline plc, Merck & Co., Inc., Johnson & Johnson, AbbVie Inc., Teva Pharmaceutical Industries Ltd., Sanofi S.A., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trachoma Treatment Market Strategic Shifts
Digital health infrastructure and precision medicine approaches are transforming trachoma control from blanket mass treatment toward data-driven, targeted intervention models that optimize resource deployment.
Single-dose azithromycin oral suspension formulations are supplanting multi-day tetracycline eye ointment regimens as the first-line community treatment standard. National elimination programs in Ethiopia and Tanzania have accelerated this transition through procurement preference for directly observed therapy. The shift is compressing treatment adherence failures while elevating manufacturing scale requirements for oral macrolide production.
WHO prequalification standards for azithromycin quality and stability are tightening procurement eligibility for mass drug administration contracts. The revised guidelines mandate enhanced bioequivalence documentation and cold-chain verification protocols that exclude non-compliant suppliers. Generic manufacturers in India are responding with upgraded production facilities to maintain access to African national tender processes.
Community health workers now execute treatment distribution directly in endemic villages, bypassing clinic-based dispensing entirely. This channel reconfiguration displaces traditional pharmaceutical wholesaler relationships with centralized national procurement contracts managed by ministry of health logistics divisions. The transformation is most advanced in Nigeria's northern states, where door-to-door campaigns have achieved coverage rates unattainable through facility-based models.
Trachoma Treatment Market Segmentation
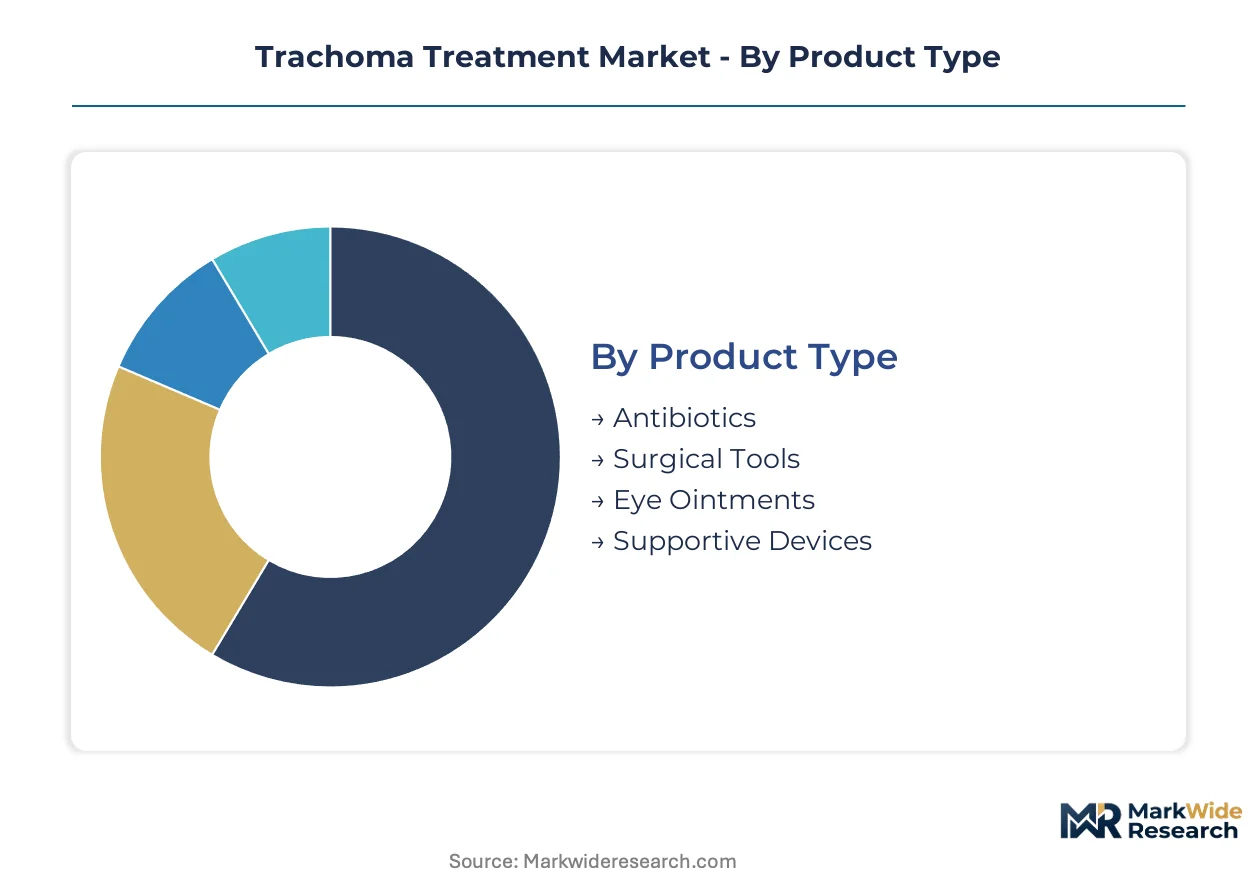
Segmentation in the trachoma treatment market reveals how procurement flows concentrate in specific channels while clinical applications span infectious disease management and ophthalmic surgery. Understanding these divisions exposes where contract volumes accumulate and where margin structures diverge across product categories.
Product Type:
Azithromycin manufacturing concentrates in Indian generic hubs for export to African national programs, while surgical instrument supply remains fragmented across regional medical device distributors.
- Antibiotics:Single-dose oral azithromycin dominates procurement volumes under WHO mass drug administration protocols. Demand concentrates in Ethiopia, Nigeria, and Tanzania where national elimination programs execute population-wide distribution campaigns through ministry of health logistics divisions.
- Surgical Tools:Tarsal rotation instruments and sterilization equipment serve trichiasis management in district hospitals. Procurement flows through specialized ophthalmic surgical suppliers serving Ethiopia's accelerated elimination timeline and Tanzania's surgical capacity-building initiatives.
- Eye Ointments:Tetracycline formulations persist in remote areas with cold-chain limitations.
- Supportive Devices:Diagnostic lamps and examination kits support field screening programs.
Antibiotics holds the largest share; momentum sits with Surgical Tools as elimination programs shift toward advanced case management.
Therapy Area:
Public health applications generate the highest procurement volumes through centralized national tenders, while ophthalmology commands premium pricing in surgical interventions.
- Infectious Diseases:Chlamydia trachomatis elimination protocols drive azithromycin procurement at scale. Community health workers in sub-Saharan Africa distribute single-dose therapy through door-to-door campaigns that bypass traditional pharmaceutical wholesale channels.
- Ophthalmology:Trichiasis surgical correction requires specialized instruments and trained surgeons. Ethiopia's national program has expanded surgical capacity contracts to meet accelerated elimination targets.
- Preventive Care:Facial cleanliness and environmental improvement components of WHO SAFE strategy.
- Public Health:Integrated disease surveillance and mapping infrastructure investments.
Infectious Diseases captures the dominant procurement volume; Public Health infrastructure spending is climbing fastest as digital surveillance systems deploy.
Delivery Mode:
Oral administration has displaced topical regimens in procurement preferences, while surgical procedures concentrate in tertiary facilities with specialist availability.
- Oral Administration:Single-dose azithromycin tablets and suspension formulations enable directly observed therapy in community settings. Nigerian northern states have achieved coverage rates through door-to-door distribution that facility-based models cannot match.
- Surgical Procedures:Tarsal rotation and eyelid correction surgeries address advanced trachomatous trichiasis. Demand clusters in Ethiopia's Amhara and Oromia regions where surgical specialist scarcity creates treatment backlogs.
- Topical Applications:Tetracycline eye ointment persists where cold-chain infrastructure fails.
- Injectable Solutions:Limited application in severe secondary infection management.
Oral Administration dominates procurement tonnage; Surgical Procedures show the steepest expansion trajectory as elimination deadlines approach.
End User:
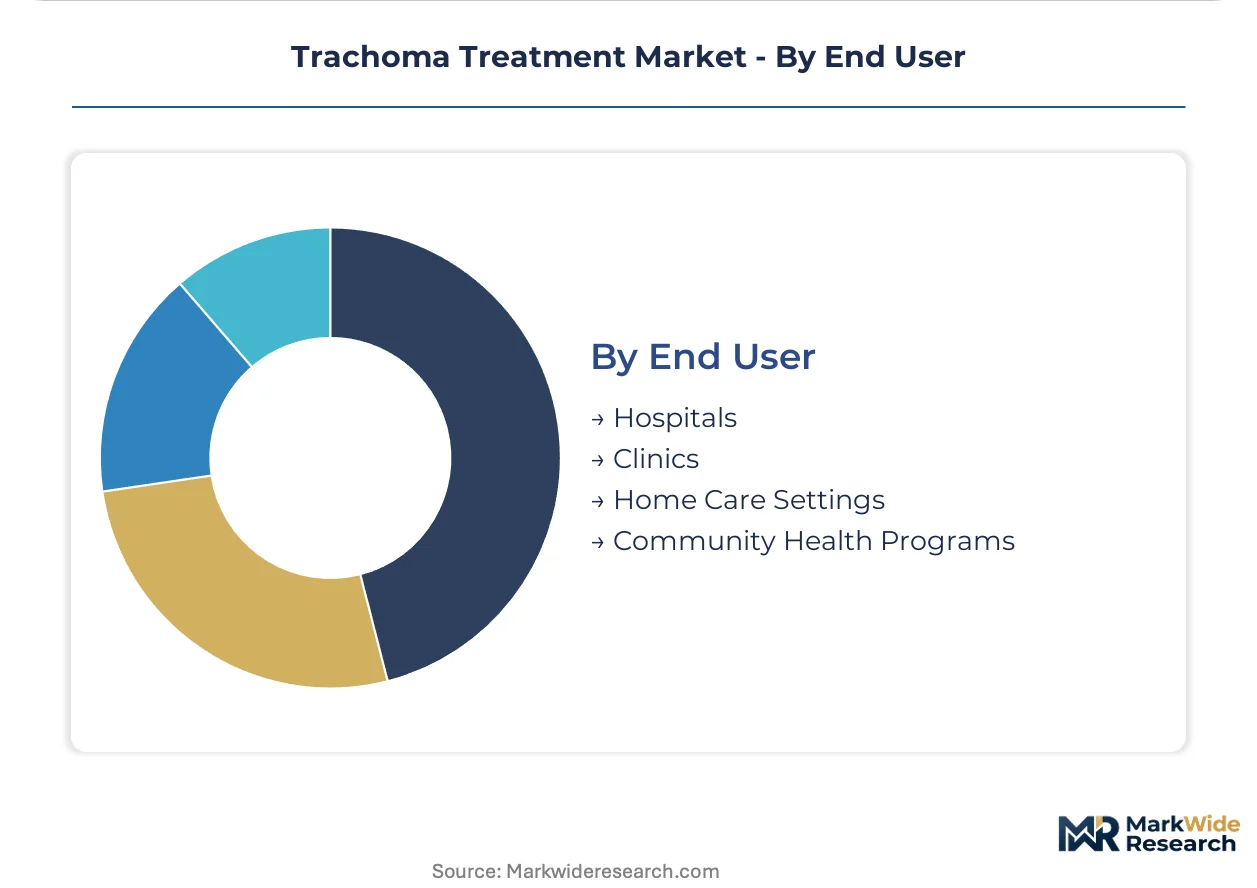
Community health programs have captured procurement flow reorganization from traditional facility-based dispensing, concentrating contract volumes in national logistics divisions.
- Community Health Programs:Door-to-door distribution models bypass clinic infrastructure entirely. Tanzania's national program has shifted procurement to centralized ministry contracts managed through community health worker networks.
- Hospitals:Surgical trichiasis management and complicated cases requiring specialist intervention. Ethiopian regional hospitals handle backlog clearance for advanced disease stages.
- Clinics:Diagnostic screening and referral functions in district health systems.
- Home Care Settings:Limited to facial hygiene compliance and post-surgical follow-up.
Community Health Programs commands the largest procurement allocation; Hospitals maintain premium pricing power in surgical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian generic manufacturers export azithromycin formulations to African national health programs, with procurement flows consolidating through WHO-prequalified supply chains into Ethiopia, Nigeria, and Tanzania.
Ethiopia
Amhara and Oromia regions host the highest active trachoma infection burden worldwide, driving mass drug administration procurement through the Federal Ministry of Health. Ethiopia's national elimination program targets trachoma-free certification by 2030, accelerating surgical capacity contracts for trichiasis backlog clearance. Addis Ababa serves as the logistics hub coordinating community health worker distribution networks.
Nigeria
Northern states including Kano, Sokoto, and Katsina execute door-to-door azithromycin campaigns achieving coverage rates facility-based models cannot match. The National Primary Health Care Development Agency manages centralized procurement contracts bypassing traditional pharmaceutical wholesalers. Abuja-based logistics divisions coordinate ministry of health distribution through community health worker networks.
Tanzania
Dodoma and Mwanza regions concentrate surgical trichiasis demand as elimination programs shift toward advanced case management. The Ministry of Health and Social Welfare directs procurement through community health program channels rather than clinic-based dispensing. Dar es Salaam anchors import and distribution infrastructure for WHO-prequalified antibiotic supplies.
India
Hyderabad and Ahmedabad manufacturing clusters produce generic azithromycin for export to African elimination programs under WHO prequalification standards. The Central Drugs Standard Control Organization regulates production facilities upgrading bioequivalence documentation to maintain tender eligibility. Indian suppliers capture contract volumes as stringent cold-chain verification protocols exclude non-compliant competitors.
Kenya
Turkana and West Pokot counties in northern Kenya sustain procurement for preventive chemotherapy campaigns in hyperendemic districts. The Division of Neglected Tropical Diseases coordinates national program integration with cross-border surveillance systems. Nairobi-based pharmaceutical importers manage supply chain logistics for ministry of health distribution networks.
Trachoma Treatment Market Competitive Environment
Listed leaders compete with private specialists across donation program access and generic manufacturing scale. The market structures around pharmaceutical incumbents with established WHO relationships and Indian generic producers with cost-optimized manufacturing. Three archetypes dominate: donation-program anchors, prequalified generic manufacturers, and surgical instrument specialists. Competitive moves concentrate on prequalification maintenance and community health network partnerships.
Within the donation-program tier, Pfizer Inc. and Novartis AG exemplify access-based positioning through integrated supply and surveillance infrastructure. Among generic manufacturers, Teva Pharmaceutical Industries Ltd. occupies a position representing scale-driven production for national tender processes. Merck & Co., Inc. sits within the alternative antibiotic segment serving targeted outbreak response needs.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Johnson & Johnson |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for azithromycin oral suspension govern procurement economics across endemic regions, compressing margin structures for manufacturers while amplifying the pricing leverage of WHO-prequalified suppliers with verified cold-chain capabilities. This lead-time discipline concentrates contract awards on Indian generic producers with integrated distribution networks into African ministry of health logistics divisions.
Pricing Analysis
Formulation-generation pricing gaps separate single-dose azithromycin oral suspension from multi-day tetracycline eye ointment regimens and next-generation point-of-care diagnostic-integrated therapy bundles. The dominant structure runs on volume-scaled contract pricing for national mass drug administration tenders, with differentiation driven by WHO prequalification status and verified bioequivalence documentation versus non-certified alternatives. Pricing pressure stems from donation program volumes displacing commercial procurement in high-burden countries. National health systems exhibit extreme price sensitivity, while surgical instrument procurement for trichiasis management commands premium tolerance due to specialist scarcity.
Supply Chain Analysis
India anchors azithromycin active pharmaceutical ingredient and finished formulation production for export to African elimination programs, with secondary concentration in Chinese raw material supply for macrolide precursors. Manufacturing draws from fermentation-based erythromycin derivatives and specialized coating technologies for tropical stability. Single-source vulnerability concentrates in WHO-prequalified facility certification, where non-compliant producers face exclusion from national tenders. Distribution runs through centralized ministry of health logistics divisions in Ethiopia, Nigeria, and Tanzania, displacing traditional pharmaceutical wholesale channels with direct-to-community health worker models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trachoma treatment sits in early-cycle expansion as national elimination programs accelerate procurement shifts from preventive mass administration toward precision-targeted case management and surgical backlog clearance.
For Market Incumbents: Fortify WHO prequalification status through upgraded bioequivalence documentation and cold-chain verification protocols to defend against emerging Indian generic competitors with enhanced production facilities. Deepen backward integration into azithromycin active pharmaceutical ingredient production to secure margin position against raw material cost volatility and regulatory scrutiny of Chinese precursor supply chains. For New Entrants and Emerging Players: WHO prequalification fast-track pathways for azithromycin oral suspension formulations offer the most penetrable entry point, targeting procurement contracts in Tanzania and Kenya where national programs are expanding beyond donor-dependent supply. Surgical instrument specialization for tarsal rotation procedures in Ethiopia's accelerated elimination timeline presents a secondary white-space opportunity with premium pricing potential and limited incumbent saturation. For Investors and Strategic Acquirers: Long-term, this sits as a public-health infrastructure play because elimination program sustainability depends on integrated surveillance and diagnostic platforms beyond drug supply alone. Acquisition targets should concentrate on community health network operators with established ministry relationships and digital health integration capabilities. The signal to watch is national trachoma-free certification timelines advancing or delaying, which will shift procurement mix from preventive chemotherapy toward reactive case management and reshape contract volume profiles.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks access to Ethiopian and Nigerian national tender processes for azithromycin suppliers. |
| Community Health Network Partnership | Establishes direct-to-village distribution channels bypassing traditional pharmaceutical wholesalers. |
| Surgical Capacity Buildout | Addresses trichiasis backlog clearance demands in Ethiopia's Amhara and Oromia regions. |
| Point-of-Care Diagnostic Integration | Enables precision targeting of antibiotic distribution reducing waste and resistance selection pressure. |
| Cold-Chain Infrastructure Investment | Secures product stability verification required for WHO mass drug administration contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical procurement officers at African ministry of health logistics divisions, community health program coordinators, and ophthalmic surgical specialists; and secondary validation through WHO prequalification databases, national trachoma elimination program reports, and Indian pharmaceutical export customs records. Bottom-up demand modeling for azithromycin procurement volumes triangulated against top-down national program coverage targets across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, therapy area, delivery mode, and end user, with geographic regulatory clusters distinguishing WHO-prequalified from nationally approved supply channels. CAGRs were derived from trend extrapolation of procurement contract volumes and surgical procedure backlogs, incorporating inputs from Chlamydia trachomatis prevalence mapping data and national elimination timeline commitments.
Decision-makers should treat outputs as directional under assumptions of sustained WHO SAFE strategy implementation and stable azithromycin donation program volumes; material deviation in antimicrobial resistance patterns or donor funding priorities would warrant model refresh. Recalibration cycles align with material shifts in national elimination certification timelines and corresponding procurement mix transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Vision Care Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Europe Dry Eye Syndrome Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Ocular Inserts Market