
 Burkitt Lymphoma Treatment Market | 2026-2036
Burkitt Lymphoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Burkitt Lymphoma Treatment Market Insights
Multi-source procurement of biologic active pharmaceutical ingredients is expanding as manufacturers diversify away from single-supplier dependencies for rituximab and cytotoxic compounds. Genentech leverages its established mammalian cell culture infrastructure to sustain bulk monoclonal antibody output for combination protocols. Novartis anchors its position through integrated supply chains spanning chemical synthesis and fill-finish capacity for cytotoxic agents. Bristol-Myers Squibb differentiates via controlled distribution networks that secure cold-chain integrity for temperature-sensitive biologics.
Burkitt lymphoma treatment encompasses intensive multi-agent chemotherapy regimens, immunotherapy with CD20-directed monoclonal antibodies, and emerging targeted interventions against MYC-driven oncogenic pathways, typically administered in hospitalized settings due to tumor lysis syndrome risk and the need for supportive care infrastructure. Chemotherapy retains the largest patient volume share among product types, while immunotherapy captures expanding utilization as front-line combination partner. Intravenous administration dominates the route landscape given the potency requirements and bioavailability constraints of high-dose protocols, though subcutaneous formulations are gaining traction in maintenance phases.
FDA orphan drug designations and EMA pediatric investigation plans shape development priorities and exclusivity timelines for sponsors targeting this rare lymphoma subset. WHO essential medicines list inclusion for core cytotoxic agents ensures procurement visibility in low-resource settings, while national pharmaceutical regulators in emerging markets calibrate import and pricing frameworks against these benchmarks. Stakeholders must monitor evolving biosimilar entry timelines for rituximab and their impact on reference pricing across public tenders.
Market Dynamics
FDA and EMA accelerated approval pathways for rare pediatric cancers are compressing clinical trial timelines while intensifying competition among sponsors to secure orphan drug exclusivity for MYC-targeted therapies.
Growth Catalysts
- Orphan drug incentives:FDA's seven-year market exclusivity and tax credits for pediatric rare disease trials are accelerating sponsor investment in Burkitt lymphoma drug development pipelines.
- Referral network density:United States academic medical centers maintain the highest concentration of aggressive lymphoma specialists, driving protocol standardization and rapid adoption of intensified regimens.
- CD20-directed monoclonal antibodies:Front-line integration of rituximab with high-dose chemotherapy has expanded the addressable patient pool by improving complete response durability in adult and pediatric populations.
Market Restraints
- Plasma-derived raw material volatility:Mammalian cell culture media and fetal bovine serum supply disruptions from South American sourcing regions create batch-to-batch variability in monoclonal antibody production yields.
- Tumor lysis syndrome infrastructure:Mandatory inpatient administration with dedicated ICU-level monitoring limits treatment scalability in regions lacking tertiary hematology-oncology capacity.
- Rituximab biosimilar entry timelines:Reference pricing erosion in European public tenders is compressing margin structures for originator manufacturers before patent cliff maturation in the United States.
Strategic Opportunities
- Sub-Saharan Africa endemic variant protocols:WHO essential medicines list inclusion for cyclophosphamide, vincristine, and prednisone enables procurement standardization in high-incidence, low-resource settings.
- Subcutaneous rituximab formulations:Reduced infusion center burden and ambulatory administration potential are reshaping maintenance phase economics in German and French outpatient networks.
- CAR-T convergence with chemotherapy backbones:CD19-directed cellular therapy integration into salvage regimens for relapsed disease is opening addressable segments beyond front-line induction.
Industry Challenges
- Pediatric hematology-oncology workforce scarcity:Fellowship pipeline constraints in the United States and Western Europe limit site activation for multi-center international trials.
- Cold-chain integrity at last-mile:Temperature excursions during rituximab distribution to satellite infusion centers in rural India and Brazil compromise product stability and dosing reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burkitt Lymphoma Treatment Market |
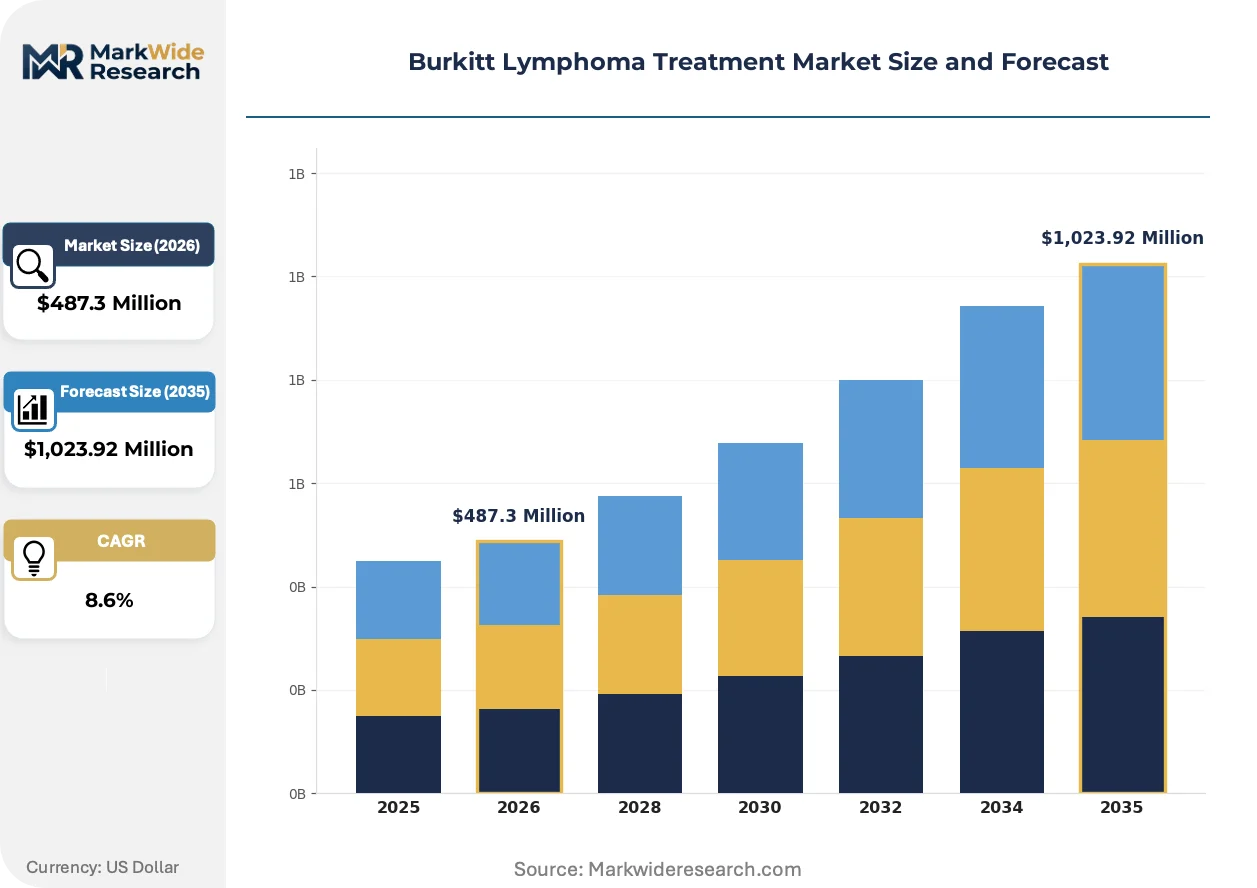
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Therapy Area: Hematology, Oncology, Cellular Therapy, Monoclonal Antibodies Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Research Institutions, Home Care |
| Companies Covered | Genentech, F. Hoffmann-La Roche Ltd, Novartis AG, Gilead Sciences, Biogen, Cothera Bioscience, Immunitas Therapeutics, Vironexis Biotherapeutics, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burkitt Lymphoma Treatment Market Trends and Innovations
Biomarker-driven patient stratification is fragmenting the homogeneous chemotherapy paradigm while digital trial infrastructure compresses enrollment timelines for rare lymphoma subsets.
Next-generation sequencing panels detecting MYC rearrangement partners are absorbing clinical decision-making authority from morphology-based diagnostic workflows. Academic medical centers in the United States and United Kingdom are adopting these platforms at accelerating cadence. The technology is absorbing budget allocation from conventional immunohistochemistry testing menus.
EMA's pediatric investigation plan requirements are mandating age-appropriate formulation development before adult indication approval. Sponsors must now commit to liquid or dispersible tablet formats for cytotoxic agents used in pediatric Burkitt lymphoma. European trial networks are responding by embedding pharmacy compounding partnerships earlier in protocol design.
Consolidated buying by United States hospital system formularies is displacing individual physician preference in regimen selection. Integrated delivery networks in Texas and California are standardizing on specific rituximab-chemotherapy combinations across all affiliated sites. This concentration is most visible in Medicare Advantage-covered populations where episode-based reimbursement incentivizes protocol uniformity.
Burkitt Lymphoma Treatment Market Segmentation
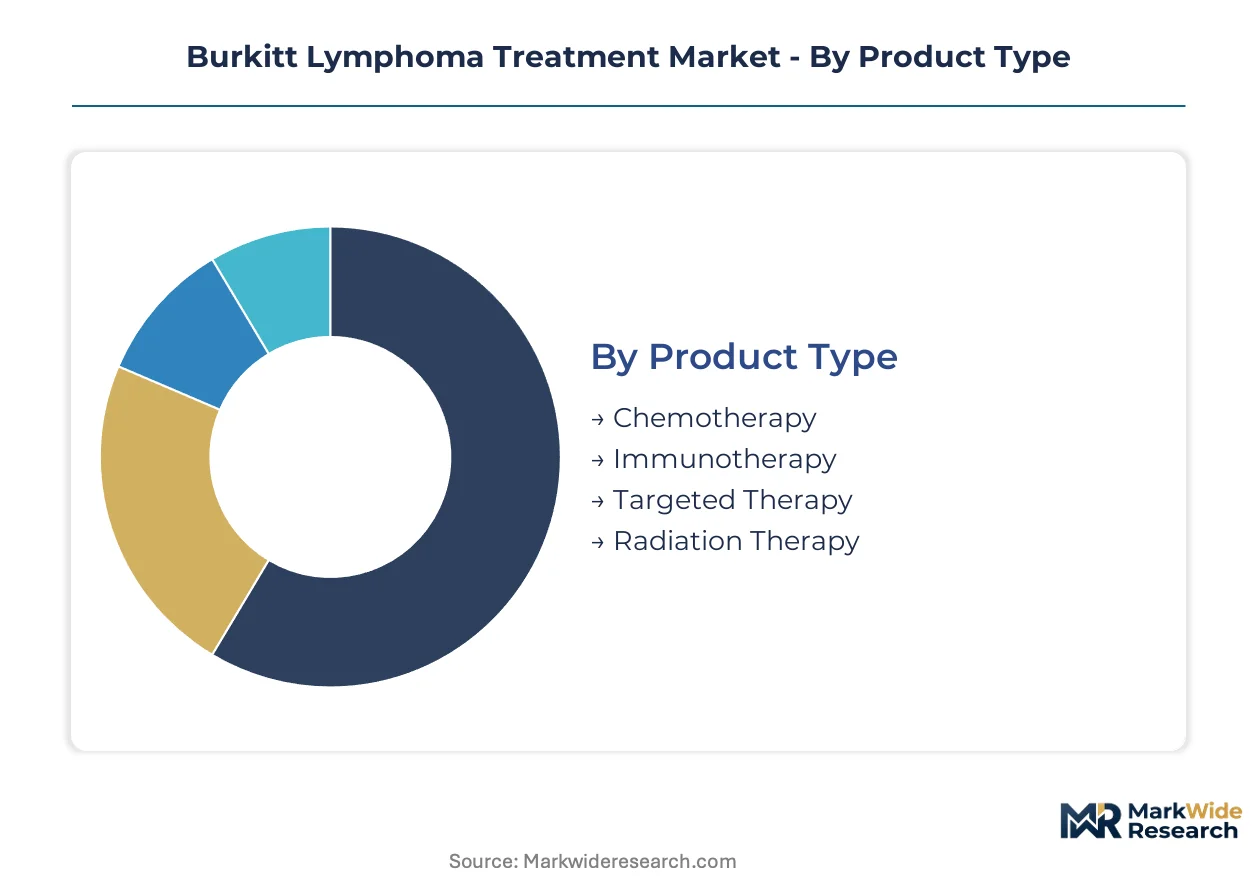
Burkitt lymphoma treatment protocols demand precise alignment between product characteristics and care setting capabilities. Segmentation reveals how regimen intensity, administration infrastructure, and patient acuity intersect to determine commercial viability across delivery channels.
Product Type:
Standalone cytotoxic agents dominate front-line protocols, while immunotherapy and targeted modalities increasingly embed within combination backbones rather than deploy as monotherapy.
- Chemotherapy:Intensive multi-agent regimens combining cyclophosphamide, vincristine, doxorubicin, and high-dose methotrexate constitute the foundational treatment paradigm. Demand concentrates in United States academic medical centers where referral networks for aggressive non-Hodgkin lymphoma maintain the highest treatment density and protocol standardization.
- Immunotherapy:CD20-directed monoclonal antibodies, principally rituximab, integrate with chemotherapy backbones to improve complete response durability. United States hospital-based oncology departments represent the primary adoption segment, driven by FDA accelerated approval pathways that compress commercialization timelines for rare pediatric cancers.
- Targeted Therapy:Emerging MYC pathway inhibitors and BCL-2 antagonists for relapsed or refractory disease.
- Radiation Therapy:Adjunctive localized treatment for central nervous system prophylaxis or residual disease sites.
Volume placements concentrate in chemotherapy; the faster expansion belongs to immunotherapy.
Therapy Area:
Cost tier stratification separates established cytotoxic infrastructure from capital-intensive cellular manufacturing platforms requiring dedicated cleanroom facilities.
- Hematology:Specialized units managing tumor lysis syndrome risk and cytopenia complications anchor regimen administration. Demand concentrates in tertiary referral centers across Germany, France, and the United Kingdom where EMA pediatric investigation plans mandate age-appropriate formulation development.
- Oncology:General medical oncology departments handle stabilized patients in maintenance phases. United States integrated delivery networks in Texas and California are standardizing specific rituximab-chemotherapy combinations across all affiliated sites.
- Cellular Therapy:CD19-directed CAR-T platforms for salvage regimens in relapsed disease.
- Monoclonal Antibodies:Engineered biologics requiring cold-chain distribution integrity.
Patient volume concentrates in hematology; steepest expansion trajectory belongs to cellular therapy.
Administration Route:
Application context determines route selection: inpatient tumor lysis syndrome monitoring favors intravenous delivery, while maintenance phase economics drive subcutaneous adoption.
- Intravenous:High-dose chemotherapy and monoclonal antibody infusions administered in hospitalized settings due to potency requirements and bioavailability constraints. Demand concentrates in United States academic medical centers where ICU-level monitoring infrastructure supports mandatory inpatient administration.
- Subcutaneous:Reduced infusion center burden and ambulatory administration potential are reshaping maintenance phase economics in German and French outpatient networks.
- Oral:Limited utility given poor bioavailability of core cytotoxic agents at required doses.
- Intramuscular:Minimal role in current treatment paradigms for this indication.
Volume placements concentrate in intravenous; the faster expansion belongs to subcutaneous.
End User:
Customer type segmentation reflects the divergence between intensive induction requiring tertiary infrastructure and maintenance phases suitable for decentralized delivery.
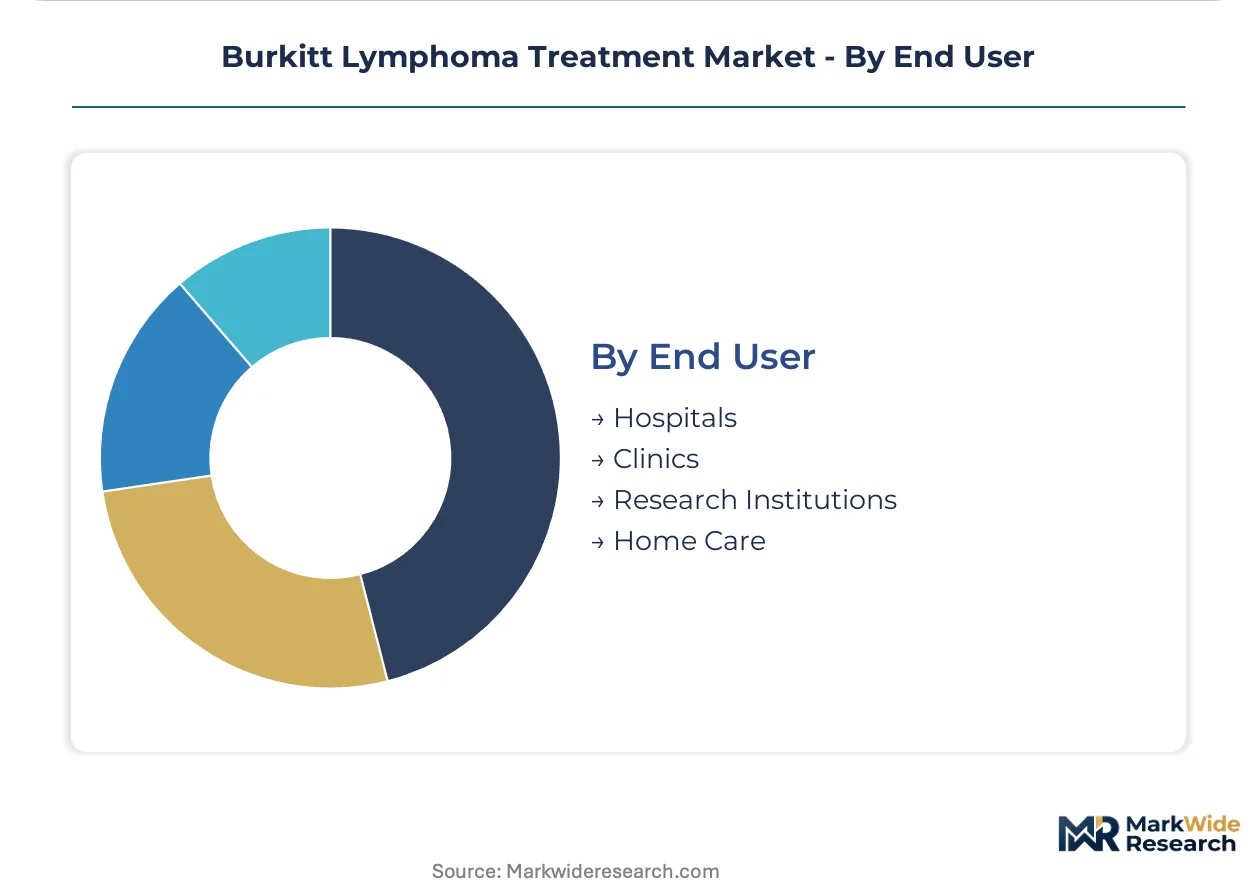
- Hospitals:Hospital-based oncology departments represent the primary adoption segment for intensive combination regimens, capturing the complete patient journey from diagnosis through induction. United States referral networks maintain the highest treatment density for aggressive lymphoma protocols.
- Clinics:Community oncology practices handle stabilized patients in maintenance or surveillance phases. Subcutaneous rituximab formulations are gaining traction in these settings across Western European outpatient networks.
- Research Institutions:Academic medical centers hosting clinical trials for MYC-targeted therapies and CAR-T convergence protocols.
- Home Care:Limited penetration due to tumor lysis syndrome risk and requirement for immediate intervention capability.
Patient volume concentrates in hospitals; the fastest share gain belongs to clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South American fetal bovine serum collection regions anchor monoclonal antibody manufacturing supply chains for Burkitt lymphoma biologics. Hospital-based oncology capacity concentrates in North American and Western European tertiary centers. Emerging markets in Sub-Saharan Africa face infrastructure constraints for tumor lysis syndrome management.
United States
Academic medical centers in Boston and Houston maintain the highest density of aggressive lymphoma specialists driving protocol standardization. FDA orphan drug incentives and seven-year market exclusivity provisions accelerate pediatric rare disease trial investment. Referral networks across the Texas Medical Center and Memorial Sloan Kettering Cancer Center anchor rapid adoption of intensified rituximab-chemotherapy combinations.
Germany
Integrated oncology networks in Bavaria and North Rhine-Westphalia standardize subcutaneous rituximab maintenance protocols across outpatient settings. EMA pediatric investigation plans mandate age-appropriate liquid formulations before adult indication approval. The Heidelberg and Munich hospital clusters concentrate CAR-T salvage therapy capacity for relapsed disease segments.
France
Public hospital procurement through regional health agencies centralizes cyclophosphamide and vincristine purchasing for pediatric protocols. ANSM oversight of clinical trial authorization compresses multi-center activation timelines for MYC-targeted therapies. The Paris-Saclay and Lyon hospital networks anchor hematology-oncology workforce training pipelines.
United Kingdom
NHS England specialized commissioning for rare cancers concentrates Burkitt lymphoma treatment in designated tertiary centers. NICE technology appraisals shape rituximab biosimilar adoption curves in maintenance settings. The Manchester and Birmingham academic hospital clusters host next-generation sequencing diagnostic platforms fragmenting morphology-based workflows.
Brazil
ANVISA import licensing frameworks for temperature-sensitive biologics create cold-chain integrity challenges at last-mile distribution to satellite centers. SUS reimbursement for essential cytotoxic agents enables procurement visibility in high-incidence pediatric populations. The São Paulo and Rio de Janeiro metropolitan hospital networks anchor the limited tertiary hematology-oncology capacity for tumor lysis syndrome management.
Burkitt Lymphoma Treatment Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and distribution reach in the Burkitt lymphoma treatment market. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with mammalian cell culture infrastructure, mid-cap cytotoxic specialists with chemical synthesis capabilities, and emerging biotech developers targeting MYC-driven pathways. Dominant competitive moves include backward integration into plasma-derived raw material sourcing and strategic partnerships with academic medical centers for trial site activation.
Among established biologics manufacturers, Genentech and Novartis AG occupy positions anchored by bulk monoclonal antibody output and integrated supply chains spanning chemical synthesis to fill-finish capacity. Bristol-Myers Squibb Company exemplifies the controlled distribution archetype securing cold-chain integrity for temperature-sensitive biologics. These three entities represent contrasting strategic postures within the competitive set: manufacturing scale dominance, supply chain verticality, and distribution network specialization.
| Leading Market Players |
|---|
| Genentech |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Gilead Sciences |
| Biogen |
| Cothera Bioscience |
| Immunitas Therapeutics |
| Vironexis Biotherapeutics |
| Bristol-Myers Squibb Company |
| Others |
Pricing and Supply Chain Analysis
Subcutaneous rituximab formulation transitions are simultaneously compressing per-dose administration costs and redistributing manufacturing scale toward fill-finish facilities with lyophilization capacity. This production-method shift concentrates supply leverage among sponsors with captive sterile injectable infrastructure while eroding margins for originators facing biosimilar substitution in European tenders.
Pricing Analysis
Service-bundling separates cold-chain logistics and ICU monitoring from drug acquisition costs in hospital procurement negotiations. Contract-based long-term offtake dominates, with price differentiation hinging on originator brand premium versus biosimilar tier and volume scale commitments from integrated delivery networks. Cost compression in the biosimilar tier is intensifying because ANSM and EMA reference pricing mechanisms accelerate substitution. Community oncology practices exhibit highest price sensitivity; academic medical centers with orphan drug exclusivity access show lowest.
Supply Chain Analysis
GMP certification and FDA/EMA qualification gating for mammalian cell culture facilities constrain active supplier pools to Switzerland, Germany, and the United States for commercial rituximab bulk. Fetal bovine serum from South American collection regions and single-use bioreactor bags constitute critical input dependencies. Single-source vulnerability runs through South American serum collection zones exposed to foot-and-mouth disease quarantine protocols. Distribution runs through controlled third-party logistics networks with validated cold-chain monitoring to hospital-based infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA pediatric investigation plan mandates and FDA orphan drug exclusivity provisions erect compliance moats that reward sponsors with pre-committed age-appropriate formulation development capabilities.
For Market Incumbents: Deploy backward integration into plasma-derived raw material sourcing to secure batch-to-batch yield consistency against South American supply volatility. Anchor capacity addition in German and Swiss fill-finish clusters to capture subcutaneous formulation demand from French and German outpatient networks. Rituximab biosimilar entry timelines in United States markets constitute the primary margin threat requiring defensive positioning. For New Entrants and Emerging Players: Enter via MYC-targeted therapy development for relapsed/refractory segments where chemotherapy backbones fail and CAR-T manufacturing capacity remains scarce. Sub-Saharan Africa endemic variant protocols offer the most penetrable geography given WHO essential medicines list procurement standardization. Partner with academic medical centers in Texas or California for trial site activation leveraging existing referral network density. For Investors and Strategic Acquirers: Re-rating potential sits with cellular therapy platform developers given CD19-directed CAR-T convergence with chemotherapy backbones opening salvage regimen addressable segments. Long-term viability centers on sponsors with integrated manufacturing scale spanning chemical synthesis through sterile injectable fill-finish. Watch EMA pediatric investigation plan enforcement stringency as inflection indicator for formulation development cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Compresses enrollment timelines for rare lymphoma subsets via digital infrastructure deployment. |
| Regulatory Approval Pathway | EMA pediatric investigation plans mandate age-appropriate formulations before adult indication approval. |
| Manufacturing Scale-Up | Lyon and Heidelberg hospital clusters concentrate CAR-T salvage therapy capacity for relapsed disease. |
| Pipeline Diversification | MYC pathway inhibitors and BCL-2 antagonists target relapsed segments beyond front-line induction. |
| Licensing Agreement | Pharmacy compounding partnerships embed earlier in European protocol design for liquid formulations. |
Research Methodology
Multi-period observation of FDA orphan drug designation timelines and EMA pediatric investigation plan submission patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down revenue reconciliation provided triangulation across the analysis window.
Input-output matrices mapped treatment line, dosage form, administration route, and patient population segments against regional regulatory clusters throughout the forecast period. CAGRs derived from log-linear trend fitting across modeled segments. Forecast inputs incorporated rituximab biosimilar entry trajectory assumptions and referral network density indices for aggressive lymphoma specialists.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden South American fetal bovine serum supply disruption or accelerated United States biosimilar approval pathways. A model refresh is warranted upon material change in EMA pediatric investigation plan enforcement stringency or FDA orphan drug exclusivity grant rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Patient Blood Management Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Lymphoma Treatment Market
Hematology
Global Immunohematology Market
Hematology
Alpha Thalassemia Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Hemoglobin Analyzer Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Hematologic Malignancies Market