
 Ophthalmology Diagnostics and Surgical Devices Market | 2026-2036
Ophthalmology Diagnostics and Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmology Diagnostics and Surgical Devices Market Analysis
Aftermarket service revenue for diagnostic equipment is reconfiguring margin capture across the ophthalmology value chain. Alcon Inc. leverages its surgical instrument installed base to sustain recurring consumable revenue streams. Carl Zeiss Meditec AG anchors premium positioning in optical imaging through proprietary software-integrated platforms. Johnson & Johnson Vision competes in vision correction applications with differentiated laser system architectures.
Ophthalmology diagnostics and surgical devices encompass precision instruments engineered to sub-micron tolerances for ocular tissue manipulation, imaging, and therapeutic intervention, with optical coherence tomography systems achieving axial resolutions below 5 micrometers to enable cross-sectional retinal visualization. These technologies serve the clinical imperative of early disease detection and minimally invasive surgical restoration of visual function. Diagnostic equipment commands the largest revenue pool due to replacement cycles tied to software obsolescence and imaging protocol advances, while laser systems within the technology dimension represent the fastest-expanding segment driven by femtosecond platform adoption in cataract and refractive procedures. Surgical instruments maintain mature, stable demand profiles anchored by disposable phacoemulsification handpiece consumption patterns.
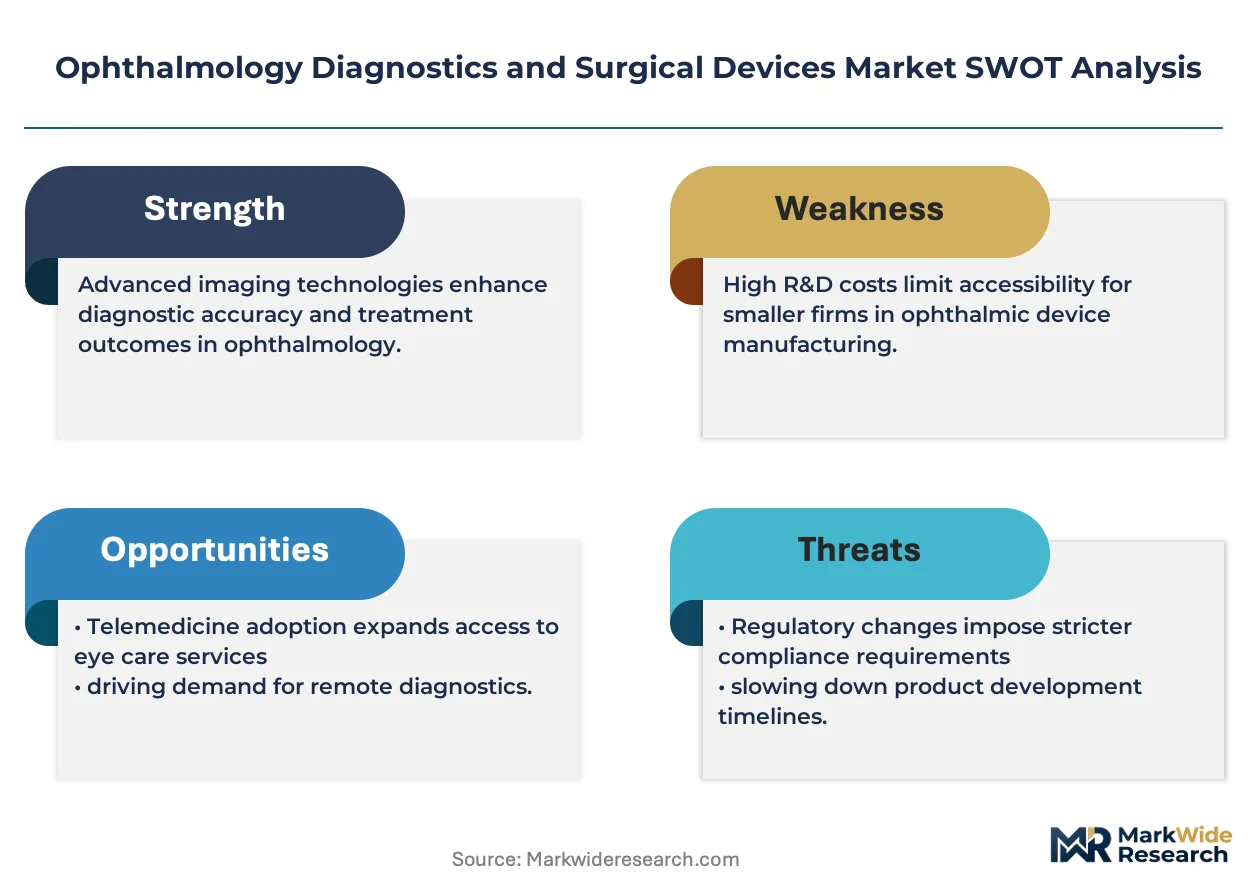
FDA premarket notification and EU MDR conformity assessment frameworks impose stringent biocompatibility and clinical validation requirements on intraocular devices, directly extending product development timelines and consolidating market access around well-capitalized manufacturers with established quality management systems. The EU AI Act introduces additional scrutiny for diagnostic algorithms embedded in imaging platforms, creating compliance differentiation between rule-based and machine-learning-enabled software. Stakeholders must monitor regulatory divergence between FDA's software-as-medical-device guidance and EU harmonized standards to anticipate certification cost structures and competitive moat dynamics.
Market Dynamics
Femtosecond laser platforms are compressing procedural timelines in cataract surgery while simultaneously elevating capital equipment requirements for outpatient surgical centers, fundamentally restructuring competitive economics across the ophthalmology device value chain.
Growth Catalysts
- EU MDR Conformity Assessment:The EU MDR's enhanced clinical evidence requirements for Class III intraocular devices are accelerating consolidation among manufacturers with established quality management systems, filtering marginal competitors from premium segments.
- Outpatient Surgical Migration:Ambulatory surgical centers in the United States are capturing cataract procedure volume from hospital-based settings, driving demand for compact, workflow-integrated diagnostic and laser platforms.
- Optical Coherence Tomography Software Obsolescence:Replacement cycles tied to imaging protocol advances and AI-enabled diagnostic algorithms are sustaining recurring revenue streams for integrated hardware-software platforms.
Market Restraints
- EU AI Act Algorithm Scrutiny:Machine-learning-enabled diagnostic algorithms embedded in OCT platforms face additional conformity assessment layers, extending certification timelines and compliance costs for imaging system manufacturers.
- German Optical Component Concentration:Precision optics manufacturing for diagnostic systems concentrates in Baden-Württemberg and Bavaria, creating geographic supply vulnerability for non-European device assemblers.
- Femtosecond Laser Capex Thresholds:Platform acquisition costs exceeding two million dollars restrict addressable market penetration to well-capitalized surgical networks, excluding independent ophthalmology practices.
Strategic Opportunities
- India Tier-II City Penetration:Diagnostic screening demand in cities such as Jaipur, Lucknow, and Indore remains underserved by premium OCT distribution networks, creating whitespace for mid-tier imaging platform deployment.
- Teleophthalmology Workflow Integration:Remote diagnostic image interpretation protocols are enabling hub-and-spoke service models that extend specialist reach into rural catchment areas without capital-intensive equipment replication.
- Japan PMDA Priority Review Pathways:Japan's Pharmaceuticals and Medical Devices Agency offers accelerated approval for AI-diagnostic software, incentivizing algorithm development investment for retinal disease screening applications.
Industry Challenges
- Biomedical Optics Talent Scarcity:The intersection of optical engineering and clinical ophthalmology requires specialized training pipelines that academic institutions have not scaled to match device industry demand.
- FDA 510(k) Predicate Device Erosion:Substantial equivalence pathways for incremental device iterations are narrowing as FDA demands more rigorous clinical validation, extending premarket notification timelines.
- Legacy EMR Integration Friction:Proprietary data formats from established imaging platforms resist interoperability with third-party electronic medical record systems, complicating hospital IT procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmology Diagnostics and Surgical Devices Market |
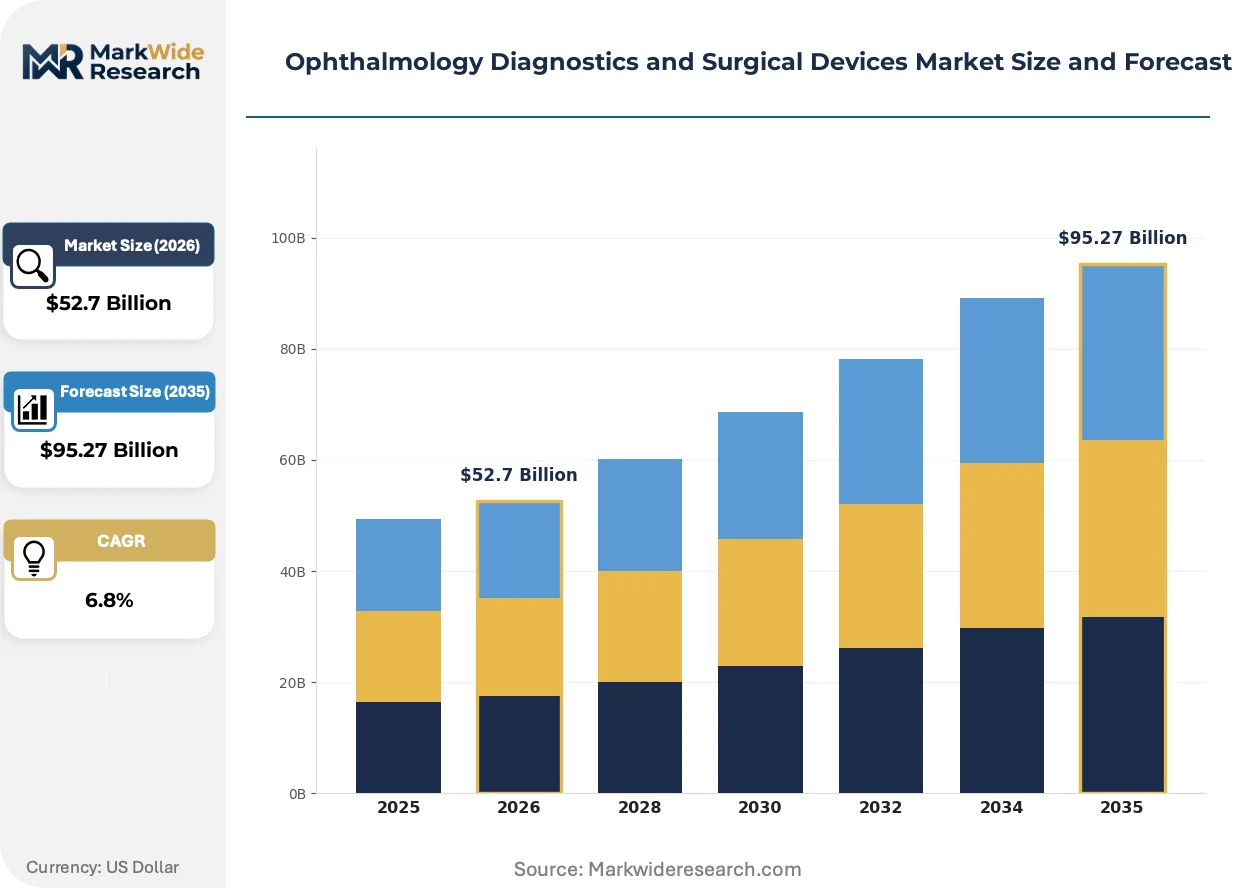
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Therapeutic Devices, Imaging Solutions Technology: Laser Systems, Optical Coherence Tomography, Ultrasound Devices, Anterior Segment Analyzers End User: Hospitals, Eye Clinics, Research Institutions, Outpatient Facilities Application: Cataract Surgery, Retinal Surgery, Glaucoma Treatment, Vision Correction |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, Bausch + Lomb, Johnson & Johnson Vision, Topcon Corporation, NIDEK Co., Ltd., EssilorLuxottica, Glaukos Corporation, Hoya Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmology Diagnostics and Surgical Devices Market Emerging Trajectories
Convergence between diagnostic imaging and surgical planning software is dissolving traditional hardware boundaries while regulatory frameworks race to classify algorithmic decision-support tools.
Extended-depth optical coherence tomography systems achieving choroidal visualization beyond the retinal pigment epithelium are rendering obsolete conventional spectral-domain platforms limited to posterior segment imaging. Outpatient retina clinics in Germany and Japan are prioritizing these systems for age-related macular degeneration monitoring. The technology is rendering obsolete standalone fundus photography as a first-line diagnostic modality in premium clinical settings.
The EU AI Act's risk-based classification framework for medical device software is imposing conformity assessment obligations on diagnostic algorithms previously regulated as accessories. Manufacturers must now document algorithm training datasets and performance validation across demographic subgroups. OCT platforms with embedded machine-learning segmentation tools face the most significant compliance recertification burden in European markets.
Subscription-based service contracts for diagnostic equipment are displacing traditional capital purchase models in United States ambulatory surgical centers. Device manufacturers are unbundling hardware, software, and maintenance into recurring revenue structures that align vendor incentives with equipment uptime performance. This shift is most visible in California and Texas surgical networks where private equity consolidation has standardized procurement practices.
Ophthalmology Diagnostics and Surgical Devices Market Segmentation
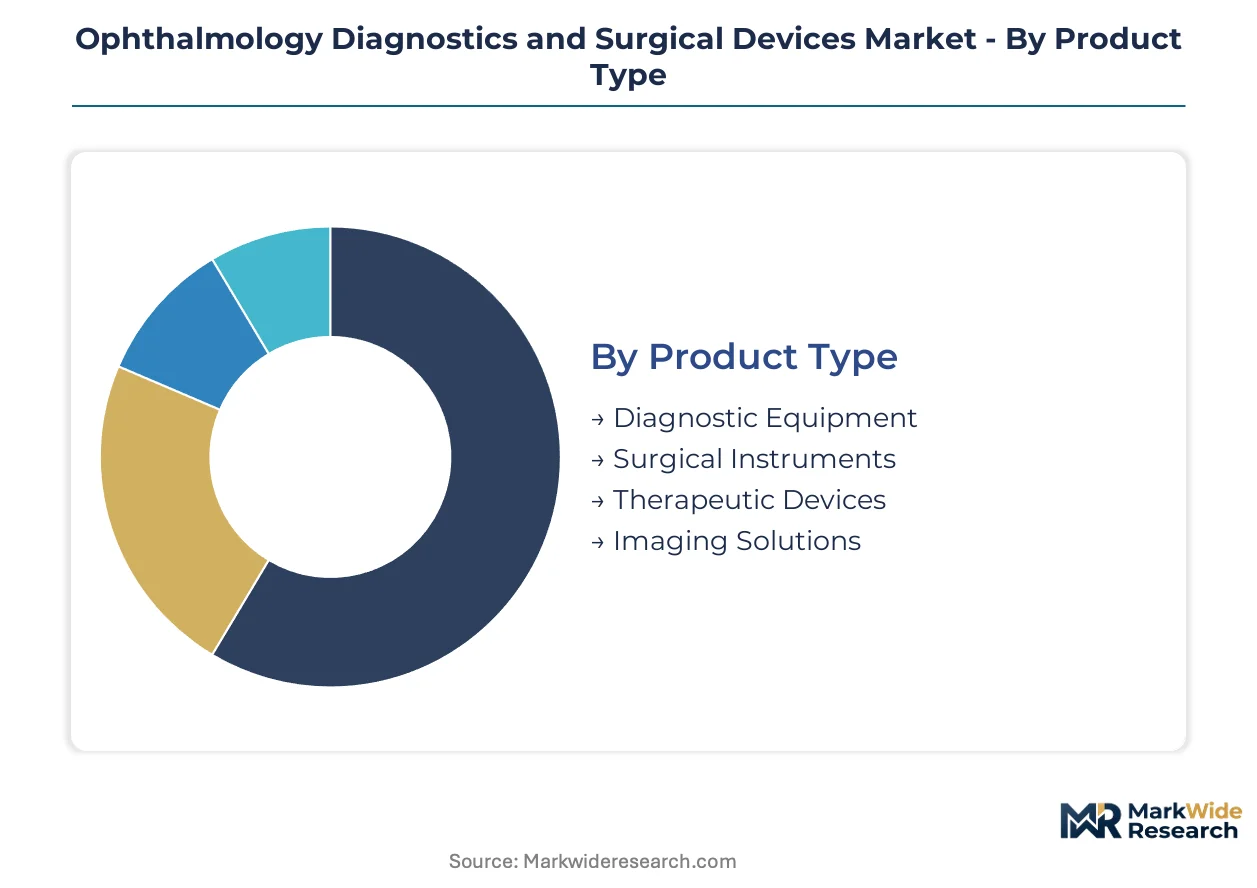
Segmentation in ophthalmology devices reveals divergent replacement cycles and margin structures. Diagnostic platforms turn over on software obsolescence timelines while surgical instruments follow consumable consumption patterns. Understanding these rhythms separates hardware-heavy from recurring-revenue business models.
Product Type:
Replacement velocity varies dramatically across this category, with capital equipment cycling every five to seven years against single-use surgical consumables turning in weeks.
- Diagnostic Equipment:Optical coherence tomography systems and fundus cameras integrate proprietary image processing software that mandates hardware refresh when protocol standards advance. German outpatient retina clinics in Baden-Württemberg prioritize these platforms for age-related macular degeneration monitoring workflows.
- Surgical Instruments:Phacoemulsification handpieces, vitrectomy probes, and microsurgical forceps achieve sub-micron tolerances for ocular tissue manipulation. Demand concentrates in United States ambulatory surgical centers where cataract procedure volume migration from hospital settings drives disposable consumption.
- Therapeutic Devices:Intraocular lenses and sustained-release drug delivery implants face EU MDR Class III clinical evidence requirements that extend certification timelines.
- Imaging Solutions:Extended-depth OCT systems achieving choroidal visualization beyond the retinal pigment epithelium render conventional spectral-domain platforms obsolete in premium clinical settings.
Diagnostic Equipment anchors the volume base while Imaging Solutions gains share at the steepest rate.
Technology:
Cost tier stratification separates million-dollar laser platforms from sub-hundred-thousand-dollar ultrasound systems, concentrating procurement decisions in well-capitalized surgical networks.
- Laser Systems:Femtosecond platforms for cataract and refractive surgery compress procedural timelines while elevating capital requirements. United States private equity-consolidated surgical networks in California and Texas standardize these acquisitions through subscription service contracts rather than capital purchase.
- Optical Coherence Tomography:Spectral-domain and swept-source architectures achieve axial resolutions below five micrometers for cross-sectional retinal visualization. Carl Zeiss Meditec anchors production in Germany where precision optics manufacturing concentrates supply.
- Ultrasound Devices:A-scan and B-scan systems serve biometric measurement and posterior segment visualization in resource-constrained settings.
- Anterior Segment Analyzers:Corneal topography and tomography systems support refractive surgery planning and contact lens fitting workflows.
Laser Systems command the premium tier while Optical Coherence Tomography expands most quickly through software-integrated platform adoption.
End User:
Customer type determines procurement sophistication, with hospital systems leveraging integrated IT infrastructure against independent clinics prioritizing workflow compactness.
- Hospitals:Academic medical centers demand interoperability with enterprise electronic medical record systems, creating friction with proprietary imaging data formats from established vendors.
- Eye Clinics:Specialized retina and refractive practices prioritize compact diagnostic platforms that integrate surgical planning software. Japan's PMDA priority review pathways for AI-diagnostic software incentivize algorithm deployment in these settings.
- Research Institutions:Clinical trial sites and university laboratories drive early adoption of extended-depth imaging and machine-learning segmentation tools.
- Outpatient Facilities:Ambulatory surgical centers in the United States capture cataract volume migration through workflow-integrated laser and diagnostic platforms.
Eye Clinics anchor the volume base while Outpatient Facilities climb the fastest as procedure economics shift toward ambulatory settings.
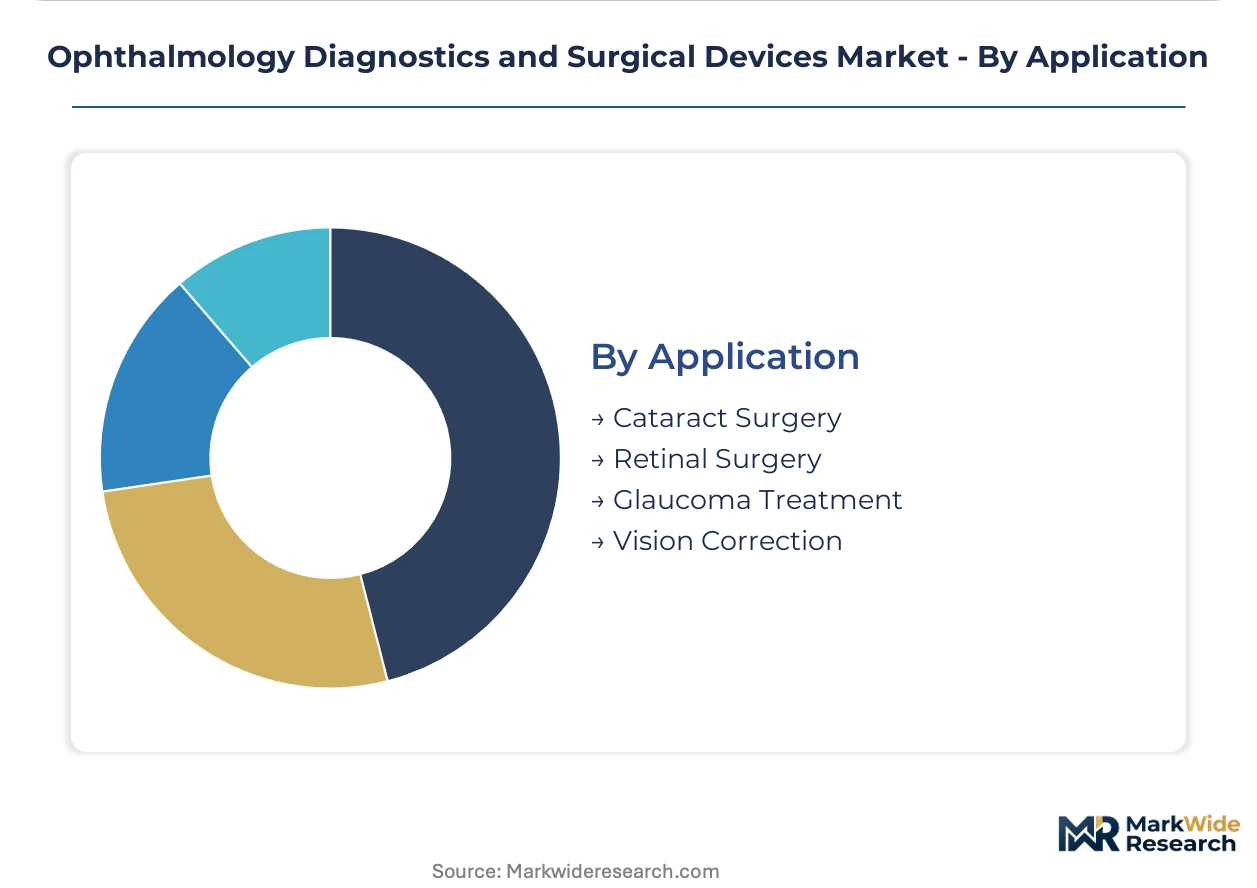
Application:
Procedure volume concentration and reimbursement dynamics separate mature cataract markets from emerging vision correction segments.
- Cataract Surgery:Femtosecond laser platform adoption elevates capital equipment requirements while compressing phacoemulsification handpiece utilization per procedure. EU MDR conformity assessment for intraocular lenses filters marginal competitors from premium segments.
- Retinal Surgery:Vitrectomy systems and laser photocoagulation devices serve diabetic retinopathy and macular hole repair. Demand concentrates in Germany and Japan where aging demographics expand treatable patient populations.
- Glaucoma Treatment:Minimally invasive glaucoma surgery devices and sustained-release drug delivery systems compete against pharmaceutical management protocols.
- Vision Correction:Excimer and femtosecond laser platforms for LASIK and SMILE procedures face cyclical demand tied to consumer discretionary spending patterns.
Cataract Surgery anchors the volume base while Vision Correction shows the steepest expansion trajectory as refractive procedure economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes ophthalmology diagnostics through integrated outpatient retina networks, while the United States absorbs femtosecond laser platforms via private equity-consolidated surgical chains. Japan and India diverge on AI-diagnostic deployment speed, with PMDA priority review accelerating algorithm commercialization against India's tier-II city infrastructure gaps.
United States
Ambulatory surgical centers in California and Texas capture cataract procedure volume migration from hospital settings. FDA 510(k) premarket notification pathways for intraocular devices demand rigorous clinical validation. Private equity-consolidated surgical networks standardize procurement through subscription service contracts rather than capital purchase.
Germany
Outpatient retina clinics in Baden-Württemberg prioritize extended-depth OCT systems for age-related macular degeneration monitoring. EU MDR conformity assessment for Class III intraocular lenses filters marginal competitors from premium segments. Carl Zeiss Meditec anchors precision optics manufacturing in Bavaria and Baden-Württemberg.
Japan
Aging demographics expand treatable patient populations for retinal surgery and glaucoma interventions. PMDA priority review pathways accelerate approval timelines for AI-diagnostic software embedded in imaging platforms. Tokyo and Osaka metropolitan areas concentrate specialized retina and refractive practices deploying algorithm-enabled screening.
India
Diagnostic screening demand in Jaipur, Lucknow, and Indore remains underserved by premium OCT distribution networks. CDSCO medical device registration requirements impose quality management system compliance on imported imaging platforms. Maharashtra and Karnataka host domestic device assembly operations serving price-sensitive clinic segments.
China
Refractive surgery volume growth drives femtosecond laser platform demand in tier-one hospital ophthalmology departments. NMPA medical device registration pathways require clinical trial data for innovative intraocular lens designs. Yangtze River Delta manufacturing clusters supply optical components to domestic and export device assemblers.
Ophthalmology Diagnostics and Surgical Devices Market Vendor Landscape
Capability concentration sits with integrated hardware-software platforms; scale advantage sits with consumable-anchored surgical instrument portfolios. The market structures around three tiers: premium imaging specialists, diversified surgical device conglomerates, and regional mid-tier platform assemblers. Two dominant competitive moves reshape positioning: M&A to capture AI-diagnostic algorithm pipelines, and backward integration into precision optics manufacturing to secure supply.
Among diversified surgical device conglomerates, Alcon Inc. and Johnson & Johnson Vision exemplify scale-driven positioning through consumable-anchored revenue models. Carl Zeiss Meditec AG occupies a position within the premium imaging tier, representing integrated hardware-software platform specialization. These three entities anchor distinct competitive vectors without overlapping archetype territory.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Bausch + Lomb |
| Johnson & Johnson Vision |
| Topcon Corporation |
| NIDEK Co., Ltd. |
| EssilorLuxottica |
| Glaukos Corporation |
| Hoya Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in femtosecond laser platform manufacturing across United States and German production facilities is compressing capital equipment margins while elevating consumable pricing power for surgical instrument portfolios. This utilization asymmetry rewards suppliers with installed base lock-in through disposable handpiece revenue streams.
Pricing Analysis
Long-term subscription contracts dominate ambulatory surgical center procurement in California and Texas, displacing capital purchase models for diagnostic equipment. Three-tier pricing structure across premium, standard, and economy levels separates Carl Zeiss Meditec's integrated OCT platforms from mid-tier Asian assemblers and refurbished equipment brokers. Pricing pressure stems from EU MDR recertification costs elevating compliance investment for Class III intraocular devices. Independent ophthalmology practices in India exhibit highest price sensitivity, while United States private equity-consolidated surgical networks absorb premium positioning through bundled service agreements.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for precision optical component sourcing. Manufacturing concentrates in Baden-Württemberg and Bavaria for spectral-domain OCT systems, with Yangtze River Delta clusters supplying lower-tier ultrasound transducers and anterior segment analyzers. German optical glass and Japanese precision motors constitute critical input dependencies. Single-source vulnerability concentrates in femtosecond laser crystal fabrication. Distribution runs through authorized dealer networks for capital equipment and direct GPO contracts for disposable surgical consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through private equity consolidation of United States ambulatory surgical networks, fragmenting procurement decision-making away from independent clinicians toward standardized enterprise contracts.
For Market Incumbents: Build regulatory certification moats by accelerating EU MDR technical documentation completion for embedded AI-diagnostic algorithms before the EU AI Act enforcement window narrows. Secure backward integration into precision optics manufacturing in Bavaria to insulate against German supply concentration risk. Capture consumable-anchored revenue through phacoemulsification handpiece exclusivity agreements with consolidated surgical networks. For New Entrants and Emerging Players: Build out teleophthalmology workflow integration capabilities to penetrate India's tier-II cities where premium OCT distribution networks remain absent. Target mid-tier imaging platform deployment in Jaipur, Lucknow, and Indore through hub-and-spoke service models. Pursue CDSCO quality management system compliance early to accelerate Maharashtra and Karnataka domestic assembly market access. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-enabled diagnostic software developers with Japan PMDA priority review pathway positioning over the medium-term horizon. Monitor femtosecond laser platform utilization rates in United States ambulatory surgical centers as inflection signal for capital equipment replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Accelerates market access for Class III intraocular lenses ahead of algorithm scrutiny deadlines. |
| Backward Integration into Precision Optics | Secures captive supply of spectral-domain OCT components from Bavarian manufacturing clusters. |
| Teleophthalmology Platform Development | Enables hub-and-spoke service models extending specialist reach into India's underserved tier-II cities. |
| Subscription Service Contract Expansion | Aligns vendor incentives with equipment uptime performance in United States private equity-consolidated networks. |
| Japan PMDA Priority Review Pathway Pursuit | Accelerates AI-diagnostic software commercialization for retinal disease screening applications. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and ophthalmology clinic administrators and refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up equipment shipment tracking triangulates against top-down spending estimates from ambulatory surgical center financial disclosures.
Demand-supply balance across diagnostic platform replacement cycles and surgical consumable consumption patterns anchors the analytical framework. Segmentation dimensions modeled include product type, technology architecture, end-user facility category, and application procedure volume. CAGRs derive from equipment installation base growth, software obsolescence timelines, and procedure migration patterns across the projection horizon. Forecast inputs incorporate EU AI Act implementation pacing and Japan PMDA priority review approval velocity.
Stress conditions across EU MDR recertification delays, femtosecond laser platform financing availability, and optical component tariff escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Uveal Melanoma Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Vision Care Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Tonometry Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Age Related Vision Dysfunction Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
United Kingdom Ophthalmology Devices Market