
 Global Vitreous Tamponades Market | 2026-2036
Global Vitreous Tamponades Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vitreous Tamponades Market Analysis
Modular kit configurations pairing silicone oil with injection systems is hardening as the default procurement format for vitreoretinal suites. Alcon, Inc. leverages its integrated surgical platform to bundle tamponade delivery with phacoemulsification infrastructure. Fluoron GmbH anchors European supply through specialized perfluorocarbon chemistry and regional manufacturing proximity. Dutch Ophthalmic Research Center (International) B.V. competes on ophthalmic-specific R&D depth rather than diversified medical portfolios.
Vitreous tamponades comprise sterile, biocompatible agents—perfluorocarbons, silicone oils, and expansile gases—introduced into the vitreous cavity to mechanically support retinal reattachment during postoperative healing. These materials vary in specific gravity, surface tension, and intraocular dwell time, with perfluorocarbons offering temporary heavy tamponade for inferior retinal breaks and silicone oil providing longer-term support in complex proliferative cases. Silicone oil retains the dominant revenue position due to its established safety profile and broad surgical indication coverage, while gas tamponades capture volume in simpler macular hole procedures where spontaneous resorption eliminates removal surgery. Perfluorocarbon liquids command premium positioning in complicated detachment protocols requiring intraoperative flattening.
FDA 510(k) clearance pathways and the EU MDR's tightened clinical evidence requirements for Class III ophthalmic implants jointly elevate barriers for new tamponade entrants. Japan's PMDA maintains distinct pharmacological testing standards that prolong market access timelines for reformulated silicone oils. Stakeholders must monitor evolving regulatory divergence across FDA, EMA, and PMDA jurisdictions when prioritizing product development and geographic launch sequencing.
Market Dynamics
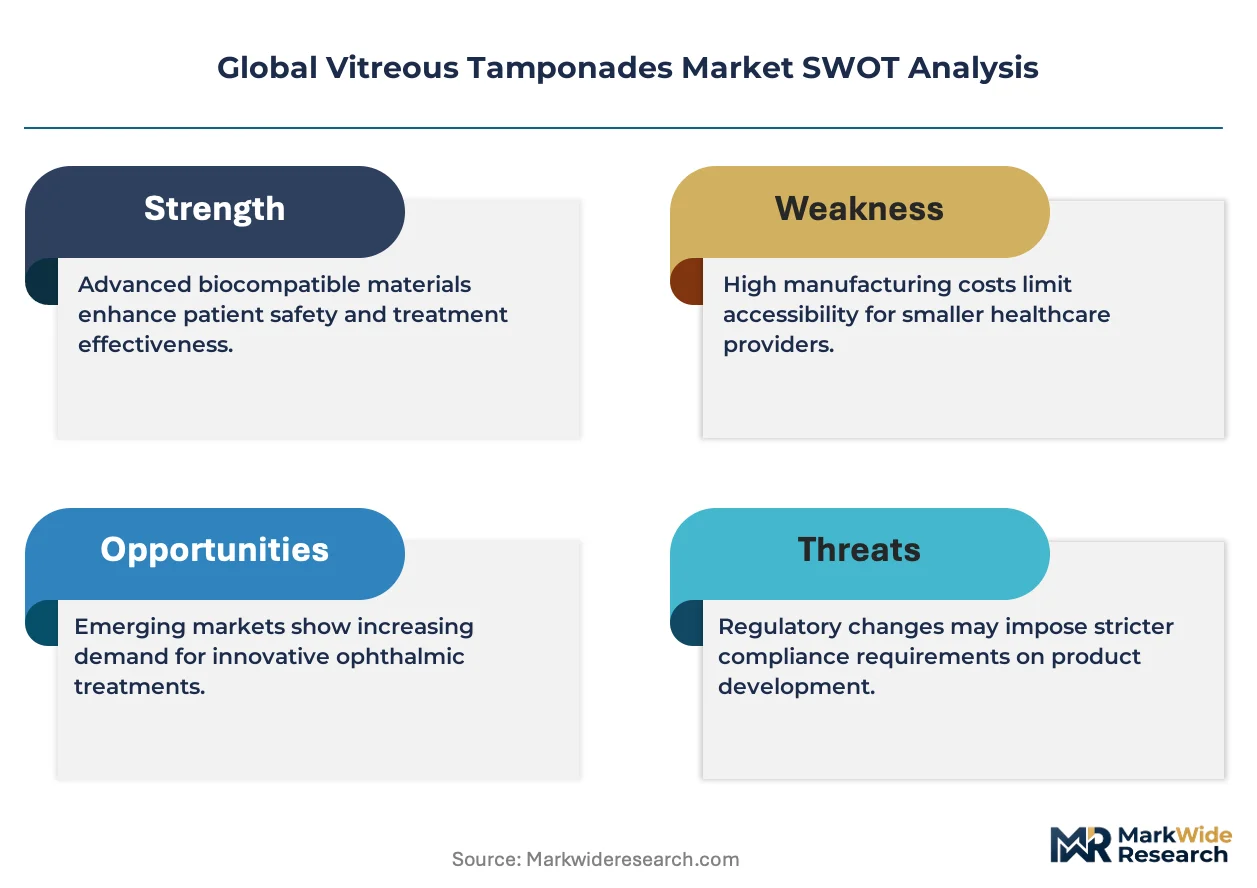
EU MDR's tightened clinical evidence requirements for Class III ophthalmic implants are forcing manufacturers to consolidate regulatory resources and extend certification timelines, fundamentally restructuring competitive entry economics in intraocular device supply.
Growth Catalysts
- Retinal surgical volume concentration:Hospital-based vitreoretinal procedure growth in the United States, Germany, and Japan sustains demand for silicone oil and gas tamponades.
- REACH-compliant perfluorocarbon chemistry:Advanced fluorinated compound manufacturing under EU chemical safety frameworks enables next-generation heavy tamponade development.
- Modular kit standardization:Integrated delivery systems pairing tamponades with injection infrastructure are hardening as the default procurement format across European vitreoretinal suites.
Market Restraints
- Silicone oil raw material concentration:Specialized medical-grade silicone feedstock supply concentrates among limited German and Japanese chemical suppliers.
- PMDA pharmacological testing prolongation:Japan's distinct biocompatibility validation standards extend market access timelines for reformulated tamponade products.
- Gas tamponade substitution pressure:Sulfur hexafluoride and perfluoropropane mixtures displace silicone oil in uncomplicated macular hole procedures.
Strategic Opportunities
- Indian ophthalmic infrastructure expansion:Tier-2 and tier-3 city hospital networks in Maharashtra and Tamil Nadu remain underpenetrated for complex retinal detachment repair.
- F-Gas Regulation compliance innovation:EU fluorinated gas phase-down mandates create white space for low-global-warming-potential alternative tamponade formulations.
- Tele-ophthalmology screening integration:Remote diabetic retinopathy detection in Brazil and Mexico funnels patients toward earlier surgical intervention.
Industry Challenges
- Vitreoretinal surgeon training pipeline constraints:Fellowship program capacity limitations in the United States and United Kingdom restrict procedure volume scaling.
- EU MDR technical documentation burden:Class III implant re-certification requirements consume 18-24 month regulatory affairs bandwidth.
- Sterile manufacturing capex intensity:ISO 13485-compliant aseptic filling lines for intraocular liquids demand substantial capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vitreous Tamponades Market |
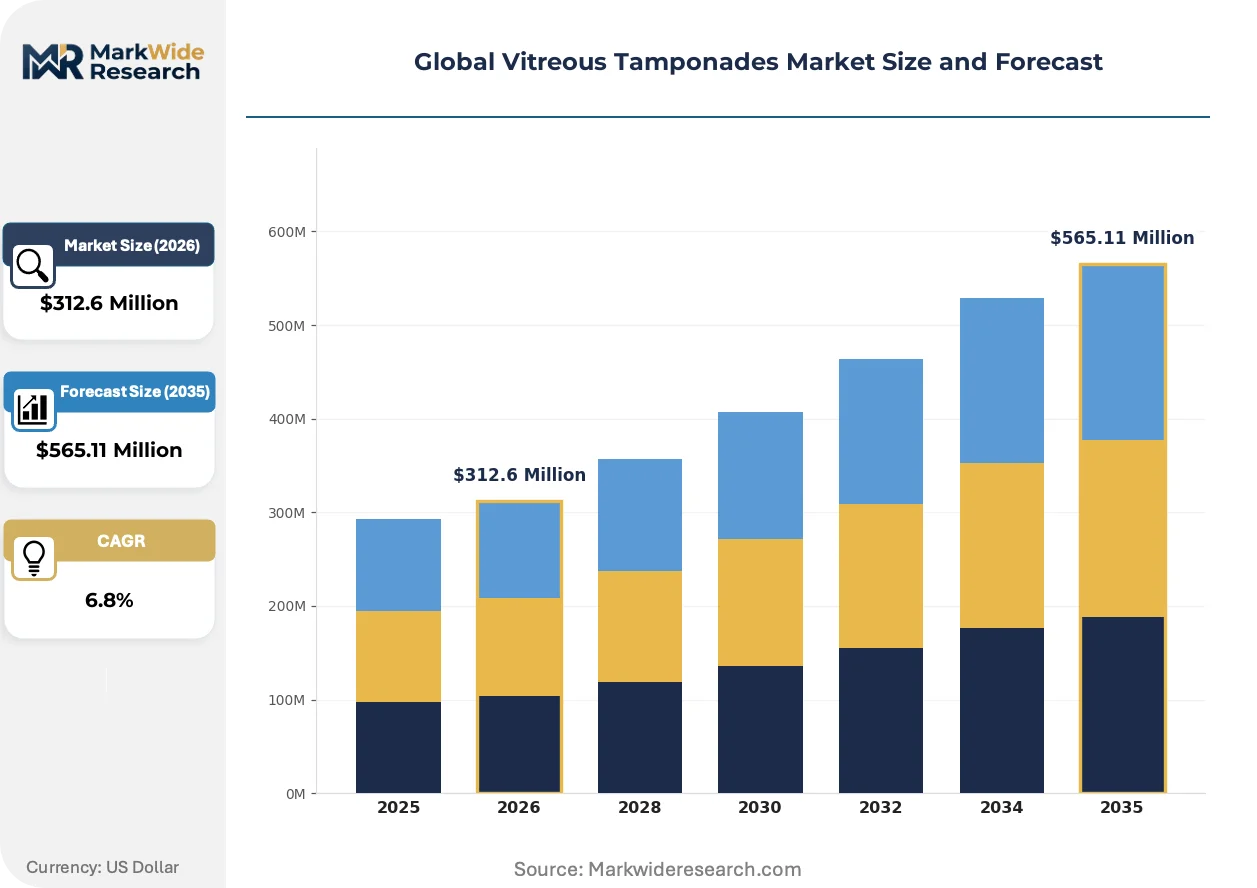
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perfluorocarbons, Silicone Oil, Gas, Others Application: Retinal Detachment, Macular Hole, Vitreous Hemorrhage, Others End User: Hospitals, Ophthalmology Clinics, Ambulatory Surgical Centers, Research Institutes Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesalers |
| Companies Covered | Alcon, Inc., Fluoron GmbH, Carl Zeiss Meditec AG, Dutch Ophthalmic Research Center (International) B.V., Alchimia Srl, Bausch & Lomb Incorporated, Croma-Pharma GmbH, MedOne Surgical Inc., FCI Ophthalmics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vitreous Tamponades Market Emerging Trajectories
Product architecture and regulatory compliance frameworks are undergoing parallel transformation, with device-solution bundling and evidence-generation requirements reshaping how tamponades reach surgical end-users.
Silicone oil tamponade delivery systems are modularizing around pre-filled syringe and integrated injection platform configurations. Vitreoretinal suites in German university hospitals and Japanese tertiary centers are adopting these formats to reduce operative preparation time. This standardization is compressing standalone component procurement and favoring suppliers with captive surgical platform ecosystems.
EU MDR's intensified clinical evidence requirements for permanent intraocular implants are extending post-market surveillance obligations. Manufacturers must now generate real-world performance data across multiple member states to maintain CE marking. High-complexity silicone oil indications face the steepest compliance cost escalation, pushing smaller specialists toward partnership or exit.
Hospital procurement committees are consolidating vendor relationships around full-procedure contracts rather than discrete material purchasing. Integrated service agreements covering tamponade supply, instrument maintenance, and surgeon training are displacing transactional spot buying in United States academic medical centers. This concentration is most visible in Medicare-dependent retinal service lines seeking predictable per-case cost structures.
Global Vitreous Tamponades Market Segmentation
Segmentation in vitreous tamponades reveals how regulatory pathways, surgical workflow integration, and procurement economics fragment commercial opportunity across distinct product and customer configurations. Understanding these divides matters for resource allocation because EU MDR compliance costs and hospital vendor consolidation pressures operate unevenly across categories.
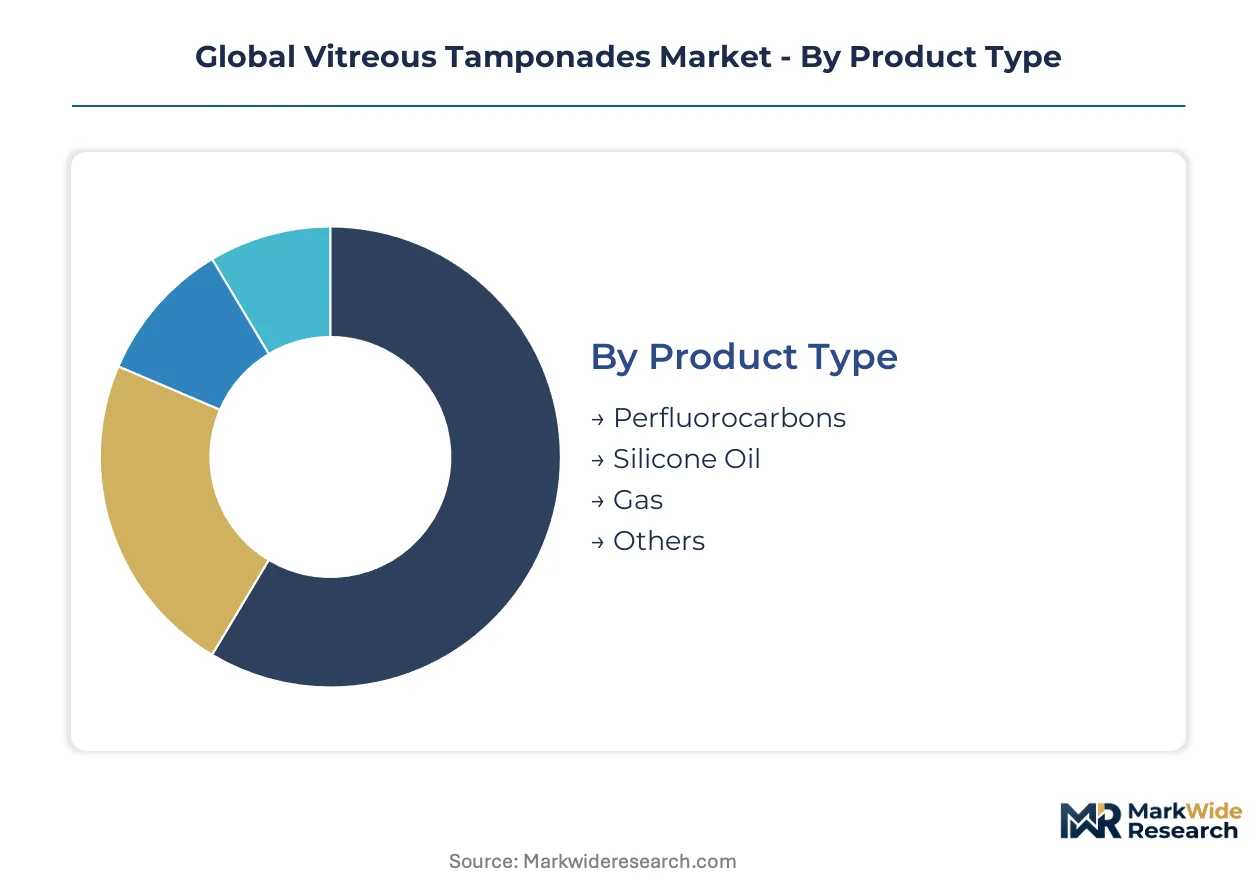
Product Type:
Each product type carries distinct certification obligations—silicone oils face Class III implant scrutiny under EU MDR and FDA 510(k) pathways, while gas tamponades navigate EPA fluorinated gas regulations alongside medical device approvals.
- Silicone Oil:Polydimethylsiloxane formulations with viscosity grades from 1,000 to 5,000 centistokes provide extended intraocular tamponade for complex proliferative vitreoretinopathy. United States academic medical centers anchor demand for higher-viscosity variants in diabetic tractional detachment protocols, though removal surgery requirements constrain volume in cost-sensitive settings.
- Perfluorocarbons:Heavy liquid fluorinated compounds with specific gravity exceeding 1.06 enable intraoperative retinal flattening and temporary inferior break tamponade. German university hospitals drive adoption of purified perfluoro-n-octane formulations, with REACH-compliant chemistry sourcing becoming a procurement discriminator under EU chemical safety frameworks.
- Gas:Sulfur hexafluoride and perfluoropropane mixtures offer spontaneous resorption without removal surgery in selected macular hole cases.
- Others:Experimental tamponade materials including semifluorinated alkanes remain investigational outside controlled trial settings.
Leading the category by volume: Silicone Oil. Growing fastest: Perfluorocarbons.
Application:
Surgical indication determines reimbursement tier and device bundling economics, with retinal detachment commanding premium procedural codes in Medicare and German DRG systems while macular hole procedures face volume compression from gas substitution trends.
- Retinal Detachment:Rhegmatogenous and tractional detachment repair consumes the majority of tamponade volume through pars plana vitrectomy with endotamponade. Japanese tertiary centers concentrate demand for silicone oil in complex proliferative cases, though PMDA pharmacological testing timelines delay access to reformulated products.
- Macular Hole:Idiopathic full-thickness macular hole closure employs gas tamponade in over 90% of primary procedures, with face-down positioning protocols driving patient selection criteria. United States outpatient surgery centers favor C3F8 gas for its extended tamponade duration versus SF6 in larger holes.
- Vitreous Hemorrhage:Diabetic and traumatic hemorrhage indications require diagnostic vitrectomy with tamponade contingency planning.
- Others:Retained lens material, dropped nucleus, and endophthalmitis represent niche tamponade applications with limited protocol standardization.
Retinal Detachment generates the highest absolute procedure value. Macular Hole procedures are expanding most quickly in ambulatory settings.
End User:
Customer type shapes procurement leverage and supplier relationship intensity, with hospital systems extracting multi-year contract concessions while ambulatory centers prioritize instrument compatibility over volume discounts.
- Hospitals:Tertiary academic centers and community hospital systems perform the majority of complex vitreoretinal surgery, with integrated delivery networks in the United States consolidating vendor relationships around full-procedure contracts. German university hospitals anchor European demand for modular kit configurations pairing tamponades with injection platforms.
- Ophthalmology Clinics:Specialized retinal practices concentrate diagnostic volume and postoperative monitoring, with limited intraoperative tamponade procurement outside surgical facility partnerships.
- Ambulatory Surgical Centers:United States Medicare-certified ASCs capture growing macular hole and uncomplicated detachment volume, favoring gas tamponades for their elimination of removal surgery logistics.
- Research Institutes:Contract research organizations and university laboratories consume tamponade materials for device development and animal model studies in preclinical ophthalmic research.
Hospitals dominate procurement value. Ambulatory Surgical Centers are gaining share fastest in United States markets.
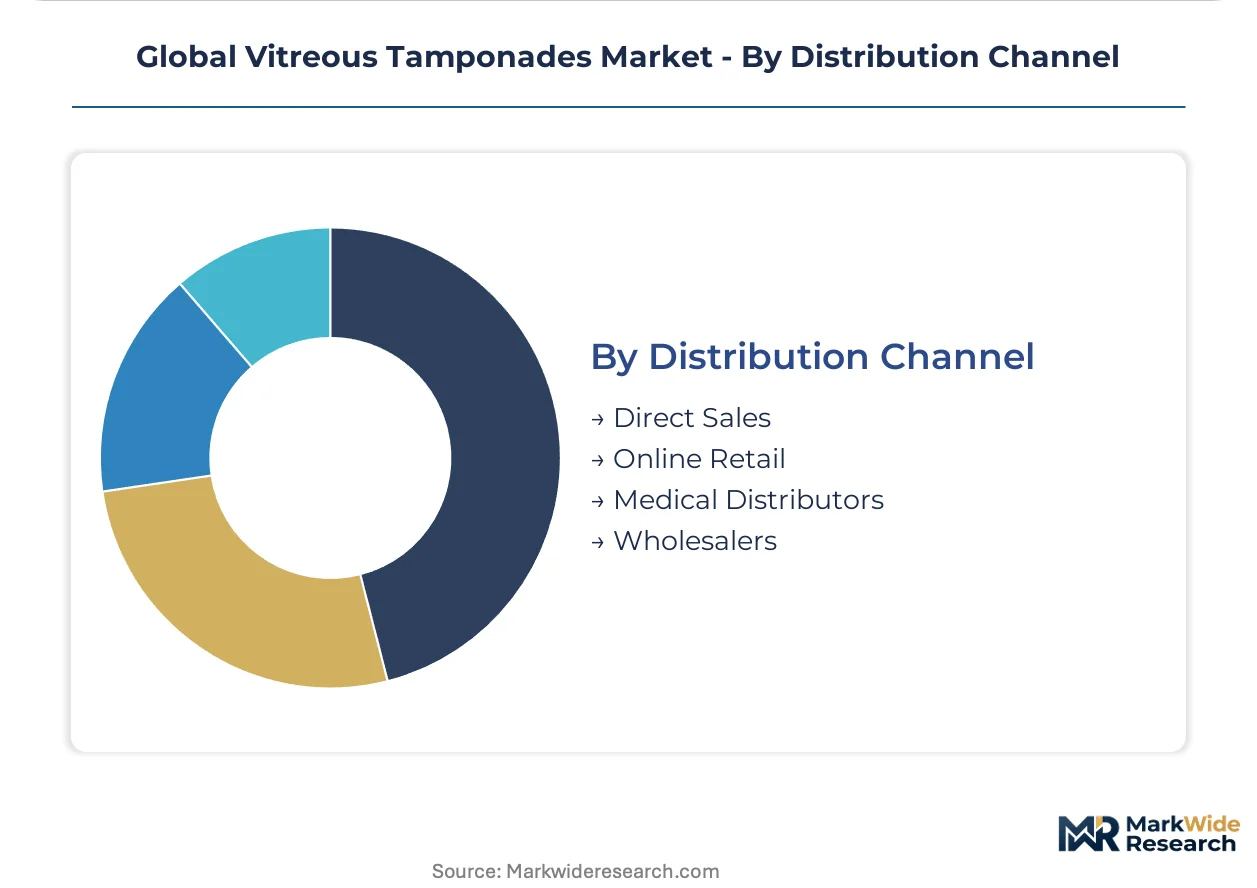
Distribution Channel:
Channel configuration reflects capital intensity and regulatory custody requirements, with direct sales commanding complex implant logistics while distributors handle geographic coverage gaps.
- Direct Sales:Manufacturer field forces manage hospital system contracts and surgical platform bundling for high-volume tamponade accounts, with Alcon and Fluoron maintaining dedicated vitreoretinal specialists in United States and German markets.
- Medical Distributors:Regional ophthalmic distributors serve mid-tier hospitals and independent clinics with inventory management and sterile field support, particularly in Japanese prefectures outside Tokyo and Osaka.
- Online Retail:Limited to non-sterile accessories and surgeon training materials given cold chain and custody requirements for intraocular implants.
- Wholesalers:Pharmaceutical wholesalers handle generic gas tamponade cylinders and commodity silicone oil feedstock for compounding pharmacies.
Direct Sales captures the highest margin concentration. Medical Distributors are expanding fastest in underpenetrated regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of medical-grade silicone feedstock concentrates among German and Japanese chemical suppliers, while surgical consumption clusters in tertiary hospital systems across the United States, Germany, and Japan where vitreoretinal procedure volumes remain elevated.
United States
Medicare-certified ambulatory surgical centers capture expanding macular hole volume, favoring gas tamponades to eliminate removal surgery logistics. FDA 510(k) clearance pathways maintain predictable regulatory timelines for silicone oil formulations. Academic medical centers in Boston and Baltimore anchor demand for higher-viscosity variants in diabetic tractional detachment protocols.
Germany
University hospitals in Heidelberg and Tübingen drive adoption of modular kit configurations pairing tamponades with injection platforms. EU MDR's tightened clinical evidence requirements for Class III implants extend certification timelines for new entrants. REACH-compliant perfluorocarbon chemistry sourcing from domestic suppliers shapes procurement decisions under EU chemical safety frameworks.
Japan
Tertiary centers in Tokyo and Osaka concentrate demand for silicone oil in complex proliferative vitreoretinopathy cases. PMDA pharmacological testing standards prolong market access timelines for reformulated tamponade products. METI industrial policy supports domestic manufacturing of medical-grade fluorinated compounds.
India
Tier-2 and tier-3 city hospital networks in Maharashtra and Tamil Nadu remain underpenetrated for complex retinal detachment repair. CDSCO medical device registration requirements create compliance hurdles for imported silicone oil formulations. Mumbai and Chennai ophthalmic clusters expand vitreoretinal fellowship training capacity to address surgeon pipeline constraints.
Brazil
Tele-ophthalmology screening programs in São Paulo and Minas Gerais funnel diabetic retinopathy patients toward earlier surgical intervention. ANVISA medical device regulations govern importation of perfluorocarbon liquids and silicone oil formulations. Rio de Janeiro academic hospitals anchor southeastern demand for heavy tamponade in complicated detachment protocols.
Global Vitreous Tamponades Market Vendor Landscape
The competitive structure tilts toward integrated surgical platform providers with captive distribution networks. Market participation fragments across three tiers: diversified ophthalmology conglomerates with full-procedure bundling capability, specialized European chemistry houses with regional manufacturing proximity, and mid-scale distributors serving geographic coverage gaps. Dominant competitive moves include strategic partnerships with hospital procurement committees and portfolio diversification into modular delivery systems.
Among diversified ophthalmology conglomerates, Alcon, Inc. and Bausch & Lomb Incorporated exemplify platform-integrated positioning through bundled tamponade-surgical instrument offerings. Fluoron GmbH occupies a specialist tier, anchoring European supply through concentrated perfluorocarbon chemistry expertise. Dutch Ophthalmic Research Center (International) B.V. represents the research-intensive archetype, competing on ophthalmic-specific R&D depth rather than diversified medical portfolios.
| Leading Market Players |
|---|
| Alcon, Inc. |
| Fluoron GmbH |
| Carl Zeiss Meditec AG |
| Dutch Ophthalmic Research Center (International) B.V. |
| Alchimia Srl |
| Bausch & Lomb Incorporated |
| Croma-Pharma GmbH |
| MedOne Surgical Inc. |
| FCI Ophthalmics |
| Others |
Supply Flow & Price Mechanics
Medical-grade silicone feedstock costs cascade through three distinct pricing tiers, with German and Japanese chemical suppliers commanding premium positioning for high-viscosity polydimethylsiloxane while REACH-compliant perfluorocarbon chemistry from domestic EU manufacturers anchors mid-tier hospital procurement.
Pricing Analysis
Margin tightening in standard-viscosity silicone oil reflects concentrated raw material supply among German and Japanese chemical houses. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified formulations from compounding pharmacy alternatives. Cost-down pressure on gas tamponades accelerates because sulfur hexafluoride faces EU F-Gas Regulation phase-down mandates. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize viscosity performance over per-unit cost.
Supply Chain Analysis
CE marking and FDA 510(k) clearance requirements gate upstream supply access, with ISO 13485-certified aseptic filling lines serving as the critical qualification bottleneck. Production concentrates in Germany, Japan, and the United States, drawing from specialized medical-grade silicone feedstock, purified fluorinated compounds, and sterile packaging components. Single-source vulnerability in medical-grade silicone supply from limited German and Japanese chemical suppliers poses structural risk. Distribution runs through manufacturer field forces for hospital system contracts, with regional ophthalmic distributors covering geographic gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated surgical platform providers as EU MDR compliance costs force smaller specialists toward partnership or exit.
For Market Incumbents: Lock in hospital procurement committee relationships through full-procedure service agreements covering tamponade supply, instrument maintenance, and surgeon training. Deepen backward integration into medical-grade silicone feedstock to secure supply against Japanese and German chemical supplier concentration. CE marking renewal investments represent the critical defensive lever against EU MDR's extended certification timelines. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down mandates in Europe open a window for low-global-warming-potential alternative tamponade formulations. Tier-2 and tier-3 city hospital networks in Maharashtra and Tamil Nadu present the most penetrable geography, with CDSCO registration hurdles filtering competition. Partner with established regional ophthalmic distributors to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: PMDA pharmacological testing timeline extensions for reformulated silicone oils are the leading indicator that Japanese market access barriers will persist, favoring domestic manufacturing acquisitions over import-dependent models. Vertically integrated specialists with captive perfluorocarbon chemistry expertise and EU MDR-ready technical documentation represent priority acquisition archetypes. Watch for METI industrial policy shifts supporting domestic fluorinated compound production as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking maintenance secures access to German university hospital procurement. |
| Modular Kit Configuration Development | Pre-filled syringe integration with injection platforms hardens as default format. |
| REACH-Compliant Chemistry Sourcing | Domestic EU perfluorocarbon supply anchors procurement decisions under chemical safety frameworks. |
| Hospital System Partnership Agreements | Full-procedure contracts displace transactional spot buying in Medicare-dependent service lines. |
| Tele-Ophthalmology Screening Integration | Remote diabetic retinopathy detection funnels patients toward earlier surgical intervention in Brazil. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among vitreoretinal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearances, EUDAMED device registrations, PMDA approval summaries, and EU MDR technical documentation databases provided secondary validation. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions across the analysis window.
Granularity-level modeling operated at product type, application, end user, and distribution channel dimensions, with viscosity grade and regional regulatory cluster as additional cross-cutting variables. CAGRs derived from segmented volume projections and pricing trajectory assumptions, incorporating vitreoretinal surgical procedure growth rates, reimbursement code evolution, and raw material cost indices as industry-specific inputs.
The model assumes silicone oil retains dominant tamponade positioning; alternative pathways for semifluorinated alkane adoption would alter the outlook. Forecasts reflect assumptions regarding EU MDR certification timeline stability, PMDA testing standard continuity, and hospital vendor consolidation velocity. A model refresh is warranted upon material change in F-Gas Regulation enforcement intensity or METI industrial policy direction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Retinal Vein Occlusion Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Pseudotumor Cerebri Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Global Posterior Segment Eye Disorders Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
United Kingdom Ophthalmology Devices Market
Ophthalmology
Coloured Contact Lenses Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Ophthalmic Devices Market