
 Herpes Zoster Ophthalmicus Market | 2026-2036
Herpes Zoster Ophthalmicus Market Size, Share, and Industry Trends Forecast 2026-2036
Herpes Zoster Ophthalmicus Market Foresight
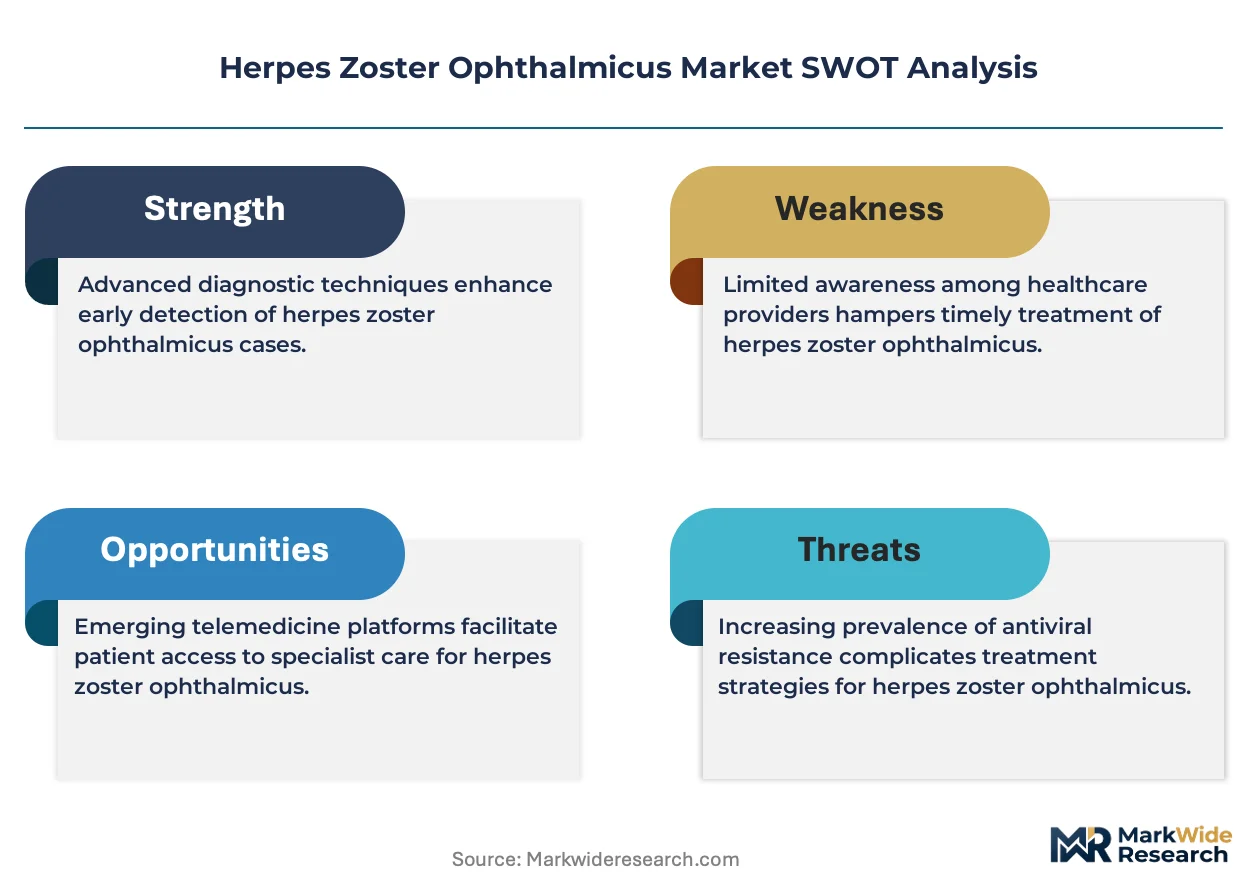
North American biopharmaceutical capacity expansion is reshaping supply security for antiviral APIs used in shingles-related ocular therapies. GlaxoSmithKline leverages its recombinant zoster vaccine platform to sustain leadership in preventive ophthalmology segments. Pfizer competes through established small-molecule antiviral manufacturing scale, while Bausch + Lomb specializes in topical corticosteroid formulations for anterior segment inflammation.
Herpes zoster ophthalmicus denotes varicella-zoster virus reactivation within the first division of the trigeminal nerve, producing corneal dendritic lesions, stromal keratitis, and potential vision loss without prompt acyclovir or valacyclovir intervention. Antiviral drugs command the largest current revenue share given their role as first-line therapy, while immunomodulators represent the fastest-expanding category as biologics target refractory postherpetic neuralgia. Intravenous delivery dominates acute hospitalized presentations, though subcutaneous biologic administration is gaining traction in outpatient specialty pharmacy channels for chronic pain management.
FDA oversight of ophthalmic drug manufacturing through current Good Manufacturing Practice standards shapes product quality thresholds, while EMA's MDR framework governs diagnostic device market access across European territories. The EU AI Act increasingly influences automated OCT analysis tools used in clinical evaluation workflows. Stakeholders must monitor evolving CMS reimbursement decisions for combination antiviral-immunomodulatory protocols versus standalone generic regimens.
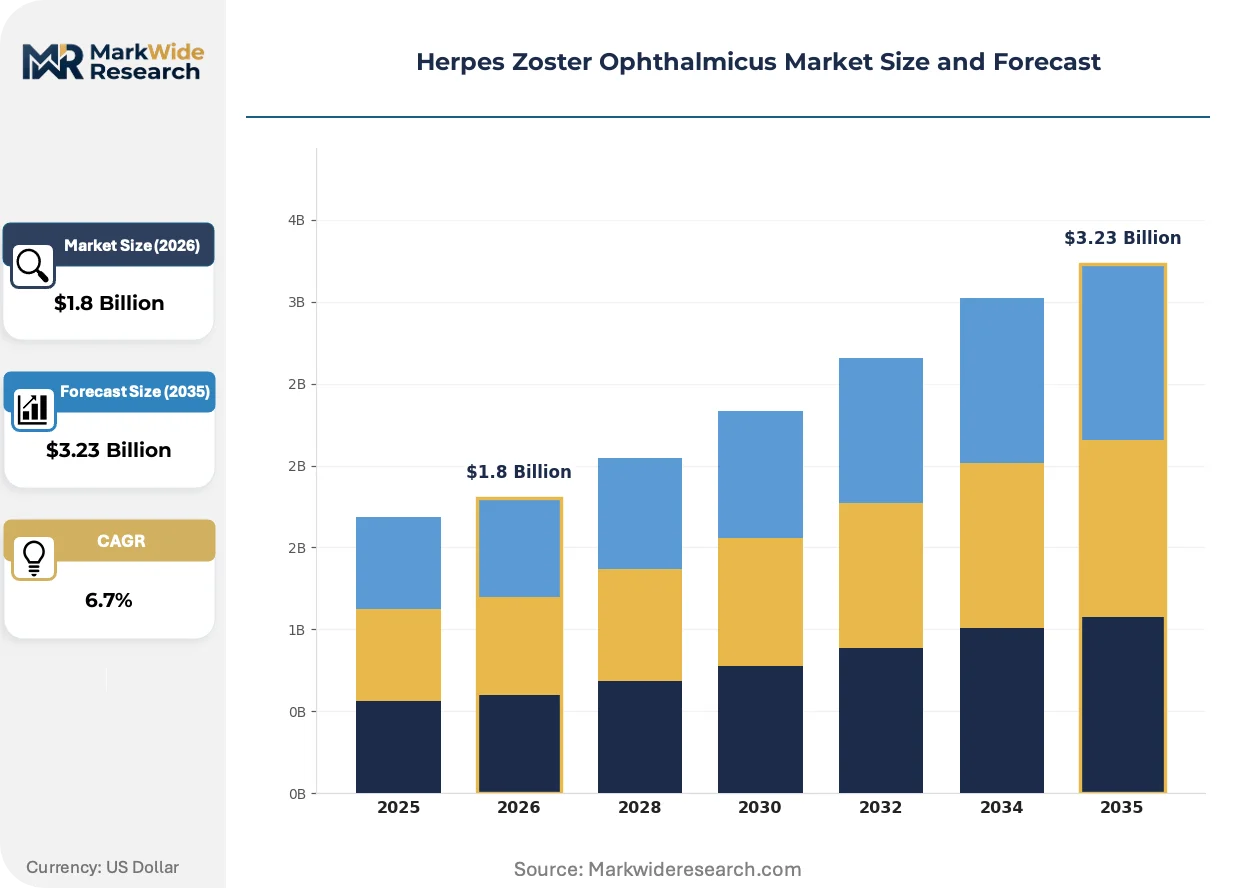
Market Dynamics
Vaccination coverage expansion among aging populations is restructuring preventive care pathways, while antiviral manufacturing concentration in specific API clusters creates supply vulnerability exposure for ophthalmic formulations.
Growth Catalysts
- Accelerated FDA Approval Pathways:The FDA's breakthrough therapy designation for novel antiviral compounds compresses clinical-to-commercial timelines, enabling faster patient access to shingles-related ocular therapies.
- Geriatric Hospital Settings:Rising inpatient vaccination protocols among Medicare-eligible populations in US acute care facilities broadens the addressable patient pool for prophylactic interventions.
- Recombinant Subunit Platforms:Adjuvanted vaccine technologies demonstrate superior immunogenicity in immunocompromised cohorts, expanding indication scope beyond standard adult populations.
Market Restraints
- API Supply Concentration:Bulk acyclovir and valacyclovir active pharmaceutical ingredient production concentrates in Chinese and Indian chemical manufacturing zones, exposing finished dose formulators to geopolitical trade friction.
- Cold Chain Infrastructure Gaps:Temperature-sensitive recombinant vaccines require uninterrupted -20°C to -70°C distribution networks that remain underdeveloped in rural and lower-tier urban healthcare systems.
- Generic Antiviral Substitution:Patent-expired oral nucleoside analogues at commodity pricing levels constrain revenue potential for novel therapeutic candidates in development pipelines.
Strategic Opportunities
- Subcutaneous Biologic Administration:Outpatient specialty pharmacy channels for chronic postherpetic neuralgia management represent underpenetrated distribution infrastructure requiring targeted formulary access investment.
- EU MDR Diagnostic Harmonization:The European Medical Device Regulation's unified conformity assessment pathway streamlines automated OCT analysis tool commercialization across 27 member states.
- Combination Protocol Reimbursement:CMS evaluation of antiviral-immunomodulatory bundled payment structures creates favorable coverage determination potential for integrated care models.
Industry Challenges
- Ophthalmic cGMP Compliance:FDA current Good Manufacturing Practice standards for sterile ophthalmic drug production impose facility validation timelines that extend product launch windows by 18-24 months.
- Retinal Specialist Workforce Density:Geographic maldistribution of cornea and uveitis fellowship-trained clinicians restricts treatment access in non-metropolitan catchment areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herpes Zoster Ophthalmicus Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Drugs, Pain Management Medications, Immunomodulators, Supportive Care Treatments Delivery Mode: Intravenous, Oral, Topical, Subcutaneous End User: Hospitals, Clinics, Home Care Settings, Specialty Pharmacies Technique: Ophthalmic Examination, PCR Testing, Serology, Clinical Evaluation |
| Companies Covered | GlaxoSmithKline, AbbVie, Pfizer, Merck, Novartis, Bausch + Lomb, Santen Pharmaceutical, Gilead Sciences, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herpes Zoster Ophthalmicus Market Shifts & Advancements
Digital pathology integration and automated diagnostic workflows are compressing clinical decision cycles, while regulatory frameworks for AI-enabled medical devices mature across major healthcare jurisdictions.
Artificial intelligence-powered optical coherence tomography analysis is virtualizing traditional slit-lamp examination protocols for herpes zoster ophthalmicus diagnosis. Academic medical centers and large multi-specialty ophthalmology groups in the United States and Germany are deploying these systems at pilot scale. This virtualization is compressing specialist referral bottlenecks and enabling earlier antiviral intervention initiation in community settings.
The EU AI Act's risk-based classification framework for medical device software imposes conformity assessment obligations on automated diagnostic algorithms used in clinical workflows. Manufacturers must now demonstrate algorithmic transparency and post-market performance monitoring for high-risk applications. Ophthalmic AI developers are responding by restructuring quality management systems and establishing notified body relationships ahead of 2026 enforcement deadlines.
Hospital outpatient departments are consolidating ophthalmic pharmaceutical procurement under centralized pharmacy and therapeutics committees, displacing individual physician preference purchasing. This concentration shifts vendor access strategy toward formulary inclusion battles and evidence-based contracting. The phenomenon is most pronounced in US integrated delivery networks where Medicare Advantage penetration exceeds 40 percent of covered lives.
Herpes Zoster Ophthalmicus Market Segmentation
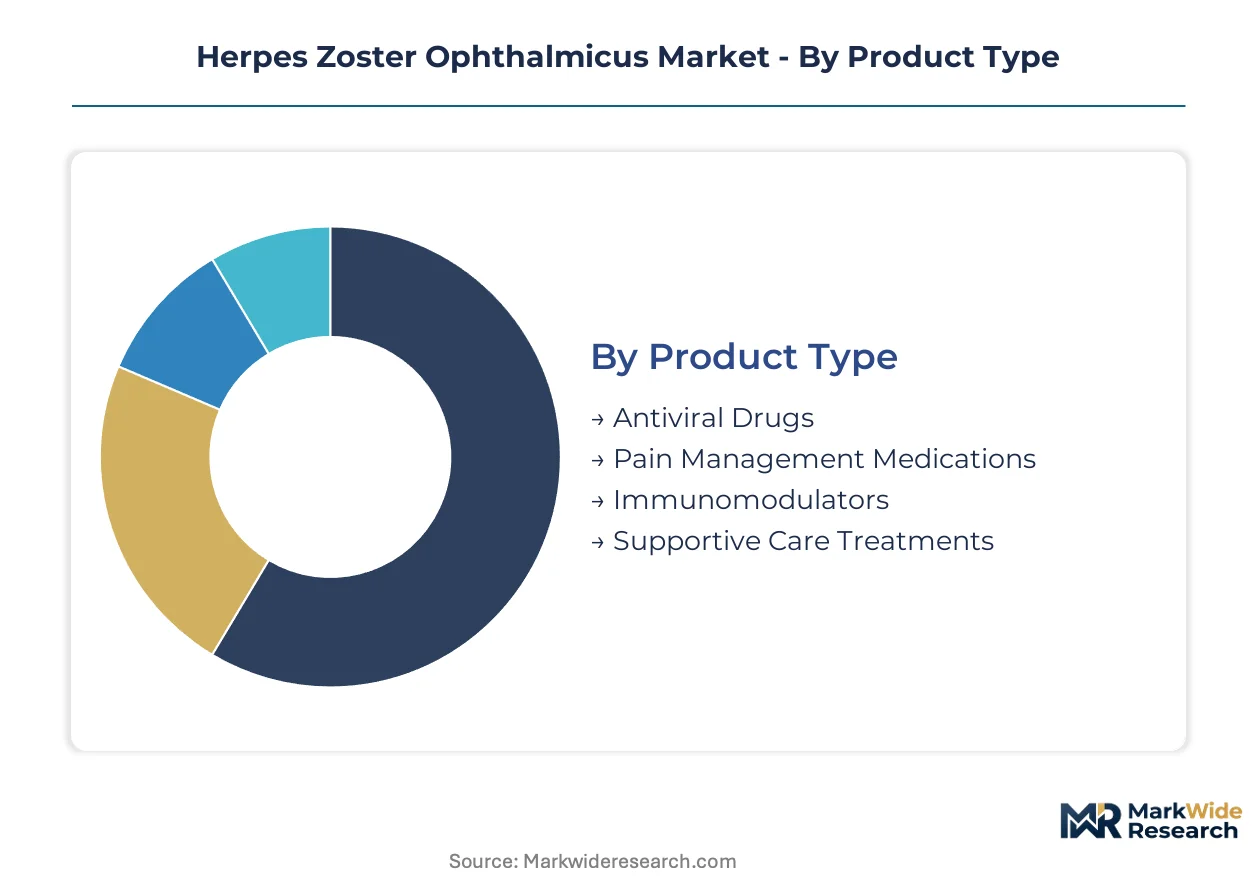
Segmentation of the Herpes Zoster Ophthalmicus Market reveals how treatment pathways diverge across acute versus chronic care settings, with product formulation and delivery infrastructure shaping access patterns. Each dimension captures distinct procurement behaviors, from hospital-based antiviral infusion protocols to outpatient biologic self-administration models.
Product Type:
Cost tier differentiation separates acute intervention therapies from chronic disease management solutions, with reimbursement intensity varying sharply across these categories.
- Antiviral Drugs:Nucleoside analogues including acyclovir, valacyclovir, and famciclovir constitute first-line intervention for acute viral replication suppression. Hospital formularies in the United States prioritize intravenous acyclovir for sight-threatening presentations, with Medicare Part B reimbursement sustaining utilization.
- Immunomodulators:Biologic agents targeting refractory postherpetic neuralgia represent the steepest expansion trajectory, with subcutaneous monoclonal antibodies gaining formulary access in US specialty pharmacy networks for immunocompromised patients with persistent pain.
- Pain Management Medications:Gabapentinoids and tricyclic antidepressants address neuropathic sequelae through oral and topical routes.
- Supportive Care Treatments:Lubricating eye drops and protective eyewear complement active pharmaceutical interventions.
Antiviral drugs command the established base. The steepest expansion runs through immunomodulators.
Delivery Mode:
Application setting dictates route selection, with severity of ocular involvement and patient acuity determining whether administration occurs in controlled clinical environments or ambulatory settings.
- Intravenous:Hospital-based infusion of acyclovir achieves therapeutic cerebrospinal fluid concentrations for sight-threatening keratouveitis and acute retinal necrosis. US academic medical centers maintain 24-hour pharmacy compounding capabilities for this indication.
- Subcutaneous:Biologic administration for chronic postherpetic neuralgia is concentrating in outpatient specialty pharmacy channels, with Medicare Advantage plans in Florida and Arizona expanding prior authorization pathways for home-based injection.
- Oral:Valacyclovir and famciclovir dominate outpatient initiation and completion of standard treatment courses.
- Topical:Ganciclovir gel and corticosteroid suspensions address localized anterior segment inflammation.
Intravenous delivery anchors acute care revenue. The fastest volume gains are occurring in subcutaneous biologic administration.
End User:
Customer type segmentation reflects site-of-care migration trends, with reimbursement policy accelerating shifts from institutional to home-based management.
- Hospitals:Inpatient admission for intravenous antiviral therapy, particularly for immunocompromised patients with disseminated zoster or vision-threatening complications. US integrated delivery networks are consolidating ophthalmic pharmaceutical procurement under centralized pharmacy and therapeutics committees.
- Specialty Pharmacies:These channels are capturing increasing biologic dispensing volume for chronic postherpetic neuralgia, with accreditation requirements from URAC and ACHC shaping network participation in Medicare Part D plans.
- Clinics:Ophthalmology and urgent care settings handle oral antiviral initiation and monitoring.
- Home Care Settings:Self-administered oral regimens and caregiver-assisted topical application predominate.
Hospitals retain the highest acuity case volume. Specialty pharmacies are climbing the fastest as biologic penetration deepens.
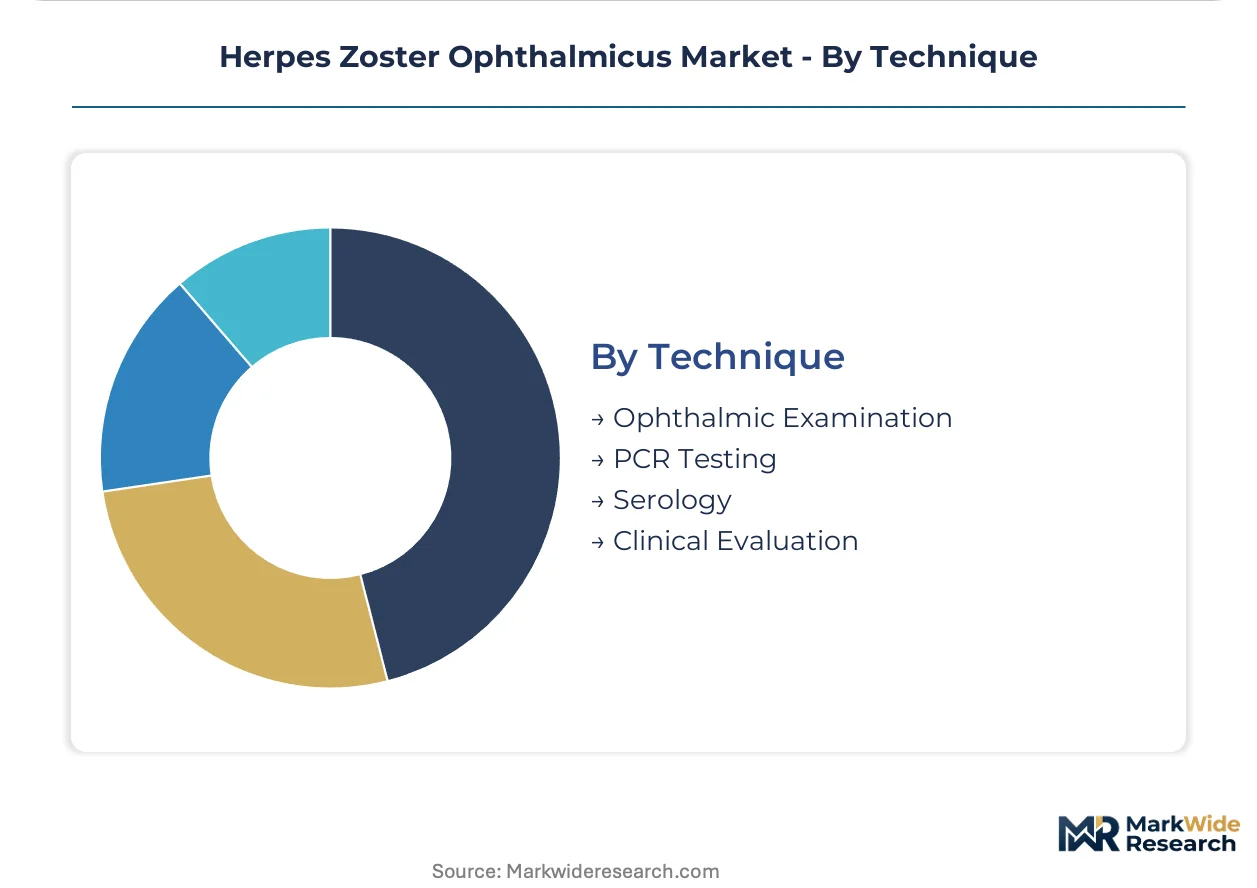
Technique:
Diagnostic maturity varies across confirmatory versus presumptive approaches, with regulatory frameworks for algorithmic tools introducing new compliance layers.
- Ophthalmic Examination:Slit-lamp biomicroscopy with fluorescein staining remains the clinical standard for detecting dendritic epithelial lesions and stromal keratitis. German academic medical centers and large US multi-specialty groups are piloting AI-enhanced optical coherence tomography analysis to compress referral timelines.
- PCR Testing:Polymerase chain reaction from corneal swabs or aqueous humor samples provides definitive varicella-zoster virus identification in atypical presentations. The EU AI Act's risk-based classification framework imposes conformity assessment obligations on automated diagnostic algorithms used in clinical workflows.
- Serology:Antibody detection supports epidemiological assessment but offers limited acute diagnostic utility.
- Clinical Evaluation:Dermatomal pain pattern recognition and vesicular rash distribution guide presumptive treatment initiation.
Ophthalmic examination commands the established base. PCR testing is gaining share fastest as laboratory turnaround times compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulk acyclovir and valacyclovir API manufacturing clusters in Chinese and Indian chemical zones expose finished dose formulators to trade friction, while recombinant vaccine cold chain infrastructure gaps persist in rural healthcare systems worldwide.
United States
Medicare Part B reimbursement for intravenous acyclovir sustains hospital formularies, and the FDA's breakthrough therapy designation compresses antiviral commercialization timelines. The Southeast region, particularly Florida and Arizona, sees Medicare Advantage plans expanding prior authorization pathways for home-based biologic injection.
Germany
Academic medical centers pilot AI-enhanced optical coherence tomography analysis to compress specialist referral bottlenecks. The EU AI Act's risk-based classification framework imposes conformity assessment obligations on automated diagnostic algorithms, with Heidelberg and Munich clusters leading ophthalmic AI quality management restructuring.
China
Domestic API production capacity for nucleoside analogues supplies regional formulators, though NMPA oversight of sterile ophthalmic drug manufacturing extends facility validation timelines. Yangtze River Delta chemical manufacturing zones concentrate bulk acyclovir production for export markets.
India
CDSCO accelerated approval pathways for generic antiviral formulations compete with innovator products, while Mumbai and Hyderabad API clusters supply global dose formulators. The country's central pharmaceutical regulator maintains current Good Manufacturing Practice standards for sterile ophthalmic production.
Japan
PMDA oversight of recombinant vaccine distribution requires uninterrupted cold chain infrastructure that remains underdeveloped in rural prefectures. Tokyo and Osaka metropolitan areas concentrate retinal specialist workforce density and ophthalmic pharmaceutical procurement consolidation.
Herpes Zoster Ophthalmicus Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The herpes zoster ophthalmicus market structures around vaccine platform developers, antiviral API manufacturers, and ophthalmic formulation specialists. Three archetypes dominate: recombinant subunit vaccine platforms, small-molecule antiviral manufacturers, and topical corticosteroid formulators. Competitive moves concentrate on formulary inclusion battles and evidence-based contracting with integrated delivery networks.
Among UK-based pharmaceutical conglomerates, GlaxoSmithKline occupies a position exemplifying recombinant zoster vaccine platform leadership. Pfizer represents the small-molecule antiviral manufacturing scale archetype, while Bausch + Lomb sits within the ophthalmic formulation specialist tier. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning across preventive, acute therapeutic, and chronic management segments.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AbbVie |
| Pfizer |
| Merck |
| Novartis |
| Bausch + Lomb |
| Santen Pharmaceutical |
| Gilead Sciences |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Overcapacity in Yangtze River Delta acyclovir API manufacturing is compressing contract pricing for finished dose formulators while simultaneously eroding supplier willingness to maintain redundant production lines. This utilization dynamic forces ophthalmic drug manufacturers toward dual-sourcing strategies that trade margin protection against supply continuity.
Pricing Analysis
Medicare Part B reimbursement schedules dictate the pricing tier structure for intravenous antiviral therapies in US hospital formularies. Three-tier pricing structure across originator, authorized generic, and commodity generic levels separates GlaxoSmithKline's recombinant vaccine from Pfizer's established antiviral portfolio from Indian CDSCO-approved generic entrants. Cost compression in oral nucleoside analogue segments is intensifying because of Mumbai and Hyderabad API cluster expansion. Medicare Advantage plans exhibit highest price sensitivity; breakthrough therapy designated biologics show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for ophthalmic antiviral manufacturers dependent on Yangtze River Delta API inputs. Bulk acyclovir and valacyclovir production concentrates in Chinese and Indian chemical manufacturing zones, with ganciclovir raw material synthesis resting on Hubei province intermediate suppliers. Single-source vulnerability persists for recombinant subunit vaccine adjuvants. Distribution runs through hospital centralized pharmacy committees and specialty pharmacy accreditation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained cornea and uveitis specialists remain concentrated in metropolitan academic medical centers, creating treatment access deserts that constrain market expansion. This human capital scarcity shapes competitive positioning more than manufacturing scale.
For Market Incumbents: Insulate formulary position through backward integration into sterile ophthalmic cGMP manufacturing capacity in Research Triangle Park and Heidelberg clusters. Expand prior authorization pathway investments with Medicare Advantage plans in Florida and Arizona. Generic substitution pressure from CDSCO-accelerated Indian entrants threatens originator antiviral margins. For New Entrants and Emerging Players: Rural Japanese prefectures present the most penetrable geography for cold chain infrastructure partnerships with METI-supported distribution networks. Target subcutaneous biologic administration training for home health agencies in US Southeast markets. Pursue EU MDR notified body pre-submission for AI-enabled OCT diagnostic algorithms ahead of enforcement deadlines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty pharmacy networks with URAC accreditation and Medicare Part D formulary lock-in. Five-to-ten year viability favors platform developers with recombinant subunit manufacturing capabilities over single-product antiviral formulators. Watch FDA breakthrough therapy designation grants as inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Breakthrough therapy designation compresses FDA commercialization timelines for novel antiviral compounds. |
| Regulatory Approval Pathway | EU MDR conformity assessment streamlines automated OCT tool distribution across 27 member states. |
| Manufacturing Scale-Up | Domestic API capacity expansion in Yangtze River Delta reduces tariff exposure for finished dose formulators. |
| Pipeline Diversification | Subcutaneous biologic development targets refractory postherpetic neuralgia in immunocompromised cohorts. |
| Reimbursement Strategy | CMS bundled payment evaluation for antiviral-immunomodulatory combinations shapes integrated care model viability. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure analysis were triangulated to establish market size boundaries.
Demand-supply balance across antiviral API manufacturing capacity and finished dose formulation output anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include treatment line, dosage form, administration route, patient immunocompetence status, and regional regulatory cluster. CAGRs were derived from patent expiry curves, generic erosion rates, and biologic penetration assumptions in specialty pharmacy channels.
Practitioners should monitor FDA cGMP enforcement actions, EU AI Act notified body capacity constraints, and Medicare Advantage formulary exclusion list updates for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Retinal Detachment Market
Ophthalmology
Choroidal Neovascularization Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Europe Ophthalmology Drug and Device Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Ophthalmic Eye Shield Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Ocular Pain Market