
 Antidepressant Drugs Market | 2026-2036
Antidepressant Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antidepressant Drugs Market Analysis
Outcome-based reimbursement for chronic mental health management is shifting how antidepressant value gets captured across the care continuum. Pfizer Inc. leverages its established psychiatric portfolio to sustain formulary positioning in key markets. AbbVie Inc. anchors its neuroscience franchise through specialized commercial infrastructure. Eli Lilly and Company differentiates via R&D intensity in novel mechanism antidepressants, including glutamatergic targets.
Antidepressant drugs are psychopharmacological agents that modulate monoamine neurotransmission—principally serotonin, norepinephrine, and dopamine signaling—to alleviate depressive symptomatology; most oral formulations achieve steady-state plasma concentrations within one to two weeks of daily administration. Their primary commercial purpose is to reduce disease burden in mood disorders within outpatient and institutional settings. Among drug classes, SSRIs occupy the mature volume base while atypical antidepressants represent the fastest-expanding margin pool due to patent-protected pricing. The prescription type dimension shows generics commanding unit volume while brand-name agents retain premium positioning in treatment-resistant populations.
The FDA maintains stringent efficacy and safety standards through controlled trial requirements and boxed warning protocols for suicidality risk in younger patients. The EMA's centralized marketing authorization process shapes access dynamics across European member states, while the EU MDR increasingly governs digital therapeutics paired with pharmacological intervention. Stakeholders must monitor how regulatory divergence between FDA and EMA pathways for novel rapid-acting antidepressants affects launch sequencing and investment allocation.
Market Dynamics
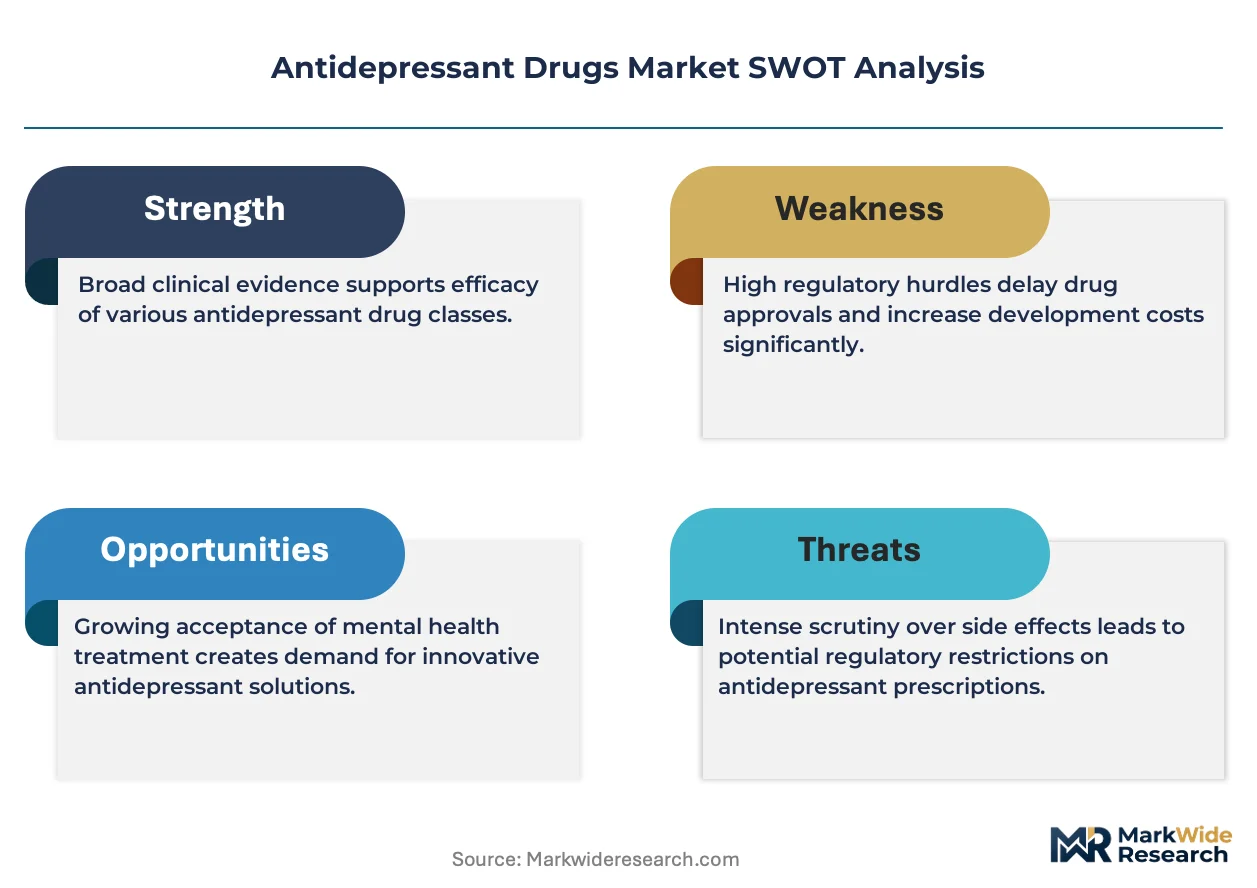
Accelerated FDA approval pathways for rapid-acting antidepressants are compressing development timelines and forcing incumbents to defend formulary positions against mechanism-diverse entrants.
Growth Catalysts
- Outpatient mental health clinics:Prescribing volumes at these facilities are expanding as integrated care models embed psychiatric services within primary care networks.
- EMA centralized marketing authorization:This framework streamlines cross-border access across European member states, reducing launch sequencing friction for novel agents.
- Glutamatergic mechanism research:R&D investment in NMDA receptor modulation is opening therapeutic avenues for treatment-resistant depression populations.
Market Restraints
- Generic sertraline and fluoxetine:These mature SSRI commodities erode pricing power across first-line depression indications.
- Suicidality boxed warning:FDA-mandated risk labeling for patients under 25 years constrains pediatric and young adult prescribing.
- Specialist psychiatrist concentration:Geographic clustering of qualified prescribers in urban corridors limits rural and exurban market penetration.
Strategic Opportunities
- Digital therapeutics pairing:EU MDR-governed software-as-medical-device combinations with pharmacological intervention represent reimbursement expansion vectors.
- Treatment-resistant depression protocols:Esketamine and emerging psychedelic-assisted frameworks address populations failing two or more prior antidepressant trials.
- Telepsychiatry channels:Virtual prescribing platforms are capturing chronic medication management encounters previously lost to appointment non-adherence.
Industry Challenges
- Clinical trial recruitment:Placebo response variability in depression studies demands larger enrollment cohorts and extended timelines.
- Reimbursement coding alignment:Novel mechanism agents face prior authorization complexity as payers apply step-therapy requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antidepressant Drugs Market |
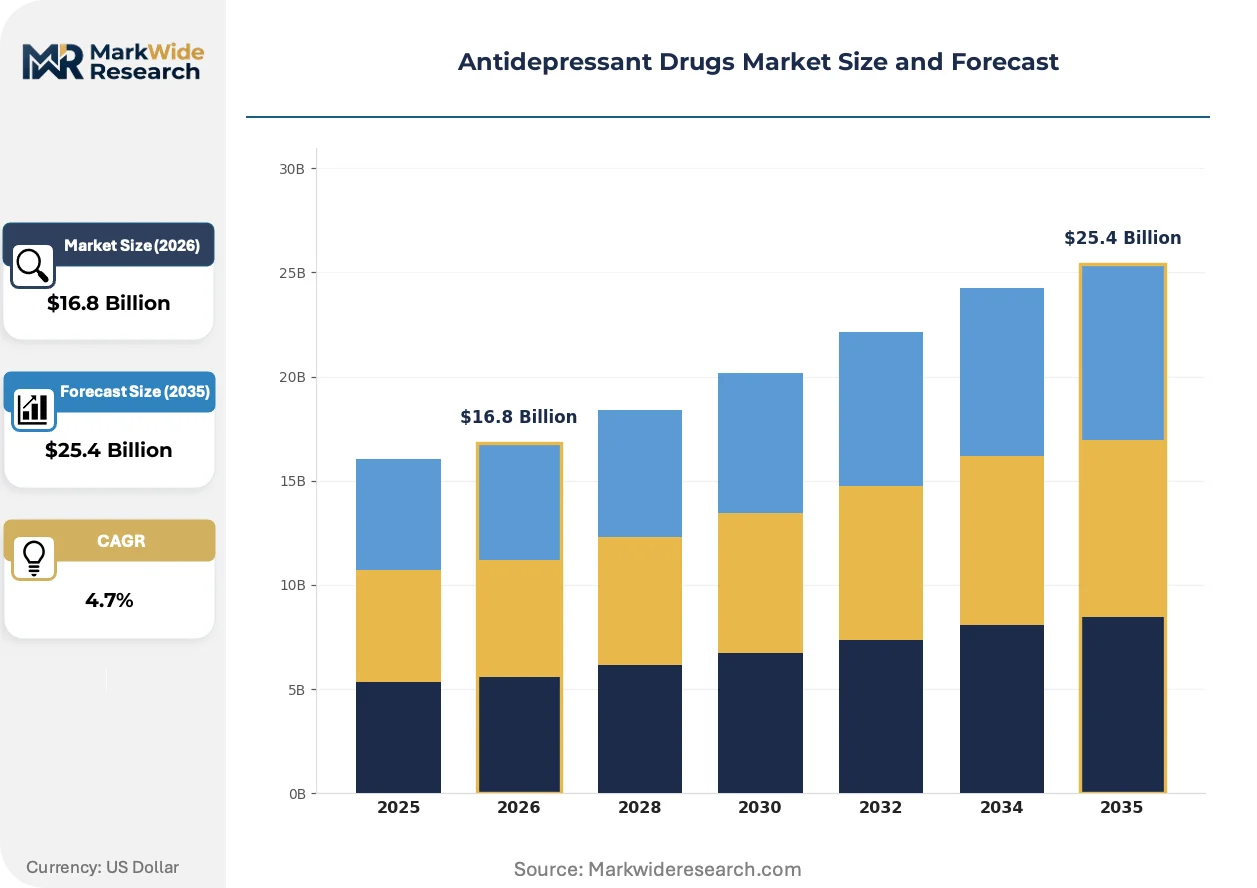
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $25.4 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: SSRIs, SNRIs, TCAs, Atypical Antidepressants Administration Route: Oral, Intravenous, Sublingual, Transdermal Patient Age Group: Pediatric, Adult, Geriatric, Adolescent Prescription Type: Brand Name, Generic, Off-label, Compounded |
| Companies Covered | Pfizer Inc., AbbVie Inc., GlaxoSmithKline, Otsuka Pharmaceutical Co., Ltd., Teva Pharmaceutical Industries Ltd., Eli Lilly and Company, H. Lundbeck A/S, AstraZeneca, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antidepressant Drugs Market Emerging Trajectories
Mechanism diversification beyond monoamine modulation is redefining competitive differentiation, while regulatory frameworks for combination digital-pharmaceutical products are creating new approval categories.
Ketamine-derived rapid-acting antidepressants are integrating into acute crisis intervention protocols and reshaping emergency psychiatric care standards. Hospital-based psychiatric units and crisis stabilization centers are adopting these agents for suicidal ideation reduction within 24-hour windows. This integration is compressing the traditional 4-6 week therapeutic onset expectation that has constrained SSRI prescribing logic for decades.
FDA breakthrough therapy designation for novel antidepressant mechanisms is compressing Phase 3 trial requirements and accelerating advisory committee scheduling. This regulatory pathway rewards drugs demonstrating substantial improvement over available therapy on clinically meaningful endpoints. European sponsors are responding by prioritizing US-first launch sequencing, creating EMA access lag for patients in Germany, France, and Italy.
Psychiatrists are consolidating prescribing decisions within large health system formularies rather than maintaining independent practice autonomy. Academic medical centers and integrated delivery networks are replacing solo practitioners as the primary volume channel for branded antidepressant access. This concentration is most visible in the United States, where vertical health system consolidation has compressed the number of independent psychiatric prescribers by over one-third in major metropolitan markets.
Antidepressant Drugs Market Segmentation
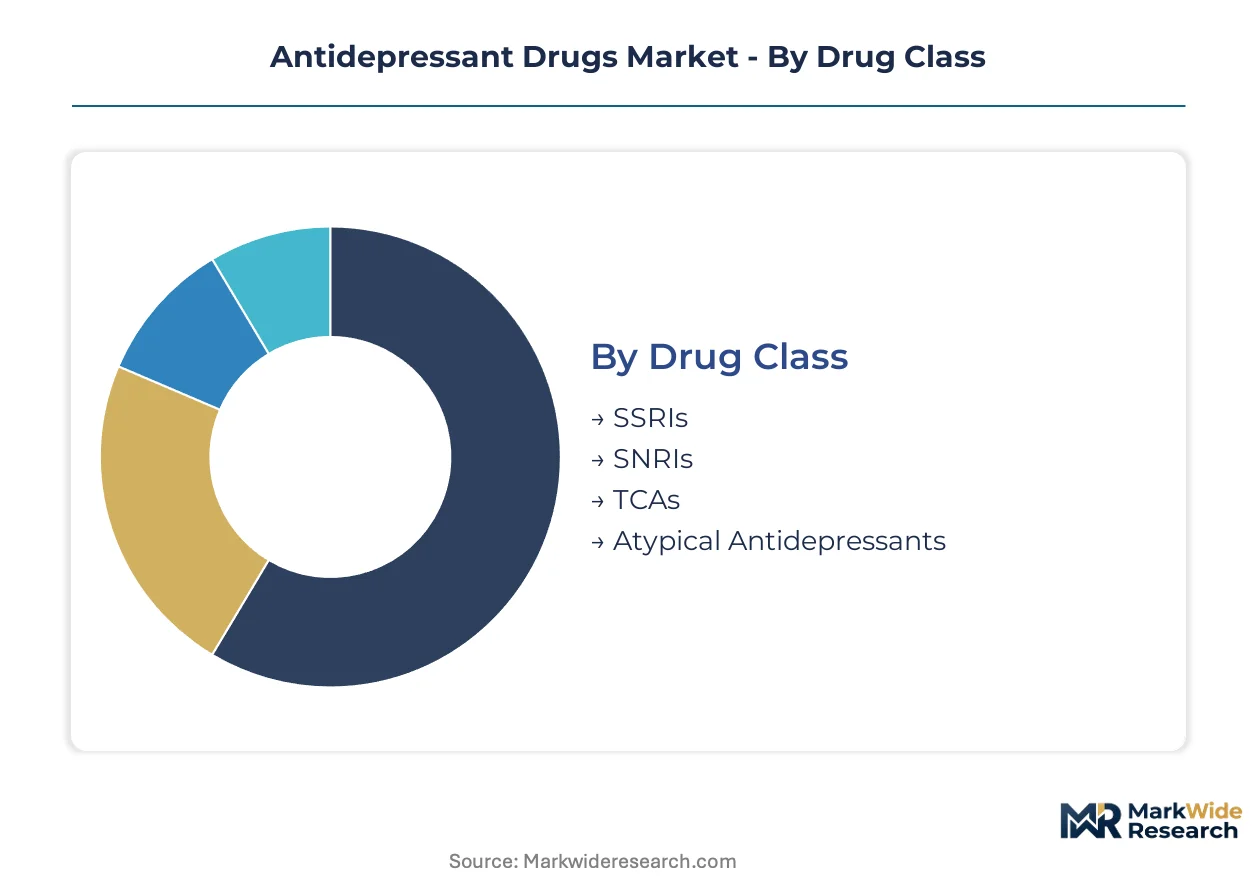
Antidepressant market segmentation reveals how prescribing economics fragment across mechanism maturity, delivery innovation, and patient risk stratification. Supply concentration in oral formulations contrasts with emerging capacity in rapid-acting delivery systems.
Drug Class:
Manufacturing infrastructure clusters around established monoamine modulators while novel mechanism capacity remains concentrated among specialty API producers.
- SSRIs:Selective serotonin reuptake inhibitors such as sertraline and escitalopram dominate outpatient prescribing volumes through extensive generic availability. United States health systems absorb the majority of global manufacturing output due to high per-capita utilization rates and reimbursement density.
- SNRIs:Dual serotonin-norepinephrine reuptake inhibitors including duloxetine and venlafaxine command premium positioning in chronic pain comorbidity populations. European markets concentrate demand through EMA centralized procurement frameworks.
- TCAs:Tricyclic antidepressants retain niche utility in neuropathic pain and migraine prophylaxis despite cardiovascular safety limitations.
- Atypical Antidepressants:Mechanism-diverse agents including bupropion and mirtazapine address specific side-effect intolerance profiles.
SSRIs absorb the bulk of installed capacity; Atypical Antidepressants is expanding most quickly.
Administration Route:
Cost tier differentiation separates commoditized oral tablets from premium-priced rapid-onset delivery systems requiring specialized manufacturing infrastructure.
- Oral:Tablet and capsule formulations achieve steady-state plasma concentrations through hepatic first-pass metabolism, dominating maintenance therapy protocols. India and China supply the majority of API feedstock for this category.
- Intravenous:Esketamine and ketamine infusions require hospital-based administration infrastructure for acute suicidal ideation intervention. United States academic medical centers concentrate adoption through FDA Risk Evaluation and Mitigation Strategy programs.
- Sublingual:Rapid buccal absorption formulations bypass gastrointestinal metabolism for faster therapeutic onset.
- Transdermal:Patch-based delivery systems offer steady plasma concentration profiles for adherence-challenged populations.
Oral formulations retain dominant volume share; Intravenous delivery is gaining share fastest among hospital-based psychiatric units.
Patient Age Group:
Application-specific risk profiles drive regulatory divergence across developmental stages, with FDA boxed warnings constraining pediatric access.
- Adult:Patients aged 18-64 represent the core commercial volume channel with established reimbursement pathways and formulary access. United States commercial payers and Medicare Part D programs concentrate demand.
- Geriatric:Elderly populations require modified dosing protocols due to pharmacokinetic changes and polypharmacy interactions. Japan's aging demographic concentrates specialty formulation demand through PMDA geriatric safety guidelines.
- Pediatric:Childhood depression indications face stringent FDA efficacy requirements and suicidality monitoring protocols.
- Adolescent:Teenage populations occupy a regulatory middle ground with approved SSRIs but restricted access to novel mechanisms.
Adult populations absorb the bulk of prescribing volume; Geriatric applications show the steepest expansion trajectory among aging developed markets.
Prescription Type:
Margin stratification separates commoditized generic volume from brand-name premium capture in treatment-resistant subpopulations.
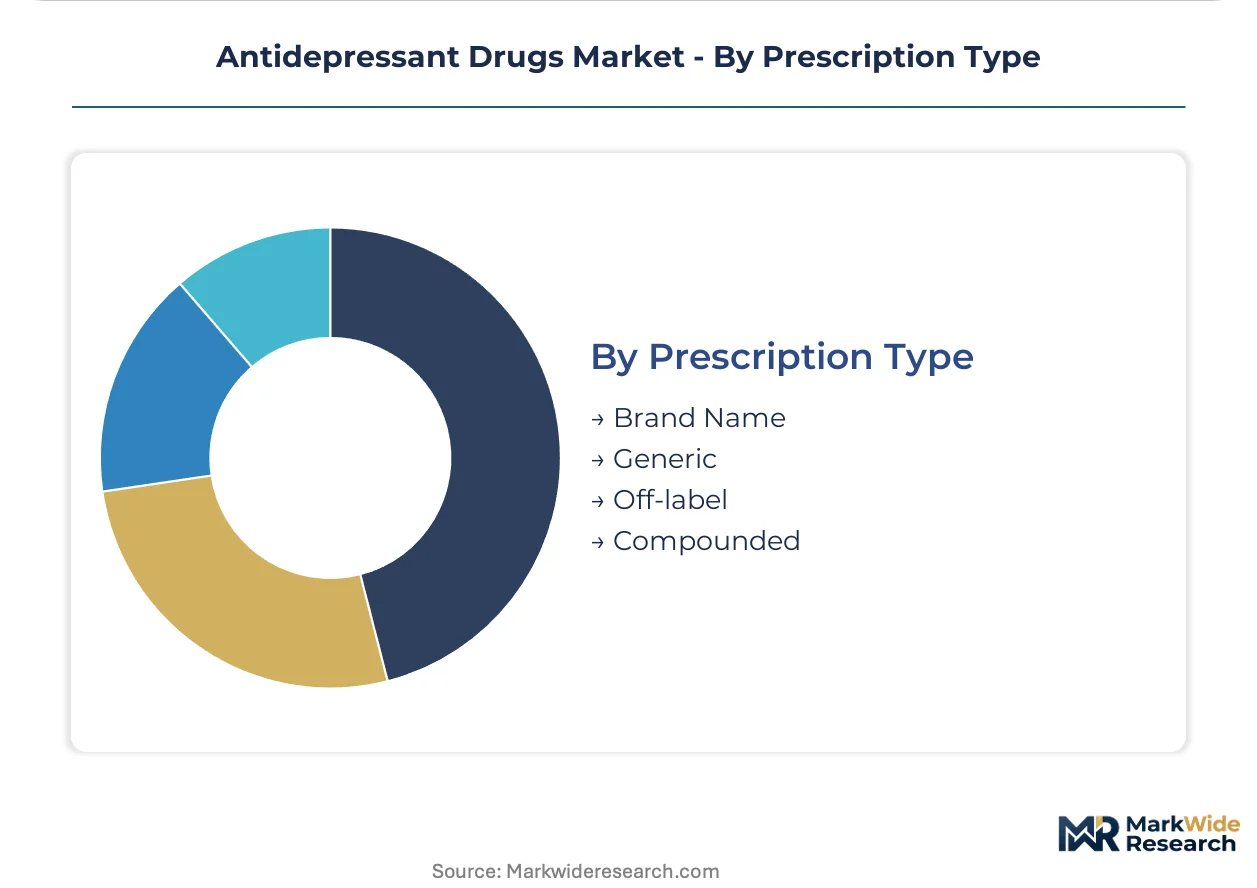
- Generic:Bioequivalent formulations of expired-patent SSRIs and SNRIs command unit volume leadership through pharmacy benefit manager tiering. United States Medicaid programs and European national health services concentrate procurement.
- Brand Name:Patent-protected novel mechanisms including glutamatergic modulators retain premium pricing through prior authorization requirements. Specialty pharmacy distribution channels capture margin in United States commercial markets.
- Off-label:Non-indication prescribing extends antidepressant utility to anxiety, insomnia, and chronic pain populations.
- Compounded:Pharmacy-formulated customized doses address specific patient intolerance or combination requirements.
Generic prescriptions absorb the bulk of unit volume; Brand Name agents command the fastest value expansion among refractory depression protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antidepressant production clusters in India and China for API supply, while consumption concentrates in the United States and Western Europe where reimbursement density supports premium formulation uptake. This geographic split shapes regulatory divergence and launch sequencing strategies across markets.
United States
Commercial payers and Medicare Part D programs drive antidepressant volume through outpatient mental health clinic networks. FDA Risk Evaluation and Mitigation Strategy protocols govern esketamine distribution, limiting administration to certified treatment centers. The Boston-Cambridge corridor concentrates psychiatric research infrastructure where academic medical centers pilot novel glutamatergic protocols.
Germany
EMA centralized marketing authorization streamlines antidepressant access across national health insurance funds. The country's statutory health system applies reference pricing pressure on generic SSRIs while preserving premium reimbursement for treatment-resistant depression indications. North Rhine-Westphalia hosts specialized psychiatric hospital networks that concentrate esketamine adoption.
Japan
PMDA geriatric safety guidelines shape antidepressant dosing protocols for the country's aging demographic. Ministry of Health, Labour and Welfare reimbursement lists prioritize formulations with established cardiovascular safety profiles. The Kanto region around Tokyo concentrates specialist psychiatrist density and university hospital prescribing authority.
India
CDSCO manufacturing licenses support domestic API production for global SSRI and SNRI supply chains. The country's national mental health program expands outpatient psychiatric access through district hospital integration. Gujarat and Maharashtra host contract manufacturing clusters serving European and North American generic markets.
United Kingdom
NICE technology appraisals determine antidepressant formulary access within National Health Service trusts. The Medicines and Healthcare products Regulatory Agency maintains post-market surveillance for suicidality signals across pediatric and adolescent populations. London's academic medical centers concentrate specialist treatment-resistant depression referral pathways.
Antidepressant Drugs Market Vendor Landscape
Top-tier vendors anchor premium novel-mechanism portfolios, while mid-tier generic manufacturers compete on API cost and supply security. The market exhibits tiered consolidation with three to five multinational firms commanding branded antidepressant revenue and fragmented Indian and Chinese suppliers dominating commoditized feedstock. Strategic archetypes include integrated pharmaceutical conglomerates with psychiatric franchises, specialty neuroscience pure-plays, and vertically integrated API-to-formulation operators. Competitive dynamics center on M&A activity targeting glutamatergic mechanism pipelines and strategic partnerships pairing pharmacological agents with digital therapeutic platforms.
Within the integrated pharmaceutical tier, Pfizer Inc., Eli Lilly and Company, and AbbVie Inc. occupy positions defined by psychiatric portfolio breadth and commercial infrastructure density. Pfizer's established formulary relationships exemplify legacy market presence, while Eli Lilly represents R&D intensity in novel mechanism antidepressants. AbbVie anchors neuroscience specialization through dedicated commercial teams. H. Lundbeck A/S and Otsuka Pharmaceutical Co., Ltd. occupy the specialty pure-play archetype with focused CNS development pipelines. Teva Pharmaceutical Industries Ltd. represents generic-scale manufacturing with vertical API control.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| GlaxoSmithKline |
| Otsuka Pharmaceutical Co., Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Eli Lilly and Company |
| H. Lundbeck A/S |
| AstraZeneca |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Captive API production in India and China anchors supply security for generic manufacturers while simultaneously constraining pricing power for formulation specialists lacking backward integration. This geographic concentration of active pharmaceutical ingredient capacity creates tiered margin structures where vertically integrated players capture value upstream, while pure-play formulators face commoditization pressure in downstream markets.
Pricing Analysis
Margin tightening in oral SSRI generics reflects FDA bioequivalence standards that prevent meaningful product differentiation. Three-tier pricing structure across premium intravenous esketamine, standard branded oral formulations, and economy generic tablets separates value capture across treatment-resistant and first-line populations. Cost-down pressure on generic sertraline and fluoxetine accelerates because Indian API suppliers compete on volume scale. Medicaid programs exhibit highest price sensitivity; academic medical centers with REMS certification demonstrate lowest sensitivity for rapid-acting mechanisms.
Supply Chain Analysis
CDSCO and NMPA manufacturing certifications gate entry for API suppliers serving regulated markets, creating qualification moats that protect incumbent feedstock producers. Active pharmaceutical ingredient production concentrates in India, China, and selected European facilities for high-potency specialty compounds. Formulation manufacturing draws from Chinese chemical intermediates, Indian bulk actives, and US/EU excipient supply. Single-source vulnerability persists for esketamine API given limited qualified manufacturers. Distribution runs through specialty pharmacy channels for branded agents and retail pharmacy networks for generic volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antidepressant market operates as a cost-of-compliance story where FDA Risk Evaluation and Mitigation Strategy protocols erect substantial barriers to entry, protecting certified treatment centers and their supplier relationships from unqualified competitors.
For Market Incumbents: Anticipate glutamatergic mechanism entrants compressing formulary access for mature SSRI portfolios by accelerating esketamine capacity expansion in certified academic medical centers. Prioritize backward integration into Indian API supply to defend margin position against generic price erosion. Channel control through specialty pharmacy partnerships represents the critical lever for preserving premium access in treatment-resistant protocols. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for novel rapid-acting antidepressants to bypass traditional Phase 3 timelines and secure accelerated advisory committee scheduling. Telepsychiatry prescribing platforms represent the most penetrable channel for capturing chronic medication management encounters lost to appointment non-adherence. A digital therapeutics pairing strategy with EU MDR-governed software-as-medical-device combinations offers the strongest go-to-market angle for reimbursement expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty neuroscience pure-plays with late-stage glutamatergic pipelines and established psychiatric commercial infrastructure. Long-term viability across the analysis window favors vertically integrated operators controlling API supply through Indian manufacturing subsidiaries. The signal to watch is EMA centralized marketing authorization lag relative to FDA approval, as European access delays compress valuation multiples for US-first launch strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase 3 requirements for novel mechanisms. |
| Manufacturing Scale-Up | Esketamine REMS-certified capacity expansion captures acute crisis intervention volume. |
| Licensing Agreement | Digital therapeutics pairings with EU MDR software create new reimbursement categories. |
| Pipeline Diversification | Glutamatergic mechanism research opens therapeutic avenues for treatment-resistant depression. |
| Reimbursement Strategy | Prior authorization protocols for novel agents secure premium positioning in commercial formularies. |
Methodological Framework
Document review covered FDA filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov antidepressant protocols, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors at US commercial payers, and hospital procurement managers specializing in psychiatric medication. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to ensure consistency across estimation approaches.
Historical prescription dispensing data from CMS Medicare Part D and commercial pharmacy benefit managers were cross-referenced against primary panel input from payer access specialists. Segmentation dimensions modeled include drug class mechanism, administration route, patient age group, prescription type, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for pipeline entry probability. Forecast inputs incorporated FDA advisory committee scheduling patterns and EMA centralized procedure timelines.
The model assumes a particular technology adoption path for rapid-acting antidepressants; alternative pathways for psychedelic-assisted therapy would alter the outlook for esketamine market penetration. Forecasts reflect assumptions regarding reimbursement coding alignment and step-therapy protocol evolution. A model refresh is warranted upon material change in FDA breakthrough therapy designation criteria or EMA access lag duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Cardiometabolic Drugs Market