
 Europe Ophthalmology Drug and Device Market | 2026-2036
Europe Ophthalmology Drug and Device Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ophthalmology Drug and Device Market Foresight
Consolidation among hospital purchasing alliances is realigning procurement power across Northern Europe. Alcon leverages its surgical device portfolio to sustain long-term contracts with centralized hospital procurement bodies. Carl Zeiss Meditec AG anchors the diagnostic imaging segment through its dominance in optical coherence tomography platforms. Johnson & Johnson Vision competes aggressively in the contact lens space, while Santen Pharmaceutical Co., Ltd. specializes in prescription ophthalmic pharmaceuticals for chronic conditions.
Europe ophthalmology drugs and devices encompass pharmaceutical formulations for ocular disease management and precision-engineered instruments for diagnosis, treatment, and vision correction, including intraocular lenses with specific dioptric powers and laser systems calibrated to sub-micrometer accuracy for corneal reshaping. These products serve to preserve visual function, restore refractive clarity, and halt progression of degenerative retinal conditions across clinical and surgical settings. Anti-VEGF therapies command substantial margin pools due to recurring administration protocols in age-related macular degeneration, while diagnostic imaging technology leads in R&D intensity as artificial intelligence integration reshapes screening workflows. Intraocular lenses represent a mature, high-volume segment where premium toric and multifocal designs differentiate pricing tiers, and laser therapy systems occupy a growth corridor driven by femtosecond platform upgrades in cataract and refractive surgery suites.
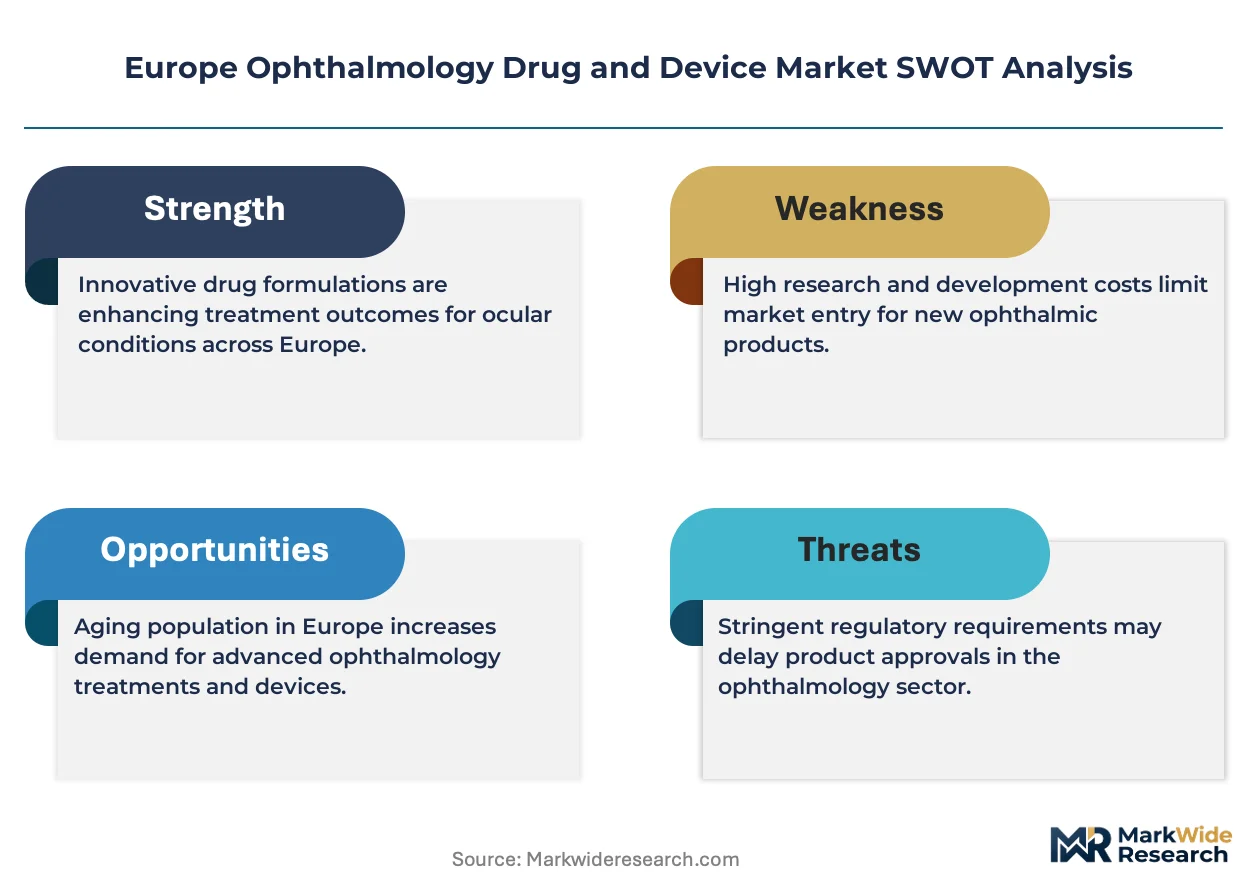
The EU Medical Device Regulation (MDR) and CE marking framework govern market access for surgical devices and diagnostic platforms, requiring enhanced clinical evidence and post-market surveillance that elevates compliance costs for manufacturers. The European Medicines Agency (EMA) oversees ophthalmic drug approvals, while national regulators such as Germany's BfArM and France's ANSM enforce pharmacovigilance standards that shape prescribing patterns for biologic therapies. Stakeholders must monitor how the EU AI Act intersects with diagnostic imaging software classifications, as algorithm-based retinal screening tools face emerging conformity assessment pathways that will determine speed to market across European territories.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing market access timelines for intraocular lenses and femtosecond laser platforms, forcing manufacturers to rebuild clinical evidence portfolios while hospital procurement alliances consolidate purchasing power across Northern European networks.
Growth Catalysts
- EMA accelerated assessment pathways:Biologic ophthalmic therapies for rare retinal conditions receive priority review, shortening time-to-reimbursement in Germany and France.
- University hospital networks:Germany's integrated eye care delivery models combine drug therapy with surgical intervention, creating bundled procurement opportunities for device-drug combinations.
- Optical coherence tomography with AI integration:Diagnostic imaging platforms incorporating algorithm-based screening are expanding retinal disease detection capacity in overstretched public health systems.
Market Restraints
- MDR clinical evidence requirements:Enhanced post-market surveillance obligations for intraocular lenses elevate compliance costs and extend certification timelines by 18-24 months.
- Silicone hydrogel raw material concentration:Contact lens manufacturers face input cost volatility due to dependence on Asian petrochemical supply chains for specialized polymer feedstocks.
- Excimer laser platform obsolescence:Refractive surgery centers hesitate to upgrade capital equipment amid uncertainty over SMILE procedure adoption curves.
Strategic Opportunities
- Poland and Czech Republic outpatient clinics:Underpenetrated markets in Central Europe present first-mover advantages for premium intraocular lens portfolios as private ophthalmology chains expand.
- EU AI Act diagnostic software classification:Algorithm-based retinal screening tools face emerging conformity pathways that will determine speed-to-market for early entrants.
- Home-based monitoring devices:Teleophthalmology reimbursement frameworks in the Netherlands and Denmark enable remote intraocular pressure monitoring for glaucoma patients.
Industry Challenges
- Vitreoretinal surgeon training pipelines:European fellowship programs produce insufficient specialists to meet anti-VEGF administration demand in aging populations.
- Femtosecond laser platform integration:Cataract surgery suites face workflow disruption and staff retraining costs when upgrading from manual phacoemulsification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ophthalmology Drug and Device Market |
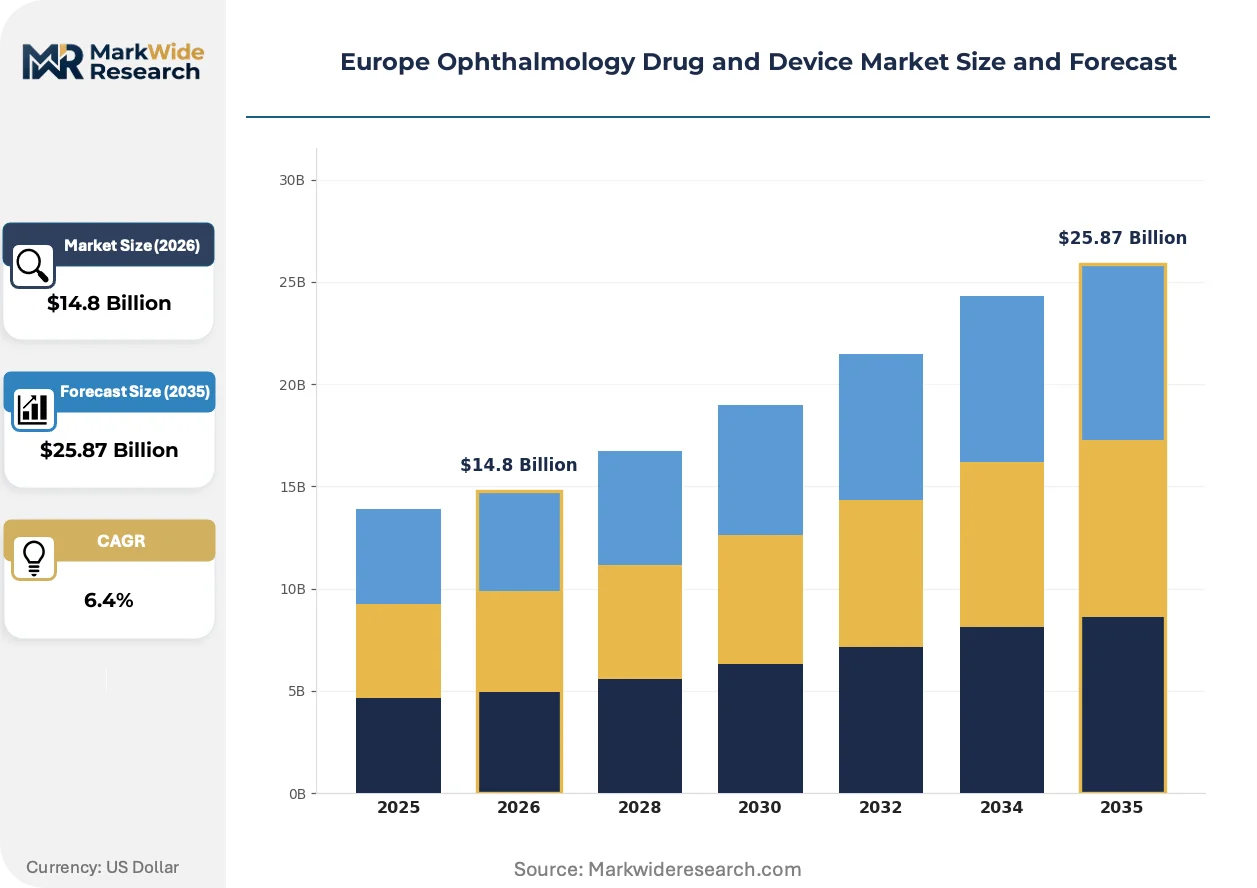
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiglaucoma Medications, Anti-VEGF Therapies, Contact Lenses, Intraocular Lenses Technology: Laser Therapy, Biotechnology, Surgical Devices, Diagnostic Imaging End User: Hospitals, Outpatient Clinics, Specialty Ophthalmology Centers, Research Institutions Application: Refractive Surgery, Cataract Treatment, AMD Treatment, Diabetic Retinopathy Care |
| Companies Covered | EssilorLuxottica, Pfizer, Alcon, Topcon Corporation, Santen Pharmaceutical Co., Ltd., Johnson & Johnson Vision, Novartis AG, Nidek Co. Ltd, Carl Zeiss Meditec AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ophthalmology Drug and Device Market Shifts & Advancements
Artificial intelligence integration is fundamentally altering diagnostic imaging workflows, while regulatory frameworks for software-based medical devices create new compliance architectures. These forces are compressing traditional equipment replacement cycles and redrawing competitive boundaries between hardware manufacturers and algorithm developers.
Extended depth-of-focus intraocular lenses are expanding into presbyopia-correcting cataract procedures across French and German university hospitals. Premium lens adopters now represent 35-40% of cataract volumes in these networks. The technology is expanding into standard-of-care territory previously occupied by monofocal designs, pressuring mid-tier pricing structures.
The EU AI Act intersects with MDR requirements for diagnostic imaging software, creating dual conformity assessment obligations for algorithm-based retinal screening tools. Manufacturers must demonstrate clinical validation across diverse European patient populations while navigating divergent national implementation timelines. Germany's BfArM and France's ANSM are developing divergent guidance documents, fragmenting market access predictability.
Hospital purchasing alliances in Northern Europe are consolidating ophthalmology device procurement into multi-year framework agreements. Independent clinics and smaller regional hospitals lose negotiating leverage as centralized bodies aggregate volume. This concentration is most visible in the United Kingdom's NHS Supply Chain and Germany's university hospital purchasing cooperatives, where bundled drug-device contracts now dominate tender specifications.
Europe Ophthalmology Drug and Device Market Segmentation
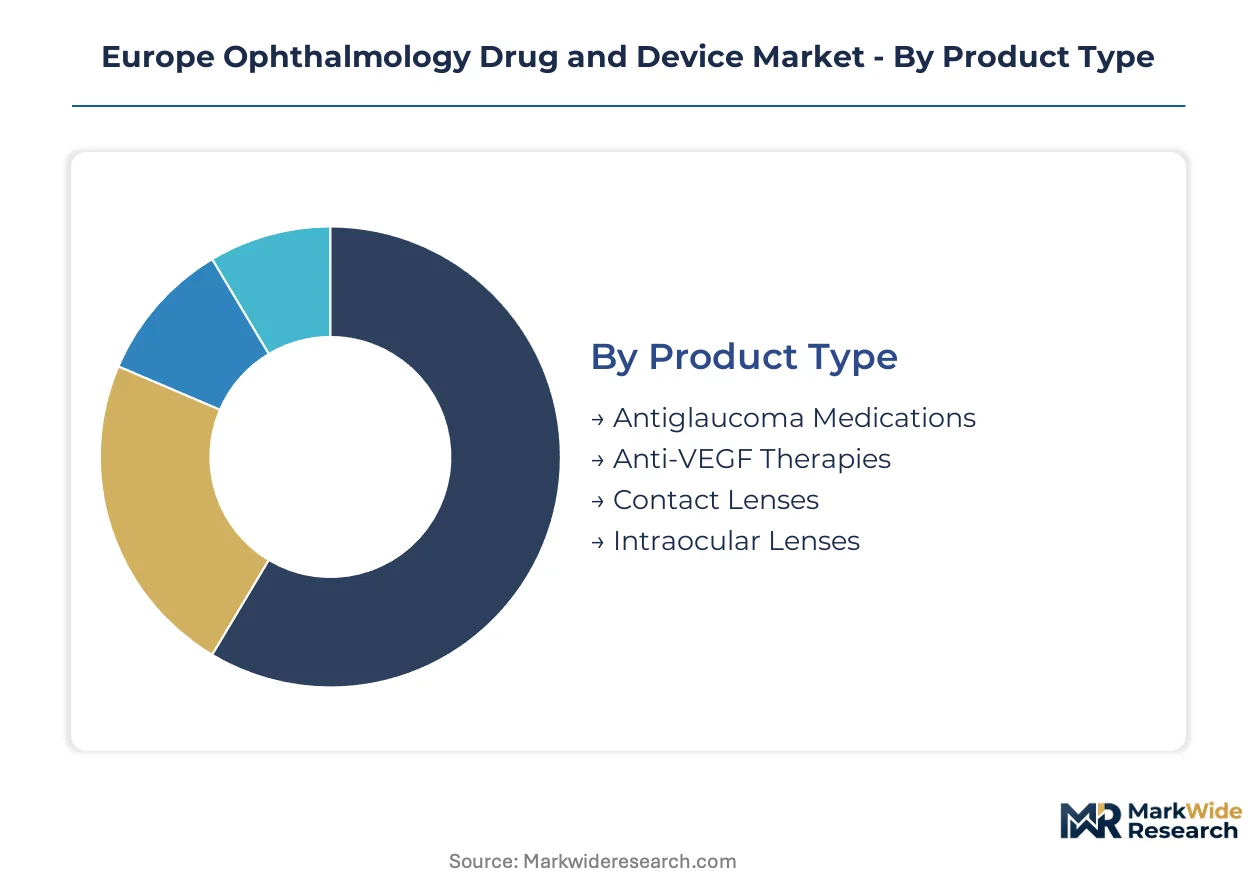
Segmentation in the Europe ophthalmology market reveals divergent margin structures across pharmaceutical and device portfolios. Volume concentration in mature categories contrasts with premium pricing power in advanced surgical and biologic segments. Understanding these splits enables targeted resource allocation across procurement channels and therapeutic areas.
Product Type:
Volume deployment concentrates in high-turnover consumables, while premium biologics command specialized distribution and administration infrastructure.
- Antiglaucoma Medications:Prostaglandin analogs and beta-blockers formulated as topical drops or sustained-release implants. Demand clusters in Germany's statutory health insurance networks where chronic management protocols dominate prescribing patterns.
- Anti-VEGF Therapies:Ranibizumab and aflibercept biologics administered via intravitreal injection for neovascular retinal disease. France's hospital outpatient departments and United Kingdom NHS treatment centers concentrate administration volume amid specialist capacity constraints.
- Contact Lenses:Silicone hydrogel daily disposables and rigid gas-permeable designs for refractive correction. Optical retail chains in the Netherlands and Scandinavia drive replacement schedule adherence through subscription fulfillment models.
- Intraocular Lenses:Monofocal, toric, and multifocal designs with specific dioptric powers for cataract replacement. German university hospital networks favor premium extended depth-of-focus variants in bundled surgical contracts.
Mature deployment sits with contact lenses and monofocal intraocular lenses. Newer deployment is concentrated in anti-VEGF therapies and premium toric-multifocal lens combinations.
Technology:
Application setting determines technology selection, with hospital-based capital equipment diverging from office-based diagnostic platforms.
- Laser Therapy:Femtosecond platforms for cataract capsulotomy and corneal flap creation, plus excimer systems for refractive ablation. United Kingdom private refractive surgery chains defer capital upgrades pending clarity on SMILE procedure reimbursement.
- Biotechnology:Gene therapy vectors and sustained-release drug delivery systems for inherited retinal disease. EMA accelerated assessment pathways in Germany and France prioritize rare disease indications with limited therapeutic alternatives.
- Surgical Devices:Phacoemulsification handpieces, vitrectomy systems, and microsurgical instrumentation. Carl Zeiss Meditec and Alcon maintain long-term service contracts with centralized German hospital purchasing cooperatives.
- Diagnostic Imaging:Optical coherence tomography with spectral-domain and swept-source architectures, increasingly incorporating algorithm-based screening. France's ANSM and Germany's BfArM develop divergent guidance for AI-integrated software classification under EU AI Act implementation.
Established installation bases center on phacoemulsification surgical devices. Steepest expansion trajectory belongs to AI-integrated diagnostic imaging platforms facing dual MDR and AI Act conformity obligations.
End User:
Procurement authority concentrates in centralized purchasing bodies, fragmenting access for independent practice operators.
- Hospitals:Acute care institutions with integrated ophthalmology departments performing complex surgical interventions. Germany's university hospital networks bundle drug and device procurement through multi-year framework agreements.
- Outpatient Clinics:Ambulatory surgical centers and community eye care facilities handling high-volume cataract and refractive procedures. Poland and Czech Republic private chains are expanding premium intraocular lens penetration in previously underserved markets.
- Specialty Ophthalmology Centers:Dedicated retinal, glaucoma, and cornea subspecialty practices with concentrated therapeutic expertise. France's regional retinal treatment hubs manage anti-VEGF administration queues through centralized scheduling systems.
- Research Institutions:Academic medical centers and contract research organizations conducting clinical trials for novel therapies. EMA's priority review designations attract early-phase development activity to German and Dutch trial sites.
Volume concentration rests with hospital and outpatient clinic networks. Emerging deployment is shifting toward specialty ophthalmology centers as subspecialization deepens across Northern European markets.
Application:
Reimbursement tiering separates elective refractive procedures from medically necessary retinal and cataract interventions.
- Refractive Surgery:Laser vision correction and lens-based procedures for myopia, hyperopia, and astigmatism. United Kingdom and Spain private clinics compete on femtosecond platform marketing amid consumer financing sensitivity.
- Cataract Treatment:Phacoemulsification with intraocular lens implantation for age-related lens opacification. French and German statutory systems cover monofocal lenses while patients self-fund premium multifocal upgrades.
- AMD Treatment:Anti-VEGF injection protocols for wet age-related macular degeneration. United Kingdom NHS rationing policies restrict treatment frequency, creating private pay overflow capacity.
- Diabetic Retinopathy Care:Panretinal photocoagulation, anti-VEGF therapy, and vitreoretinal surgery for diabetes-related complications. Netherlands and Denmark teleophthalmology programs enable remote screening and referral triage.
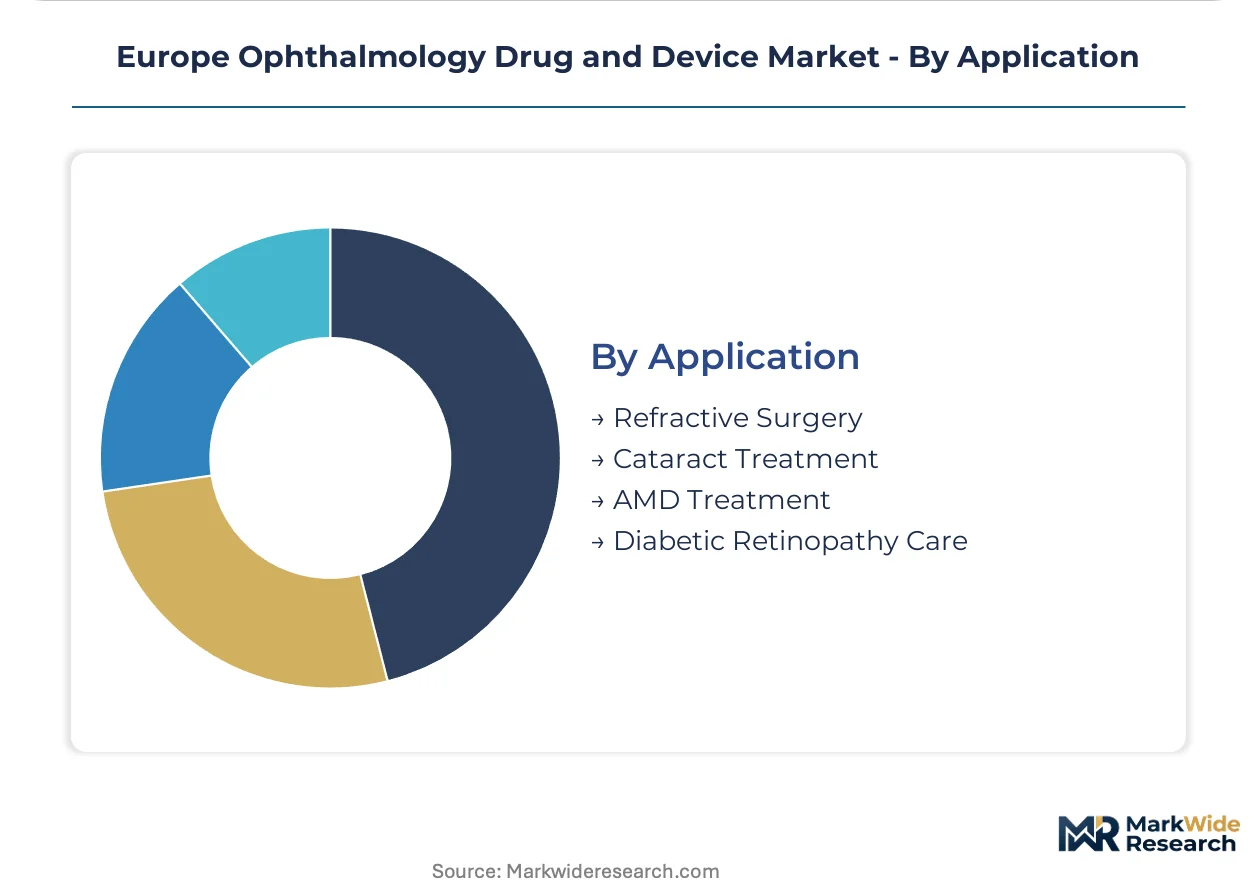
Established procedure volumes concentrate in cataract treatment. Gaining share fastest is diabetic retinopathy care as screening program expansion and diabetes prevalence drive detection rates across European health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university hospital networks concentrate device procurement power through multi-year framework agreements, while France's regional retinal hubs manage anti-VEGF administration queues. The United Kingdom's NHS Supply Chain consolidates ophthalmology tenders into centralized contracts.
Germany
Statutory health insurance networks drive chronic glaucoma management protocols, while university hospital purchasing cooperatives bundle drug-device combinations. BfArM enforces pharmacovigilance standards that shape biologic prescribing patterns. Bavaria's integrated eye care delivery models in Munich and Erlangen combine laser-based surgical intervention with pharmaceutical therapy.
France
Hospital outpatient departments concentrate anti-VEGF administration volume amid specialist capacity constraints. ANSM develops divergent guidance from Germany for AI-integrated diagnostic software classification under EU AI Act implementation. Île-de-France's regional retinal treatment hubs in Paris manage centralized scheduling systems for neovascular disease patients.
United Kingdom
NHS rationing policies restrict AMD treatment frequency, creating private pay overflow capacity for refractive procedures. NHS Supply Chain ophthalmology tenders aggregate volume into multi-year framework agreements. London's private refractive surgery chains defer femtosecond platform upgrades pending SMILE procedure reimbursement clarity.
Netherlands
Teleophthalmology reimbursement frameworks enable remote intraocular pressure monitoring for glaucoma patients. Optical retail chains drive contact lens replacement schedule adherence through subscription fulfillment models. Randstad's outpatient clinic networks expand home-based monitoring device deployment for chronic disease management.
Poland
Private ophthalmology chains expand premium intraocular lens penetration in previously underserved cataract markets. EU MDR compliance timelines compress market access for device manufacturers entering Central Europe. Warsaw and Krakow outpatient clinics present first-mover advantages for toric and multifocal lens portfolios as surgical volumes rise.
Europe Ophthalmology Drug and Device Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue algorithm-based diagnostic software and home monitoring devices. The vendor base stratifies across multinational conglomerates with surgical device portfolios, specialized pharmaceutical firms, and precision optics manufacturers. Three archetypes dominate: diversified healthcare conglomerates leveraging cross-divisional synergies, mid-cap device specialists with long-term hospital service contracts, and pharmaceutical pure-plays focused on chronic ocular disease. Competitive moves concentrate on M&A for AI diagnostic capabilities and strategic partnerships for teleophthalmology platform deployment.
Among diversified healthcare conglomerates, Alcon and Johnson & Johnson Vision represent the integrated surgical-device-and-consumer-optics archetype. Carl Zeiss Meditec AG anchors the precision diagnostic imaging segment. Santen Pharmaceutical Co., Ltd. exemplifies the chronic disease pharmaceutical specialist model.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Pfizer |
| Alcon |
| Topcon Corporation |
| Santen Pharmaceutical Co., Ltd. |
| Johnson & Johnson Vision |
| Novartis AG |
| Nidek Co. Ltd |
| Carl Zeiss Meditec AG |
| Others |
Supply & Pricing Matrix
Vitreoretinal surgeon concentration in Germany's university hospital networks amplifies labor-cost differentials that separate premium bundled surgical contracts from standard cataract reimbursement tiers. This workforce scarcity feeds directly into pricing spreads across intraocular lens categories, where extended depth-of-focus designs command substantial patient self-pay premiums against monofocal baseline coverage.
Pricing Analysis
Volume-vs-margin splits sharply across the European ophthalmology landscape. High-turnover contact lenses and monofocal intraocular lenses operate on per-unit transactional pricing with thin spreads, while anti-VEGF biologics sustain value-based recurring administration models. Three-tier pricing structure across premium, standard, and economy levels separates toric-multifocal combinations from basic monofocal designs, with certification grade under MDR compliance timelines serving as the primary quality differentiator. Pricing pressure stems from hospital purchasing alliance consolidation in Northern Europe, where aggregated tender volumes squeeze mid-tier suppliers. Independent outpatient clinics exhibit highest price sensitivity due to exclusion from framework agreements, while German university hospital networks maintain lowest sensitivity through bundled procurement leverage.
Supply Chain Analysis
Workforce availability constraints in precision optics manufacturing concentrate supply chain nodes in Germany, Switzerland, and Japan for femtosecond laser platforms and diagnostic imaging systems. Raw material dependencies center on Asian petrochemical feedstocks for silicone hydrogel polymers, rare earth elements for laser optical components, and specialized glass substrates for OCT imaging. Single-source vulnerability runs through Taiwanese semiconductor foundries supplying image processing chips for AI-integrated diagnostic platforms. Distribution runs through centralized hospital procurement cooperatives in Germany and NHS Supply Chain frameworks in the United Kingdom, with independent optical retail chains handling contact lens fulfillment in the Netherlands and Scandinavia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European ophthalmology market is becoming a vertical-integration race, with device manufacturers pursuing captive supply of AI diagnostic algorithms and pharmaceutical firms acquiring surgical platform capabilities to capture bundled contract value.
For Market Incumbents: Hedge against algorithm-based diagnostic disruption by acquiring retinal screening software developers before EU AI Act conformity pathways solidify. Secure long-term service contracts with German university hospital purchasing cooperatives to lock out mid-tier competitors. Deepen backward integration into silicone hydrogel polymer production to offset Asian supply chain volatility.
For New Entrants and Emerging Players: Teleophthalmology platform deployment offers the most penetrable white-space entry, particularly in Netherlands and Denmark where reimbursement frameworks already enable remote glaucoma monitoring. Target Poland and Czech Republic outpatient clinic expansion for premium intraocular lens penetration before EU MDR compliance timelines compress market access for later entrants. Pursue direct-to-clinic digital sales channels bypassing consolidated hospital procurement alliances.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-integrated diagnostic imaging specialists given EMA accelerated assessment pathway prioritization for algorithm-based screening tools. Long-term viability over the projection horizon favors firms with dual MDR and AI Act regulatory capabilities. Watch for inflection signals in EU AI Act national implementation divergence between Germany's BfArM and France's ANSM guidance documents.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence requirements for intraocular lenses extend certification timelines and elevate compliance investment thresholds. |
| Hospital System Partnership | German university hospital purchasing cooperatives bundle drug-device combinations into multi-year framework agreements. |
| Software Companion Development | AI-integrated OCT platforms face dual conformity assessment under EU AI Act and MDR regulations. |
| Reimbursement Strategy | EMA accelerated assessment pathways in France and Germany prioritize rare retinal disease biologics. |
| Backward Integration | Contact lens manufacturers seek captive silicone hydrogel polymer supply to reduce Asian petrochemical dependency. |
Research Methodology
Independent corroboration across hospital procurement managers, vitreoretinal surgeons, regulatory affairs specialists, and optical retail chain executives underwrites the qualitative findings. Primary interviews with German university hospital purchasing cooperative administrators, French ANSM policy leads, and Netherlands teleophthalmology program directors combined with secondary validation from EMA submission databases, EU MDR guidance documents, and hospital tender records. Bottom-up procedure volume estimates and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical anti-VEGF administration trends and cataract surgical volumes established the forecast baseline. The quantitative framework models segmentation across product type, technology platform, end-user procurement channel, and application reimbursement tier. CAGRs derive from procedure volume elasticity to aging population demographics, premium lens adoption curves, and AI diagnostic platform deployment rates. Forecast inputs incorporate EU AI Act implementation timelines and MDR transition period compliance bottlenecks.
The model holds under stable regulatory implementation schedules; deviation in EU AI Act national guidance divergence or MDR notified body capacity constraints would shift market access timelines. Forecasts reflect assumptions on surgeon training pipeline output and teleophthalmology reimbursement expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Dacryocystitis Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
North America Ophthalmic Devices and Drugs Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Amblyopia Treatment Market