
 Global Self-Administered Drugs Market | 2026-2036
Global Self-Administered Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self-Administered Drugs Market Foresight
Market Context
The gap between premium biologic injectables and commodity oral tablets is realigning competitive investment across the Global Self-Administered Drugs Market. Novo Nordisk anchors its position through captive supply of GLP-1 receptor agonist delivery systems, while Eli Lilly & Co. differentiates via R&D intensity in automated injection devices. Amgen leverages manufacturing scale for prefilled syringe portfolios, and Sanofi competes through brand strength in insulin pen platforms across European pharmacy chains.
Technical Definition and Segment Structure
Self-administered drugs encompass pharmaceutical formulations engineered for patient-controlled delivery outside clinical supervision, incorporating precise dosing mechanisms, stability profiles for ambient storage, and ergonomic device interfaces that ensure therapeutic adherence without professional assistance. The injectables segment dominates value creation as monoclonal antibodies and peptide hormones require parenteral bioavailability, while inhalers capture expanding share in respiratory diseases through dry-powder and metered-dose innovations. Oral tablets remain the volume backbone across cardiovascular disorders and pain management, though margin pools concentrate in specialty auto-injector formats for biologic therapy areas.
Regulatory Framework and Outlook
FDA combination product regulations, EMA MDR device-drug interface requirements, and WHO prequalification standards for fixed-dose delivery systems collectively elevate barriers to market entry while accelerating substitution toward validated self-administration platforms. Japan's PMDA and China's NMPA are tightening pharmacovigilance for at-home biologics, forcing manufacturers to integrate real-world adherence data into post-market surveillance. Stakeholders must monitor divergence between FDA's streamlined 510(k) auto-injector pathway and EMA's escalating clinical evidence demands for patient-handling studies.
Market Dynamics
Patient preference for home-based therapy is compressing institutional care volumes and forcing manufacturers to redesign delivery systems for untrained users rather than clinical professionals. This demand rotation is absorbing R&D budgets previously allocated to hospital-administered formulations.
Growth Catalysts
- Reimbursement framework expansion:Germany's statutory health insurance now covers continuous glucose monitoring with insulin pen co-prescribing, eliminating out-of-pocket barriers for Type 2 diabetes patients transitioning to self-managed care.
- Biologics stability engineering:Room-temperature monoclonal antibody formulations are removing cold-chain dependency for rheumatoid arthritis therapies, enabling pharmacy dispensing without specialized logistics.
- Japan's aging demographics:METI incentives for home medical devices are accelerating PMDA fast-track approvals for elderly-friendly auto-injector interfaces in Tokyo and Osaka prefectures.
Market Restraints
- Glass primary packaging concentration:Borosilicate syringe barrel supply is consolidating among three European specialty glass manufacturers, creating single-source vulnerability for prefilled biologic delivery systems.
- EMA MDR interface requirements:Device-drug combination product dossiers now require patient-handling studies that add 18-24 months to approval timelines for novel injection platforms.
- Needle phobia substitution:Oral small-molecule JAK inhibitors for psoriasis are capturing patients who would otherwise initiate IL-17 biologic self-injection regimens.
Strategic Opportunities
- Brazil's pharmacy channel modernization:ANVISA's 2023 self-medication category expansion permits behind-the-counter dispensing of pre-filled adrenaline auto-injectors without prescription renewal requirements.
- Connected device convergence:Bluetooth-enabled dose-capture technology paired with cloud adherence platforms is creating subscription revenue streams alongside disposable hardware sales.
- Saudi Arabia's healthcare privatization:SFDA regulatory harmonization with FDA 510(k) pathways is attracting Western manufacturers to establish local assembly for Gulf Cooperation Council distribution.
Industry Challenges
- Human factors engineering talent scarcity:Industrial designers with ISO 14955 usability certification command premium compensation, constraining mid-size manufacturers' device development pipelines.
- Legacy ERP integration friction:Pharmaceutical batch record systems require customization to capture real-world adherence data from connected delivery devices for PMDA pharmacovigilance submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self-Administered Drugs Market |
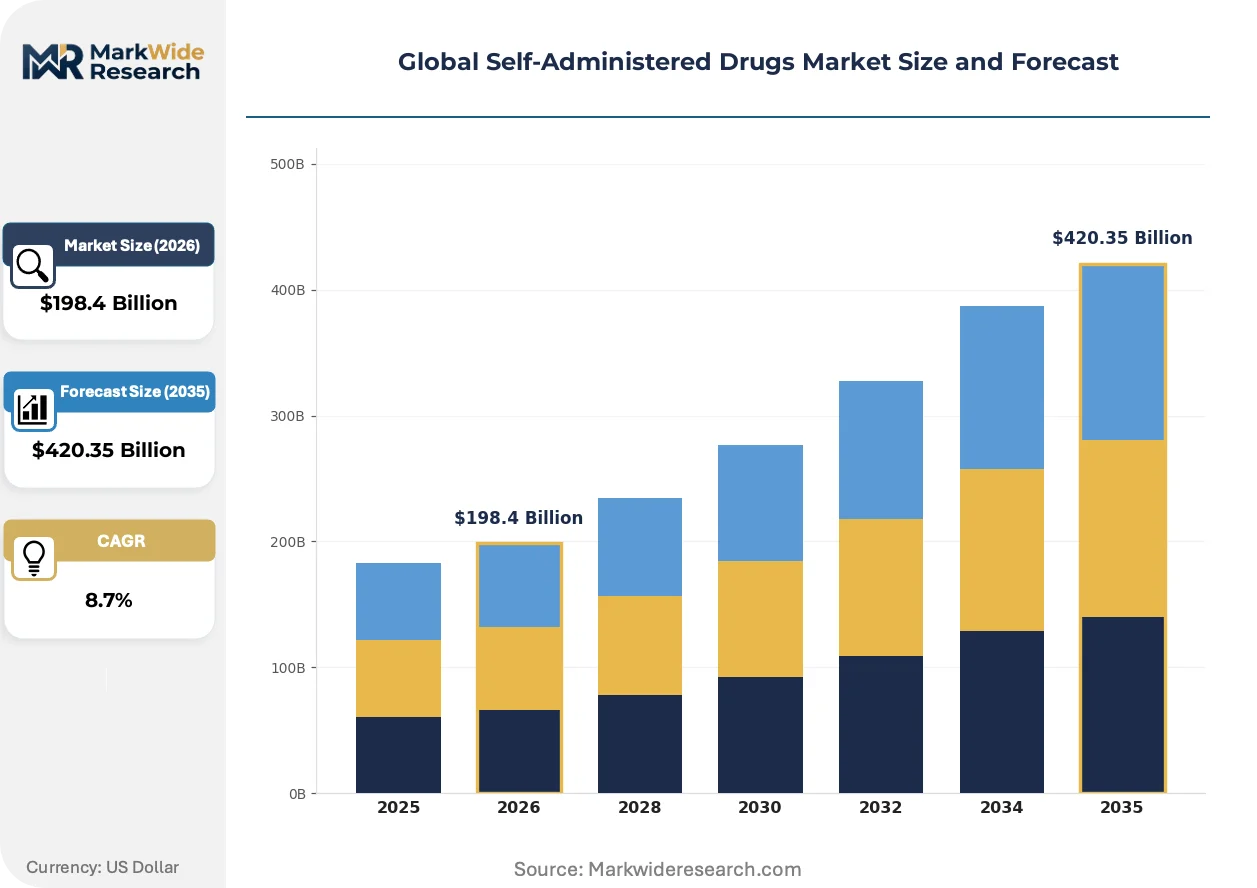
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $420.35 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Injectables, Oral Tablets, Topical Creams, Inhalers, Nasal Sprays Therapy Area: Diabetes, Respiratory Diseases, Dermatology, Cardiovascular Disorders, Pain Management End User: Home Care, Specialty Clinics, Pharmacy Chains, Long-term Care Facilities Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct-to-Consumer |
| Companies Covered | GlaxoSmithKline, Amgen, Novo Nordisk, BD, Novartis, Eli Lilly & Co., Pfizer, Takeda Pharmaceutical, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self-Administered Drugs Market Shifts & Advancements
Device intelligence and formulation stability are converging to eliminate the clinical intermediary from chronic disease management. This dual-track evolution is reallocating value capture from healthcare providers to manufacturers with integrated platform capabilities.
Connected auto-injectors with embedded sensors are absorbing adherence monitoring functions previously performed by nursing staff. Rheumatology practices in the United States are deploying these devices to reduce infusion center overhead. The technology is absorbing compliance verification into the delivery hardware itself, compressing the role of traditional patient support programs.
EMA's Medical Device Regulation is mandating clinical evidence for patient handling errors in combination product submissions. Manufacturers must now submit use-related risk analyses that quantify failure modes in simulated home environments. Prefilled syringe portfolios targeting European markets are absorbing additional usability engineering costs to satisfy notified body expectations for layperson administration.
Direct-to-patient pharmacy fulfillment is displacing wholesale distribution for maintenance biologics. Specialty pharmacies in Germany and the United Kingdom are capturing scripts through digital prescriber platforms that bypass hospital outpatient dispensing. Rheumatoid arthritis and multiple sclerosis patients in these markets now receive temperature-controlled shipments to residential addresses with nurse hotline support bundled into the dispensing fee.
Global Self-Administered Drugs Market Segmentation
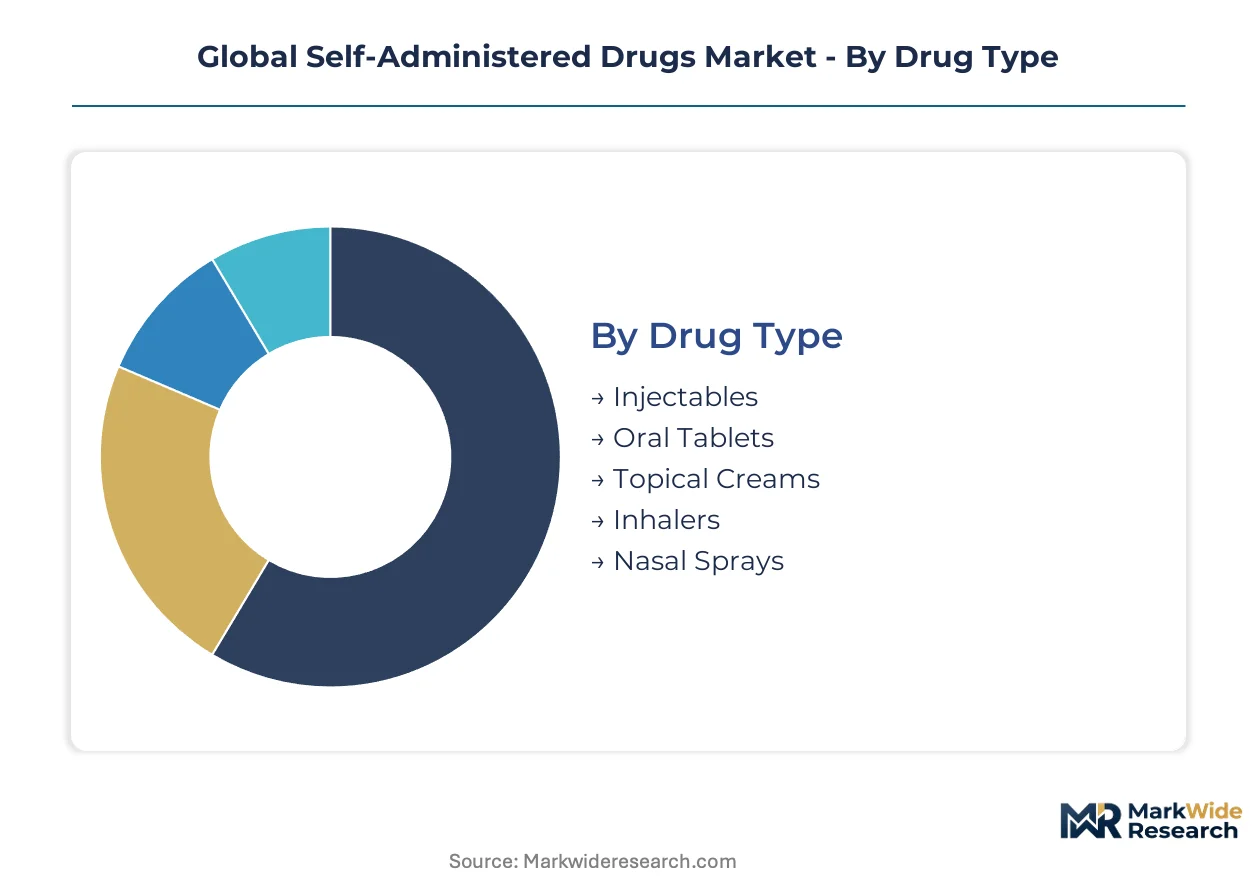
Segmentation in self-administered drugs reveals how formulation requirements, patient capability profiles, and reimbursement pathways split manufacturing investment across incompatible technical platforms. Each dimension carries distinct regulatory burdens and margin structures that reshape competitive positioning.
Drug Type:
Supply concentration in primary packaging materials and device engineering talent pools determines which formats absorb capital investment versus which remain commoditized.
- Injectables:Monoclonal antibodies and peptide hormones require parenteral bioavailability through prefilled syringes or auto-injector devices. Demand concentrates in Germany and Japan as statutory insurers expand reimbursement for at-home biologic administration in Type 2 diabetes and rheumatoid arthritis.
- Oral Tablets:Solid dosage forms dominate cardiovascular and pain management volumes through immediate-release and extended-release matrix technologies. United States pharmacy chains capture recurring refill volumes through 90-day maintenance dispensing programs that bypass hospital outpatient departments.
- Topical Creams:Transdermal formulations for dermatology and localized pain deliver APIs through permeation-enhanced emulsion bases.
- Inhalers:Dry-powder and metered-dose devices for respiratory diseases incorporate breath-actuated mechanisms and dose counters.
- Nasal Sprays:Intranasal delivery systems for migraine and hormone therapies exploit vascularized mucosal absorption kinetics.
Injectables absorb the bulk of installed capacity; inhalers are expanding most quickly as respiratory device platforms capture connected-dose monitoring subscriptions.
Therapy Area:
Cost tier stratification separates chronic maintenance indications requiring continuous supply security from acute episodic conditions with lower switching barriers.
- Diabetes:Insulin analogs and GLP-1 receptor agonists drive auto-injector innovation through pen devices and continuous glucose monitor integration. Germany's statutory health insurance now covers co-prescribing of monitoring systems with insulin delivery, eliminating out-of-pocket friction for self-managed care transitions.
- Respiratory Diseases:Asthma and COPD maintenance therapies rely on corticosteroid-long-acting beta agonist combinations in breath-actuated inhalers. United States specialty pharmacies are displacing hospital dispensing through direct-to-patient temperature-controlled shipments with bundled nurse hotline support.
- Dermatology:Biologic self-injection for psoriasis competes with oral JAK inhibitors that capture needle-averse patients.
- Cardiovascular Disorders:Anticoagulant and antihypertensive oral tablets sustain high-volume manufacturing through established solid-dose infrastructure.
- Pain Management:Opioid and non-opioid oral formulations face tightening prescription surveillance that constrains refill automation.
Diabetes commands the deepest manufacturing investment; respiratory diseases are climbing the fastest as connected inhaler platforms capture adherence data revenue streams.
End User:
Customer type determines device complexity tolerance, training burden, and the economics of remote support infrastructure.
- Home Care:Untrained patients administer therapy through ergonomic devices with embedded error-prevention features. Japan's METI incentives for elderly-friendly medical devices are accelerating PMDA fast-track approvals for simplified auto-injector interfaces in Tokyo and Osaka prefectures.
- Specialty Clinics:Supervised initiation of biologic therapy transitions patients to independent administration after dose tolerance verification.
- Pharmacy Chains:United Kingdom and German retail pharmacies capture maintenance biologic scripts through digital prescriber platforms that bypass hospital outpatient dispensing.
- Long-term Care Facilities:Staff-mediated administration of oral and injectable therapies serves populations with cognitive or physical limitations.
Home care absorbs the bulk of installed capacity; pharmacy chains are gaining share fastest as direct-to-patient fulfillment displaces wholesale distribution.
Distribution Channel:
Margin structure and regulatory custody requirements fragment logistics investment across temperature-controlled and ambient supply chains.
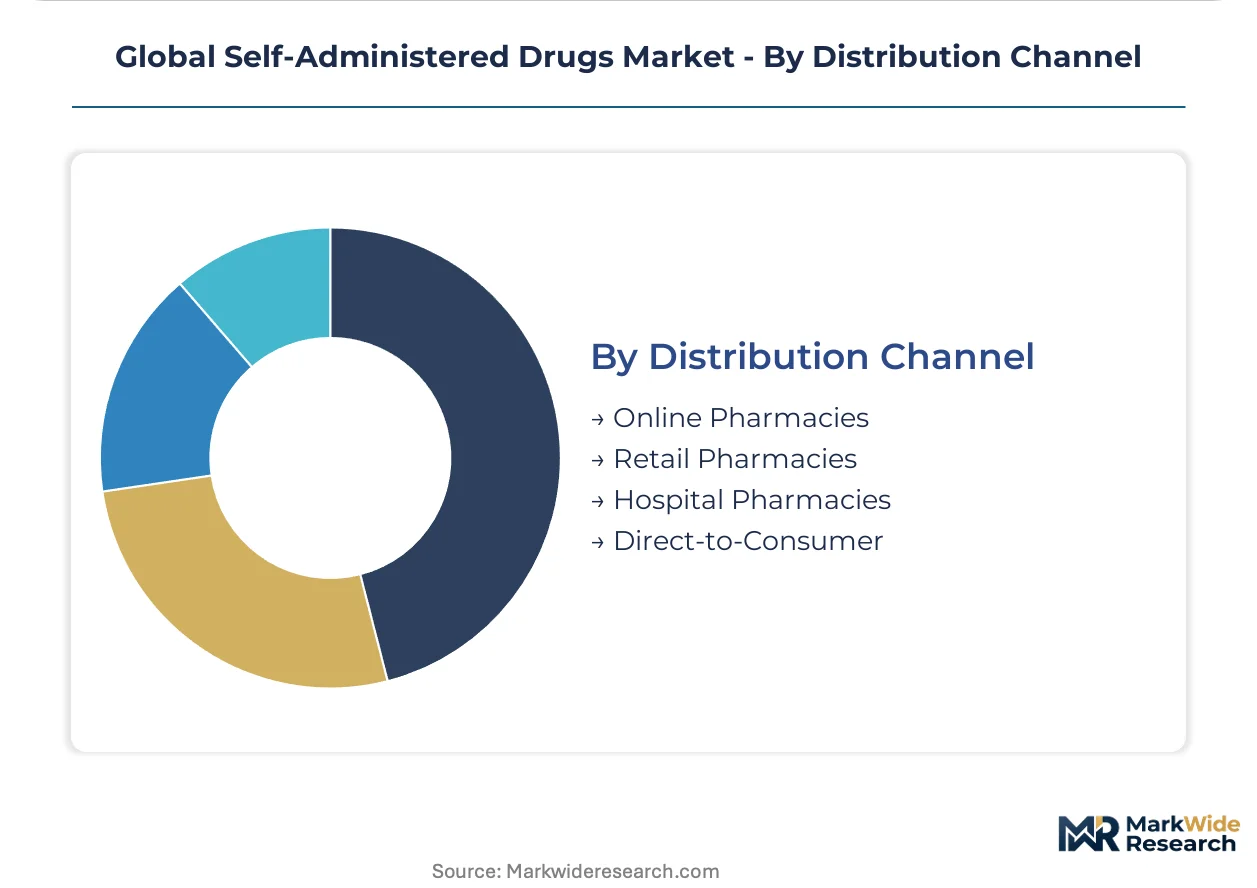
- Online Pharmacies:Digital platforms with cold-chain fulfillment capabilities capture recurring biologic prescriptions through subscription models. Brazil's ANVISA self-medication category expansion permits behind-the-counter dispensing of pre-filled adrenaline auto-injectors without prescription renewal requirements.
- Retail Pharmacies:Community dispensing of oral tablets and ambient-stable injectables leverages existing inventory management systems.
- Hospital Pharmacies:Institutional dispensing of initiation-phase biologics retains patients until transition to home administration.
- Direct-to-Consumer:Manufacturer-controlled fulfillment of connected devices enables adherence data capture and subscription revenue stacking.
Retail pharmacies retain the bulk of transaction volume; online pharmacies are expanding most quickly as specialty digital platforms bundle nurse support into dispensing fees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors North American self-administered drug development, while Frankfurt's pharmaceutical logistics hub and Tokyo's medical device manufacturing belt concentrate complementary capabilities across three continents.
United States
Specialty pharmacies in Massachusetts and North Carolina capture maintenance biologic prescriptions through direct-to-patient fulfillment models. FDA's streamlined 510(k) auto-injector pathway accelerates approval timelines for connected delivery devices. The Research Triangle Park cluster in North Carolina hosts manufacturing scale-up facilities for prefilled syringe portfolios serving domestic distribution networks.
Germany
Statutory health insurance expansion for continuous glucose monitoring with insulin pen co-prescribing eliminates out-of-pocket barriers for Type 2 diabetes patients. EMA MDR device-drug interface requirements enforce patient-handling studies that extend approval timelines for novel injection platforms. The Frankfurt-Rhine-Main logistics corridor maintains cold-chain distribution infrastructure for ambient-stable biologic formulations.
Japan
METI incentives for elderly-friendly medical devices accelerate PMDA fast-track approvals for simplified auto-injector interfaces. Aging demographics in Tokyo and Osaka prefectures drive demand for ergonomic delivery systems designed for untrained home users. The Kansai manufacturing belt concentrates prefilled syringe assembly operations serving domestic pharmacy chains.
United Kingdom
Digital prescriber platforms in London and the Southeast capture rheumatoid arthritis and multiple sclerosis scripts through specialty pharmacy networks. MHRA alignment with EMA combination product standards streamlines post-Brexit regulatory continuity for device-drug submissions. The Cambridge life sciences cluster supports connected device engineering for cloud-based adherence monitoring platforms.
Brazil
ANVISA's 2023 self-medication category expansion permits behind-the-counter dispensing of pre-filled adrenaline auto-injectors without prescription renewal requirements. Pharmacy channel modernization in São Paulo and Rio de Janeiro absorbs distribution investment from Western manufacturers seeking Latin American market entry. The São Paulo state industrial corridor hosts local assembly operations for Gulf Cooperation Council re-export.
Global Self-Administered Drugs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across device complexity and biologic formulation tiers, with GLP-1 delivery systems and automated injection platforms commanding superior returns against oral solid-dose commoditization. The competitive field separates into three archetypes: captive device manufacturers controlling proprietary delivery ecosystems, scale-driven prefilled syringe specialists, and connected platform integrators capturing subscription revenue alongside hardware. Dominant competitive moves include strategic partnerships for real-world adherence data integration and geographic expansion into pharmacy-direct fulfillment markets.
Among Danish and US-based innovators, Novo Nordisk and Eli Lilly & Co. exemplify the captive-device archetype through proprietary GLP-1 delivery ecosystems, while Amgen occupies a position representing scale-driven manufacturing for prefilled biologic portfolios. Sanofi anchors the European insulin pen segment through brand strength across pharmacy chain networks. These three named entities collectively illustrate how competitive positioning stratifies between device-integrated and formulation-centric business models.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Amgen |
| Novo Nordisk |
| BD |
| Novartis |
| Eli Lilly & Co. |
| Pfizer |
| Takeda Pharmaceutical |
| Sanofi |
| Others |
Supply & Pricing Matrix
Borosilicate glass barrel costs cascade through prefilled syringe pricing tiers, with European specialty glass manufacturers commanding premium pass-through to biologic auto-injector platforms while commodity oral tablets absorb compressed margins from solid-dose API sourcing.
Pricing Analysis
Value-based pricing anchored to adherence outcomes separates connected auto-injector subscriptions from disposable hardware sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by device intelligence certification and cloud platform bundling. Pricing pressure stems from oral JAK inhibitors capturing needle-averse psoriasis patients who would otherwise initiate IL-17 biologic regimens. Retail pharmacy chains exhibit highest price sensitivity through 90-day refill automation, while specialty pharmacies with bundled nurse support maintain lowest sensitivity.
Supply Chain Analysis
Temperature-controlled freight costs from Frankfurt-Rhine-Main logistics hubs to United States distribution centers absorb margin from ambient-stable biologic formulations. Supply concentrates in Germany, Japan, and the United States for prefilled syringe assembly and auto-injector device engineering. Raw material dependencies rest on borosilicate glass from three European manufacturers, medical-grade elastomers, and Bluetooth sensor modules. Single-source vulnerability in glass primary packaging creates structural risk. Distribution runs through specialty pharmacy direct-to-patient fulfillment with cold-chain custody.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive device manufacturing and real-world adherence data integration form the upstream-downstream vertical-integration race, with GLP-1 delivery ecosystems and connected platform subscriptions as the contested levers.
For Market Incumbents: Deploy proprietary delivery ecosystem lock-in to counter oral small-molecule substitution in dermatology and rheumatoid arthritis. Deepen backward integration into borosilicate glass supply through long-term offtake agreements with European specialty manufacturers. Expand FDA 510(k) auto-injector pathway submissions ahead of EMA MDR patient-handling study requirements. For New Entrants and Emerging Players: Capture Brazil's ANVISA self-medication category expansion through behind-the-counter adrenaline auto-injector distribution without prescription renewal. Target Saudi Arabia's SFDA-FDA harmonization corridor for Gulf Cooperation Council assembly and re-export. Pursue connected device convergence with cloud adherence platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale prefilled syringe specialists with ISO 14955 usability certification in Germany and Japan. Long-term viability across the projection horizon hinges on integration of real-world pharmacovigilance data streams. Monitor PMDA fast-track approval velocity for elderly-friendly auto-injector interfaces as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Device Platform Integration | Bluetooth-enabled dose-capture technology creates recurring subscription revenue alongside disposable hardware. |
| Backward Integration into Primary Packaging | Captive borosilicate glass supply secures prefilled syringe capacity against European manufacturer consolidation. |
| Regulatory Approval Pathway Diversification | FDA 510(k) streamlining versus EMA MDR patient-handling studies shapes geographic launch sequencing. |
| Specialty Pharmacy Partnership | Direct-to-patient fulfillment with bundled nurse hotline support captures maintenance biologic prescriptions. |
| Real-World Adherence Data Integration | Cloud platforms satisfy PMDA pharmacovigilance requirements while generating proprietary outcome datasets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews of drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. FDA 510(k) submissions, EMA combination product dossiers, ClinicalTrials.gov entries, and hospital procurement databases supplied validation layers. Bottom-up segment sizing and top-down macro constraint reconciliation ensured triangulation integrity.
Data-stream reconciliation across patient population projections, reimbursement framework expansions, and device engineering cost curves informed the analytical framework. Segmentation dimensions modeled encompassed therapy area, drug type, end-user setting, and regional regulatory cluster. CAGRs derived from slope consistency checks against historical analogs and elasticity-adjusted volume assumptions. Biologics stability engineering timelines and connected device adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA MDR interface requirement evolution and oral small-molecule substitution rates in immunology. Forecasts reflect documented assumptions about reimbursement expansion velocity and glass supply concentration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Global Equine Pharmaceuticals and Supplements Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Asia-Pacific Vaccines Market