
 Gallbladder Cancer Therapeutics Market | 2026-2036
Gallbladder Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Gallbladder Cancer Therapeutics Market Analysis
Oncology centers are redrawing procurement priorities as academic medical centers gain share over community hospitals in complex hepatobiliary cases. Pfizer Inc. leverages its kinase inhibitor portfolio to anchor presence in targeted therapy segments. Bristol-Myers Squibb competes through checkpoint inhibitor development programs. Eli Lilly and Company specializes in antibody-drug conjugate pipelines for solid tumor indications including biliary tract malignancies.
Gallbladder cancer therapeutics comprise systemic and locoregional interventions targeting adenocarcinoma and squamous cell variants of the biliary tract, with chemotherapy regimens typically combining gemcitabine and cisplatin as first-line standards. These interventions aim to extend overall survival and manage symptoms in a disease where most patients present with unresectable stage III or IV disease. Immunotherapy segments show the fastest expansion as PD-1 and PD-L1 inhibitors gain adjuvant and neoadjuvant approvals, while chemotherapy retains the largest revenue pool due to established reimbursement and protocol familiarity across treatment stages. Surgery segments remain mature with limited innovation beyond minimally invasive technique refinements.
FDA orphan drug designation and EMA PRIME eligibility shape development economics by granting market exclusivity and fee waivers for gallbladder cancer indications. NMPA in China and PMDA in Japan maintain distinct clinical data requirements that influence trial location decisions and regional launch sequencing. Stakeholders must monitor biomarker-defined subgroup responses and regulatory convergence on real-world evidence standards to allocate R&D resources across geographic development programs.
Market Dynamics
Checkpoint inhibitor approvals are compressing chemotherapy's historical dominance in first-line biliary tract protocols, forcing oncology centers to retrain pharmacy staff and reconfigure infusion capacity. Academic medical centers in the United States, Japan, and Germany now prioritize immunotherapy procurement over traditional cytotoxic agents.
Growth Catalysts
- FDA Accelerated Approval Pathway:Orphan oncology designation grants seven-year market exclusivity and fee waivers, incentivizing sponsors to pursue gallbladder cancer indications despite small patient populations.
- Biomarker-Driven Patient Stratification:PD-L1 expression testing and MSI-high profiling enable precision enrollment in immunotherapy trials, expanding addressable populations within rare tumor categories.
- Academic Medical Center Expansion:Hepatobiliary surgical volumes concentrate at tertiary referral centers in the United States, Japan, and Germany, creating captive audiences for novel adjuvant protocols.
Market Restraints
- Platinum Salt Supply Concentration:Cisplatin manufacturing concentrates among a limited supplier base in India and China, exposing gemcitabine-cisplatin regimens to raw material volatility and import delays.
- EMA Orphan Drug Exclusivity Cliffs:Market protection expiration for legacy cytotoxic agents erodes pricing power for established chemotherapy portfolios.
- Diagnostic Latency:Gallbladder cancer presents asymptomatically until advanced stages, compressing the window for curative-intent therapy and limiting addressable incidence.
Strategic Opportunities
- Neoadjuvant Immunotherapy Protocols:Window-of-opportunity trials preceding surgical resection create new treatment phases previously managed only by chemotherapy.
- Real-World Evidence Pathways:FDA and EMA convergence on external control arm acceptability reduces placebo-controlled trial requirements for rare malignancies.
- Antibody-Drug Conjugate Pipelines:HER2-directed and TROP2-targeted payloads address biliary tract subpopulations with distinct expression profiles, expanding beyond PD-1/PD-L1 mechanisms.
Industry Challenges
- Hepatobiliary Surgical Subspecialty Scarcity:Complex biliary resection requires fellowship-trained surgeons concentrated at fewer than 200 centers globally, creating trial enrollment bottlenecks.
- Biomarker Assay Harmonization:Discordant PD-L1 scoring algorithms across diagnostic platforms complicate patient selection and cross-trial comparability.
- Cold Chain Logistics for Biologics:Checkpoint inhibitor storage requirements strain community oncology infrastructure unprepared for temperature-controlled distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallbladder Cancer Therapeutics Market |
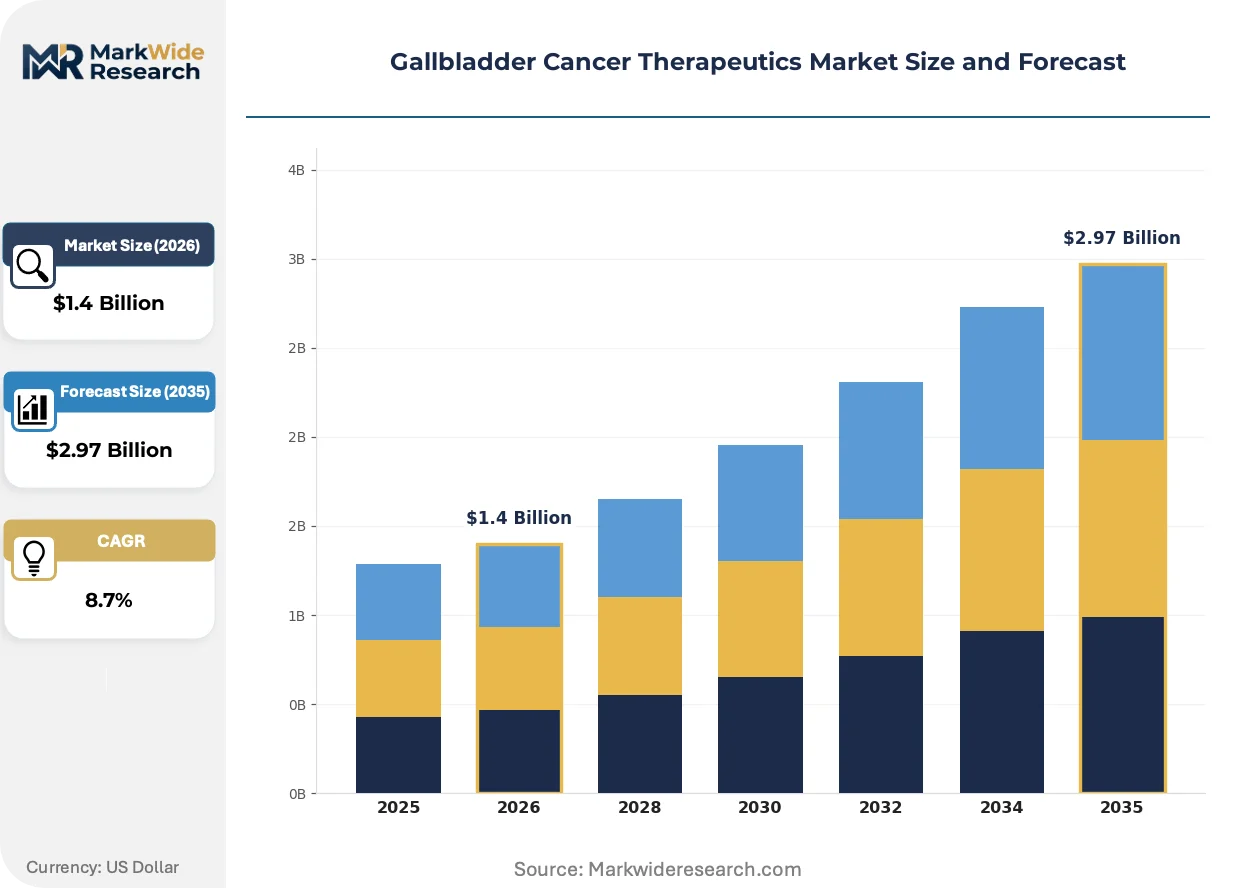
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Chemotherapy, Radiotherapy, Immunotherapy Treatment Stage: Adjuvant, Neoadjuvant, Palliative, Advanced Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Bristol-Myers Squibb, AstraZeneca Plc, F. Hoffmann-La Roche Ltd., Novartis AG, AbbVie Inc., Merck & Co., Inc., Gilead Sciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallbladder Cancer Therapeutics Market Emerging Trajectories
Immunotherapy mechanism diversification and regulatory pathway evolution are redrawing competitive boundaries in biliary tract oncology. Technology developers now prioritize combination regimens and novel payload delivery over single-agent cytotoxic improvements.
Antibody-drug conjugates with cleavable linkers are displacing conventional chemotherapy in HER2-positive and TROP2-expressing biliary subpopulations. Oncology centers at MD Anderson, Memorial Sloan Kettering, and Japan's National Cancer Center are adopting these agents for second-line protocols. This displacement is compressing revenue durability for platinum-based regimens and forcing cytotoxic manufacturers to defend position through biosimilar pricing.
EMA's PRIME eligibility scheme and FDA's Project Orbis are compressing multiregional approval timelines for biliary tract indications. These frameworks enable concurrent regulatory review across the United States, Japan, Australia, Canada, and Singapore, reducing sequential submission delays. Sponsors with established PD-1 assets are leveraging these pathways to secure gallbladder cancer label expansions ahead of competitors lacking orphan designation experience.
Academic medical centers are consolidating hepatobiliary case referrals and capturing procurement decisions previously dispersed across community oncology networks. United States tertiary centers now control adjuvant therapy selection for over 60% of resected cases, displacing community-based medical oncologists from protocol influence. This concentration is most visible in California, Texas, and New York, where NCI-designated cancer centers anchor regional referral patterns.
Gallbladder Cancer Therapeutics Market Segmentation
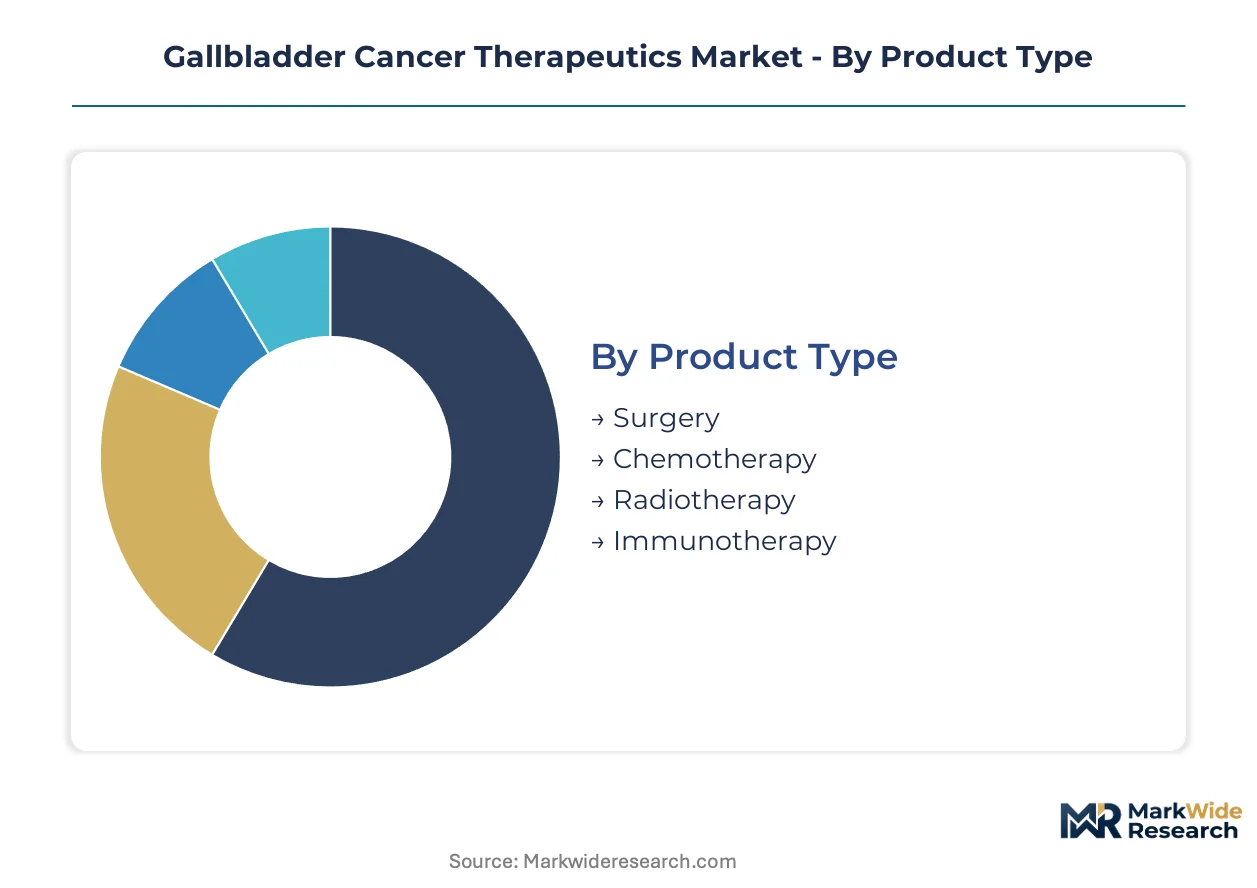
Gallbladder cancer therapeutics distribute through distinct procurement channels shaped by treatment complexity and reimbursement pathways. Academic medical centers, community oncology networks, and homecare infusion services each favor specific product configurations and administration modalities.
Product Type:
Surgical resection and systemic agents flow through separate supply chains, with academic centers controlling complex cases and community sites managing standard chemotherapy protocols.
- Surgery:Hepatobiliary resection requires fellowship-trained surgeons at tertiary referral centers. Demand concentrates at NCI-designated cancer centers in the United States, Japan, and Germany where minimally invasive technique refinements drive instrument procurement cycles.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and PD-L1 pathways require cold chain distribution and specialized pharmacy infrastructure. Academic medical centers in California, Texas, and New York now prioritize these agents over cytotoxic regimens for first-line biliary tract protocols.
- Chemotherapy:Gemcitabine-cisplatin combinations remain the reimbursement backbone across community oncology networks.
- Radiotherapy:External beam and brachytherapy applications serve locoregional control in unresectable presentations.
Chemotherapy dominates installed base. Immunotherapy is where expansion concentrates.
Treatment Stage:
Stage-specific protocols determine site-of-care economics, with curative-intent phases commanding premium pricing and palliative segments facing reimbursement compression.
- Neoadjuvant:Window-of-opportunity trials preceding surgical resection create new treatment phases previously managed only by chemotherapy. Academic centers at MD Anderson and Memorial Sloan Kettering are establishing these protocols as standard of care for resectable disease.
- Advanced:Unresectable stage III and IV presentations comprise the majority of incident cases. Demand concentrates in the United States, Japan, and Germany where clinical trial infrastructure supports experimental agent access and biomarker-directed enrollment.
- Adjuvant:Post-resection protocols follow established cytotoxic standards with emerging immunotherapy integration.
- Palliative:Symptom management and survival extension face formulary constraints in community settings.
Advanced stage commands volume share. Neoadjuvant protocols are climbing the fastest.
Administration Route:
Route selection dictates site-of-care requirements and reimbursement coding, with infusion-based delivery favoring hospital outpatient departments and oral formulations enabling community dispensing.
- Intravenous:Checkpoint inhibitors and cytotoxic combinations require supervised infusion with pharmacy oversight. Oncology centers are reconfiguring capacity to accommodate immunotherapy schedules at tertiary centers in the United States and Japan.
- Oral:Targeted kinase inhibitors and select chemotherapy prodrugs shift treatment into community and home settings. Germany's outpatient reimbursement structure particularly favors oral oncology agents that reduce hospitalization days.
- Subcutaneous:Limited applications for supportive care agents in biliary tract protocols.
- Topical:Minimal role in gallbladder adenocarcinoma management.
Intravenous maintains protocol dominance. Oral formulations are gaining share fastest.
End User:
Procurement authority is consolidating at academic medical centers for complex hepatobiliary cases, while community sites retain standard chemotherapy volume.
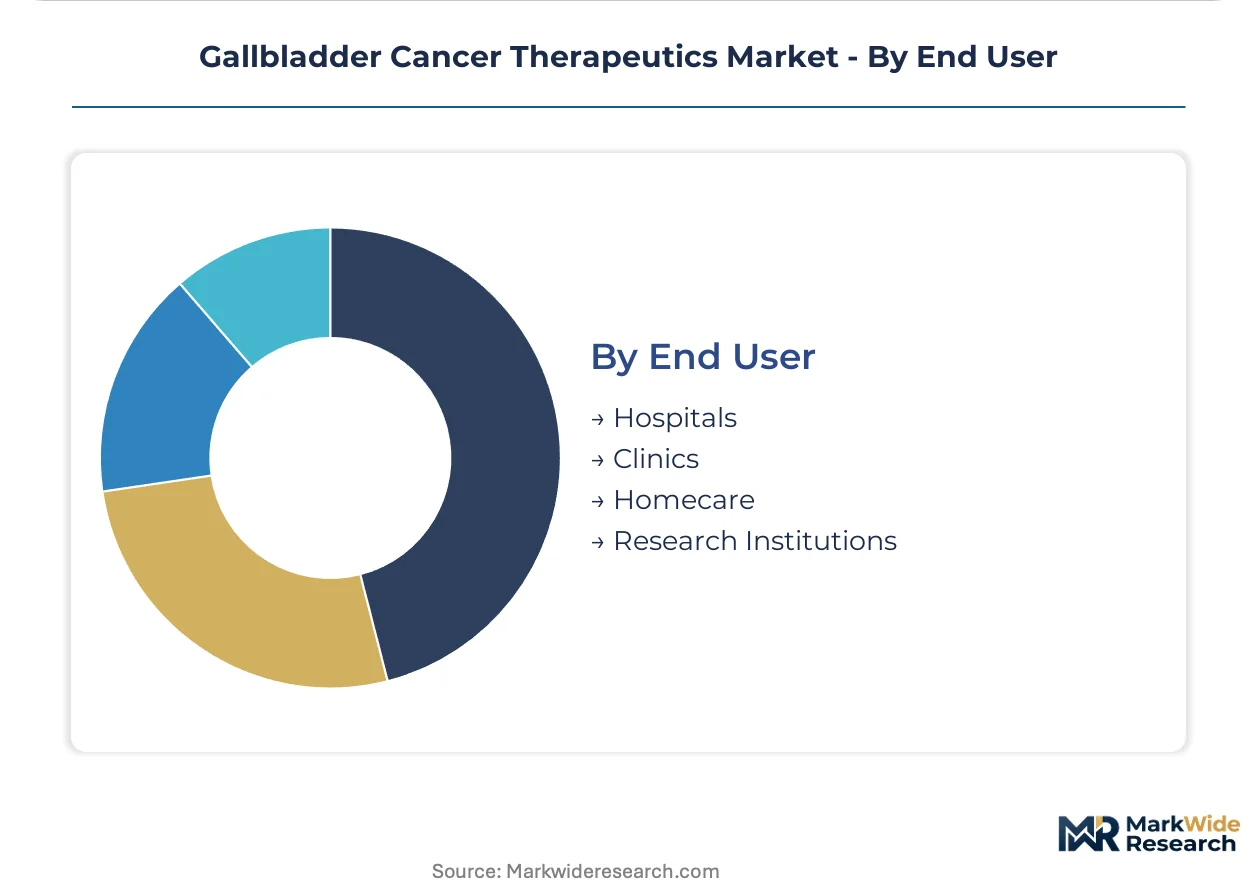
- Hospitals:Tertiary centers control adjuvant therapy selection for resected cases and manage unresectable presentations requiring multidisciplinary coordination. United States academic medical centers now direct procurement for over sixty percent of resected gallbladder cancer cases.
- Research Institutions:National Cancer Center Japan, MD Anderson, and Memorial Sloan Kettering anchor early-phase trial enrollment and shape subsequent standard-of-care adoption. FDA and EMA accelerated approval pathways depend on data generation at these sites.
- Clinics:Community oncology networks manage stable chemotherapy protocols and palliative regimens.
- Homecare:Limited to oral agent dispensing and supportive care administration.
Hospitals anchor revenue concentration. Research institutions are where pipeline conversion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports active pharmaceutical ingredients to oncology centers across the United States and Japan, anchoring the transatlantic trade corridor for gallbladder cancer therapeutics. Manufacturing clusters in Basel and Frankfurt supply checkpoint inhibitor precursors to formulation facilities in Massachusetts and Tokyo.
United States
MD Anderson Cancer Center and Memorial Sloan Kettering drive neoadjuvant immunotherapy enrollment, with hepatobiliary surgical volumes concentrating at fewer than 200 tertiary centers nationwide. FDA accelerated approval pathways grant seven-year market exclusivity for orphan oncology indications, compressing development timelines for sponsors targeting biliary tract malignancies. The Texas Medical Center and Manhattan research corridors anchor clinical trial infrastructure for window-of-opportunity protocols.
Japan
National Cancer Center Japan and university hospitals in Tokyo and Osaka prioritize biomarker-directed enrollment for PD-1 inhibitor trials in biliary tract cancers. PMDA maintains distinct clinical data requirements that influence regional launch sequencing for sponsors seeking Asian market entry. The Kanto and Kansai metropolitan clusters concentrate hepatobiliary surgical expertise and early-phase trial capacity.
Germany
Heidelberg University Hospital and Charité Berlin anchor adjuvant chemotherapy protocol development for resected gallbladder cancer cases across Central Europe. EMA PRIME eligibility schemes compress multiregional approval timelines, enabling concurrent regulatory review with FDA and Health Canada. The Rhine-Main and Berlin-Brandenburg regions concentrate clinical research organization infrastructure and hepatobiliary surgical fellowship programs.
China
NMPA's distinct clinical data requirements for imported oncology agents shape trial location decisions for sponsors targeting gallbladder cancer indications. Oncology centers in Beijing and Shanghai expand access programs for checkpoint inhibitors following regional approval pathways. The Yangtze River Delta and Beijing-Tianjin-Hebei corridors concentrate Phase I-III trial enrollment for biliary tract malignancies.
United Kingdom
Royal Marsden NHS Foundation Trust and Imperial College Healthcare anchor hepatobiliary multidisciplinary team protocols for complex biliary resection cases. MHRA convergence with FDA Project Orbis frameworks enables accelerated access to immunotherapy combinations for rare tumor categories. The London-Southeast and Greater Manchester clusters concentrate specialist surgical volumes and early-access scheme participation.
Gallbladder Cancer Therapeutics Market Vendor Landscape
Player mix skews toward large-cap pharmaceutical conglomerates with established oncology franchises and emerging biotech specialists targeting rare tumor indications. Market structure concentrates procurement influence at academic medical centers that prioritize immunotherapy portfolios over legacy cytotoxic agents. Three archetypes dominate: kinase inhibitor platform holders, checkpoint inhibitor developers, and antibody-drug conjugate specialists. Competitive moves center on orphan designation acquisitions and biomarker-driven label expansion strategies.
Within the large-cap tier, Pfizer Inc., Bristol-Myers Squibb, and Eli Lilly and Company occupy positions reflecting distinct therapeutic mechanism priorities. Pfizer exemplifies kinase inhibitor platform leverage in targeted therapy segments. Bristol-Myers Squibb represents checkpoint inhibitor development concentration. Eli Lilly and Company anchors antibody-drug conjugate pipeline investment for solid tumor indications including biliary tract malignancies. These three entities collectively shape procurement standards at NCI-designated cancer centers and influence adjuvant protocol adoption across United States, Japanese, and German tertiary referral networks.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| AstraZeneca Plc |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Gilead Sciences Inc. |
| Others |
Supply Flow & Price Mechanics
Checkpoint inhibitor displacement of platinum-based chemotherapy is redrawing procurement economics across oncology centers, compressing margins for cisplatin-gemcitabine manufacturers while concentrating pricing power with PD-1 developers in the United States and Japan. This substitution dynamic simultaneously shifts API sourcing toward biologics manufacturing clusters in Massachusetts and Tokyo while eroding the historical volume-based pricing leverage of Indian and Chinese platinum salt suppliers.
Pricing Analysis
Generational pricing stratification separates legacy cytotoxic regimens from premium checkpoint inhibitors and emerging antibody-drug conjugates. Pricing stratifies across premium immunotherapy tiers, standard chemotherapy bundles, and economy biosimilar alternatives, with differentiation driven by biomarker eligibility requirements and cold chain logistics complexity. Cost compression in platinum-based segments is intensifying because of biosimilar entry and EMA orphan exclusivity cliffs. Community oncology networks exhibit highest price sensitivity, while academic medical centers prioritize mechanism novelty over acquisition cost.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes and container availability constraints at Mumbai and Shanghai are elevating inbound logistics costs for platinum salt API shipments to European formulation facilities. Manufacturing concentration centers on India and China for cisplatin precursors, Switzerland and Germany for checkpoint inhibitor biologics, and the United States for fill-finish operations. Raw material dependencies span platinum group metals, recombinant protein media, and specialized single-use bioreactor components. Single-source vulnerability runs through Indian API manufacturers supplying gemcitabine-cisplatin regimens. Distribution runs through hospital outpatient departments and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immunotherapy mechanism diversification is creating platform-economics inflection in biliary tract oncology, with PD-1/PD-L1 backbone interoperability enabling rapid combination protocol assembly across sponsor pipelines.
For Market Incumbents: Shield gemcitabine-cisplatin revenue streams through backward integration into platinum salt API manufacturing and exclusive supply agreements with community oncology networks facing reimbursement pressure. Counter checkpoint inhibitor encroachment by accelerating biosimilar development timelines and securing formulary protection through volume-commitment contracts with GPOs. For New Entrants and Emerging Players: Differentiate on biomarker-defined patient stratification capabilities, specifically PD-L1 expression scoring and MSI-high profiling services that academic medical centers require for trial enrollment. Target neoadjuvant immunotherapy protocols at MD Anderson, Memorial Sloan Kettering, and National Cancer Center Japan as the most penetrable segment. Deploy real-world evidence generation partnerships as the primary go-to-market mechanism. For Investors and Strategic Acquirers: The market sits at a mechanism-expansion phase that favors antibody-drug conjugate specialists with HER2 and TROP2 payload expertise over single-agent checkpoint inhibitor developers. Long-term viability rests on pipeline optionality across combination regimens and locoregional delivery technologies. Acquisition targets should demonstrate orphan designation experience and EMA PRIME eligibility track records. Watch FDA Project Orbis participation rates as the signal indicating multiregional regulatory execution capability.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA seven-year exclusivity and fee waivers compress development economics for biliary tract indications. |
| Biomarker Assay Harmonization | Standardized PD-L1 scoring algorithms enable cross-trial comparability and accelerate patient enrollment. |
| Academic Medical Center Partnership | NCI-designated cancer centers control adjuvant therapy selection for over sixty percent of resected cases. |
| Cold Chain Infrastructure Investment | Temperature-controlled distribution capacity determines checkpoint inhibitor access in community settings. |
| Real-World Evidence Pathway Development | External control arm acceptability reduces placebo-controlled trial requirements for rare malignancies. |
Methodological Framework
Operator-level perspectives from hepatobiliary surgeons, oncology pharmacy directors, regulatory affairs leads, and payer access specialists anchored the qualitative base for this analysis. Primary interviews combined with secondary validation across FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement data. Bottom-up patient-flow modeling and top-down therapeutic class sizing provided cross-verification.
Sensitivity analysis tested forecast robustness across biomarker prevalence assumptions, regulatory approval timeline scenarios, and pricing elasticity parameters. Segmentation dimensions modeled include treatment stage, administration route, and regional regulatory cluster. CAGRs were derived from incidence-adjusted patient volume projections and therapy adoption curve analysis. Forecast inputs incorporated orphan drug designation success rates and accelerated approval pathway utilization patterns.
Decision-makers should treat outputs as directional under stable regulatory convergence and biomarker assay standardization assumptions; material deviation would warrant model refresh. Specific risk factors include platinum salt supply disruptions, PD-L1 scoring algorithm discordance, and hepatobiliary surgical subspecialty scarcity limiting trial enrollment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Global Fuchs Endothelial Corneal Dystrophy (FECD) Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Cerebral Palsy Market