
 Fragile X Syndrome Market | 2026-2036
Fragile X Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Fragile X Syndrome Market Analysis
North American clinical trial infrastructure is rewriting competitive dynamics for Fragile X therapeutics. Roche leverages its neuroscience R&D footprint across Massachusetts and Basel to sustain pipeline momentum. Zynerba Pharmaceuticals anchors transdermal cannabinoid delivery development for behavioral symptoms. Tetra Therapeutics specializes in phosphodiesterase inhibition approaches that differentiate its mechanism from standard-of-care options.
Fragile X syndrome is a monogenic neurodevelopmental disorder caused by CGG triplet expansion silencing the FMR1 gene on the X chromosome, resulting in absent fragile X mental retardation protein and altered synaptic plasticity. Medications targeting mGluR5 pathway modulation command the largest current revenue pool, while genetic testing via next-generation sequencing represents the fastest-expanding segment as newborn screening panels broaden. CRISPR-based therapeutic platforms remain preclinical but attract disproportionate R&D capital allocation due to curative potential.
FDA orphan drug designation and EMA priority medicines frameworks shape development economics by extending market exclusivity and accelerating review timelines. The country's national pharmaceutical regulator in Japan, PMDA, maintains distinct pediatric trial requirements that influence Asia-Pacific study design. Stakeholders must monitor biomarker validation progress and payer willingness to fund genetic therapies against chronic behavioral management paradigms.
Market Dynamics
FDA orphan drug designation and EMA priority medicines frameworks are compressing development timelines while pediatric neurology clinics expand newborn screening panels, creating a structural pull toward earlier intervention and genetic testing integration.
Growth Catalysts
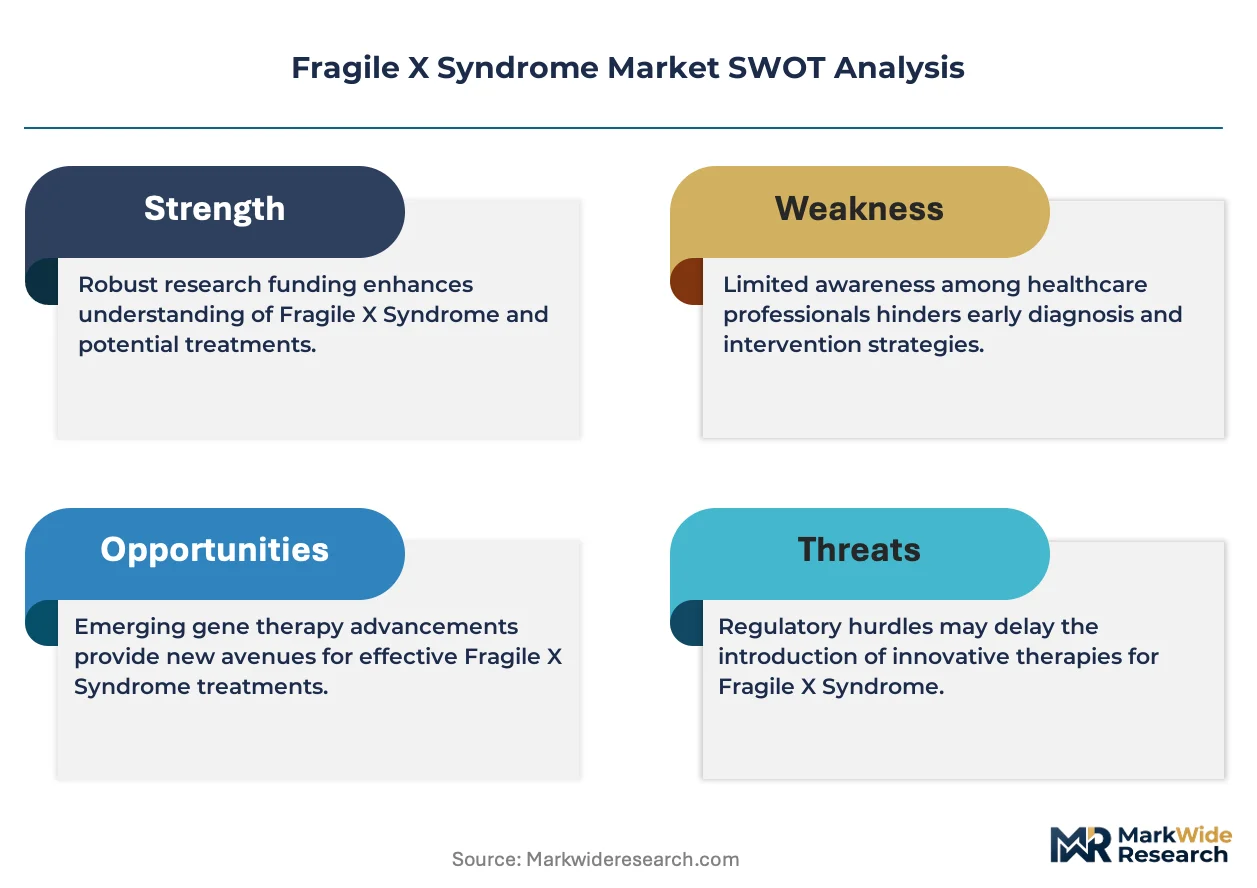
- Orphan Drug Incentives:FDA designation extends market exclusivity for Fragile X therapeutics, improving investor risk-adjusted returns for high-cost development programs targeting small patient populations.
- Newborn Screening Expansion:State-level mandates in the United States are broadening genetic testing panels to include FMR1 CGG triplet expansion detection, capturing patients before symptom onset.
- Transdermal Delivery Innovation:Cannabinoid-based behavioral symptom management via skin patches addresses gastrointestinal tolerability limitations of oral formulations in pediatric populations.
Market Restraints
- CGG Expansion Heterogeneity:Variable repeat lengths across the FMR1 gene produce inconsistent phenotypic expression, complicating endpoint selection and statistical powering in clinical trials.
- Biomarker Validation Gaps:Absence of accepted surrogate endpoints for cognitive improvement forces reliance on behavioral assessments with high placebo response rates in neurodevelopmental disorders.
- Reimbursement Uncertainty:Payer willingness to fund genetic therapies against established chronic behavioral management paradigms remains unproven for single-gene disorders with lifetime treatment horizons.
Strategic Opportunities
- CRISPR Platform Development:Preclinical gene editing approaches targeting FMR1 reactivation offer curative potential distinct from chronic symptomatic management, attracting disproportionate R&D capital allocation.
- Academic Medical Center Networks:Massachusetts and California pediatric neurology hubs anchor multi-site trial infrastructure that accelerates patient enrollment for rare disease indications.
- Phosphodiesterase Inhibition:Mechanisms modulating cAMP signaling downstream of mGluR5 pathway dysfunction provide differentiation from direct receptor antagonists with established safety liabilities.
Industry Challenges
- Placebo Response Management:High variability in parent-reported behavioral outcomes necessitates complex trial designs with multiple assessment modalities and centralized raters.
- Cross-Functional Talent Scarcity:Integration of neurodevelopmental clinical expertise with gene therapy manufacturing capabilities strains organizational capacity at emerging biotechnology firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragile X Syndrome Market |
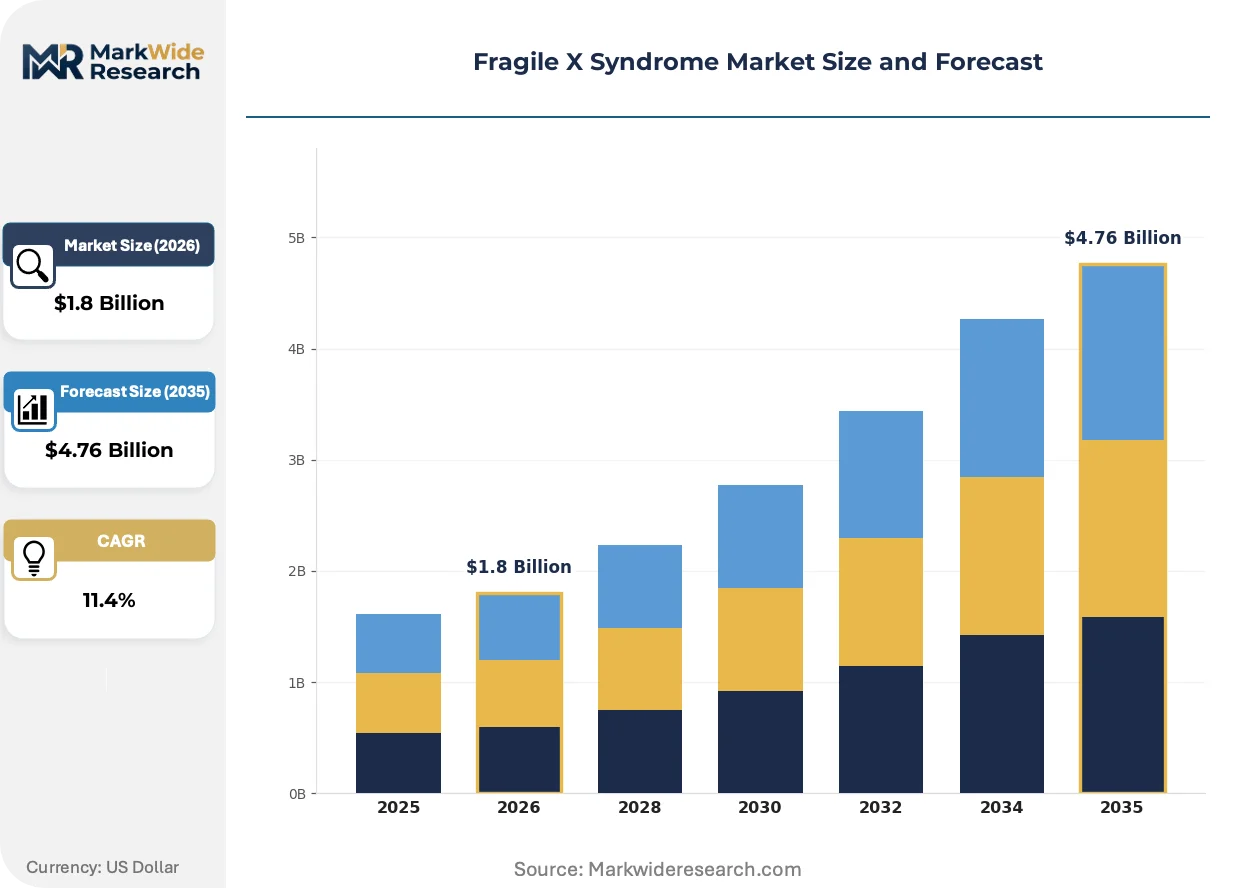
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Diagnostic Tools, Genetic Testing End User: Clinics, Hospitals, Research Institutions, Home Care Application: Behavioral Management, Educational Support, Medical Intervention, Genetic Counseling Technology: CRISPR, Next-Generation Sequencing, Pharmacogenomics, Bioinformatics |
| Companies Covered | Zynerba Pharmaceuticals, Tetra Therapeutics, Neuren Pharmaceuticals, Marinus Pharmaceuticals, Ovid Therapeutics, Fulcrum Therapeutics, Healx, Roche, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragile X Syndrome Market Emerging Trajectories
Next-generation sequencing platforms and digital biomarker capture are restructuring how Fragile X syndrome is diagnosed, monitored, and treated, shifting value toward data-integrated care models.
Artificial intelligence-enabled electroencephalography analysis is digitizing objective measurement of sensory processing abnormalities in pediatric patients. Academic medical centers in Massachusetts and California are deploying these tools to reduce reliance on subjective caregiver reports. The technology is digitizing trial endpoint selection by enabling continuous, home-based neural activity monitoring that captures treatment effects invisible to intermittent clinical assessments.
EMA's priority medicines pathway is accelerating review timelines for therapies addressing unmet needs in neurodevelopmental disorders. The framework compresses regulatory lag between Phase II evidence generation and conditional marketing authorization. Pediatric neurology programs across Germany, France, and the Netherlands are restructuring early access protocols to align with these accelerated timelines.
Caregiver-driven demand for non-pharmacological intervention data is reshaping how behavioral symptom outcomes are reported and reimbursed. Digital health platforms capturing real-world evidence on sleep, attention, and social engagement are displacing traditional clinic-based rating scales in treatment decisions. This behavioral data ownership shift is most visible in United States commercial payer contracts, where outcomes guarantees increasingly reference patient-generated health data rather than physician assessments alone.
Fragile X Syndrome Market Segmentation
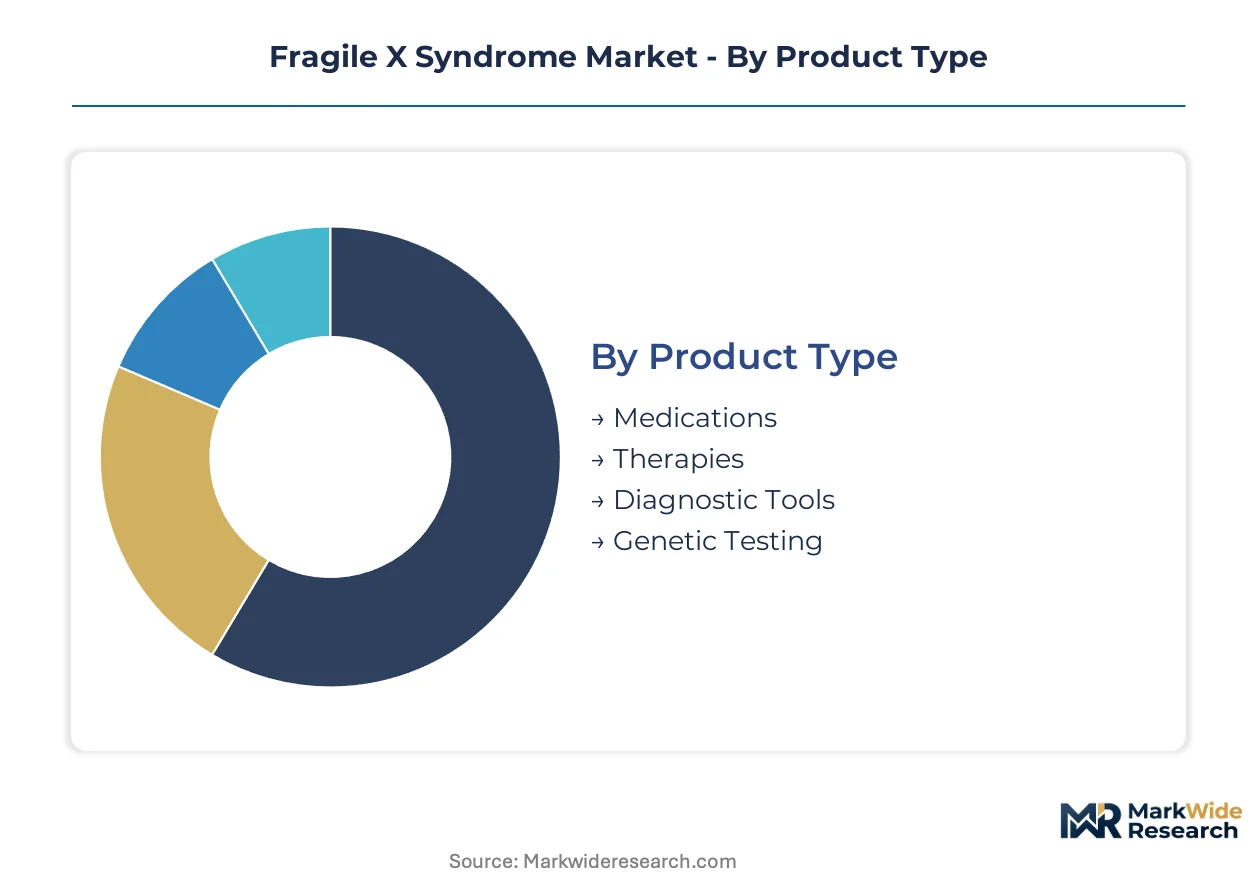
Fragmentation across therapeutic modalities and care settings shapes procurement patterns in Fragile X syndrome management. Segment boundaries blur as genetic testing platforms integrate with behavioral intervention protocols, forcing vendors to bundle across traditional category lines.
Product Type:
Diagnostic Tools turn inventory fastest due to screening panel refresh cycles, while Medications sit longest on hospital formularies pending formulary committee review.
- Medications:Small-molecule and biologic formulations targeting mGluR5 pathway modulation or downstream phosphodiesterase inhibition. Demand concentrates in academic medical centers across Massachusetts and California where pediatric neurology programs anchor prescription volume. FDA orphan drug exclusivity periods protect revenue streams for approved molecules.
- Genetic Testing:Next-generation sequencing panels detecting FMR1 CGG triplet expansion with automated repeat-length quantification. State-level newborn screening mandates in the United States are broadening panel inclusion, pulling volume toward centralized reference laboratories with high-throughput capabilities.
- Therapies:Occupational, speech, and behavioral intervention protocols delivered via structured clinical programs.
- Diagnostic Tools:Biomarker assays and neuroimaging modalities supporting phenotypic characterization.
Medications anchors the volume base while Genetic Testing gains share at the steepest rate.
End User:
Cost tier stratification separates high-acuity intervention sites from distributed monitoring settings, with reimbursement differentials driving site selection for novel therapeutic trials.
- Hospitals:Tertiary pediatric centers managing complex comorbidities and coordinating multi-specialty care teams. Academic medical centers in the United States anchor clinical trial enrollment for investigational therapies, with infrastructure investments concentrated in Massachusetts and California hubs.
- Clinics:Outpatient neurology and developmental pediatrics practices delivering longitudinal behavioral management. Community-based clinic networks across Germany, France, and the Netherlands are restructuring around EMA priority medicines accelerated access protocols.
- Research Institutions:Academic centers conducting preclinical and clinical investigation.
- Home Care:Family-mediated intervention and remote monitoring platforms.
Hospitals capture the premium intervention tier while Clinics expand most quickly through decentralized care models.
Application:
Volume concentration clusters around behavioral symptom management, though margin structure favors genetic counseling as test complexity increases.
- Behavioral Management:Pharmacologic and non-pharmacologic interventions targeting irritability, attention deficits, and social anxiety. Parent-reported outcome measures dominate endpoint selection, with high placebo response rates complicating trial design for novel agents.
- Medical Intervention:Targeted treatments addressing seizures, sleep disturbance, and gastrointestinal comorbidities. Demand concentrates in specialized pediatric neurology units with integrated psychiatric consultation capacity.
- Educational Support:Individualized education plans and classroom accommodation strategies.
- Genetic Counseling:Family planning guidance and carrier risk assessment.
Behavioral Management anchors the volume base while Genetic Counseling climbs the fastest as expanded screening broadens the at-risk population.
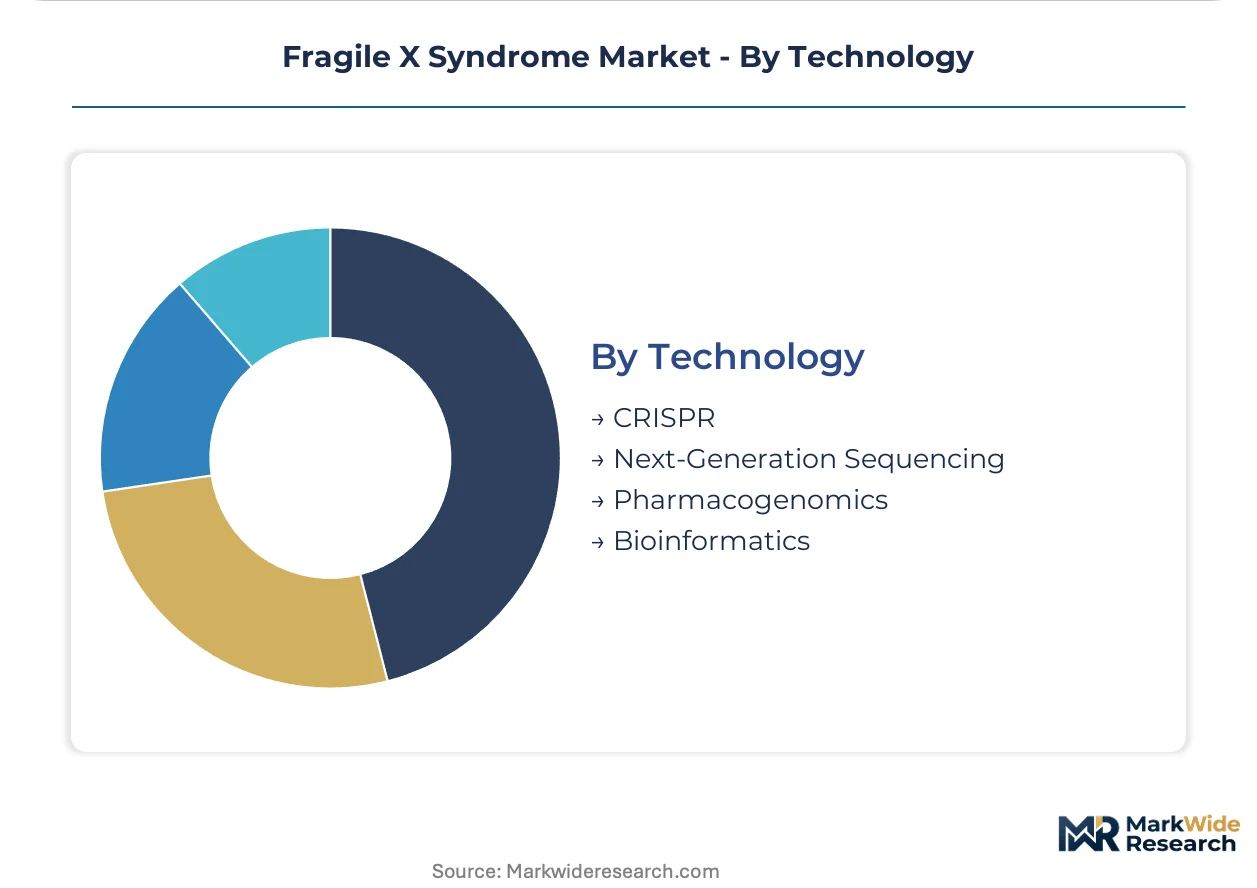
Technology:
Supply concentration in sequencing hardware vendors shapes access economics, while CRISPR platforms remain preclinical with longest development horizons.
- Next-Generation Sequencing:High-throughput platforms enabling FMR1 expansion detection with single-molecule resolution. Reference laboratories in the United States and Germany are consolidating around standardized assay formats to support newborn screening scale-up.
- CRISPR:Gene editing approaches targeting FMR1 reactivation through epigenetic modulation or triplet repeat excision. Preclinical programs attract disproportionate capital allocation due to curative potential distinct from chronic management paradigms.
- Pharmacogenomics:Genotype-guided dosing and adverse event prediction for psychotropic medications.
- Bioinformatics:Computational platforms for repeat-length quantification and variant interpretation.
Next-Generation Sequencing anchors the volume base while CRISPR gains share at the steepest rate despite preclinical status.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designation anchors the United States as the dominant geography, with EMA priority medicines pathways and PMDA pediatric requirements shaping distinct development economics across regulatory jurisdictions.
United States
Academic medical centers in Massachusetts and California anchor clinical trial networks for investigational therapeutics. State-level newborn screening mandates are broadening FMR1 CGG triplet expansion detection in genetic testing panels. The Greater Boston pediatric neurology hub coordinates multi-site enrollment infrastructure for rare disease indications.
Germany
Pediatric neurology programs across Bavaria and Baden-Württemberg are restructuring early access protocols around EMA accelerated timelines. The country's national pharmaceutical regulator maintains distinct requirements for neurodevelopmental disorder endpoints. Heidelberg and Munich academic centers deploy digital biomarker platforms for objective sensory processing measurement.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement for genetic testing and behavioral intervention protocols. The MHRA operates post-Brexit alignment with EMA priority medicines pathways while retaining independent pediatric trial assessment. London and Cambridge research clusters concentrate preclinical CRISPR platform development for FMR1 reactivation approaches.
Japan
PMDA pediatric trial requirements influence Asia-Pacific study design for transdermal and oral formulations. Domestic pharmaceutical development concentrates in the Kanto region around Tokyo academic medical centers. The regulator's distinct evidentiary standards for cognitive endpoints in neurodevelopmental disorders shape endpoint selection for regional trials.
Switzerland
Swissmedic maintains streamlined orphan drug review pathways that attract European headquarters operations for biotechnology firms. Basel anchors neuroscience R&D infrastructure with cross-border access to German and French clinical sites. The country's regulatory framework supports early-phase trial execution for phosphodiesterase inhibition mechanisms.
Fragile X Syndrome Market Vendor Landscape
Capability concentration sits with specialized biotechnology firms possessing integrated neurodevelopmental clinical expertise; scale advantage sits with diversified pharmaceutical companies leveraging existing neuroscience infrastructure. The market structure tiers between preclinical platform developers and late-stage commercialization players. Strategic archetypes include transdermal delivery specialists, phosphodiesterase inhibition researchers, and gene editing platform builders. Competitive moves center on academic medical center partnership networks and biomarker validation consortium formation.
Among the disclosed participants, Roche exemplifies the diversified pharmaceutical archetype with cross-continental neuroscience infrastructure, while Zynerba Pharmaceuticals and Tetra Therapeutics occupy positions as mechanism-focused specialists. Neuren Pharmaceuticals and Marinus Pharmaceuticals represent the mid-cap development-stage tier targeting behavioral symptom endpoints. Fulcrum Therapeutics and Healx sit within the computational and artificial intelligence-driven discovery segment. Ovid Therapeutics and Novartis anchor the broader neurological disorder portfolio approach, with the latter representing integrated commercial scale. These named entities collectively illustrate the competitive segmentation across delivery innovation, pathway modulation, and genetic therapeutic platforms.
| Leading Market Players |
|---|
| Zynerba Pharmaceuticals |
| Tetra Therapeutics |
| Neuren Pharmaceuticals |
| Marinus Pharmaceuticals |
| Ovid Therapeutics |
| Fulcrum Therapeutics |
| Healx |
| Roche |
| Novartis |
| Others |
Supply Flow & Price Mechanics
Air freight corridors linking Basel to Boston carry temperature-controlled biologics at premium rates that concentrate supply-side power among reference laboratories with validated cold-chain infrastructure. This logistics cost structure reinforces price stratification between academic medical center hubs and distributed clinic networks.
Pricing Analysis
Geographic price spreads separate Massachusetts and California academic centers from community neurology practices across Germany and the Netherlands. Contract-based long-term offtake agreements dominate genetic testing procurement, with price differentiation resting on ISO 15189 certification tier and sample volume scale. Pricing pressure stems from state-level newborn screening mandates expanding panel coverage at fixed reimbursement rates. Community clinics exhibit highest price sensitivity due to thin margins on behavioral management services, while research institutions tolerate premium pricing for biomarker assay customization.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for next-generation sequencing hardware vendors serving reference laboratories. Manufacturing concentrates in the United States, Germany, and China for sequencing platforms and reagent kits. Raw material dependencies include fluorophore-conjugated oligonucleotides, polymerase enzymes, and synthetic CGG repeat standards. Single-source vulnerability sits with CRISPR guide RNA synthesis for preclinical therapeutic programs. Distribution runs through centralized reference laboratories rather than point-of-care sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pipeline setbacks as FDA orphan drug designation renewals restore investor confidence in neurodevelopmental disorder programs. Cyclical recovery is anchored by EMA priority medicines pathway acceleration compressing regulatory timelines.
For Market Incumbents: Pre-empt CRISPR platform developers by securing exclusive academic medical center partnerships in Massachusetts and California before gene editing candidates advance to Phase I. Invest in backward integration into biomarker assay manufacturing to capture margin from genetic testing volume expansion. Defend against emerging transdermal delivery specialists by accelerating phosphodiesterase inhibitor development timelines.
For New Entrants and Emerging Players: Japan's underpenetrated pediatric neurology infrastructure offers white-space access for transdermal cannabinoid formulations addressing PMDA's distinct cognitive endpoint requirements. Target home-based digital biomarker platforms as the most penetrable segment, leveraging caregiver-driven demand for real-world evidence capture. Pursue outcomes-based contracting with United States commercial payers as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Mechanism-focused biotechnology firms with validated mGluR5 pathway assets represent the priority acquisition archetype for portfolio diversification into neurodevelopmental disorders. Long-term viability over the next decade rests on biomarker validation progress enabling surrogate endpoint acceptance. Watch for FDA breakthrough therapy designation grants to preclinical CRISPR programs as the inflection signal indicating curative therapeutic modality shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Validation Consortium | Academic medical centers in Heidelberg and Munich anchor multi-site endpoint standardization for cognitive improvement measures. |
| Orphan Drug Exclusivity Extension | FDA designation protects revenue streams for approved small-molecule therapeutics targeting behavioral symptom endpoints. |
| Transdermal Manufacturing Scale-Up | Skin-patch production capacity expansion addresses gastrointestinal tolerability limitations in pediatric populations. |
| Reference Laboratory Partnership | Exclusive agreements with high-throughput sequencing providers secure newborn screening panel inclusion and volume commitments. |
| Digital Health Platform Integration | AI-enabled EEG analysis tools reduce placebo response variability in parent-reported behavioral outcome trials. |
Methodological Framework
Initial hypotheses were tested against primary input from pediatric neurologists, regulatory affairs specialists at FDA and EMA, formulary directors at United States academic medical centers, and genetic testing laboratory directors, then refined through secondary validation against FDA orphan drug designation databases, ClinicalTrials.gov enrollment records, EMA priority medicines pathway submissions, and state-level newborn screening mandate legislation. Bottom-up patient volume estimates and top-down therapeutic revenue projections were triangulated to constrain forecast variance.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions including therapeutic modality, patient age cohort, diagnostic versus treatment setting, and regional regulatory cluster. CAGRs were derived from epidemiological prevalence projections cross-referenced with newborn screening expansion timelines and therapy penetration assumptions. Forecast inputs incorporated biomarker validation progress curves and payer reimbursement policy evolution for genetic versus behavioral management paradigms.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CRISPR platform developers or artificial intelligence-driven discovery firms would shift outcomes beyond modeled ranges. Macroeconomic contraction affecting healthcare budgets, regulatory restriction on gene editing clinical applications, or technological breakthrough in FMR1 reactivation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Dravet Syndrome Market