
 North America Ophthalmic Devices and Drugs Market | 2026-2036
North America Ophthalmic Devices and Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ophthalmic Devices and Drugs Market Analytics
Hospital procurement channels is fragmenting as specialty practices and ambulatory surgical centers gain direct purchasing power across the United States and Canada. Johnson & Johnson leverages its integrated surgical suite ecosystem to anchor premium cataract workflows. Alcon Inc. dominates consumable attach rates through proprietary intraocular lens and viscoelastic bundling. Bausch Health Companies Inc. competes on contact lens and dry eye pharmaceutical portfolios across retail pharmacy and clinic channels.
Ophthalmic devices and drugs encompass diagnostic instruments, surgical platforms, corrective lenses, and therapeutics engineered to precision tolerances measured in micrometers for intraocular applications, with primary commercial purpose spanning vision correction, disease management, and surgical restoration of ocular function. Intraocular lenses and diagnostic devices command concentrated margin pools where optical coherence tomography systems sustain premium pricing through software-locked upgrade cycles. Drug delivery systems for glaucoma management and retinal disorders represent the fastest-expanding application cluster as sustained-release implants displace chronic topical dosing regimens.
FDA premarket notification and PMA pathways govern device commercialization in the United States, while Health Canada Medical Device Licensing and ISO 13485 quality system certification establish baseline market access requirements across North America. The IRA Medicare drug price negotiation provisions reshape ophthalmic pharmaceutical reimbursement calculus for manufacturers serving aging patient populations. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic devices and provincial formulary decisions in Ontario and Quebec that increasingly determine provincial procurement winners.
Market Dynamics
Hospital procurement consolidation is fragmenting as ambulatory surgical centers and specialty ophthalmology practices acquire direct purchasing authority, bypassing traditional group purchasing organizations across the United States and Canada. This structural shift redistributes pricing power toward mid-sized clinical buyers while compressing legacy distributor margins.
Growth Catalysts
- IRA Medicare Drug Price Negotiation:The Inflation Reduction Act provisions for Medicare drug price negotiation reshape pharmaceutical reimbursement frameworks, accelerating manufacturer investment in sustained-release drug delivery implants that reduce chronic dosing frequency for glaucoma and retinal disease patients.
- Artificial Intelligence Diagnostic Integration:FDA guidance on AI-enabled diagnostic devices is clarifying approval pathways for machine learning algorithms analyzing optical coherence tomography scans, enabling faster clinical decision support deployment in retinal disease screening workflows.
- Ambulatory Surgical Center Expansion:Texas, California, and New York metropolitan clusters are licensing standalone ophthalmic surgery centers at accelerated rates, concentrating demand for compact phacoemulsification platforms and disposable surgical consumables in outpatient settings.
Market Restraints
- Silicone Hydrogel Raw Material Concentration:Contact lens and intraocular lens manufacturing depends on concentrated silicone hydrogel precursor supply chains, exposing producers to input cost volatility when specialty chemical production faces disruption.
- FDA PMA Timeline Friction:Class III ophthalmic devices requiring premarket approval face extended review cycles averaging 18-24 months, compressing effective patent life and delaying revenue recognition for novel surgical platforms.
- Pharmaceutical Substitution Pressure:Branded glaucoma therapeutics confront accelerating generic substitution as patent cliffs approach, eroding margin pools for topical prostaglandin analog formulations.
Strategic Opportunities
- Canadian Provincial Formulary Expansion:Ontario and Quebec provincial procurement decisions increasingly determine ophthalmic pharmaceutical access, creating targeted pathways for sustained-release implant manufacturers to secure preferential reimbursement status through health technology assessment submissions.
- Optical Coherence Tomography-Angiography Convergence:Integration of OCT hardware with AI-powered angiography analysis software creates premium upgrade revenue streams through software-locked feature activation.
- Direct-to-Practice Distribution Models:Specialty distributors are building last-mile logistics networks serving ambulatory surgical centers, bypassing hospital central supply and capturing higher-margin consumable attach rates.
Industry Challenges
- Retinal Surgeon Training Pipeline:Fellowship programs produce insufficient vitreoretinal specialists to match expanding surgical volume, constraining adoption rates for complex surgical platforms in community practice settings.
- ISO 13485 Certification Timeline:Quality management system certification requirements for Health Canada licensing create 12-18 month compliance windows that delay market entry for novel diagnostic devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ophthalmic Devices and Drugs Market |
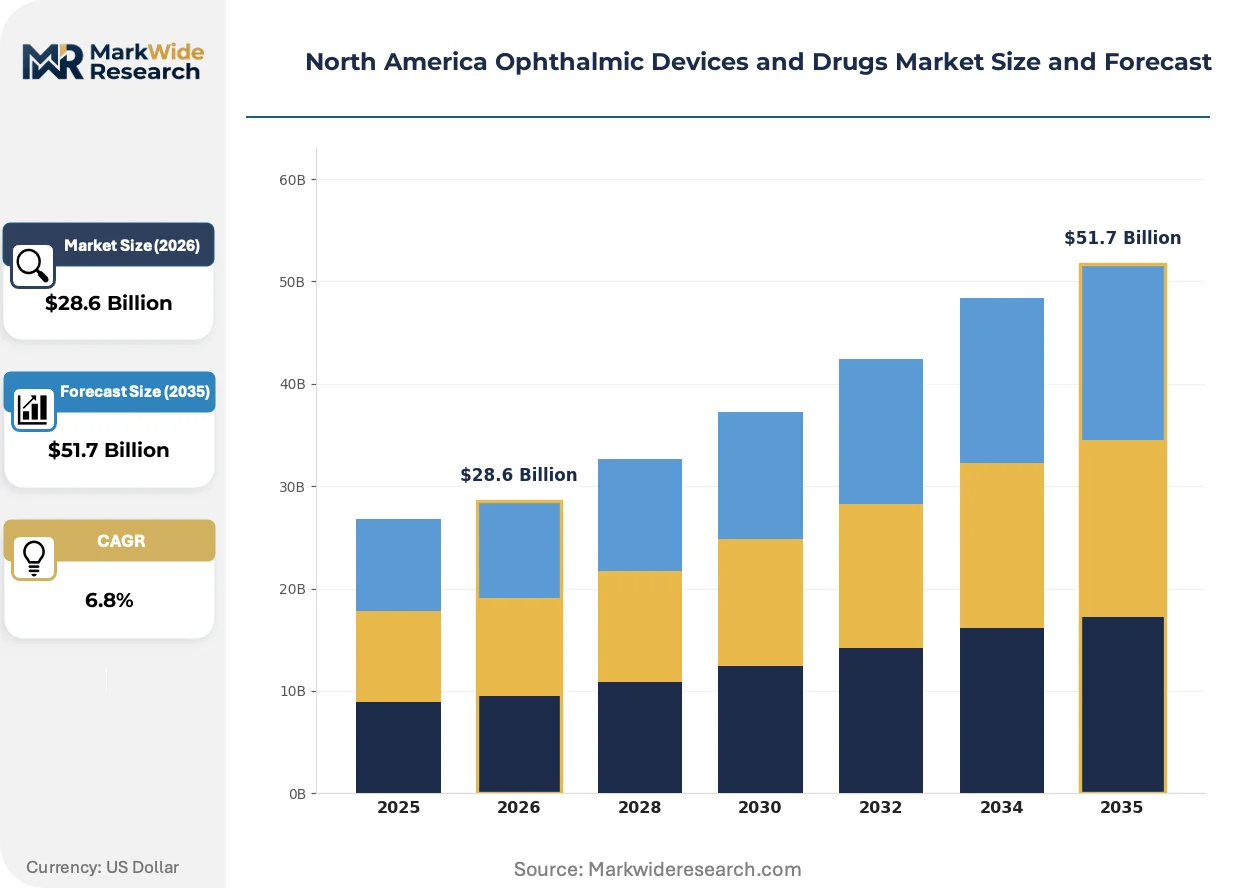
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Contact Lenses, Diagnostic Devices, Surgical Instruments End User: Hospitals, Eye Clinics, Retail Pharmacies, Specialty Practices Technology: Laser Surgery, Microincisional Surgery, Drug Delivery Systems, Optical Coherence Tomography Application: Cataract Surgery, Glaucoma Management, Retinal Disorders, Refractive Error Correction |
| Companies Covered | Alcon Inc., Johnson & Johnson, Bausch Health Companies Inc., Carl Zeiss Meditec AG, Haag-Streit Group, EssilorLuxottica, Regeneron Pharmaceuticals Inc., AbbVie Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ophthalmic Devices and Drugs Market Evolving Landscape
Software-defined diagnostic platforms and sustained-release pharmaceutical delivery systems are restructuring how ophthalmic care is provisioned, measured, and reimbursed across North American clinical settings.
Extended-depth-of-focus intraocular lenses are collapsing the historical trade-off between near and distance vision correction that forced cataract patients into monofocal or multifocal binary choices. Ambulatory surgical centers in Texas and California metropolitan markets are adopting these presbyopia-correcting platforms at accelerated rates. The technology is collapsing premium lens upgrade pricing premiums as optical engineering improvements reduce manufacturing cost differentials against standard monofocal alternatives.
FDA draft guidance on artificial intelligence-enabled medical devices is establishing predicate pathways for machine learning diagnostic algorithms, clarifying validation requirements for software-as-a-medical-device submissions. The framework accelerates regulatory review timelines for AI-integrated optical coherence tomography analysis tools. Retinal disease screening programs in United States hospital networks are restructuring procurement criteria to prioritize FDA-cleared autonomous diagnostic capabilities.
Direct purchasing by specialty ophthalmology practices is displacing hospital supply chain intermediaries across United States and Canadian markets. Group purchasing organization contracts are losing enforceability as ambulatory surgical centers negotiate direct manufacturer agreements for phacoemulsification platforms and disposable instrument kits. California and New York metropolitan clusters exhibit the most pronounced channel disintermediation, with specialty practices capturing 15-20 point margin improvements on capital equipment acquisitions.
North America Ophthalmic Devices and Drugs Market Segmentation
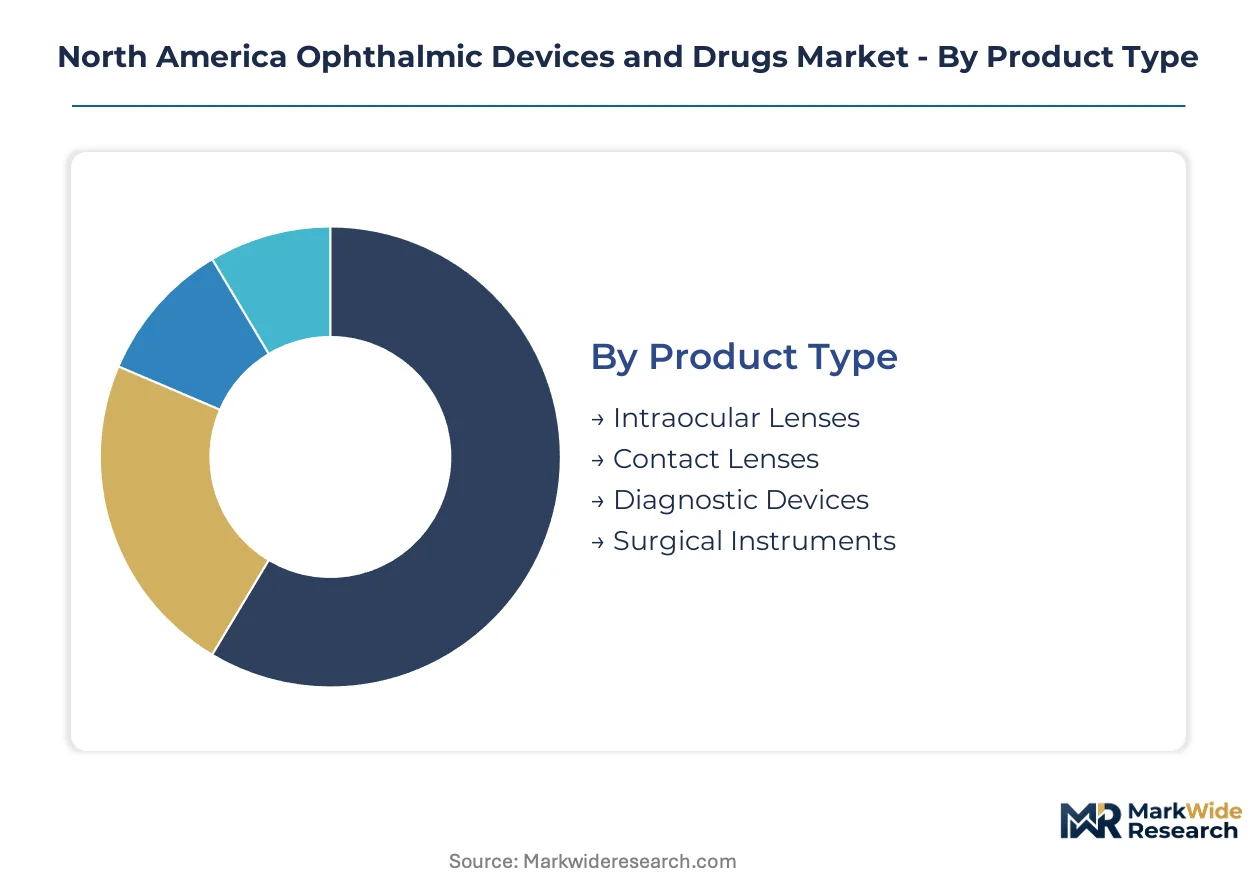
Segmentation in ophthalmic devices and drugs reveals divergent procurement rhythms, with capital equipment cycling across decade-long replacement windows while consumables and pharmaceuticals turn over in quarterly replenishment cycles. Understanding these velocity differentials shapes inventory planning, pricing architecture, and channel strategy across North American clinical settings.
Product Type:
Replacement cycles stretch from months for disposables to years for capital platforms, creating distinct margin profiles and customer lock-in mechanisms across the product spectrum.
- Intraocular Lenses:Precision-molded silicone or acrylic optical implants engineered to micrometer tolerances for cataract replacement. Demand concentrates in ambulatory surgical centers across Texas and California metropolitan clusters, where bundled lens-viscoelastic contracts anchor surgeon loyalty and consumable attach rates.
- Diagnostic Devices:Optical coherence tomography systems and fundus cameras delivering cross-sectional retinal imaging through software-defined hardware platforms. Hospital networks in New York and Ontario prioritize FDA-cleared and Health Canada-licensed units with locked upgrade pathways that extend effective product lifecycles through recurring software revenue.
- Contact Lenses:Silicone hydrogel daily disposables and extended-wear modalities serving refractive correction and therapeutic applications. Retail pharmacy channels in the United States and Canada dominate volume distribution, with prescription renewal cycles driving predictable replenishment patterns.
- Surgical Instruments:Phacoemulsification handpieces, vitrectomy probes, and disposable instrument kits for anterior and posterior segment procedures. Specialty practices in California and New York are acquiring direct purchasing authority, bypassing hospital supply chains for compact platform configurations suited to outpatient settings.
Intraocular lenses dominate installed base across North American surgical volumes. Diagnostic devices are where expansion concentrates as AI-enabled software upgrades displace hardware replacement cycles.
End User:
Procurement authority is fragmenting across customer types, with traditional hospital supply chains losing enforceability as mid-sized clinical buyers negotiate direct manufacturer relationships.
- Specialty Practices:Independent ophthalmology groups and single-specialty clinics acquiring capital equipment and consumables through direct distribution channels. Texas and California metropolitan markets exhibit the most pronounced channel disintermediation, with these practices capturing margin improvements on phacoemulsification platform acquisitions.
- Hospitals:Integrated delivery networks and academic medical centers maintaining centralized procurement for high-value diagnostic platforms and complex surgical suites. Medicare reimbursement frameworks and IRA drug pricing provisions reshape pharmaceutical formulary decisions within these institutions.
- Eye Clinics:Dedicated vision care facilities focusing on refractive services, dry eye management, and routine diagnostic screening. Ontario and Quebec provincial formulary decisions increasingly determine pharmaceutical access for these settings.
- Retail Pharmacies:Chain and independent dispensaries handling contact lens distribution and over-the-counter dry eye therapeutics. Consumer-direct subscription models are compressing traditional dispensing margins across the United States and Canada.
Hospitals retain dominance in capital equipment installed base. Specialty practices represent the steepest expansion trajectory as ambulatory surgical center licensing accelerates.
Technology:
Platform convergence is collapsing historical boundaries between surgical, diagnostic, and pharmaceutical modalities, with software integration becoming the primary differentiation vector.
- Optical Coherence Tomography:Non-invasive imaging technology generating micron-resolution cross-sectional retinal maps through low-coherence interferometry. FDA guidance on AI-enabled diagnostic devices is clarifying approval pathways for machine learning algorithms analyzing OCT scans in United States hospital networks.
- Drug Delivery Systems:Sustained-release implants and intravitreal injection platforms displacing chronic topical dosing for glaucoma and retinal disease. Medicare drug price negotiation under IRA provisions is accelerating manufacturer investment in these long-acting formulations.
- Laser Surgery:Femtosecond and excimer laser platforms for corneal reshaping and cataract fragmentation. Refractive surgery volumes concentrate in metropolitan markets across California, Texas, and New York.
- Microincisional Surgery:Phacoemulsification and microsurgical techniques enabling sutureless cataract extraction through sub-3mm incisions. Ambulatory surgical centers are adopting compact platform configurations at accelerated rates.
Laser surgery dominates procedural volume in refractive correction. Drug delivery systems are where expansion concentrates as sustained-release formulations displace chronic dosing regimens.
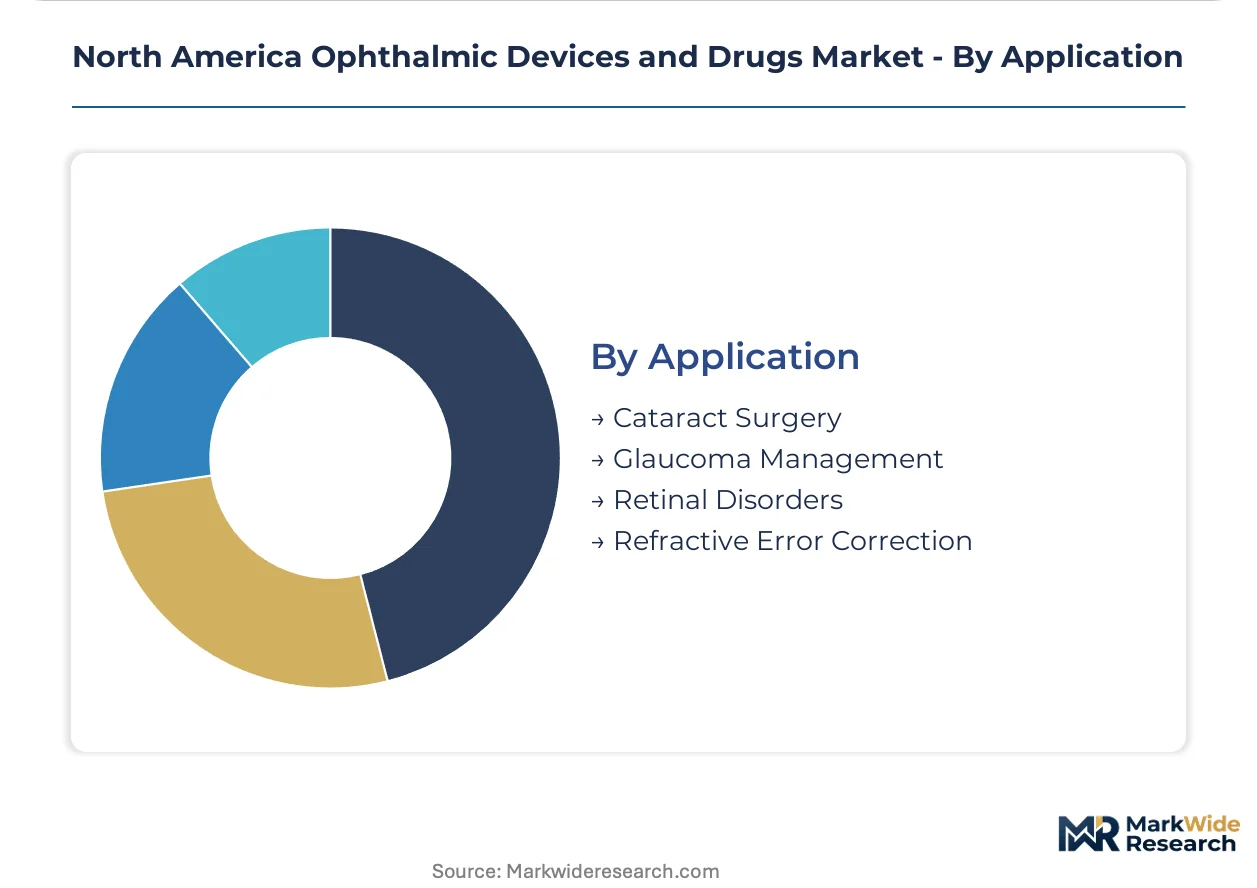
Application:
Clinical application segments map directly to demographic burden and reimbursement intensity, with aging-related conditions commanding premium pricing and volume concentration.
- Cataract Surgery:Lens extraction and intraocular implantation representing the highest-volume surgical procedure across North American ophthalmology. Extended-depth-of-focus lenses are collapsing historical trade-offs between near and distance vision correction in ambulatory surgical centers across Texas and California.
- Retinal Disorders:Medical and surgical management of age-related macular degeneration, diabetic retinopathy, and retinal detachment. Fellowship-trained specialist scarcity constrains adoption of complex surgical platforms in community practice settings.
- Glaucoma Management:Intraocular pressure reduction through pharmaceutical, laser, and surgical interventions. Generic substitution pressure is eroding margin pools for branded topical prostaglandin analogs as patent cliffs approach.
- Refractive Error Correction:Spectacle, contact lens, and surgical interventions for myopia, hyperopia, and astigmatism. Consumer preference is shifting toward daily disposable contact lenses and premium intraocular lens upgrades.
Cataract surgery dominates procedural volume across North American markets. Retinal disorders represent the steepest expansion trajectory as diabetic population burden and aging demographics expand addressable patient pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing power through Medicare reimbursement intensity, while Canadian provincial procurement compresses pharmaceutical margins through centralized formulary negotiations.
United States
California, Texas, and New York metropolitan clusters license ambulatory surgical centers at accelerated rates, concentrating demand for compact phacoemulsification platforms. FDA premarket approval pathways for Class III devices extend review cycles to 18-24 months, compressing effective patent life. Medicare drug price negotiation under IRA provisions reshapes manufacturer investment in sustained-release glaucoma implants across aging patient populations.
Canada
Ontario and Quebec provincial formulary decisions increasingly determine ophthalmic pharmaceutical access through health technology assessment submissions. Health Canada Medical Device Licensing requires ISO 13485 quality system certification, creating 12-18 month compliance windows for novel diagnostic devices. Toronto and Montreal hospital networks prioritize FDA-cleared optical coherence tomography systems with software-locked upgrade pathways.
Mexico
Mexico City Metro anchors private ophthalmology practice expansion, with Guadalajara and Monterrey emerging as secondary surgical volume centers. COFEPRIS regulatory pathways for medical devices establish convergence with FDA predicate standards, accelerating parallel submission strategies. Northern border states exhibit cross-border patient flows for premium cataract procedures, creating pricing arbitrage with Texas surgical centers.
North America Ophthalmic Devices and Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-molded optics and silicone hydrogel precursors. The market structure concentrates around three to five integrated surgical suite ecosystems competing for hospital network contracts, while upstream material suppliers face input cost volatility from specialty chemical production constraints. Strategic archetypes span integrated platform vendors, consumable bundling specialists, and retail pharmacy channel operators. Competitive moves center on direct-to-practice distribution bypass and software-locked diagnostic upgrade cycles.
Among Swiss and German precision optics fabricators, Alcon Inc. and Carl Zeiss Meditec AG occupy positions anchoring the premium diagnostic and surgical platform tier. Johnson & Johnson represents the integrated surgical suite archetype, while Bausch Health Companies Inc. sits within the retail pharmacy and consumable channel specialist segment. These three names exemplify divergent competitive positioning around platform integration versus channel fragmentation.
| Leading Market Players |
|---|
| Alcon Inc. |
| Johnson & Johnson |
| Bausch Health Companies Inc. |
| Carl Zeiss Meditec AG |
| Haag-Streit Group |
| EssilorLuxottica |
| Regeneron Pharmaceuticals Inc. |
| AbbVie Inc. |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Texas metropolitan surgical clusters anchor silicone hydrogel precursor demand, where concentrated specialty chemical capacity in the Gulf Coast corridor feeds intraocular lens and contact lens manufacturing. Input cost volatility from this geographic concentration transmits directly to downstream pricing power for precision-molded optics, while ambulatory surgical center procurement fragmentation compresses distributor margins across California and New York channels.
Pricing Analysis
The customization-premium spread separates extended-depth-of-focus intraocular lenses from standard monofocal alternatives, with optical engineering improvements collapsing historical upgrade premiums. Three-tier pricing structure across premium, standard, and economy levels reflects FDA PMA certification tier and surgeon training depth as primary differentiation drivers. Cost compression in standard monofocal lenses is intensifying because optical coherence tomography-guided selection tools reduce surgeon preference stickiness. Ambulatory surgical centers exhibit highest price sensitivity due to capital equipment financing constraints, while academic medical centers absorb premium pricing for AI-enabled diagnostic platforms.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for optical coherence tomography hardware components and silicone hydrogel raw materials. Manufacturing draws from Germany, Switzerland, and Japan for precision optics fabrication, with silicone hydrogel precursors sourced from U.S. Gulf Coast specialty chemical producers and select European suppliers. Single-source vulnerability concentrates in femtosecond laser cavity components and proprietary viscoelastic formulations. Distribution runs through specialty distributors building last-mile logistics networks that bypass hospital central supply for ambulatory surgical center direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ophthalmic devices and drugs market sits in a cyclical recovery phase, with ambulatory surgical center licensing waves in Texas and California metropolitan clusters driving capital equipment replacement demand. IRA Medicare drug price negotiation provisions compress pharmaceutical margins while accelerating sustained-release implant investment cycles.
For Market Incumbents: Entrench platform ecosystem lock-in through proprietary intraocular lens-viscoelastic bundling contracts that anchor surgeon loyalty in high-volume ambulatory surgical centers. Defend against direct-to-practice distribution disintermediation by acquiring specialty distributors with established last-mile logistics networks in California and New York metropolitan clusters. Prioritize ISO 13485 certification maintenance for Health Canada licensing continuity.
For New Entrants and Emerging Players: Canadian provincial formulary underpenetration in Ontario and Quebec offers targeted health technology assessment submission pathways for sustained-release glaucoma implant manufacturers seeking preferential reimbursement status. Target eye clinic channels with direct pharmaceutical access models that bypass hospital formulary committees. Pursue AI-enabled optical coherence tomography software-as-a-medical-device clearance as the fastest regulatory pathway to hospital network procurement.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sustained-release drug delivery system specialists with Medicare reimbursement tailwinds over hardware-dependent diagnostic platform vendors facing software-locked upgrade cycle saturation. Long-term viability hinges on FDA AI-enabled device guidance clarity and provincial formulary expansion velocity. Monitor fellowship-trained retinal surgeon pipeline output as the critical capacity constraint signal for complex surgical platform adoption inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Technology Assessment Submission | Ontario and Quebec provincial formulary decisions determine pharmaceutical access for sustained-release implants. |
| FDA AI-Enabled Device Clearance | Machine learning diagnostic algorithms for optical coherence tomography analysis accelerate hospital procurement cycles. |
| Ambulatory Surgical Center Partnership | Direct manufacturer agreements in Texas and California metropolitan clusters capture 15-20 point margin improvements. |
| Software-Locked Upgrade Pathway | Recurring revenue streams from optical coherence tomography-angiography convergence extend effective product lifecycles. |
| Specialty Distributor Acquisition | Last-mile logistics networks bypass hospital central supply and capture higher-margin consumable attach rates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA PMA filings, Health Canada Medical Device Licensing records, CMS Medicare reimbursement databases, and provincial formulary decision documents. The research program combined structured interviews with vitreoretinal surgeons, ambulatory surgical center administrators, hospital purchasing committee members, and GPO contracts managers with bottom-up and top-down triangulation across installed base estimates and procedural volume projections.
Forecast inputs span product type replacement cycle velocity, end-user procurement authority fragmentation, technology platform convergence patterns, and application-specific reimbursement intensity across the projection horizon. Segmentation dimensions modeled include product type capital-consumable distinction, end-user channel structure, technology software-hardware integration depth, and application procedural volume growth. CAGRs were derived from weighted average growth rate synthesis across segment-level drivers.
Practitioners should monitor FDA draft guidance finalization on artificial intelligence-enabled diagnostic devices, IRA Medicare drug price negotiation implementation timelines, and retinal surgeon fellowship program output for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Eye Melanoma Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Anterior Uveitis Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Global Ophthalmology PACS Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Optometry/Eye Exam Equipment Market