
 Arthroscopic Shaver Market | 2026-2036
Arthroscopic Shaver Market Size, Share, and Industry Trends Forecast 2026-2036
Arthroscopic Shaver Market Analysis
Multi-source component procurement is shifting toward captive blade manufacturing among top-tier suppliers. Arthrex leverages in-house milling capabilities to control insert geometries. Smith & Nephew sustains broad electromechanical portfolios across hospital networks. Stryker anchors North American service contracts with bundled instrument-replacement programs.
An arthroscopic shaver is a motorized surgical instrument with a rotating or oscillating inner cannula housed within an outer sheath, typically operating at 5,000–10,000 RPM to resect synovial tissue, meniscal fragments, or bony spurs during minimally invasive joint procedures. Powered shavers dominate hospital procurement budgets due to reusable handpiece durability, while disposable shaver adoption accelerates in ambulatory surgical centers seeking to eliminate reprocessing liability. Electromechanical technology occupies the largest installed base, though ultrasonic platforms compete on soft-tissue selectivity and reduced thermal necrosis risk.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations extend development timelines for new blade geometries. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 constrain material substitutions in cutting inserts. Stakeholders must monitor reimbursement coding revisions for outpatient arthroscopy procedures and position disposable-rechargeable hybrid systems accordingly.
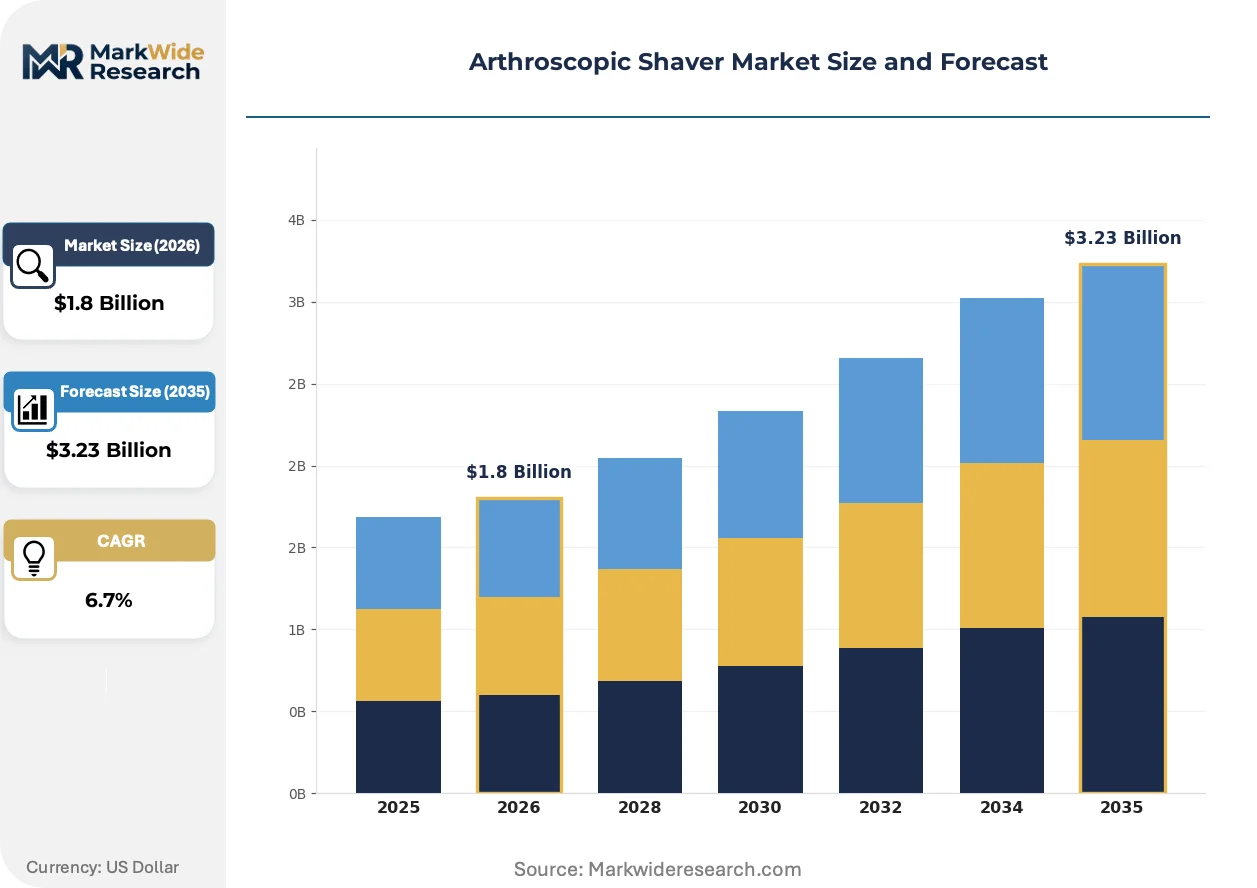
Market Dynamics
EU MDR recertification timelines and FDA 510(k) clearance pathways are compressing product launch windows, forcing manufacturers to front-load technical documentation and biocompatibility testing before commercialization. This regulatory density is reshaping competitive positioning toward incumbents with established quality management systems.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient migration drives disposable shaver adoption to eliminate reprocessing liability and turnover delays. ASCs in the United States now represent the fastest-growing installation channel.
- EU MDR Harmonization:Unified technical documentation requirements across member states reduce redundant conformity assessments, accelerating cross-border distribution for compliant manufacturers.
- Ultrasonic Platform Development:Soft-tissue selectivity and reduced thermal necrosis risk position ultrasonic shavers for meniscal and synovial applications previously dominated by electromechanical systems.
Market Restraints
- Stainless Steel Price Volatility:Cutting insert alloys face input cost pressure from nickel and chromium supply fluctuations, squeezing margin on disposable blade portfolios.
- Captive Manufacturing Concentration:Top-tier suppliers control in-house milling capabilities for precision insert geometries, creating supply bottlenecks for mid-tier competitors dependent on contract manufacturers.
- Reusable Handpiece Durability:Hospital procurement favors long-life electromechanical handpieces with 7-10 year service cycles, delaying replacement revenue and compressing annual addressable volume.
Strategic Opportunities
- Japan's Aging Surgical Population:Elevated osteoarthritis prevalence and established arthroscopy infrastructure create replacement demand for next-generation shaver systems with enhanced ergonomics.
- Hybrid Disposable-Rechargeable Systems:Modular handpiece designs with rechargeable power units and disposable cutting attachments bridge hospital and ASC preference divides.
- ISO 13485 Certification Arbitrage:Emerging manufacturers in South Korea and Taiwan leverage quality management credentials to supply private-label blades for distributor networks in Southeast Asia.
Industry Challenges
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, extending development timelines for new polymer sheath materials.
- Service Contract Integration:Bundled instrument-replacement programs require field engineering networks that smaller competitors cannot replicate without capital-intensive infrastructure buildout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthroscopic Shaver Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Shavers, Powered Shavers, Disposable Shavers, Rechargeable Shavers End User: Orthopedic Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Technology: Electromechanical, Pneumatic, Ultrasonic, Laser Application: Joint Surgery, Soft Tissue Surgery, Orthopedic Procedures, Sports Medicine |
| Companies Covered | Medtronic, Zimmer Biomet, Arthrex, DePuy Synthes, KARL STORZ, Stryker, CONMED Corporation, Olympus Corporation, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthroscopic Shaver Market Emerging Trajectories
Arthroscopic shaver technology is fragmenting across power modalities and procurement models, with electromechanical dominance eroding as ultrasonic alternatives and disposable architectures gain procedural share. This diversification is compressing traditional equipment financing structures.
Radiofrequency-enhanced shaver systems are decentralizing soft-tissue resection workflows by combining mechanical cutting with simultaneous hemostasis. Sports medicine clinics in Germany and Japan are piloting these platforms for shoulder instability procedures. The technology is decentralizing surgical steps previously requiring separate instrument exchanges, reducing operative time and tray complexity.
EU MDR technical documentation obligations now mandate clinical evidence for blade geometry modifications previously cleared through predicate equivalence. Manufacturers face expanded notified body scrutiny of cleaning validation for reusable handpieces. German and French orthopedic distributors report six-month delays in new product registrations as notified body capacity saturates.
Hospital procurement committees are consolidating vendor relationships around full-procedure portfolios spanning shavers, fixation devices, and visualization systems. Bundled contracting displaces standalone instrument purchasing in United States health networks. This concentration is most visible in integrated delivery networks in Texas and Florida, where standardization committees mandate single-source arthroscopy platforms.
Arthroscopic Shaver Market Segmentation
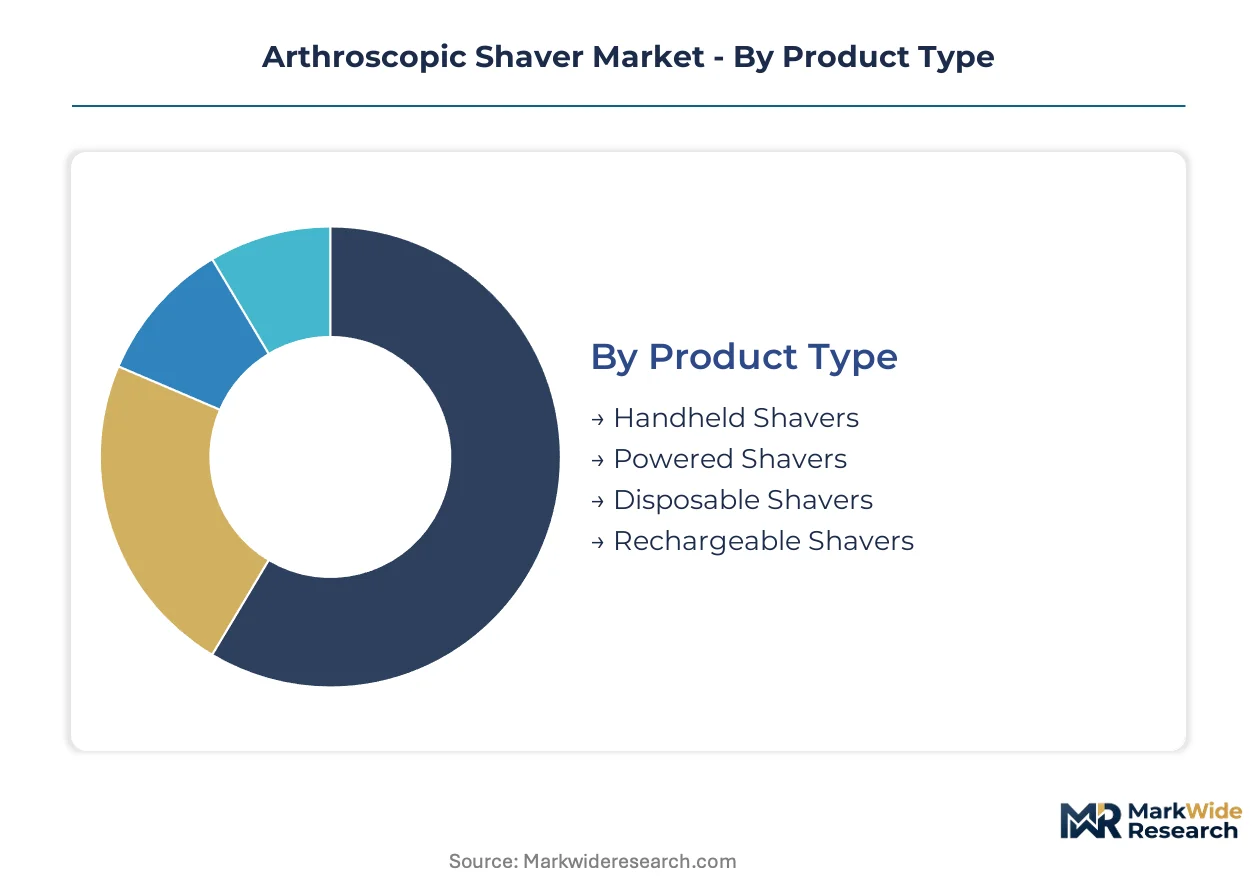
Arthroscopic shaver procurement splits sharply between capital-intensive hospital systems and efficiency-driven outpatient facilities. Technology choices determine thermal profile and tissue selectivity. End-user economics dictate reusable versus disposable architectures.
Product Type:
Standardized electromechanical platforms dominate hospital capital budgets while customization accelerates in ambulatory settings seeking workflow flexibility.
- Handheld Shavers:Manual rotation mechanisms without motorized assistance serve resource-constrained settings and backup scenarios. Demand concentrates in India and Southeast Asia where cost sensitivity overrides speed requirements.
- Powered Shavers:Electric motor-driven systems operating at 5,000–10,000 RPM constitute the installed base majority. United States hospital networks favor these for durability and service contract integration.
- Disposable Shavers:Single-use sterile units eliminate reprocessing liability. ASCs in Germany and Texas adopt these to minimize turnover delays between cases.
- Rechargeable Shavers:Battery-powered portable units bridge hospital and outpatient needs. Japanese clinics pilot these for satellite surgery centers.
Leading the category by volume: Powered Shavers. Growing fastest: Disposable Shavers.
End User:
Procurement authority shifts from centralized materials management toward procedure-level decision-making as outpatient migration accelerates.
- Orthopedic Clinics:Specialized joint practices in Germany and Japan drive adoption of precision shaver geometries for high-volume arthroscopy.
- Hospitals:Integrated delivery networks in the United States consolidate vendor relationships around full-procedure portfolios with bundled service agreements.
- Ambulatory Surgical Centers:Outpatient facilities prioritize disposable architectures and rapid instrument turnover. Texas and Florida ASCs represent the steepest expansion trajectory for shaver system installations.
- Research Institutions:Academic medical centers evaluate next-generation ultrasonic and radiofrequency platforms before commercial scale-up.
Volume concentrates in Hospitals. Share gains accelerate in Ambulatory Surgical Centers.
Technology:
Power modality selection determines thermal necrosis risk and soft-tissue selectivity in resection workflows.
- Electromechanical:Rotating or oscillating blade mechanisms dominate procedural volume. FDA 510(k) clearance pathways for new blade geometries extend development timelines for manufacturers.
- Pneumatic:Compressed gas-driven systems offer torque control in dense tissue. Niche adoption persists in legacy European installations.
- Ultrasonic:High-frequency vibration enables soft-tissue selectivity with reduced thermal damage. German and Japanese sports medicine clinics pilot these for meniscal procedures.
- Laser:Photothermal ablation provides precise cutting with simultaneous coagulation. Limited adoption due to capital cost and training requirements.
Electromechanical systems anchor installed base. Ultrasonic platforms climb the fastest.
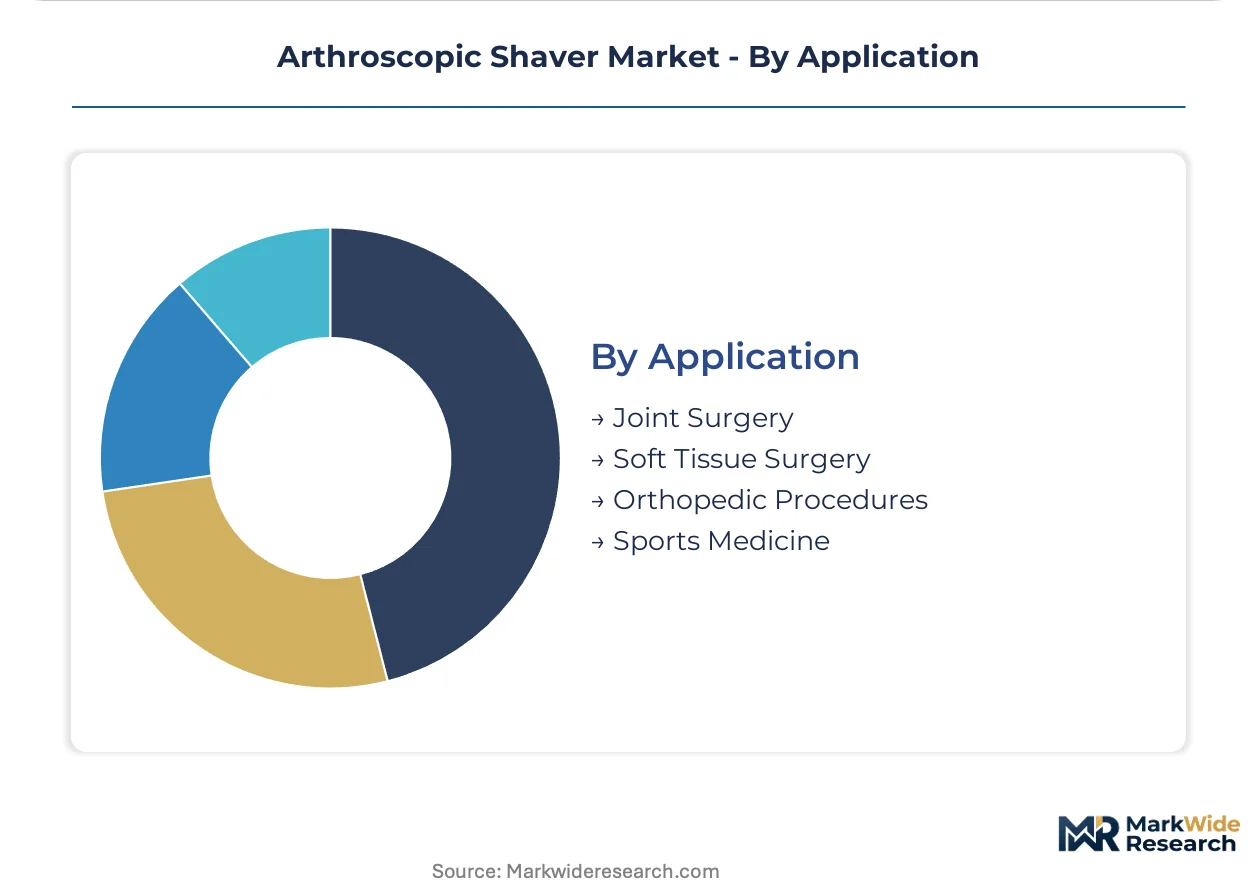
Application:
Procedure complexity and reimbursement coding influence instrument configuration and blade geometry selection.
- Joint Surgery:Knee and shoulder arthroscopy drives shaver utilization. United States procedure volumes sustain replacement demand for worn handpieces.
- Soft Tissue Surgery:Synovectomy and debridement require aggressive cutting profiles. Japanese aging demographics expand addressable cases.
- Orthopedic Procedures:General bone and cartilage resection spans multiple joint types. German hospitals standardize platforms across service lines.
- Sports Medicine:Athlete-specific interventions demand rapid recovery protocols. Radiofrequency-enhanced shavers reduce operative time in shoulder instability cases.
Joint Surgery generates largest procedure volume. Sports Medicine applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock from Pittsburgh and Sheffield anchors electromechanical shaver manufacturing clusters. Nickel-chromium alloy supply chains concentrate near these legacy metalworking centers. Arthroscopy procedure volumes in industrialized economies drive regional demand patterns.
United States
Texas and Florida ASCs deploy disposable shaver systems to minimize turnover delays between high-volume shoulder cases. FDA 510(k) clearance pathways compress product launch windows for blade geometry modifications. Minneapolis medical device corridor hosts service contract engineering teams supporting bundled instrument-replacement programs.
Germany
Bavarian orthopedic distributors face six-month notified body delays as EU MDR technical documentation requirements saturate conformity assessment capacity. REACH compliance obligations constrain polymer sheath material substitutions in cutting insert assemblies. Tuttlingen surgical instrument cluster maintains precision milling capabilities for shaver blade geometries.
Japan
Kanto region sports medicine clinics pilot rechargeable shaver systems for satellite surgery centers serving aging osteoarthritis patients. PMDA consultation procedures extend development timelines for ultrasonic platform modifications. Osaka medical device corridor evaluates radiofrequency-enhanced shavers for meniscal resection workflows.
United Kingdom
London integrated delivery networks consolidate arthroscopy vendor relationships around full-procedure portfolios spanning shavers and visualization systems. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements. Midlands manufacturing corridor supplies private-label blade assemblies to distributor networks.
South Korea
Seoul Capital Area manufacturers leverage ISO 13485 certification credentials to supply disposable cutting inserts for Southeast Asian distributor networks. MFDS quality management inspections align with EU MDR technical documentation standards. Busan-Ulsan medical device cluster produces electromechanical handpiece components for regional OEM supply.
Arthroscopic Shaver Market Vendor Landscape
Captive manufacturing investments dominate the current landscape as suppliers secure in-house milling capabilities for precision insert geometries. The vendor base concentrates around three tiers: integrated multinationals with full-procedure portfolios, mid-tier specialists in electromechanical handpieces, and emerging private-label blade suppliers from East Asian manufacturing corridors. Strategic archetypes include bundled service contract providers, disposable architecture innovators, and ultrasonic platform developers. Competitive intensity centers on regulatory certification speed and field engineering network density.
Within the integrated multinational tier, Medtronic, Stryker, and Smith & Nephew exemplify full-procedure portfolio positioning. Medtronic represents the service-contract archetype with North American field engineering infrastructure. Stryker anchors bundled instrument-replacement program offerings. Smith & Nephew occupies the broad electromechanical portfolio position across hospital network procurement committees. Arthrex and Zimmer Biomet sit within the precision-manufacturing specialist category, with Arthrex exemplifying in-house milling capability and Zimmer Biomet representing orthopedic-focused diversification. CONMED Corporation and Olympus Corporation occupy visualization-integrated positioning, while KARL STORZ anchors German-engineered surgical instrument heritage.
| Leading Market Players |
|---|
| Medtronic |
| Zimmer Biomet |
| Arthrex |
| DePuy Synthes |
| KARL STORZ |
| Stryker |
| CONMED Corporation |
| Olympus Corporation |
| Smith & Nephew |
| Others |
Supply Flow & Price Mechanics
Nickel-chromium alloy feedstock from Pittsburgh and Sheffield mills cascades through three pricing tiers determined by ISO 13485 certification status and bundled field service coverage. Hospital procurement committees in Texas and Florida negotiate multi-year service contracts that embed blade replacement costs within capital equipment financing, while ambulatory surgical centers in Germany transact per-procedure disposable pricing without warranty infrastructure.
Pricing Analysis
Warranty bundling separates premium tier positioning from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, volume commitment scale, and geographic proximity to service engineering networks. Pricing pressure stems from stainless steel input volatility squeezing margin on disposable blade portfolios. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure cost accounting, whereas integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand in the United States, while distributor-mediated pathways serve German orthopedic clinics and Japanese sports medicine practices. Manufacturing concentrates in the United States, Germany, and South Korea, with Tuttlingen and Minneapolis hosting precision milling clusters for blade geometries. Supply chains draw from nickel-chromium alloy feedstock, polymer sheath materials, and electromechanical motor assemblies. Single-source vulnerability concentrates in captive blade manufacturing capabilities controlled by top-tier suppliers. Distribution runs through hospital materials management, GPO contracts, and regional orthopedic distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity saturation under EU MDR technical documentation requirements props pricing power by extending competitor entry timelines. Manufacturing bottlenecks in precision insert milling constrain supply expansion.
For Market Incumbents: Anticipate ultrasonic platform substitution threatening electromechanical dominance in meniscal procedures by accelerating radiofrequency-enhanced shaver development. Defend position through backward integration into nickel-chromium alloy supply and expanded ISO 13485 certification scope for polymer sheath innovations. Prioritize field engineering network density in Texas and Florida ASC corridors to lock in bundled contract renewals.
For New Entrants and Emerging Players: Private-label blade suppliers serving Southeast Asian distributor networks represent the most penetrable buyer archetype. Target South Korean and Taiwanese manufacturers with ISO 13485 credentials seeking CE marking pathway partnerships. Pursue hybrid disposable-rechargeable system development to bridge hospital and ambulatory preference divides without competing directly on electromechanical handpiece durability.
For Investors and Strategic Acquirers: Six-month notified body delays in Germany are the leading indicator that regulatory certification speed will determine competitive survival. Position portfolios toward mid-tier specialists with captive milling capabilities and established EU MDR technical documentation portfolios. Monitor ultrasonic platform adoption rates in German and Japanese sports medicine clinics as inflection signal for technology substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates cross-border distribution by reducing redundant conformity assessments across member states. |
| Captive Blade Manufacturing Expansion | Secures supply continuity for precision insert geometries amid contract manufacturer bottlenecks. |
| Hybrid Disposable-Rechargeable Development | Bridges procurement preference divides between hospital durability requirements and ASC turnover efficiency. |
| Ultrasonic Platform Clinical Validation | Positions soft-tissue selective resection for meniscal applications in German and Japanese clinics. |
| Service Contract Engineering Network Buildout | Supports bundled instrument-replacement programs that lock in multi-year hospital procurement commitments. |
Methodological Framework
Multi-period observation of arthroscopy procedure volumes, FDA 510(k) clearance timelines, and EU MDR recertification backlogs anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and orthopedic distributor principals. Secondary validation drew from FDA device listings, EUDAMED registration databases, hospital procurement records, and CMS outpatient procedure coding data. Bottom-up modeling of installed base replacement cycles triangulated against top-down market sizing across product type, end user, technology, application, and regional regulatory cluster dimensions.
Input-output matrices mapped electromechanical handpiece durability curves, disposable shaver adoption rates in ambulatory settings, and ultrasonic platform penetration trajectories across the projection horizon. Segmentation dimensions spanned power modality, procurement architecture, procedure type, and facility certification tier. CAGRs were derived from regression analysis of historical procedure growth correlated with demographic osteoarthritis prevalence and sports medicine infrastructure expansion. Forecast inputs included nickel-chromium alloy price indices and notified body capacity utilization rates.
Revisions become necessary when EU MDR technical documentation requirements intensify, FDA 510(k) predicate equivalence pathways narrow, or ultrasonic platform clinical evidence accelerates technology substitution beyond modeled rates. Forecasts reflect assumptions regarding reimbursement stability for outpatient arthroscopy and stainless steel feedstock supply continuity. Periodic stress-testing of base assumptions against regulatory filing backlogs and raw material price volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Hand and Wrist Devices Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Thoracolumbar Stabilization Devices Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Tracheostomy Tubes Market
Medical Devices
Nerve Locator Stimulator Market