
 North America Surgical Glue Market | 2026-2036
North America Surgical Glue Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surgical Glue Market Insights
Domestic biopolymer production capacity in the United States is realigning toward medical-grade raw material streams. Baxter International leverages its plasma-derived protein supply chain to sustain fibrin glue output at scale. Johnson & Johnson (Ethicon) anchors its position through integrated R&D across cyanoacrylate formulations. Medtronic competes by controlling distribution into integrated hospital networks.
Surgical glue comprises biocompatible adhesive formulations—fibrin sealants derived from human plasma proteins, synthetic cyanoacrylate polymers, and collagen-based compounds—that polymerize upon tissue contact to achieve hemostasis and wound closure without mechanical suturing. These materials function through exothermic or enzymatic cross-linking reactions that form flexible bonds across moist biological surfaces, serving primarily to reduce operative time and postoperative infection risk in open and minimally invasive procedures. Cyanoacrylate formulations dominate current volume due to rapid setting speed and broad surgical applicability. Fibrin glue occupies premium positioning where bioresorbability and minimal inflammatory response command higher reimbursement. Albumin-based variants represent the fastest-growing chemistry subset as manufacturers refine recombinant production methods.
The FDA Class II device pathway governs premarket notification requirements for tissue adhesives, while ISO 10993 biocompatibility standards shape material testing protocols across North American manufacturing facilities. Health Canada and the FDA coordinate on post-market surveillance for adverse tissue reaction reporting, tightening quality documentation burdens on importers. The Centers for Medicare & Medicaid Services reimbursement thresholds for outpatient surgical procedures directly influence hospital procurement decisions between premium sealants and conventional closure methods. Stakeholders must monitor evolving FDA guidance on synthetic versus biological origin classifications, as this distinction increasingly determines coverage eligibility and competitive positioning across hospital formularies.
Market Dynamics
FDA's updated Class II medical device guidance for tissue adhesives is compressing product development timelines while forcing manufacturers to accelerate biocompatibility testing investments. This regulatory recalibration is reshaping competitive positioning across hospital procurement channels.
Growth Catalysts
- Bioresorbability Standards:Albumin-based formulations are gaining formulary preference as academic medical centers prioritize inflammatory response profiles. Recombinant production methods are expanding supply security for these variants.
- United States:CMS reimbursement thresholds for outpatient procedures are tilting hospital purchasing toward premium sealants over conventional closure. Northeast and Midwest corridor systems are leading this shift.
- Minimally Invasive Surgery:Laparoscopic and robotic platforms are expanding glue-based closure protocols. General surgery departments are formalizing these standards to reduce operative time and suture-related complications.
Market Restraints
- Plasma Protein Supply:Fibrin glue output depends on fractionated human plasma availability. Baxter International's captive supply chain concentration creates vulnerability to donor pool fluctuations.
- ISO 10993 Testing Burden:Biocompatibility protocol expansion is extending premarket notification timelines. Small manufacturers face disproportionate compliance cost absorption.
- Synthetic Cyanoacrylate Substitution:Lower-cost polymer alternatives are pressuring premium biologic positioning. Hospital value-analysis committees are widening cost-effectiveness evaluations.
Strategic Opportunities
- Canada:Health Canada and FDA post-market surveillance coordination is tightening quality documentation requirements. Importers with dual-compliance infrastructure can capture underserved provincial health system contracts.
- Emergency Medicine:Trauma bay applications for rapid hemostasis remain underpenetrated. Field-deployable formulations could extend usage beyond operating theater environments.
- Biological Origin Classification:Evolving FDA guidance on synthetic versus biologic designation is determining coverage eligibility. Manufacturers with flexible chemistry platforms can pivot classification strategies.
Industry Challenges
- Biopolymer Talent Scarcity:Medical-grade raw material stream realignment requires polymer scientists with FDA submission experience. Recruitment competition from pharmaceutical and device sectors is intensifying.
- Integrated Network Certification:Medtronic's hospital network distribution control demands vendor qualification across multiple IDN platforms. Smaller manufacturers face protracted credentialing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surgical Glue Market |
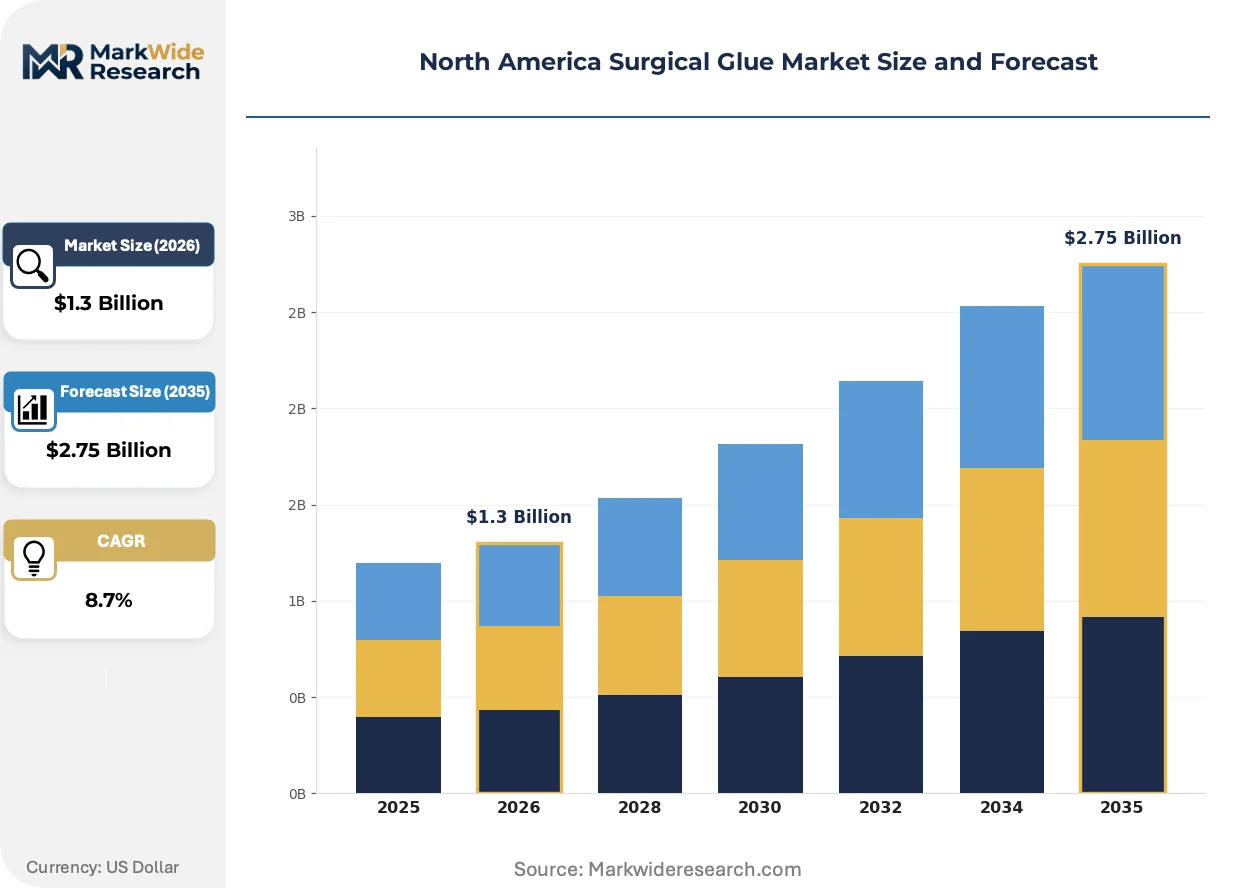
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
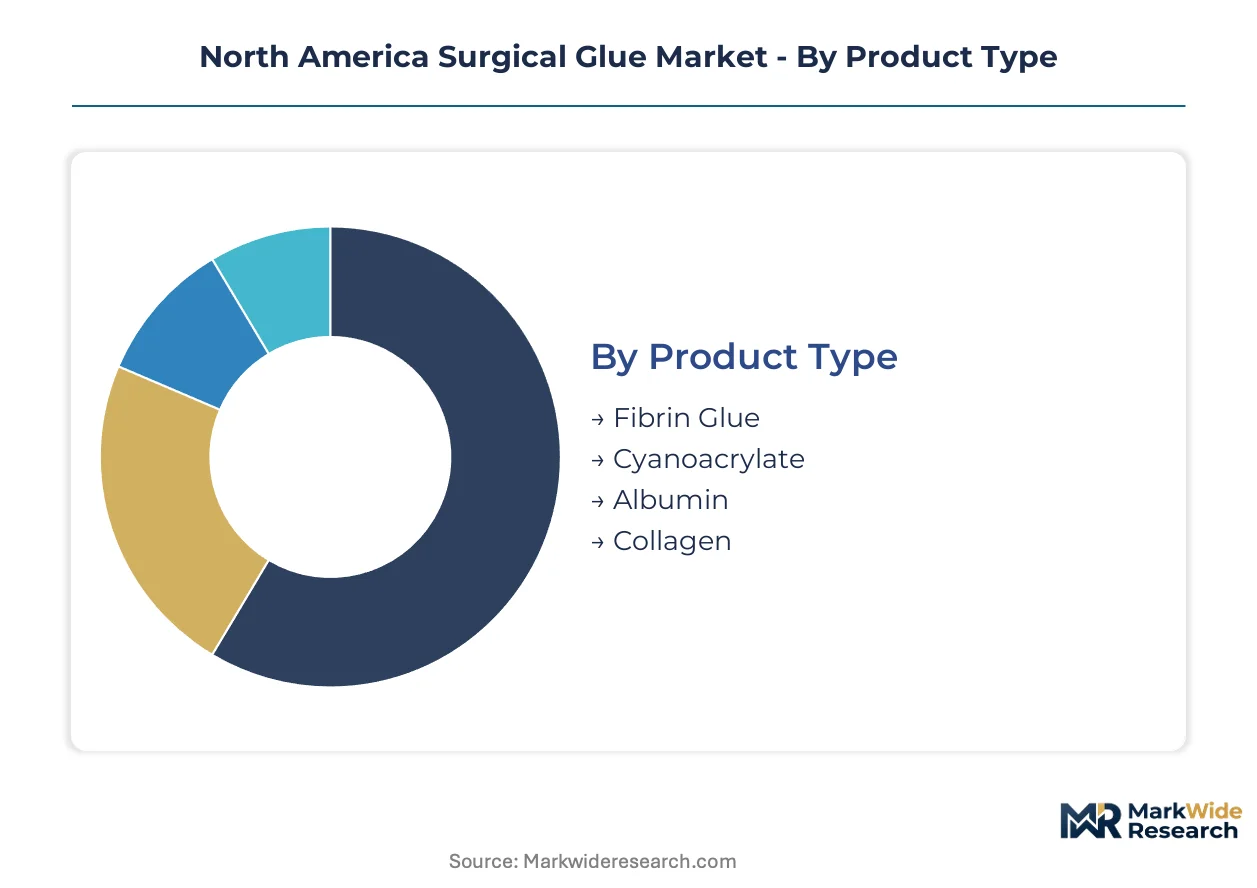
| Segmentation | Product Type: Fibrin Glue, Cyanoacrylate, Albumin, Collagen End User: Hospitals, Outpatient Clinics, Specialty Clinics, Surgical Centers Application: Wound Closure, Tissue Adhesion, Hemostasis, Surgical Procedures Distribution Channel: Direct Sales, Retail Pharmacies, Online Sales, Wholesalers |
| Companies Covered | Baxter International, Johnson & Johnson (Ethicon), Medtronic, CryoLife, Integra LifeSciences Corporation, B. Braun Melsungen, Cardinal Health, Artivion, C.R. Bard (BD), Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surgical Glue Market Trends and Innovations
Formulation chemistry convergence and procurement digitization are compressing traditional competitive moats. Three developments are restructuring how value flows through the surgical closure ecosystem.
Albumin-based sealants are overtaking collagen compounds in premium positioning. Academic medical centers in the Northeast corridor are adopting these formulations for their recombinant production scalability and reduced immunogenicity profile. This chemistry shift is enabling manufacturers to command sustained reimbursement premiums while compressing plasma-dependent supply risks.
FDA Class II device pathway refinements are accelerating premarket notification review velocity for synthetic origin products. The industrial consequence is a bifurcation in competitive strategy: biologic manufacturers emphasize clinical differentiation while synthetic producers exploit speed-to-market advantages. Cyanoacrylate formulations are responding by expanding indication breadth through 510(k) predicate stacking.
Hospital value-analysis committees are consolidating supplier rosters around integrated service agreements. Group purchasing organizations are displacing individual hospital procurement autonomy in the Midwest corridor. This concentration is most visible in tertiary care systems where standardization across multiple campuses drives formulary rationalization.
North America Surgical Glue Market Segmentation
Surgical glue segmentation in North America tracks how formulation chemistry, care setting, and procurement channel intersect with regulatory classification. FDA Class II device pathways and CMS reimbursement tiers create divergent commercial trajectories across each dimension.
Product Type:
FDA Class II premarket notification requirements vary sharply by biological versus synthetic origin, with fibrin and albumin derivatives facing extended ISO 10993 biocompatibility protocols compared to cyanoacrylate polymers.
- Cyanoacrylate:Synthetic polymer formulations polymerize rapidly through exothermic reactions upon tissue contact. Demand concentrates in general surgery departments across Midwest hospital systems seeking operative time reduction without plasma supply dependencies.
- Fibrin Glue:Plasma-derived protein sealants achieve hemostasis through enzymatic cross-linking mimicking natural clotting cascades. Northeast academic medical centers prioritize these formulations where bioresorbability commands premium reimbursement despite donor pool vulnerability.
- Albumin:Recombinant production methods are expanding supply security for these variants with reduced immunogenicity profiles.
- Collagen:Animal-derived compounds serve niche applications where structural scaffolding properties outweigh cost considerations.
Cyanoacrylate sits at the top of the volume ranking, with albumin climbing the fastest.
End User:
Procurement autonomy varies dramatically across care settings, with integrated delivery networks consolidating purchasing power while outpatient channels retain vendor selection flexibility.
- Hospitals:Tertiary care systems with expanded general surgery departments are formalizing glue-based closure protocols to reduce suture-related complications and operative time. Value-analysis committees in these institutions are widening cost-effectiveness evaluations between premium sealants and conventional closure.
- Surgical Centers:Ambulatory facilities face CMS reimbursement thresholds that directly influence procurement decisions between premium biologics and synthetic alternatives. These settings prioritize rapid-setting formulations that compress procedure schedules.
- Outpatient Clinics:Limited procedure volumes restrict formulary breadth to multi-application sealants.
- Specialty Clinics:Narrow clinical focus supports indication-specific adhesive selection.
Hospitals capture the dominant procurement volume, though surgical centers are expanding most quickly as procedure migration accelerates.
Application:
Clinical indication determines polymer selection criteria, with hemostasis applications tolerating broader inflammatory profiles than cosmetic-sensitive wound closure.
- Hemostasis:Rapid bleeding control in open and minimally invasive procedures drives volume concentration. Laparoscopic and robotic platforms are expanding glue-based protocols across general surgery departments in the United States.
- Wound Closure:Cosmetic outcome sensitivity in visible anatomical regions elevates biologic formulation preference. Academic medical centers prioritize albumin-based and fibrin sealants where inflammatory response minimization justifies reimbursement premiums.
- Tissue Adhesion:Structural bonding applications favor cyanoacrylate setting speed over bioresorbability.
- Surgical Procedures:Broad indication category encompasses multi-application sealant deployment.
Hemostasis leads application volume, while wound closure gains share fastest on cosmetic outcome prioritization.
Distribution Channel:
Channel selection reflects procurement scale and formulary standardization pressure, with direct sales dominating institutional contracts and retail channels serving fragmented outpatient demand.
- Direct Sales:Manufacturer-controlled distribution into integrated hospital networks and group purchasing organizations. Medtronic and integrated delivery network certification requirements favor established vendors with multi-platform vendor qualification infrastructure.
- Wholesalers:Regional distributors serve mid-tier hospital systems and surgical centers with consolidated logistics. These intermediaries are displacing individual hospital procurement autonomy in the Midwest corridor through standardized formulary offerings.
- Retail Pharmacies:Limited to postoperative patient-directed sealant products.
- Online Sales:Emerging channel for specialty clinic and outpatient replenishment.
Direct sales commands institutional procurement volume, with wholesalers capturing the steepest expansion trajectory through GPO consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's regulatory coordination with the United States creates dual-compliance advantages for importers, while Mexico's manufacturing proximity offers supply chain alternatives for North American distribution networks.
United States
FDA Class II device pathway refinements are compressing premarket notification timelines for synthetic origin products. CMS reimbursement thresholds for outpatient procedures directly influence hospital procurement decisions between premium sealants and conventional closure methods. Northeast corridor academic medical centers are formalizing glue-based closure protocols to reduce operative time and suture-related complications.
Canada
Health Canada's post-market surveillance coordination with the FDA tightens quality documentation burdens on importers. Provincial health systems in Ontario and Quebec prioritize bioresorbable formulations where inflammatory response profiles justify reimbursement premiums. Dual-compliance infrastructure enables vendors to capture underserved contracts across Canadian integrated delivery networks.
Mexico
Manufacturing proximity to United States distribution hubs offers supply chain alternatives for North American market coverage. Mexico's national pharmaceutical regulator maintains alignment with ISO 10993 biocompatibility standards for imported medical devices. Northern border states concentrate contract manufacturing operations serving United States hospital procurement channels.
North America Surgical Glue Market Competitive Landscape
United States producers anchor one tier; European specialists hold positions through plasma-derived protein supply chains. The vendor base clusters around three strategic archetypes: integrated medical device conglomerates controlling hospital network distribution, biologics specialists leveraging captive plasma fractionation capabilities, and synthetic polymer manufacturers exploiting speed-to-market advantages. Dominant competitive moves include strategic partnerships with group purchasing organizations and portfolio diversification across biological and synthetic chemistry platforms.
Within the integrated conglomerate tier, Baxter International and Johnson & Johnson (Ethicon) exemplify divergent strategic positioning. Baxter represents the plasma-derived protein supply chain concentration, while Johnson & Johnson anchors cyanoacrylate formulation integration. Medtronic occupies a position emphasizing distribution control into integrated hospital networks.
| Leading Market Players |
|---|
| Baxter International |
| Johnson & Johnson (Ethicon) |
| Medtronic |
| CryoLife |
| Integra LifeSciences Corporation |
| B. Braun Melsungen |
| Cardinal Health |
| Artivion |
| C.R. Bard (BD) |
| Others |
Pricing and Supply Chain Analysis
Fractionated human plasma protein spot prices cascade through surgical glue manufacturing into three distinct procurement tiers. Hospital value-analysis committees translate raw-material volatility into formulary preference shifts between biologic and synthetic sealants.
Pricing Analysis
Distributor margins compress as group purchasing organizations consolidate Midwest hospital procurement. Three-tier pricing structure across premium fibrin sealants, mid-grade albumin formulations, and economy cyanoacrylate polymers dominates institutional contracts. Price differentiation hinges on ISO 10993 certification tier and plasma-protein origin classification. Cost compression in the synthetic tier intensifies because hospital value-analysis committees are widening cost-effectiveness evaluations. Surgical centers exhibit highest price sensitivity; academic medical centers in the Northeast corridor demonstrate lowest sensitivity due to reimbursement premium capture.
Supply Chain Analysis
Plasma protein supply rests on United States donor pool concentration and European fractionation facility output. Raw material streams draw from human plasma collection centers, recombinant albumin fermentation facilities, and specialty cyanoacrylate monomer producers. Single-source vulnerability concentrates in Baxter International's captive plasma supply chain. Distribution runs through direct manufacturer-to-hospital contracts and regional wholesaler intermediaries serving surgical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
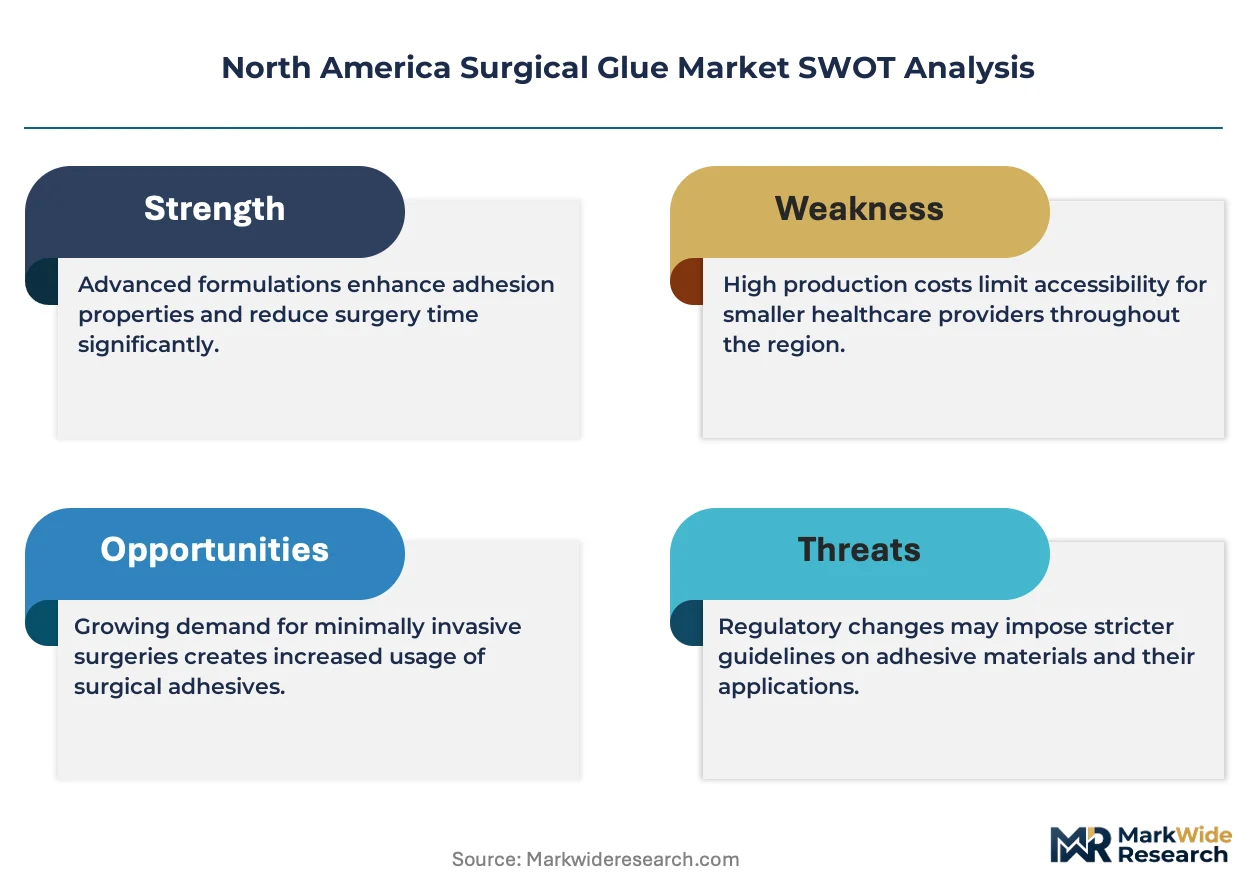
The North America surgical glue market represents a late-cycle quality story as academic medical centers shift procurement criteria toward inflammatory response profiles and bioresorbability specifications.
For Market Incumbents: Anchor market position through dual-chemistry platform maintenance across fibrin and synthetic portfolios. Plasma supply chain concentration creates vulnerability to donor pool fluctuations; backward integration into recombinant albumin production mitigates this exposure. FDA Class II device pathway refinements reward manufacturers with established 510(k) predicate libraries. For New Entrants and Emerging Players: Direct-to-surgical-center digital procurement portals offer lowest barrier to initial contract capture. Emergency medicine trauma bay applications remain underpenetrated relative to operating theater saturation. Target provincial Canadian health systems with dual FDA-Health Canada compliance infrastructure as beachhead expansion vector. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic polymer manufacturers possessing rapid 510(k) pathway navigation capabilities. Five-to-ten year viability favors platforms with flexible chemistry classification strategies. Watch FDA guidance evolution on synthetic versus biological origin designation as inflection indicator for reimbursement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Synthetic origin products gain speed-to-market advantage over biologics facing extended ISO 10993 protocols. |
| Recombinant Albumin Scale-Up | Manufacturers reduce plasma dependency while commanding premium positioning in academic medical center formularies. |
| Group Purchasing Organization Consolidation | Midwest hospital network standardization displaces individual procurement autonomy toward centralized supplier rosters. |
| Dual-Compliance Infrastructure Investment | Importers capture underserved Canadian provincial contracts through coordinated FDA-Health Canada quality documentation. |
| Emergency Medicine Formulation Development | Field-deployable hemostasis products extend usage beyond traditional operating theater environments into trauma bays. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down plasma fractionation capacity tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and ISO 10993 biocompatibility registries. Triangulation between demand-side formulary adoption patterns and supply-side manufacturing capacity ensures statistical integrity.
Input-output matrices map formulation chemistry segmentation against end-user procurement channel dynamics across the projection horizon. Segmentation dimensions include product type, care setting, clinical application, and distribution channel. CAGRs derive from regression analysis of historical adoption curves calibrated to reimbursement threshold shifts. Forecast inputs incorporate plasma donor pool trends and CMS outpatient procedure reimbursement trajectories.
The model assumes a particular technology adoption path; alternative pathways for recombinant albumin production scaling would alter the outlook. Forecasts reflect assumptions about regulatory pathway stability and plasma supply security. A small set of named triggers—FDA origin classification guidance evolution, donor pool fluctuation events, and GPO consolidation acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Anti Venom Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market