
 Vascular Access Catheters Market | 2026-2036
Vascular Access Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Access Catheters Market Analytics
Multi-source procurement for catheter raw materials is restructuring supply relationships across the vascular access industry. Becton, Dickinson and Company leverages backward integration into polymer compounding to secure silicone and polyurethane supply chains. Teleflex Incorporated anchors its position through specialized manufacturing of peripherally inserted central catheter lines. B. Braun SE competes on geographic dominance with extensive European production footprints and hospital direct contracts.
Vascular access catheters are sterile, flexible tubes manufactured from medical-grade silicone, polyurethane, or hydrogel composites, designed for percutaneous insertion into veins to enable infusion therapy, hemodynamic monitoring, or blood withdrawal. Central line catheters command premium pricing due to complex tip-positioning requirements and infection-risk protocols, while peripheral catheters dominate procedure volume in emergency and short-stay settings. Dialysis catheters represent the fastest-expanding product category as home-based renal replacement therapy gains reimbursement traction. Material selection increasingly favors polyurethane for its tensile strength and kink resistance in high-flow applications.
FDA enforces stringent biocompatibility and sterility standards under 21 CFR Part 820 quality system regulations, while EMA's Medical Device Regulation mandates clinical evidence for catheter longevity claims. ISO 10555 sets international benchmarks for intravascular catheter mechanical performance and surface integrity. Stakeholders must monitor evolving reimbursement pathways for outpatient catheter placement and antimicrobial-coated device categories.
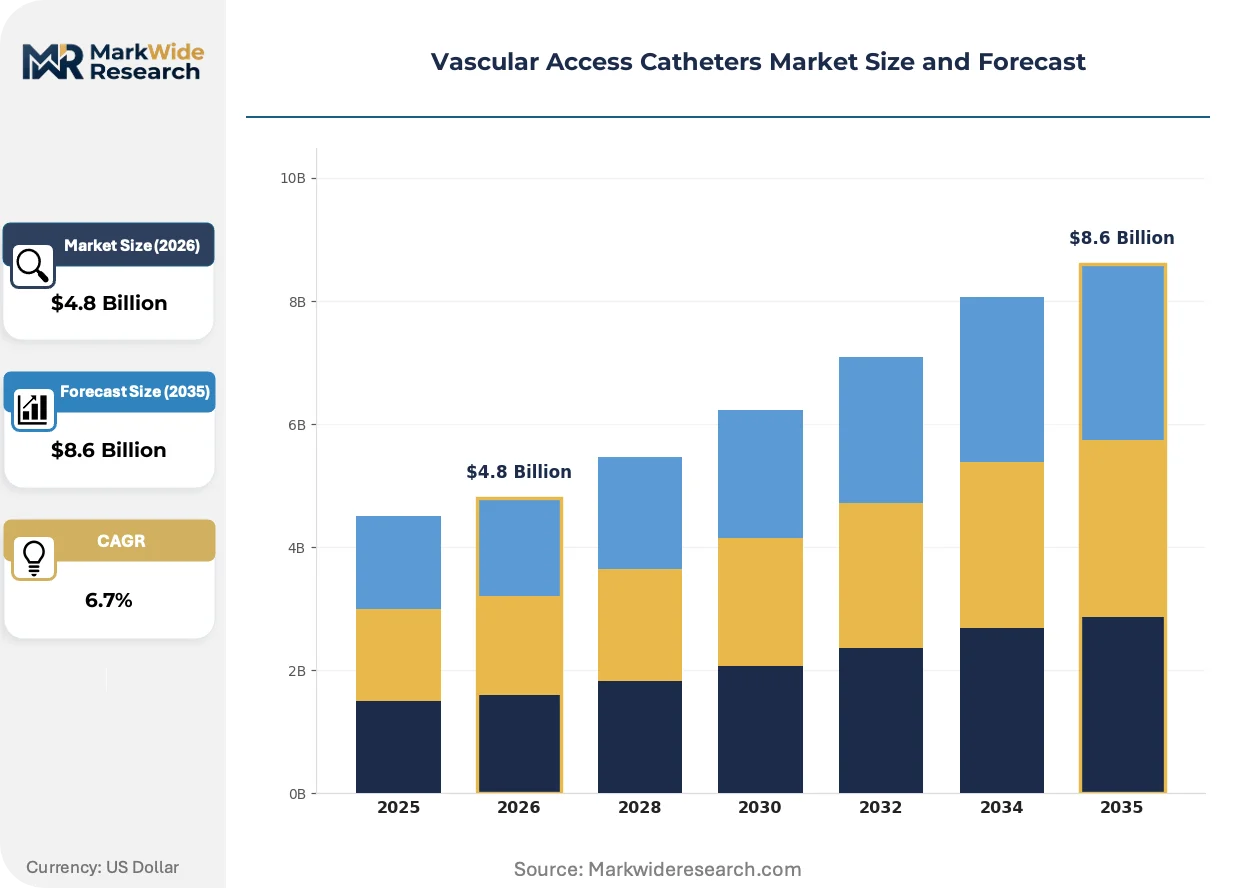
Market Dynamics
Antimicrobial coating mandates under FDA 21 CFR Part 820 and EMA MDR are forcing catheter manufacturers to restructure material supply chains and validation protocols before product clearance.
Growth Catalysts
- Home dialysis reimbursement expansion:Medicare and private payers in the United States now cover peripherally inserted central catheter placement for renal replacement therapy outside hospital settings, accelerating ambulatory care device demand.
- ISO 10555 mechanical performance standards:International harmonization of tensile strength and kink resistance benchmarks enables manufacturers to design single platforms for multiple regulatory jurisdictions, reducing time-to-market friction.
- Chronic kidney disease prevalence clusters:Japan, Germany, and the United States exhibit concentrated patient populations requiring long-term vascular access, sustaining procedure volume growth in dialysis catheter categories.
Market Restraints
- Medical-grade silicone supply concentration:Polymer compounding capacity concentrates among three specialized chemical suppliers in Germany and the United States, exposing catheter manufacturers to input price volatility and allocation risk.
- Catheter-related bloodstream infection liability:FDA adverse event reporting requirements and malpractice exposure in the United States impose substantial post-market surveillance costs on device holders regardless of antimicrobial coating claims.
- Peripheral intravenous catheter substitution:Ultrasound-guided peripheral access techniques reduce central line placement necessity in emergency departments, compressing premium catheter pricing power in acute care settings.
Strategic Opportunities
- Antimicrobial coating technology convergence:Combination of silver ion release with hydrogel surface modification creates differentiated positioning against standard polyurethane devices in high-risk patient populations.
- Outpatient catheter placement channels:Ambulatory surgical centers and interventional radiology clinics in the United States are capturing procedures previously performed in hospital operating rooms, requiring tailored device form factors and kit configurations.
- EMA MDR clinical evidence pathways:Stricter longevity and biocompatibility documentation requirements favor manufacturers with established post-market registries, creating competitive moats against new entrants lacking longitudinal data assets.
Industry Challenges
- Polymer biocompatibility validation timelines:FDA 510(k) clearance for new catheter materials requires extensive cytotoxicity and hemocompatibility testing, extending product development cycles by 18-24 months.
- Interventional radiologist training gaps:Tip positioning for central venous access demands specialized ultrasound and fluoroscopy skills; workforce shortages in Japan and rural United States limit procedure expansion despite device availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Access Catheters Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Catheters, Central Line Catheters, Dialysis Catheters, Implantable Ports Indication: Chemotherapy, IV Administration, Nutritional Support, Blood Transfusion Material: Silicone, Polyurethane, PVC, Hydrogel End User: Hospitals, Ambulatory Surgical Centers, Home Care, Clinics |
| Companies Covered | Becton, Dickinson and Company, Teleflex Incorporated, ICU Medical, Inc., B. Braun SE, Medtronic, AngioDynamics, Inc., Terumo Corporation, Cook Medical, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Access Catheters Market Evolving Landscape
Material science advances and regulatory harmonization efforts are compressing the technology lifecycle for vascular access devices, with polyurethane formulations and antimicrobial surface treatments commanding disproportionate development investment.
Polyurethane catheter construction is consolidating market preference for high-flow dialysis and central venous applications. Hospital purchasing committees in the United States and Germany now specify tensile strength and kink resistance as mandatory technical criteria. This material shift is compressing silicone catheter share in acute care segments while elevating manufacturing complexity for suppliers lacking in-house polymer compounding capabilities.
EMA Medical Device Regulation clinical evidence requirements are restructuring competitive positioning across European markets. Manufacturers must now submit prospective data on catheter dwell times and infection rates to support longevity claims previously accepted on bench testing alone. Dialysis catheter portfolios face the steepest compliance burden, driving consolidation among vendors with established European post-market surveillance infrastructure.
Buyer consolidation among United States dialysis center chains is reshaping procurement negotiations and device specification authority. Large operators now mandate standardized catheter platforms across their clinic networks, displacing fragmented purchasing by individual nephrologists. This concentration is most visible in southeastern and midwestern states where private equity-backed renal care platforms have aggregated substantial market presence.
Vascular Access Catheters Market Segmentation
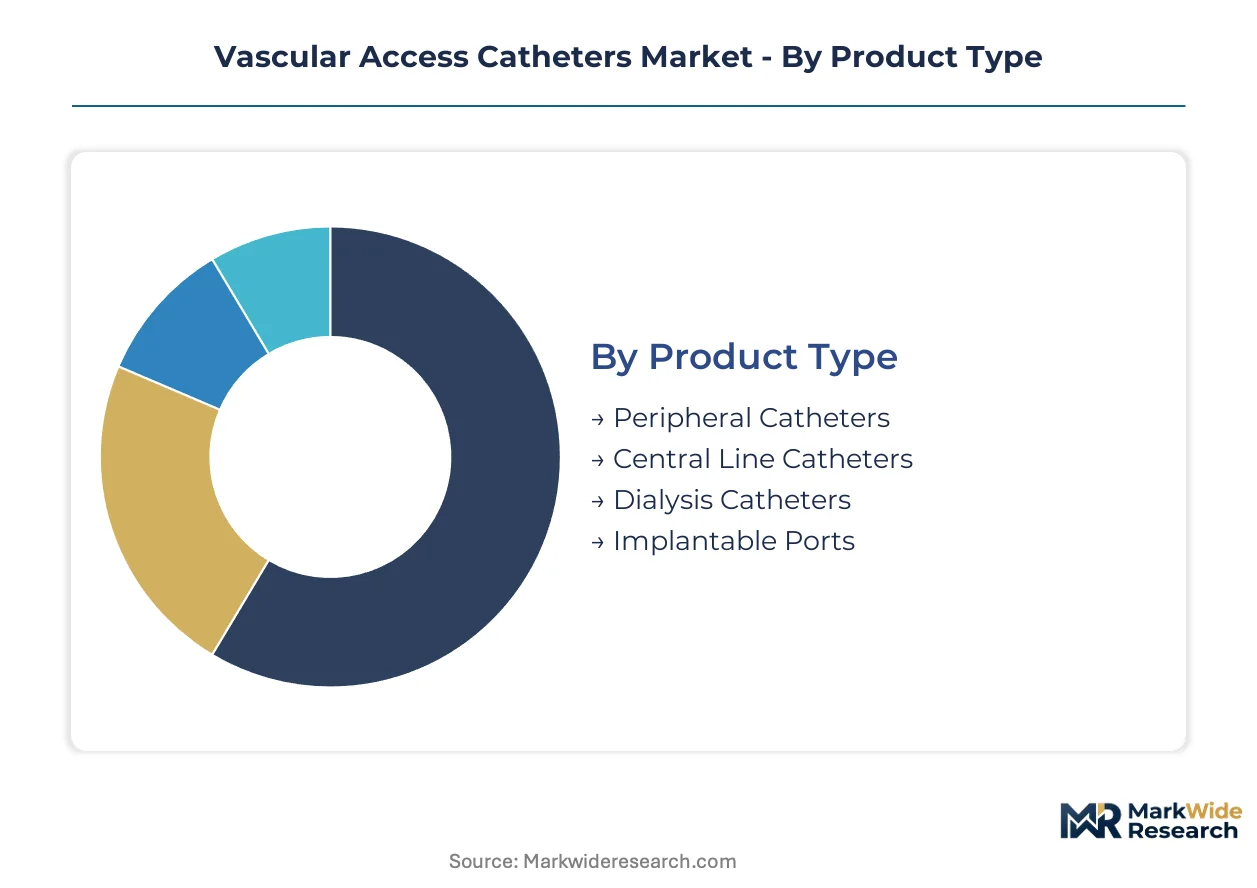
Vascular access catheter procurement diverges sharply across clinical settings, with material specifications and infection-risk protocols driving distinct sourcing patterns. Manufacturers must align production capacity with four intersecting dimensions: acute versus chronic care, institutional versus ambulatory channels, and premium versus standard material tiers.
Product Type:
Supply concentration for catheter manufacturing clusters around specialized polymer compounding capabilities, with polyurethane and silicone formulations requiring dedicated production lines that limit supplier flexibility.
- Peripheral Catheters:Short-length devices manufactured from PVC or standard polyurethane for emergency department and short-stay infusion therapy. Demand concentrates in United States hospital emergency departments where ultrasound-guided placement protocols sustain high procedure volumes despite compression of central line indications.
- Central Line Catheters:Multi-lumen devices with complex tip-positioning requirements and antimicrobial coating specifications for hemodynamic monitoring and extended infusion therapy. Japanese and German tertiary hospitals anchor demand due to stringent ICU infection control protocols and reimbursement premiums for coated devices.
- Dialysis Catheters:High-flow dual-lumen construction with reinforced polyurethane walls for renal replacement therapy.
- Implantable Ports:Subcutaneous reservoir systems with silicone septum for long-term intermittent vascular access.
Peripheral catheters absorb the bulk of installed capacity; dialysis catheters are expanding most quickly.
Indication:
Application-specific catheter requirements reshape manufacturing priorities, with chemotherapy and dialysis protocols demanding the most specialized material validation and coating technologies.
- Chemotherapy:Central venous access devices with power-injectable specifications and vesicant-resistant materials for oncology infusion protocols. United States cancer center networks and German university hospitals drive specification authority for implanted port configurations.
- IV Administration:Standard peripheral and midline catheters for medication and fluid delivery across acute and ambulatory settings. Japanese hospital purchasing consortia negotiate volume contracts that favor single-source supplier relationships for this high-frequency category.
- Nutritional Support:Dedicated parenteral nutrition catheters with lipid-compatible materials and minimal dead-space design.
- Blood Transfusion:Large-bore peripheral or central devices with filtered connections for rapid volume resuscitation.
IV administration commands the greatest production volume; chemotherapy applications carry the steepest margin profile.
Material:
Raw material sourcing geography directly constrains catheter manufacturing footprints, with medical-grade silicone supply concentrating among German and United States chemical compounders.
- Silicone:Platinum-cured elastomer with superior biocompatibility and flexibility for long-term implantable devices. Supply concentrates among three specialized polymer suppliers in Germany and the United States, exposing manufacturers to allocation risk during demand surges.
- Polyurethane:Aromatic and aliphatic formulations with tensile strength and kink resistance for high-flow dialysis and central venous applications. Japanese device makers and United States dialysis chains now mandate this material for acute care segments, displacing silicone in shorter-dwell indications.
- PVC:Standard plasticized formulation for cost-sensitive peripheral access in short-stay settings.
- Hydrogel:Surface-modified coating material for antimicrobial and lubricious properties.
Polyurethane claims the steepest expansion trajectory; silicone retains dominance in implantable and long-dwell categories.
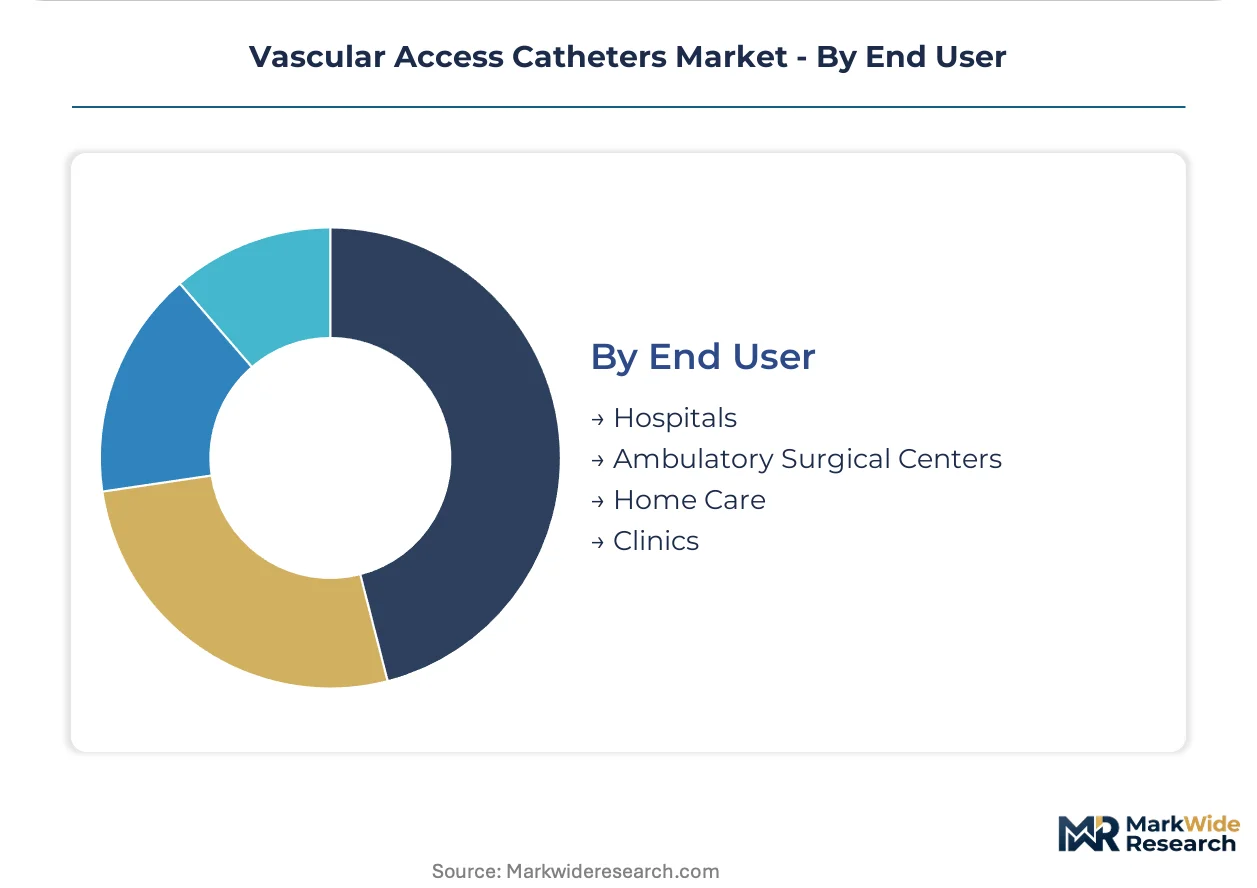
End User:
Channel consolidation among United States dialysis operators and ambulatory surgical center chains is compressing vendor diversity and standardizing device specifications across geographic markets.
- Hospitals:Integrated delivery networks with value-based purchasing committees that specify antimicrobial-coated central lines and power-injectable ports. German hospital procurement alliances and Japanese tertiary centers anchor premium pricing for validated coating technologies.
- Ambulatory Surgical Centers:Fast-turnover facilities requiring pre-packaged catheter kits with standardized configurations for interventional radiology placement. United States ASC networks in southeastern and midwestern states aggregate sufficient volume to displace individual physician purchasing authority.
- Home Care:Patient or caregiver-managed dialysis and infusion therapy outside institutional settings.
- Clinics:Physician office-based infusion and vascular access services.
Hospitals retain the largest absolute consumption; ambulatory surgical centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German polymer compounding clusters anchor raw material supply for catheter manufacturing, while procedure demand concentrates in aging populations across three continents. Regulatory frameworks in the United States, Germany, and Japan tighten infection control standards, reshaping procurement patterns and device specifications.
United States
Medicare reimbursement expansion for home dialysis and ambulatory surgical center procedures drives catheter volume growth. FDA enforces antimicrobial coating validation under 21 CFR Part 820 quality system regulations. Southeastern and midwestern states host consolidated dialysis center chains that now mandate standardized device platforms across clinic networks.
Germany
Hospital procurement alliances specify power-injectable ports and antimicrobial-coated central lines for tertiary ICU settings. EMA Medical Device Regulation mandates clinical evidence for catheter longevity claims beyond bench testing. Baden-Württemberg and North Rhine-Westphalia concentrate medical-grade silicone compounding capacity among specialized chemical suppliers serving European device manufacturers.
Japan
Chronic kidney disease prevalence clusters sustain long-term vascular access procedure demand in tertiary centers. PMDA aligns with ISO 10555 mechanical performance standards for tensile strength and kink resistance benchmarks. Tokyo and Osaka metropolitan areas anchor purchasing consortia that negotiate volume contracts favoring single-source supplier relationships for high-frequency catheter categories.
China
Domestic production capacity expansion targets import substitution for dialysis and central venous catheter categories. NMPA strengthens biocompatibility and sterility standards under revised medical device registration pathways. Yangtze River Delta manufacturing clusters attract polymer processing investments to reduce dependence on German and United States chemical compounders.
Vascular Access Catheters Market Competitive Landscape
Backward integration into polymer compounding dominates the current landscape as manufacturers seek captive supply of medical-grade silicone and polyurethane. The vendor base separates into three tiers: diversified medical technology conglomerates with full catheter portfolios, mid-cap specialists focused on interventional radiology placement systems, and regional fabricators serving contract manufacturing demand. Two strategic archetypes predominate: integrated suppliers controlling raw material through in-house compounding, and kit assemblers leveraging outsourced polymer supply. Competitive moves concentrate on geographic expansion through hospital direct contracts and technology licensing for antimicrobial surface treatments.
Among United States-based conglomerates, Becton, Dickinson and Company exemplifies the integrated archetype through upstream control over polymer supply chains, while Teleflex Incorporated occupies a position emphasizing specialized manufacturing capabilities. German competitor B. Braun SE anchors the European tier through extensive production footprints and established hospital procurement relationships. These three entities represent distinct strategic postures rather than uniform market approaches.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| ICU Medical, Inc. |
| B. Braun SE |
| Medtronic |
| AngioDynamics, Inc. |
| Terumo Corporation |
| Cook Medical |
| Merit Medical Systems |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up dialysis center operators in the southeastern and midwestern United States now wield consolidated purchasing power that compresses catheter pricing while demanding standardized device platforms across clinic networks. This ownership concentration simultaneously tightens payment terms for manufacturers and accelerates volume-based procurement shifts that favor suppliers with captive polymer compounding capabilities.
Pricing Analysis
Warranty and service bundling separates premium antimicrobial-coated central lines from uncoated standard devices, with validated infection-reduction claims commanding inclusion of post-market surveillance support. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating technology certification tier and volume commitment scale. Cost compression in the peripheral catheter tier is intensifying because ultrasound-guided placement protocols reduce central line necessity in emergency departments. Ambulatory surgical center chains exhibit highest price sensitivity; Japanese tertiary ICU purchasing committees show lowest sensitivity due to reimbursement premiums for coated devices.
Supply Chain Analysis
Reverse-logistics flows for explanted dialysis catheters remain underdeveloped, with limited refurbishment pathways constraining circular material recovery and elevating virgin polymer demand. Manufacturing gravity centers on Germany, the United States, and China, with medical-grade silicone compounding capacity tethered to specialized chemical suppliers in Baden-Württemberg and North Rhine-Westphalia. Raw material dependencies rest on platinum-cured silicone elastomers, aromatic polyurethane formulations, and silver-ion antimicrobial agents. Single-source vulnerability concentrates in German polymer compounders serving European device manufacturers. Distribution runs through hospital purchasing committees, GPO contracts, and direct agreements with consolidated dialysis operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EMA MDR clinical evidence requirements and FDA antimicrobial coating mandates force weaker players lacking post-market registries toward exit or acquisition.
For Market Incumbents: To counter substitution pressure from ultrasound-guided peripheral access techniques, deepen backward integration into polyurethane compounding to secure input cost stability, and expand post-market surveillance infrastructure to satisfy EMA longevity documentation requirements that create competitive moats against new entrants lacking longitudinal data assets. For New Entrants and Emerging Players: Begin with ambulatory surgical center channels in the United States southeastern states where private equity-backed renal care platforms have aggregated substantial market presence and standardized procurement favors new suppliers with kit configuration flexibility. Target home dialysis catheter placement outside institutional settings as the most penetrable segment, leveraging Medicare reimbursement expansion for peripherally inserted central catheter placement in renal replacement therapy. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with established European post-market surveillance infrastructure in Germany and Japan, where EMA MDR compliance burdens drive consolidation among vendors lacking longitudinal data assets. Long-term viability centers on manufacturers controlling captive polymer supply chains. Monitor FDA adverse event reporting trends for catheter-related bloodstream infections as early signals of antimicrobial coating efficacy differentiation and liability exposure concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Secures medical-grade silicone and polyurethane supply chains against allocation risk from German and United States chemical suppliers. |
| EMA MDR Clinical Evidence Pathway Investment | Builds post-market registries for catheter dwell times and infection rates that satisfy longevity documentation requirements beyond bench testing. |
| Antimicrobial Coating Technology Convergence | Combines silver ion release with hydrogel surface modification to differentiate against standard polyurethane devices in high-risk patient populations. |
| Ambulatory Surgical Center Channel Development | Captures procedures shifting from hospital operating rooms to interventional radiology clinics requiring tailored device form factors and kit configurations. |
| Hospital System Direct Contracting | Bypasses fragmented purchasing by individual nephrologists through agreements with consolidated dialysis center chains in southeastern and midwestern United States. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, interventional radiologists, and dialysis center operations directors. FDA 510(k) clearance databases, EMA Medical Device Regulation submission records, ISO 10555 mechanical performance standards, and hospital procurement databases provided validation layers. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Data-stream reconciliation across shipment records, import-export documentation, and institutional purchasing contracts informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompass product type, indication, material formulation, and end-user channel. CAGRs derived from procedure volume growth trajectories in dialysis and central venous access categories, calibrated against reimbursement pathway evolution and antimicrobial coating adoption curves.
Underlying measurement precision varies by segment; dialysis catheter forecasts carry tighter precision than peripheral catheter projections due to consolidated demand visibility from large operator chains. Forecasts reflect assumptions regarding Medicare reimbursement stability, EMA MDR enforcement timelines, and polymer supply chain resilience. Practitioners should monitor FDA adverse event reporting trends for catheter-related bloodstream infections and German chemical supplier allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Endovascular Therapy Devices Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Artificial Blood Vessels Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Cardiac Medical Device Market