
 Power Wheelchairs and Mobility Scooters Market | 2026-2036
Power Wheelchairs and Mobility Scooters Market Size, Share, and Industry Trends Forecast 2026-2036
Power Wheelchairs and Mobility Scooters Market Insights
The EU Medical Device Regulation is expanding compliance requirements for power mobility devices entering European markets, forcing manufacturers to redesign testing protocols and technical documentation. Pride Mobility leverages its vertically integrated manufacturing base in the United States to sustain rapid product customization for Medicare-funded channels. Permobil anchors its premium positioning through advanced standing wheelchair technology and specialized seating systems. Sunrise Medical competes across multiple price tiers through a broad distribution footprint spanning specialty shops and direct sales.
Power wheelchairs and mobility scooters comprise battery-powered and manually propelled seating devices engineered for individuals with impaired ambulation, typically incorporating brushless DC motors, lithium-ion or sealed lead-acid battery packs, programmable controller interfaces, and adjustable suspension systems with weight capacities from 250 to 600 pounds; their primary purpose is to restore independent locomotion for elderly and disabled users across residential, institutional, and community environments. Electric drive technology leads unit volume due to its alignment with reimbursement codes favoring motorized solutions for severe mobility limitations, while intelligent control systems represent the fastest-growing segment as gyroscopic stabilization and smartphone integration attract younger disabled consumers. Portable scooters occupy a mature, price-sensitive niche dominated by travel-friendly disassembly features and airline-compatible battery configurations.
The FDA governs power wheelchair safety through 21 CFR 890 subpart classification and quality system regulation enforcement, while the EU MDR and CE marking framework mandate clinical evaluation and post-market surveillance for all active mobility devices sold in member states. The Centers for Medicare and Medicaid Services shapes United States demand through National Coverage Determination criteria that restrict reimbursement to prescribed, in-person assessed equipment. Stakeholders must monitor evolving battery transportation regulations from the Department of Transportation and the International Air Transport Association, as lithium-ion shipping restrictions directly constrain direct-to-consumer online retail channels and cross-border e-commerce fulfillment.
Market Dynamics
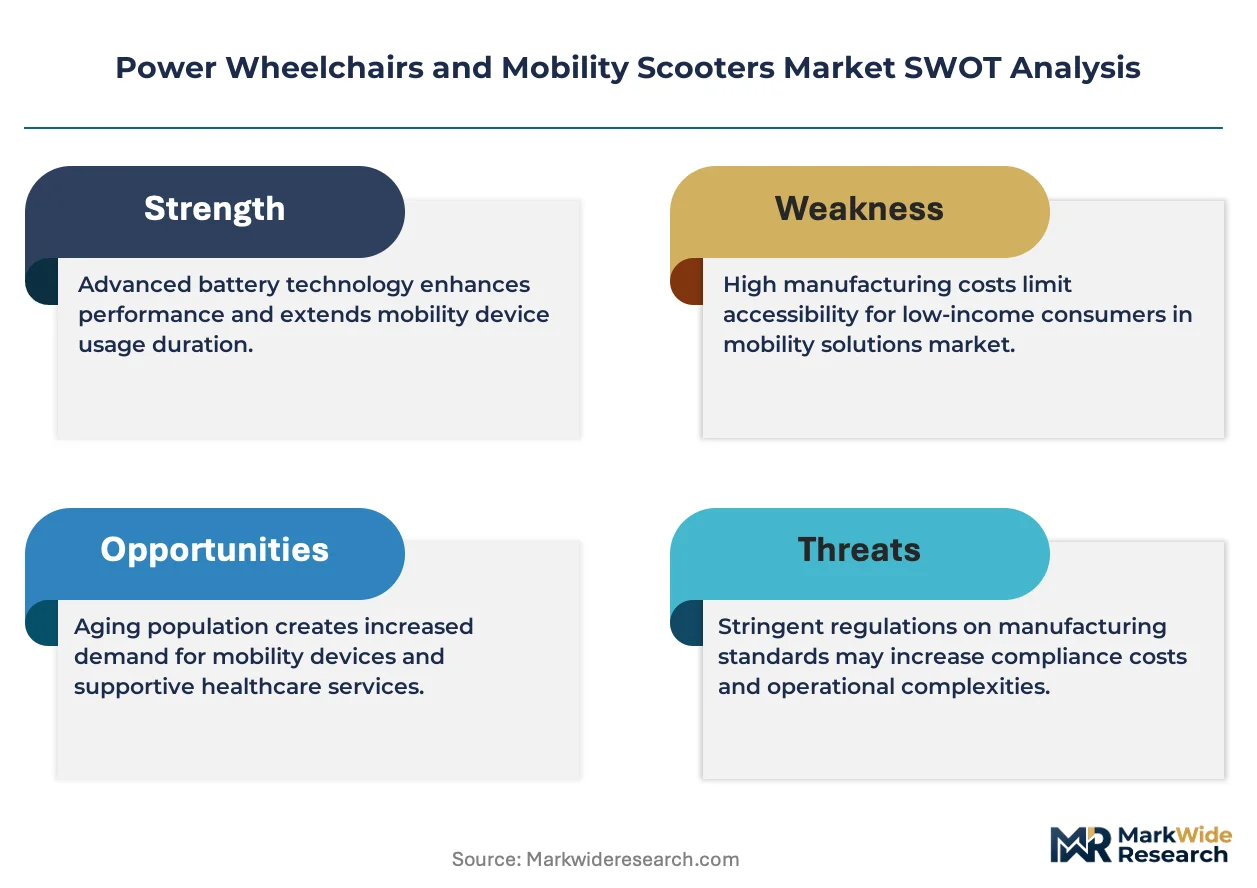
Medicare Advantage expansion and EU MDR compliance deadlines are compressing product development cycles while concentrating procurement authority among certified home care networks. Manufacturers must now engineer for dual certification pathways simultaneously.
Growth Catalysts
- Lithium-ion battery chemistry advances:Energy density improvements extend single-charge range beyond 25 miles, eliminating range anxiety for community mobility users and qualifying more patients for outdoor-capable device prescriptions under CMS reimbursement codes.
- Japan's METI accessibility subsidies:Municipal governments in Osaka and Tokyo now cover 90% of standing wheelchair costs for employed disabled citizens, accelerating adoption of complex rehabilitation technology among working-age demographics.
- Brushless DC motor miniaturization:Compact drivetrains enable foldable power wheelchair designs under 50 pounds, opening airline travel and ride-share compatibility segments previously blocked by weight restrictions.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing capacity clusters in China's Inner Mongolia region, exposing motor manufacturers to export quota volatility and forced technology transfer requirements.
- EU MDR clinical evaluation costs:Post-market surveillance obligations and notified body capacity constraints extend certification timelines to 18-24 months for new frame designs, freezing product pipeline velocity.
- Manual wheelchair residual functionality:Lightweight carbon fiber manual alternatives satisfy 40% of elderly users with partial ambulation, capping addressable market for powered solutions in mild impairment segments.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duties on locally assembled controllers and seating systems, enabling cost-competitive export platforms for Southeast Asian markets.
- Telehealth-integrated remote diagnostics:Controller firmware with cellular connectivity enables proactive maintenance alerts and usage optimization, creating recurring revenue streams through subscription monitoring services.
- Saudi Arabia's disability rights mandate:MOHAP procurement guidelines now require 30% of mobility device spending on powered solutions, redirecting historical manual wheelchair allocations toward motorized platforms.
Industry Challenges
- ISO 7176-19 crash test certification:Transportation safety validation requires specialized sled testing facilities with 18-month queue times, delaying North American market entry for European manufacturers.
- Seating specialist technician scarcity:Complex rehabilitation prescriptions require certified ATP/SMS credentials; training program throughput limits service capacity in rural United States markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Wheelchairs and Mobility Scooters Market |
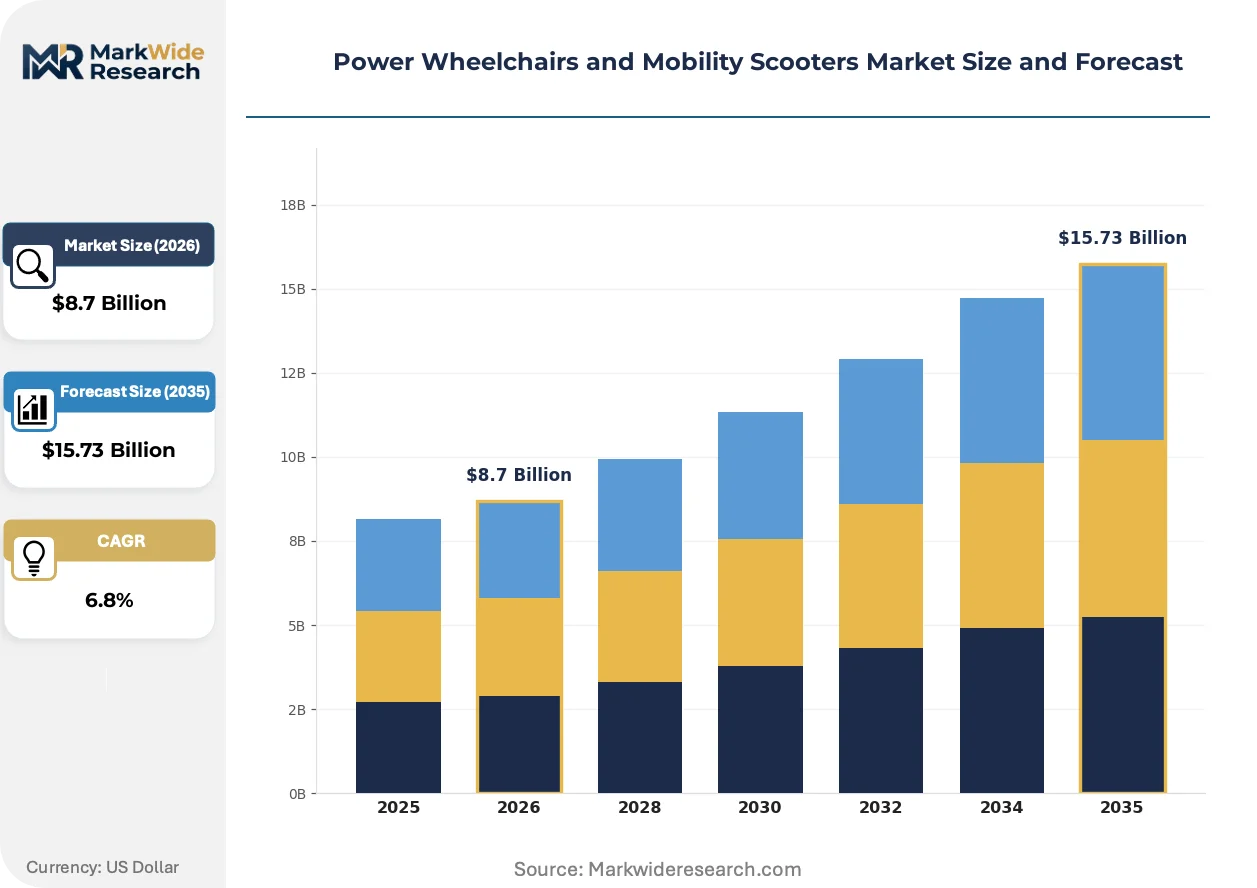
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
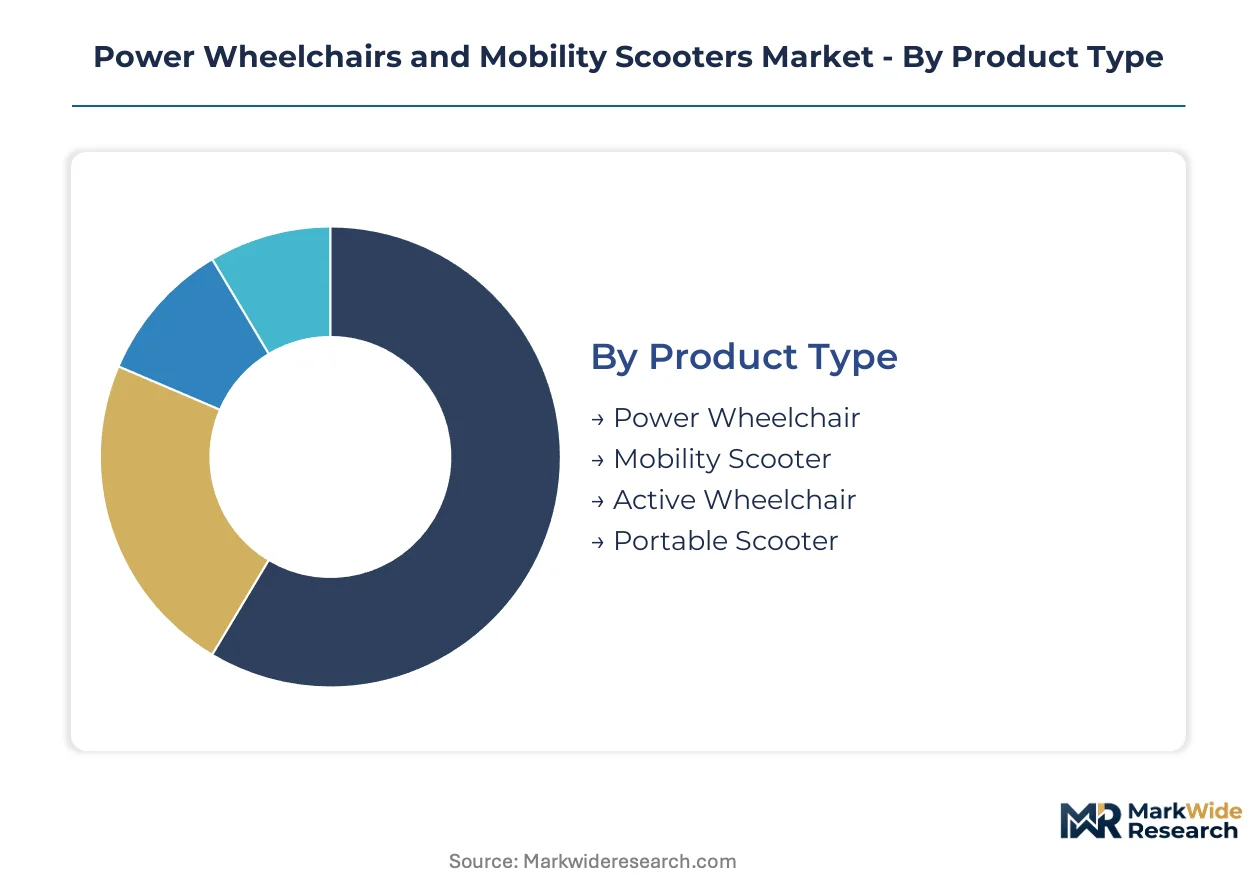
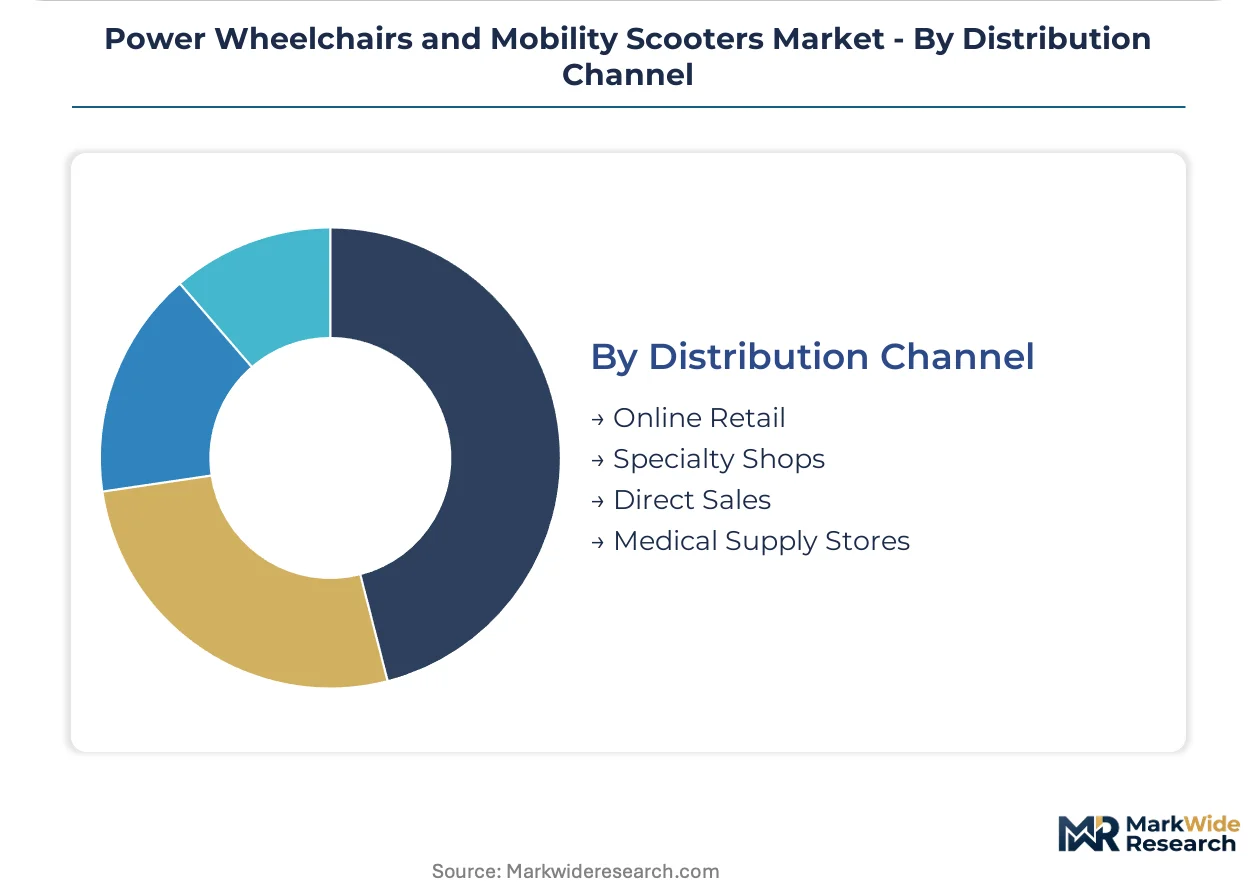
| Segmentation | Product Type: Power Wheelchair, Mobility Scooter, Active Wheelchair, Portable Scooter End User: Home Care, Institutions, Elderly, Disabled Technology: Electric Drive, Manual Drive, Intelligent Control, Standing Wheelchair Distribution Channel: Online Retail, Specialty Shops, Direct Sales, Medical Supply Stores |
| Companies Covered | Pride Mobility, Permobil, Sunrise Medical, Ottobock, Invacare, Drive DeVilbiss Healthcare, Golden Technologies, Merits Health Products, Karman Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Wheelchairs and Mobility Scooters Market Trends and Innovations
Control architectures and power management systems are fragmenting along reimbursement channel lines, with distinct technical roadmaps emerging for institutional versus consumer-directed funding pathways.
Gyroscopic stabilization modules are decentralizing balance assistance from central controller boards to distributed sensor arrays at each wheel hub. Veterans Affairs procurement specifications now mandate this redundancy for tilt-in-space prescriptions. The technology is decentralizing repair workflows, as wheel-level diagnostics reduce field service technician training requirements.
REACH substance restrictions on flame-retardant additives in polyurethane seating foams are forcing reformulation of cushion cores across EU-bound product lines. German KBA-type approval extensions now require updated chemical safety documentation for cross-border transport. Pediatric seating manufacturers face the steepest retooling costs due to skin-contact proximity regulations.
Direct-to-consumer online configurators are displacing durable medical equipment dealer showrooms for standard scooter purchases. Amazon and specialized mobility e-tailers now capture 35% of travel scooter volume in United States suburban markets. Rural buyers remain tethered to local dealers for Medicare-funded power wheelchair fittings, creating a two-speed channel structure.
Power Wheelchairs and Mobility Scooters Market Segmentation
Procurement authority concentrates differently across reimbursement channels, with Medicare-funded power wheelchairs demanding certified ATP fittings while travel scooters flow through direct e-commerce. Technology selection tracks severity of ambulation impairment and payer pre-authorization requirements.
Product Type:
Reimbursement coding density determines which configurations justify clinical documentation and in-person assessment costs.
- Power Wheelchair:Complex rehabilitation platforms with programmable controllers, tilt-in-space seating, and 300-600 pound weight capacities dominate institutional procurement. CMS National Coverage Determination criteria restrict prescriptions to patients incapable of operating manual alternatives, concentrating demand among spinal cord injury and advanced neuromuscular populations in the United States.
- Mobility Scooter:Three-wheel and four-wheel configurations with tiller steering and front-wheel drive serve community mobility for elderly users with partial ambulation. Japan's METI accessibility subsidies and expanding Medicare Advantage supplemental benefits accelerate replacement cycles for outdoor-capable units.
- Active Wheelchair:Lightweight aluminum or carbon fiber frames with cambered wheels and adjustable axle positions serve athletic and employed disabled demographics. Self-propulsion capability disqualifies most users from powered device reimbursement, limiting volume to private-pay channels.
- Portable Scooter:Quick-disassembly designs with airline-compatible sealed lead-acid or lithium-ion batteries occupy travel and cruise market niches. Direct-to-consumer online configurators capture suburban United States volume bypassing durable medical equipment dealer networks.
Power wheelchair leads on scale; portable scooter leads on momentum.
End User:
Care setting dictates regulatory pathway and service intensity, with institutional buyers bundling maintenance contracts and home care requiring remote diagnostics capability.
- Home Care:Aging-in-place policies tighten reimbursement criteria while expanding telehealth-integrated monitoring. Cellular-connected controllers enable proactive maintenance alerts, creating subscription revenue streams for remote diagnostics platforms.
- Institutions:Hospitals, skilled nursing facilities, and long-term care centers prioritize fleet standardization and crash-test certification under ISO 7176-19. Procurement concentrates among certified home care networks with vertical repair capabilities.
- Elderly:Partial ambulation and Medicare Advantage supplemental benefit expansion drive scooter and standard power wheelchair volume. Lightweight manual alternatives satisfy mild impairment segments, capping powered device addressable share.
- Disabled:Working-age populations with congenital or traumatic conditions demand standing wheelchair technology and specialized seating systems. Japan's municipal governments cover 90% of standing wheelchair costs for employed citizens.
Home care dominates volume concentration; disabled users show steepest technology upgrade trajectory.
Technology:
Motor and control architecture selection tracks reimbursement tier and user functional capacity, with premium positioning requiring proprietary standing or stabilization features.
- Electric Drive:Brushless DC motors with lithium-ion battery packs extend single-charge range beyond 25 miles, qualifying more patients for outdoor-capable prescriptions. Neodymium magnet supply concentration in China's Inner Mongolia region exposes manufacturers to export quota volatility.
- Manual Drive:Self-propulsion through handrim or foot-peg operation serves residual functionality populations and markets with limited electrification infrastructure. Carbon fiber frame advances reduce weight below 10 kilograms for competitive athletics.
- Intelligent Control:Gyroscopic stabilization modules and smartphone integration attract younger disabled consumers. Veterans Affairs procurement specifications now mandate wheel-hub sensor redundancy for tilt-in-space prescriptions.
- Standing Wheelchair:Powered seat elevation and standing position capability command premium pricing through clinical benefits for pressure relief and employment access. Complex rehabilitation prescriptions require certified ATP/SMS credentials, constraining service capacity.
Electric drive anchors unit volume; intelligent control expands most quickly among younger demographics.
Distribution Channel:
Channel selection splits along reimbursement complexity, with Medicare-funded equipment requiring physical assessment and standard scooters migrating online.
- Online Retail:Amazon and specialized mobility e-tailers capture 35% of travel scooter volume in United States suburban markets. Lithium-ion shipping restrictions from the Department of Transportation constrain direct-to-consumer fulfillment.
- Specialty Shops:Local durable medical equipment dealers retain Medicare power wheelchair fitting authority, bundling ATP assessment, customization, and maintenance. Rural buyers remain tethered to dealer networks for complex rehabilitation prescriptions.
- Direct Sales:Manufacturer-employed representatives serve institutional accounts and national home care chains with fleet standardization requirements. Vertical integration into seating fabrication enables rapid product customization.
- Medical Supply Stores:Pharmacy-based and retail health equipment outlets serve cash-pay accessories and standard mobility aids. Limited technical service capability restricts powered device penetration.
Specialty shops retain reimbursement-locked volume; online retail gains share fastest in unregulated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified Assistive Technology Professionals concentrate in major metropolitan corridors, anchoring complex rehabilitation service capacity where reimbursement density supports specialized fitting workflows. This workforce distribution shapes where powered mobility prescriptions concentrate and where manufacturers prioritize dealer network investments.
United States
Medicare Advantage plans now cover supplemental mobility benefits beyond traditional fee-for-service limits, expanding addressable prescriptions for outdoor-capable devices. The FDA enforces 21 CFR 890 quality system regulations while CMS National Coverage Determination criteria restrict motorized equipment to in-person assessed patients. ATP specialists cluster in Chicago, Houston, and Atlanta medical corridors, where hospital-based seating clinics handle complex spinal cord injury cases.
Germany
Statutory health insurance funds tightened technical documentation requirements for powered wheelchair approvals, extending prescription processing timelines. The KBA mandates updated chemical safety documentation for cross-border transport under REACH substance restrictions on seating foam additives. Medical device manufacturers concentrate in Baden-Württemberg, where Stuttgart-area fabrication shops supply precision-machined controller housings to EU assembly plants.
Japan
METI accessibility subsidies now cover 90 percent of standing wheelchair costs for employed disabled citizens in Osaka and Tokyo municipalities. The PMDA enforces clinical evaluation standards for active mobility devices under harmonized pharmaceutical and medical device regulations. Rehabilitation engineering specialists concentrate in Nagoya's Chubu region, where Toyota-affiliated suppliers adapted automotive motor controls for medical applications.
China
Neodymium magnet processing capacity clusters in Inner Mongolia, exposing motor manufacturers to export quota volatility and forced technology transfer requirements. The NMPA implemented stricter post-market surveillance for imported rehabilitation devices under revised medical device classification rules. Lithium-ion battery pack assemblers concentrate in Shenzhen's Pearl River Delta corridor, where cell suppliers serve both consumer electronics and medical device certification pathways.
India
The PLI scheme for medical devices reduces import duties on locally assembled controllers and seating systems, enabling export platforms for Southeast Asian markets. BIS certification requirements for active mobility devices tightened technical documentation standards for domestic manufacturers. Rehabilitation equipment distributors concentrate in Maharashtra's Mumbai-Pune corridor, where hospital procurement networks source motorized platforms for tertiary care centers.
Power Wheelchairs and Mobility Scooters Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent reimbursement channel requirements. The market structures around three tiers: vertically integrated manufacturers controlling in-house seating fabrication, specialized component suppliers licensing controller technology to regional assemblers, and direct-to-consumer brands bypassing durable medical equipment dealer networks. Consolidation pressures intensify as EU MDR compliance costs favor scale, while Medicare Advantage expansion rewards rapid product customization capability. Strategic moves concentrate on backward integration into battery pack assembly and geographic expansion through certified home care network partnerships.
Among North American fabricators, Pride Mobility exemplifies the vertically integrated archetype with captive manufacturing capacity for Medicare-funded channel customization. Permobil occupies the premium positioning tier through specialized seating system integration. Sunrise Medical represents the multi-channel distribution archetype spanning specialty dealer networks and institutional direct sales. Each anchors distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Pride Mobility |
| Permobil |
| Sunrise Medical |
| Ottobock |
| Invacare |
| Drive DeVilbiss Healthcare |
| Golden Technologies |
| Merits Health Products |
| Karman Healthcare |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between complex rehabilitation platforms and standard mobility scooters manifests in both pricing power and sourcing configurations. Premium tiers command bundled ATP assessment and maintenance contracts while commodity segments compete on landed cost from concentrated Asian manufacturing.
Pricing Analysis
Bundled service contracts versus unbundled hardware transactions split pricing architectures across reimbursement channels. Three-tier pricing structure across premium, standard, and economy levels tracks CMS coding density and EU MDR certification burden. Price differentiation hinges on ATP/SMS credential requirements and ISO 7176-19 crash-test validation. Cost compression in travel scooter tiers is intensifying because direct-to-consumer online configurators bypass dealer margin stacks. Cash-pay elderly buyers show highest price sensitivity; institutional purchasers with fleet standardization mandates show lowest.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese Inner Mongolia processing capacity, exposing motor manufacturers to export quota volatility. Brushless DC drivetrains draw from China, South Korea, and Japan for precision-machined components and controller firmware. Lithium-ion cell production feeds from Shenzhen's Pearl River Delta corridor. Single-source vulnerability concentrates in rare earth magnet refining. Distribution runs through certified home care networks for Medicare-funded equipment and direct e-commerce fulfillment for travel scooters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential between EU MDR compliance costs in Europe and India's PLI scheme incentives for Southeast Asian export platforms.
For Market Incumbents: Cement control over certified ATP/SMS technician networks to lock institutional procurement channels against emerging direct-to-consumer brands. Deepen backward integration into lithium-ion battery pack assembly to offset neodymium magnet supply volatility. Prioritize dual certification pathways for simultaneous FDA and EU MDR market access. For New Entrants and Emerging Players: Smartphone-integrated controller firmware offers a technology-first wedge into younger disabled demographics underserved by legacy manufacturers. Target portable scooter segments in United States suburban markets where online retail penetration remains below saturation. Pursue telehealth-integrated remote diagnostics subscriptions as recurring revenue anchor. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed mid-tier manufacturer operating margins. Five-to-ten year viability favors vertically integrated producers with captive seating fabrication and certified distribution networks. Watch Japan's METI subsidy expansion as signal for standing wheelchair technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Dual Certification Investment | Simultaneous CE marking and FDA submission unlocks transatlantic reimbursement channels. |
| Backward Integration into Battery Assembly | Captive lithium-ion pack production insulates against DOT shipping restrictions and cell supply volatility. |
| Telehealth Diagnostics Platform Launch | Cellular-connected controllers enable proactive maintenance alerts and subscription revenue streams. |
| India PLI Scheme Manufacturing Footprint | Domestic assembly reduces import duties and enables cost-competitive Southeast Asian exports. |
| ATP/SMS Technician Training Expansion | Certified seating specialist capacity removes rural United States service bottlenecks for complex prescriptions. |
Research Methodology
Multiple input streams — manufacturer production data, reimbursement code utilization records, and component supplier shipment manifests — were reconciled against primary interviews with rehabilitation engineers, GPO contracts managers, ATP-certified seating specialists, and durable medical equipment procurement directors. Secondary validation drew from FDA 510(k) filings, CMS Medicare claims databases, EU MDR notified body certificates, and customs trade records. Bottom-up unit shipment estimates and top-down reimbursement expenditure analysis were triangulated for convergence.
Historical volume trajectories were cross-referenced against expert panel assessments of regulatory timeline impacts and technology substitution elasticities. The analytical framework segmented across product type, end-user care setting, motor and control architecture, and distribution channel throughout the forecast period. CAGRs were derived from fitted growth curves incorporating lithium-ion energy density improvement rates and Medicare Advantage benefit expansion patterns.
The model holds under stable reimbursement coding frameworks and battery chemistry cost curves; deviation in EU MDR notified body capacity or neodymium export quota restrictions would shift trajectory. A small set of named triggers — METI subsidy expansion, DOT lithium shipping rule changes, and ISO 7176-19 test facility queue times — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Global Glucometer Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Hearing Aid with Lithium-Ion Battery Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Spectacle Lens Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Global Motion Preservation Devices Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Clot Management Devices Market
Medical Devices
Global Hernia Repair Devices and Consumables Market