
 Global IV Bags Market | 2026-2036
Global IV Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global IV Bags Market Foresight
Project finance and equipment leasing for sterile manufacturing lines is tilting competitive dynamics toward capital-efficient operators. Fresenius Kabi AG leverages captive polymer compounding to anchor its European supply position. Baxter International Inc. sustains scale advantages across North American hospital networks through integrated distribution. ICU Medical Inc. differentiates via specialized oncology bag configurations with closed-system transfer device compatibility.
IV bags are sterile, flexible containers manufactured from polyvinyl chloride, ethylene vinyl acetate, or multi-layer coextruded films, designed to hold solutions for intravenous administration at volumes ranging from 50 mL to 1,000 mL with validated extractables profiles. Their primary purpose is to deliver fluids, medications, blood products, and nutritional formulations directly into patient vasculature while maintaining sterility and chemical stability. Non-PVC polymer bags command premium positioning due to di-2-ethylhexyl phthalate elimination mandates from regulators including EMA and FDA. Multi-layer bags represent the fastest-expanding product category, driven by biologic drug compatibility requirements and extended shelf-life demands from hospital pharmacies.
FDA container closure integrity guidance, EU MDR biocompatibility requirements, and ISO 15747 standards collectively define material selection, sterilization validation, and migration testing protocols for IV bag manufacturers seeking market access. Health Canada and Japan's PMDA enforce comparable extractables thresholds, creating a harmonized but stringent compliance baseline across major jurisdictions. Stakeholders must monitor evolving polymer substitution timelines and sterilization modality shifts as regulatory bodies finalize updated leachable thresholds for next-generation infusion containers.
Market Dynamics
Polymer substitution timelines are compressing as regulators finalize updated leachable thresholds, forcing manufacturers to accelerate multi-layer film validation while hospital pharmacies demand extended shelf-life compatibility for biologic drugs.
Growth Catalysts
- EMA Phthalate Elimination Mandates:European di-2-ethylhexyl phthalate bans are accelerating non-PVC polymer bag adoption across oncology and pediatric infusion applications.
- Biologic Drug Compatibility Requirements:Monoclonal antibody formulations require multi-layer coextruded films with validated extractables profiles, expanding premium bag demand.
- Japan Parenteral Nutrition Expansion:Tokyo and Osaka university hospitals are scaling home parenteral nutrition programs, driving 1,000 mL multi-chamber bag volume.
Market Restraints
- Ethylene Vinyl Acetate Feedstock Volatility:EVA resin prices fluctuate with petrochemical spreads, squeezing margin on mid-tier polymer bags.
- German Polymer Compounding Concentration:Captive resin production anchors at three Central European suppliers, creating single-source vulnerability for non-PVC formulations.
- Gamma Sterilization Capacity Bottlenecks:Cobalt-60 irradiation facility queues extend validation timelines for new bag configurations.
Strategic Opportunities
- India CDSCO Fast-Track Pathways:Accelerated approval timelines for sterile medical devices enable earlier market entry for multi-layer oncology bags.
- Closed-System Transfer Device Convergence:Oncology bag configurations integrating with CSTD protocols capture premium positioning in US hospital networks.
- Brazil ANVISA Harmonization:Emerging alignment with FDA extractables standards reduces redundant testing for manufacturers targeting Latin American expansion.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with multi-layer coextrusion expertise command premium compensation, constraining R&D scaling.
- ISO 15747 Migration Testing Burden:Extended analytical validation cycles delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IV Bags Market |
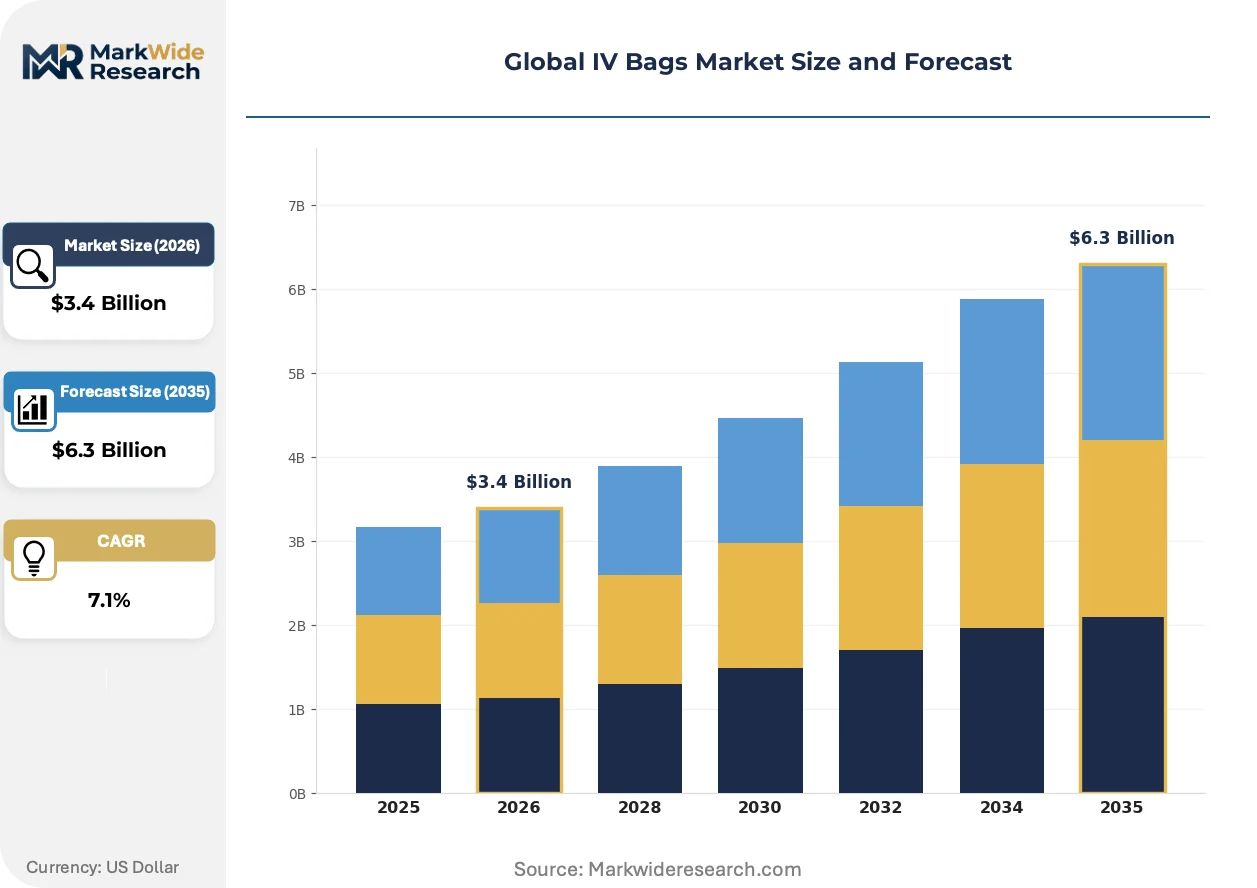
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.3 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible PVC Bags, Non-PVC Polymer Bags, Glass Bottles, Multi-layer Bags, Polyolefin Bags Application: Fluid Replacement, Drug Delivery, Blood Transfusion, Nutrition Therapy, Anesthesia End User: Hospitals, Ambulatory Surgical Centers, Home Healthcare, Oncology Clinics, Dialysis Centers Packaging Type: Single Chamber Bags, Dual Chamber Bags, Triple Chamber Bags, Pre-filled Bags, Sterile Pouches |
| Companies Covered | ICU Medical Inc., Nipro Corporation, Baxter International Inc., Renolit SE, Technoflex, Fresenius Kabi AG, Terumo Corporation, Vygon SA, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IV Bags Market Shifts & Advancements
Material science advances and regulatory harmonization are reconfiguring competitive advantage around validated extractables data and sterilization modality flexibility rather than commodity polymer supply.
Multi-layer coextruded films are migrating from standard infusion applications toward biologic drug containment. Hospital pharmacies in the United States and Germany are adopting these configurations at accelerated pace for monoclonal antibody storage. The shift is compressing market share for single-layer PVC alternatives while elevating barrier property specifications across procurement tenders.
EU MDR biocompatibility requirements are tightening material documentation obligations for polymer suppliers. Manufacturers must now demonstrate comprehensive extractables profiles across temperature cycling conditions. Oncology and critical care bag categories face the steepest compliance burden, with notified body review timelines extending certification cycles.
Hospital pharmacy consolidation is compressing supplier qualification processes. Integrated delivery networks in the United States are reducing approved vendor lists from twelve to four participants, prioritizing manufacturers with captive polymer compounding and validated gamma-sterilized capacity. This concentration favors operators with backward integration into resin formulation and multi-site sterilization infrastructure.
Global IV Bags Market Segmentation
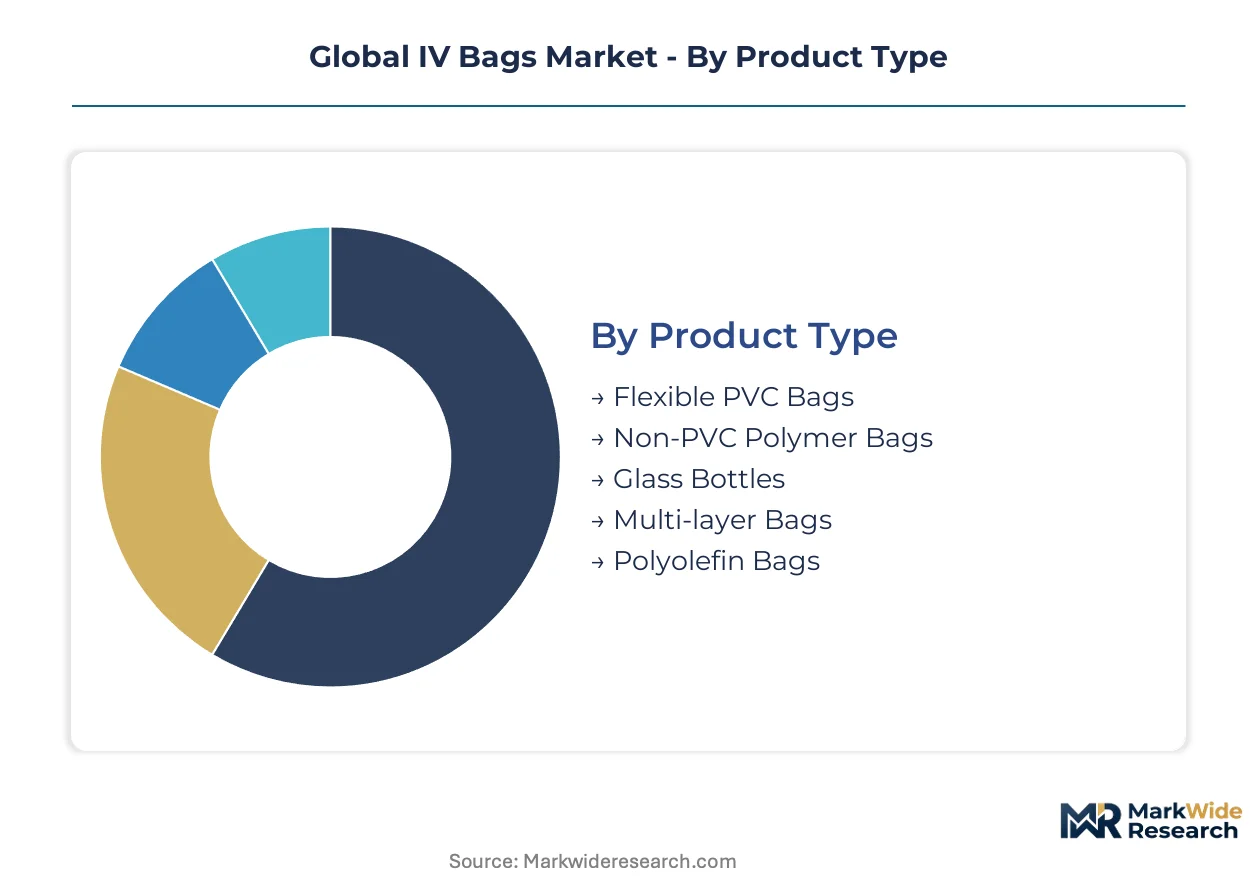
IV bag segmentation reflects divergent material science capabilities, sterilization infrastructure, and clinical workflow requirements across therapeutic areas. Manufacturers configure product portfolios around polymer substitution timelines, biologic drug compatibility mandates, and end-user consolidation patterns that favor integrated supply relationships.
Product Type:
Material composition determines regulatory pathway complexity, extractables testing burden, and hospital pharmacy procurement tier placement.
- Flexible PVC Bags:Polyvinyl chloride formulations with di-2-ethylhexyl phthalate plasticizers dominate established fluid replacement protocols in United States community hospitals. EMA phthalate elimination mandates are compressing oncology and pediatric application share, forcing accelerated portfolio transitions at European operators.
- Multi-layer Bags:Coextruded films combining ethylene vinyl acetate, polyolefin, and barrier layers deliver validated extractables profiles for monoclonal antibody containment. Demand concentrates in German university hospital pharmacies and United States integrated delivery networks managing biologic drug inventories.
- Non-PVC Polymer Bags:Phthalate-free alternatives including ethylene vinyl acetate and polyolefin formulations serve pediatric and oncology infusion protocols.
- Glass Bottles:Borosilicate containers retain niche positioning for high-barrier parenteral nutrition and light-sensitive chemotherapy agents.
- Polyolefin Bags:Cycloolefin polymer and polypropylene configurations offer intermediate barrier properties for standard infusion applications.
Flexible PVC bags command the established base. The steepest expansion runs through multi-layer bags.
Application:
Clinical use case dictates volume scale, chamber configuration requirements, and closed-system transfer device compatibility specifications.
- Drug Delivery:Oncology chemotherapy, antibiotic infusion, and analgesic administration require multi-layer barrier properties and CSTD integration. United States hospital networks prioritize bags with validated compatibility for monoclonal antibodies and immune checkpoint inhibitors.
- Nutrition Therapy:Parenteral nutrition formulations demand multi-chamber configurations separating amino acids, glucose, and lipids until point-of-use mixing. Japanese university hospitals in Tokyo and Osaka are scaling home parenteral nutrition programs, driving 1,000 mL triple-chamber bag procurement.
- Fluid Replacement:Crystalloid and colloid resuscitation volumes concentrate in emergency departments and surgical suites.
- Blood Transfusion:Red cell, platelet, and plasma containment requires specialized PVC formulations with DEHP or alternative plasticizers.
- Anesthesia:Volatile agent and intravenous anesthetic delivery utilizes standard single-chamber configurations.
Fluid replacement commands the established base. The steepest expansion runs through drug delivery.
End User:
Customer type shapes sterilization modality requirements, distribution logistics, and vendor qualification complexity.
- Hospitals:Acute care facilities in Germany, Japan, and the United States drive multi-layer bag adoption for biologic drug compatibility. Integrated delivery networks are consolidating approved vendor lists from twelve to four participants, favoring manufacturers with captive polymer compounding.
- Oncology Clinics:Outpatient chemotherapy infusion centers require CSTD-compatible bag configurations with closed-system transfer device integration. United States community oncology practices prioritize premixed chemotherapy bags to reduce compounding pharmacy burden.
- Ambulatory Surgical Centers:Same-day procedure volumes concentrate fluid replacement and anesthesia bag demand.
- Home Healthcare:Parenteral nutrition and hydration therapy patients utilize portable pump-compatible configurations.
- Dialysis Centers:Hemodialysis and peritoneal dialysis applications require specialized electrolyte solution containment.
Hospitals command the established base. The steepest expansion runs through oncology clinics.
Packaging Type:
Chamber architecture determines formulation stability, reconstitution workflow, and shelf-life extension potential.
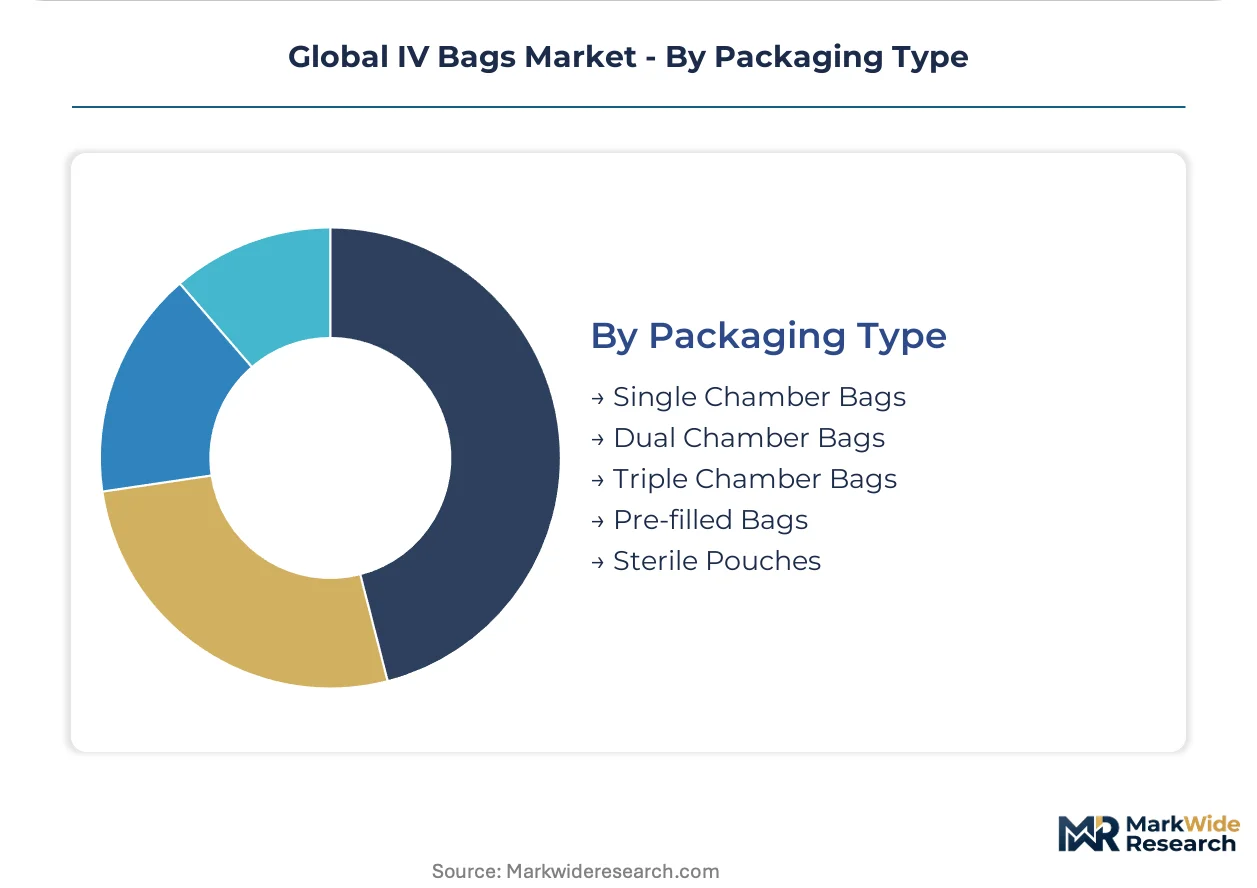
- Triple Chamber Bags:Separated compartments for amino acids, glucose, and lipids enable extended stability parenteral nutrition. Japanese and German hospital pharmacies are adopting these configurations for home parenteral nutrition discharge protocols.
- Pre-filled Bags:Manufacturer-compounded saline, dextrose, and medication solutions reduce hospital pharmacy labor intensity. United States health systems prioritize these for high-volume standardized infusions.
- Single Chamber Bags:Standard configurations dominate crystalloid resuscitation and basic drug delivery.
- Dual Chamber Bags:Two-compartment designs serve antibiotic reconstitution and select nutrition applications.
- Sterile Pouches:Secondary packaging configurations protect primary containers during distribution.
Single chamber bags command the established base. The steepest expansion runs through triple chamber bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor manufacturing clusters with captive polymer compounding and validated sterilization infrastructure. Germany and the United States run structural trade surpluses in multi-layer oncology bags, while Japan and India remain net importers of specialized parenteral nutrition configurations.
United States
FDA container closure integrity guidance and integrated delivery network consolidation are accelerating multi-layer bag procurement. Hospital pharmacy standardization programs in Texas and Florida are reducing approved vendor lists from twelve to four participants. Baxter International Inc. anchors North American supply through captive distribution networks.
Germany
EMA phthalate elimination mandates and university hospital biologic drug expansion are compressing PVC bag timelines. Fresenius Kabi AG leverages captive polymer compounding in Central European resin clusters. Baden-Württemberg and Bavaria house the continent's densest concentration of gamma sterilization infrastructure.
Japan
PMDA extractables thresholds and Tokyo-Osaka home parenteral nutrition scaling are driving triple-chamber bag volume. Terumo Corporation and Nipro Corporation anchor domestic manufacturing. Kanto region university hospitals are adopting 1,000 mL multi-chamber configurations for discharge protocols.
India
CDSCO fast-track pathways and oncology clinic expansion in Maharashtra and Gujarat are enabling earlier market entry for multi-layer configurations. Domestic production concentrates in Haryana and Telangana. Import dependency persists for specialized non-PVC formulations with validated extractables profiles.
Brazil
ANVISA harmonization with FDA extractables standards is reducing redundant testing for manufacturers targeting Latin American expansion. São Paulo and Rio de Janeiro hospital networks are adopting CSTD-compatible oncology bag configurations. Local compounding capacity lags behind demand for premium multi-layer films.
Global IV Bags Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying polymer films and sterilization services. Market structure tilts toward consolidated hospital procurement relationships, with integrated delivery networks compressing supplier qualification processes. Three archetypes dominate: captive polymer compounders with backward resin integration, gamma sterilization operators with multi-site infrastructure, and oncology configuration specialists with closed-system transfer device compatibility. Competitive moves concentrate on strategic partnerships for sterilization capacity access and portfolio diversification into multi-chamber nutrition formats.
Among diversified medical technology conglomerates, Baxter International Inc., Fresenius Kabi AG, and B. Braun Melsungen AG exemplify platform integrators with captive supply chain control. These operators occupy positions spanning polymer compounding through hospital distribution. Component specialists including Renolit SE and Technoflex represent the upstream film and barrier layer tier. ICU Medical Inc. and Vygon SA sit within the oncology-specialist archetype, with configurations targeting CSTD protocol integration. Nipro Corporation, Terumo Corporation, and B. Braun Melsungen AG anchor regional manufacturing clusters across East Asia and Central Europe.
| Leading Market Players |
|---|
| ICU Medical Inc. |
| Nipro Corporation |
| Baxter International Inc. |
| Renolit SE |
| Technoflex |
| Fresenius Kabi AG |
| Terumo Corporation |
| Vygon SA |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Gamma sterilization capacity underutilization in Central Europe is forcing contract manufacturers to extend payment terms and absorb validation delays, compressing margin recovery while hospital GPOs consolidate purchasing power across multi-layer bag categories.
Pricing Analysis
Hospital GPO buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across premium multi-layer, standard non-PVC, and economy PVC configurations. Price differentiation hinges on FDA extractables certification tier and captive polymer compounding status. Cost compression in mid-tier EVA formulations is intensifying because of petrochemical spread volatility. Community hospital procurement committees exhibit highest price sensitivity; integrated delivery networks managing biologic inventories show lowest.
Supply Chain Analysis
Extended payment terms from German resin compounders to film converters are lengthening working capital cycles across the value chain. Manufacturing concentrates in Germany, the United States, and Japan. Feedstocks draw from ethylene, vinyl acetate monomer, and medical-grade polyolefin resins. Single-source vulnerability runs through Central European captive compounding facilities. Distribution runs through integrated delivery network central warehouses and regional medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization validation services and extractables testing laboratories represent a recurring-revenue layer expanding faster than bag hardware manufacturing, creating attach opportunities for operators with captive analytical infrastructure.
For Market Incumbents: Entrench position through backward integration into gamma sterilization infrastructure and accelerated multi-layer film certification under EU MDR timelines. Threat from non-PVC polymer substitution mandates in European oncology applications demands preemptive portfolio transition. Capacity addition in Baden-Württemberg resin clusters anchors supply security. For New Entrants and Emerging Players: Maharashtra and Gujarat oncology clinic networks offer underpenetrated white-space for CSTD-compatible bag configurations. Home parenteral nutrition programs in Japan's Kanto region present second penetration target. Partner with established sterilization operators to bypass cobalt-60 facility queues. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extractables testing laboratories and sterilization validation service providers with hospital pharmacy contracts. Five-to-ten year viability favors operators with backward resin integration and multi-site gamma infrastructure. Watch FDA leachable threshold finalization as inflection signal for polymer substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Notified body pre-submission compresses multi-layer bag approval timelines for German manufacturers. |
| Gamma Sterilization Capacity Expansion | Cobalt-60 facility addition in Bavaria reduces validation queue bottlenecks for oncology configurations. |
| Closed-System Transfer Device Partnership | CSTD protocol integration captures premium positioning in United States hospital network tenders. |
| Triple-Chamber Nutrition Format Launch | 1,000 mL multi-chamber configurations serve Japanese home parenteral nutrition discharge protocols. |
| Extractables Testing Laboratory Acquisition | Analytical validation capability shortens product launch cycles by 8-14 months under ISO 15747. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contract managers, and polymer formulation chemists; and secondary validation through FDA 510(k) filings, EMA device registration databases, hospital procurement records, and ISO 15747 certification registries. Bottom-up volume triangulation against top-down expenditure analysis anchored market sizing.
Forecast inputs span material type, application, end-user category, chamber configuration, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macro healthcare expenditure trends. Modeled inputs include EMA phthalate elimination compliance timelines and Japanese home parenteral nutrition program scaling.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or polymer feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization pace and sterilization infrastructure expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Breast Shells Market
Medical Supplies
Suture Wire Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Serological Pipettes Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Trauma Products Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Suture Tapes Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Global Disposable and Reusable Masks Market