
 Retinal Implant Market | 2026-2036
Retinal Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Implant Market Outlook
Modular device configurations is decoupling hardware from software upgrade cycles, letting buyers replace electrode arrays without full system replacement. Second Sight Medical Products leverages its Argus platform heritage to sustain institutional relationships across academic medical centers. Pixium Vision competes through specialized wireless transmission architectures, while Retina Implant AG anchors European manufacturing with in-house microfabrication capabilities.
A retinal implant constitutes a bioelectronic neuroprosthesis that interfaces directly with retinal tissue through microelectrode arrays, typically operating at stimulation frequencies between 10-100 Hz to elicit visual percepts in photoreceptor-degenerated retinas. These devices restore functional vision by bypassing damaged rods and cones to transmit processed visual signals directly to surviving retinal ganglion cells or bipolar neurons. Epiretinal implants currently lead clinical deployment due to established surgical accessibility and explantability, though subretinal approaches occupy the fastest-growing segment as photovoltaic pixel density improves. Electrode array technology dominates R&D investment, while image processing modules concentrate margin pools through proprietary algorithm licensing.
FDA breakthrough device designation and EU MDR Article 52 clinical evaluation requirements shape product development timelines and market access conditions for manufacturers seeking transatlantic commercialization. Japan's PMDA Sakigake designation accelerates priority review for novel ophthalmic devices, creating parallel regulatory pathways that fragment go-to-market strategies. Stakeholders must monitor evolving reimbursement coding for neuroprosthetic procedures across Medicare, NHS England, and statutory health insurers in Germany to anticipate volume inflection points.
Market Dynamics
Modular device architectures are fragmenting traditional system replacement cycles, forcing manufacturers to decouple hardware refresh schedules from software upgrade trajectories while ophthalmology departments demand backward-compatible electrode arrays.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress premarket approval timelines for novel neuroprosthetic platforms, incentivizing early-stage manufacturers to prioritize transatlantic regulatory strategies.
- Photovoltaic pixel density improvements:Subretinal implant performance gains from advanced semiconductor microfabrication are expanding addressable patient populations beyond epiretinal candidacy thresholds.
- Germany's statutory health insurance framework:Reimbursement parity for vision restoration procedures versus conventional low-vision aids drives procedure volume at academic medical centers.
Market Restraints
- Platinum-iridium electrode material costs:Precious metal price volatility compresses gross margins on electrode array production, particularly affecting high-channel-count configurations.
- Surgical infrastructure concentration:Vitreoretinal surgical expertise clusters in tertiary ophthalmology centers across the United States, Germany, and Japan, limiting addressable procedure sites.
- Long-term biocompatibility uncertainty:Chronic foreign body response to polyimide substrate materials creates regulatory hesitation for extended-duration pivotal trials.
Strategic Opportunities
- Japan's PMDA Sakigake priority review:Expedited approval pathways for first-in-class ophthalmic devices enable earlier commercialization versus standard PMA timelines.
- Wireless power transmission convergence:Integration of inductive coupling architectures with photovoltaic stimulation eliminates trans-scleral power cables, reducing surgical complexity and infection risk.
- India's tertiary ophthalmology network expansion:Underpenetrated retinal prosthetic penetration at regional specialty hospitals creates volume potential as surgical training programs proliferate.
Industry Challenges
- Vitreoretinal surgical skill scarcity:Limited fellowship-trained surgeons capable of subretinal implantation constrains procedure throughput at newly activated implant centers.
- ISO 14155 clinical investigation compliance:Multinational trial coordination across FDA, EMA, and PMDA jurisdictions fragments study design and prolongs data lock timelines.
- Legacy system interoperability:External camera and processing unit obsolescence creates patient lock-in concerns that complicate upgrade pathway negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Implant Market |
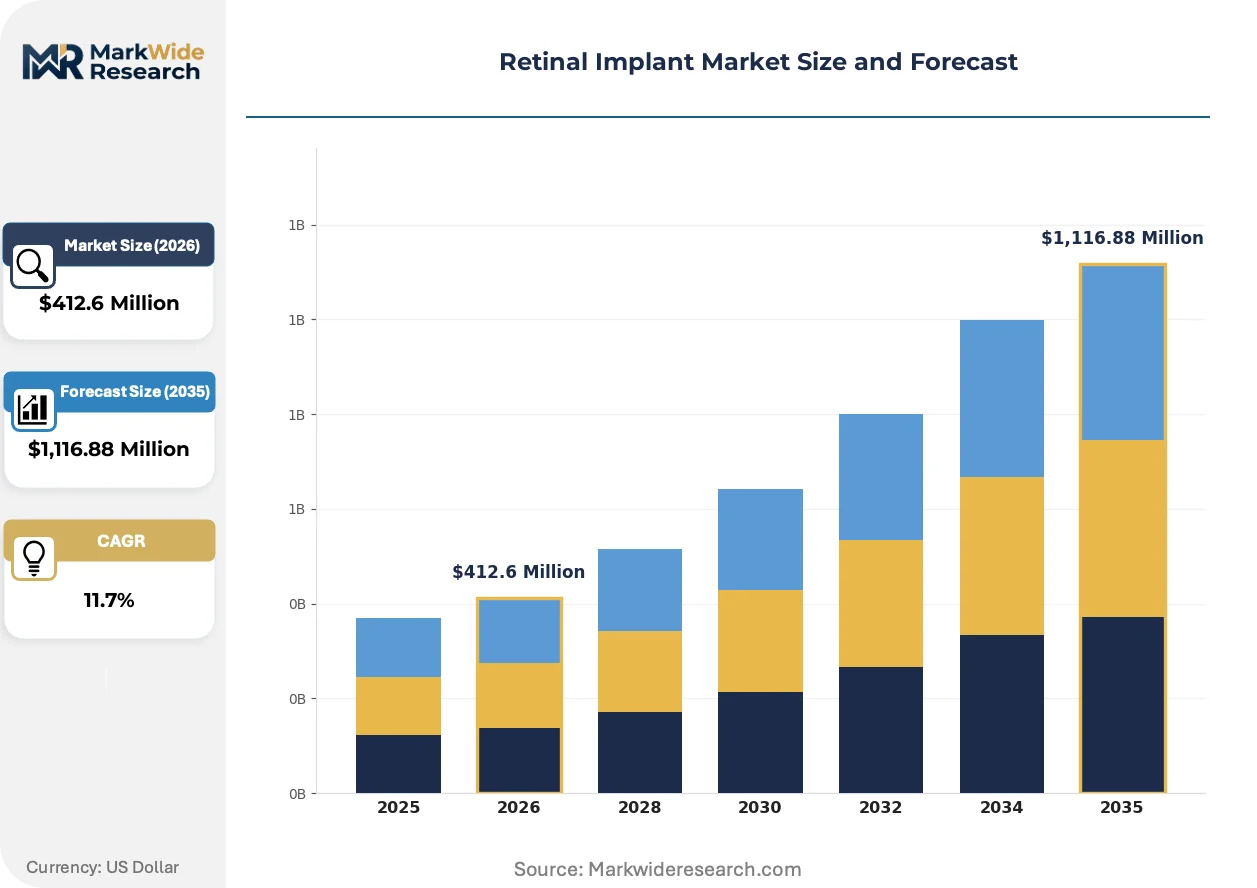
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,116.88 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epiretinal Implants, Subretinal Implants, Optoelectronic Devices, Bioelectronic Devices End User: Hospitals, Specialty Clinics, Research Institutes, Outpatient Facilities Technology: Wireless Transmission, Image Processing, Electrode Array, Microelectronic Technology Application: Retinal Degeneration, Vision Restoration, Blindness Treatment, Neuroprosthetics |
| Companies Covered | Second Sight Medical Products, Pixium Vision, Retina Implant AG, Bionic Vision Technologies, Nano Retina, VisionCare Ophthalmic Technologies, LambdaVision, Nidek Co., Ltd., Vivani Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Implant Market Strategic Shifts
Photovoltaic stimulation architectures and wireless telemetry protocols are compressing the functional gap between epiretinal and subretinal approaches while regulatory harmonization efforts attempt to synchronize transatlantic approval timelines.
High-density microelectrode arrays with channel counts exceeding 250 electrodes are consolidating competitive positioning among manufacturers targeting functional acuity thresholds necessary for independent mobility. Academic medical centers in the United States and Germany are prioritizing these configurations for their institutional review board-approved compassionate use programs. The technology is consolidating procurement decisions around single-platform commitments rather than multi-vendor evaluations, compressing sales cycles for established suppliers.
EU MDR Article 52 clinical evaluation requirements are extending notified body review timelines for legacy device recertifications, forcing manufacturers to accelerate real-world evidence collection through post-market clinical follow-up studies. The industrial consequence is a bifurcation between well-capitalized firms capable of sustaining extended regulatory investment and smaller entrants seeking strategic partnerships. Subretinal photovoltaic platforms face the steepest compliance burden due to novel mechanism-of-action classifications.
Academic medical centers are unbundling device procurement from surgical training and post-implant rehabilitation services, creating discrete contracting opportunities for specialized vision restoration clinics. This fragmentation disrupts traditional bundled pricing models that historically captured multi-year patient management revenue. The shift is most visible in Germany's university hospital network, where ophthalmology departments now separately negotiate electrode array supply, external hardware lease, and rehabilitation therapy protocols.
Retinal Implant Market Segmentation
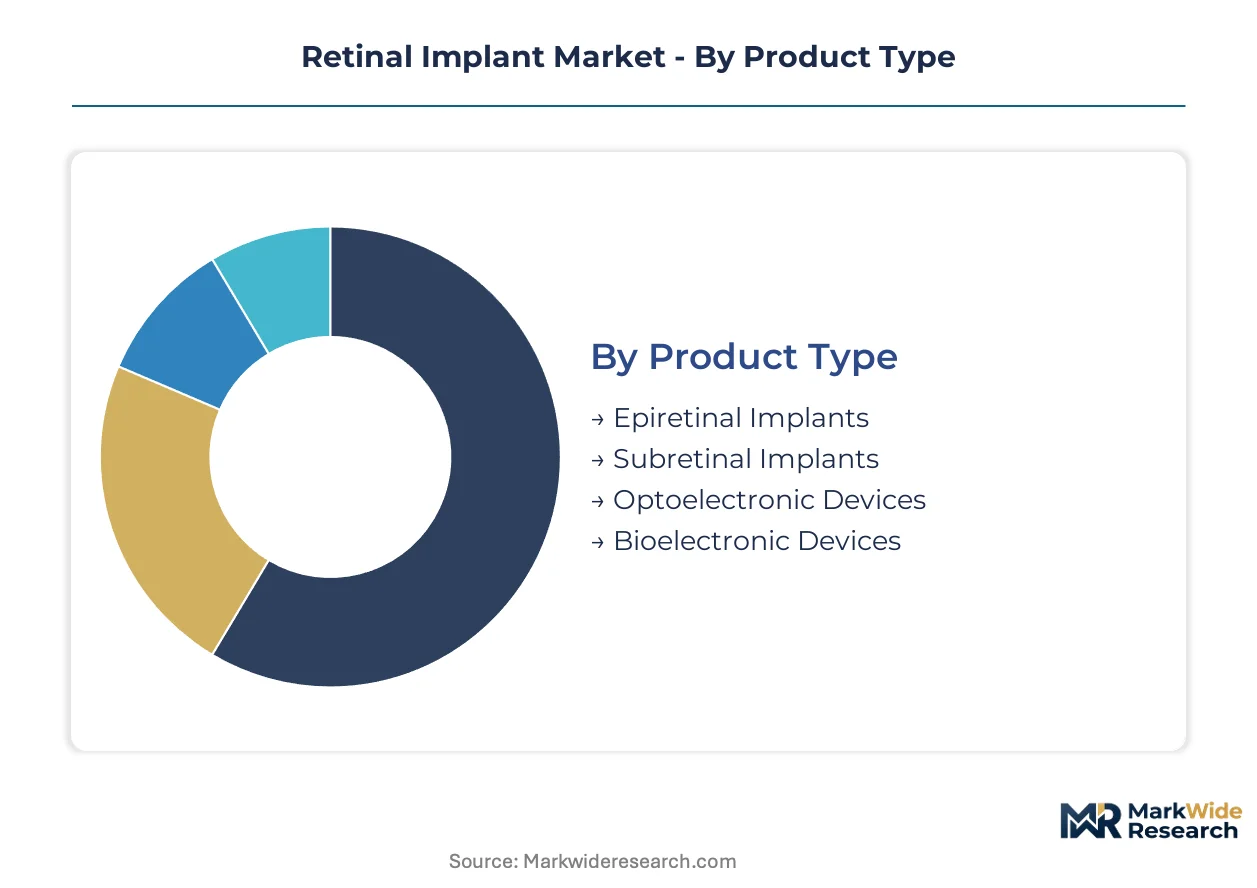
Retinal implant procurement decisions fragment across surgical site capabilities, reimbursement coding, and patient candidacy thresholds. Manufacturers must align product configurations with distinct regulatory pathways and institutional purchasing authority structures.
Product Type:
Standardized surgical protocols dominate epiretinal configurations, while subretinal platforms require customized photovoltaic engineering and extended preoperative planning cycles.
- Epiretinal Implants:Electrode arrays positioned on the inner retinal surface leverage established vitrectomy techniques. Demand clusters at academic medical centers in the United States and Germany where explantability and revision surgery familiarity reduce institutional risk aversion. FDA breakthrough device designations have concentrated manufacturing investment here.
- Subretinal Implants:Photovoltaic pixel arrays implanted between retinal pigment epithelium and photoreceptor layers demand advanced semiconductor microfabrication. Japan's PMDA Sakigake priority review accelerates clinical adoption at Tokyo and Osaka university hospitals. Higher electrode density expands addressable patient populations beyond peripheral vision restoration.
- Optoelectronic Devices:Hybrid architectures combining external cameras with implanted stimulators.
- Bioelectronic Devices:Biocompatible substrate materials with integrated neural interface electronics.
Most installed capacity flows through epiretinal platforms. Expansion is steepest in subretinal photovoltaic configurations.
End User:
Cost tier separation distinguishes tertiary hospital capital budgets from outpatient facility leasing arrangements and research institute grant-funded procurement.
- Hospitals:Integrated ophthalmology departments at university-affiliated centers in the United States, Germany, and Japan anchor implant program development. Bundled reimbursement for device and surgical procedure under Medicare DRG coding and Germany's statutory health insurance G-DRG system sustains capital equipment investment.
- Specialty Clinics:Focused vision restoration centers concentrate post-implant rehabilitation and device programming services. These facilities separate electrode array supply from external hardware lease agreements, fragmenting traditional bundled pricing models.
- Research Institutes:Compassionate use programs and investigator-initiated trials.
- Outpatient Facilities:Limited surgical infrastructure restricts penetration to preoperative screening and post-implant monitoring.
Procedure volume concentrates at hospital-based centers. Specialty clinics are gaining share fastest through unbundled service contracting.
Technology:
Supply concentration for high-channel-count electrode arrays creates margin capture opportunities distinct from commoditized wireless transmission components.
- Electrode Array:Platinum-iridium microelectrode configurations with channel counts exceeding 250 electrodes consolidate competitive positioning. Precious metal price volatility compresses gross margins on high-density configurations, particularly affecting manufacturers without backward integration into microfabrication.
- Image Processing:Proprietary algorithm licensing for camera-to-implant signal encoding concentrates margin pools. External processing unit obsolescence cycles create patient lock-in concerns that complicate upgrade pathway negotiations.
- Wireless Transmission:Inductive coupling architectures eliminating trans-scleral power cables.
- Microelectronic Technology:Semiconductor fabrication for implantable stimulator electronics.
Electrode array technology absorbs the majority of R&D investment. Wireless power transmission is climbing the fastest as surgical complexity reduction becomes a procurement priority.
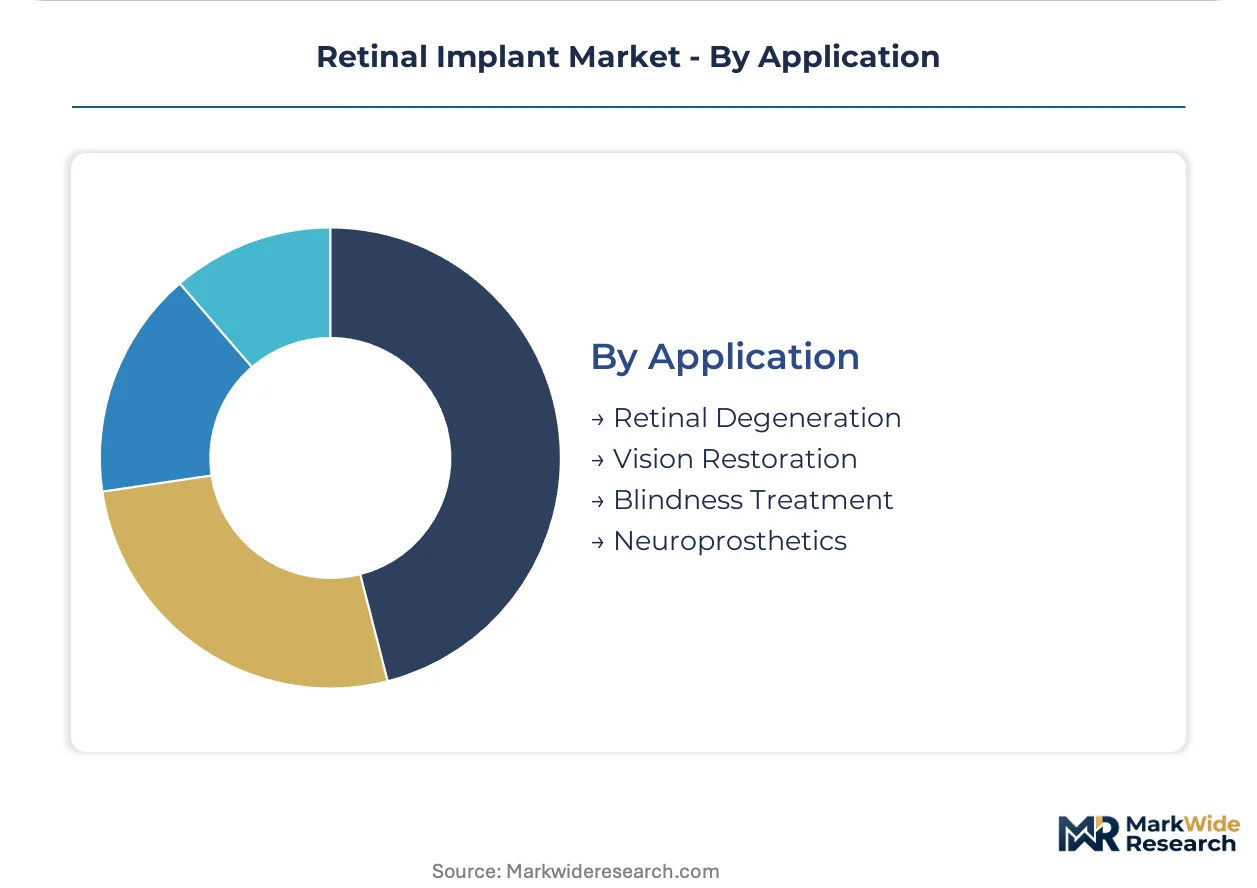
Application:
Patient candidacy thresholds separate reimbursed vision restoration procedures from experimental neuroprosthetic indications.
- Retinal Degeneration:Age-related macular degeneration and retinitis pigmentosa patient populations drive commercial volume. Medicare coverage determinations and NHS England specialized commissioning frameworks define addressable markets.
- Vision Restoration:Functional acuity outcomes necessary for independent mobility anchor regulatory approval endpoints. Germany's statutory health insurance reimbursement parity with conventional low-vision aids accelerates procedure adoption.
- Blindness Treatment:Complete vision loss indications with narrower approved device labeling.
- Neuroprosthetics:Broader neural interface research applications beyond retinal tissue.
Retinal degeneration applications capture the majority of commercial procedures. Vision restoration is expanding most quickly as functional acuity thresholds improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The retinal implant industry traces its commercial origins to Second Sight Medical Products' pioneering work in the United States during the early 2000s, establishing the surgical protocols and regulatory templates that subsequent entrants adapted across Germany and Japan.
United States
Medicare DRG reimbursement coding and FDA breakthrough device designations sustain procedure volume at academic medical centers in Baltimore, Los Angeles, and Boston. The FDA's priority review vouchers for ophthalmic devices compress premarket approval timelines. Johns Hopkins Wilmer Eye Institute and Massachusetts Eye and Ear anchor clinical trial recruitment for next-generation electrode arrays.
Germany
Statutory health insurance parity between vision restoration procedures and conventional low-vision aids eliminates patient cost barriers at university hospitals. The EU MDR Article 52 framework governs notified body conformity assessments for implantable neuroprosthetics. Tübingen University Hospital and University Hospital Bonn concentrate subretinal photovoltaic surgical expertise.
Japan
PMDA Sakigake priority review accelerates commercialization timelines for novel ophthalmic devices versus standard PMA pathways. METI funding for regenerative medicine infrastructure supports manufacturing scale-up. Tokyo Medical and Dental University and Osaka University Hospital lead compassionate use programs for high-density electrode configurations.
Switzerland
Swissmedic's streamlined approval procedures for breakthrough medical devices attract EU-parallel development programs. Federal funding through Innosuisse supports microfabrication research for biocompatible substrate materials. University Hospital Zurich and Geneva University Hospitals concentrate vitreoretinal surgical training for cross-border patient referral networks.
United Kingdom
NHS England specialized commissioning frameworks determine patient access thresholds for retinal prosthetic procedures. The MHRA's post-Brexit recognition routes for EU-approved devices maintain market continuity. Moorfields Eye Hospital and Oxford University Hospitals anchor national referral pathways for inherited retinal dystrophy patients.
Retinal Implant Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory sophistication and electrode array channel density. The vendor base stratifies between established neuroprosthetic platforms with institutional relationships and specialized entrants targeting wireless transmission architectures. Three archetypes dominate: heritage platform holders, semiconductor microfabrication specialists, and wireless power transmission innovators. Capacity expansion and strategic technology licensing represent the dominant competitive moves as manufacturers decouple hardware refresh cycles from software upgrade trajectories.
Within the heritage platform tier, Second Sight Medical Products and Retina Implant AG occupy positions sustained by academic medical center relationships and in-house microfabrication capabilities. Pixium Vision exemplifies the wireless architecture specialist archetype. These three entities represent the competitive anchors around which procurement decisions at tertiary ophthalmology centers consolidate.
| Leading Market Players |
|---|
| Second Sight Medical Products |
| Pixium Vision |
| Retina Implant AG |
| Bionic Vision Technologies |
| Nano Retina |
| VisionCare Ophthalmic Technologies |
| LambdaVision |
| Nidek Co., Ltd. |
| Vivani Medical |
| Others |
Value Chain & Pricing Dynamics
Backward integration into platinum-iridium microfabrication anchors both supply security and margin protection for electrode array manufacturers facing precious metal price volatility. This captive production model concentrates pricing power among heritage platform holders while forcing smaller entrants toward outsourced semiconductor foundry relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-channel-count configurations from basic wireless transmission modules. Price differentiation rests on FDA breakthrough device certification tier and electrode density specifications. Cost compression in standard-tier wireless components is intensifying because inductive coupling architectures commoditize faster than microelectrode arrays. Academic medical centers in Germany and Japan exhibit lowest price sensitivity due to statutory reimbursement parity, while outpatient facilities in India face acute budget constraints.
Supply Chain Analysis
Domestic-content mandates under EU MDR Article 52 and Japan's METI funding frameworks are reshaping sourcing patterns toward regional microfabrication clusters. Supply concentrates in Germany for polyimide substrate production, the United States for image processing algorithms, and Japan for photovoltaic semiconductor wafers. Raw material dependencies center on platinum-iridium alloys, biocompatible polyimide films, and CMOS image sensors. Single-source vulnerability in precious metal refining creates exposure to commodity price swings. Distribution runs through hospital-based GPO contracts and direct academic medical center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Japan's PMDA Sakigake expedited review and the EU MDR's extended notified body timelines creates regulatory cost differentials worth exploiting. Manufacturers can compress time-to-revenue by prioritizing Japanese commercialization before European scale-up.
For Market Incumbents: Hedge against subretinal photovoltaic displacement by accelerating wireless power transmission R&D while locking multi-year electrode array supply contracts with Tübingen and Johns Hopkins implant programs. Backward integration into semiconductor microfabrication preserves margin pools as wireless components commoditize. For New Entrants and Emerging Players: The premium-to-economy price-point gap in wireless transmission modules offers entry leverage for inductive coupling specialists targeting India's expanding tertiary ophthalmology network. Focus initial penetration on post-implant rehabilitation service unbundling at German university hospitals before pursuing full system approvals. For Investors and Strategic Acquirers: Roll-up economics work for wireless architecture specialists because regulatory fragmentation across FDA, EMA, and PMDA jurisdictions favors platform consolidation over standalone navigation. Target mid-cap entrants with PMDA Sakigake designations but limited European notified body relationships. Watch for inflection when Medicare DRG coding expands beyond academic medical centers to community hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses premarket timelines for novel neuroprosthetic platforms. |
| CE Marking Pathway under EU MDR | Article 52 clinical evaluation requirements extend recertification burdens for legacy systems. |
| Hospital System Partnership | Academic medical center alliances anchor implant program development and trial recruitment. |
| Software Companion Development | Proprietary image processing algorithms capture recurring licensing revenue streams. |
| Reimbursement Strategy | Medicare DRG and Germany's G-DRG parity decisions determine addressable patient volumes. |
Study Parameters
Direct dialogue with vitreoretinal surgeons, hospital purchasing committee members, biomedical engineers at implant centers, and regulatory affairs specialists at notified bodies grounded the qualitative foundation. Secondary validation drew from FDA 510(k) and PMA filings, EMA notified body certificates, PMDA Sakigake designation records, and CMS Medicare coverage determinations. Bottom-up procedure volume estimates triangulated against top-down market sizing across the analysis window.
Segment-level outputs across epiretinal and subretinal product configurations, electrode array channel density tiers, and hospital versus specialty clinic end-use categories fed into the analytical framework. CAGRs derived from logistic diffusion modeling of reimbursement adoption curves and surgical training program expansion rates. Forecast inputs incorporated platinum-iridium price volatility indices and photovoltaic pixel density improvement trajectories.
Caveats apply where PMDA regulatory priority shifts or EU MDR notified body capacity constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding Medicare DRG expansion timing and Germany's statutory health insurance reimbursement stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
ECG Sensor Patch Market
Medical Devices
Facial Pumps Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Global Operating Microscopes Market
Medical Devices
India Clear Aligners Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
Incubator Devices Market
Medical Devices
Arthroscopy Procedures and Products Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Liver-On-Chip Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Guide Extension Catheter Market
Medical Devices
Sweden Respiratory Devices Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Repetitive Transcranial Magnetic Stimulation Market