
 Urinary Flow Meters Market | 2026-2036
Urinary Flow Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Flow Meters Market Intelligence
Software-as-a-Service for patient data management is decoupling the sale of hardware from long-term clinical value. This shift allows for recurring revenue streams. Laborie leverages its extensive product portfolio and established presence in urodynamics to lead the market. Dantec Dynamics differentiates through its focus on advanced diagnostic systems, while Medica S.p.A. competes on manufacturing precision and reliability for its medical devices.
A urinary flow meter is a diagnostic instrument that measures the volume of urine expelled over time, known as the uroflow rate. These devices often utilize technologies like rotating discs or weight-based sensors to calculate flow rates in milliliters per second, providing critical data for urologists. Portable and handheld units are gaining share over benchtop models due to their flexibility in diverse clinical settings. Urology clinics and specialized diagnostic laboratories remain the primary end users, driving demand for accurate urodynamic study equipment.
Device approval and market access are governed by stringent regulatory frameworks, including the FDA's 510(k) clearance process in the United States and the EU's Medical Device Regulation (MDR). In China, the National Medical Products Administration (NMPA) sets the standards for registration, creating distinct compliance pathways for manufacturers. Future device development will hinge on integrating wireless data transmission and AI-driven analytics while navigating these complex international regulatory requirements.
Market Dynamics
The urinary flow meter market is defined by the convergence of diagnostic hardware with data management software. Stricter regulatory frameworks, particularly the EU's MDR, are simultaneously elevating product standards and creating compliance hurdles, influencing both device design and market access strategies.
Growth Catalysts
- Portable Device Adoption:The increasing use of handheld and portable uroflowmeters in decentralized settings like private urology clinics and mobile diagnostic services enhances patient accessibility and clinical flexibility.
- Aging Demographics:A rising prevalence of urological conditions such as benign prostatic hyperplasia (BPH) and bladder dysfunction in aging populations, especially in developed healthcare markets like Germany, supports sustained demand for accurate diagnostic tools.
- Regulatory Modernization:The European Union's Medical Device Regulation (MDR) creates a demand for next-generation devices with superior clinical evidence and post-market surveillance, favoring manufacturers who invest in compliance.
Market Restraints
- High Capital Costs:The significant initial investment required for sophisticated, multi-channel urodynamic systems can be a substantial barrier for smaller clinics and hospitals, particularly in price-sensitive emerging economies.
- Regulatory Compliance Burden:Navigating disparate and stringent regulatory pathways, such as the FDA's 510(k) clearance in the US and the NMPA's registration process in China, adds complexity and cost for manufacturers.
- Clinical Substitution:In initial diagnostic workups, non-instrumental methods like patient diaries or symptom scores are sometimes used as a low-cost alternative to formal uroflowmetry, limiting device usage in primary care settings.
Strategic Opportunities
- AI-Powered Analytics:Integrating artificial intelligence and machine learning algorithms with flow rate data offers the potential for predictive diagnostics, helping clinicians identify patterns of bladder dysfunction earlier and more accurately.
- Emerging Market Expansion:There is a significant opportunity to introduce advanced uroflowmetry systems in regions like Latin America and Southeast Asia, where healthcare infrastructure is improving and investment in specialized diagnostic equipment is rising.
- SaaS Business Models:Expanding Software-as-a-Service platforms for patient data management allows for the generation of recurring revenue streams, decoupling long-term value from the initial hardware transaction.
Industry Challenges
- System Interoperability:Ensuring seamless integration of data from new urinary flow meters with legacy Electronic Health Record (EHR) systems in hospitals remains a persistent technical and logistical challenge for vendors.
- Data Privacy Compliance:Adherence to rigorous data protection regulations, including HIPAA in the United States and GDPR in Europe, is critical for devices that handle and transmit sensitive patient health information.
- Lack of Data Standardization:The absence of universal standards for data formats and analytical parameters across different manufacturers’ devices complicates the process of conducting multi-center clinical trials and comparing results.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Flow Meters Market |
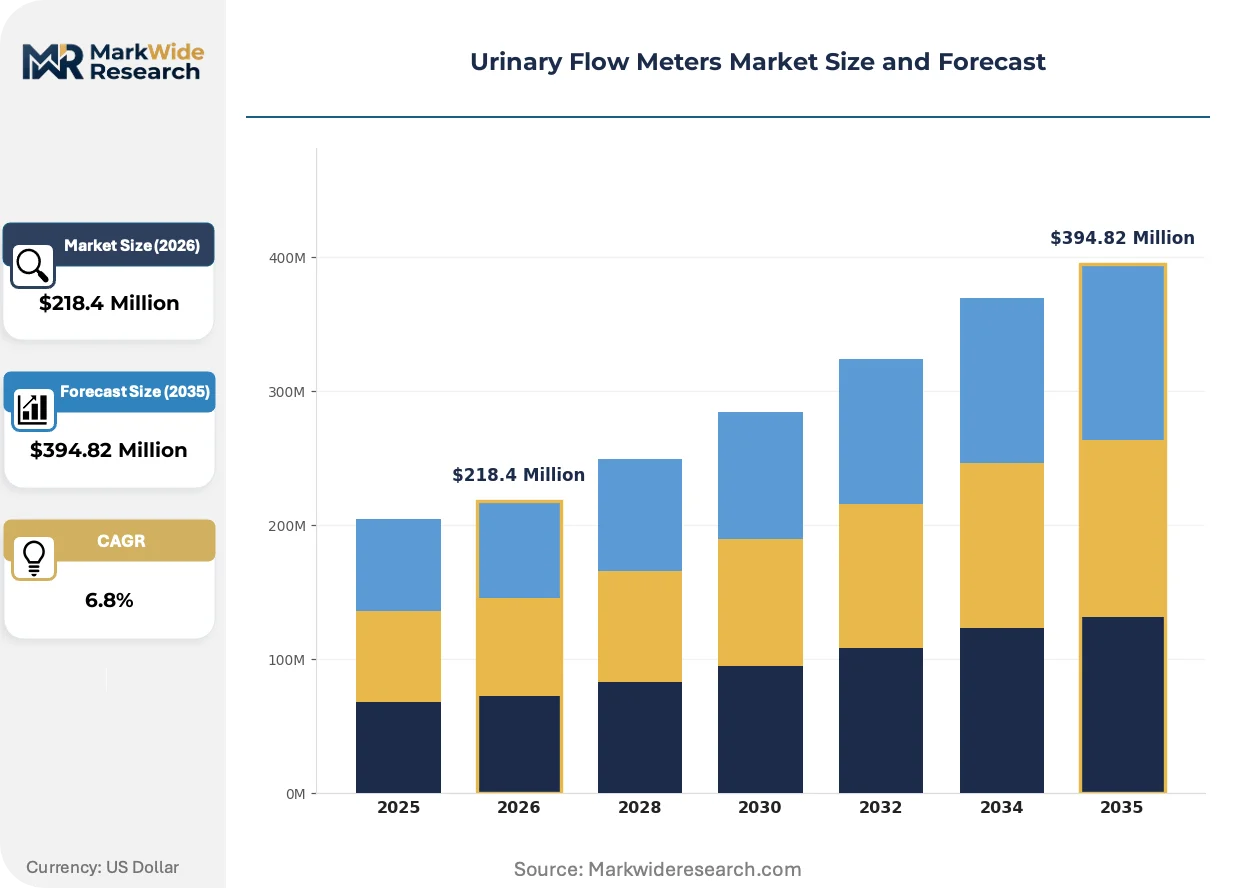
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $394.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Handheld, Digital Technology: Ultrasound, Electromagnetic, Pneumatic, Mechanical Application: Urodynamic Studies, Postoperative Monitoring, Bladder Dysfunction Diagnosis, Kidney Disorder Assessment End User: Urology Clinics, Diagnostic Laboratories, Rehabilitation Centers, Specialized Medical Institutions |
| Companies Covered | Laborie, Medica S.p.A., MEDKONSULT Medical Technology, Apex Meditech, Dantec Dynamics, CellSonic Medical, HC Italia, Schippers Medizintechnik, Best Smart Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Flow Meters Market Strategic Shifts & Innovations
The market's evolution is centered on transforming standalone diagnostic devices into connected components of a broader digital health ecosystem. This shift prioritizes wireless connectivity, software-driven insights, and compliance with next-generation data security and medical device regulations, pushing innovation beyond hardware performance alone.
Wireless sensor technology, incorporating weight-based or rotating disc mechanisms, enables precise, real-time measurement of urinary flow rates. Urology clinics and specialized diagnostic centers are adopting these systems for their operational flexibility and reduced clutter. This advancement is modularizing the diagnostic workstation, allowing the data capture unit to function independently from the analysis software, which can be run on a standard tablet or computer.
The European Union’s Medical Device Regulation (MDR) establishes more rigorous requirements for clinical evaluation and post-market surveillance. This directive significantly increases the compliance burden, impacting development timelines and overall product costs for all medical device classes. Manufacturers of uroflowmetry equipment are most affected, as they must update extensive technical files and quality management systems to maintain CE marking for access to the EU market.
A notable behavioral shift involves the unbundling of hardware sales from software and data analytics services. This disrupts the traditional capital equipment purchase model, introducing a hybrid approach that combines an initial device sale with a recurring subscription for software updates and cloud-based data management. This trend is most prominent in developed healthcare systems in North America and Europe, where clinics seek to convert capital expenditures into predictable operational costs.
Urinary Flow Meters Market Segmentation
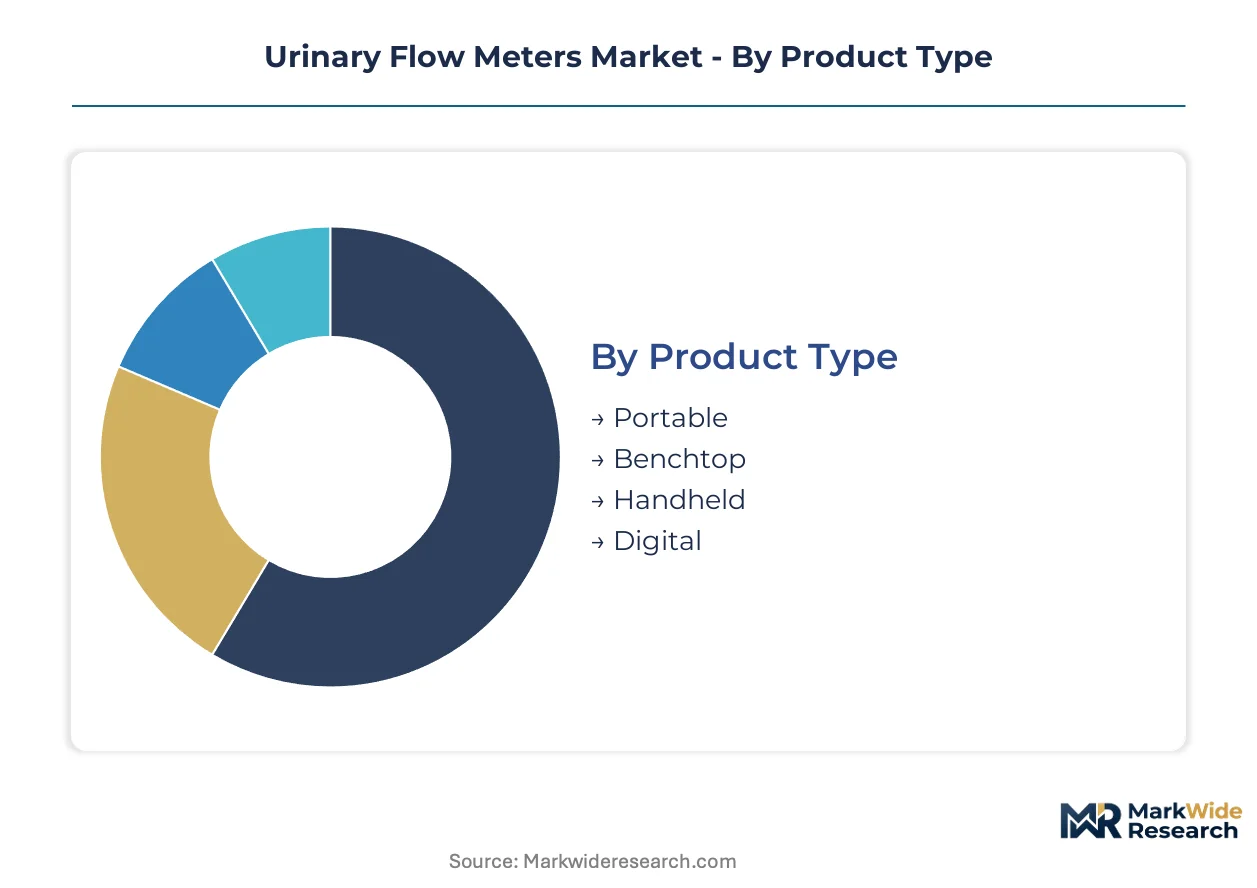
The urinary flow meters market distinguishes itself through device types, underlying technologies, primary applications, and diverse end-user environments. Understanding these segments is crucial for manufacturers to align product development with evolving clinical needs and regulatory demands across different healthcare settings.
Product Type:
The market's product type segmentation highlights a clear shift in investment cycles, with newer, more flexible devices replacing traditional models. This transition reflects a preference for enhanced clinical utility and patient comfort in modern diagnostics.
- Portable:These compact devices offer flexibility for use in various clinical settings, including private urology clinics and mobile diagnostic services, enhancing patient accessibility. Portable uroflowmeters are gaining share in developed healthcare markets like Germany, driven by demand for decentralized diagnostic capabilities.
- Handheld:Designed for maximum convenience and ease of use, handheld units facilitate rapid screening and monitoring in diverse clinical environments, from outpatient clinics to home care. Their adoption is accelerating in North America, where emphasis on point-of-care diagnostics is increasing.
- Benchtop:Traditional benchtop models provide robust and highly accurate measurements, typically found in specialized diagnostic laboratories and larger hospital departments. These systems remain standard for comprehensive urodynamic studies requiring a stable setup.
- Digital:Devices categorized as digital emphasize data capture, processing, and integration capabilities, often featuring advanced software for analysis and connectivity with Electronic Health Record (EHR) systems.
Volume placements concentrate in Benchtop units; the faster expansion belongs to Portable devices.
Technology:
Technological differentiation drives the performance capabilities and precision of urinary flow meters, influencing their suitability for specific diagnostic challenges. Manufacturers prioritize advancements that offer greater accuracy and non-invasive measurement techniques.
- Ultrasound:Utilizing sound waves to measure urine flow, ultrasound-based systems offer non-invasive, real-time data, often integrated with bladder volume measurements for a comprehensive assessment. These systems are favored in urology clinics seeking multi-parameter diagnostics.
- Mechanical:This category includes devices that employ physical mechanisms, such as rotating discs or weight-based sensors, to precisely quantify the volume of urine expelled over time. Mechanical systems provide reliable and established methods for uroflow rate calculation.
- Electromagnetic:Electromagnetic technology provides highly accurate and sensitive flow rate measurements by detecting changes in electrical conductivity of the urine stream. Specialized diagnostic laboratories utilize these for advanced research.
- Pneumatic:Pneumatic systems measure flow rates by detecting changes in air pressure as urine passes through a calibrated channel, offering a robust method for specific clinical applications.
Advanced diagnostic capabilities are driving investment in Ultrasound technology, while Mechanical systems remain a cost-effective choice.
Application:
The diverse applications of urinary flow meters underscore their critical role across the spectrum of urological diagnostics and patient management. Each application addresses distinct clinical needs, from initial screening to detailed functional assessments.
- Urodynamic Studies:These comprehensive investigations assess bladder and sphincter function, providing detailed insights into the lower urinary tract's physiological processes. Specialized urology clinics rely on uroflowmeters as a core component of these studies.
- Bladder Dysfunction Diagnosis:Uroflowmetry is a primary tool for identifying and characterizing various bladder dysfunctions, including overactive bladder and voiding difficulties, particularly prevalent in aging populations. This application sees significant demand in countries like Germany.
- Postoperative Monitoring:Following urological surgeries, these devices are used to monitor patient recovery and identify potential complications related to urinary flow, ensuring effective post-surgical care. Hospitals frequently deploy these for patient follow-up.
- Kidney Disorder Assessment:While primarily focused on lower urinary tract function, uroflowmeters can indirectly contribute to the assessment of broader kidney and urinary system health, aiding in the diagnostic process.
The broadest utility resides in Urodynamic Studies, with Bladder Dysfunction Diagnosis showing significant growth due to demographic shifts.
End User:
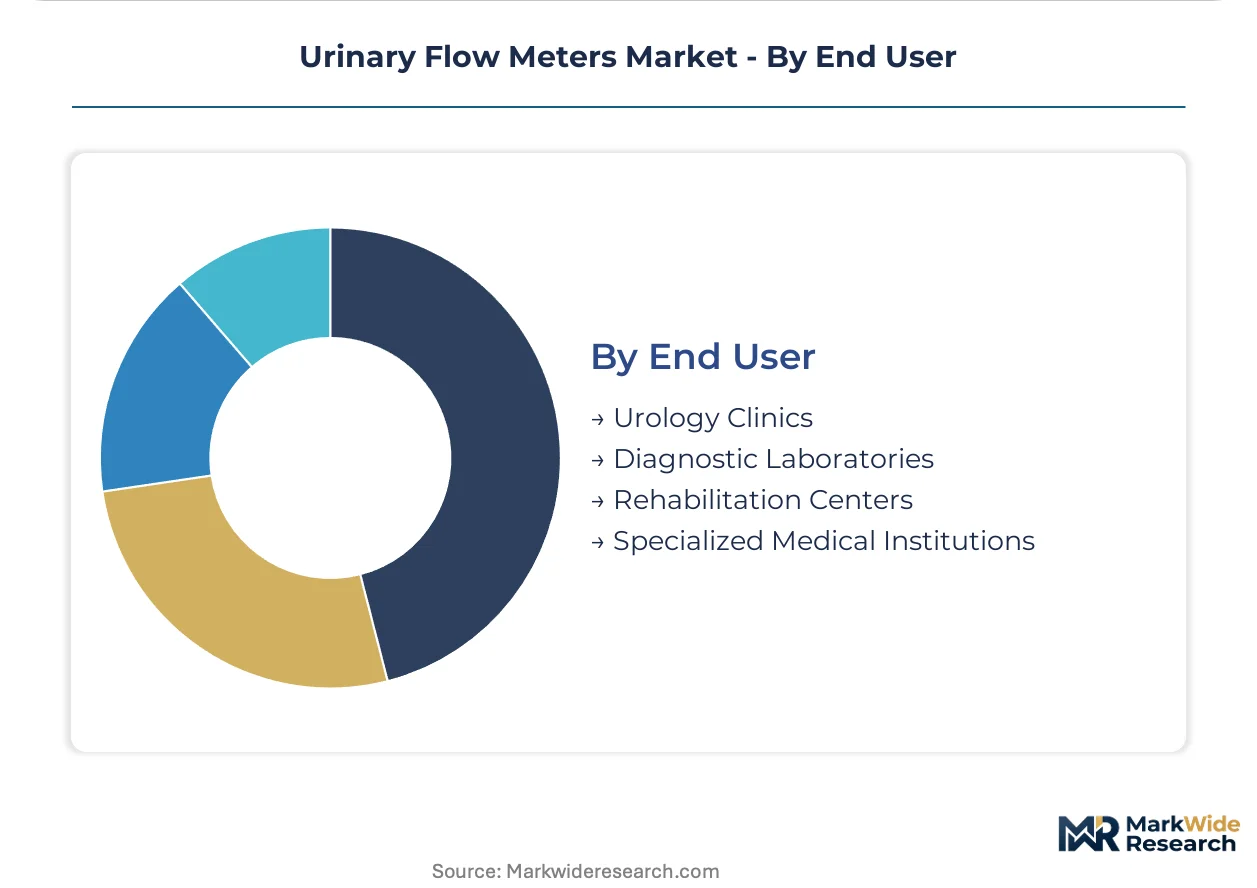
The end-user segmentation reflects where urinary flow meters are deployed, highlighting the varied operational models and specific requirements of different healthcare providers. Each setting leverages these devices to deliver specialized care.
- Urology Clinics:These specialized outpatient facilities represent the primary end-users, integrating uroflowmeters into routine diagnostic protocols for a wide range of urological conditions. They demand user-friendly and accurate diagnostic tools.
- Diagnostic Laboratories:Independent or hospital-affiliated laboratories utilize these devices for high-volume testing and specialized analyses, often supporting multiple clinics and physicians. These labs prioritize precision and data integration.
- Rehabilitation Centers:In settings focused on recovery and functional improvement, uroflowmeters assist in monitoring bladder function as part of a broader rehabilitation program for patients with neurological or musculoskeletal conditions.
- Specialized Medical Institutions:This category encompasses academic medical centers, research hospitals, and large multi-specialty facilities that use advanced uroflowmetry equipment for complex cases, clinical trials, and training.
Core demand originates from Urology Clinics, while Diagnostic Laboratories represent an expanding customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The urinary flow meters market exhibits a consumption-driven landscape, with developed economies leading in diagnostic tool adoption, while production capabilities are more globally distributed. Demand for advanced diagnostic solutions primarily originates from established healthcare systems seeking to improve patient outcomes for urological conditions.
Germany
Demand for urinary flow meters in Germany stems from a high prevalence of urological conditions in its aging population, particularly benign prostatic hyperplasia. The European Union's Medical Device Regulation (MDR) influences product design, requiring robust clinical evidence for market access. Munich and Berlin serve as key hubs for medical technology innovation, driving adoption of next-generation devices.
United States
The United States market sees strong demand for portable and handheld uroflowmeters, driven by a shift towards decentralized diagnostics and point-of-care testing. FDA 510(k) clearance is a critical regulatory hurdle for manufacturers seeking to enter this lucrative market. Major medical device clusters in California and Massachusetts foster innovation in connected health solutions.
China
China represents a significant growth opportunity, with expanding healthcare infrastructure and a rising awareness of urological health. The National Medical Products Administration (NMPA) sets stringent registration standards for medical devices, impacting market entry strategies. Cities like Shanghai and Shenzhen are developing specialized diagnostic laboratories, increasing demand for advanced equipment.
Japan
Japan's market for urinary flow meters is characterized by a strong emphasis on precision engineering and integration with existing electronic health record systems. PMDA regulations ensure high standards for device safety and efficacy, influencing local and international manufacturers. Tokyo and Osaka house numerous research hospitals and academic centers, driving the adoption of sophisticated urodynamic systems.
India
India's market is experiencing rising demand due to improving healthcare access and increasing investment in specialized diagnostic equipment in urban centers. Regulatory bodies like the CDSCO are streamlining approval processes for medical devices, encouraging market expansion. Bengaluru and Hyderabad are emerging as medical device manufacturing and R&D hubs, supporting local production.
Urinary Flow Meters Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized manufacturers focus on niche applications or cost-effective solutions. The market structure is tiered, reflecting varying levels of technological sophistication and geographic reach among participants. Strategic archetypes include integrated solution providers, technology specialists, and regional market leaders. Key competitive moves involve portfolio diversification and strategic partnerships to navigate regulatory complexities.
Within the established players, Laborie exemplifies a company with an extensive product portfolio and a strong presence in urodynamics. Medica S.p.A. occupies a position among manufacturers known for precision engineering and reliability in medical devices. Dantec Dynamics represents firms that differentiate through advanced diagnostic systems, focusing on comprehensive solutions for complex urological assessments.
| Leading Market Players |
|---|
| Laborie |
| Medica S.p.A. |
| MEDKONSULT Medical Technology |
| Apex Meditech |
| Dantec Dynamics |
| CellSonic Medical |
| HC Italia |
| Schippers Medizintechnik |
| Best Smart Medical |
| Others |
Cost & Logistics Intelligence
Outsourced manufacturing of specific components anchors the supply position for many urinary flow meter producers, influencing the broader pricing power across device tiers. This strategic choice allows companies to focus on core R&D and market access, while managing production costs.
Pricing Analysis
Margin tightening in the benchtop segment reflects intense competition and the commoditization of older models. A hybrid pricing model combines an initial per-unit transactional sale for hardware with recurring subscription fees for SaaS data management platforms. Price differentiation stems from CE marking or FDA 510(k) clearance and the inclusion of advanced AI-driven analytics. Urology clinics demonstrate high price sensitivity for basic devices, while specialized diagnostic laboratories prioritize advanced features, showing less sensitivity.
Supply Chain Analysis
Component supply for urinary flow meters rests on specialized electronics manufacturers in China and medical-grade plastic suppliers in Germany. Key raw material dependencies include advanced sensors and microcontrollers for precise measurement. Regulatory compliance complexity, especially navigating NMPA standards in China and MDR in Europe, constitutes a structural supply chain risk. Distribution runs through a combination of direct sales forces and specialized medical device distributors across different regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a supply-constrained story, where the limited availability of specialized regulatory expertise for MDR compliance props up pricing for compliant devices.
For Market Incumbents: Extend product portfolios to include wireless, portable devices that integrate seamlessly with existing EHR systems. This move helps counter the threat from new entrants offering flexible diagnostic solutions. Leverage established relationships with urology clinics and invest in advanced clinical evidence to meet stringent EU MDR requirements. Strengthen intellectual property around AI-driven analytics to maintain a competitive edge.
For New Entrants and Emerging Players: Underserved private urology clinics in emerging markets like India represent a significant white-space target. Focus on developing cost-effective, portable uroflowmeters with intuitive software interfaces for rapid adoption. A go-to-market angle emphasizing ease of use and local regulatory compliance can accelerate market penetration. Target the bladder dysfunction diagnosis application, which sees high demand from aging demographics.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated solution providers with strong software capabilities and established market access in developed healthcare systems. Long-term viability depends on acquiring firms possessing robust regulatory compliance frameworks and a diversified product pipeline. A signal to watch is the increasing adoption rate of AI-powered analytics platforms by major diagnostic laboratories.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Portable Device Portfolio | Laborie can capture market share in decentralized diagnostic settings, enhancing patient accessibility. |
| Invest in AI-Driven Analytics | Dantec Dynamics can offer predictive diagnostics, identifying bladder dysfunction earlier for urologists. |
| Strengthen EU MDR Compliance | Medica S.p.A. ensures continued access to the European market, maintaining a competitive advantage. |
| Develop SaaS Data Management | Companies generate recurring revenue streams, decoupling value from initial hardware sales. |
| Target Emerging Market Distribution | Manufacturers can tap into rising healthcare investment in regions like Latin America and Southeast Asia. |
Research Approach
Independent corroboration across primary interviews, secondary literature, and market intelligence reports underwrites the qualitative findings within this study. This approach integrates insights from clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary data sources included FDA 510(k) clearances, EU MDR documentation, NMPA registration standards, and industry association reports.
Rate-of-change decomposition informed the analytical framework for projecting market growth across the modeling period. The study modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived by analyzing historical market trends and future demand drivers. Key forecast inputs included the prevalence of urological conditions and healthcare expenditure patterns in developed economies.
Revisions become necessary when significant regulatory shifts or unforeseen technological disruptions materialize. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Europe Ambulatory Infusion Pumps Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Prosthetic Liners Market