
 APAC AMH Market | 2026-2036
APAC AMH Market Size, Share, and Industry Trends Forecast 2026-2036
APAC AMH Market Outlook
Project finance and equipment leasing is narrowing the competitive field for mid-sized diagnostic distributors who previously relied on outright capital purchases. Daifuku Co., Ltd. leverages its automation engineering heritage to anchor material handling integration for laboratory supply chains. Toyota Industries Corporation sustains manufacturing scale advantages in precision conveyor systems that feed analyzer production lines. SSI Schaefer AG competes through modular storage architectures that reduce footprint in crowded hospital campuses.
Automated material handling in the APAC AMH context encompasses conveyor networks, robotic sortation, automated storage and retrieval systems, and software-controlled inventory tracking, typically operating at throughput rates exceeding 1,000 samples per hour in clinical settings. These systems eliminate manual specimen transport errors while maintaining cold-chain integrity for reagents and biological samples. Automated analyzers command the largest installed base among product categories, though software segments capture disproportionate margin pools through recurring licensing and compliance update cycles. Hospitals dominate end-user demand, with research institutes representing the fastest-growing adoption segment as translational medicine programs expand across Singapore, South Korea, and Australia.
Japan's PMDA enforces stringent quality management system audits for automated diagnostic equipment, while Australia's TGA mandates local clinical evidence for IVD software algorithms, shaping product development priorities for vendors seeking multi-country registration. China's NMPA has accelerated review pathways for innovative diagnostic devices under its priority review program, though GB standards compliance remains mandatory for electromagnetic compatibility and electrical safety. Stakeholders must monitor evolving harmonization between ASEAN medical device directives and individual national pharmacopeia requirements to optimize registration sequencing and avoid redundant conformity assessments.
Market Dynamics
Centralized laboratory networks across China's tier-one cities are consolidating procurement of high-throughput analyzer systems, compressing vendor margins while favoring integrated material handling suppliers capable of end-to-end automation deployment.
Growth Catalysts
- China's NMPA priority review pathway:Accelerated device approvals for innovative diagnostic equipment shorten time-to-market for automated analyzers with embedded AMH modules.
- Translational medicine expansion:Research institutes in Singapore, South Korea, and Australia are building specimen biobanks requiring automated storage and retrieval systems at throughputs exceeding 1,000 samples per hour.
- Equipment leasing penetration:Project finance structures enable mid-sized hospital laboratories to access conveyor and robotic sortation systems without outright capital commitment.
Market Restraints
- GB standards compliance burden:Mandatory electromagnetic compatibility and electrical safety testing for NMPA registration adds 8-14 months to product launch timelines.
- Precision component supply concentration:High-grade servo motors and linear actuators for robotic arms concentrate in Japanese and German manufacturing clusters, exposing assemblers to currency and logistics volatility.
- Legacy analyzer retrofit limitations:Older immunoassay platforms lack standardized communication protocols, blocking seamless integration with modern warehouse management software.
Strategic Opportunities
- India's CDSCO compliance surge:Tightened IVD registration requirements force domestic distributors to upgrade cold-chain material handling infrastructure, opening service contracts for temperature-controlled conveyor networks.
- Modular storage architecture:SSI Schaefer AG's footprint-reducing designs address space constraints in crowded Southeast Asian hospital campuses where expansion is physically constrained.
- Software-as-a-service convergence:Cloud-based inventory tracking platforms merge with automated storage systems, creating recurring revenue pools through compliance update cycles.
Industry Challenges
- Multi-country registration sequencing:Vendors must navigate divergent ASEAN medical device directives and national pharmacopeia requirements without redundant conformity assessments.
- Integration complexity with hospital information systems:Middleware development for HL7 and FHIR protocol translation consumes 15-25% of deployment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC AMH Market |
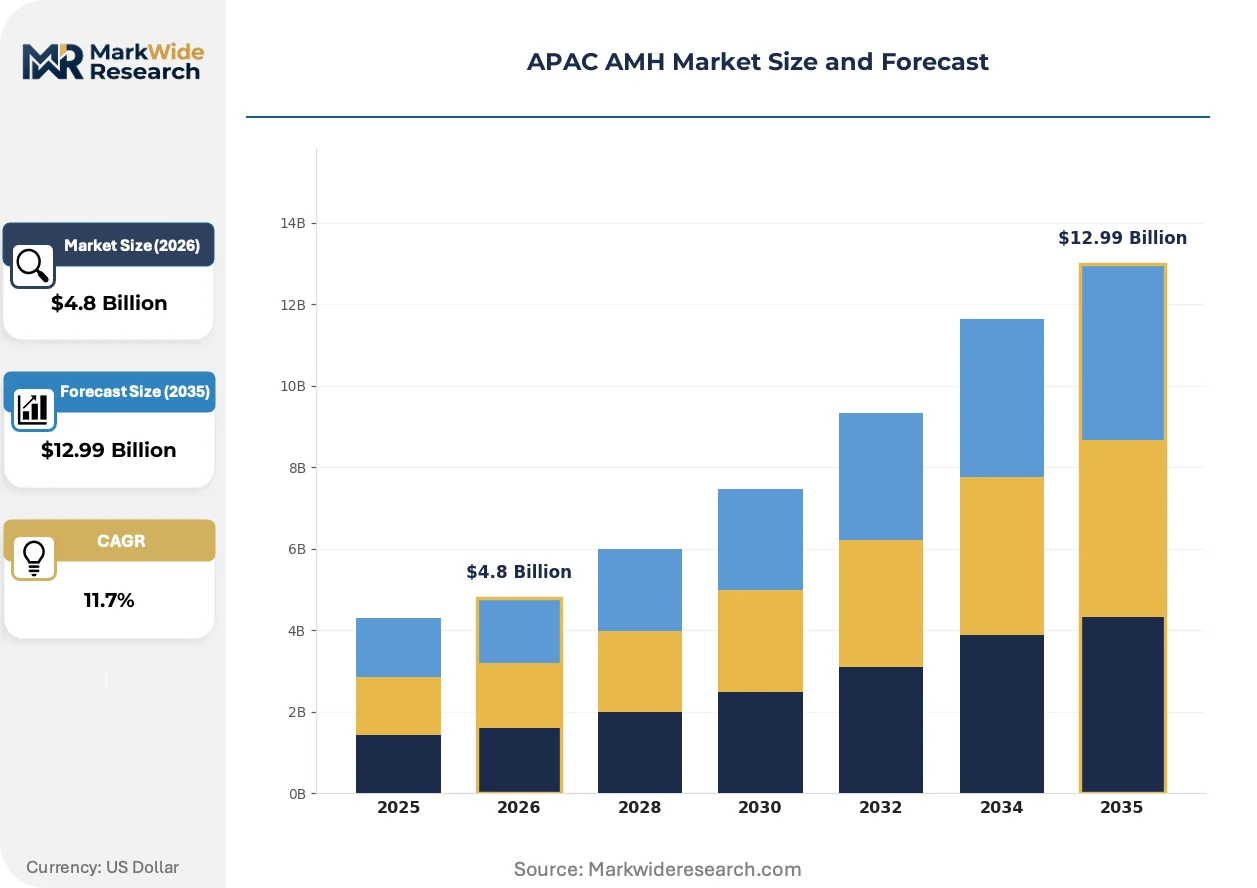
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Reagents, Consumables, Software End User: Hospitals, Laboratories, Blood Banks, Research Institutes Technology: Flow Cytometry, PCR, ELISA, Immunoassay Application: Infectious Disease, Blood Screening, Cancer Research, Genetic Testing |
| Companies Covered | Daifuku Co., Ltd., KION Group AG, Toyota Industries Corporation, Jungheinrich AG, SSI Schaefer AG, Murata Machinery Ltd., Honeywell Intelligrated Inc., BEUMER Group GmbH & Co KG, Kardex Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC AMH Market Strategic Shifts
Specimen transport automation is advancing beyond point-to-point conveyor belts toward autonomous mobile robots with dynamic path optimization. Three developments are compressing competitive timelines and reshaping procurement criteria.
Collaborative robotic arms with force-torque sensing and machine vision guidance are rendering obsolete fixed-position pick-and-place mechanisms in high-mix, low-volume laboratory environments. Tier-two hospitals in Malaysia and Thailand are piloting these systems for overnight batch processing. The shift is compressing payback period calculations from five-year depreciation cycles to 18-month operational savings models.
Japan's PMDA has intensified quality management system audits for automated diagnostic equipment, extending factory inspection durations by 30-40% for foreign manufacturers. This regulatory friction is favoring domestic Japanese automation vendors with established PMDA rapport and localized documentation capabilities. Korean and Australian manufacturers are responding by pre-positioning quality personnel in Tokyo to accelerate response cycles.
Leasing structures now dominate analyzer procurement in Vietnam and Indonesia, displacing traditional capital purchase committees with operating expense approvals managed by procurement chiefs rather than hospital CFOs. Equipment financiers are bundling maintenance and software updates into per-test pricing. This shift is most visible in Jakarta's private hospital chains, where 60% of 2024 material handling deployments followed consumption-based contracts rather than asset ownership models.
APAC AMH Market Segmentation
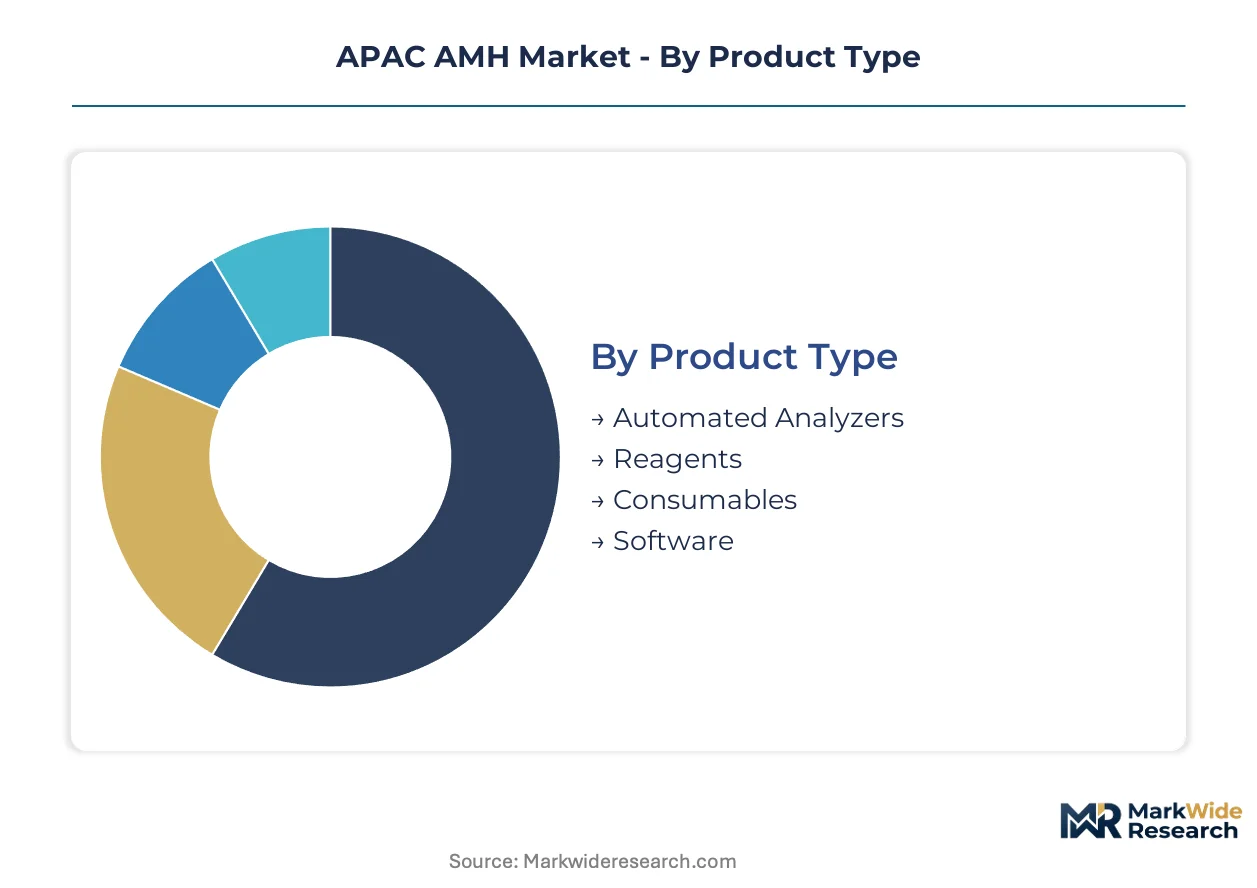
Segmentation reveals how procurement priorities diverge across customer archetypes in the APAC AMH landscape. Technical specifications, regulatory compliance burdens, and throughput requirements reshape vendor positioning depending on whether buyers operate centralized hospital laboratories or distributed research networks.
Product Type:
Cost tier stratification separates capital-intensive hardware from recurring revenue streams in software and consumables.
- Automated Analyzers:High-throughput systems process over 1,000 samples per hour through integrated conveyor and robotic sortation modules. China's tier-one cities are consolidating procurement around these platforms, compressing vendor margins while favoring suppliers capable of end-to-end automation deployment.
- Software:Cloud-based inventory tracking and compliance management platforms capture disproportionate margin pools through recurring licensing cycles. Australia's TGA mandates local clinical evidence for IVD software algorithms, elevating development costs for foreign entrants seeking multi-country registration.
- Reagents:Cold-chain-dependent biological materials require temperature-controlled material handling infrastructure throughout distribution networks.
- Consumables:Disposable pipette tips, microplates, and reaction vessels generate steady replacement demand tied to analyzer utilization rates.
Automated analyzers hold installed capacity. Software is rotating up the share rankings.
End User:
Customer type determines integration complexity and purchasing authority structures across the region.
- Hospitals:Centralized laboratory networks dominate procurement of high-throughput systems, with Southeast Asian facilities expanding automated testing capacity to manage rising patient volumes. India's CDSCO tightened IVD registration requirements, accelerating compliance investments by domestic distributors.
- Research Institutes:Specimen biobanks in Singapore, South Korea, and Australia demand automated storage and retrieval systems at throughputs exceeding 1,000 samples per hour. Translational medicine programs are expanding most quickly across these three markets.
- Laboratories:Independent diagnostic facilities prioritize modular systems with smaller footprints in physically constrained urban campuses.
- Blood Banks:Stringent cold-chain protocols drive investment in temperature-monitored conveyor networks and robotic sortation.
Hospitals anchor procurement volume. Research institutes are climbing the fastest in adoption velocity.
Technology:
Application maturity and protocol standardization create divergent integration pathways for material handling systems.
- Immunoassay:Established automation protocols enable seamless conveyor-fed sample processing in high-volume hospital laboratories. Legacy analyzer retrofit limitations persist where older platforms lack standardized communication protocols with modern warehouse management software.
- PCR:Pandemic-era infrastructure investments created installed bases now requiring upgraded robotic handling for multiplexed testing panels. Japan's PMDA enforces stringent quality management system audits for automated diagnostic equipment utilizing nucleic acid amplification.
- Flow Cytometry:Complex sample preparation workflows benefit from collaborative robotic arms with force-torque sensing in high-mix, low-volume environments.
- ELISA:Batch processing requirements favor fixed-position pick-and-place mechanisms in cost-sensitive tier-two hospital markets.
Immunoassay maintains protocol dominance. PCR is gaining share fastest as infrastructure upgrades accelerate.
Application:
Disease burden distribution and research funding flows concentrate demand in specific diagnostic categories.
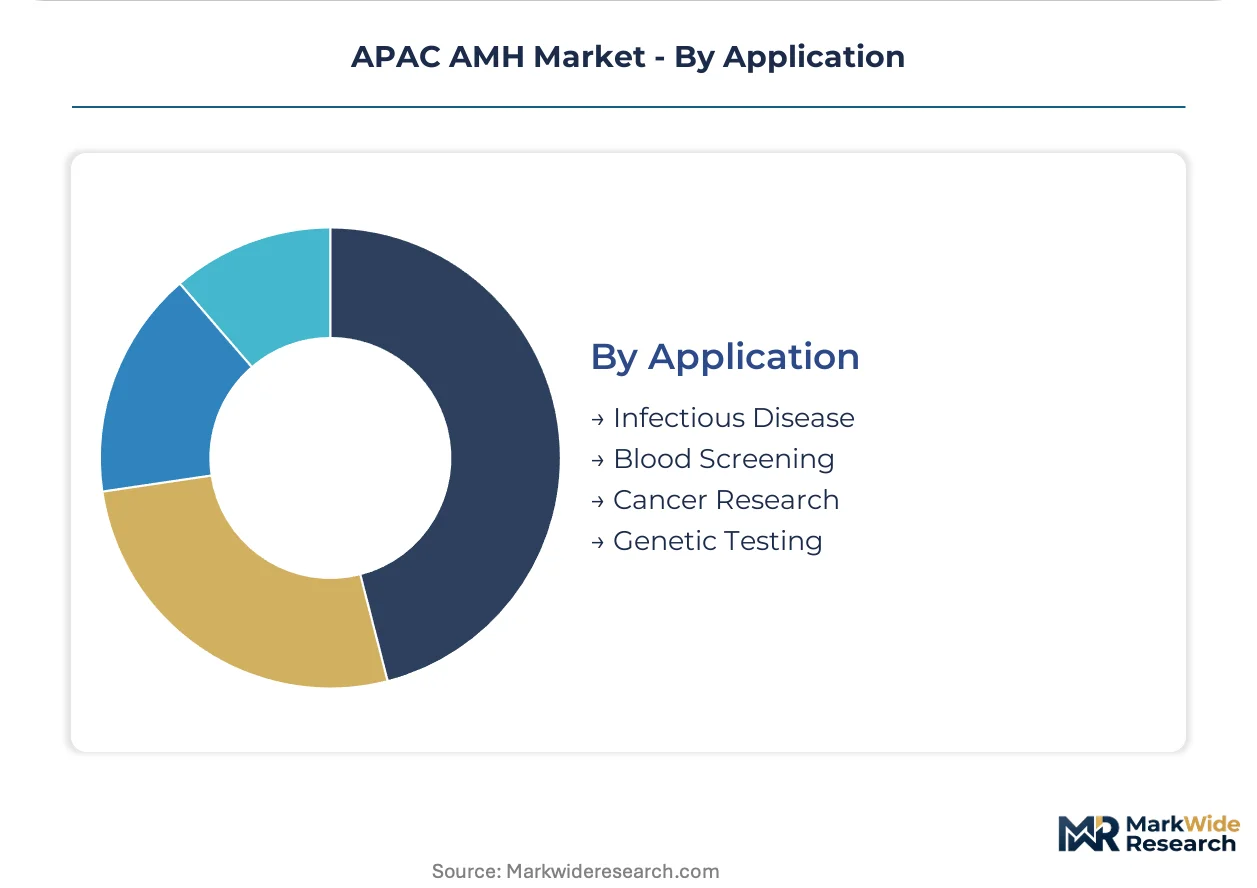
- Infectious Disease:Sustained screening programs for tuberculosis, hepatitis, and respiratory pathogens drive continuous analyzer utilization in Southeast Asian hospital networks. China's NMPA priority review pathway accelerates device approvals for innovative diagnostic equipment in this category.
- Cancer Research:Biomarker discovery programs in Australian and South Korean institutes require ultra-low temperature automated storage for specimen biobanks. GB standards compliance for electromagnetic compatibility and electrical safety adds 8-14 months to product launch timelines for equipment serving this segment.
- Blood Screening:National transfusion safety mandates enforce 100% testing coverage, creating stable replacement demand for analyzer consumables.
- Genetic Testing:Expanding prenatal and oncology screening applications are penetrating private hospital chains in Vietnam and Indonesia through equipment leasing structures.
Infectious disease commands the largest installed base. Cancer research is expanding most steeply in research institute adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's precision automation corridor, while Vietnamese and Indonesian buyers extract concessions through equipment leasing structures that compress vendor margins.
China
Centralized laboratory networks in Beijing, Shanghai, and Guangzhou are consolidating procurement of high-throughput analyzer systems. The NMPA priority review pathway accelerates device approvals for innovative diagnostic equipment, though GB standards compliance for electromagnetic compatibility adds 8-14 months to product launch timelines. The Yangtze River Delta anchors manufacturing scale for precision conveyor systems feeding analyzer production lines.
Japan
The PMDA enforces stringent quality management system audits for automated diagnostic equipment, extending factory inspection durations by 30-40% for foreign manufacturers. Kanto's Tokyo-Osaka industrial corridor hosts domestic automation vendors with established regulator rapport. Collaborative robotic arms with force-torque sensing are rendering obsolete fixed-position pick-and-place mechanisms in high-mix laboratory environments.
India
The CDSCO has tightened in-vitro diagnostic device registration requirements, accelerating compliance investments by domestic distributors. Maharashtra's Mumbai-Pune pharmaceutical belt is upgrading cold-chain material handling infrastructure to meet new standards. Project finance structures enable mid-sized hospital laboratories to access conveyor systems without outright capital commitment.
South Korea
Translational medicine programs are expanding specimen biobank capacity requiring automated storage and retrieval systems at throughputs exceeding 1,000 samples per hour. The MFDS maintains alignment with international quality management standards for diagnostic equipment. Seoul's research institute cluster is climbing fastest in adoption velocity for automated material handling systems.
Australia
The TGA mandates local clinical evidence for IVD software algorithms, elevating development costs for foreign entrants seeking multi-country registration. Research institutes across Sydney and Melbourne are building specimen biobanks with ultra-low temperature automated storage. Cloud-based inventory tracking platforms are merging with automated storage systems to create recurring revenue pools through compliance update cycles.
APAC AMH Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision servo motors and linear actuators. The vendor base concentrates around three strategic archetypes: Japanese precision engineering houses with regulator rapport, German modular storage architects, and automation-focused conglomerates with manufacturing scale advantages. Competitive moves center on strategic partnerships for end-to-end automation deployment and geographic expansion through localized quality personnel placement.
Within the precision automation tier, Daifuku Co., Ltd. and Toyota Industries Corporation exemplify Japanese engineering houses with established manufacturing heritage. SSI Schaefer AG occupies a position among modular storage specialists addressing footprint constraints in crowded hospital campuses. These three anchors represent distinct competitive vectors: system integration depth, manufacturing scale, and space-optimized architecture.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| KION Group AG |
| Toyota Industries Corporation |
| Jungheinrich AG |
| SSI Schaefer AG |
| Murata Machinery Ltd. |
| Honeywell Intelligrated Inc. |
| BEUMER Group GmbH & Co KG |
| Kardex Group |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor's container cost dynamics tie Japanese precision component sourcing to downstream price differentiation between tier-one Chinese hospital networks and Southeast Asian leasing markets. Supply concentration in Kanto's servo motor manufacturing clusters amplifies procurement power for domestic automation vendors while exposing foreign assemblers to logistics volatility that compresses margins on conveyor-fed analyzer systems.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the APAC AMH landscape. Price differentiation rests on NMPA registration tier and after-sales service bundling, with priority review pathway certification commanding substantial premiums. Cost compression in the economy tier is intensifying because Vietnamese and Indonesian hospital chains now negotiate consumption-based contracts rather than capital purchases. Tier-two hospital laboratories in Malaysia and Thailand exhibit highest price sensitivity, while Singaporean research institutes prioritize throughput specifications over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk calculus for precision linear actuator procurement. Component manufacturing concentrates in Japan, Germany, and South Korea, with high-grade servo motors drawing from Kanto and Osaka industrial belts. Raw material dependencies center on rare-earth magnets, specialized aluminum alloys, and precision bearings. Single-source vulnerability persists for force-torque sensors used in collaborative robotic arms. Distribution runs through regional automation integrators who bundle installation with regulatory compliance support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native inventory platforms that displace on-premise warehouse management software in mid-sized hospital laboratories. Material handling vendors must defend against software-as-a-service convergence that threatens hardware-centric revenue models.
For Market Incumbents: Build regulatory moats through pre-positioned quality personnel in Tokyo to accelerate PMDA response cycles. Deepen backward integration into precision conveyor manufacturing to offset currency volatility from Japanese servo motor suppliers. Consolidate service contracts for temperature-controlled networks in India's CDSCO compliance surge to lock out modular storage competitors.
For New Entrants and Emerging Players: Build out collaborative robotic arm deployments for high-mix, low-volume flow cytometry workflows in Australian research institutes. Target specimen biobank automation in South Korea's translational medicine expansion where incumbent footprint remains shallow. Lead with 18-month operational savings models rather than five-year depreciation cycles to bypass capital purchase committees.
For Investors and Strategic Acquirers: Software-anchored automation vendors with recurring compliance update revenue represent the most defensible acquisition profile. Long-term viability hinges on cloud platform integration that captures margin pools from hardware commoditization. Monitor NMPA priority review approval velocity as inflection signal for innovative diagnostic equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Positioning | Tokyo-based quality teams compress PMDA factory inspection durations for foreign manufacturers. |
| Modular Storage Architecture | Footprint-optimized designs unlock physically constrained Southeast Asian hospital campuses. |
| Equipment Leasing Structuring | Per-test pricing models displace capital committees in Vietnam and Indonesia procurement. |
| Software Platform Integration | Cloud inventory tracking merges with automated storage for recurring compliance revenue. |
| Cold-Chain Infrastructure Upgrade | CDSCO tightening forces Indian distributors into temperature-controlled service contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, biomedical engineers, automation integrators, and GPO contracts managers. Secondary validation drew from NMPA registration databases, PMDA quality audit disclosures, ASEAN medical device directive harmonization documents, and hospital procurement records across China's tier-one cities. Bottom-up installation base modeling and top-down equipment spending forecasts were triangulated to anchor volume projections.
Calibration against historical analyzer deployment patterns and leasing penetration rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology protocol, and regional regulatory cluster. CAGRs were derived from equipment replacement cycles and translational medicine program expansion trajectories. Forecast inputs incorporated NMPA review pathway velocity and CDSCO compliance investment timelines.
Stress conditions across currency volatility in Japanese component sourcing, NMPA GB standards testing duration, and leasing market penetration ceilings were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Dermal Allograft Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Photomedicine Technology Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Lancing Devices and Lancets Market