
 Forensic Equipment and Supplies Market | 2026-2036
Forensic Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Forensic Equipment and Supplies Market Analysis
Equipment leasing and managed-service contracts is fragmenting competitive dynamics in forensic instrumentation, allowing mid-sized laboratories to access mass spectrometry and sequencing platforms without capital outlay. Thermo Fisher Scientific dominates thermal cyclers and capillary electrophoresis systems through direct institutional channels. QIAGEN specializes in sample preparation chemistries that lock laboratories into consumable ecosystems. Waters Corporation anchors high-resolution mass spectrometry for toxicology and seized-drug analysis in accredited government labs.
Forensic equipment and supplies encompass instruments, reagents, and consumables used to collect, preserve, analyze, and document physical evidence for legal proceedings, including systems capable of detecting picogram-level analytes in complex matrices and generating courtroom-admissible chain-of-custody documentation. DNA analysis tools lead product-type revenue due to CODIS database expansion and familial search protocols, while digital forensics grows fastest as encrypted device volumes overwhelm regional cybercrime units. Crime investigation applications capture the largest application share, though forensic laboratories concentrate margin pools through long-term service contracts and validation support.
FBI Quality Assurance Standards, ISO 17025 accreditation, and state-level forensic science commissions shape procurement specifications and disqualify non-compliant vendors from government tenders. The European Union's ENFSI guidelines and GDPR constraints on biometric data storage create divergent compliance pathways for multinationals. Stakeholders must monitor accelerating regulatory divergence between jurisdictions that mandate rapid DNA analysis turnaround times and those restricting predictive genetic profiling.
Market Dynamics
Equipment leasing and managed-service contracts are fragmenting competitive dynamics in forensic instrumentation, allowing mid-sized laboratories to access mass spectrometry and sequencing platforms without capital outlay. This shift compresses traditional equipment sales cycles while expanding addressable laboratory capacity.
Growth Catalysts
- FBI Quality Assurance Standards:These accreditation requirements push laboratories toward higher-specification instrumentation, sustaining equipment refresh cycles in government-funded facilities.
- CODIS database expansion:Federal forensic backlog reduction programs in the United States concentrate procurement of DNA analysis tools as a core law enforcement capability.
- Familial search protocols:Advanced genetic matching techniques drive demand for next-generation sequencing platforms in accredited crime laboratories.
Market Restraints
- ISO 17025 compliance costs:Accreditation maintenance requires continuous validation documentation and proficiency testing that strains smaller laboratory budgets.
- Consumable lock-in:Sample preparation chemistries from specialized suppliers create switching costs that limit vendor diversification.
- GDPR biometric constraints:European Union restrictions on predictive genetic profiling create divergent compliance pathways that complicate multinational product strategies.
Strategic Opportunities
- Digital forensics capacity gaps:Encrypted device volumes overwhelm regional cybercrime units, creating demand for mobile device extraction and cloud analytics tools.
- Managed validation services:Long-term service contracts and method validation support offer margin expansion beyond hardware sales in government laboratory segments.
- ENFSI guideline harmonization:European Network of Forensic Science Institutes standardization creates procurement specification alignment across member state laboratories.
Industry Challenges
- Forensic scientist workforce shortages:Specialized training requirements for DNA interpretation and mass spectrometry operation limit laboratory throughput expansion.
- Legacy system integration:New instrumentation must interface with existing laboratory information management systems and chain-of-custody databases.
- Cross-jurisdictional evidence standards:Variability in admissibility requirements between state and federal courts complicates multi-site laboratory operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forensic Equipment and Supplies Market |
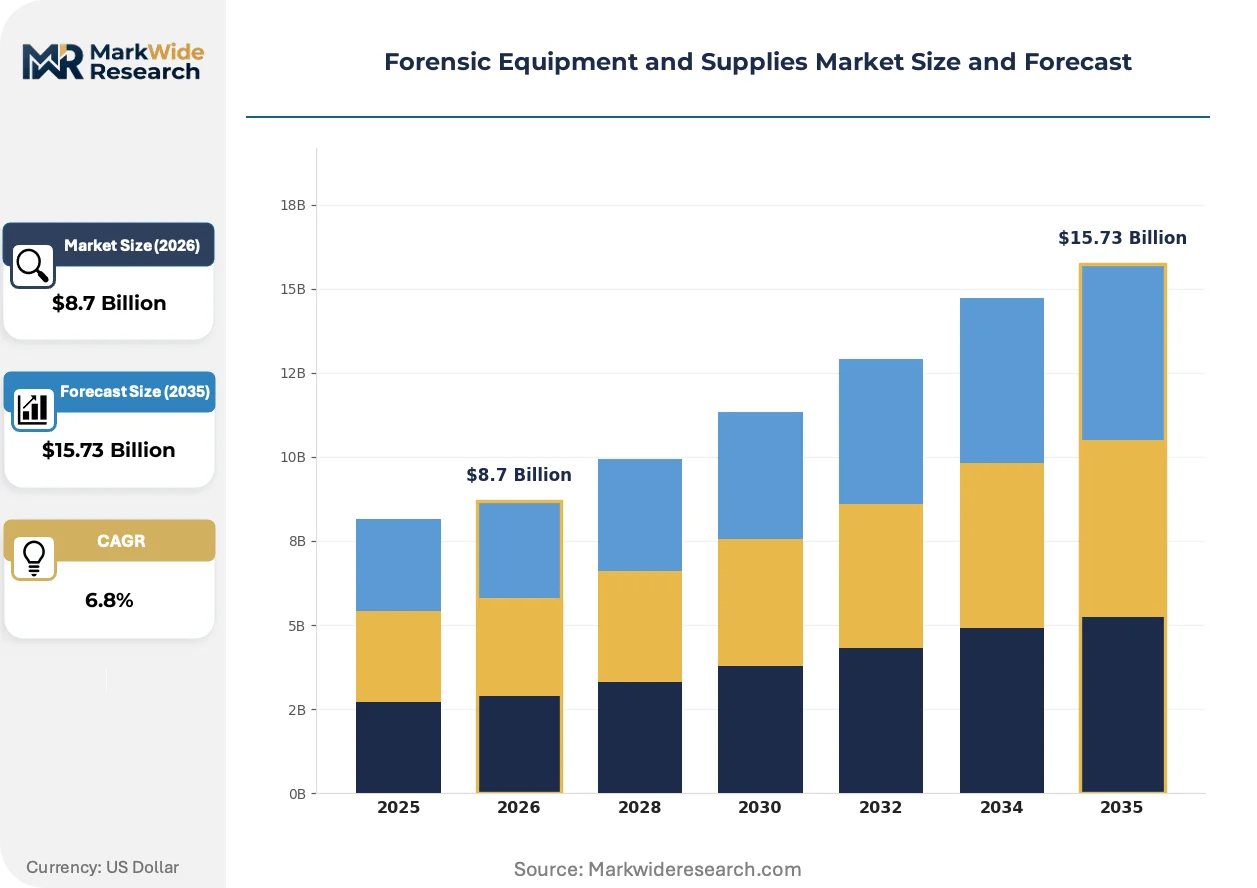
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crime Scene Kits, Evidence Collection Bags, Fingerprint Kits, DNA Analysis Tools Application: Crime Investigation, Forensic Laboratories, Legal Proceedings, Research Purposes End User: Law Enforcement, Private Investigators, Forensic Scientists, Educational Institutions Technology: Optical Imaging, Chemical Analysis, Digital Forensics, Bioinformatics |
| Companies Covered | Waters Corporation, SCIEX, Thermo Fisher Scientific Inc., HORIBA Ltd., Illumina Inc., Agilent Technologies Inc., QIAGEN, BVDA International BV, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forensic Equipment and Supplies Market Emerging Trajectories
Next-generation sequencing platforms are actively reshaping evidence analysis workflows. Three developments dominate instrumentation roadmaps and procurement specifications across accredited facilities.
Rapid DNA analysis systems are migrating from centralized crime laboratories toward booking stations and field deployment. Local law enforcement agencies in the United States are adopting portable thermal cycler units that return genetic profiles within ninety minutes. This decentralization is compressing the traditional evidence submission backlog while creating new training and quality control demands at the point of collection.
The European Union's GDPR constraints on biometric data storage are forcing forensic laboratories to implement automated data retention protocols and enhanced access logging. ENFSI member laboratories must now demonstrate technical and organizational measures for genetic profile deletion timelines. High-resolution mass spectrometry vendors are responding with embedded audit trail firmware that timestamps every analytical event.
Service unbundling is separating instrument hardware from validation support and reagent supply in government tenders. State forensic science commissions now specify multi-year operational expenditure contracts rather than capital purchase frameworks. This preference shift is most visible in United States federal backlog reduction programs, where managed-service contracts now outpace direct equipment acquisitions in award value.
Forensic Equipment and Supplies Market Segmentation
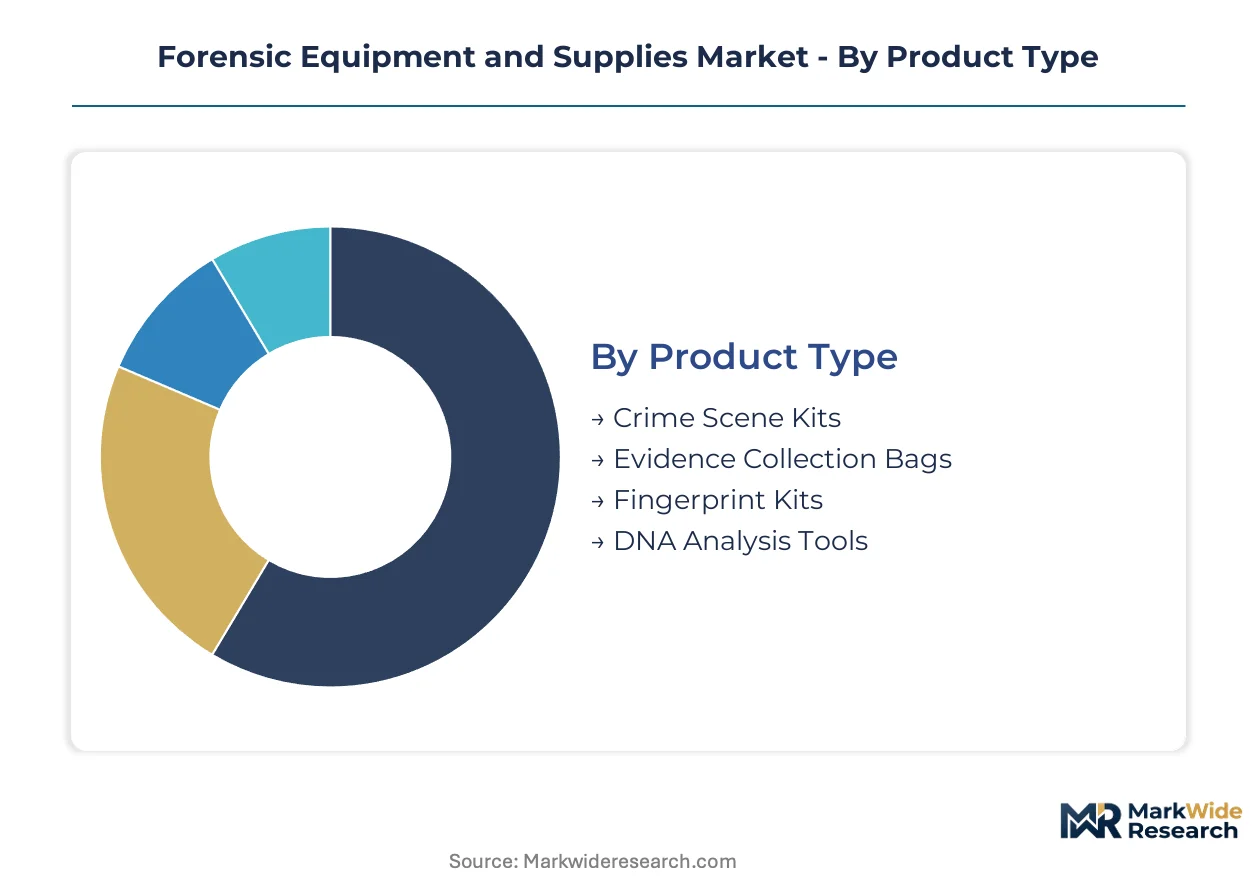
Forensic equipment procurement varies sharply by operational context. Crime laboratories prioritize analytical precision and chain-of-custody documentation. Field units demand portability and rapid turnaround under adverse conditions.
Product Type:
Cost tier stratification separates consumable-heavy workflows from capital-intensive instrumentation platforms.
- DNA Analysis Tools:Capillary electrophoresis systems and next-generation sequencing platforms detect picogram-level genetic material in degraded samples. Federal backlog reduction programs in the United States sustain refresh cycles for these high-specification instruments. Thermo Fisher Scientific and QIAGEN dominate consumable ecosystems that lock laboratories into recurring revenue streams.
- Crime Scene Kits:Integrated collections of swabs, containers, and documentation materials preserve biological and trace evidence from collection through laboratory submission. Local law enforcement agencies in the United States drive volume procurement through standardized state-level specifications. Kit standardization reduces evidence contamination risk while simplifying training requirements for patrol officers.
- Fingerprint Kits:Powder, tape, and chemical reagent systems visualize latent ridge detail on porous and non-porous surfaces.
- Evidence Collection Bags:Tamper-evident packaging with serialized barcoding maintains chain-of-custody integrity during transport.
DNA Analysis Tools hold installed capacity. Crime Scene Kits is rotating up the share rankings.
Application:
Customer workflow determines margin structure and contract duration across forensic service delivery.
- Crime Investigation:Field-deployable rapid DNA systems and portable fingerprint visualization tools compress evidence-to-intelligence timelines. Booking stations across the United States now deploy ninety-minute thermal cycler units that previously required centralized laboratory processing. This decentralization creates new quality control demands at point of collection.
- Forensic Laboratories:Accredited facilities concentrate margin pools through multi-year service contracts and method validation support. ISO 17025 requirements in the United States and ENFSI guidelines in Europe mandate continuous proficiency testing and instrumentation calibration. Managed-service contracts now outpace direct equipment acquisitions in government tender value.
- Legal Proceedings:Court-admissible documentation standards govern expert testimony preparation and evidence presentation.
- Research Purposes:Academic and government research programs advance forensic methodology through controlled validation studies.
Forensic Laboratories holds installed capacity. Crime Investigation is rotating up the share rankings.
End User:
Procurement authority and budget scale fragment across institutional buyer categories with divergent technical requirements.
- Law Enforcement:Federal, state, and municipal agencies constitute the dominant procurement channel for DNA analysis tools and crime scene collection systems. FBI Quality Assurance Standards shape equipment specifications that disqualify non-compliant vendors from government tenders. Familial search protocol expansion drives demand for advanced genetic matching capabilities.
- Forensic Scientists:Accredited practitioners in government laboratories influence vendor selection through technical evaluation committees and method validation requirements. Specialized training requirements for mass spectrometry operation and DNA interpretation limit workforce expansion and constrain laboratory throughput.
- Private Investigators:Limited-budget operators purchase entry-level fingerprint and documentation equipment for civil and defense casework.
- Educational Institutions:University forensic science programs acquire training-grade instrumentation for student laboratory instruction.
Law Enforcement holds installed capacity. Forensic Scientists is rotating up the share rankings.
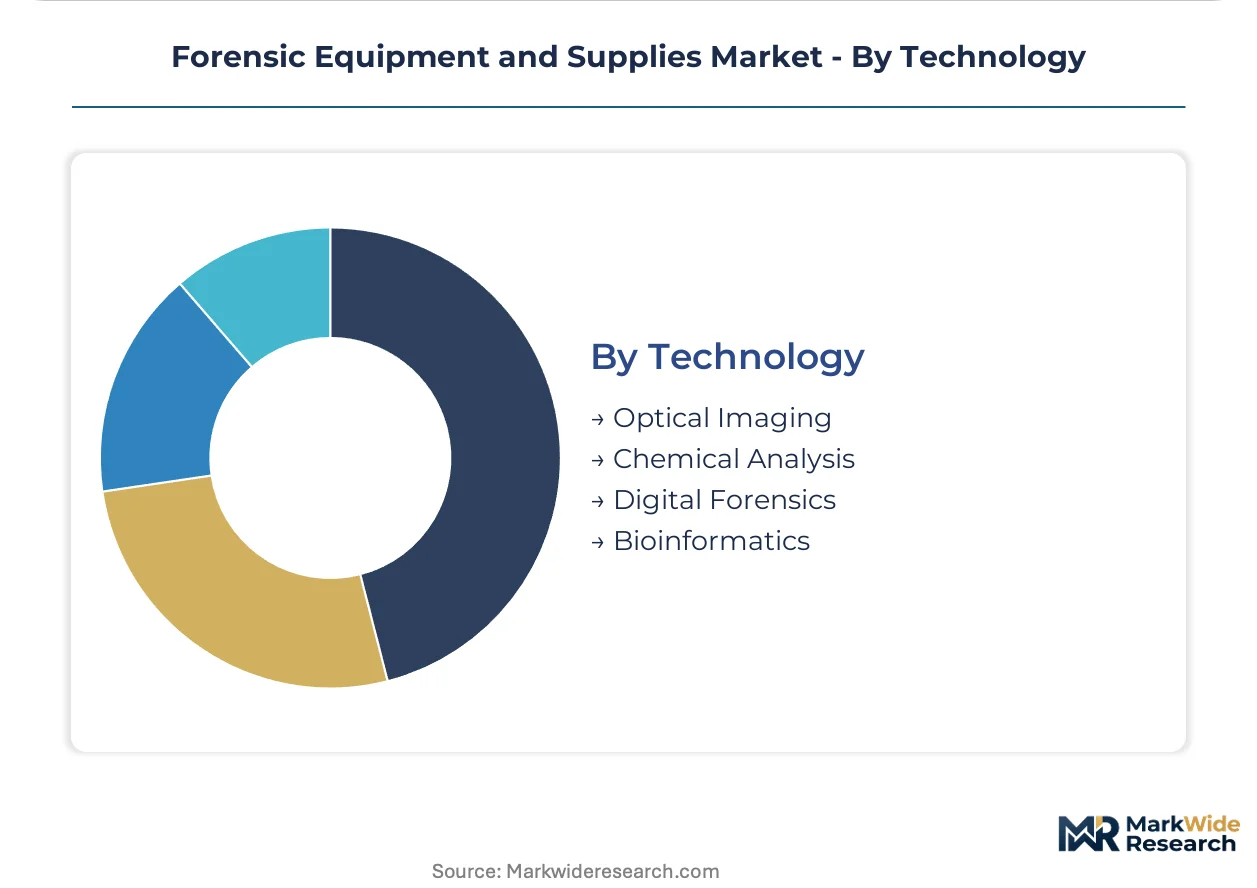
Technology:
Maturity stage and regulatory validation burden separate established analytical methods from emerging digital capabilities.
- Digital Forensics:Mobile device extraction, cloud analytics, and encrypted data recovery tools address capacity gaps as cybercrime unit caseloads overwhelm regional resources. GDPR constraints on biometric data storage in Europe force automated retention protocol implementation. This segment is expanding most quickly across accredited facilities.
- Chemical Analysis:High-resolution mass spectrometry from Waters Corporation anchors toxicology and seized-drug analysis in government laboratories. ISO 17025 accreditation requirements sustain equipment refresh cycles for chromatography and spectrometry platforms.
- Optical Imaging:Alternative light sources and digital comparison microscopes support latent print and questioned document examination.
- Bioinformatics:Software pipelines for genetic profile interpretation and database searching complement hardware sequencing investments.
Chemical Analysis holds installed capacity. Digital Forensics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States government laboratories where federal backlog reduction programs sustain premium equipment procurement, while European facilities face compressed margins under GDPR compliance cost burdens.
United States
FBI Quality Assurance Standards and CODIS database expansion drive DNA analysis tool procurement across federal, state, and municipal agencies. State forensic science commissions in California, Texas, and New York mandate ISO 17025 accreditation that disqualifies non-compliant vendors from government tenders. The Greater Boston cluster anchors high-resolution mass spectrometry validation for toxicology applications in accredited government facilities.
Germany
ENFSI guideline harmonization creates procurement specification alignment across member state laboratories, concentrating demand in Baden-Württemberg and Bavaria industrial regions. The country's national forensic science regulator enforces technical standards for genetic profile interpretation that exceed baseline EU requirements. Munich and Stuttgart host validation centers for next-generation sequencing platform deployment in centralized crime laboratories.
United Kingdom
Forensic Science Regulator statutory codes reshape equipment specifications for DNA analysis and digital evidence handling in England and Wales. The London Metropolitan Police and regional forces drive rapid DNA system adoption at booking stations under ninety-minute turnaround mandates. The Southeast England cluster concentrates private laboratory capacity serving defense and civil casework markets.
China
Ministry of Public Security standards for forensic DNA databases sustain thermal cycler and capillary electrophoresis procurement across provincial public security bureaus. The country's national standardization administration issues GB standards for evidence collection kit manufacturing that shape domestic supplier qualification. The Yangtze River Delta cluster hosts instrument assembly operations serving East China regional laboratories.
Japan
National Police Agency guidelines for forensic evidence handling drive accreditation requirements for private sector laboratories supporting criminal investigations. METI industrial standards shape quality management system specifications for analytical instrumentation deployed in government facilities. The Kanto region around Tokyo concentrates forensic science research institutes that validate emerging DNA analysis methodologies.
Forensic Equipment and Supplies Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The forensic equipment market exhibits consolidated dominance in analytical instrumentation alongside fragmented competition in collection kits and field supplies. Three archetypes define competitive positioning: diversified life science conglomerates with forensic divisions, specialized forensic instrumentation pure-plays, and consumable-focused chemistry suppliers. Strategic moves center on managed-service contract expansion and validation support bundling to capture recurring revenue streams.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific Inc. and Waters Corporation exemplify platform integrators that anchor government laboratory procurement through direct institutional channels. QIAGEN occupies a position within the consumable specialist tier, representing chemistry suppliers that lock laboratories into recurring reagent ecosystems. These three entities illustrate the competitive structure where hardware platforms and consumable workflows create divergent margin profiles and customer retention mechanisms.
| Leading Market Players |
|---|
| Waters Corporation |
| SCIEX |
| Thermo Fisher Scientific Inc. |
| HORIBA Ltd. |
| Illumina Inc. |
| Agilent Technologies Inc. |
| QIAGEN |
| BVDA International BV |
| PerkinElmer Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on specialized mass spectrometry components from Germany and Japan determines both pricing tier spreads and supply chain shape in forensic instrumentation, compressing margins for mid-tier laboratories while concentrating premium pricing power among accredited government facilities with multi-year managed-service contracts.
Pricing Analysis
Government laboratory buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 17025 certification grade and after-sales validation bundling as the primary price differentiation drivers. Pricing pressure stems from federal backlog reduction programs shifting procurement toward operational expenditure frameworks that squeeze hardware margins. State forensic science commissions exhibit the highest price sensitivity due to constrained annual budgets, while federal agencies demonstrate lowest sensitivity given dedicated program funding streams.
Supply Chain Analysis
Export-control restrictions on high-resolution mass spectrometry and next-generation sequencing platforms limit technology flows from the United States, Germany, and Japan into non-allied jurisdictions. The supply chain draws from specialized optical components sourced from Germany, precision thermal cycling modules from Japan, and rare earth magnet assemblies from China. Single-source vulnerability concentrates in capillary electrophoresis consumable chemistries. Distribution runs through direct institutional channels for government laboratories alongside regional distributors serving private forensic service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by federal forensic backlog reduction program renewals, which refresh equipment procurement cycles across government-funded facilities.
For Market Incumbents: Insulate recurring revenue streams by deepening captive supply of validation-support services and consumable chemistries that lock laboratories into multi-year contracts. Counter emerging digital forensics pure-plays by bundling hardware platforms with ISO 17025 compliance documentation. Prioritize certification investment in rapid DNA analysis systems for booking station deployment.
For New Entrants and Emerging Players: Regional cybercrime units in secondary metropolitan markets represent underpenetrated demand for mobile device extraction and cloud analytics tools. White-space exists in managed validation services for mid-sized private laboratories lacking internal proficiency testing infrastructure. Pursue channel partnerships with state forensic science commissions as the most penetrable entry path.
For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors consumable-specialist acquisitions over hardware platform consolidation. Long-term viability over the next decade hinges on recurring revenue exposure rather than capital equipment cyclicality. Target firms with embedded positions in DNA analysis consumable ecosystems. Watch ENFSI guideline harmonization progress as the signal indicating procurement specification alignment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Managed-Service Contract Expansion | Captures recurring revenue from federal backlog reduction programs shifting procurement toward operational expenditure frameworks. |
| Validation Support Bundling | Locks accredited laboratories into long-term relationships through ISO 17025 compliance documentation and proficiency testing services. |
| Digital Forensics Capability Buildout | Addresses capacity gaps as encrypted device volumes overwhelm regional cybercrime units in secondary metropolitan markets. |
| Rapid DNA System Deployment | Compresses evidence-to-intelligence timelines for local law enforcement agencies adopting ninety-minute thermal cycler units at booking stations. |
| Consumable Ecosystem Deepening | Creates switching costs through specialized sample preparation chemistries that tether laboratories to recurring reagent supply contracts. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with forensic laboratory directors, government procurement officers, crime scene investigation unit commanders, and analytical instrumentation technical specialists; and secondary validation against FBI Quality Assurance Standards documentation, ISO 17025 accreditation records, ENFSI guideline publications, and federal procurement database extracts. Bottom-up equipment installation counts triangulated against top-down government budget appropriation analysis.
Forecast inputs considered product-type segmentation across DNA analysis tools, crime scene kits, fingerprint systems, and digital forensics platforms; application segmentation spanning crime investigation, forensic laboratories, legal proceedings, and research purposes; and end-user segmentation by law enforcement, forensic scientists, private investigators, and educational institutions. CAGRs were derived from equipment refresh cycle analysis, federal program funding trajectories, and accreditation mandate expansion timelines across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese analytical instrumentation manufacturers or disruptive digital forensics pure-plays would shift outcomes. Material shifts in FBI Quality Assurance Standards revision timelines or ENFSI guideline adoption acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
MRI Transport Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Autoclaves Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Cath Lab Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Global Mortuary Equipment Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Global Microtome Market