
 Global Advanced Balloon Catheter Market | 2026-2036
Global Advanced Balloon Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Balloon Catheter Market Foresight
The premium-commodity split in advanced balloon catheters is shifting toward material science differentiation and regulatory certification depth. Abbott Laboratories leverages in-house polymer development to sustain pricing power in drug-coated platforms. Boston Scientific anchors its position through manufacturing scale across coronary and peripheral lines. Medtronic competes on integrated catheter-delivery system architectures that reduce procedural variability.
Advanced balloon catheters are inflatable medical devices constructed from multilayer polyamide or polyethylene terephthalate films, featuring hydrophilic coatings and radiopaque marker bands for fluoroscopic guidance, designed to dilate stenosed vessels or deploy stents during minimally invasive procedures. Drug-coated balloon catheters command margin concentration due to paclitaxel formulation complexity and extended regulatory validation cycles. Coronary angioplasty applications dominate volume throughput, while peripheral angioplasty segments accelerate through expanding diabetes-related limb ischemia interventions. Semi-compliant balloon materials occupy the broadest deployment footprint across catheterization labs globally.
FDA premarket notification and EU MDR conformity assessment compress development timelines while elevating clinical evidence requirements for novel coatings. Japan's PMDA and China's NMPA impose additional localization testing that shapes regional product launch sequencing. Stakeholders must monitor reimbursement parity between drug-coated and bare balloon platforms across Medicare, NHS England, and China's NHSA to anticipate volume migration between premium and standard tiers.
Market Dynamics
Material science differentiation is compressing the competitive landscape in advanced balloon catheters, as polymer formulation capabilities separate premium drug-coated platforms from commodity semi-compliant alternatives. Regulatory certification depth now determines pricing power more than manufacturing scale alone.
Growth Catalysts
- EU MDR conformity assessment:Accelerated CE marking timelines for drug-coated platforms are compressing product development cycles and rewarding early regulatory investment with faster market access across European catheterization labs.
- Diabetes-related limb ischemia interventions:Expanding peripheral angioplasty volumes in China and India are pulling semi-compliant and non-compliant balloon catheter demand into hospital systems previously focused on coronary applications.
- Multilayer polyamide film construction:Advances in hydrophilic coating adhesion and radiopaque marker band integration are enabling thinner wall profiles that improve trackability through tortuous anatomy.
Market Restraints
- Specialized polymer supply concentration:High-barrier polyethylene terephthalate film production concentrates among a limited supplier base in Germany and Japan, creating input cost volatility for catheter manufacturers without backward integration.
- Paclitaxel formulation complexity:Drug coating uniformity requirements impose technical limitations on manufacturing yield rates, elevating cost structures for drug-coated balloon platforms relative to bare alternatives.
- Japan PMDA localization testing:Additional clinical evidence requirements for novel coatings create regulatory friction that extends launch timelines and elevates development expenditure for foreign manufacturers.
Strategic Opportunities
- India's NHSA reimbursement expansion:Underpenetrated peripheral angioplasty coverage in tier-two and tier-three cities creates white space for standard semi-compliant balloon catheter penetration as public insurance broadens interventional cardiology access.
- Integrated catheter-delivery system architectures:Technology convergence between balloon dilation platforms and stent deployment mechanisms is opening design partnerships with coronary device manufacturers seeking procedural simplification.
- Direct hospital procurement channels:Group purchasing organization consolidation in the United States is creating distribution innovation opportunities for manufacturers with demonstrated FDA premarket notification track records and volume scale.
Industry Challenges
- Polymer chemist and coating engineer talent scarcity:Specialized formulation expertise required for paclitaxel-matrix development concentrates among a limited workforce pool, elevating compensation costs and recruitment timelines.
- EU MDR technical documentation requirements:Extended certification timelines for legacy product lines are forcing simultaneous maintenance of multiple quality management systems and clinical evidence portfolios.
- Fluoroscopic guidance system integration:Radiopaque marker band positioning standardization delays across catheterization lab equipment manufacturers are creating compatibility testing burdens for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Balloon Catheter Market |
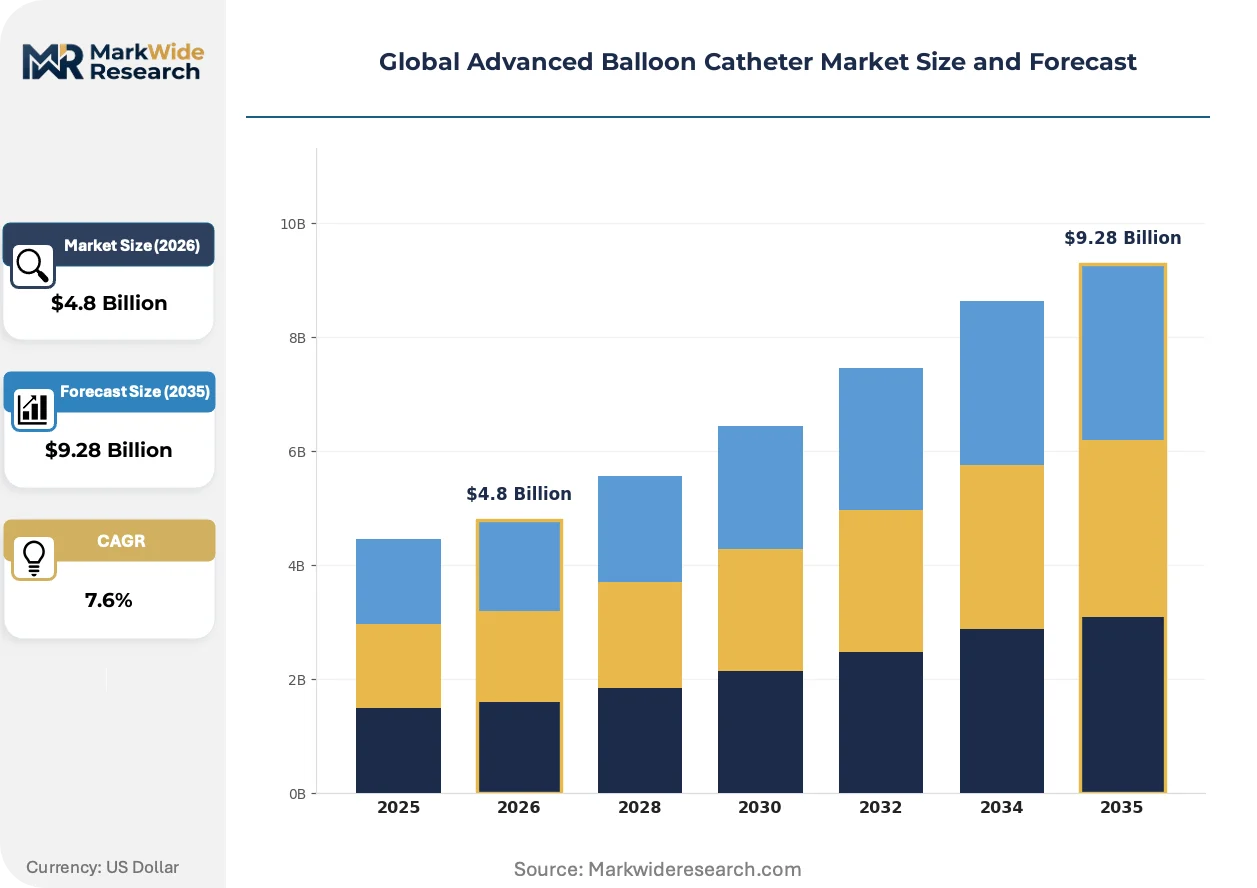
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Compliant, Semi-Compliant, Cutting, Drug-Coated, Scoring Application: Coronary Angioplasty, Peripheral Angioplasty, Urology, Gastroenterology, Neurovascular End User: Cardiology Clinics, Interventional Radiology Centers, Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories Deployment: Hospital Settings, Outpatient Facilities, Cardiac Care Units, Catheterization Labs |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic, Terumo Corporation, B. Braun Melsungen AG, MicroPort Scientific Corporation, Cook Medical, Cordis Corporation, BIOTRONIK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Balloon Catheter Market Shifts & Advancements
Active reshaping in advanced balloon catheters centers on coating technology maturation, regulatory pathway compression, and procurement model rationalization that together elevate technical barriers to competitive entry.
Drug-coated balloon technology is consolidating market position through paclitaxel-matrix formulation advances that improve tissue transfer kinetics and reduce systemic exposure. Interventional cardiologists in Germany and Japan are adopting these platforms for in-stent restenosis cases at accelerating rates. This technology is consolidating margin concentration around manufacturers with in-house polymer development capabilities, compressing competitive space for bare balloon specialists.
EU MDR Article 117 clinical evaluation requirements are elevating evidence standards for novel hydrophilic coatings and drug-matrix combinations. Manufacturers must now demonstrate biocompatibility and performance equivalence through extended bench testing and clinical follow-up. Coronary angioplasty applications face the steepest compliance burden, with European notified bodies prioritizing drug-coated platform reviews over semi-compliant bare balloon renewals.
Hospital system consolidation in the United States is compressing vendor lists and elevating certification-driven preference for manufacturers with demonstrated FDA premarket notification histories and integrated coronary-peripheral product portfolios. Traditional distributor relationships are fragmenting as integrated delivery networks negotiate direct contracts with Abbott Laboratories, Boston Scientific, and Medtronic for standardized platform procurement. This behavioral shift is most visible in Medicare reimbursement zones where catheterization lab standardization programs prioritize supply chain simplification over product variety.
Global Advanced Balloon Catheter Market Segmentation
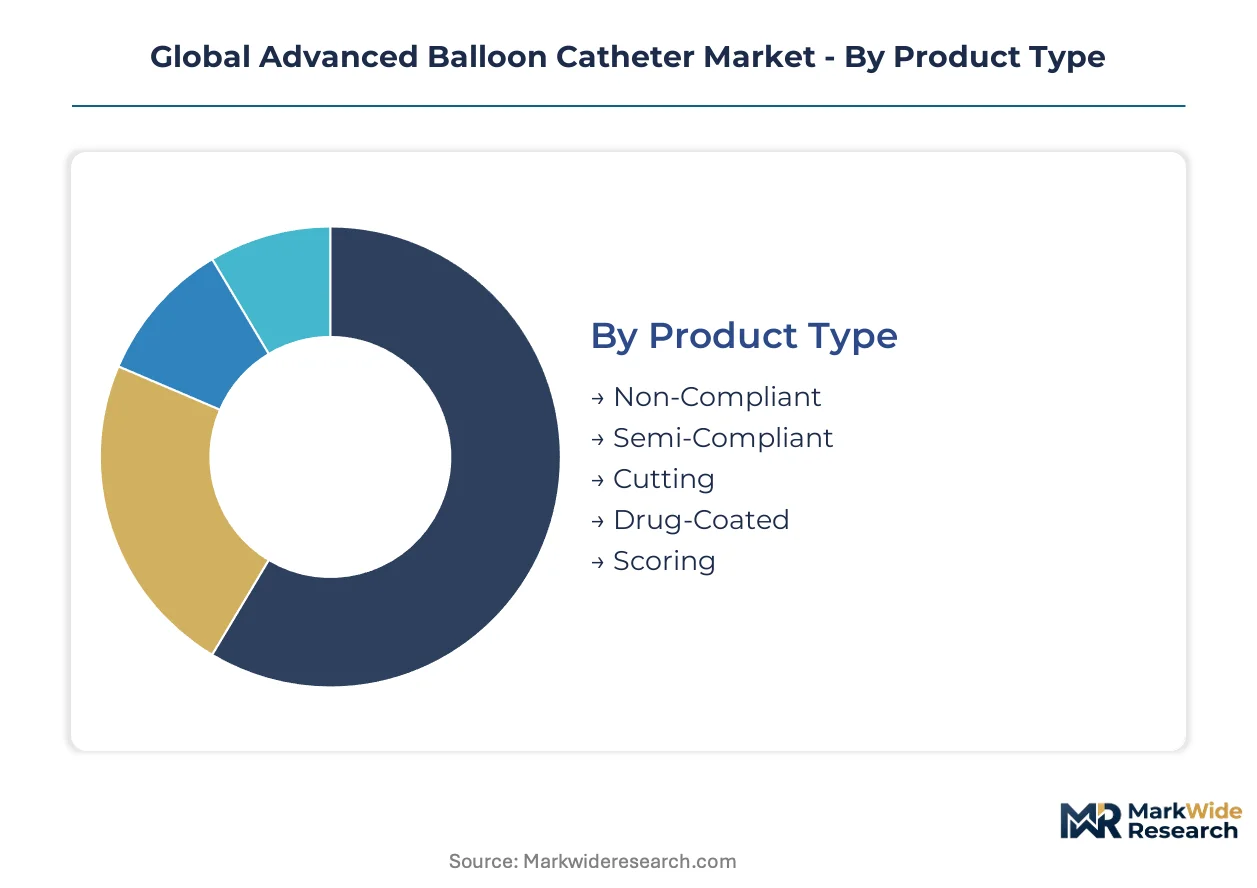
Advanced balloon catheter segmentation reveals how supply-side capabilities align with procedural complexity tiers. Manufacturers configure polymer science investments and regulatory certification depth around specific clinical use cases rather than pursuing horizontal coverage.
Product Type:
Supply concentration in polymer formulation separates commodity balloon platforms from premium drug-coated architectures, with backward integration into hydrophilic coating chemistry determining competitive position.
- Drug-Coated:Multilayer polyamide construction integrates paclitaxel-matrix coatings for controlled drug transfer kinetics. Demand concentrates in German and Japanese catheterization labs for in-stent restenosis cases, driven by EU MDR accelerated CE marking timelines rewarding early regulatory investment.
- Semi-Compliant:Polyethylene terephthalate film construction balances radial force with trackability through tortuous anatomy. Volume throughput centers on coronary angioplasty applications across United States, China, and India hospital systems, pulled by expanding interventional cardiology suite capacity.
- Non-Compliant:High-pressure inflation profiles suit calcified lesion dilation with minimal diameter variation.
- Cutting:Atherotomy blade integration enables precise plaque modification in fibrotic lesions.
- Scoring:External wire elements concentrate force for controlled vessel preparation prior to stent deployment.
Today's leader: Drug-Coated. Tomorrow's challenger: Semi-Compliant.
Application:
Cost tier stratification across procedural settings separates high-complexity coronary interventions from volume-driven peripheral cases, with reimbursement parity dictating platform selection.
- Coronary Angioplasty:Stenosed vessel dilation and stent deployment in cardiac circulation. Demand anchors in United States Medicare reimbursement zones and China's NHSA-covered tier-one hospitals, constrained by FDA premarket notification evidence requirements for novel coating introductions.
- Peripheral Angioplasty:Lower extremity revascularization for diabetes-related limb ischemia. Expansion accelerates across India's tier-two and tier-three cities as public insurance broadens access, creating white space for standard semi-compliant balloon penetration.
- Urology:Stricture dilation in ureteral and urethral applications.
- Gastroenterology:Biliary and pancreatic duct intervention platforms.
- Neurovascular:Intracranial aneurysm and vessel occlusion treatments.
Coronary Angioplasty commands current revenue concentration. Peripheral Angioplasty is climbing the fastest as diabetes prevalence drives limb salvage priorities.
End User:
Customer type fragmentation across care settings creates divergent procurement specifications, with integrated delivery networks imposing standardization that compresses vendor lists.
- Cardiology Clinics:Dedicated cardiac intervention facilities with high procedural volume. Concentration in United States group purchasing organization territories and Germany's hospital system networks, shaped by direct manufacturer contracting replacing traditional distributor relationships.
- Interventional Radiology Centers:Cross-specialty vascular access and image-guided therapy hubs. Growth centers on China's expanding provincial medical centers, driven by NMPA localization testing requirements that favor domestic supply partnerships.
- Specialty Clinics:Focused procedural environments with limited platform breadth.
- Ambulatory Surgical Centers:Same-day discharge settings with compressed supply chain requirements.
- Diagnostic Laboratories:Pre-interventional imaging and physiological assessment facilities.
Cardiology Clinics dominate procurement scale. Interventional Radiology Centers are gaining share fastest through peripheral procedure migration.
Deployment:
Geography of care delivery determines regulatory pathway selection and reimbursement coding complexity, with hospital-based catheterization labs maintaining premium platform preference.
- Catheterization Labs:Dedicated fluoroscopy-equipped suites for minimally invasive vascular intervention. Concentration in Japan's PMDA-regulated academic medical centers and India's emerging tier-one private hospital chains, constrained by radiopaque marker band positioning standardization delays across equipment manufacturers.
- Hospital Settings:Full-service inpatient environments with comprehensive emergency backup. Volume anchors in NHS England reimbursement zones and United States integrated delivery networks, pulled by catheterization lab standardization programs prioritizing supply chain simplification.
- Cardiac Care Units:Monitored environments for post-interventional observation.
- Outpatient Facilities:Lower-acuity settings with streamlined procedural protocols.
Catheterization Labs hold current technology leadership. Hospital Settings present the steepest expansion trajectory through system consolidation and vendor rationalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's catheterization lab expansion outpaces Japan's regulatory-driven consolidation, while India's public insurance reforms accelerate peripheral angioplasty access in tier-two cities. Material science capabilities and reimbursement policy divergence shape regional competitive positioning.
United States
Medicare reimbursement zones drive catheterization lab standardization programs across integrated delivery networks. FDA premarket notification pathways compress development timelines for novel hydrophilic coatings. Greater Boston and Minneapolis-St. Paul anchor polymer formulation R&D clusters where drug-coated platform innovation concentrates.
Germany
Hospital system networks expand interventional cardiology suites for in-stent restenosis cases using drug-coated platforms. EU MDR Article 117 clinical evaluation requirements elevate evidence standards for coating biocompatibility. Baden-Württemberg's medical technology corridor hosts polyethylene terephthalate film suppliers serving catheter manufacturers.
China
NHSA reimbursement expansion pulls semi-compliant balloon demand into tier-one hospitals while tier-two cities build peripheral angioplasty capacity. NMPA localization testing requirements favor domestic supply partnerships for novel coating introductions. Yangtze River Delta medical device clusters scale manufacturing for coronary and peripheral lines.
Japan
Academic medical centers concentrate drug-coated balloon adoption for complex coronary interventions. PMDA localization testing extends launch timelines for foreign manufacturers seeking coating approval. Kanto region catheterization labs prioritize radiopaque marker band standardization across fluoroscopy equipment platforms.
India
Diabetes-related limb ischemia interventions accelerate peripheral angioplasty volumes in tier-two and tier-three cities. Public insurance broadens interventional cardiology access beyond tier-one metropolitan centers. Maharashtra and Karnataka private hospital chains invest in catheterization lab capacity for coronary and peripheral procedures.
Global Advanced Balloon Catheter Market Competitive Landscape
Top-tier vendors anchor integrated coronary-peripheral portfolios, while mid-scale specialists concentrate on single-modality manufacturing or regional regulatory expertise. The competitive landscape compresses around three archetypes: polymer science-integrated developers, manufacturing scale operators, and integrated catheter-delivery system architects. M&A activity targets coating technology assets, while strategic partnerships link balloon platforms with stent deployment mechanisms.
Among US-based multinationals, Abbott Laboratories, Boston Scientific Corporation, and Medtronic occupy positions across the premium-tier drug-coated and semi-compliant balloon segments. Abbott Laboratories represents the polymer science-integrated archetype through in-house formulation capabilities. Boston Scientific Corporation exemplifies manufacturing scale advantages across coronary and peripheral product lines. Medtronic anchors the integrated catheter-delivery system architecture approach that reduces procedural variability.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic |
| Terumo Corporation |
| B. Braun Melsungen AG |
| MicroPort Scientific Corporation |
| Cook Medical |
| Cordis Corporation |
| BIOTRONIK |
| Others |
Supply & Pricing Matrix
Polyethylene terephthalate film costs originating in Baden-Württemberg and Osaka manufacturing corridors cascade through three pricing tiers, with hydrophilic coating chemistry investments separating premium drug-coated platforms from commodity semi-compliant alternatives in hospital procurement decisions.
Pricing Analysis
Capacity additions in China's Yangtze River Delta medical device clusters are reshaping price floors for standard semi-compliant balloon catheters. Three-tier pricing structure across premium, standard, and economy levels reflects EU MDR certification depth and FDA premarket notification history as primary differentiation drivers. Pricing pressure stems from group purchasing organization consolidation in United States Medicare zones, compressing margins for bare balloon specialists. Tier-two hospital systems in India exhibit highest price sensitivity, while German academic medical centers prioritize coating performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Shanghai, and Minneapolis-St. Paul anchor hub-and-spoke patterns for catheter manufacturers serving integrated delivery networks. High-barrier polyethylene terephthalate film production concentrates in Germany and Japan, with hydrophilic coating chemistries and radiopaque marker bands as critical component inputs. Single-source vulnerability in specialized polymer supply elevates risk exposure for manufacturers lacking backward integration into formulation capabilities. Distribution runs through direct hospital procurement channels and group purchasing organization networks, bypassing traditional medical device distributors in consolidated United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced balloon catheter markets have entered a late-cycle quality phase where drug-coated platform specifications command procurement preference, driven by interventional cardiologist demand for in-stent restenosis cases with superior tissue transfer kinetics.
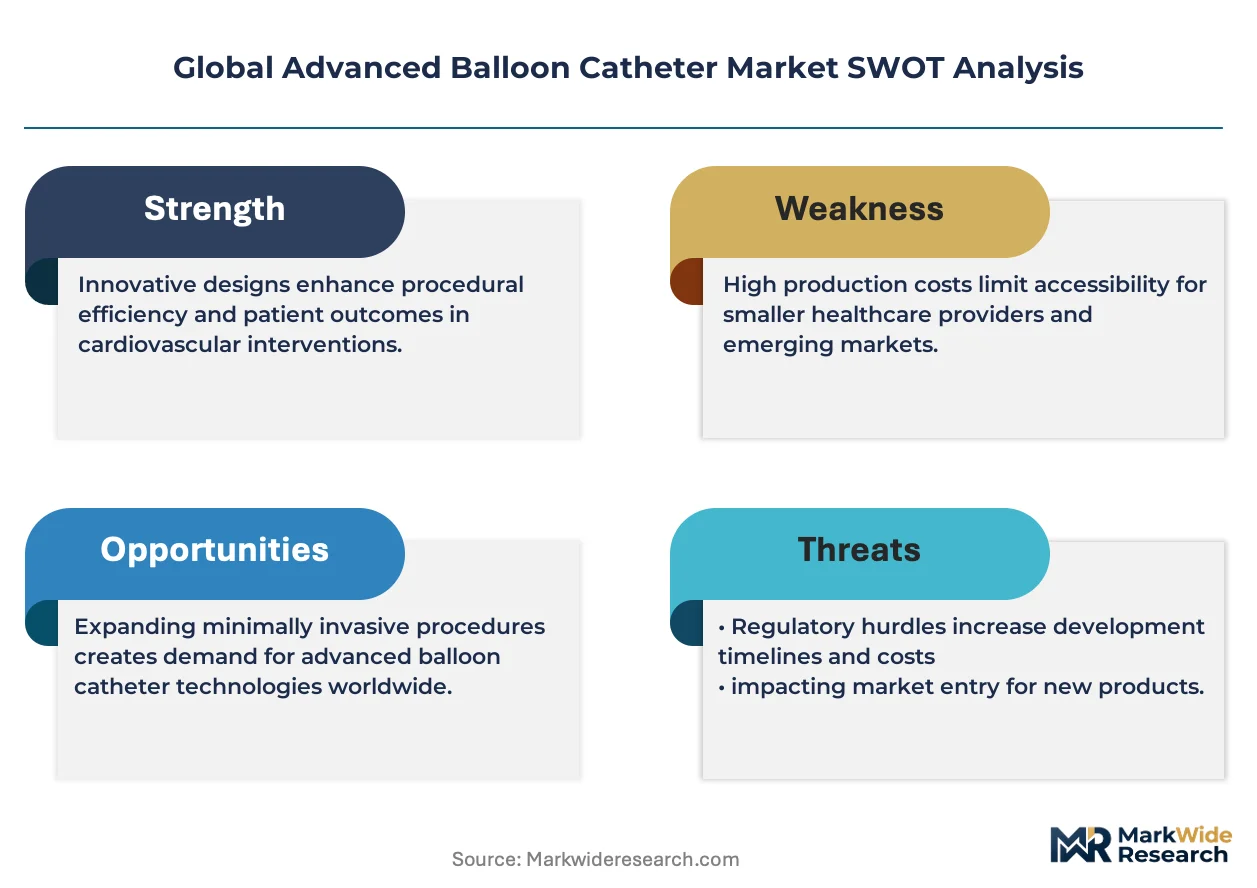
For Market Incumbents: To counter margin compression from group purchasing organization consolidation, Abbott Laboratories and Boston Scientific should deepen captive supply of paclitaxel-matrix formulations while accelerating EU MDR Article 117 clinical evaluation submissions for novel hydrophilic coatings. Hospital system direct contracting capabilities represent the critical defensive lever for vendor list retention. For New Entrants and Emerging Players: Specialty distributors serving India's tier-two and tier-three cities offer the most penetrable channel partnership for standard semi-compliant balloon catheter penetration, leveraging NHSA reimbursement expansion as the go-to-market angle. Peripheral angioplasty white space in Maharashtra and Karnataka private hospital chains presents volume-scale opportunity without direct incumbent confrontation. For Investors and Strategic Acquirers: Consolidation pressure builds where polymer chemist and coating engineer talent scarcity intersects with EU MDR technical documentation requirements forcing legacy product line maintenance. Acquisition targets should display in-house formulation capabilities and demonstrated FDA premarket notification track records. The signal to watch is reimbursement parity shifts between drug-coated and bare balloon platforms across Medicare, NHS England, and China's NHSA.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Accelerated CE Marking Pathway | Early regulatory investment compresses market access timelines for drug-coated platforms in German catheterization labs. |
| Hospital System Partnership | Direct contracting with United States integrated delivery networks bypasses distributor fragmentation and secures vendor list position. |
| Backward Integration into Polymer Formulation | In-house paclitaxel-matrix development insulates margin concentration from specialized supplier cost volatility. |
| Peripheral Angioplasty Reimbursement Strategy | NHSA coverage expansion in India's tier-two cities unlocks white space for semi-compliant balloon volume penetration. |
| Radiopaque Marker Band Standardization | Compatibility alignment with Japan's PMDA-regulated fluoroscopy equipment reduces catheterization lab integration delays. |
Research Methodology
Multiple input streams — primary interviews with interventional cardiologists and hospital purchasing committees, secondary validation through FDA 510(k) filings and EU MDR notified body documentation, and procurement database analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed biomedical engineers at German academic medical centers, GPO contracts managers in United States Medicare zones, and regulatory affairs leads navigating Japan's PMDA localization testing requirements. Secondary sources included CMS Medicare reimbursement data, NHS England procurement records, and China's NHSA coverage expansion announcements.
Historical volume trajectories were cross-referenced against panel input from catheterization lab directors and polymer formulation specialists to construct projections across the analysis window. Segmentation modeling incorporated product type differentiation, application complexity tiers, end-user procurement specifications, and deployment setting regulatory pathways. CAGRs were derived from procedure volume elasticity to reimbursement expansion and interventional cardiology suite capacity additions. Industry-specific inputs included diabetes-related limb ischemia intervention rates and drug-coated balloon adoption curves for in-stent restenosis cases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR certification timeline compression, polymer supply concentration disruptions, and reimbursement parity shifts between platform tiers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global 3D Vascular Ultrasound Imaging Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Drug Eluting Stent (DES) Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Blood Fluid Warming System Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
United Kingdom Cardiovascular Devices Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Blood Pressure Transducers Market