
 North America Renal Denervation Devices Market | 2026-2036
North America Renal Denervation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Renal Denervation Devices Market Analytics
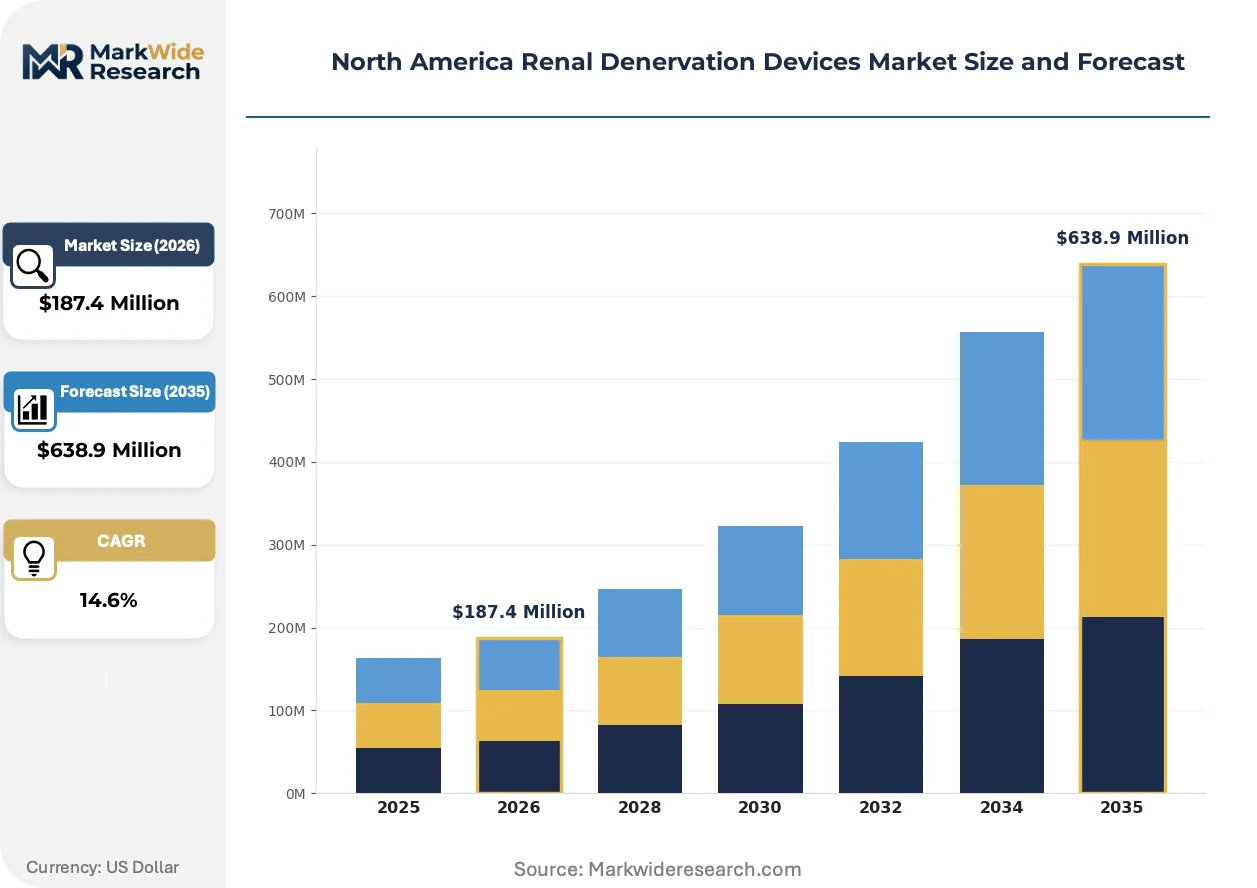
CE marking reciprocity under the FDA's Medical Device Single Audit Program is reorganizing competitive access across North America. Medtronic leverages its integrated catheter manufacturing footprint to sustain supply continuity for radiofrequency platforms. Boston Scientific Corporation anchors its position through deep electrophysiology channel relationships. ReCor Medical differentiates via ultrasound-based systems that bypass traditional RF energy delivery.
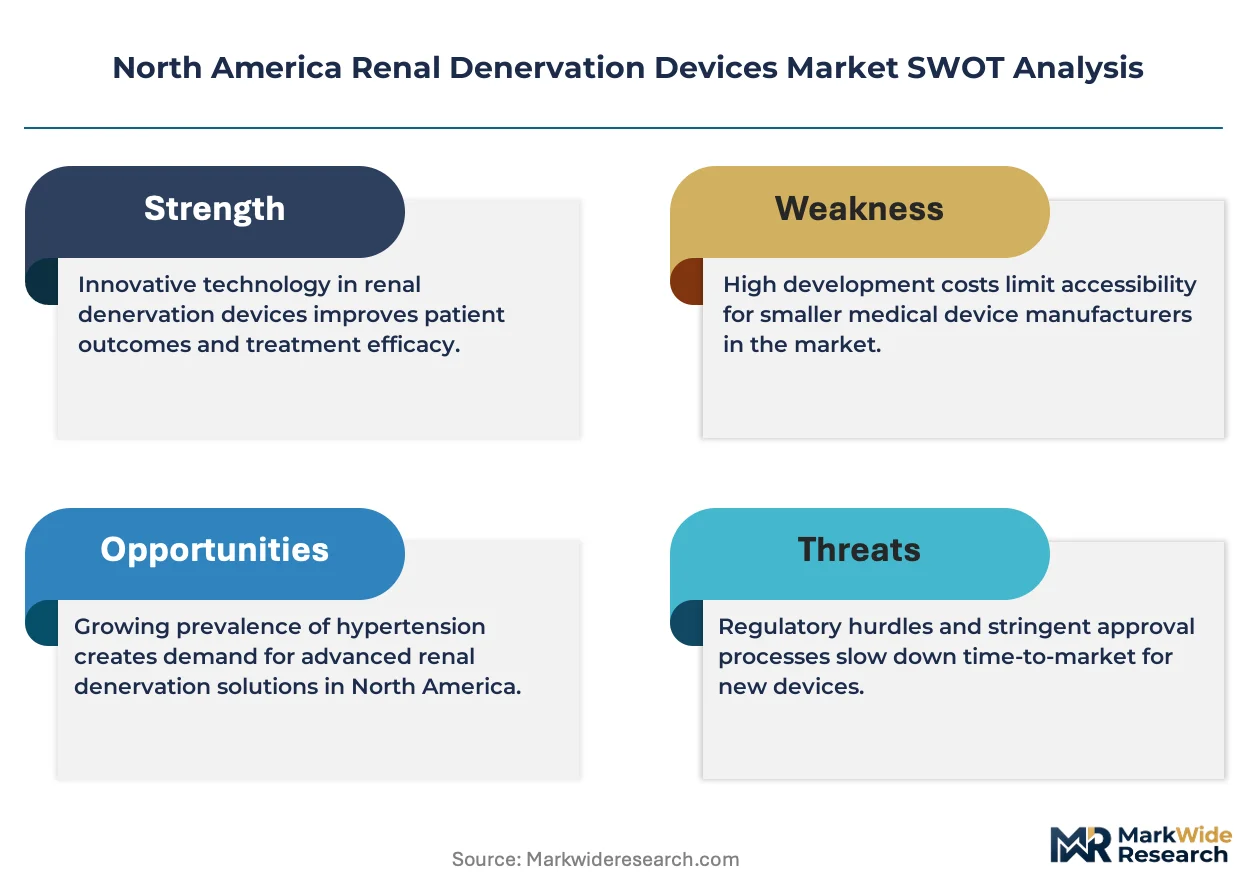
Renal denervation devices are interventional instruments designed to ablate perivascular renal sympathetic nerves through controlled energy delivery, typically operating at radiofrequency ranges of 460–500 kHz or ultrasonic frequencies near 20 MHz to achieve nerve fiber disruption without vascular injury. Their primary purpose is to reduce systemic sympathetic tone in patients with treatment-resistant hypertension. Radiofrequency catheter systems occupy the dominant revenue position due to established reimbursement codes and physician familiarity, while ultrasound-based platforms represent the fastest-expanding segment as clinical data accumulates for denervation without vessel contact. Hospitals command the largest end-user share given capital requirements and interventional cardiology staffing, though outpatient surgical centers are gaining procedure volume as same-day protocols standardize.
The FDA's Breakthrough Devices Program and subsequent premarket approval reviews govern commercial entry timelines, while Health Canada's Medical Devices Directorate maintains parallel but non-identical evidentiary standards that delay synchronized launches. CMS national coverage determinations and provincial health technology assessments in Canada directly shape hospital procurement budgets and adoption velocity. Stakeholders must monitor evolving symplicity trial readouts and parallel reimbursement rulings to calibrate capital allocation between established RF platforms and next-generation ultrasonic modalities.
Market Dynamics
The FDA's premarket approval pathway for catheter-based hypertension therapies is compressing commercial timelines while Health Canada's Medical Devices Directorate maintains divergent evidentiary standards, creating asynchronous launch windows across the continent.
Growth Catalysts
- Radiofrequency catheter standardization:Established Medicare reimbursement codes under CMS national coverage determinations accelerate hospital procurement cycles for interventional cardiology departments.
- Ultrasound-based nerve ablation:Non-contact energy delivery mechanisms reduce procedural complexity and expand treatable patient populations at academic medical centers.
- Ontario and Quebec adoption corridors:Provincial health technology assessments in Canada create secondary demand concentration beyond United States hospital systems.
Market Restraints
- Capital intensity of RF platform manufacturing:Integrated catheter production requires specialized cleanroom facilities and precision extrusion capabilities concentrated among limited equipment suppliers.
- FDA-Health Canada regulatory asynchrony:Non-identical evidentiary standards delay synchronized product launches and fragment commercial resource allocation.
- Sympathetic nerve regeneration biology:Incomplete durability data for denervation effects creates payer hesitation for repeat-procedure coverage determinations.
Strategic Opportunities
- Outpatient surgical center channel expansion:Same-day discharge protocols standardize across ambulatory facilities in the United States, reducing per-procedure overhead capture.
- Ultrasound-RF hybrid platform development:Convergence of energy modalities enables physician selection based on renal artery anatomy without capital equipment switching.
- Breakthrough Devices Program qualification:Expedited FDA review pathways compress time-to-reimbursement for novel denervation technologies addressing treatment-resistant hypertension.
Industry Challenges
- Interventional cardiology fellowship pipeline constraints:Limited training slots for complex endovascular procedures restrict qualified operator availability outside tertiary academic centers.
- Symplicity trial readout dependency:Ongoing clinical evidence generation creates commercial planning uncertainty until long-term efficacy endpoints mature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Renal Denervation Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Ultrasound, Cryoablation, Laser End User: Hospitals, Clinics, Outpatient Surgical Centers, Specialty Practices Technology: Catheter-based, Non-invasive, Robotic-assisted, Mapping Procedure Type: Interventional, Electrophysiology, Catheter Ablation, Surgical |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, ReCor Medical, Ablative Solutions, Mercator MedSystems, Terumo Corporation, Symple Surgical, Otsuka Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Renal Denervation Devices Market Evolving Landscape
Energy modality diversification and procedural site-of-care migration are restructuring competitive positioning across North American hypertension intervention markets.
Ultrasound-based renal denervation systems operate at frequencies near 20 MHz to achieve nerve fiber disruption without direct vessel contact. Cardiology departments at academic medical centers adopt these platforms fastest as operators seek reduced thermal injury risk. This modality is displacing radiofrequency dominance in tortuous renal anatomy cases where catheter contact proves unreliable.
The FDA's Breakthrough Devices Program creates expedited premarket review pathways for novel hypertension therapies. This regulatory mechanism compresses commercial entry timelines by 12-18 months relative to standard PMA submissions. Device manufacturers targeting the United States prioritize this qualification to accelerate CMS national coverage determination eligibility.
Hospital procurement committees now bundle capital equipment acquisitions with multi-year disposable supply agreements. This contractual structure locks interventional cardiology departments into single-vendor energy platforms. The shift is most visible in United States integrated delivery networks where standardization reduces inventory complexity across multiple catheterization laboratories.
North America Renal Denervation Devices Market Segmentation
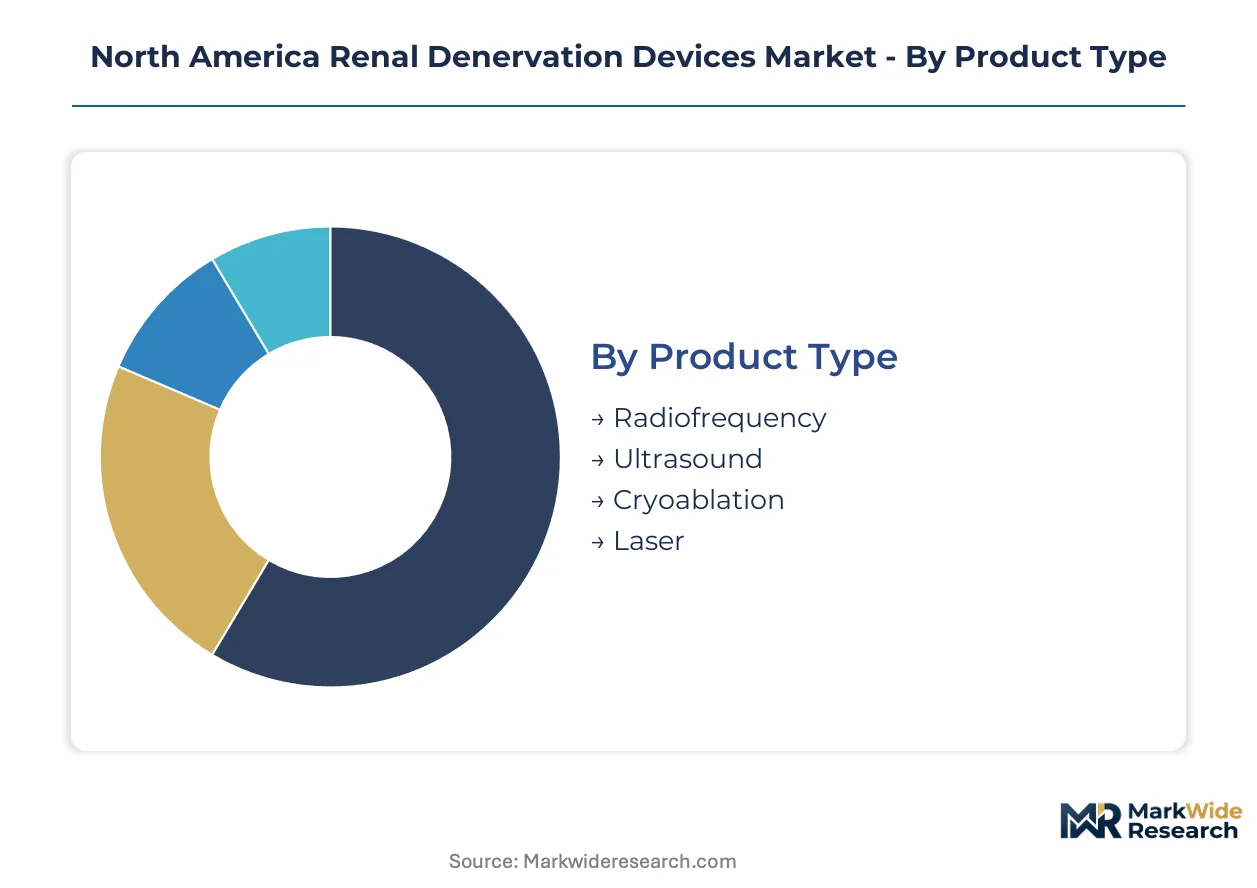
Segmentation in renal denervation reveals how energy delivery mechanisms, procedural settings, and technological interfaces compete for capital allocation across North American healthcare systems. Understanding these divisions exposes substitution risks between established radiofrequency platforms and emerging ultrasound modalities.
Product Type:
Radiofrequency catheter systems face the strongest substitution pressure from ultrasound-based alternatives that eliminate vessel contact requirements and reduce thermal injury risk.
- Radiofrequency:These systems deliver energy at 460–500 kHz through catheter electrodes positioned against renal artery walls. United States academic medical centers concentrate procurement of these platforms due to established Medicare reimbursement codes and deep physician familiarity with catheter manipulation techniques.
- Ultrasound:Operating near 20 MHz, these devices achieve nerve fiber disruption without direct vessel contact. Ontario and Quebec hospital systems are expanding adoption fastest as operators seek reduced procedural complexity in tortuous renal anatomy cases.
- Cryoablation:Balloon-based cooling systems deliver targeted thermal destruction through nitrous oxide or argon gas expansion.
- Laser:Optical energy delivery platforms remain developmental with limited commercial penetration in North American markets.
Radiofrequency retains volume leadership; ultrasound holds the steepest expansion curve.
End User:
Site-of-care economics are shifting procedure volume from inpatient settings toward ambulatory facilities as same-day discharge protocols standardize across the United States.
- Hospitals:Tertiary care centers with interventional cardiology departments command capital equipment budgets and specialized staffing for complex endovascular procedures.
- Clinics:Cardiology specialty clinics in urban United States corridors are adding procedural capabilities through mobile catheterization laboratory partnerships.
- Outpatient Surgical Centers:These facilities capture growing volume through streamlined same-day protocols that reduce per-procedure overhead capture.
- Specialty Practices:Electrophysiology-focused groups in Texas and California are integrating denervation into hypertension management workflows.
Hospitals dominate capital deployment; outpatient surgical centers are climbing the fastest.
Technology:
Interface complexity separates segments that require specialized operator training from those designed for broader clinical adoption.
- Catheter-based:Flexible delivery systems with steerable tips enable precise positioning against renal artery walls. United States integrated delivery networks bundle these acquisitions with multi-year disposable supply agreements.
- Non-invasive:External energy delivery systems remain investigational with limited commercial availability pending FDA premarket approval pathways.
- Robotic-assisted:Magnetic navigation and robotic catheter manipulation platforms address operator skill constraints outside tertiary academic centers.
- Mapping:Integrated imaging and nerve localization technologies reduce procedure time and improve ablation completeness.
Catheter-based systems anchor current revenue; robotic-assisted platforms are gaining share fastest.
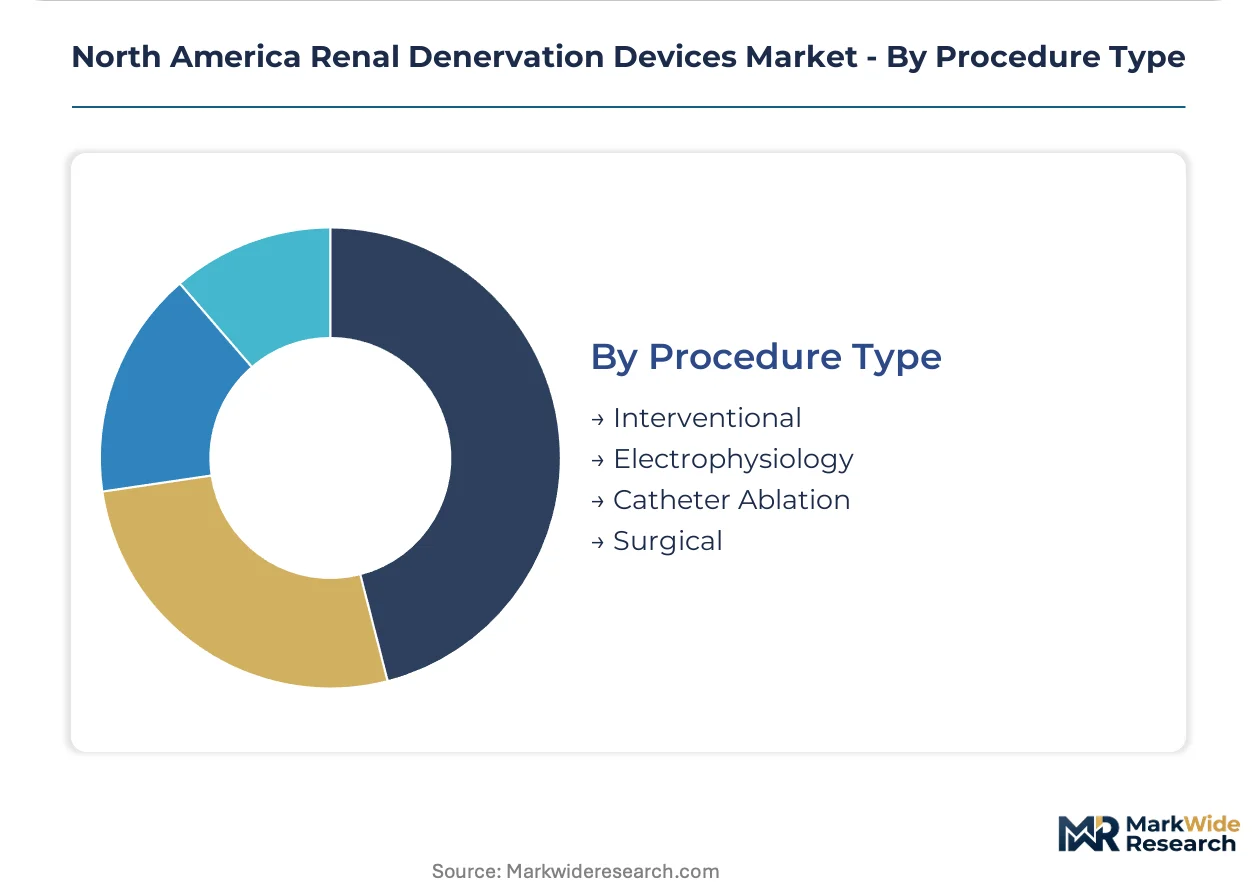
Procedure Type:
Procedural categorization reflects how renal denervation integrates into existing cardiovascular service lines versus establishing standalone clinical programs.
- Interventional:Standard catheter-based approaches performed by interventional cardiologists in dedicated catheterization laboratories.
- Electrophysiology:Integration into EP laboratory workflows leverages existing mapping equipment and operator expertise in energy delivery.
- Catheter Ablation:Hybrid procedures combining renal denervation with cardiac ablation for patients with comorbid arrhythmia and hypertension.
- Surgical:Laparoscopic and open surgical approaches for patients with anatomical contraindications to endovascular access.
Interventional procedures capture the largest volume; electrophysiology integration shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways and Medicare reimbursement determinations from CMS accelerate hospital procurement cycles across the United States. Health Canada's Medical Devices Directorate maintains parallel evidentiary standards that shape adoption velocity in provincial health systems.
United States
Academic medical centers in Boston and Houston drive catheter-based radiofrequency system adoption through established interventional cardiology fellowship programs. The FDA's Breakthrough Devices Program compresses commercial entry timelines by 12-18 months for novel hypertension therapies. Integrated delivery networks in Texas and California bundle capital equipment with multi-year disposable supply agreements.
Canada
Ontario and Quebec hospital systems represent secondary demand concentration as provincial health technology assessments expand coverage eligibility. Health Canada's Medical Devices Directorate applies non-identical evidentiary standards that delay synchronized launches with United States markets. Toronto and Montreal academic centers adopt ultrasound-based platforms fastest for tortuous renal anatomy cases.
Mexico
Private hospital chains in Mexico City and Monterrey introduce renal denervation through medical tourism channels serving North American patients. The country's national pharmaceutical regulator evaluates device registrations under convergent standards with FDA determinations. Guadalajara medical clusters build electrophysiology capacity through cross-border training partnerships with United States academic centers.
North America Renal Denervation Devices Market Competitive Landscape
Player mix skews toward diversified cardiovascular device conglomerates with integrated catheter manufacturing footprints. The market structure concentrates around established electrophysiology channel relationships and premarket approval regulatory expertise. Strategic archetypes include radiofrequency platform incumbents, ultrasound modality specialists, and integrated hospital supply contractors. Dominant competitive moves encompass multi-year disposable supply agreements with integrated delivery networks and expedited FDA qualification through the Breakthrough Devices Program.
Within the diversified cardiovascular device tier, Medtronic and Boston Scientific Corporation occupy positions anchored by deep interventional cardiology channel relationships. ReCor Medical exemplifies the ultrasound modality specialist archetype, differentiating through non-contact energy delivery mechanisms. These three entities represent the competitive spectrum from integrated manufacturing scale to technology-specific clinical positioning.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| ReCor Medical |
| Ablative Solutions |
| Mercator MedSystems |
| Terumo Corporation |
| Symple Surgical |
| Otsuka Medical Devices |
| Others |
Value Network & Pricing Analysis
Multi-year disposable supply agreements with integrated delivery networks lock in catheter volume commitments and stabilize unit economics across volatile reimbursement cycles. These contracts bundle capital equipment placement with recurring consumable purchases, creating mutual hostage positions that dampen spot-market pricing volatility.
Pricing Analysis
Cost-plus contracts with Medicare reimbursement indexation anchor hospital procurement negotiations for radiofrequency catheter systems. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with research commitments from community hospitals and ambulatory surgical centers. Price differentiation hinges on catheter electrode configuration complexity and after-sales clinical training bundling. Pricing pressure stems from ultrasound modality substitution in tortuous anatomy cases where RF contact proves unreliable. Outpatient surgical centers exhibit highest price sensitivity due to thin per-procedure margins, while academic centers prioritize clinical outcome data over unit cost.
Supply Chain Analysis
United States and Ireland anchor precision catheter extrusion and electrode assembly for radiofrequency platforms, while Germany and Japan supply high-frequency ultrasound transducer components. Raw material dependencies center on medical-grade nitinol for catheter shafts, platinum-iridium for electrodes, and specialized polymers for balloon catheters. Supply chain risk concentrates in single-source vulnerability for precision extrusion equipment used in integrated cleanroom manufacturing. Distribution runs through dedicated cardiovascular device distributors with consignment inventory at hospital catheterization laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Energy modality fragmentation creates niche opportunities as ultrasound platforms displace RF dominance in specific anatomical indications. The shift from inpatient to ambulatory settings fragments buyer power and opens channel entry points.
For Market Incumbents: Fortify catheter manufacturing scale through backward integration into nitinol wire drawing and electrode plating operations. Lock in interventional cardiology fellowship training slots to restrict qualified operator pipeline access for ultrasound competitors. Prioritize Breakthrough Devices Program qualification to compress FDA review timelines and accelerate CMS coverage determination eligibility. For New Entrants and Emerging Players: Anchor in Ontario and Quebec hospital systems where provincial health technology assessments create faster adoption corridors than United States integrated delivery networks. Target outpatient surgical centers in Texas and California with same-day discharge protocol equipment packages. Pursue robotic-assisted catheter navigation to address operator skill constraints outside tertiary academic centers. For Investors and Strategic Acquirers: The market sits at a modality-transition phase that favors ultrasound technology specialists with differentiated non-contact energy delivery. Long-term viability hinges on durability data maturation for sympathetic nerve regeneration biology. Acquisition target archetype: pre-revenue ultrasound platform developers with Health Canada submissions pending. The signal to watch is CMS national coverage determination timing for novel energy modalities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Program Qualification | Expedited premarket review compresses commercial entry timelines by 12-18 months for novel hypertension therapies. |
| Multi-Year Disposable Supply Agreements | Bundled contracts with integrated delivery networks lock catheter volume and reduce inventory complexity across laboratories. |
| Ultrasound-RF Hybrid Platform Development | Convergence enables physician energy selection based on renal artery anatomy without capital equipment switching costs. |
| Outpatient Surgical Center Channel Expansion | Same-day discharge protocols standardize across ambulatory facilities, capturing procedure volume from inpatient settings. |
| Interventional Cardiology Fellowship Partnerships | Training slot control restricts qualified operator availability and defends channel access against emerging competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, CMS national coverage determination databases, hospital procurement records, and Health Canada medical device licenses. Bottom-up triangulation across catheter shipment data and top-down reconciliation against reimbursement claim volumes anchored market size estimates.
Across the analysis window, the forecasting framework modeled energy modality substitution dynamics, procedural site-of-care migration, and regional regulatory asynchrony between FDA and Health Canada pathways. Segmentation dimensions included product type, end-user facility tier, technology interface complexity, and procedural integration pattern. CAGRs were derived from procedural volume elasticity to reimbursement coverage expansion and operator training pipeline constraints.
Underlying assumptions cover Medicare coverage determination timelines and sympathetic nerve regeneration durability, with deviation risk concentrated in FDA-Health Canada regulatory asynchrony and ultrasound clinical data maturation. Forecasts reflect these assumptions with explicit sensitivity to reimbursement policy shifts. Recalibration cycles align with material shifts in CMS national coverage determinations and provincial health technology assessment rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Global Walking Assist Devices Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Medical Injection Molding Machine Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Massage Equipment Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Epistaxis Devices Market