
 Italy Water Soluble Fertilizer Market | 2026-2036
Italy Water Soluble Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Water Soluble Fertilizer Market Intelligence
Modular micronutrient bundles paired with macronutrient base packs is rebalancing procurement patterns among Italian greenhouse operators. ICL sustains strong positions in specialty potassium formulations for protected agriculture. Biolchim SPA specializes in biostimulant-integrated water soluble lines for high-value vegetable crops. Valagro competes through marine-extraction technologies that differentiate its micronutrient portfolio in the premium horticulture segment.
Water soluble fertilizers are multi-nutrient compounds manufactured to dissolve completely in irrigation water, typically containing nitrogen, phosphorus, and potassium in ratios engineered for immediate plant uptake through fertigation or foliar delivery systems. These formulations achieve near-total solubility specifications exceeding 99.5% to prevent emitter clogging in drip systems and enable precise nutrient dosing aligned with crop phenological stages. NPK complexes occupy the dominant value position due to their versatility across Italy's diverse vegetable and fruit production systems. Drip irrigation application mode represents the fastest-expanding channel as subsurface fertigation infrastructure spreads through the Po Valley and southern greenhouse clusters. Liquid formulation types command margin premiums where growers prioritize tank-mix compatibility and labor efficiency in large-scale operations.
Italy's Ministry of Agriculture enforces the National Fertilizer Register requiring complete guaranteed analysis disclosure and heavy metal limits on all water soluble products, directly conditioning market access for domestic and imported formulations. CE marking under EU fertilizer regulations harmonizes cross-border product circulation while REACH compliance governs raw material sourcing for chelated micronutrient components. Stakeholders must monitor evolving EU sustainability criteria for fertilizer products and anticipate how Italy's irrigation efficiency incentives will reshape demand toward precision-compatible soluble formulations.
Market Dynamics
Fertigation infrastructure density across the Po Valley is compressing application cycles and forcing formulation upgrades. Greenhouse operators in Emilia-Romagna now demand near-total solubility specifications to prevent emitter clogging in subsurface drip systems, reshaping procurement specifications throughout the supply chain.
Growth Catalysts
- Italy's National Fertilizer Register:Mandatory nutrient disclosure and heavy metal limits under the Ministry of Agriculture are filtering out low-grade imports and elevating quality standards across domestic distribution channels.
- Protected agriculture expansion:Greenhouse operators in the Po Valley are scaling precision irrigation programs that require soluble NPK complexes engineered for immediate plant uptake.
- EU Green Deal alignment:Sustainability criteria for fertilizer products are redirecting R&D investment toward precision-compatible formulations with reduced environmental runoff profiles.
Market Restraints
- Potassium sulfate cost volatility:Raw material price swings in global potash markets compress margin stability for specialty potassium formulation producers serving Italian protected agriculture.
- Chelated micronutrient supply concentration:REACH compliance requirements for raw material sourcing limit supplier pools for EDTA and EDDHA chelates, creating dependency on concentrated European chemical processors.
- Organic fertilizer substitution:Biostimulant-integrated organic alternatives are capturing share in premium vegetable segments where growers prioritize soil microbiome restoration over mineral nutrition.
Strategic Opportunities
- Southern greenhouse clusters:Puglia and Sicily protected agriculture infrastructure remains underpenetrated by precision fertigation systems, offering expansion terrain for soluble formulation providers.
- Marine-extraction technology convergence:Integration of algae-derived biostimulants with water soluble base packs creates differentiated positioning in high-value tomato and pepper production.
- Irrigation efficiency incentives:Italy's regional agricultural development programs subsidize drip system upgrades, indirectly subsidizing demand for compatible soluble fertilizers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in chelation chemistry and compatibility testing for tank-mix applications is concentrated among aging technical staff at established manufacturers.
- CE marking timeline compression:Evolving EU fertilizer regulations require accelerated recertification cycles that strain regulatory affairs capacity at mid-scale producers.
- Legacy blending equipment integration:Retrofitting continuous dissolution systems into existing fertilizer production lines demands capital outlays that smaller regional blenders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Water Soluble Fertilizer Market |
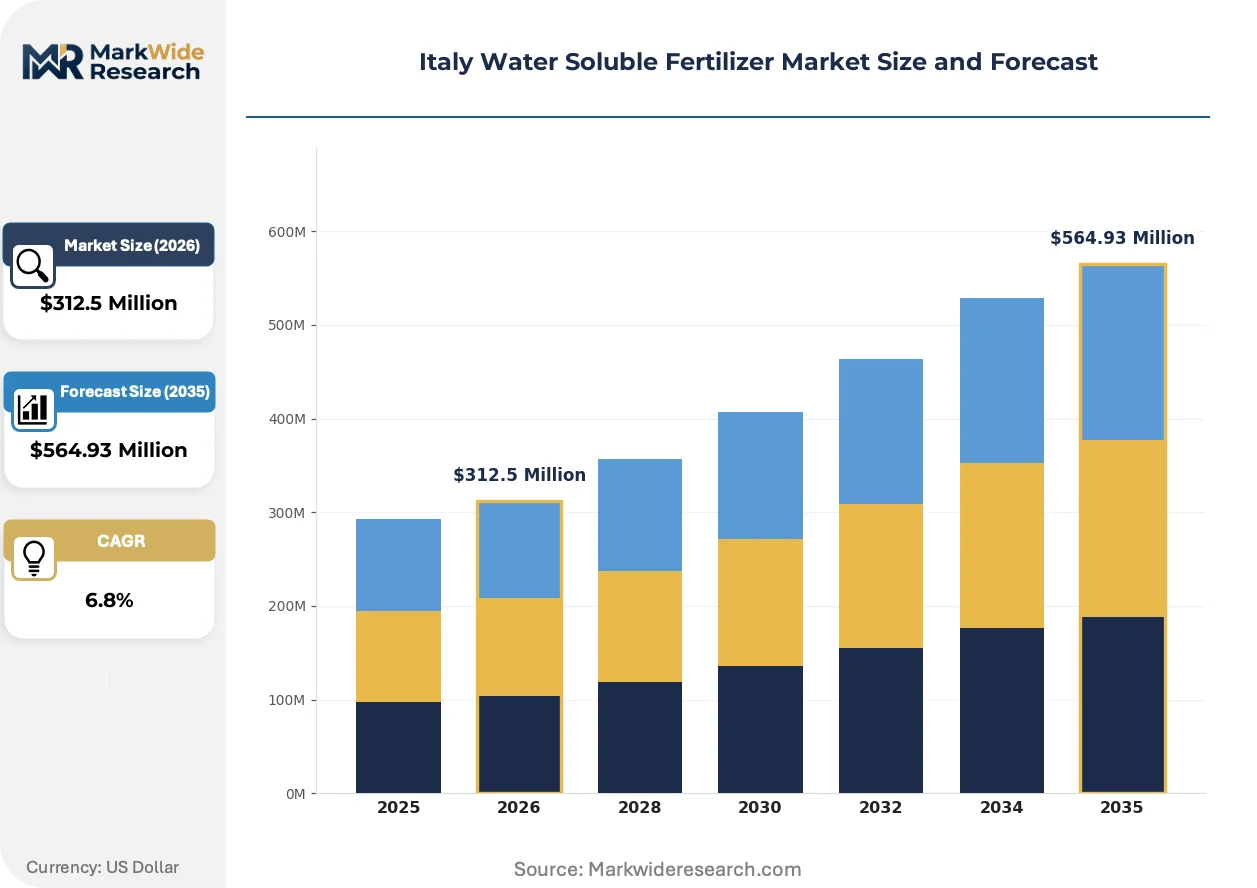
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NPK, Calcium, Micronutrients, Urea End User: Agricultural Producers, Greenhouses, Nurseries, Landscape Professionals Application Mode: Foliar, Drip Irrigation, Soil Application, Hydroponics Formulation Type: Granular, Liquid, Powder, Others |
| Companies Covered | TIMAC AGRO, K+S Aktiengesellschaft, ICL, Biolchim SPA, COMPO EXPERT, Akzo Nobel N.V., Valagro, Haifa Negev Technologies LTD, EuroChem, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Water Soluble Fertilizer Market Strategic Shifts & Innovations
Digital nutrient management platforms are converging with precision irrigation hardware to enable real-time dosing adjustments. This integration is compressing the gap between soil sensor data and soluble fertilizer application rates across Italian protected agriculture.
Controlled-release coating technologies applied to water soluble granules are rewriting application frequency economics for greenhouse operators. Tomato producers in Emilia-Romagna are piloting these hybrid formulations to reduce labor cycles from weekly to biweekly fertigation events. The technology is compressing operational costs while maintaining nutrient delivery precision.
Italy's Ministry of Agriculture is tightening heavy metal thresholds under the National Fertilizer Register beyond baseline EU requirements. Domestic manufacturers are reformulating micronutrient lines to meet stricter cadmium and nickel limits, while importers face exclusion from distribution networks. Specialty potassium producers serving the premium horticulture segment are absorbing the highest compliance costs.
Buyer concentration among large-scale greenhouse cooperatives is consolidating procurement decisions into centralized technical committees. Smaller regional distributors are losing direct access to end-users as these cooperatives negotiate volume contracts with formulation manufacturers. The shift is most visible in the Po Valley where irrigation density correlates with cooperative membership density.
Italy Water Soluble Fertilizer Market Segmentation
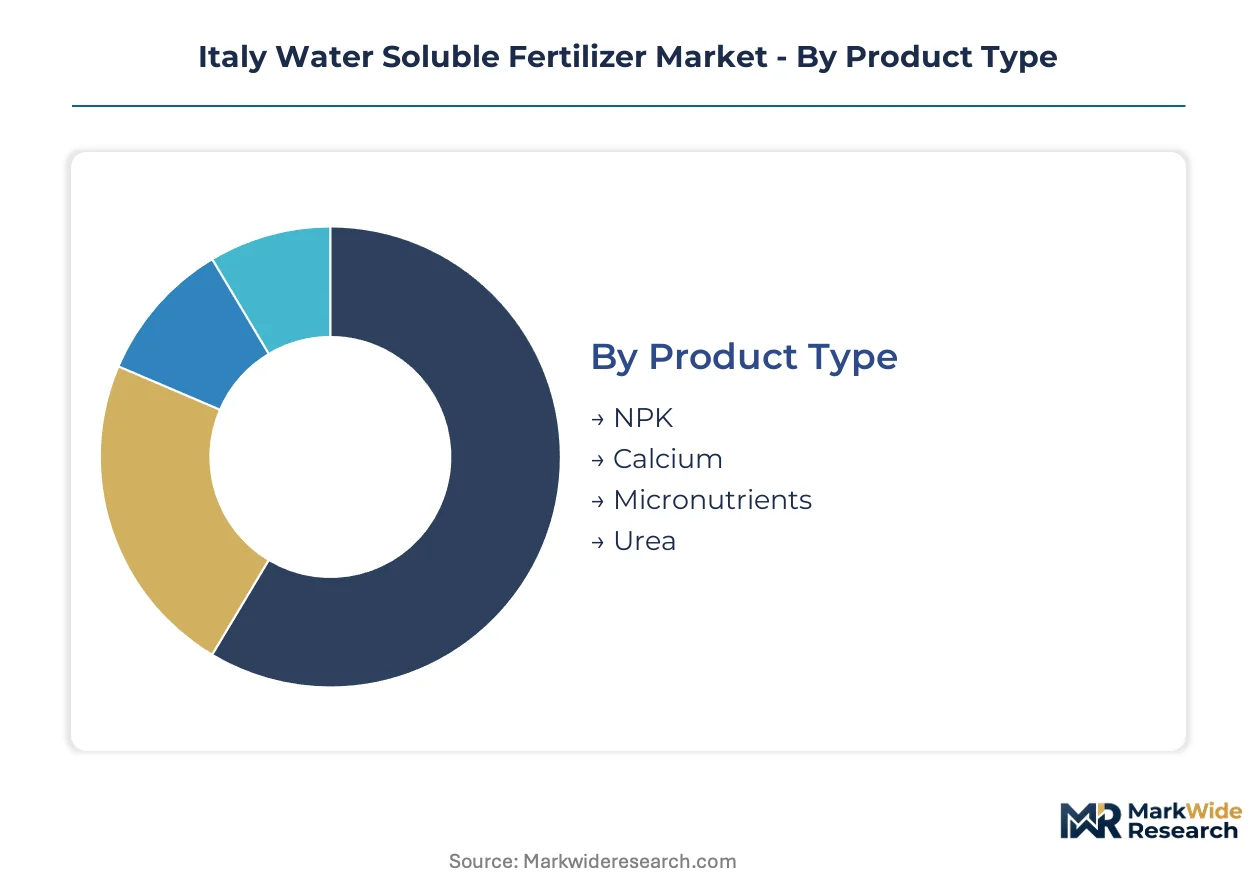
Segmentation in Italy's water soluble fertilizer market reveals how procurement decisions split across technical specifications, application infrastructure, and end-user scale. Understanding these divides exposes where formulation manufacturers must adapt solubility grades, packaging formats, and distribution channels to capture value.
Product Type:
Buyers differentiate by nutrient complexity requirements and crop phenological timing rather than price alone.
- NPK:Multi-nutrient complexes engineered for immediate plant uptake dominate procurement volumes across Italy's vegetable and fruit production systems. Demand concentrates in the Emilia-Romagna horticulture belt where greenhouse operators require precise nitrogen-phosphorus-potassium ratios matched to tomato and pepper growth stages, with formulations achieving near-total solubility specifications exceeding 99.5% to prevent emitter clogging in drip systems.
- Micronutrients:Chelated iron, zinc, manganese, and boron formulations address deficiency correction in high-value protected crops. Demand clusters among precision agriculture adopters in the Po Valley who integrate soil sensor data with targeted micronutrient dosing, though REACH compliance requirements for EDTA and EDDHA raw material sourcing constrain supplier pools and create dependency on concentrated European chemical processors.
- Calcium:Nitrate and chloride forms support cell wall development in fruiting vegetables.
- Urea:High-nitrogen soluble source for rapid vegetative growth phases in field crops.
Volume sits with NPK complexes; growth tilts toward micronutrient bundles as precision agriculture spreads.
End User:
Customer scale and technical sophistication determine service intensity and formulation customization depth.
- Greenhouses:Protected agriculture operators across the Po Valley and southern clusters drive premium formulation demand with requirements for tank-mix compatibility and labor efficiency in large-scale operations. Procurement centralizes into technical committees at cooperative level, compressing distributor margins while elevating manufacturer direct relationships.
- Agricultural Producers:Field crop growers in open-air cereal and industrial crop systems prioritize cost efficiency over precision dosing. Demand spreads across Lombardy and Veneto where subsurface fertigation infrastructure remains less dense, with buyers accepting standard NPK ratios rather than customized blends.
- Nurseries:Ornamental and tree propagation specialists require gentle formulations for young plant establishment.
- Landscape Professionals:Turf and amenity maintenance operators seek convenient application formats for municipal and private contracts.
Revenue concentrates with greenhouse cooperatives; expansion opportunity sits with agricultural producers adopting first-generation precision systems.
Application Mode:
Infrastructure investment cycles and labor cost structures shape delivery method preferences.
- Drip Irrigation:Subsurface fertigation systems spreading through the Po Valley and Puglia greenhouse clusters demand soluble formulations with absolute purity to prevent emitter clogging. Italy's regional agricultural development programs subsidize drip system upgrades, indirectly subsidizing demand for compatible soluble fertilizers and compressing application cycles that force formulation upgrades.
- Foliar:Leaf-applied nutrients address acute deficiency correction and bypass soil fixation issues. Demand persists among high-value vegetable producers in Sicily where soil salinity complicates root uptake, with spray application requiring specialized surfactant packages for cuticle penetration.
- Soil Application:Traditional broadcast or banding methods retain share in field crop systems without precision infrastructure.
- Hydroponics:Soilless cultivation systems in advanced greenhouse facilities require ultra-pure formulations with complete elemental disclosure.
Installation density peaks with drip irrigation; hydroponics climbs fastest as protected agriculture technology upgrades accelerate.
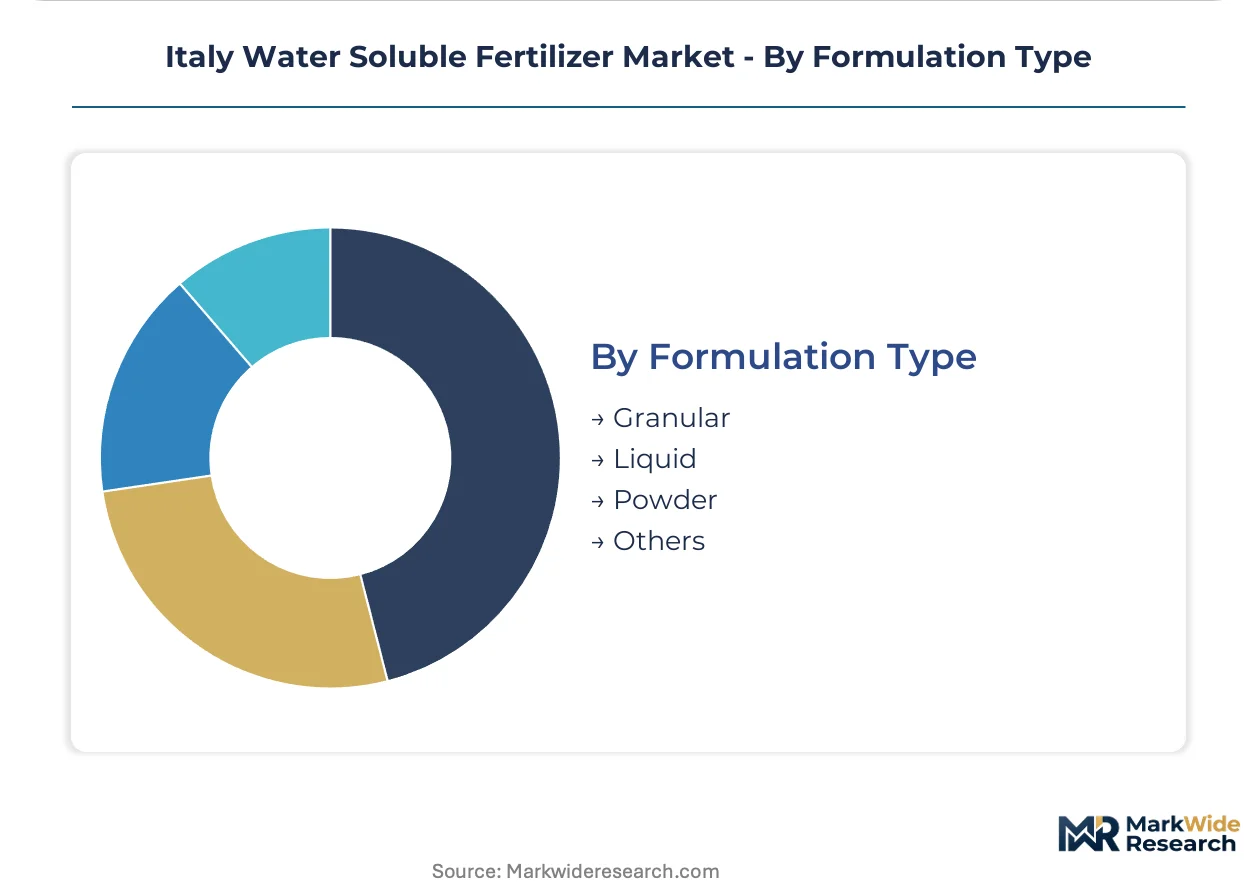
Formulation Type:
Operational workflow preferences and equipment compatibility determine physical format selection.
- Liquid:Ready-to-use solutions command margin premiums where growers prioritize tank-mix compatibility and labor efficiency in large-scale operations. Concentrates reduce handling costs and enable automated dosing systems in Emilia-Romagna greenhouse clusters with advanced fertigation controllers.
- Granular:Controlled-release coating technologies applied to water soluble granules are rewriting application frequency economics for greenhouse operators. Tomato producers in Emilia-Romagna pilot these hybrid formulations to reduce labor cycles from weekly to biweekly fertigation events.
- Powder:Crystalline formulations offer transport cost advantages and extended shelf stability for regional distributors serving fragmented nursery and landscape segments.
- Others:Gel and suspension formats address niche compatibility requirements in specialty crop systems.
Margin capture concentrates with liquid concentrates; granule innovations gain traction fastest among labor-constrained operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy consumes the bulk of water soluble fertilizers produced domestically, with limited export orientation. Northern regions concentrate manufacturing capacity near raw material corridors, while southern areas rely on distribution networks for supply.
Emilia-Romagna
Greenhouse tomato and pepper operations in the Po Valley drive premium formulation demand with precision fertigation requirements. Italy's National Fertilizer Register mandates complete nutrient disclosure for all products entering this zone. Bologna and Modena host technical service hubs where manufacturers deploy field agronomists to cooperative buyers.
Lombardy
Rice cultivation in the Pavia plains and protected horticulture around Milan create dual demand streams for standard and specialty soluble grades. Regional agricultural development programs subsidize drip irrigation retrofits, indirectly boosting compatible fertilizer procurement. Bergamo-based distributors serve as logistics nodes for cross-border flows from Swiss and German suppliers.
Veneto
Ornamental nurseries in the Padua-Vicenza corridor require gentle micronutrient formulations for young plant establishment. CE marking under EU fertilizer regulations governs product entry from neighboring Austria and Slovenia. Verona anchors a blending cluster where regional producers compound base NPK mixes for local greenhouse cooperatives.
Puglia
Expanding greenhouse infrastructure around Foggia and Bari presents underpenetrated terrain for precision fertigation system providers. Italy's irrigation efficiency incentives subsidize drip system installations that precondition soluble fertilizer demand. Taranto-area distributors currently rely on northern supply chains with limited local formulation capacity.
Sicily
Soil salinity challenges in the Catania and Ragusa horticulture belts sustain foliar application demand alongside root-zone fertigation. High-value vegetable producers integrate soil sensor data with targeted nutrient dosing. Palermo serves as the import gateway for North African and Middle Eastern formulation suppliers.
Italy Water Soluble Fertilizer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Italy's water soluble fertilizer landscape. The vendor base stratifies into three tiers: multinational chemical groups with broad agricultural portfolios, European specialty fertilizer houses with regional manufacturing footprints, and Italian domestic blenders serving fragmented nursery and landscape segments. Consolidation pressure concentrates among mid-scale regional producers facing CE marking recertification costs. Competitive moves center on backward integration into chelated micronutrient sourcing and technology licensing for controlled-release coating systems.
Within the specialty formulation tier, ICL and Biolchim SPA exemplify divergent strategic positioning. ICL anchors the potassium-focused segment with protected agriculture expertise. Biolchim SPA occupies the biostimulant-integrated niche for high-value vegetable systems. Valagro represents the marine-extraction technology archetype in premium horticulture positioning. K+S Aktiengesellschaft and EuroChem sit within the diversified chemical group tier, leveraging raw material access across multiple agricultural input categories. TIMAC AGRO and COMPO EXPERT exemplify European specialty houses with established Italian distribution networks.
| Leading Market Players |
|---|
| TIMAC AGRO |
| K+S Aktiengesellschaft |
| ICL |
| Biolchim SPA |
| COMPO EXPERT |
| Akzo Nobel N.V. |
| Valagro |
| Haifa Negev Technologies LTD |
| EuroChem |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between CE-marked specialty formulations and unregistered commodity imports splits procurement economics across Italian distribution channels. Premium horticulture cooperatives in Emilia-Romagna absorb 40-60% price premiums for guaranteed heavy metal compliance under the National Fertilizer Register, while southern greenhouse operators face supply fragmentation as northern blenders prioritize compliant production lines.
Pricing Analysis
Margin tightening in micronutrient bundles reflects REACH-compliant chelate sourcing concentration among German and Dutch chemical processors. Three-tier pricing structure across premium, standard, and economy levels separates biostimulant-integrated lines from base NPK complexes and unregistered imports. Cost-down pressure on standard-grade powders accelerates because southern distributors bypass technical service premiums. Field crop growers in Lombardy exhibit highest price sensitivity; greenhouse cooperatives with centralized procurement committees demonstrate lowest.
Supply Chain Analysis
Formulation chemist scarcity in northern Italian manufacturing clusters constrains batch expansion capacity at mid-scale regional blenders. Production gravity centers on Germany, Israel, and Belgium for chelated micronutrient inputs; domestic compounding concentrates in Emilia-Romagna and Veneto. Raw material sourcing draws from Moroccan phosphate rock, Belarusian potash, and Chinese urea. Single-source vulnerability sits with EDTA/EDDHA chelate supply. Distribution runs through cooperative technical committees that disintermediate traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chelation chemistry expertise functions as the binding capacity constraint propping margin structures for compliant formulation manufacturers. This scarcity dynamic rewards early certification investments and punishes commodity blending strategies.
For Market Incumbents: Cement backward integration into REACH-compliant micronutrient sourcing to insulate margin structures from German chemical processor concentration. Defend position by locking multi-year supply agreements with Po Valley greenhouse cooperatives before southern infrastructure subsidies accelerate competitive entry. Prioritize in-house production of EDDHA chelates over reliance on concentrated European suppliers. For New Entrants and Emerging Players: The 25-35% price-point gap between premium biostimulant-integrated lines and economy NPK powders in Puglia and Sicily offers white-space terrain. Target underpenetrated southern greenhouse clusters where irrigation efficiency incentives precondition soluble fertilizer demand but local formulation capacity remains absent. Enter through marine-extraction technology partnerships that differentiate against mineral-nutrition incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale Italian blenders possessing National Fertilizer Register compliance infrastructure given accelerating CE marking recertification timelines. Long-term viability favors targets with captive technical service teams embedded in cooperative procurement committees. Monitor Italy's regional agricultural development program disbursement rates as inflection signal for southern demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chelated Micronutrients | REACH compliance requirements concentrate European processor power; captive sourcing insulates margin stability. |
| Controlled-Release Coating Technology Licensing | Emilia-Romagna tomato producers pilot biweekly application cycles that compress labor costs. |
| Marine-Extraction Biostimulant Convergence | Algae-derived formulations differentiate positioning in premium pepper and tomato segments. |
| Cooperative Technical Committee Embedding | Centralized procurement decisions at Po Valley greenhouse cooperatives disintermediate regional distributors. |
| Southern Greenhouse Cluster Expansion | Puglia and Sicily infrastructure subsidies precondition precision fertigation demand with limited local supply. |
Research Approach
Italian Ministry of Agriculture regulatory filings, EU fertilizer trade databases, and Po Valley irrigation infrastructure investment records formed the secondary backbone for this analysis. Primary interviews with greenhouse cooperative procurement managers, formulation manufacturer regulatory affairs leads, and chelated micronutrient chemical processors validated secondary findings. Bottom-up triangulation across product-type demand estimates and top-down reconciliation with national fertilizer consumption statistics anchored volume projections.
Historical trendline analysis of protected agriculture expansion rates and fertigation infrastructure density informed growth trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, application mode, end-user scale, and regional irrigation efficiency program uptake. CAGRs derived from slope analysis of correlated input variables including drip system installation rates and National Fertilizer Register compliance timelines. Industry-specific forecast inputs included potassium sulfate price volatility indices and marine-extraction biostimulant patent filing trends.
Inputs from cooperative procurement managers and regional agricultural development program administrators were available through the study window; gaps in real-time southern greenhouse operator adoption rates introduce uncertainty bands around Puglia and Sicily demand projections. Forecasts reflect documented assumptions regarding CE marking recertification pacing and REACH compliance cost pass-through elasticity. Material deviation in Italy's irrigation efficiency incentive disbursement rates or EU fertilizer sustainability criteria implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
Global Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Crop Micronutrients Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
India Fertilizers Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
North America Organic Fertilizers Market