
 India Fertilizers Market | 2026-2036
India Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
India Fertilizers Market Foresight
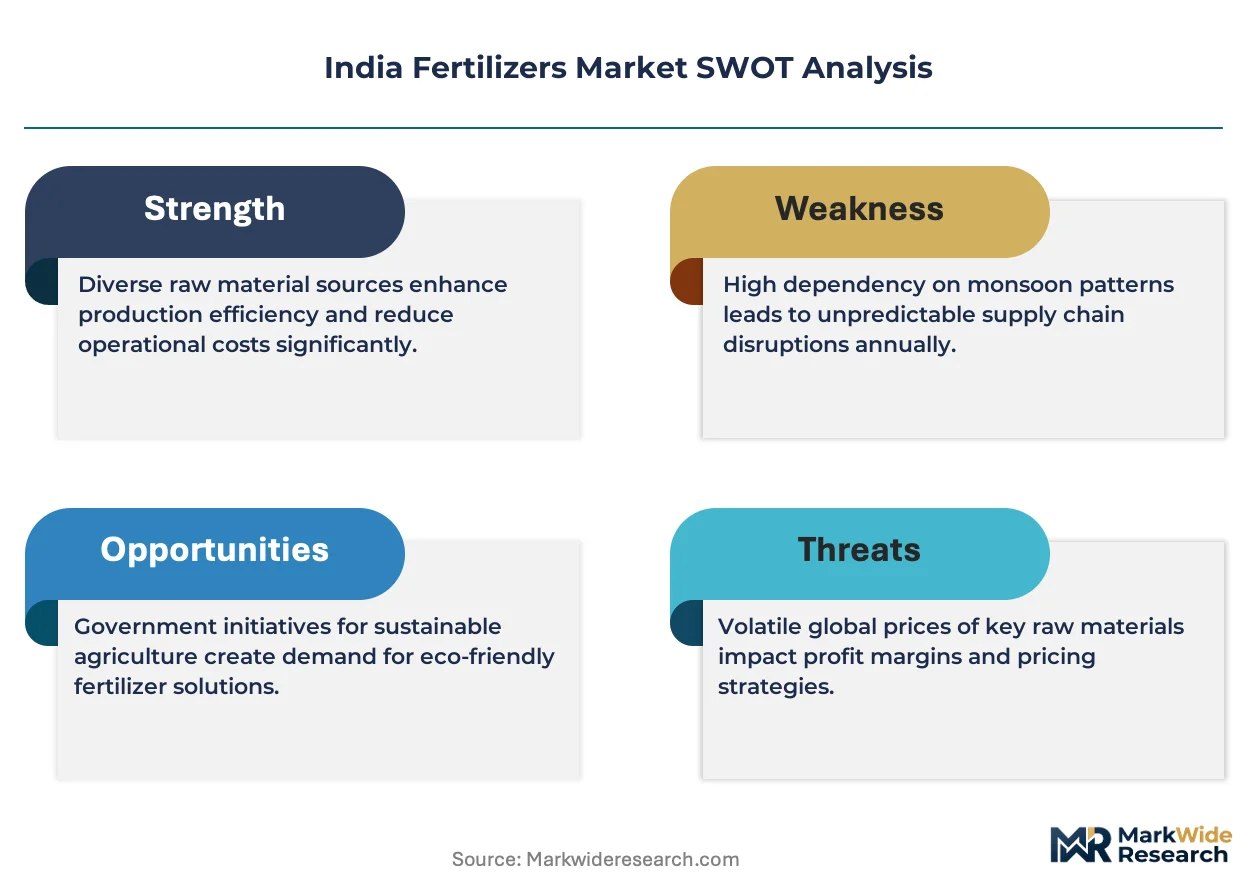
PLI scheme eligibility criteria is pivoting investment toward coated urea and micronutrient fortification, raising the capital threshold for new entrants. Indian Farmers Fertiliser Cooperative Limited leverages its cooperative network to sustain last-mile distribution across 19 states. Coromandel International Limited anchors its position through backward integration into phosphoric acid and sulfuric acid production. National Fertilizers Limited competes on urea manufacturing scale, operating five gas-based plants with combined capacity exceeding 3.2 million tonnes annually.
Fertilizers are chemically synthesized or organically derived nutrient formulations containing nitrogen, phosphorus, and potassium compounds in specified NPK ratios, manufactured through Haber-Bosch ammonia synthesis, phosphate rock acidulation, or potash refining processes, designed to replenish soil macronutrients and correct micronutrient deficiencies in commercial agriculture. Urea dominates product type volumes due to subsidized pricing and established distribution infrastructure, though NPK complexes are gaining share as soil health card data exposes regional nutrient imbalances. Agricultural crops application absorbs the bulk of fertilizer offtake, while organic farming represents a structurally distinct channel with separate certification requirements and premium pricing dynamics.
BIS nutrient content standards and FSSAI residue limits for food crops shape product formulation mandates, while CEA environmental clearances constrain greenfield plant siting near ecologically sensitive zones. The PLI scheme administered by the Department of Fertilizers is redirecting R&D budgets toward nano-urea and bio-stimulant blends, compressing timelines for conventional product registration. Stakeholders must monitor soil health card database expansion and state-level organic farming missions to anticipate subsidy reallocation and procurement priority shifts.
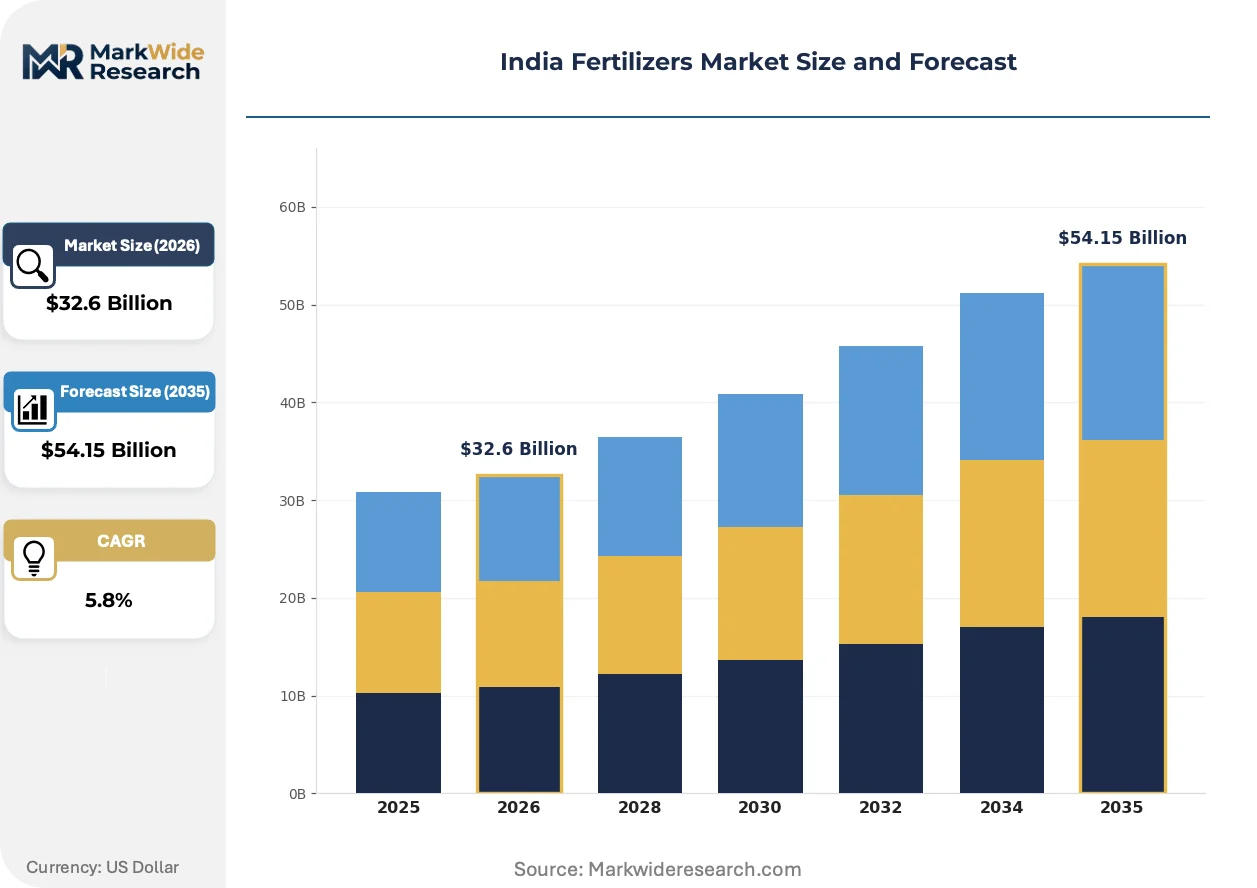
Market Dynamics
The PLI scheme for specialty fertilizers is compressing investment timelines and redirecting R&D budgets toward coated urea and micronutrient fortification, fundamentally altering competitive capital allocation across the sector.
Growth Catalysts
- PLI scheme incentives:The Department of Fertilizers' production-linked incentive framework is accelerating domestic manufacturing of nano-urea and bio-stimulant blends by subsidizing capital expenditure on advanced coating technologies.
- Soil health card penetration:Government-mandated soil testing is exposing regional NPK imbalances and driving demand for complex fertilizers tailored to specific district-level nutrient deficiencies.
- Pulses and oilseeds expansion:Cultivation of leguminous and oilseed crops among smallholder farmers in Maharashtra and Gujarat is increasing micronutrient fertilizer uptake beyond traditional cereal applications.
Market Restraints
- Natural gas price volatility:Urea production depends on imported LNG and domestic gas allocation under the New Pricing Scheme, exposing margins to global energy market swings.
- Phosphate rock import concentration:Domestic phosphoric acid manufacturers rely on Moroccan and Jordanian phosphate rock supplies, creating geopolitical supply risk for DAP and NPK complex producers.
- Subsidy payment delays:The Department of Fertilizers' nutrient-based subsidy disbursement lag compresses working capital cycles for manufacturers and distributors.
Strategic Opportunities
- Uttar Pradesh micro-irrigation corridors:State-level drip and sprinkler irrigation expansion in western districts is creating demand for water-soluble fertilizers and fertigation-compatible formulations.
- Organic farming missions:State-level certification programs in Madhya Pradesh and Karnataka are opening premium channels for bio-fertilizers and organic amendments with separate pricing dynamics.
- Drone-based nano-urea spraying:Convergence of unmanned aerial vehicle technology with liquid nano-urea formulations is enabling foliar application at scale, reducing soil fixation losses.
Industry Challenges
- BIS nutrient content compliance:Bureau of Indian Standards testing protocols for fortified fertilizers extend product registration timelines and require reformulation investments.
- Last-mile distribution fragmentation:Cooperative society networks and private dealer channels operate on thin margins, complicating inventory forecasting for specialty product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Fertilizers Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $54.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, DAP, MOP, NPK Application: Agricultural Crops, Horticultural Plants, Turf Management, Organic Farming Distribution Channel: Retail Outlets, Online Platforms, Direct Sales, Cooperative Societies End User: Farmers, Agricultural Cooperatives, Agri-entrepreneurs, Research Institutions |
| Companies Covered | Indian Farmers Fertiliser Cooperative Limited, National Fertilizers Limited, Coromandel International Limited, Chambal Fertilisers and Chemicals Limited, Rashtriya Chemicals and Fertilizers Limited, Gujarat Narmada Valley Fertilizers & Chemicals Limited, Deepak Fertilisers and Petrochemicals Corporation Limited, ICL Group Ltd, Gujarat State Fertilizers & Chemicals Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Fertilizers Market Shifts & Advancements
Formulation chemistry and application technology are converging to reduce nutrient losses and align fertilizer use with precision agriculture protocols across India's major cropping belts.
Nano-urea liquid formulations developed by Indian Farmers Fertiliser Cooperative Limited and public research institutions are absorbing nitrogen more efficiently through foliar uptake pathways. Progressive farmers in Gujarat and Punjab are adopting drone-mounted spraying systems for these concentrates, bypassing soil fixation losses entirely. The technology is absorbing market share from conventional prilled urea in high-value horticulture segments where labor costs justify mechanized application.
BIS nutrient content standards and FSSAI residue limits for food crops are tightening formulation mandates for domestic manufacturers. The regulatory pressure is forcing reformulation of NPK complexes to exclude heavy metal contaminants and align micronutrient claims with certified laboratory testing. Fertilizer producers in Maharashtra and Andhra Pradesh are responding by investing in captive quality control laboratories and third-party certification partnerships.
Soil health card data is restructuring procurement patterns among district-level fertilizer cooperatives. Aggregated nutrient deficiency maps are enabling targeted subsidy allocation and customized product bundling for specific block-level requirements. This data-driven approach is most visible in Haryana and western Uttar Pradesh, where rice-wheat rotation has depleted specific micronutrient profiles and cooperative societies are pre-positioning fortified blends before planting seasons.
India Fertilizers Market Segmentation
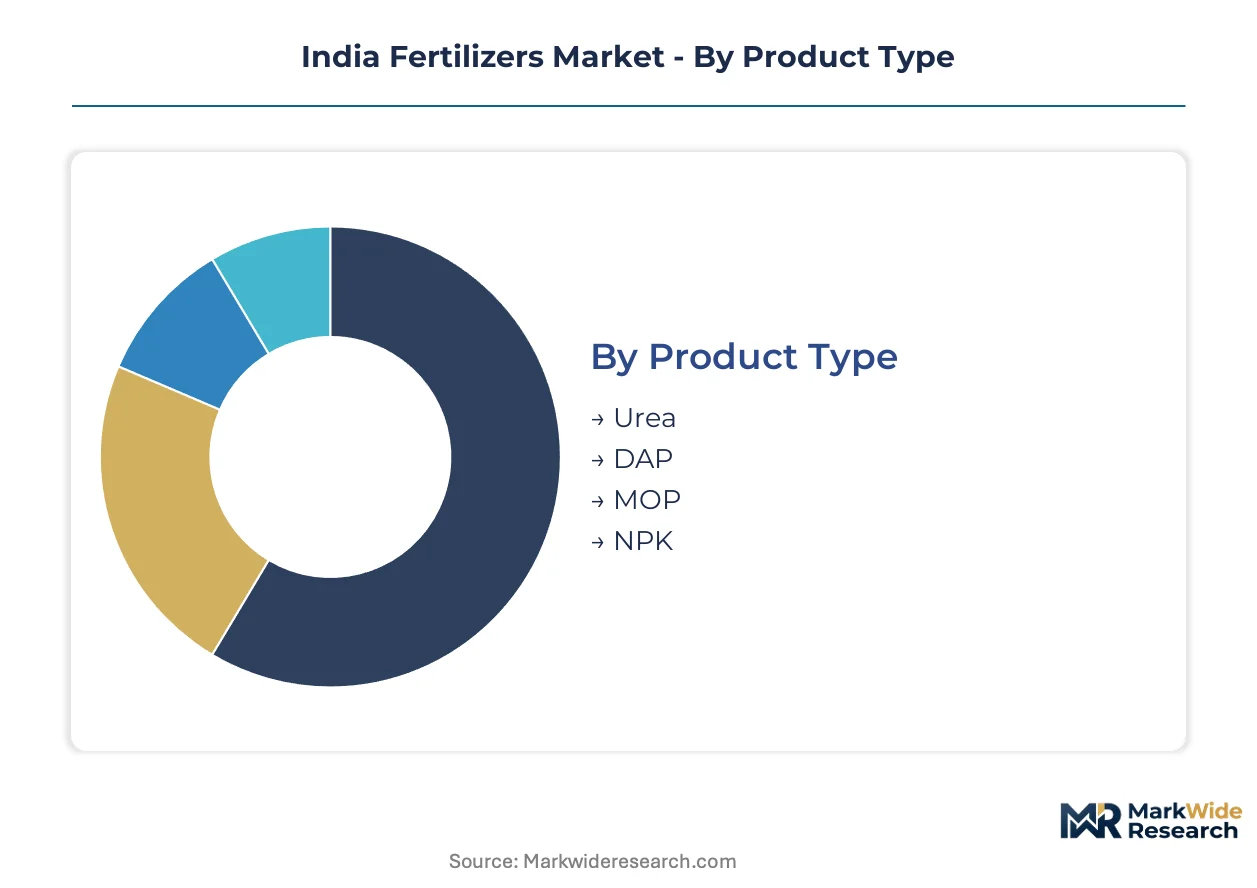
India's fertilizer market segments around subsidy mechanics, crop-specific nutrient requirements, and the cooperative infrastructure that dominates last-mile delivery. Each category reveals distinct procurement patterns between price-controlled commodities and premium specialty formulations.
Product Type:
Standardization dominates urea through centralized pricing, while specialty complexes offer formulation flexibility for soil-specific deficiencies.
- Urea:Nitrogen-dense prilled or granular formulations synthesized via Haber-Bosch ammonia process, commanding subsidized pricing under the New Pricing Scheme. Procurement concentrates in Punjab and Haryana rice-wheat belts where nitrogen deficiency drives the highest per-hectare application rates. Gas allocation under the New Pricing Scheme caps production margins and limits import competition.
- NPK:Balanced nitrogen-phosphorus-potassium complexes tailored to soil health card data revealing regional micronutrient gaps. Maharashtra and Gujarat horticulture zones are absorbing customized NPK blends as drip irrigation expansion enables precision fertigation. The PLI scheme is accelerating domestic coating technology investment for slow-release variants.
- DAP:High-phosphorus compound manufactured through phosphate rock acidulation, dependent on Moroccan and Jordanian ore imports.
- MOP:Potassium chloride refined from Canadian and Belarusian potash deposits, applied primarily in sugarcane and plantation crops.
Most installed capacity flows through urea. Expansion is steepest in NPK.
Application:
Volume concentrates in broad-acre cereals, while value migrates toward high-margin horticulture and certified organic channels.
- Agricultural Crops:Cereals, pulses, and oilseeds absorb bulk fertilizer offtake through the public distribution system. Uttar Pradesh and Madhya Pradesh wheat belts generate the highest seasonal procurement volumes under nutrient-based subsidy allocation.
- Horticultural Plants:Vegetable and fruit cultivation in Maharashtra, Karnataka, and Andhra Pradesh demands water-soluble and micronutrient-fortified formulations. Precision fertigation systems in Nashik and Bengaluru peri-urban belts are displacing conventional broadcasting methods.
- Turf Management:Golf courses and commercial landscaping in Delhi NCR and Mumbai metropolitan zones procure slow-release nitrogen for aesthetic maintenance.
- Organic Farming:Certified operations in Madhya Pradesh and Sikkim operate under separate FSSAI residue limits and premium pricing protocols.
Cereal applications capture volume leadership. Horticulture is climbing the fastest.
Distribution Channel:
Cooperative societies anchor rural penetration, while digital platforms and direct sales target commercial farming enterprises.
- Cooperative Societies:Indian Farmers Fertiliser Cooperative Limited and state-level federations operate 50,000-plus rural touchpoints across 19 states. Last-mile inventory pre-positioning ahead of monsoon and rabi planting seasons determines competitive access in Bihar and eastern Uttar Pradesh.
- Retail Outlets:Licensed dealer networks in Gujarat and Rajasthan trade on thin margins under Department of Fertilizers price monitoring.
- Direct Sales:Bulk supply contracts with plantation estates and contract farming aggregators in Tamil Nadu and Kerala tea-coffee belts.
- Online Platforms:Agri-input marketplaces targeting progressive farmers in Punjab and Haryana with drone-compatible nano-urea concentrates.
Cooperative infrastructure handles the deepest rural penetration. Online channels are gaining share fastest among commercial farms.
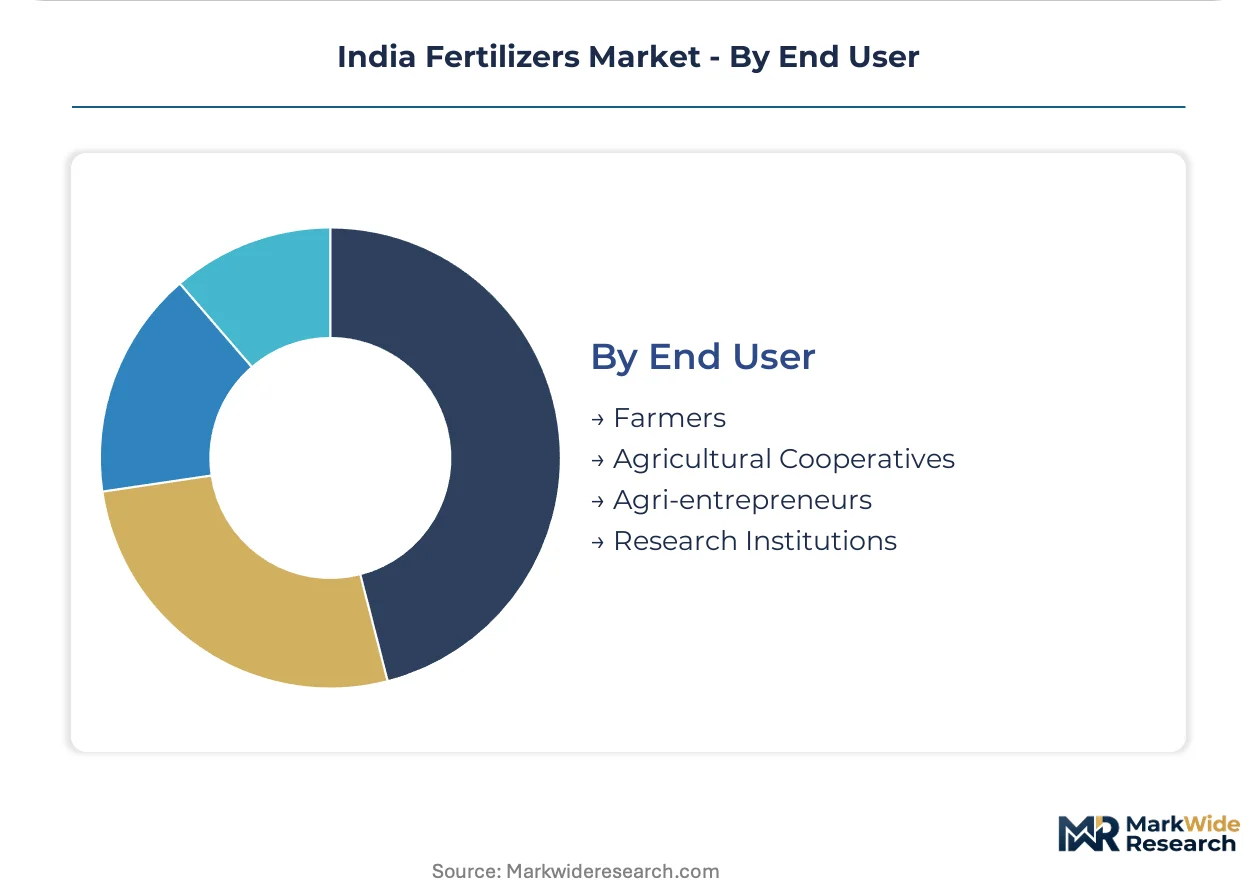
End User:
Smallholder farmers drive volume through subsidized entitlement, while agri-entrepreneurs and cooperatives consolidate procurement for precision application.
- Farmers:146 million smallholders across India access fertilizers through biometric-authenticated point-of-sale systems under the Direct Benefit Transfer mechanism. Soil health card holders in Haryana and western Uttar Pradesh are shifting from straight urea toward customized complexes based on district-level nutrient deficiency maps.
- Agricultural Cooperatives:Primary societies aggregate demand for fortified blends and negotiate bulk procurement terms with manufacturers.
- Agri-entrepreneurs:Drone service providers and precision farming operators in Gujarat are contracting nano-urea spraying services to horticulture clusters.
- Research Institutions:Indian Council of Agricultural Research stations trial bio-stimulant and nano-formulation efficacy for regulatory registration support.
Individual farmers absorb the dominant volume share. Agri-entrepreneurs are expanding most quickly as service-based input delivery models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural workforce concentration in the Indo-Gangetic belt and western irrigation corridors anchors fertilizer procurement geography across India's major cropping zones.
Maharashtra
Sugarcane and horticulture expansion in Nashik and Pune districts drives water-soluble fertilizer demand through drip irrigation networks. The state's micro-irrigation mission subsidizes fertigation infrastructure for precision nutrient delivery. Jalna and Aurangabad industrial clusters host blending facilities for customized NPK complexes targeting vineyard and vegetable cultivation.
Gujarat
Cotton and groundnut cultivation in Saurashtra and North Gujarat sustains high-volume urea offtake through cooperative distribution channels. The Gujarat State Fertilizers & Chemicals Limited complex at Vadodara anchors domestic phosphoric acid production for DAP manufacturing. Kutch and Jamnagar districts are absorbing nano-urea formulations through drone service provider networks in horticulture belts.
Uttar Pradesh
Wheat-rice rotation across western districts generates India's highest per-hectare fertilizer consumption intensity. The state agriculture department's soil health card database exposes zinc and sulfur deficiencies, redirecting procurement toward fortified complexes. Kanpur and Gorakhpur fertilizer depots pre-position inventory ahead of rabi planting seasons under the Direct Benefit Transfer mechanism.
Haryana
Intensive paddy cultivation in Karnal and Kurukshetra districts drives nitrogen-heavy application patterns despite groundwater depletion warnings. The Haryana government mandates neem-coated urea to reduce leaching losses in paddy fields. Panipat and Hisar serve as redistribution hubs for Punjab and western Uttar Pradesh cooperative networks.
Andhra Pradesh
Chilli and tobacco cultivation in Guntur and Prakasam districts demands micronutrient-fortified formulations for export-quality crop production. The state's zero-budget natural farming mission creates parallel demand channels for bio-fertilizers and organic amendments. Vijayawada and Visakhapatnam port infrastructure handles imported MOP for sugarcane and plantation crop applications.
India Fertilizers Market Competitive Landscape
The competitive structure tilts toward public sector undertakings and cooperative federations with privileged access to subsidized feedstock and established last-mile networks. Three archetypes dominate: gas-based urea manufacturers operating under New Pricing Scheme allocations, integrated phosphate compound producers with backward linkages to sulfuric acid capacity, and cooperative societies leveraging member equity for bulk procurement leverage. Capacity expansion and strategic partnerships with drone service providers constitute the primary competitive vectors reshaping market access.
Within the cooperative archetype, Indian Farmers Fertiliser Cooperative Limited exemplifies member-owned distribution scale, while National Fertilizers Limited represents public sector manufacturing concentration. Coromandel International Limited occupies a position among integrated phosphate compound specialists with captive acid production infrastructure. These three entities collectively illustrate the sector's segmentation between subsidy-dependent commodity production and value-added specialty formulation.
| Leading Market Players |
|---|
| Indian Farmers Fertiliser Cooperative Limited |
| National Fertilizers Limited |
| Coromandel International Limited |
| Chambal Fertilisers and Chemicals Limited |
| Rashtriya Chemicals and Fertilizers Limited |
| Gujarat Narmada Valley Fertilizers & Chemicals Limited |
| Deepak Fertilisers and Petrochemicals Corporation Limited |
| ICL Group Ltd |
| Gujarat State Fertilizers & Chemicals Limited |
| Others |
Supply & Pricing Matrix
Henry Hub natural gas futures cascade through urea production economics, compressing margins at gas-based plants under the New Pricing Scheme and widening spreads between subsidized domestic supply and imported spot cargoes.
Pricing Analysis
Bundled nutrient-based subsidy disbursements from the Department of Fertilizers coexist with unbundled specialty fertilizer premiums for nano-urea and micronutrient formulations. Three-tier pricing structure across premium, standard, and economy levels separates drone-compatible liquid concentrates from neem-coated urea and straight prilled grades. Price differentiation hinges on coating technology and fertigation compatibility. Cost compression in standard urea is intensifying because of gas allocation formula rigidities. Smallholder farmers accessing biometric-authenticated POS terminals exhibit highest price sensitivity; plantation estates and horticulture clusters absorb premium tiers with least friction.
Supply Chain Analysis
Phosphate rock supply rests on Moroccan and Jordanian mining concessions, with sulfuric acid production clustering around Gujarat and Andhra Pradesh industrial corridors. Ammonia synthesis draws from domestic gas fields and imported LNG regasification terminals at Dahej and Hazira. Potassium chloride sources from Canadian and Belarusian deposits through Visakhapatnam and Mundra port handling. Single-source vulnerability concentrates in phosphoric acid feedstock, where OCP Group and Jordan Phosphate Mines Company control contracted offtake. Distribution runs through Indian Farmers Fertiliser Cooperative Limited's 50,000-plus rural touchpoints, supplemented by state-level federations in Maharashtra and Uttar Pradesh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between gas-abundant Middle Eastern ammonia exporters and India's subsidized domestic manufacturing base, with the New Pricing Scheme creating artificial cost floors that protect incumbent margins.
For Market Incumbents: Extend backward integration into sulfuric acid and phosphoric acid production to offset Moroccan phosphate rock import concentration. Deepen captive quality control laboratory networks ahead of BIS nutrient content standard tightening. Anchor capacity utilization through long-term gas allocation renewals under the New Pricing Scheme.
For New Entrants and Emerging Players: Drone service providers offer the most penetrable channel partner type for nano-urea liquid concentrate distribution, bypassing cooperative society inventory pre-positioning requirements. Target western Uttar Pradesh micro-irrigation corridors where drip expansion outpaces fortified fertilizer supply. Pursue toll-manufacturing arrangements with existing gas-based plants to circumvent greenfield siting restrictions.
For Investors and Strategic Acquirers: Consolidation pressure builds where working capital cycles stretch under nutrient-based subsidy disbursement lags. Five-to-ten-year viability favors integrated phosphate compound specialists with captive acid infrastructure over pure-play urea manufacturers exposed to gas price volatility. Watch soil health card database expansion rates as inflection indicator for customized NPK blend demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphoric Acid | Captive sulfuric acid production at Gujarat industrial clusters reduces Moroccan rock import dependency. |
| Nano-Urea Formulation Scale-Up | Indian Farmers Fertiliser Cooperative Limited liquid concentrate capacity absorbs PLI scheme incentives. |
| Drone Service Provider Partnerships | Foliar application networks in Kutch and Nashik bypass soil fixation losses for horticulture clusters. |
| Soil Health Card Data Monetization | Block-level nutrient deficiency maps enable customized NPK blend pre-positioning ahead of rabi planting. |
| Micro-Irrigation Corridor Expansion | Western Uttar Pradesh drip infrastructure subsidies create water-soluble fertilizer demand pockets. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Uttar Pradesh, and Haryana, with primary inputs from each state-level agricultural department and cooperative federation. Research combined interviews with plant managers at gas-based urea facilities, procurement leads at state fertilizer corporations, distribution channel partners in cooperative societies, and technical R&D directors at phosphoric acid complexes. Secondary validation drew from Department of Fertilizers subsidy disbursement records, BIS nutrient content certification databases, SEC filings of listed manufacturers, and customs import data for phosphate rock and potash. Bottom-up district-level consumption estimates triangulated against top-down national production capacity assessments.
Rate-of-change decomposition framed volume trajectories across product type, application, and distribution channel dimensions throughout the forecast period. Segmentation modeling incorporated crop-specific nutrient requirement intensity, irrigation infrastructure penetration, and cooperative society network density as industry-specific forecast inputs. CAGRs derived from spline-interpolated annual production and offtake data, cross-referenced against state-level procurement seasonality patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural gas price volatility, Moroccan phosphate rock export policy shifts, and PLI scheme extension decisions. Forecasts reflect documented assumptions on subsidy continuity and gas allocation formula stability. A small set of named triggers warrants ongoing watch: soil health card database coverage expansion, drone spraying regulatory clarity from DGFT, and neem-coated urea mandate geographic extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
Global NPK Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market