
 Thailand Fertilizers Market | 2026-2036
Thailand Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Fertilizers Market Analytics
Horticulture is pivoting toward higher-value fruit and vegetable cultivation, altering nutrient formulation requirements across Thailand's agricultural belt. Yara International leverages its precision agriculture portfolio to serve this transition, while Thai Central Chemical Public Company Limited anchors domestic production capacity for conventional NPK blends. Saksiam Group competes through extensive distribution networks reaching provincial farming cooperatives.
Thailand fertilizers encompass chemically synthesized or organically derived nutrient formulations containing nitrogen, phosphorus, and potassium compounds, typically manufactured through ammonia synthesis, phosphate rock acidulation, or potash extraction processes, designed to replenish soil macronutrients and boost crop yield per hectare. Urea maintains volume leadership due to its cost-efficiency in rice paddies, though NPK complexes capture expanding margin pools as farmers pursue balanced nutrition strategies. The horticulture application segment demonstrates accelerated uptake of water-soluble and specialty grades, while potassium chloride faces substitution pressure from sulfate-based alternatives in chloride-sensitive cropping systems.
Thailand's Ministry of Agriculture and Cooperatives, alongside the Department of Agriculture, enforces fertilizer quality standards and registration protocols that filter substandard imports from neighboring markets. The country's national agricultural policy framework ties input subsidies to certified product specifications, compelling distributors and cooperatives to source from registered suppliers. Stakeholders must monitor evolving soil health mandates and potential carbon-footprint labeling requirements that could reshape procurement criteria across the Central Plains and northeastern farming zones.
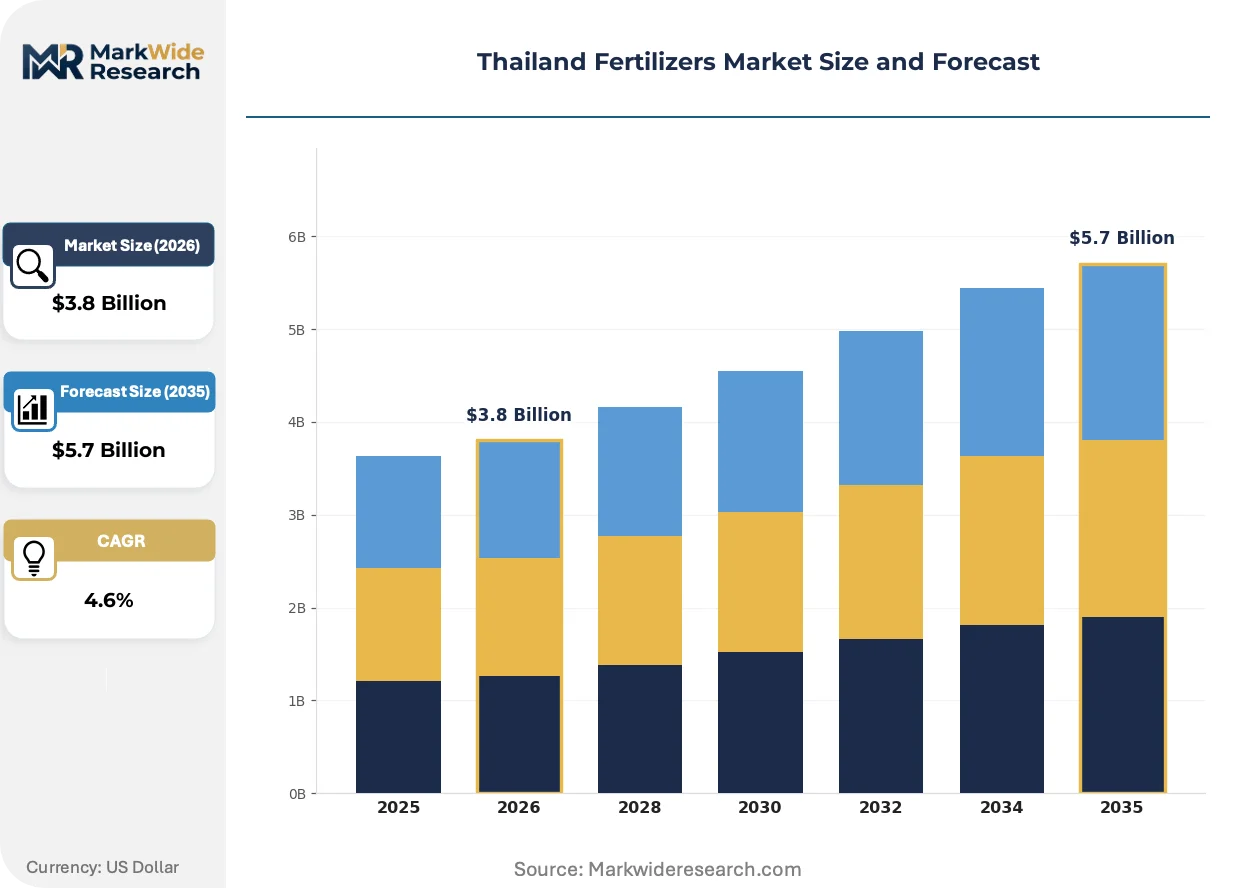
Market Dynamics
Thailand's fertilizer sector confronts a structural pivot from volume-driven rice subsidies to precision nutrition for horticulture, forcing incumbents to reconfigure product portfolios and distribution economics around smaller, higher-margin orders.
Growth Catalysts
- Soil Health Mandates:The Department of Agriculture's registration protocols now require micronutrient disclosure, pushing cooperatives toward certified NPK complexes and away from unlabeled imports.
- Horticulture Expansion:Durian and mango cultivation in the Eastern Economic Corridor demands sulfate-based potassium formulations, opening premium formulation opportunities.
- Subsidized Input Access:Thailand's national agricultural policy framework channels subsidized urea and compound fertilizers through registered provincial cooperatives, locking in baseline demand.
Market Restraints
- Import Dependency:Potassium chloride supply concentrates in Maha Sarakham and Udon Thani transshipment corridors, exposing buyers to Thai baht volatility against Belarusian and Russian contract currencies.
- Technical Limitations:Chloride-sensitive cropping systems in the Central Plains face yield suppression from standard KCl applications, restricting product substitution flexibility.
- Regulatory Friction:Fertilizer quality standards enforcement at Laem Chabang port creates 15-30 day clearance bottlenecks for unregistered Southeast Asian suppliers.
Strategic Opportunities
- Northeastern Underpenetration:Isan farming zones exhibit 40% lower NPK application rates than Central Plains benchmarks, presenting volume expansion potential for registered distributors.
- Water-Soluble Convergence:Drip irrigation adoption in greenhouse vegetable operations converges with soluble fertilizer technology, enabling foliar application services.
- Carbon Labeling Preparation:Anticipated carbon-footprint procurement criteria from Thailand's Board of Investment creates first-mover advantage for ammonia producers with emission-verified supply chains.
Industry Challenges
- Soil Science Talent Scarcity:Agronomists capable of interpreting site-specific nutrient prescriptions remain concentrated in Bangkok-based research stations, limiting provincial extension service quality.
- Legacy System Integration:Cooperative inventory management platforms require manual data entry for specialty grade SKUs, complicating traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Fertilizers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, NPK, Ammonium Sulfate, Potassium Chloride Application: Crops, Horticulture, Turf, Landscaping End User: Farmers, Agricultural Cooperatives, Retailers, Distributors Distribution Channel: Online, Offline, Wholesalers, Direct Sales |
| Companies Covered | Saksiam Group, NFC Public Company Limited, Yara International, Baba Thai Group, Thai Peace Pulp (Thailand) Co., Ltd, Thai Central Chemical Public Company Limited, Chia Tai Group, ICL Fertilizers (Ranthai Agro Co. Ltd), Haifa Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Fertilizers Market Evolving Landscape
Digital soil mapping and variable-rate application technologies are compressing the traditional one-formulation-fits-all model, while regulatory pressure on environmental runoff accelerates formulation specificity requirements.
Variable-rate spreaders equipped with GPS-guided nozzle control are automating nutrient placement in large-scale rice operations. Chonburi and Suphan Buri contract farming collectives pilot these systems to reduce over-application penalties. The technology is automating the shift from blanket broadcasting to zone-specific dosing, compressing per-hectare urea volumes by 15-20% without yield sacrifice.
Thailand's Ministry of Agriculture and Cooperatives tightened fertilizer registration protocols in 2023, requiring heavy metal content testing for all imported organic amendments. This regulatory friction filters out uncharacterized compost products from Cambodian and Lao PDR cross-border trade. Domestic blenders with in-house laboratory certification capacity capture cooperative procurement contracts previously lost to price-undercutting informal suppliers.
Provincial farming cooperatives now consolidate input purchasing through centralized digital tender platforms, displacing individual farm-level negotiations with volume-based annual contracts. This procurement compression squeezes distributor margins while favoring blenders with certified warehousing networks reaching Nakhon Ratchasima and Khon Kaen. The behavioral shift concentrates buyer power in the Central Plains before radiating toward secondary rice belts.
Thailand Fertilizers Market Segmentation
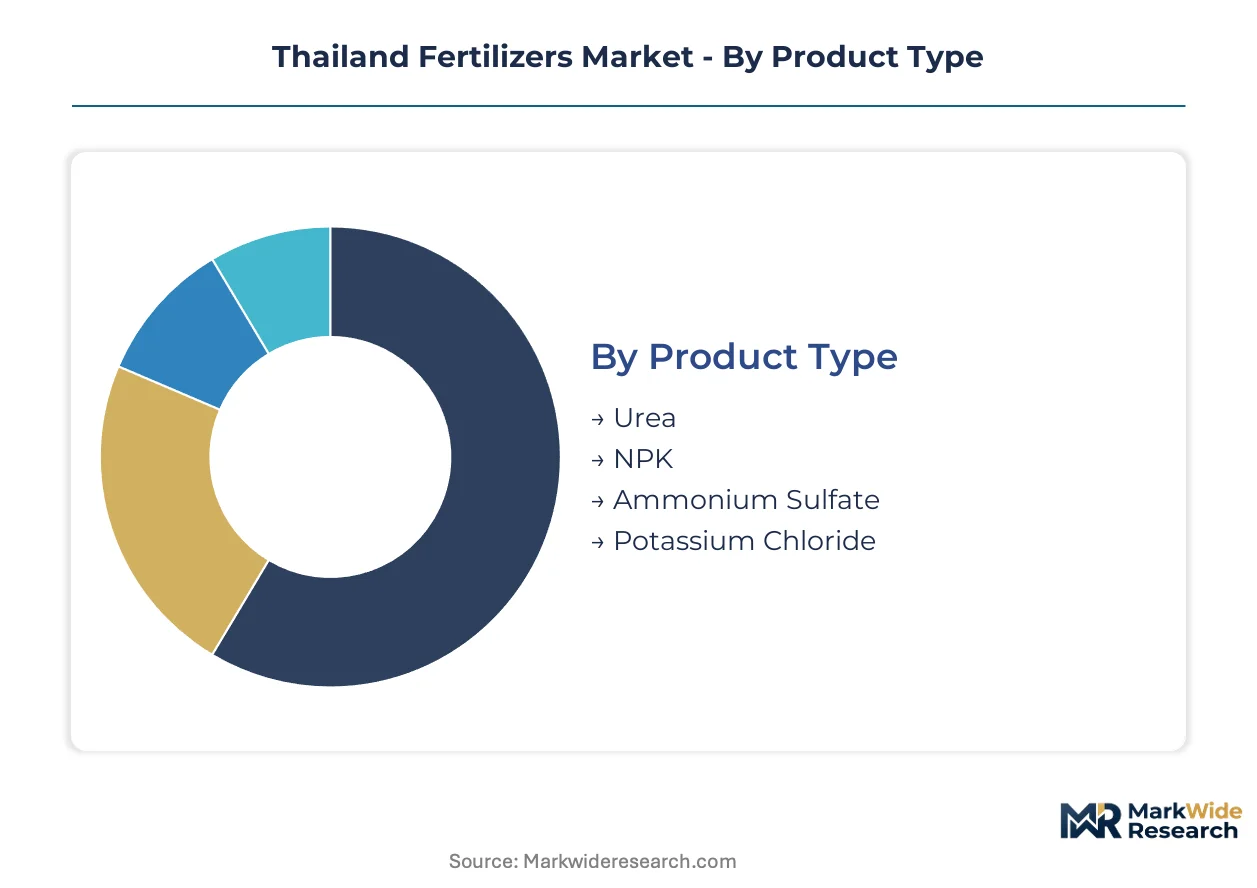
Thailand's fertilizer segmentation reveals how regulatory certification, subsidy eligibility, and distribution infrastructure fragment procurement patterns across the agricultural value chain. Understanding these divides exposes where margin pools concentrate versus where volume flows through subsidized channels.
Product Type:
Thailand's Department of Agriculture mandates distinct registration protocols for each chemical class, with nitrogen-heavy formulations facing lighter micronutrient disclosure burdens than compound blends.
- Urea:This nitrogen-dense formulation delivers 46% N content through ammonia synthesis, making it the subsidized backbone of rice cultivation across the Central Plains. Demand concentrates in provincial cooperative procurement tenders where price sensitivity overrides formulation sophistication.
- NPK:Balanced nutrient complexes require full heavy metal testing and micronutrient labeling under tightened 2023 protocols, pushing domestic blenders with laboratory certification toward cooperative contracts. Eastern Economic Corridor durian operations drive sulfate-based NPK uptake.
- Ammonium Sulfate:Dual nitrogen-sulfur source suits chloride-sensitive cropping systems in the Central Plains, offering yield protection where standard potassium applications suppress output.
- Potassium Chloride:MOP-grade material flows through Maha Sarakham and Udon Thani transshipment corridors, exposing buyers to currency volatility against Belarusian and Russian contract denominations.
Urea sits at the top of the volume ranking, with NPK climbing the fastest as horticulture expansion demands certified, balanced nutrition.
Application:
Margin structure varies sharply by cultivation intensity, with permanent crop systems commanding formulation premiums over annual rice cycles.
- Crops:Rice paddies dominate tonnage consumption through subsidized urea channels, though declining per-hectare application rates under precision agriculture pilots compress absolute volumes.
- Horticulture:Durian and mango operations in Chonburi and Rayong provinces drive water-soluble and sulfate-based specialty demand, with drip irrigation convergence enabling foliar application services at premium pricing.
- Turf:Golf course and sports field maintenance in Bangkok periphery districts absorbs slow-release formulations, though this segment remains marginal to national volume.
- Landscaping:Urban greening projects and commercial estate development generate sporadic demand for blended topsoil amendments, typically sourced through retail rather than cooperative channels.
Crops anchor volume throughput, with horticulture gaining share fastest as permanent crop acreage expands.
End User:
Procurement scale and subsidy access credentials determine which buyer categories capture price advantages versus paying retail premiums.
- Farmers:Individual smallholders below cooperative membership thresholds purchase through registered retailers at unsubsidized rates, though many access indirect subsidy benefits via village-level pooling arrangements.
- Agricultural Cooperatives:Centralized digital tender platforms now consolidate provincial purchasing power, squeezing distributor margins while favoring blenders with certified warehousing networks reaching Nakhon Ratchasima and Khon Kaen.
- Retailers:Provincial shop networks serve non-cooperative farmers with bagged urea and basic NPK blends, facing margin compression as cooperative procurement concentrates.
- Distributors:Licensed entities with Department of Agriculture registration handle import clearance at Laem Chabang, absorbing 15-30 day bottlenecks for unregistered Southeast Asian suppliers.
Agricultural cooperatives command the largest aggregate procurement volume, with distributors expanding fastest as import registration requirements tighten.
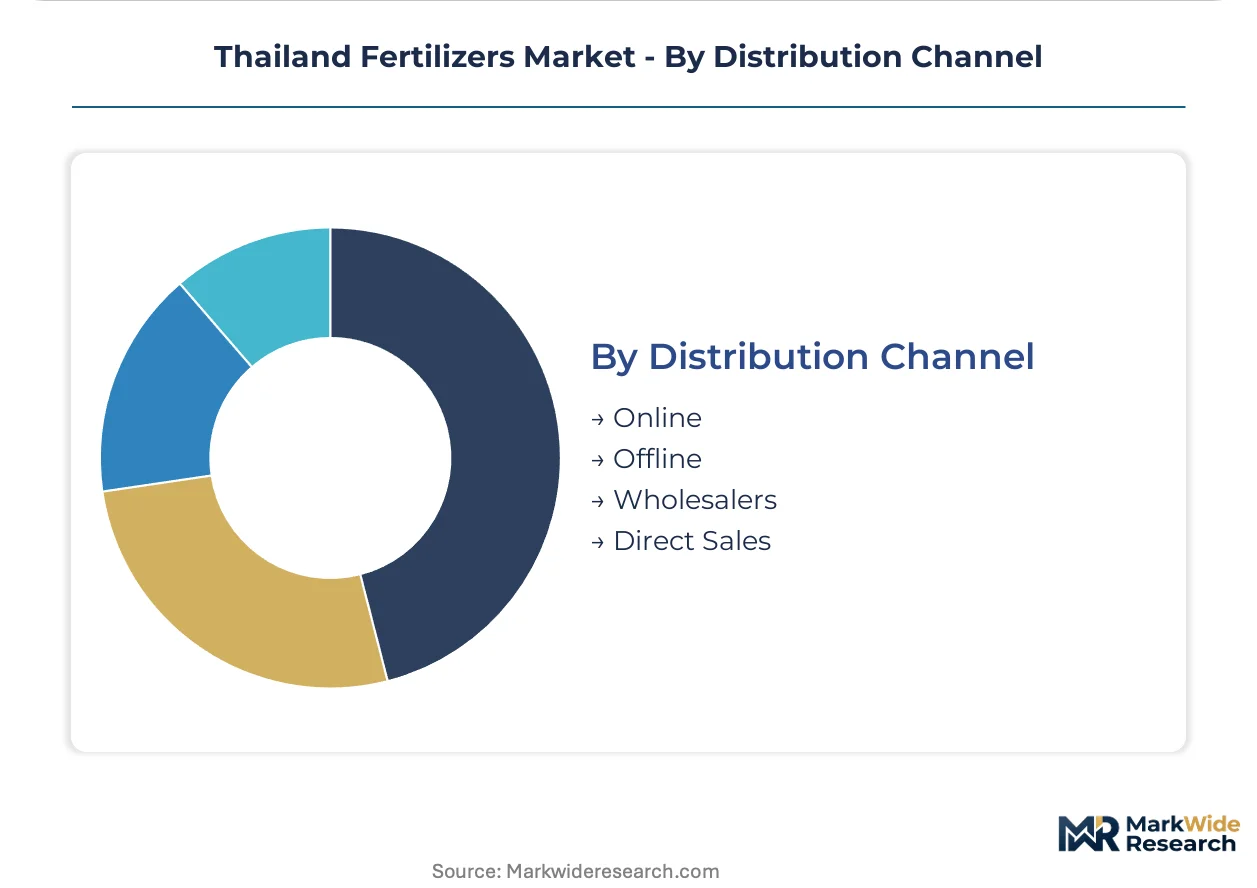
Distribution Channel:
Physical infrastructure requirements and traceability compliance create divergent cost structures across channel types.
- Online:Emerging platforms serve greenhouse operators and estate managers with specialty water-soluble grades, though cooperative subsidy eligibility requires offline verification.
- Offline:Cooperative collection points and provincial retail networks handle the subsidized volume core, with manual inventory systems complicating specialty grade traceability.
- Wholesalers:Volume aggregators with certified warehousing capacity capture cooperative tender business, displacing informal cross-border suppliers filtered by heavy metal testing requirements.
- Direct Sales:Blender-to-farm arrangements for large contract farming collectives in Suphan Buri and Chonburi bypass distributor margins, typically paired with precision application equipment leases.
Offline channels dominate subsidized throughput, with direct sales expanding most quickly among commercial horticulture operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fertilizer trade flows across Southeast Asia as Thailand's tightened 2023 registration protocols divert substandard imports toward neighboring markets with lighter compliance burdens. Production capacity is migrating toward jurisdictions where cost-of-compliance gaps preserve margin structures for commodity-grade blending operations.
Central Plains
Rice paddies surrounding Bangkok and Suphan Buri consume subsidized urea volumes that anchor national demand benchmarks. The Department of Agriculture's cooperative procurement channels concentrate purchasing power through provincial collection points. Chai Nat and Nakhon Sawan blending facilities serve this corridor with registered NPK complexes that satisfy micronutrient disclosure mandates.
Eastern Economic Corridor
Durian and mango cultivation in Chonburi and Rayong provinces drives sulfate-based potassium formulation demand incompatible with standard MOP applications. The Eastern Economic Corridor Office coordinates infrastructure investment that supports precision agriculture equipment deployment. Horticulture operations here command premium pricing for water-soluble grades through drip-irrigation convergence.
Northeastern Region
Isan farming zones exhibit 40% lower NPK application rates than Central Plains benchmarks, presenting volume expansion potential for registered distributors penetrating Nakhon Ratchasima and Khon Kaen. The Ministry of Agriculture's soil health initiatives target this region for demonstration farm programs. Udon Thani transshipment corridors handle potassium chloride flows exposed to currency volatility against Eastern European contract denominations.
Northern Highlands
Chiang Mai and Chiang Rai high-value coffee and temperate vegetable operations require chloride-sensitive nutrient management absent from rice-dominated formulations. Provincial cooperatives here source through registered distributors with certified warehousing networks reaching mountainous terrain. Cold-chain logistics constraints limit just-in-time delivery models that function in lowland corridors.
Southern Peninsula
Rubber plantation renewal cycles in Surat Thani and Nakhon Si Thammarat generate periodic demand spikes for balanced NPK applications. The Southern Border Provinces Administrative Center coordinates agricultural extension services across fragmented terrain. Coastal logistics infrastructure at Songkhla supports import clearance for specialty grades serving peri-urban horticulture near Hat Yai.
Thailand Fertilizers Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents reconfigure around horticulture's shift from volume-driven rice subsidies. The vendor base clusters into three tiers: multinational precision-agriculture specialists, domestic blenders with laboratory certification capacity, and regional distributors with cooperative network penetration. Strategic archetypes include registration-advantaged domestic producers, technology-licensed international formulators, and warehouse-network-anchored logistics players. M&A activity concentrates on acquiring certified laboratory capacity, while backward integration into ammonia synthesis secures margin protection against raw material volatility.
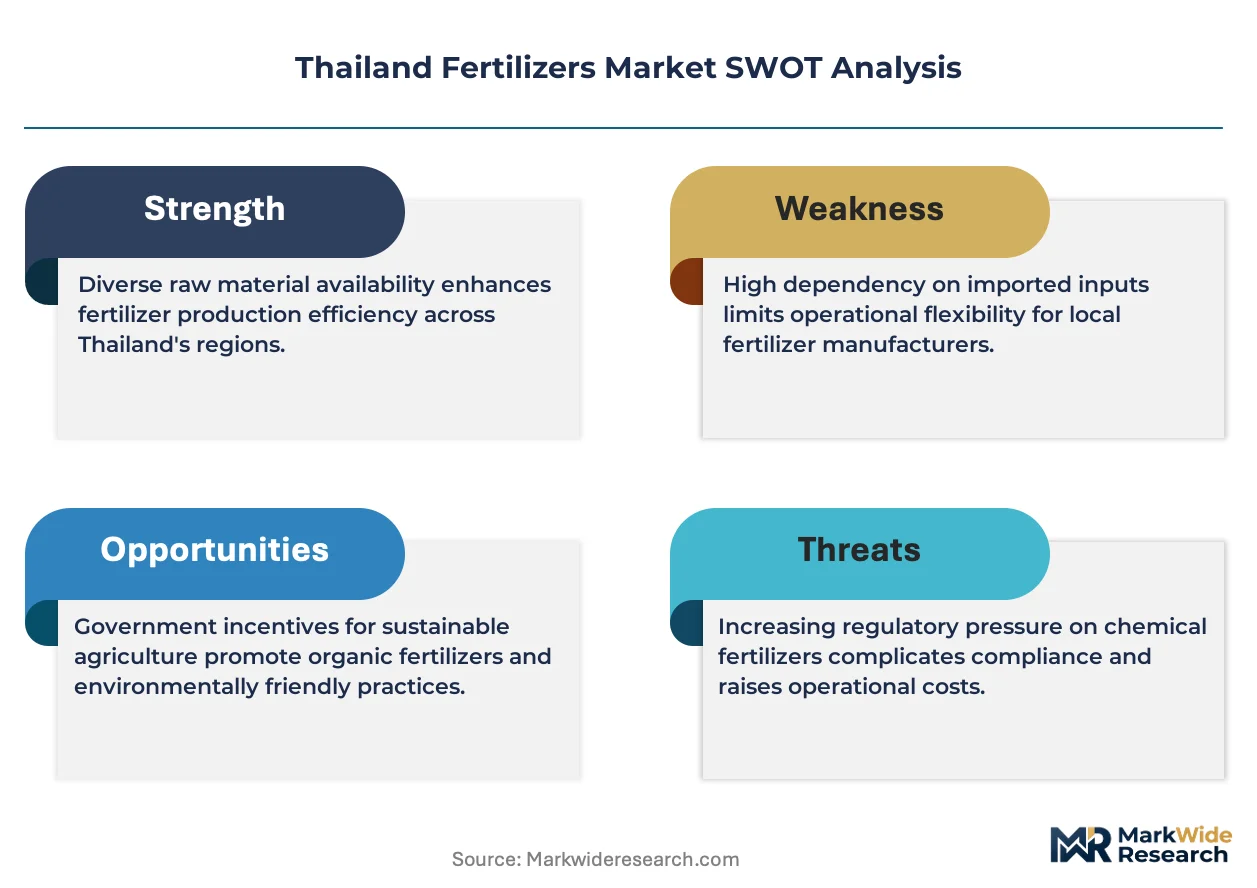
Among Thailand-anchored conglomerates, Saksiam Group and Thai Central Chemical Public Company Limited exemplify the domestic certification-advantaged archetype, leveraging Department of Agriculture registration protocols to capture cooperative procurement contracts. Yara International occupies the multinational precision-agriculture tier, representing technology-licensed international formulators targeting horticulture transition zones. These three anchors illustrate how regulatory compliance capacity and distribution infrastructure depth determine competitive positioning across subsidized and premium market segments.
| Leading Market Players |
|---|
| Saksiam Group |
| NFC Public Company Limited |
| Yara International |
| Baba Thai Group |
| Thai Peace Pulp (Thailand) Co., Ltd |
| Thai Central Chemical Public Company Limited |
| Chia Tai Group |
| ICL Fertilizers (Ranthai Agro Co. Ltd) |
| Haifa Group |
| Others |
Value Network & Pricing Analysis
Cooperative procurement consolidation through centralized digital tender platforms is compressing distributor margins and forcing blenders to absorb cost volatility or surrender volume share. This buyer-power concentration rewards registered suppliers with certified warehousing networks while squeezing unregistered cross-border suppliers out of subsidized channels.
Pricing Analysis
Distributor margin compression dominates Thailand's fertilizer pricing structure as cooperative tender platforms consolidate provincial purchasing power. Three-tier pricing stratifies across premium water-soluble grades for Eastern Economic Corridor horticulture, certified NPK complexes for registered cooperative supply, and commodity urea for rice subsidy channels. Pricing pressure intensifies in the standard tier where domestic blenders compete for cooperative contracts against filtered informal imports. Individual smallholders below cooperative membership thresholds exhibit highest price sensitivity, purchasing at unsubsidized retail rates, while commercial durian operations in Chonburi absorb premium pricing for sulfate-based formulations.
Supply Chain Analysis
Single-source vulnerability sits with Belarusian and Russian potassium chloride contracts denominated in volatile currencies against the Thai baht. Ammonia synthesis feedstock draws from natural gas supply anchored in Qatar, Australia, and Malaysia, while phosphate rock acidulation depends on Moroccan and Jordanian extraction. Tariff exposure runs through Laem Chabang port clearance bottlenecks where 15-30 day delays punish unregistered Southeast Asian suppliers. Distribution runs through provincial cooperative collection points and certified warehousing networks reaching Nakhon Ratchasima and Khon Kaen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's fertilizer sector offers margin-expansion pathways through premium-grade formulation shifts in horticulture and cost-down capture from precision agriculture adoption compressing per-hectare application rates.
For Market Incumbents: Lock in cooperative procurement contracts by acquiring certified laboratory capacity for heavy metal testing and micronutrient disclosure compliance. Deepen backward integration into ammonia synthesis to hedge natural gas feedstock volatility. Defend against Yara International's precision-agriculture encroachment by bundling variable-rate spreader leases with NPK complex supply to Chonburi contract farming collectives. For New Entrants and Emerging Players: Smallholder farming cooperatives in Isan farming zones represent the most penetrable buyer archetype, with Nakhon Ratchasima and Khon Kaen exhibiting 40% lower application rates than Central Plains benchmarks. Specialty water-soluble grades for greenhouse vegetable operations offer white-space capture as drip irrigation adoption accelerates. Lead with foliar application services bundled with soluble fertilizer supply to differentiate from commodity blenders. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic blenders possessing Department of Agriculture registration and certified warehousing networks, as regulatory friction filters out informal cross-border competition. Long-term viability hinges on carbon-footprint labeling preparation ahead of anticipated Board of Investment procurement criteria. Watch for ammonia producers with emission-verified supply chains capturing first-mover advantage as sustainability mandates tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Certification Investment | Heavy metal testing capacity secures cooperative contracts under tightened 2023 Department of Agriculture protocols. |
| Backward Integration into Ammonia Synthesis | Captive natural gas feedstock supply hedges margin compression from Qatari and Australian contract volatility. |
| Precision Agriculture Equipment Leasing | GPS-guided variable-rate spreaders bundled with NPK complexes lock in Chonburi durian operation loyalty. |
| Sulfate-Based Formulation Expansion | Potassium sulfate production capacity captures Eastern Economic Corridor chloride-sensitive cropping demand. |
| Carbon-Footprint Supply Chain Verification | Emission-verified ammonia production positions for anticipated Board of Investment procurement criteria. |
Research Methodology
Bottom-up horticulture and rice cultivation modeling reconciled against top-down import clearance and cooperative procurement tracking forms the analytical core of this study. Primary interviews with Department of Agriculture registration officers, provincial cooperative procurement managers, blending facility plant managers, and Eastern Economic Corridor durian contract farming operators combined with secondary validation from customs trade data, Ministry of Agriculture subsidy disbursement records, and Department of Agriculture fertilizer registration databases. Triangulation across these sources ensures demand-side consumption patterns align with supply-side import and domestic production flows.
Historical trendline analysis of urea and NPK complex pricing across cooperative tender platforms established baseline growth trajectories. Segmentation modeling incorporated product type, application intensity, end-user procurement scale, and distribution channel infrastructure dimensions. CAGRs were derived from volume and value progression across the projection horizon, with horticulture expansion rates and precision agriculture adoption curves as key forecast inputs.
Underlying measurement precision varies by segment; subsidized urea flows through cooperative channels carry tighter precision than specialty water-soluble grade estimates for greenhouse operations. Forecasts reflect assumptions around regulatory enforcement consistency at Laem Chabang, currency stability against Eastern European potash contracts, and soil health mandate implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
Nano Fertilizer Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Global Urea Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Russia Fertilizers Market