
 Australia Fertilizer Market | 2026-2036
Australia Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Fertilizer Market Insights
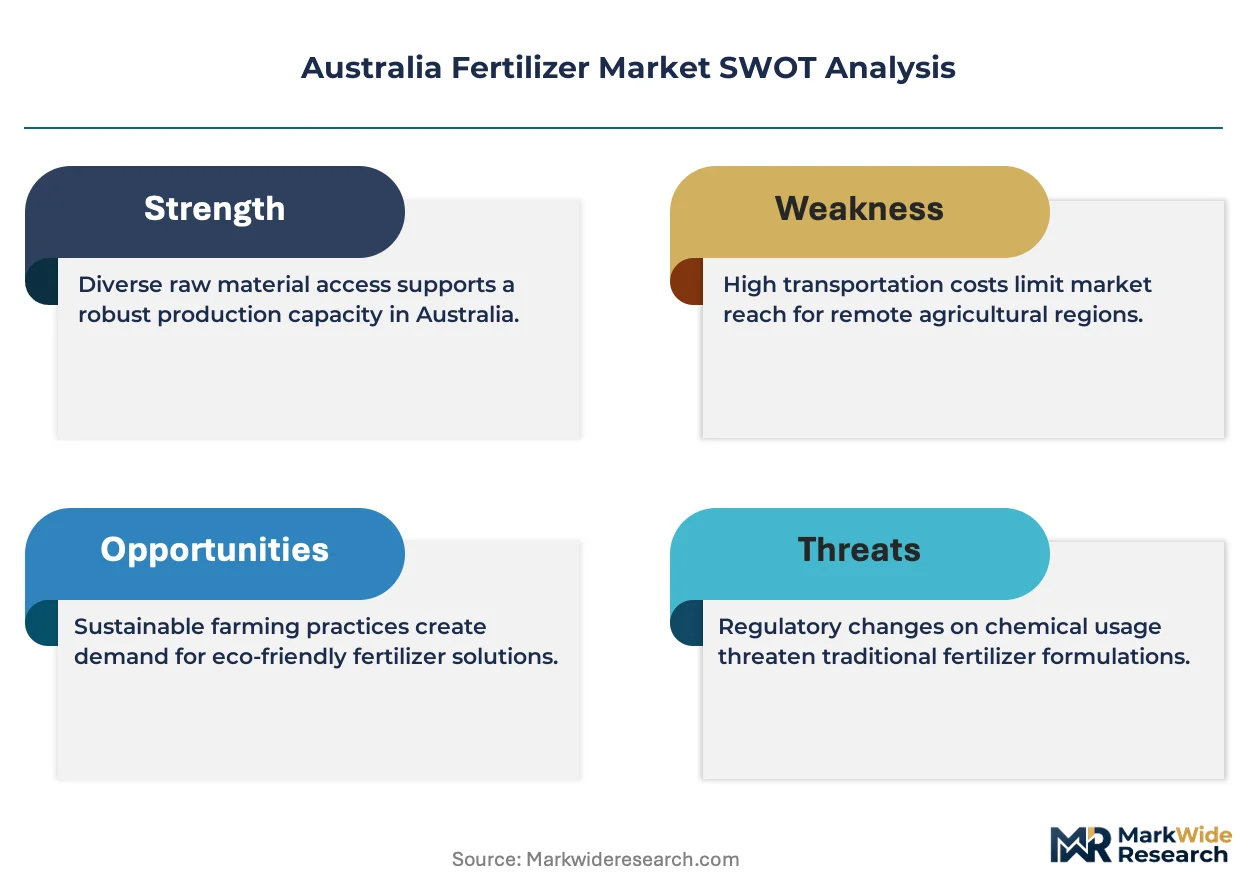
Horticultural exports is decoupling from traditional broadacre fertilizer norms as protected cropping expands. Incitec Pivot Limited leverages its Gibson Island manufacturing complex to sustain domestic ammonium nitrate supply chains. Yara Australia competes through precision agriculture platforms that anchor its position in controlled-release product lines. Wesfarmers Limited extends retail distribution reach across rural Western Australia through its Landmark network.
Fertilizers are nutrient-dense chemical or organic compounds formulated with specified N-P-K ratios, typically manufactured via Haber-Bosch ammonia synthesis or phosphate rock acidulation, designed to replenish soil macronutrients and correct micronutrient deficiencies for commercial crop production. Urea dominates volume flows into cereal cropping systems while phosphate concentrates margin pools in horticultural and high-value vegetable segments. Agricultural cooperatives channel bulk urea and potash to broadacre operators whereas direct sales relationships capture premium pricing in greenhouse operator accounts for customized micronutrient blends.
TGA regulates agricultural chemical registration timelines while the Australian Pesticides and Veterinary Medicines Authority governs fertilizer contaminant thresholds, and the Clean Energy Regulator administers carbon credit methodologies for nitrification inhibitor adoption. These frameworks elevate compliance costs for imported formulations while creating domestic manufacturing incentives through emissions accounting advantages. Stakeholders must monitor evolving biosecurity protocols for organic fertilizer inputs and assess positioning against emerging soil carbon measurement standards.
Market Dynamics
Precision variable-rate application is decoupling wheat production from historical nitrogen intensity across Australia's wheatbelt, compressing volume demand while elevating margin capture for technology-enabled suppliers. The Clean Energy Regulator's carbon credit methodologies for nitrification inhibitors simultaneously pull product mix toward enhanced-efficiency formulations.
Growth Catalysts
- Emissions Reduction Fund incentives:The Australian government's carbon credit framework rewards enhanced-efficiency fertilizer adoption, redirecting grower procurement toward nitrification inhibitor blends.
- Protected cropping expansion:Horticultural export growth is decoupling from broadacre fertilizer norms as greenhouse operators demand customized micronutrient formulations.
- Western Australia wheatbelt corridor:Concentrated demand from broadacre operators creates density economics for bulk urea distribution infrastructure.
Market Restraints
- Natural gas price volatility:Ammonia synthesis feedstock costs swing with international LNG benchmarks, compressing domestic manufacturer margins.
- Import dependency for potash:No domestic potash extraction leaves Australian agriculture exposed to Saskatchewan and Belarus supply concentration.
- TGA registration timelines:Agricultural chemical approval delays extend product commercialization cycles for novel fertilizer formulations.
Strategic Opportunities
- Queensland sugarcane districts:Cane-specific nutrient management protocols remain underpenetrated by precision agriculture platforms.
- Soil carbon measurement standards:Emerging biosecurity protocols for organic inputs create certification-premium capture potential.
- Controlled-release polymer convergence:Integration of moisture-activated coatings with variable-rate hardware enables subscription-based nutrient service models.
Industry Challenges
- Agronomic data science talent scarcity:Variable-rate platform deployment requires field-level digital agronomy expertise that outstrips supply.
- Legacy supply chain reconfiguration:Cooperative bulk channels resist disintermediation by precision product direct-sales models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Fertilizer Market |
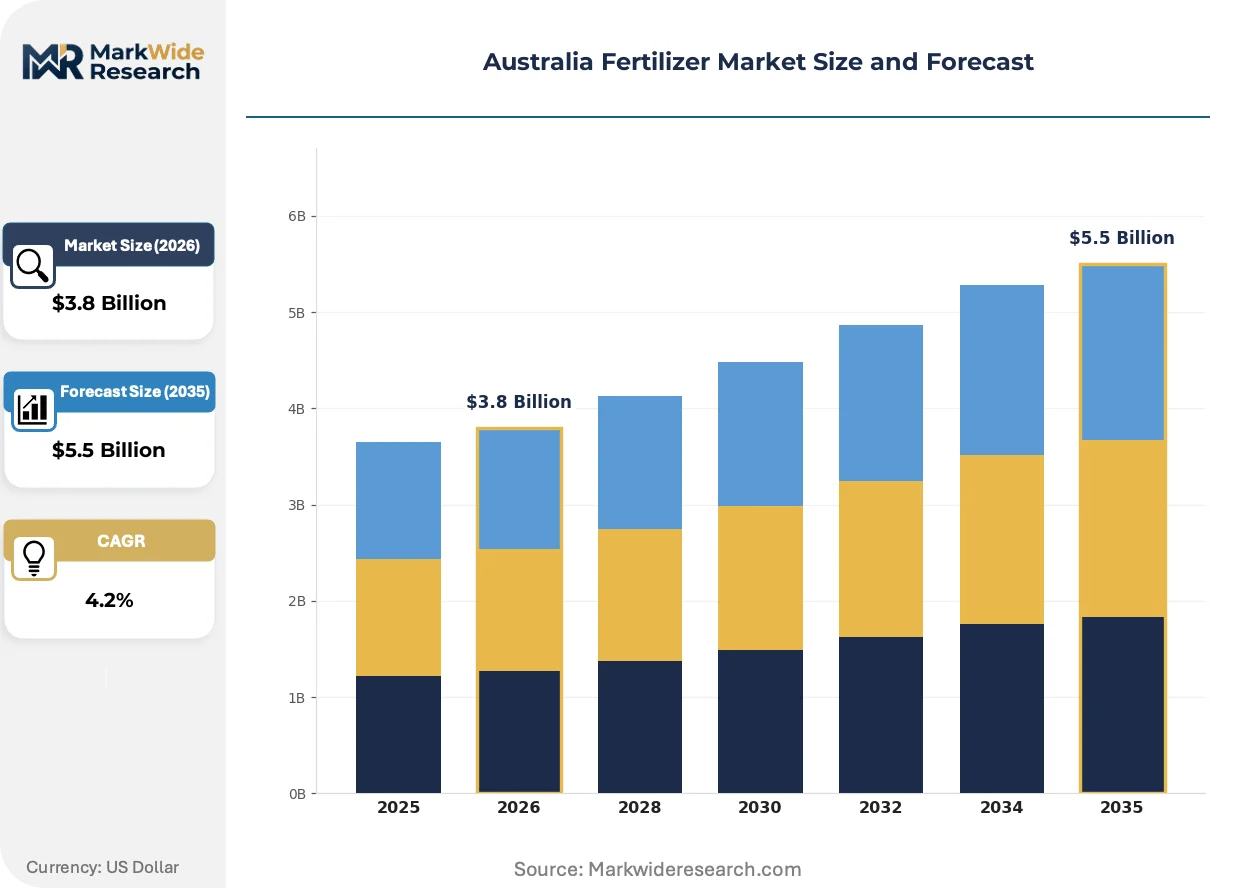
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Phosphate, Potash End User: Agricultural Producers, Commercial Growers, Crop Farmers, Greenhouse Operators Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Agricultural Cooperatives Application: Cereal Crops, Fruits, Vegetables, Turf |
| Companies Covered | Impact Fertilisers, ICL Group Ltd, Incitec Pivot Limited, Nutrien Ag Solutions, K+S Aktiengesellschaft, Wesfarmers Limited, Yara Australia, Ravensdown Fertiliser Co-operative Limited, CSBP Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Fertilizer Market Trends and Innovations
Digital agriculture platforms are compressing the distance between soil sensor data and fertilizer prescription, collapsing traditional agronomist-mediated buying cycles. Three concurrent developments are reshaping competitive positioning.
Variable-rate nitrogen application technology is rewriting yield optimization protocols across Western Australia's wheatbelt. Broadacre operators are adopting sensor-guided equipment at accelerating replacement cycles for broadcast spreaders. This compression is enabling input suppliers to capture service revenue streams previously retained by independent agronomists.
The Clean Energy Regulator's nitrification inhibitor methodology is mandating product reformulation across manufacturing facilities. Domestic producers gain emissions accounting advantages over import-dependent competitors. Queensland sugarcane operators face the steepest compliance cost elevation due to high-volume nitrogen application rates.
Greenhouse operator procurement is consolidating around customized micronutrient blend contracts. Direct manufacturer relationships are displacing cooperative channel intermediaries for protected cropping accounts. This concentration is most visible in Victoria's glasshouse vegetable export corridor.
Australia Fertilizer Market Segmentation
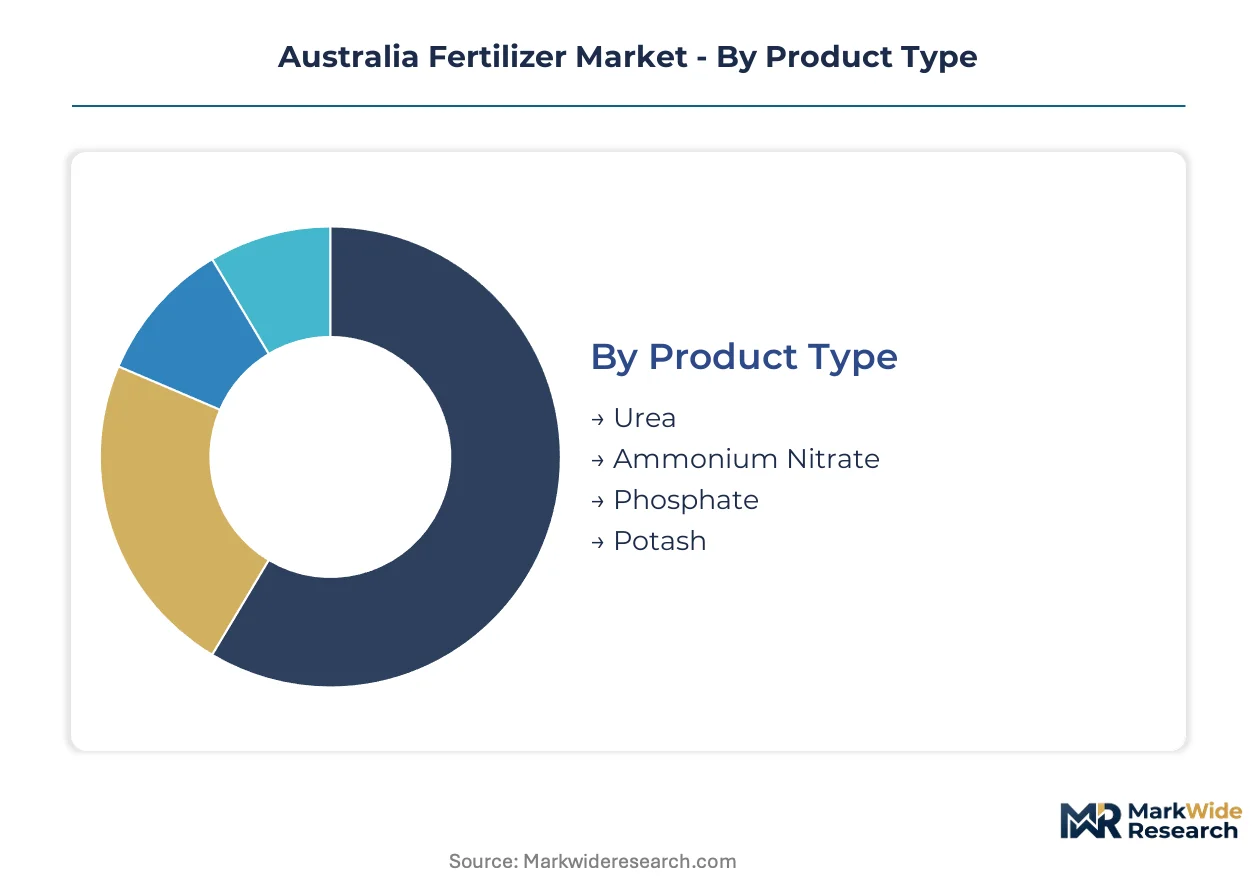
Segmentation in the Australia Fertilizer Market reveals how nutrient flows bifurcate between bulk commodity channels and precision-enabled service models. Understanding these divides exposes where margin compression and premium capture concentrate across the value chain.
Product Type:
Standalone commodity fertilizers dominate volume placements, while enhanced-efficiency formulations embed into precision agriculture platforms as integrated service offerings.
- Urea:Nitrogen-dense granular formulation manufactured via Haber-Bosch synthesis with 46% nitrogen content. Western Australia's wheatbelt corridor drives concentrated bulk demand, though variable-rate application technology is compressing per-hectare intensity while elevating margin capture for technology-enabled suppliers.
- Ammonium Nitrate:High-nitrogen compound (34% N) with superior handling safety and controlled-release compatibility. Domestic manufacturing at Gibson Island secures supply chain resilience against LNG price volatility that squeezes import-dependent competitors.
- Phosphate:Phosphoric acid-derivatives from phosphate rock acidulation, concentrated in DAP and MAP formulations. Queensland sugarcane districts represent the steepest demand concentration for high-analysis phosphate blends.
- Potash:Potassium chloride (KCl) sourced entirely through import channels from Saskatchewan and Belarus supply basins. No domestic extraction leaves Australian agriculture exposed to international supply concentration and currency fluctuation risk.
Volume placements concentrate in urea; the faster expansion belongs to ammonium nitrate as enhanced-efficiency formulations gain carbon credit eligibility.
End User:
Customer segmentation separates bulk procurement operators from customized blend buyers, with channel intermediation collapsing fastest among high-value horticultural accounts.
- Agricultural Producers:Broadacre wheat and barley operators managing thousand-hectare holdings across Western Australia's wheatbelt. Cooperative bulk channels dominate procurement, though precision platform adoption is fragmenting traditional agronomist-mediated buying cycles.
- Commercial Growers:Mid-scale vegetable and fruit enterprises supplying domestic supermarket chains and export markets. Direct manufacturer relationships are displacing cooperative intermediaries as customized micronutrient specifications proliferate.
- Crop Farmers:Diverse cereal and oilseed operators in South Australia and New South Wales grain belts. Price-sensitive procurement patterns resist premium formulation uptake without demonstrated yield response documentation.
- Greenhouse Operators:Protected cropping enterprises in Victoria's glasshouse vegetable export corridor. Consolidated procurement around long-term customized blend contracts enables subscription-based nutrient service models with moisture-activated coating integration.
Procurement volume clusters with agricultural producers; greenhouse operators are climbing the fastest as protected cropping expansion outpaces broadacre input growth.
Distribution Channel:
Channel structure maps onto customer scale and formulation complexity, with digital platforms penetrating fastest where agronomic data integration creates switching costs.
- Direct Sales:Manufacturer-to-grower relationships for customized micronutrient blends and controlled-release formulations. Greenhouse operator accounts in Victoria and Queensland horticultural districts show highest concentration.
- Retail Stores:Wesfarmers' Landmark network and independent rural suppliers serving small-to-mid scale broadacre operators. Geographic reach across rural Western Australia sustains density economics for bulk urea and standard NPK compounds.
- Online Platforms:Digital procurement portals with integrated soil sensor data and prescription delivery. Penetration accelerates where variable-rate hardware deployment creates demand for algorithm-driven input recommendations.
- Agricultural Cooperatives:Legacy bulk channels channeling urea and potash to broadacre operators. Cooperative structures resist disintermediation through embedded financing and harvest-linked payment terms.
Transaction volume flows through agricultural cooperatives; online platforms are gaining share fastest as digital agriculture platforms compress prescription-to-purchase cycles.
Application:
Application segmentation exposes where nutrient intensity decouples from hectare expansion as precision technologies rewrite yield optimization protocols.
- Cereal Crops:Wheat, barley, and canola systems across Western Australia, South Australia, and New South Wales grain belts. Variable-rate nitrogen application is decoupling production from historical intensity while the Clean Energy Regulator's nitrification inhibitor methodology mandates product reformulation.
- Fruits:Orchard and vineyard systems in Riverina, Sunraysia, and Tasmania. Micronutrient deficiency correction drives premium formulation demand with specifications varying by cultivar and rootstock.
- Vegetables:Field and protected production supplying domestic and export markets. Greenhouse operator procurement consolidation around direct manufacturer relationships concentrates in Victoria's export corridor.
- Turf:Sports field, golf course, and amenity grass management. Specialized slow-release nitrogen formulations with reduced burn risk dominate, though segment scale remains limited relative to agricultural applications.
Hectare coverage peaks in cereal crops; vegetables are expanding most quickly as protected cropping area accelerates and horticultural export growth decouples from broadacre fertilizer norms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Emissions Reduction Fund's carbon credit methodology for nitrification inhibitors concentrates enhanced-efficiency fertilizer demand in states with intensive broadacre cropping. State-level agricultural extension programs and biosecurity protocols further differentiate regional procurement patterns across Australia's fertilizer value chain.
Western Australia
The wheatbelt corridor generates concentrated bulk urea demand from thousand-hectare broadacre operators. The state's Department of Primary Industries and Regional Development administers precision agriculture subsidy programs that accelerate variable-rate equipment adoption. Geraldton and Esperance port infrastructure anchors import-dependent supply chains for potash and phosphate rock derivatives.
Queensland
Sugarcane districts in the Burdekin and Mackay regions sustain high-volume nitrogen application rates that face steepest compliance cost elevation under Clean Energy Regulator methodologies. The Queensland Department of Agriculture and Fisheries enforces reef protection regulations that mandate controlled-release formulations in coastal catchments. Brisbane-based distribution hubs channel enhanced-efficiency products to cane-specific nutrient management protocols.
Victoria
The glasshouse vegetable export corridor around Werribee and the Mornington Peninsula drives fastest-growing demand for customized micronutrient blends. Agriculture Victoria oversees soil carbon measurement standard pilots that create certification-premium capture potential for organic input suppliers. Direct manufacturer relationships displace cooperative intermediaries as greenhouse operator procurement consolidates around long-term contracts.
New South Wales
The Riverina and Sunraysia irrigation districts generate premium formulation demand for orchard and vineyard micronutrient deficiency correction. The EPA's agricultural chemical registration timelines extend product commercialization cycles for novel fertilizer formulations. Griffith and Mildura serve as consolidation points for horticultural export supply chains that bypass traditional bulk cooperative channels.
Australia Fertilizer Market Competitive Landscape
Top-tier vendors anchor domestic manufacturing capacity, while import-dependent traders and regional distributors populate lower tiers. The vendor base stratifies across three concentration levels: integrated manufacturers with captive ammonia synthesis, cooperative bulk channels with embedded financing structures, and precision agriculture platforms with subscription service models. Two dominant competitive moves define current positioning: backward integration into natural gas feedstock arrangements and forward integration into soil sensor data platforms.
Among domestic integrated manufacturers, Incitec Pivot Limited and Wesfarmers Limited occupy positions that exemplify contrasting strategic archetypes. Incitec Pivot represents the manufacturing-anchored model with Gibson Island production assets securing supply chain resilience against LNG price volatility. Wesfarmers exemplifies the retail-distribution vector through Landmark network density economics across rural Western Australia. Yara Australia sits within the precision agriculture platform tier, competing through controlled-release product lines integrated with variable-rate hardware systems.
| Leading Market Players |
|---|
| Impact Fertilisers |
| ICL Group Ltd |
| Incitec Pivot Limited |
| Nutrien Ag Solutions |
| K+S Aktiengesellschaft |
| Wesfarmers Limited |
| Yara Australia |
| Ravensdown Fertiliser Co-operative Limited |
| CSBP Limited |
| Others |
Pricing and Supply Chain Analysis
Thousand-hectare broadacre operators across Western Australia's wheatbelt anchor volume procurement through cooperative bulk channels, locking in contract-based long-term offtake structures that compress spot-market liquidity and elevate price transparency gaps between bulk commodity and precision-enabled tiers.
Pricing Analysis
Short lead-time premiums for controlled-release ammonium nitrate formulations command substantial markups over standard urea spot inventory, with three-tier pricing structure across premium, standard, and economy levels stratifying by carbon credit eligibility and variable-rate hardware compatibility. Price differentiation hinges on certification grade under Clean Energy Regulator methodologies and geographic delivery cost to Queensland sugarcane districts. Pricing pressure stems from LNG feedstock volatility squeezing domestic manufacturer margins. Agricultural producers exhibit highest price sensitivity; greenhouse operators in Victoria's glasshouse corridor show least sensitivity due to subscription-based nutrient service lock-in.
Supply Chain Analysis
Ammonia synthesis feedstock rests on international LNG benchmark pricing, with potash supply anchored in Saskatchewan and Belarus extraction basins and phosphate rock derivatives concentrated in Moroccan and Chinese processing corridors. Raw material dependencies span natural gas molecules, potassium chloride ore, and phosphoric acid intermediates. Single-source vulnerability for potash imports exposes Australian agriculture to currency fluctuation and geopolitical disruption. Distribution runs through agricultural cooperative bulk channels for broadacre operators, with direct manufacturer relationships penetrating fastest among protected cropping accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturing-anchored players with captive ammonia synthesis assets, as natural gas price volatility forces import-dependent traders toward margin compression or exit.
For Market Incumbents: Cement supply chain resilience through backward integration into natural gas feedstock arrangements or long-term LNG offtake contracts, while capturing service revenue from variable-rate platform deployment that fragments traditional agronomist-mediated buying cycles. Priority lever: controlled-release polymer convergence with moisture-activated coatings to lock in greenhouse operator subscription contracts against cooperative channel resistance. For New Entrants and Emerging Players: The mid-tier price-point gap between Incitec Pivot's Gibson Island premium ammonium nitrate and economy urea imports offers white-space penetration through precision agriculture platform partnerships in Queensland sugarcane districts, where cane-specific nutrient management protocols remain underpenetrated. Target online platform procurement channels with algorithm-driven input recommendations that compress prescription-to-purchase cycles for mid-scale commercial growers. For Investors and Strategic Acquirers: The window for entry favors precision agriculture platform specialists with integrated soil sensor data capabilities and established variable-rate hardware relationships. Acquisition target archetype: regional distributors with embedded financing structures and harvest-linked payment terms that resist disintermediation. Signal to watch: Clean Energy Regulator expansion of nitrification inhibitor methodologies to additional cropping systems as inflection indicator for enhanced-efficiency formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Feedstock | Captive LNG supply secures Gibson Island manufacturing cost position against import-dependent competitors. |
| Controlled-Release Polymer Convergence | Moisture-activated coating integration enables subscription-based nutrient service models with greenhouse operators. |
| Precision Agriculture Platform Deployment | Variable-rate hardware systems compress prescription-to-purchase cycles and displace cooperative intermediaries. |
| Carbon Credit Certification Investment | Clean Energy Regulator methodology compliance unlocks Emissions Reduction Fund incentive capture for nitrification inhibitor blends. |
| Direct Manufacturer Relationship Expansion | Long-term customized blend contracts with Victoria's glasshouse vegetable export corridor bypass cooperative bulk channels. |
Research Methodology
Trade flow databases, agricultural chemical registration filings, and Clean Energy Regulator carbon credit methodology documents formed the secondary backbone, cross-referenced with primary interviews spanning fertilizer manufacturing plant managers, broadacre cooperative procurement leads, greenhouse operator technical directors, and precision agriculture platform engineers. Bottom-up segmentation modeling triangulated against top-down macroeconomic agricultural output projections.
Historical trendline analysis across domestic urea consumption, import dependency ratios, and variable-rate equipment installation rates established baseline growth trajectories. The analytical framework modeled product type, end user scale tier, distribution channel structure, and application crop category across the projection horizon. CAGRs derived from segmented volume-to-value conversion using nitrogen-content-equivalent pricing and carbon credit eligibility premia.
Inputs from TGA registration timelines and Australian Pesticides and Veterinary Medicines Authority contaminant threshold filings were available through the study window; gaps in real-time soil carbon measurement standard pilot data introduce uncertainty bands around organic input certification-premium capture potential. Forecasts reflect assumptions regarding Emissions Reduction Fund incentive continuity and LNG price normalization trajectories. A small set of triggers—nitrification inhibitor methodology expansion, potash supply disruption events, and precision platform adoption inflection—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Global Urea Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Global Green Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Urea Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
GCC Organic Fertilizer Market