
 North America Liquid Fertilizers Market | 2026-2036
North America Liquid Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Liquid Fertilizers Market Analytics
Horticultural crop demand is decoupling from traditional row-crop dominance as greenhouse and specialty vegetable operations scale fertigation infrastructure. Nutrien Ltd. anchors the Canadian prairie supply chain through its Redwater, Alberta nitrogen complex and extensive farm retail network. AgroLiquid specializes in customized micronutrient blends for high-value fruit and vegetable producers in Michigan and the Pacific Northwest. Yara International ASA extends its footprint via terminal and vessel logistics along the Mississippi River corridor.
North America liquid fertilizers comprise concentrated aqueous or suspension nutrient solutions, typically formulated with nitrogen, phosphorus, and potassium compounds dissolved or dispersed in water for direct soil application, foliar feeding, or injection through irrigation systems; urea-ammonium nitrate solutions dominate volume due to their high nitrogen content and compatibility with existing application equipment. Ammonium phosphate formulations command premium positioning in starter fertilizer programs where phosphorus availability at planting critically influences early root development. Potassium nitrate segments serve high-value horticultural and greenhouse operations where chloride sensitivity restricts conventional muriate of potash use. Calcium nitrate applications are expanding fastest among hydroponic vegetable producers in Mexico's Sinaloa and Baja California greenhouse clusters.
The EPA regulates nutrient management under the Clean Water Act Total Maximum Daily Load framework, while state-level fertilizer certification programs in Illinois, Iowa, and Minnesota mandate applicator training for nitrogen stewardship. Canada's Fertilizer Act and CFIA oversight govern product registration, labeling, and contaminant limits for cross-border trade. Mexico's SEMARNAT implements ecological standards for aquifer protection in intensive agricultural zones. Stakeholders must monitor evolving 4R Nutrient Stewardship adoption metrics and state-level carbon intensity scoring for fertilizer production as these frameworks increasingly influence procurement specifications and cooperative purchasing agreements.
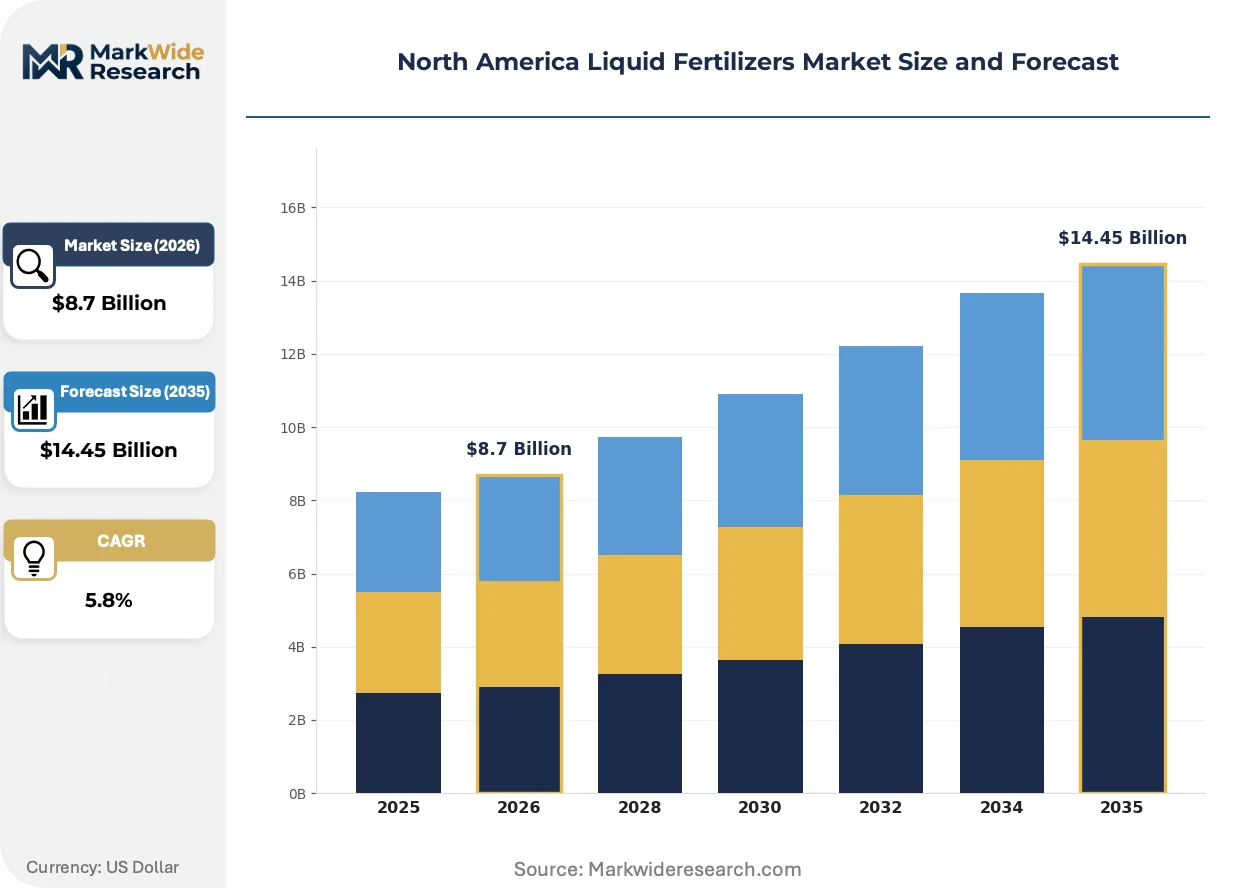
Market Dynamics
The EPA's Clean Water Act enforcement around nutrient runoff is compressing demand toward controlled-release liquid formulations, while precision agriculture adoption accelerates fertigation infrastructure deployment across specialty crop regions.
Growth Catalysts
- USDA Conservation Programs:Incentives for precision nutrient delivery are expanding fertigation adoption among California and Florida specialty crop growers.
- 4R Nutrient Stewardship:State-level carbon intensity scoring frameworks are influencing cooperative purchasing specifications across the Corn Belt.
- Urea-ammonium nitrate compatibility:Existing application equipment infrastructure reduces switching costs for row-crop operators transitioning from dry blends.
Market Restraints
- Natural gas feedstock volatility:Nitrogen solution production costs fluctuate with Henry Hub pricing, compressing blender margins during price spikes.
- Mississippi River logistics concentration:Terminal and vessel infrastructure bottlenecks create supply vulnerability during low-water events.
- Phosphate rock import dependency:Ammonium phosphate formulations rely on Moroccan and Russian supply chains subject to trade friction.
Strategic Opportunities
- Mexico greenhouse expansion:Hydroponic vegetable producers in Sinaloa and Baja California clusters are driving calcium nitrate demand acceleration.
- Carbon intensity procurement mandates:Cooperative purchasing agreements increasingly specify low-carbon fertilizer production methods.
- Customized micronutrient blending:High-value fruit and vegetable producers seek tailored formulations beyond commodity nitrogen solutions.
Industry Challenges
- Applicator certification timelines:Illinois, Iowa, and Minnesota nitrogen stewardship programs create workforce bottlenecks during planting windows.
- Fertigation infrastructure capex:Greenhouse and specialty vegetable operations face upfront irrigation system retrofit costs.
- Cross-border registration complexity:Canada's CFIA and Mexico's SEMARNAT maintain divergent contaminant limit standards complicating product harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Liquid Fertilizers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea Ammonium Nitrate, Calcium Nitrate, Potassium Nitrate, Ammonium Phosphate Application: Agricultural Crops, Horticultural Crops, Turf & Ornamentals, Perennials Distribution Channel: Direct Sales, Wholesale Distributors, Retail Stores, Online Retail End User: Farmers, Agricultural Cooperatives, Landscapers, Greenhouses |
| Companies Covered | The Mosaic Company, AgroLiquid, Nutrien Ltd., Kugler Company, Haifa Group, Yara International ASA, ICL Group, FoxFarm Soil & Fertilizer Company, CF Industries Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Liquid Fertilizers Market Evolving Landscape
Formulation chemistry and application hardware are converging to enable site-specific nutrient delivery, while regulatory pressure on runoff accelerates product innovation cycles.
Controlled-release polymer coating technology for liquid nitrogen solutions is modularizing application timing flexibility. Large-scale agricultural cooperatives across the Delta region are adopting these formulations to split nitrogen applications across growth stages. The technology is compressing the risk premium previously assigned to single-pass dry fertilizer programs.
The EPA's evolving Total Maximum Daily Load framework under the Clean Water Act is tightening nutrient management requirements for watersheds draining into the Gulf of Mexico. Agricultural operations in the Corn Belt face escalating compliance documentation burdens. Fertilizer retailers are responding by bundling application services with runoff monitoring to deflect liability exposure.
Buyer concentration among agricultural cooperatives is consolidating procurement leverage and squeezing independent blender margins. Volume-based pricing tiers now dominate contract negotiations, displacing historical relationship-based supply arrangements. This pattern is most visible across Iowa and Illinois where cooperative mergers have reduced the number of independent buying entities by half over the past decade.
North America Liquid Fertilizers Market Segmentation
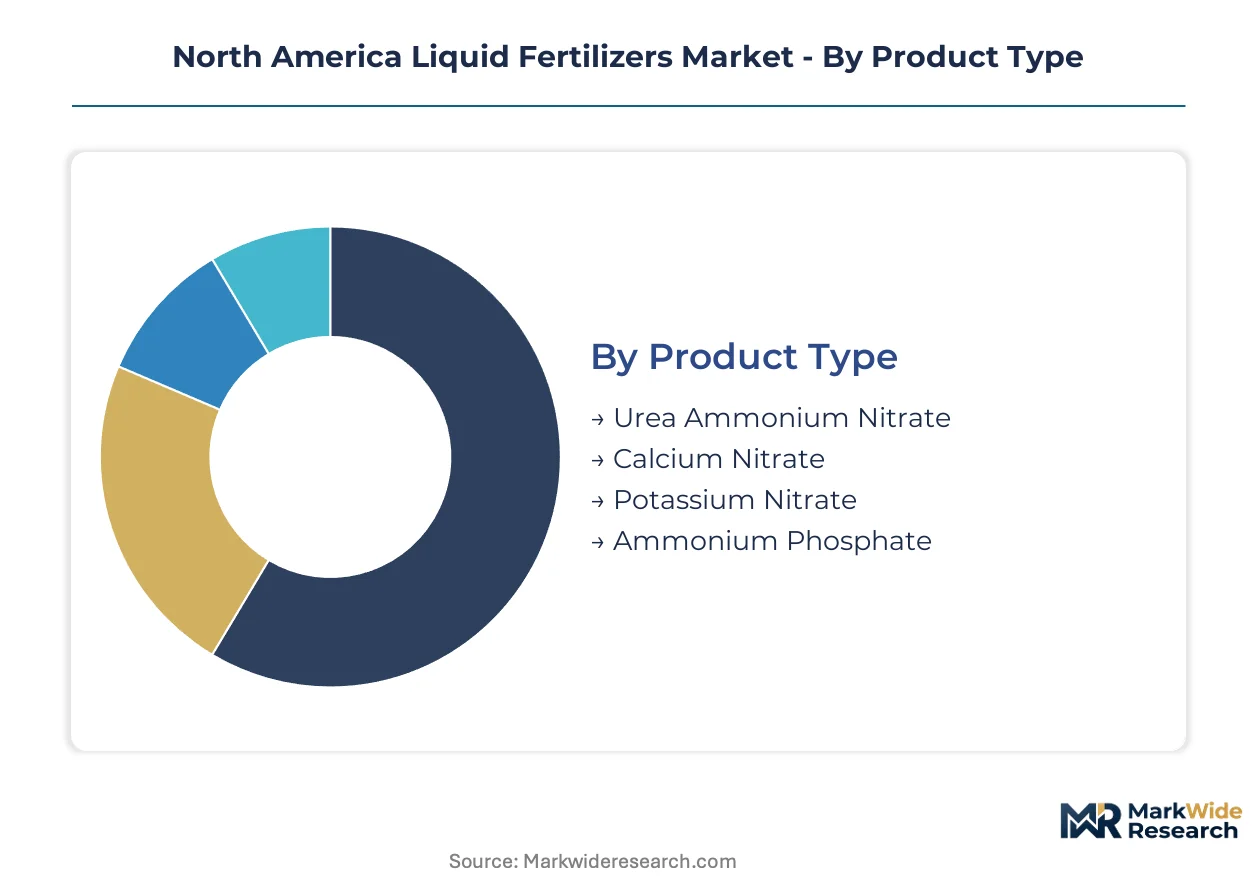
Segmentation in liquid fertilizers reveals how nutrient chemistry, crop economics, and procurement channels fragment demand across divergent buyer priorities. Each dimension exposes distinct margin structures and switching costs that shape competitive positioning.
Product Type:
Buyers select formulations based on equipment compatibility, crop sensitivity to chloride or salt index, and the timing flexibility required in their rotation schedules.
- Urea Ammonium Nitrate:Aqueous solutions combining urea and ammonium nitrate deliver high nitrogen concentration with low salt index, compatible with standard spray equipment across the Corn Belt. Volume concentrates among large-scale row-crop operators in Iowa and Illinois who value single-tank simplicity and established supply infrastructure.
- Calcium Nitrate:Fully water-soluble calcium and nitrogen source eliminates chloride toxicity risk, critical for hydroponic tomato and pepper operations. Demand is accelerating fastest among greenhouse clusters in Mexico's Sinaloa and Baja California where fertigation precision determines fruit quality premiums.
- Potassium Nitrate:Dual-nutrient formulation serves chloride-sensitive crops including strawberries, tobacco, and citrus in Florida and California Central Valley orchards.
- Ammonium Phosphate:Starter fertilizer grade supplies phosphorus and nitrogen in planting-band placement for early root development in wheat and corn programs across the Canadian prairie.
Volume sits with urea ammonium nitrate; growth tilts toward calcium nitrate.
Application:
Crop value per acre and irrigation infrastructure availability determine formulation sophistication and service bundling requirements.
- Agricultural Crops:Corn, soybean, and wheat operations across the Delta and Corn Belt drive baseline nitrogen demand through broadcast and sidedress applications. USDA conservation program incentives in Minnesota and Wisconsin are compressing application windows toward split-rate timing.
- Horticultural Crops:Specialty vegetables, tree nuts, and citrus command premium micronutrient blends with foliar and drip delivery. California's Central Valley and Florida's Ridge region dominate procurement as groundwater quality regulations tighten nutrient management documentation.
- Turf & Ornamentals:Golf course superintendents and municipal park managers in Texas and Arizona prioritize uniform greening with minimal burn risk during high-temperature application windows.
- Perennials:Orchard and vineyard operators in Washington's Yakima Valley and Michigan's Fruit Ridge seek late-season potassium supplementation to enhance winter hardiness and fruit set consistency.
Revenue concentrates in horticultural crops; expansion is steepest among agricultural crops adopting precision fertigation retrofits.
Distribution Channel:
Scale and technical support requirements fragment channel preference between price-sensitive volume buyers and service-dependent specialty operators.
- Direct Sales:Manufacturer-to-farm contracts lock in seasonal volumes for cooperatives exceeding 50,000 acres, with bundled application and soil testing services. Nutrien and Yara leverage terminal proximity along the Mississippi River corridor to defend these relationships.
- Wholesale Distributors:Regional blenders in Ohio and Indiana aggregate demand from independent retailers, capturing margin through formulation customization and just-in-time delivery during compressed planting windows.
- Retail Stores:Farm supply cooperatives and independent dealers serve mid-scale operators with standard UAN grades and basic micronutrient packages.
- Online Retail:E-commerce platforms capture small greenhouse and landscape contractors seeking specialty calcium nitrate and potassium formulations with technical specification transparency.
Procurement gravity centers on wholesale distributors; channel expansion is climbing fastest through direct sales as cooperative consolidation amplifies buyer leverage.
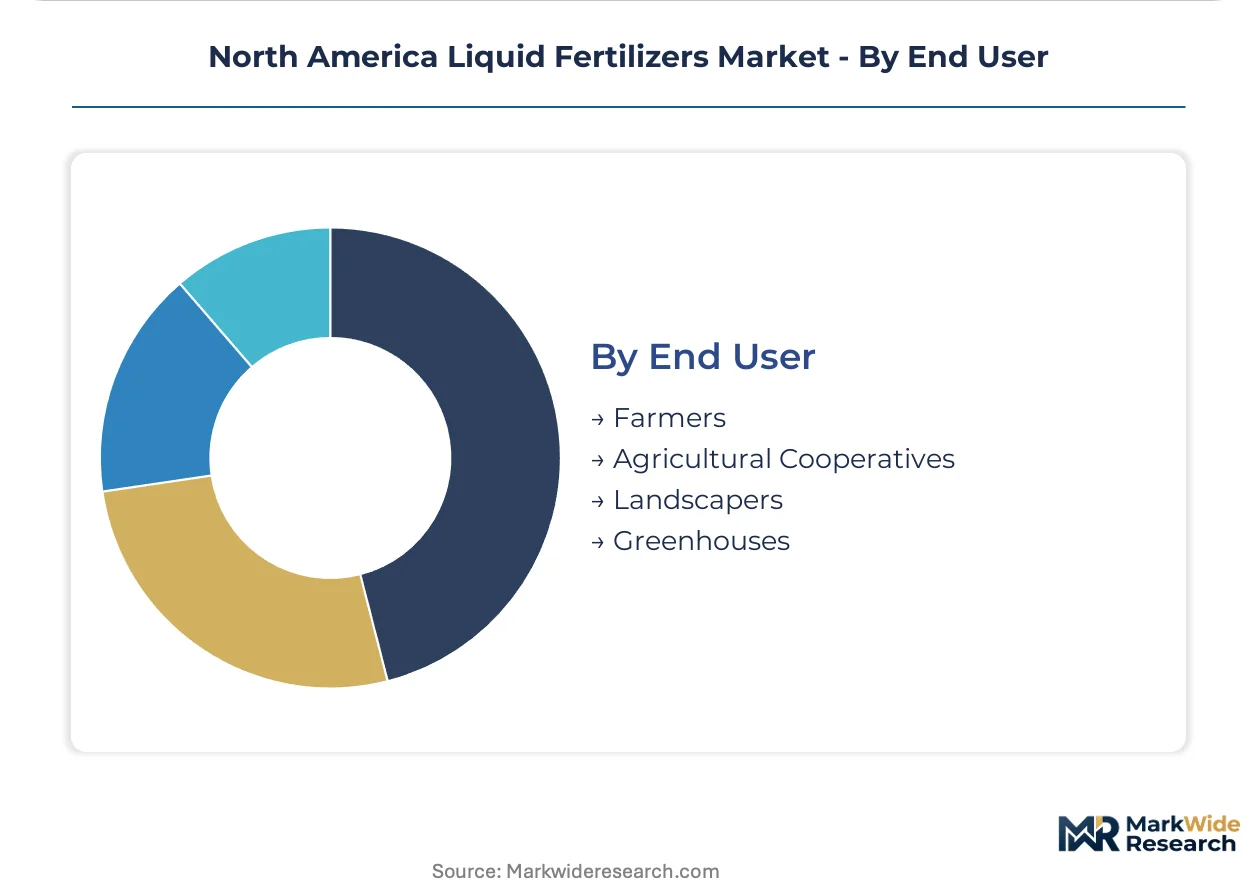
End User:
Capital intensity and technical sophistication separate commodity nitrogen buyers from customized blend seekers.
- Farmers:Individual operators below 5,000 acres rely on retail channels and standard UAN grades, with EPA Clean Water Act compliance documentation increasingly outsourced to applicator services.
- Agricultural Cooperatives:Consolidated buying entities across Iowa and Illinois command volume-based pricing tiers and bundled precision agriculture services, squeezing independent blender margins.
- Landscapers:Commercial turf maintenance contractors in Florida and Texas prioritize rapid green-up formulations with minimal irrigation requirement during establishment phases.
- Greenhouses:Controlled-environment vegetable producers in Mexico and the US Southwest demand complete hydroponic nutrient programs with pH-buffered calcium nitrate and chelated micronutrient packages.
Volume aggregates with agricultural cooperatives; customer expansion is gaining share fastest among greenhouses scaling hydroponic infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates along the Mississippi River corridor and Canadian prairie, while consumption clusters in intensive agricultural zones across the Corn Belt, California Central Valley, and Mexican greenhouse belts. The three-country configuration creates distinct regulatory and logistical dynamics shaping procurement patterns.
United States
Corn Belt cooperatives in Iowa and Illinois drive urea-ammonium nitrate volume through consolidated purchasing agreements. The EPA's Clean Water Act Total Maximum Daily Load framework tightens nutrient runoff compliance for watersheds draining into the Gulf of Mexico. California's Central Valley specialty vegetable operations are retrofitting drip irrigation systems for fertigation precision under tightening groundwater quality regulations.
Canada
Prairie wheat and canola programs across Alberta and Saskatchewan anchor nitrogen demand through spring and fall application windows. Health Canada's PMRA and the CFIA govern product registration, labeling, and contaminant limits for cross-border trade with US buyers. The Redwater, Alberta nitrogen complex supplies regional farm retail networks while terminal infrastructure along the Great Lakes-St. Lawrence corridor handles import-export flows.
Mexico
Hydroponic tomato and pepper producers in Sinaloa and Baja California greenhouse clusters are accelerating calcium nitrate consumption for fertigation programs. SEMARNAT implements ecological standards for aquifer protection in intensive agricultural zones, pressuring conventional fertilizer practices. Jalisco's berry expansion and the Bajío region's protected vegetable infrastructure are driving customized micronutrient blend demand.
North America Liquid Fertilizers Market Competitive Landscape
Top-tier vendors anchor terminal and vessel logistics along the Mississippi River corridor, while mid-scale blenders and regional distributors compete on formulation customization and just-in-time delivery. The vendor base stratifies across three archetypes: integrated nitrogen producers with captive feedstock, specialty micronutrient formulators serving high-value horticulture, and wholesale distributors aggregating fragmented retail demand. Dominant competitive moves include cooperative consolidation amplifying buyer leverage, and capacity investments in controlled-release polymer coating technology.
Among North American integrated producers, Nutrien Ltd. and CF Industries Holdings, Inc. exemplify the scale-driven archetype with terminal proximity to major agricultural demand centers. AgroLiquid occupies a position within the specialty formulation tier, representing customized micronutrient blending capabilities for fruit and vegetable producers. Yara International ASA anchors the international logistics vector, with vessel and terminal infrastructure supporting cross-border supply security.
| Leading Market Players |
|---|
| The Mosaic Company |
| AgroLiquid |
| Nutrien Ltd. |
| Kugler Company |
| Haifa Group |
| Yara International ASA |
| ICL Group |
| FoxFarm Soil & Fertilizer Company |
| CF Industries Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Cooperative purchasing consolidation across Iowa and Illinois is compressing independent blender margins and forcing supply-side adaptation toward volume-based contract structures. This buyer concentration dynamics is reshaping how nitrogen solutions are priced and distributed across the Corn Belt.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as compressed planting windows in Minnesota and Wisconsin reward just-in-time delivery capabilities. Three-tier pricing structure across premium, standard, and economy levels separates controlled-release polymer-coated formulations from commodity urea-ammonium nitrate and unbranded spot market purchases. Cost compression in the standard tier is intensifying because agricultural cooperatives wield consolidated procurement leverage against regional blenders. Individual farmers below 5,000 acres exhibit highest price sensitivity, while greenhouse operators in Mexico's Sinaloa cluster accept premium positioning for chloride-free calcium nitrate.
Supply Chain Analysis
CFIA certification requirements and EPA Clean Water Act compliance documentation create qualification gating that filters out smaller blenders unable to maintain regulatory infrastructure. Production draws from the United States, Canada, and Mexico, with nitrogen solution manufacturing anchored along the Mississippi River corridor and the Canadian prairie. Raw material dependencies include natural gas feedstock, phosphate rock imports, and specialized polymer coating inputs. Single-source vulnerability concentrates in Moroccan and Russian phosphate supply chains subject to trade friction. Distribution runs through wholesale distributors aggregating fragmented retail demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where cooperative buyer concentration and regulatory compliance burdens are systematically eliminating undercapitalized regional blenders.
For Market Incumbents: Extend terminal infrastructure along the Mississippi River corridor to defend against logistics bottlenecks during low-water events. Secure captive natural gas supply through backward integration into regional pipeline networks to buffer Henry Hub volatility. Invest in controlled-release polymer coating capacity to meet cooperative procurement specifications for split-application nitrogen programs. For New Entrants and Emerging Players: Capture the customized micronutrient blending white space serving high-value fruit producers in Michigan's Fruit Ridge and Washington's Yakima Valley. Target Mexico's Baja California greenhouse expansion with pH-buffered calcium nitrate formulations and technical agronomy support bundled with product supply. For Investors and Strategic Acquirers: Re-rating potential sits with specialty formulators possessing CFIA-registered micronutrient portfolios given tightening cross-border contaminant standards. Long-term viability favors assets with hydroponic nutrient program capabilities and established relationships with controlled-environment agriculture operators. Watch for inflection signals in SEMARNAT enforcement intensity around aquifer protection zones in Jalisco and the Bajío region.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Supply | Captive feedstock access insulates nitrogen production margins from Henry Hub price spikes. |
| Controlled-Release Polymer Coating Capacity Expansion | Meets cooperative procurement specifications for 4R Nutrient Stewardship compliance. |
| CFIA Registration Investment for Cross-Border Products | Unlocks Canadian prairie demand through compliant micronutrient formulation access. |
| Hydroponic Nutrient Program Development | Captures Mexico greenhouse expansion with complete pH-buffered calcium nitrate systems. |
| Terminal Infrastructure Along Mississippi River | Defends supply security against low-water logistics disruptions affecting vessel movements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fertilizer retail managers, cooperative procurement officers, agronomists, and EPA compliance consultants provided operational validation. Secondary sources included USDA conservation program documentation, EPA Total Maximum Daily Load enforcement records, CFIA product registration databases, and SEMARNAT ecological standard filings. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation between production capacity surveys, import-export trade flows, and end-user consumption patterns generated the analytical framework. Segmentation dimensions modeled include nutrient chemistry grade, crop application type, distribution channel tier, and end-user scale category. CAGRs derived from trend extrapolation of historical volume movements adjusted for regulatory inflection points and technology adoption curves. Industry-specific forecast inputs incorporated fertigation infrastructure deployment rates and cooperative merger activity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural gas feedstock volatility and evolving state-level carbon intensity scoring frameworks. Forecasts reflect documented assumptions regarding conservation program incentive continuity and cross-border regulatory harmonization progress. A model refresh is warranted upon material change in EPA Clean Water Act enforcement intensity or Mississippi River navigation conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
Europe Controlled Release Fertilizer Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Mineral Fertilizers Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
United States Fertilizers Market
Fertilizers
Global Foliar Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Global Urea Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Potash Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Brazil Fertilizers Market