
 Global Foliar Fertilizer Market | 2026-2036
Global Foliar Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foliar Fertilizer Market Foresight
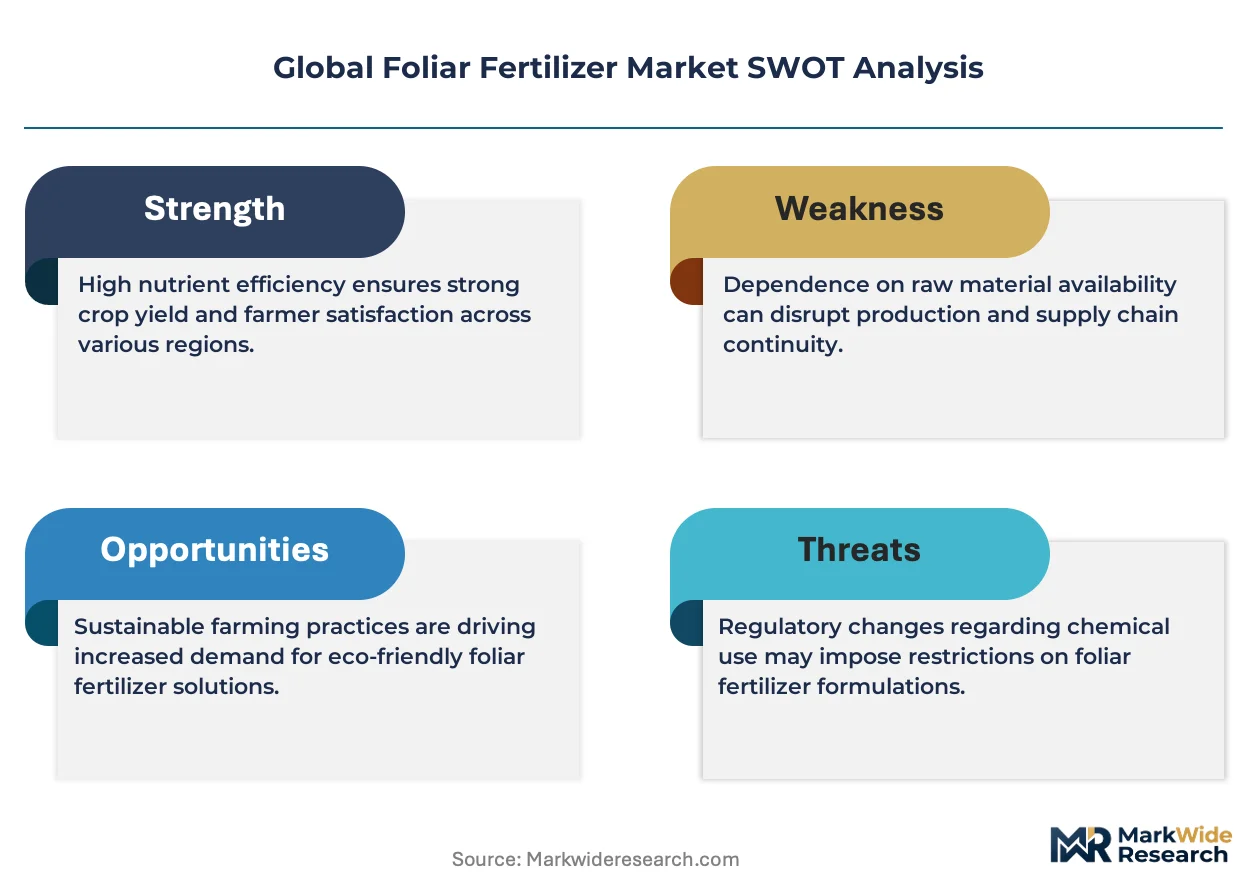
The EU Green Deal is realigning the cost-of-entry calculus for foliar fertilizer manufacturers targeting European commercial growers. Nutrien Ltd. leverages its integrated potash mining and distribution network to sustain cost advantages across nitrogen-based formulations. Yara International ASA anchors its position through controlled-release micronutrient technology leadership in horticultural applications. Haifa Group differentiates via specialized water-soluble powder production for greenhouse operators requiring precision dosing systems.
Foliar fertilizer denotes nutrient formulations applied directly to plant leaves for absorption through stomata and cuticular pathways, typically containing urea, phosphates, potassium compounds, or chelated trace elements in concentrations optimized for foliar uptake rather than root-zone application. Nitrogen-based products dominate volume due to established efficacy in cereal crop recovery phases, while micronutrient blends command premium positioning in specialty herb cultivation where deficiency correction drives yield quality. Biofertilizers represent the fastest-expanding category as organic farmers seek microbial inoculant alternatives to synthetic inputs under tightening residue protocols.
The EPA regulates foliar fertilizer registration and environmental release thresholds in the United States, while REACH governs chemical composition disclosures and hazard classifications across European supply chains. India's FSSAI and CDSCO jointly oversee contaminant limits in agricultural inputs destined for food crop applications, creating multi-jurisdictional compliance burdens for exporters. Stakeholders must monitor evolving carbon border adjustment mechanisms that threaten to reclassify energy-intensive nitrogen production as jurisdictions embed agricultural input emissions into trade policy frameworks.
Market Dynamics
Precision agriculture platforms are compressing application windows and demanding micronutrient formulations calibrated to real-time crop sensor data, forcing manufacturers to abandon standardized SKUs in favor of programmable nutrient cocktails.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Tightening permissible fertilizer residue thresholds compels Brazilian and Southeast Asian exporters to upgrade formulations for European market access.
- Controlled-release chelation technology:Horticultural operators in Spain and the Netherlands deploy precision dosing systems that extend nutrient availability windows during critical flowering phases.
- Brazil's Cerrado soybean belt:Intensive double-cropping regimes deplete soil micronutrient stocks, generating sustained demand for foliar zinc and manganese correction programs.
Market Restraints
- Natural gas price volatility:Nitrogen-based urea production remains tethered to European and Asian LNG spot markets, compressing margin predictability for formulation specialists.
- Phosphate rock concentration:Moroccan and Chinese state-controlled suppliers dominate upstream phosphate reserves, exposing downstream blenders to supply rationing risks.
- Cuticular penetration limits:Leaf surface hydrophobicity restricts micronutrient absorption efficiency below root-zone delivery rates for certain crop phenologies.
Strategic Opportunities
- India's FSSAI contaminant protocols:Stringent heavy metal limits for food crop inputs create first-mover advantages for certified low-impurity formulation exporters.
- Drone-based variable-rate application:Brazilian and Australian broadacre operators integrate aerial platforms with prescription maps for spatially targeted nutrient delivery.
- Biofertilizer microbial inoculants:Organic certification requirements under USDA NOP and EU 2018/848 drive substitution demand away from synthetic nitrogen sources.
Industry Challenges
- REACH dossier compilation timelines:European chemical substance registrations demand 18-24 month preparation cycles for novel chelating agent introductions.
- Legacy soil testing infrastructure incompatibility:Regional agronomic laboratories lack standardized foliar tissue analysis protocols, fragmenting recommendation credibility across advisory networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foliar Fertilizer Market |
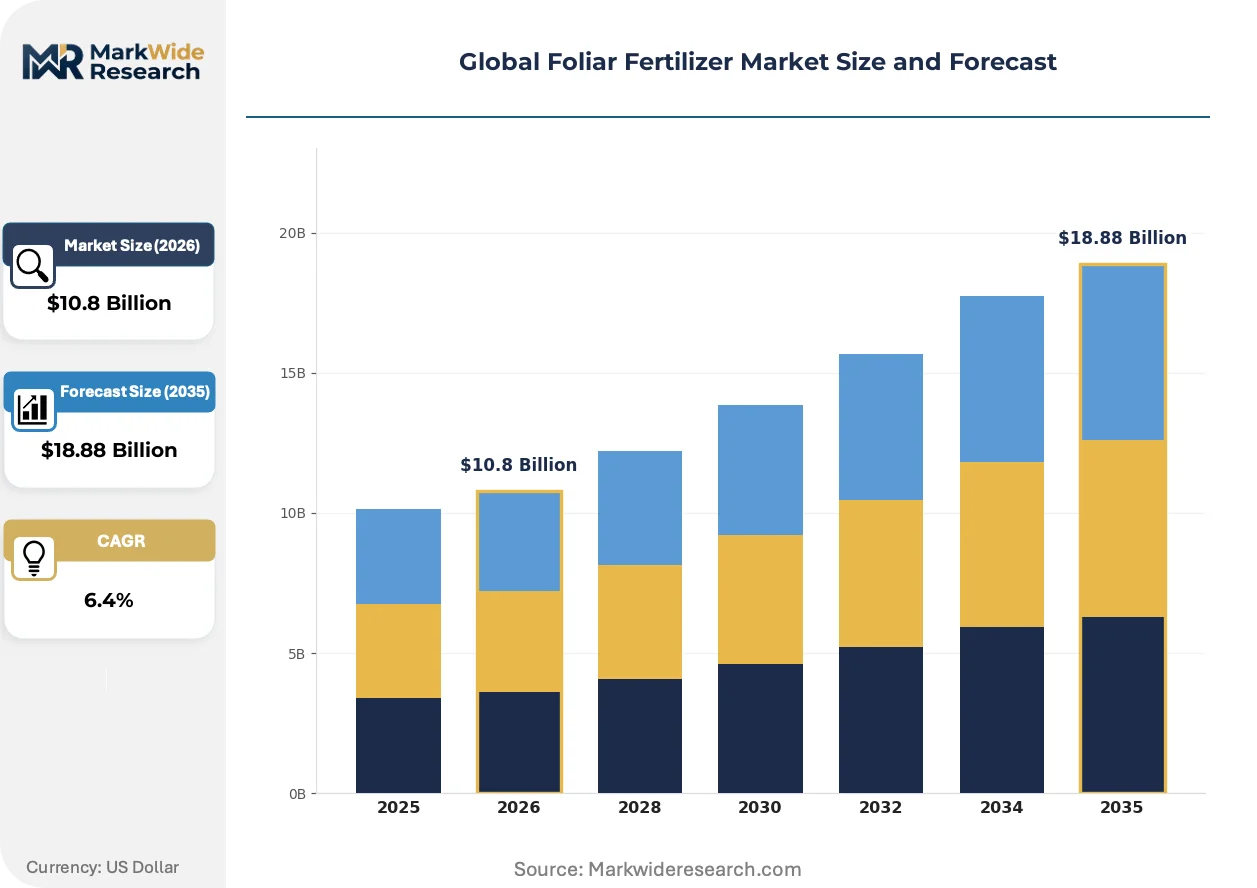
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen-Based, Phosphorus-Enriched, Potassium-Infused, Micronutrient Blends, Biofertilizers Application: Cereal Crops, Horticultural Plants, Oilseed Cultivation, Fiber Crops, Specialty Herbs Packaging Type: Liquid Concentrates, Water-Soluble Powders, Granules, Sachets, Bulk Containers End User: Commercial Growers, Greenhouse Operators, Organic Farmers, Research Institutes |
| Companies Covered | Sociedad Química y Minera de Chile SA, Nutrien Ltd., Yara International ASA, AgroLiquid, J.R. Simplot Company, The Mosaic Company, Indian Farmers Fertiliser Cooperative Limited, Haifa Group, ICL Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foliar Fertilizer Market Shifts & Advancements
Digital agriculture ecosystems are collapsing the distance between nutrient prescription and application execution, embedding foliar formulations within closed-loop crop management platforms rather than standalone input categories.
Hyperspectral imaging coupled with machine learning algorithms is automating real-time canopy stress detection across California almond orchards and Australian wheat belts. Large-scale cooperatives deploy tractor-mounted sensors that trigger variable-rate foliar nitrogen applications within 24-hour windows. This compression of sensing-to-spray intervals is automating inventory management for regional distributors who must position formulations closer to field edges.
REACH authorization requirements for persistent organic pollutant precursors are forcing reformulation of certain organophosphate chelators used in specialty horticulture. ECHA substance evaluation deadlines in 2026-2027 are accelerating substitution toward biodegradable complexing agents. Greenhouse operators in Belgium and Denmark face the steepest compliance curves given their reliance on high-frequency micronutrient programs.
Direct-to-farm procurement platforms are disintermediating traditional agricultural retail cooperatives in Brazil's Mato Grosso and Goiás states. Grower associations negotiate volume contracts with formulation manufacturers through digital tendering systems that transparentize pricing. This channel restructuring concentrates purchasing power among fewer buyer entities while fragmenting last-mile logistics requirements across rural road networks.
Global Foliar Fertilizer Market Segmentation
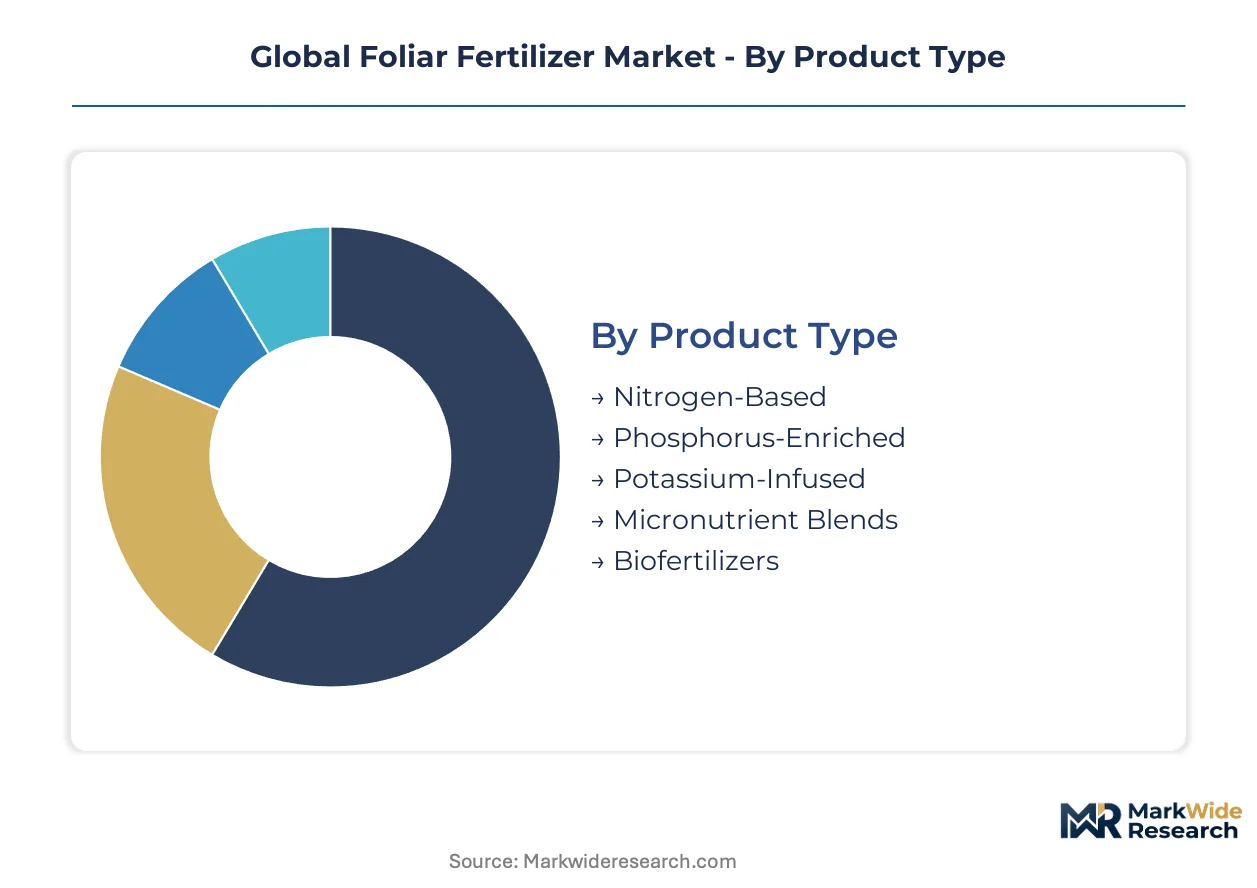
Foliar fertilizer segmentation reveals distinct integration patterns across product portfolios. Nutrient chemistry determines compatibility with precision delivery systems. Application context dictates formulation specifications and service intensity requirements.
Product Type:
Nitrogen-based formulations operate as standalone recovery inputs, while micronutrient and biofertilizer categories embed within integrated crop management protocols.
- Nitrogen-Based:Urea-based solutions dominate volume through established efficacy in cereal crop vegetative stages. Demand concentrates in Brazil's Cerrado soybean belt where intensive double-cropping depletes soil reserves and foliar nitrogen bridges yield gaps during reproductive phases.
- Micronutrient Blends:Chelated zinc, manganese, and boron formulations target deficiency correction in high-value horticultural systems. Spanish and Dutch greenhouse operators deploy these through precision dosing systems calibrated to real-time sensor data during critical flowering windows.
- Phosphorus-Enriched:Phosphate compounds support root development and energy transfer functions in oilseed establishment phases.
- Potassium-Infused:Potassium chloride and sulfate variants address drought stress tolerance in fiber crop regions with erratic precipitation.
- Biofertilizers:Microbial inoculant alternatives attract organic certification requirements under USDA NOP and EU 2018/848 protocols.
Volume placements concentrate in Nitrogen-Based formulations; the faster expansion belongs to Biofertilizers.
Application:
Application segmentation tracks cultivation intensity gradients from broadacre commodity systems to controlled-environment specialty production.
- Cereal Crops:Wheat, rice, and maize applications leverage foliar nitrogen for grain filling optimization. Australian wheat belts deploy tractor-mounted sensors triggering variable-rate applications within compressed 24-hour windows.
- Specialty Herbs:Basil, mint, and medicinal herb cultivation demands micronutrient precision for essential oil concentration and phytochemical profiles. California almond orchards integrate hyperspectral imaging with machine learning for automated canopy stress detection.
- Horticultural Plants:Vegetable and fruit operations in Belgium and Denmark face steep ECHA compliance curves for chelator substitutions.
- Oilseed Cultivation:Soybean and canola producers in Brazil's Mato Grosso negotiate direct-to-farm procurement contracts through digital tendering platforms.
- Fiber Crops:Cotton systems in India operate under FSSAI heavy metal limits that create first-mover advantages for certified low-impurity exporters.
Revenue concentration sits with Cereal Crops; Specialty Herbs command the steepest premium expansion.
Packaging Type:
Packaging configurations align with farm scale and application technology infrastructure across distribution networks.
- Liquid Concentrates:Ready-to-use or dilutable formulations dominate commercial grower procurement through compatibility with drone-based variable-rate systems. Brazilian broadacre operators integrate aerial platforms with prescription maps for spatially targeted delivery.
- Water-Soluble Powders:Dry concentrate formats serve greenhouse operators requiring precision dosing flexibility. Haifa Group specializes in this category for controlled-environment systems.
- Granules:Slow-release particulate forms suit research institute trial protocols and legacy application equipment.
- Sachets:Single-use packaging addresses smallholder access and reduces contamination risks in remote storage conditions.
- Bulk Containers:Tanker and tote deliveries support cooperative purchasing consolidation in Brazil's Goiás state grower associations.
Procurement scale favors Liquid Concentrates; Water-Soluble Powders retain the highest margin structure.
End User:
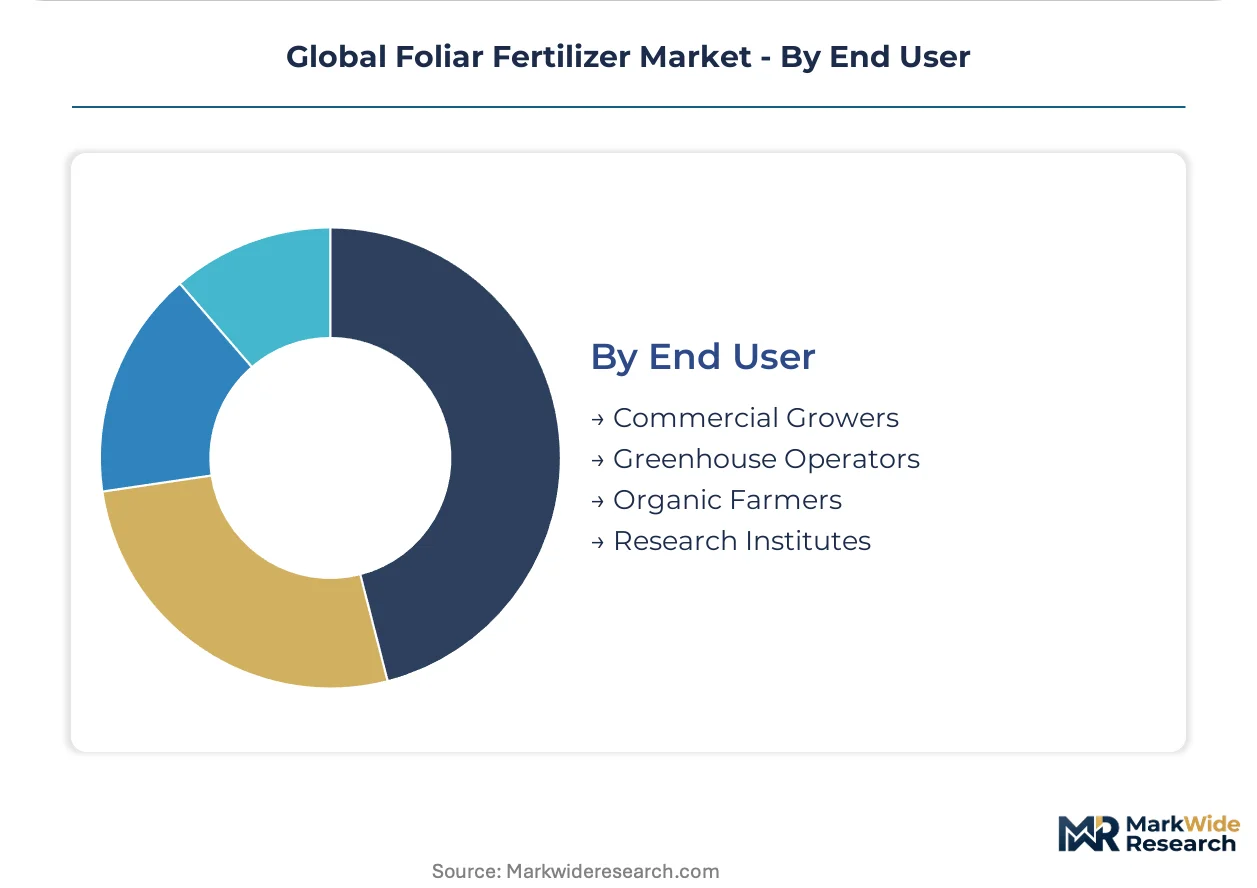
End user categories reflect divergent purchasing sophistication and regulatory exposure profiles.
- Commercial Growers:Large-scale operations in Australia's wheat belts and Brazil's Cerrado drive volume through digital procurement platforms that disintermediate traditional agricultural retail cooperatives.
- Greenhouse Operators:Controlled-environment specialists in Spain and the Netherlands deploy controlled-release chelation technology extending nutrient availability during critical flowering phases.
- Organic Farmers:Certification requirements under tightening residue protocols accelerate substitution toward biofertilizer microbial inoculants.
- Research Institutes:Trial infrastructure demands standardized formulations with documented batch consistency for reproducible agronomic studies.
Transaction volume aggregates with Commercial Growers; Greenhouse Operators generate the highest formulation complexity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's MATOPIBA agricultural frontier operates as a special economic zone for agribusiness, concentrating foliar fertilizer demand from double-cropping soybean operations that deplete micronutrient stocks across the Cerrado biome.
Brazil
Intensive soybean-corn rotation in Mato Grosso and Goiás drives zinc and manganese correction programs. ANVISA regulates agricultural input contaminant limits for food crop applications. Digital procurement platforms in Goiás disintermediate traditional cooperatives as grower associations negotiate direct manufacturer contracts.
United States
California almond orchards deploy hyperspectral imaging for automated canopy stress detection triggering foliar nitrogen applications. EPA registration requirements govern environmental release thresholds for nutrient formulations. The Central Valley's precision agriculture clusters integrate tractor-mounted sensors with 24-hour application windows.
India
Cotton systems in Gujarat and Maharashtra operate under FSSAI heavy metal limits creating certification advantages for low-impurity exporters. CDSCO and FSSAI jointly oversee contaminant protocols for food crop inputs. The Godavari delta's rice belts generate sustained demand for urea-based foliar recovery programs during grain filling phases.
Spain
Greenhouse operators in Almería deploy controlled-release chelation technology extending nutrient availability during tomato flowering windows. REACH governs chemical composition disclosures and hazard classifications for European supply chains. The Murcia region's intensive horticulture clusters face ECHA 2026-2027 deadlines for biodegradable complexing agent substitutions.
Australia
Wheat belt cooperatives integrate drone-based variable-rate systems with prescription maps for spatially targeted nutrient delivery. The country's national agricultural regulator oversees input safety standards for broadacre cereal production. Western Australia's grain-growing regions compress sensing-to-spray intervals through automated inventory positioning at field edges.
Global Foliar Fertilizer Market Competitive Landscape
North American integrated producers anchor one tier; European and Israeli specialists hold differentiated positions through controlled-release technology and water-soluble formats. The vendor base separates between mining-backed nitrogen formulators and precision horticulture micronutrient blenders. Three archetypes dominate: upstream-integrated commodity suppliers, chelation technology specialists, and biofertilizer microbial innovators. Competitive dynamics center on direct-to-farm channel expansion and REACH-compliant reformulation cycles.
Within the mining-integrated tier, Nutrien Ltd. and The Mosaic Company represent upstream resource control strategies. Yara International ASA and Haifa Group exemplify technology-differentiated positioning through specialized formulation capabilities. Sociedad Química y Minera de Chile SA anchors the lithium-iodine chemical complex that supplies specialty agricultural mineral inputs.
| Leading Market Players |
|---|
| Sociedad Química y Minera de Chile SA |
| Nutrien Ltd. |
| Yara International ASA |
| AgroLiquid |
| J.R. Simplot Company |
| The Mosaic Company |
| Indian Farmers Fertiliser Cooperative Limited |
| Haifa Group |
| ICL Group |
| Others |
Supply & Pricing Matrix
Formulation chemist concentrations in Germany's Rhineland and India's Gujarat feed labor-cost differentials into pricing-tier spreads across European and Asian manufacturing bases. Premium-mid-economy pricing differentiation separates REACH-compliant micronutrient blends from commodity urea formulations, with labor-intensive chelation processes commanding sustained margin premiums.
Pricing Analysis
Short lead-time premiums apply to drone-compatible liquid concentrates positioned for Brazilian soybean operators facing compressed application windows. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with organic-certified biofertilizers extracting brand premiums. Cost compression in nitrogen-based urea runs through European LNG spot market exposure. Smallholder cooperatives in India's cotton belt exhibit highest price sensitivity; greenhouse operators in Spain and the Netherlands demonstrate lowest sensitivity due to yield-quality optimization priorities.
Supply Chain Analysis
Phosphate rock supply rests on Moroccan state-controlled reserves and Chinese state-owned mining operations, with Chilean lithium-iodine complexes feeding specialty mineral inputs. Upstream dependencies center on natural gas for urea synthesis, phosphate rock for phosphorus enrichment, and chelating agent precursors for micronutrient formulations. Single-source vulnerability concentrates in Moroccan phosphate exports subject to export quota rationing. Distribution runs through agricultural retail cooperatives in legacy markets and direct-to-farm digital platforms in Brazil's Mato Grosso and Goiás states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where upstream control over phosphate rock and natural gas feedstocks determines margin capture against spot-market volatility.
For Market Incumbents: Anchor position through backward integration into phosphate mining partnerships or captive natural gas offtake agreements. Biofertilizer microbial innovators threaten substitution demand under EU 2018/848 organic certification protocols; incumbents must accelerate chelator reformulation cycles ahead of ECHA 2026-2027 deadlines. Priority lever sits with channel control via direct-to-farm platform investments in Brazil's digital procurement corridors. For New Entrants and Emerging Players: Enter via India's FSSAI-certified low-impurity formulation segment where heavy metal compliance creates first-mover certification advantages. Cotton systems in Gujarat and Maharashtra represent the most penetrable geography given stringent contaminant protocols and limited certified supplier bases. Go-to-market angle should leverage drone-based variable-rate application partnerships with Brazilian broadacre cooperatives seeking spatially targeted nutrient delivery. For Investors and Strategic Acquirers: Re-rating potential sits with chelation technology specialists given REACH-driven reformulation cycles and biodegradable complexing agent substitution mandates. Long-term viability frames around 5-10 year windows where precision agriculture platform integration determines formulation commoditization resistance. Acquisition target archetype: water-soluble powder specialists serving greenhouse operators with precision dosing requirements. Signal to watch: ECHA substance evaluation deadlines accelerating substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Captive supply of Moroccan or Chinese phosphate rock secures margin against state-controlled export rationing. |
| Biodegradable Chelator Development | REACH-compliant complexing agents address ECHA 2026-2027 deadlines for greenhouse operator retention. |
| Direct-to-Farm Platform Expansion | Digital procurement penetration in Brazil's Mato Grosso disintermediates legacy cooperative channels. |
| Drone-Compatible Liquid Concentrate Scale-Up | Aerial application compatibility captures Brazilian soybean operator demand for variable-rate delivery. |
| FSSAI Certification Investment | Low-impurity formulation credentials unlock India's cotton and rice belt procurement decisions. |
Research Methodology
Independent corroboration across formulation plant managers, agricultural cooperative procurement leads, greenhouse operator technical directors, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from ANVISA regulatory filings, REACH dossier submissions, FSSAI contaminant protocol documents, and customs trade data for phosphate rock and urea movements. Bottom-up segmentation modeling triangulates against top-down macroeconomic agricultural input demand indicators.
Comparable-period anchoring against historical fertilizer consumption patterns and precision agriculture adoption curves structures the projection horizon. Segmentation dimensions span nutrient chemistry, application context, packaging format, and regional regulatory cluster. CAGRs derive from fitted growth curves across the modeling period, with inputs including natural gas price volatility indices, phosphate rock export quota trends, and drone-based application penetration rates in Brazilian broadacre systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Moroccan phosphate export restrictions or EU carbon border adjustment mechanism implementation. Assumptions reflect sustained double-cropping intensity in Brazil's Cerrado and continued tightening of residue protocols under EU Farm to Fork strategy. A small set of named triggers warrants ongoing watch: ECHA substance evaluation timelines, Indian FSSAI enforcement intensity, and Brazilian digital procurement platform consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Brazil Micronutrient Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Egypt Fertilizer Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Thailand Fertilizers Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Soil Conditioners Market
Fertilizers
Urea Fertilizers Market
Fertilizers
China Fertilizers Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Global Complex Fertilizers Market