
 Middle East and Africa Micronutrient Fertilizer Market | 2026-2036
Middle East and Africa Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Micronutrient Fertilizer Market Foresight
Sulfur is restructuring micronutrient formulation economics as manufacturers reduce phosphate binder dependence and shift toward sulfate-based chelation systems. Haifa Group leverages its Dead Sea mineral extraction infrastructure to sustain captive supplies of zinc and manganese precursors. Yara International anchors its MEA position through integrated ammonia-to-micronutrient complexes on the Arabian Gulf. SABIC competes via petrochemical-derived sulfuric acid integration that feeds regional micronutrient sulfate production.
Micronutrient fertilizers deliver essential trace elements—iron, zinc, manganese, copper—typically at concentrations below one percent by weight, to correct soil deficiencies and optimize enzymatic functions in plant metabolism. These products are manufactured through crystallization, granulation, or chelation with synthetic organic ligands such as EDTA to enhance bioavailability under alkaline soil conditions prevalent across arid MEA regions. Zinc products lead the product type landscape due to widespread deficiency in calcareous soils across North Africa and the Levant. Foliar spray delivery dominates application mode selection where soil fixation risks render soil application inefficient, particularly for iron and manganese in high-pH environments. Agri-input companies represent the fastest-growing customer channel as consolidated farm operations bypass traditional distributor tiers and contract directly for bulk micronutrient blends.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces fertilizer registration under the Fertilizers, Farm Feeds, Seeds and Remedies Act, while Saudi Arabia's SFDA oversees import quality certification for micronutrient products entering the Kingdom. These frameworks shape demand by mandating guaranteed analysis labeling and restricting unregistered chelating agents. Egypt's Ministry of Agriculture and Land Reclamation operates parallel inspection protocols for Nile Delta imports that create additional compliance layers for foreign suppliers. Stakeholders must monitor evolving heavy-metal thresholds in national fertilizer standards and assess backward integration into sulfuric acid or mining assets to secure formulation cost stability against volatile raw material cycles.
Market Dynamics
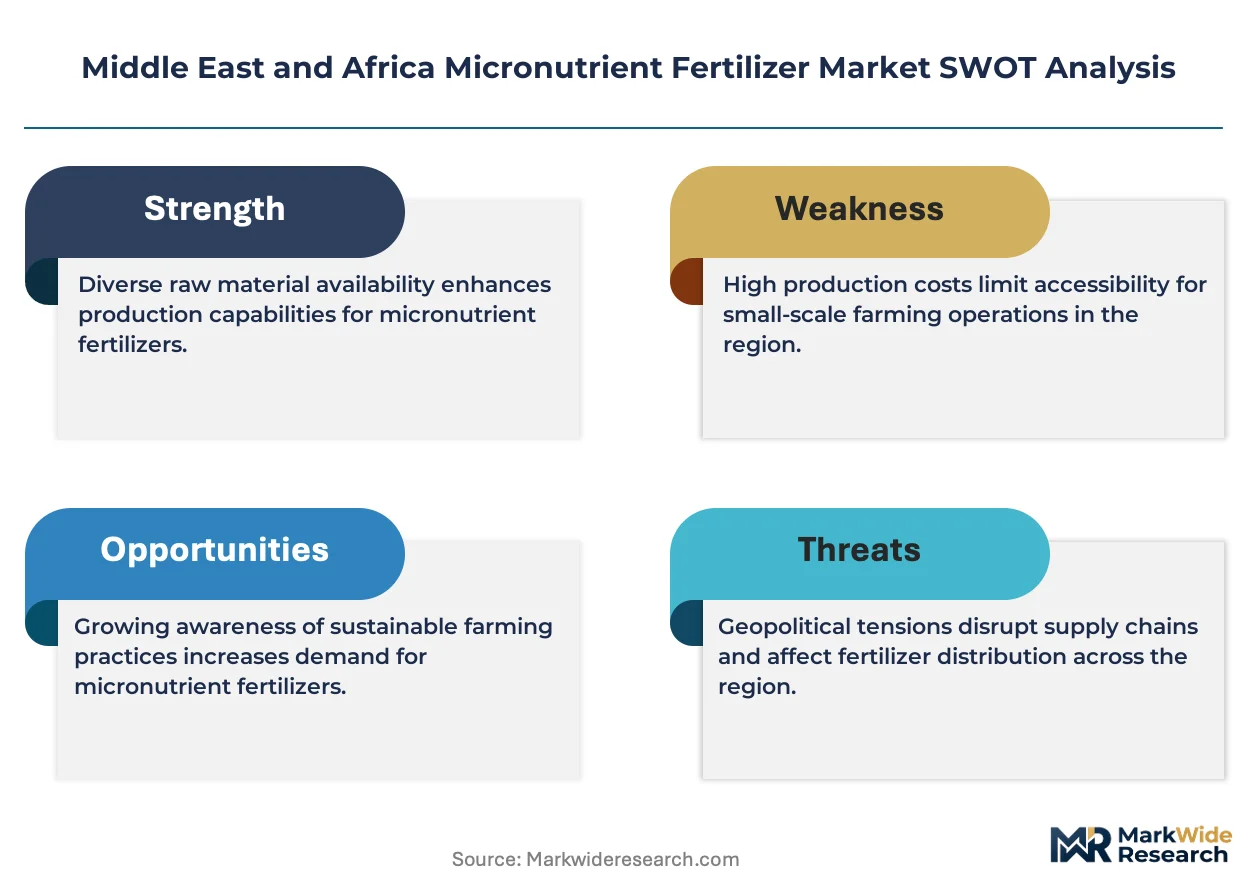
Sulfate-based chelation systems are displacing phosphate binders across MEA formulation plants, restructuring input cost profiles and supply security calculations for regional micronutrient manufacturers.
Growth Catalysts
- SFDA Import Certification:Saudi Arabia's quality mandates for micronutrient products entering the Kingdom filter out substandard imports, consolidating demand around registered suppliers with guaranteed analysis labeling.
- Citrus Orchard Precision Programs:South African citrus growers expand foliar micronutrient schedules to meet EU export residue thresholds, driving volume through specialized agri-input channels.
- Nile Delta Intensive Cropping:Egypt's vegetable production zones face acute zinc and iron depletion from multi-cropping cycles, forcing systematic trace element replenishment protocols.
Market Restraints
- Sulfur Price Volatility:Petrochemical-derived sulfuric acid feedstock costs fluctuate with crude oil cycles, squeezing sulfate-based micronutrient margins unpredictably.
- Dead Sea Concentration Risk:Captive mineral extraction infrastructure for zinc and manganese precursors concentrates supply geography, exposing buyers to geopolitical and climatic disruption.
- High-pH Soil Fixation:Calcareous soils across North Africa and the Levant immobilize soil-applied iron and manganese, forcing costlier foliar delivery modes.
Strategic Opportunities
- Kenyan Highlands Underpenetration:Tea and coffee smallholder cooperatives lack systematic micronutrient programs, presenting white-space expansion for bulk blend suppliers.
- EU Green Deal Export Alignment:Tightening residue and input standards for MEA agricultural exports create compliance-service bundling opportunities around certified micronutrient packages.
- Direct Farm Contracting:Consolidated South African and Saudi farm operations bypass distributor tiers, opening channel innovation for agri-input companies delivering customized bulk blends.
Industry Challenges
- Multi-Jurisdiction Registration Burden:Egypt's parallel inspection protocols for Nile Delta imports layer compliance complexity atop Saudi SFDA and South African Fertilizers Act requirements, stretching regulatory affairs capacity.
- Chelating Agent Substitution Complexity:Heavy-metal threshold tightening in national fertilizer standards forces reformulation investments, with EDTA alternatives requiring agronomic revalidation under local soil conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Micronutrient Fertilizer Market |
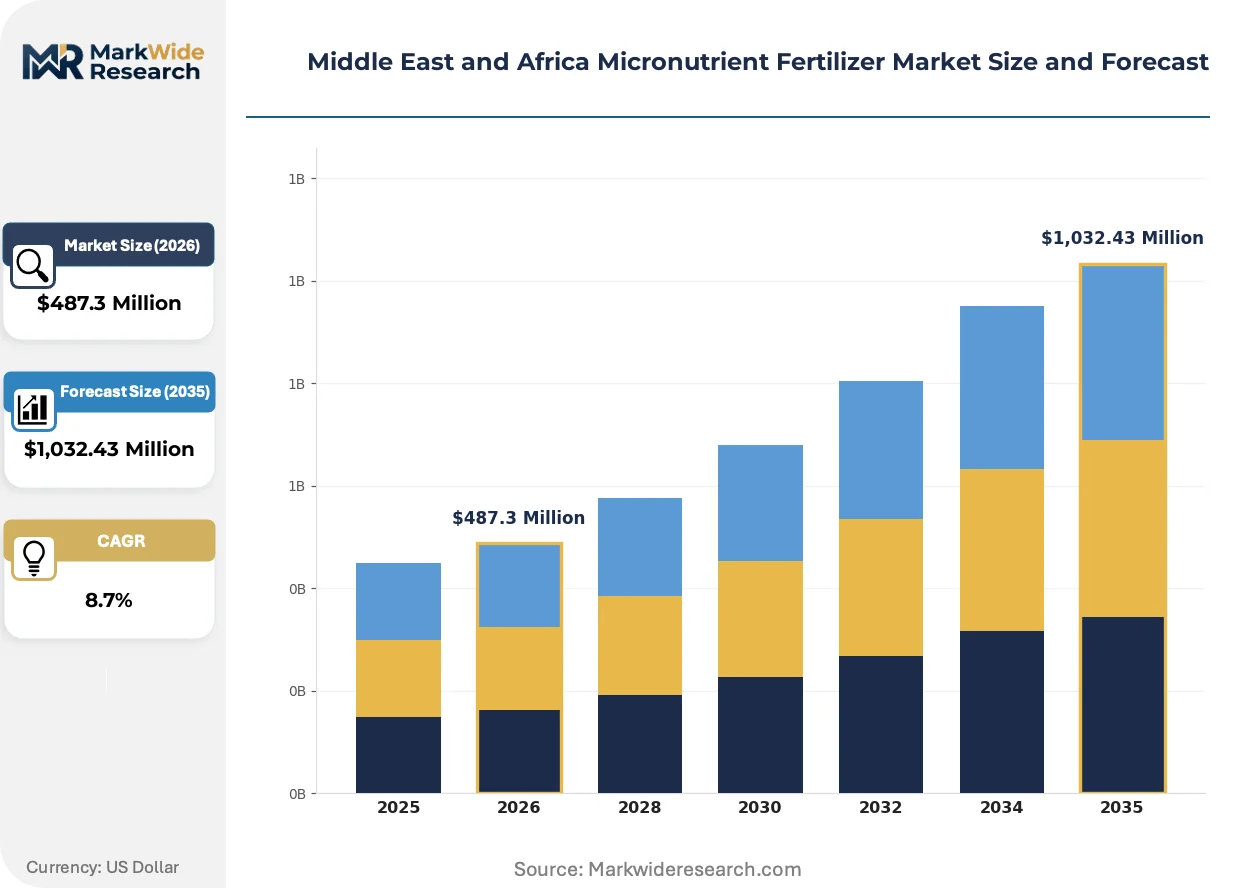
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron, Zinc, Manganese, Copper Application: Agricultural, Horticultural, Turf, Ornamental Delivery Mode: Foliar Spray, Soil Application, Fertigation, Granular Customer Type: Farmers, Distributors, Retailers, Agri-Input Companies |
| Companies Covered | Nutrien Ltd., Yara International, The Mosaic Company, Haifa Group, SABIC, ICL Group Ltd., BASF SE, K+S Aktiengesellschaft, Unikeyterra Chemical, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Micronutrient Fertilizer Market Shifts & Advancements
Formulation chemistry and delivery systems are converging around bioavailability optimization under alkaline soil constraints, while regulatory alignment with European export standards reshapes product certification priorities.
Controlled-release coating technology for micronutrient granules is modularizing application flexibility across MEA's diverse irrigation infrastructures. Israeli and UAE desert agriculture operators adopt these systems to synchronize nutrient release with drip irrigation pulses. The technology compresses labor input requirements while stabilizing uptake efficiency in sandy, high-pH soils where conventional applications leach rapidly.
EU Green Deal residue standards exert indirect force on MEA export-oriented agriculture through supermarket chain procurement specifications. Egyptian and Moroccan vegetable exporters face mandatory input documentation proving micronutrient provenance and heavy-metal compliance. Foliar spray suppliers with EU-recognized organic chelation certifications capture preferential positioning in Nile Delta and Souss Valley sourcing contracts.
Consolidated farm operations in South Africa and Saudi Arabia now contract directly with micronutrient blenders, disintermediating traditional distributor networks. Large citrus and date palm estates negotiate volume-based pricing and customized formulation services previously channeled through regional agro-dealers. This pattern concentrates procurement leverage among fewer buyers while rewarding suppliers with integrated technical advisory capabilities and captive sulfuric acid or mineral precursor assets.
Middle East and Africa Micronutrient Fertilizer Market Segmentation
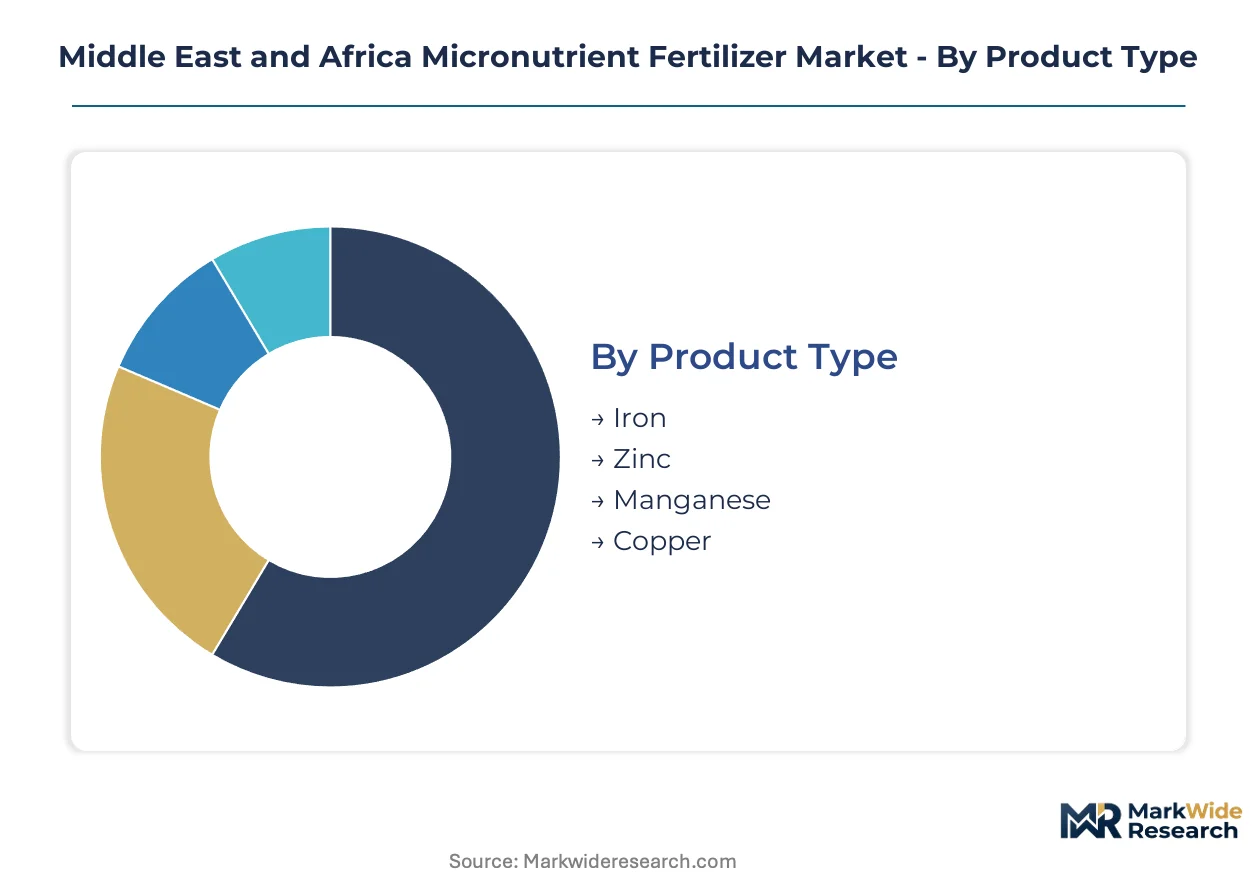
Micronutrient fertilizer segmentation in the Middle East and Africa reveals distinct technical and commercial fault lines. Product chemistry, application context, delivery infrastructure, and procurement channel each reshape margin structures and competitive positioning across Egypt's Nile Delta, South African citrus belts, and Saudi Arabian date palm estates.
Product Type:
Replacement cycles for micronutrient formulations accelerate as sulfur-based chelation systems displace legacy phosphate binders, forcing growers to reassess product economics.
- Zinc:Sulfate and oxide formulations dominate calcareous soil correction programs across North Africa and the Levant. Egyptian vegetable producers in the Nile Delta deploy systematic zinc replenishment to counter multi-cropping depletion.
- Iron:Chelated iron products using EDTA or alternative ligands address chlorosis in high-pH environments where soil fixation renders conventional applications ineffective. Foliar delivery dominates uptake in Saudi Arabian and UAE desert agriculture.
- Manganese:Manganese sulfate serves enzymatic activation requirements in South African citrus orchards meeting EU export residue thresholds.
- Copper:Copper sulfate applications concentrate in fungicidal and nutritional dual-use scenarios across Moroccan and Tunisian cereal zones.
Zinc sits at the top of the volume ranking, with iron climbing the fastest as alkaline soil fixation forces chelated product upgrades.
Application:
Cost tier stratification separates commodity field crops from high-value export-oriented systems with precision input requirements.
- Agricultural:Broadacre cereal and oilseed operations across Morocco, Tunisia, and Sudan apply bulk micronutrient blends through conventional soil incorporation. Price sensitivity limits chelated product penetration outside deficiency hotspots.
- Horticultural:Egyptian and Moroccan vegetable exporters facing EU Green Deal procurement specifications invest in certified organic chelation systems. Documentation requirements for residue compliance drive premium product selection.
- Turf:Golf course and sports field maintenance across UAE, Qatar, and South African urban centers demands rapid green-up response. Soluble sulfate formulations serve high-frequency foliar schedules.
- Ornamental:Nursery and landscape operations in Saudi Arabian and Kuwaiti markets prioritize visual deficiency correction over yield optimization.
Agricultural applications generate baseline volume, while horticultural segments are expanding most quickly under export compliance pressure.
Delivery Mode:
Customer type concentration among large farm estates and cooperatives favors delivery systems compatible with mechanized or precision irrigation infrastructure.
- Foliar Spray:Aerial and ground-based foliar systems bypass soil fixation risks for iron and manganese in high-pH North African and Levantine soils. South African citrus precision programs rely on calibrated spray timing aligned with phenological stages.
- Fertigation:Drip-integrated soluble micronutrients synchronize with Israeli and UAE desert agriculture pulse irrigation. Controlled-release coatings stabilize nutrient availability in sandy substrates prone to leaching.
- Soil Application:Granular and bulk-blended soil products serve conventional tillage systems across Sudanese and Ethiopian smallholder contexts where irrigation infrastructure remains limited.
- Granular:Coated granular micronutrients target labor-constrained operations seeking single-pass application compatibility with macronutrient fertilization.
Foliar spray commands the volume lead, with fertigation gaining share fastest as drip irrigation expands across Gulf Cooperation Council agriculture.
Customer Type:
Supply concentration around captive mineral extraction and sulfuric acid integration favors direct relationships with volume purchasers over fragmented retail channels.
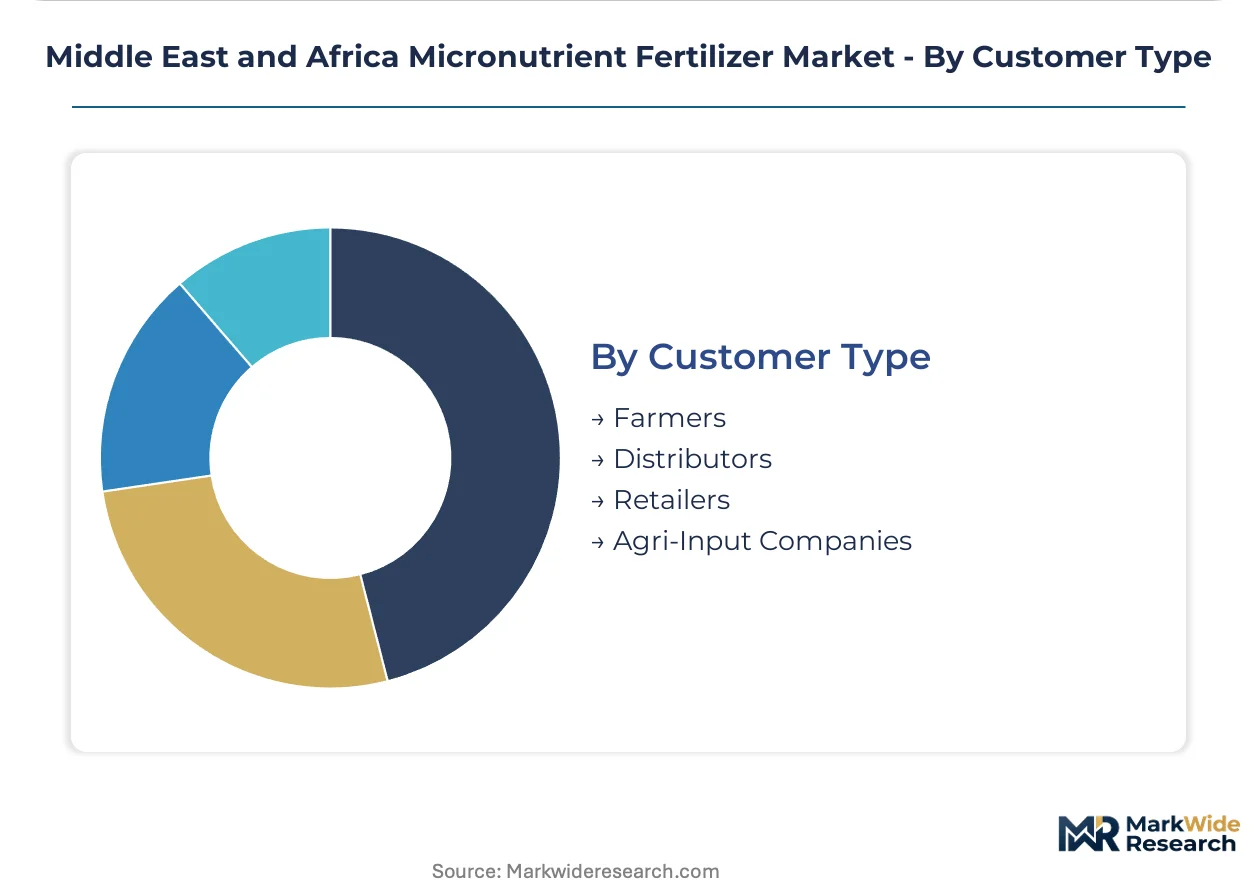
- Agri-Input Companies:Consolidated South African citrus estates and Saudi Arabian date palm operations contract directly for customized bulk blends and technical advisory services. Procurement leverage concentrates among fewer buyers with specialized formulation requirements.
- Farmers:Egyptian smallholders in the Nile Delta access micronutrients through cooperative purchasing arrangements. Price sensitivity and credit constraints limit premium chelated product adoption.
- Distributors:Regional agro-dealer networks in Kenya, Tanzania, and Ethiopia face disintermediation pressure as large estates bypass traditional tiers. Inventory financing and technical support capabilities determine survival.
- Retailers:Independent input retailers serve fragmented smallholder demand across West African and East African markets with limited product differentiation.
Agri-input companies anchor current volume, with farmer cooperatives showing the steepest expansion trajectory as consolidation accelerates procurement professionalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nile Delta anchors micronutrient demand across the Middle East and Africa, with intensive vegetable production depleting zinc and iron reserves from multi-cropping cycles. Egyptian vegetable exporters face mounting pressure to document input provenance for EU supermarket procurement specifications. Four national markets concentrate distinct supply chain configurations and regulatory environments.
Egypt
Nile Delta vegetable zones drive systematic zinc replenishment protocols as intensive cropping strips trace elements from alluvial soils. The Ministry of Agriculture and Land Reclamation operates parallel inspection protocols for imports that layer compliance complexity atop standard registration requirements. Alexandria and Damietta port clusters handle bulk sulfate formulations for domestic blending operations serving cooperative purchasing networks.
Saudi Arabia
Date palm estates across the Eastern Province expand precision foliar schedules to sustain yields in high-pH desert substrates. SFDA import certification mandates filter substandard products, consolidating procurement around registered suppliers with guaranteed analysis labeling. Riyadh-based agri-input companies negotiate direct contracts with consolidated farm operations, bypassing traditional distributor tiers.
South Africa
Citrus belt operations in Limpopo and Mpumalanga provinces scale micronutrient programs to meet EU export residue thresholds under the Fertilizers, Farm Feeds, Seeds and Remedies Act. The Department of Agriculture enforces registration requirements that shape demand through guaranteed analysis labeling mandates. Cape Town logistics hubs coordinate specialized foliar formulations for precision orchard applications.
Israel
Desert agriculture operators in the Negev and Arava valleys adopt controlled-release coating technology to synchronize nutrient delivery with drip irrigation pulses. Dead Sea mineral extraction infrastructure sustains captive supplies of zinc and manganese precursors for regional formulation plants. Haifa Group leverages this geographic concentration to supply sulfate-based chelation systems across Levantine markets.
Morocco
Souss Valley vegetable exporters invest in certified organic chelation systems to satisfy EU Green Deal procurement specifications from supermarket chains. The country's national agricultural regulator enforces heavy-metal thresholds that force reformulation investments among foreign suppliers. Casablanca formulation plants blend copper sulfate for fungicidal and nutritional dual-use across cereal zones.
Middle East and Africa Micronutrient Fertilizer Market Competitive Landscape
Global majors compete with regional champions across captive mineral access and sulfuric acid integration dimensions. The vendor base stratifies into three tiers: integrated fertilizer conglomerates with ammonia-to-micronutrient complexes, Dead Sea mineral specialists with captive precursor extraction, and petrochemical-derived sulfuric acid integrators feeding regional sulfate production. Consolidated farm procurement and direct contracting represent the dominant competitive moves, alongside backward integration into mining or acid assets to secure formulation cost stability.
Within the integrated complex tier, Yara International anchors MEA positioning through Arabian Gulf ammonia infrastructure, while Haifa Group exemplifies mineral-captive specialization through Dead Sea extraction assets. SABIC occupies a position as the petrochemical-integrated sulfuric acid supplier feeding regional micronutrient sulfate manufacturers. These three represent distinct strategic archetypes: nitrogen-integrated global major, mineral-captive regional champion, and petrochemical-integrated feedstock supplier.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Yara International |
| The Mosaic Company |
| Haifa Group |
| SABIC |
| ICL Group Ltd. |
| BASF SE |
| K+S Aktiengesellschaft |
| Unikeyterra Chemical |
| Others |
Supply & Pricing Matrix
Sulfuric acid feedstock costs cascade through sulfate-based micronutrient formulation economics, with petrochemical-derived sulfur fluctuations compressing margins at regional blending plants serving Egyptian vegetable cooperatives and Saudi date palm estates.
Pricing Analysis
Input-cost pass-through from Dead Sea mineral extraction and Arabian Gulf ammonia complexes shapes three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on chelation certification grade and volume scale, with EU-recognized organic ligands commanding substantial premiums over conventional sulfate formulations. Pricing pressure stems from crude oil cycle volatility affecting sulfuric acid derivatives. Egyptian smallholder cooperatives exhibit acute price sensitivity, while consolidated South African citrus estates absorb premium foliar schedules to secure export compliance.
Supply Chain Analysis
Direct-to-farm channels handle consolidated estate demand across Saudi Arabia's Eastern Province and South Africa's Limpopo citrus belt, bypassing traditional agro-dealer tiers. Supply concentrates in Israel's Dead Sea extraction zone, Saudi Arabia's petrochemical corridor, and South Africa's Cape Town formulation hubs. Raw material dependencies include sulfuric acid, zinc and manganese precursors, and synthetic chelating agents. Single-source vulnerability around Dead Sea mineral infrastructure creates geographic concentration risk. Distribution runs through Alexandria and Damietta port clusters for Nile Delta cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa micronutrient fertilizer market functions as a geographic-arbitrage play where Egyptian Nile Delta zinc depletion and Saudi SFDA certification mandates create divergent cost-to-serve profiles against South African EU-export compliance requirements.
For Market Incumbents: Cement captive supply positions through backward integration into sulfuric acid assets or Dead Sea mineral extraction infrastructure to defend against petrochemical price volatility. Prioritize direct contracting capabilities with consolidated farm estates to offset disintermediation pressure on traditional distributor networks. Technical advisory bundling serves as the critical retention lever against specialized agri-input competitors. For New Entrants and Emerging Players: Capture Kenyan Highlands tea and coffee cooperative white space where systematic micronutrient programs remain underdeveloped. Target bulk blend supply contracts bypassing fragmented retail channels through cooperative purchasing aggregation. Lead with fertigation-compatible soluble formulations aligned with drip irrigation expansion across Gulf Cooperation Council agriculture. For Investors and Strategic Acquirers: Consolidation pressure builds where mineral-captive regional champions face nitrogen-integrated global majors with superior balance sheet capacity for direct farm contracting scale. Long-term viability favors acquisition targets with captive precursor extraction or sulfuric acid integration anchoring formulation cost stability. Watch SFDA and Egyptian Ministry of Agriculture registration backlog clearance rates as inflection indicators for market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive sulfuric acid production insulates Haifa Group and SABIC from crude oil cycle volatility. |
| Direct Farm Contracting Scale-Up | Yara International's Arabian Gulf ammonia complexes enable volume pricing with Saudi date palm estates. |
| EU Organic Chelation Certification | Egyptian and Moroccan vegetable exporters require certified ligands for supermarket procurement compliance. |
| Controlled-Release Coating Technology | Israeli and UAE desert operators adopt synchronized nutrient release for drip irrigation pulse compatibility. |
| Multi-Jurisdiction Registration Investment | Parallel SFDA, Egyptian Ministry, and South African Fertilizers Act compliance stretches regulatory affairs capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fertilizer formulation plant managers, agri-input procurement leads at consolidated citrus estates, cooperative purchasing coordinators in the Nile Delta, and regulatory affairs specialists navigating SFDA certification. Secondary validation drew from customs and trade data, Fertilizers Farm Feeds Seeds and Remedies Act registration filings, EU Green Deal procurement specification documents, and SEC 10-K disclosures from listed agricultural input conglomerates. Bottom-up volume modeling and top-down value triangulation anchored market size estimates.
Comparable-period anchoring linked historical micronutrient consumption patterns to forward projection assumptions across the analysis window. The analytical framework modeled segmentation dimensions spanning product chemistry grade, application context, delivery infrastructure compatibility, and customer procurement channel. CAGRs were derived through regression-based trend extrapolation calibrated to sulfur price cycle assumptions and drip irrigation adoption trajectories. Industry-specific forecast inputs included Dead Sea mineral extraction capacity utilization and Egyptian vegetable export volume growth under EU supermarket compliance pressure.
Crude oil price volatility, SFDA registration processing delays, and EU residue standard tightening are the dominant revision risks to baseline projections. Forecasts reflect assumptions regarding sulfuric acid cost pass-through elasticity and cooperative purchasing consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Multi-Nutrient Fertilizer Market
Fertilizers
France Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Brazil Specialty Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
Biological Organic Fertilizers Market
Fertilizers
Boron Fertilizers Market