
 Ammonium Sulfate Fertilizer Market | 2026-2036
Ammonium Sulfate Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Sulfate Fertilizer Market Analysis
Trained agronomists capable of diagnosing sulfur micronutrient deficiencies is redrawing competitive boundaries in fertilizer distribution. BASF leverages its crop science division to bundle ammonium sulfate with digital soil analytics, extending its advisory reach beyond commodity sales. Nutrien Ltd. anchors its North American position through integrated mining and production assets that sustain cost discipline. OCI Global competes via merchant ammonia and sulfate capacity positioned at major European port hubs.
Ammonium Sulfate Fertilizer is an inorganic salt compound containing 21 percent nitrogen and 24 percent sulfur by mass, manufactured primarily through the reaction of ammonia with sulfuric acid or recovered as a co-product from caprolactam and acrylonitrile production. Its commercial purpose centers on correcting sulfur deficiencies in alkaline and high-pH soils while supplying readily available ammoniacal nitrogen. Granular formulations dominate volume channels due to superior handling characteristics and compatibility with mechanized spreaders, while liquid variants capture growth in precision fertigation systems where sulfur timing aligns with critical crop uptake windows. Coated products command premium positioning among specialty crop segments requiring controlled nutrient release.
The EPA regulates ammonium sulfate as a fertilizer material under the Federal Insecticide, Fungicide, and Rodenticide Act framework, while China's MEE enforces emission caps on caprolactam co-production facilities that constrain sulfate supply elasticity. REACH registration requirements in Europe elevate compliance costs for imported material, tilting procurement toward domestic manufacturers. Stakeholders must monitor evolving carbon border adjustment mechanisms and sulfur recovery technology economics that could restructure feedstock availability for merchant producers.
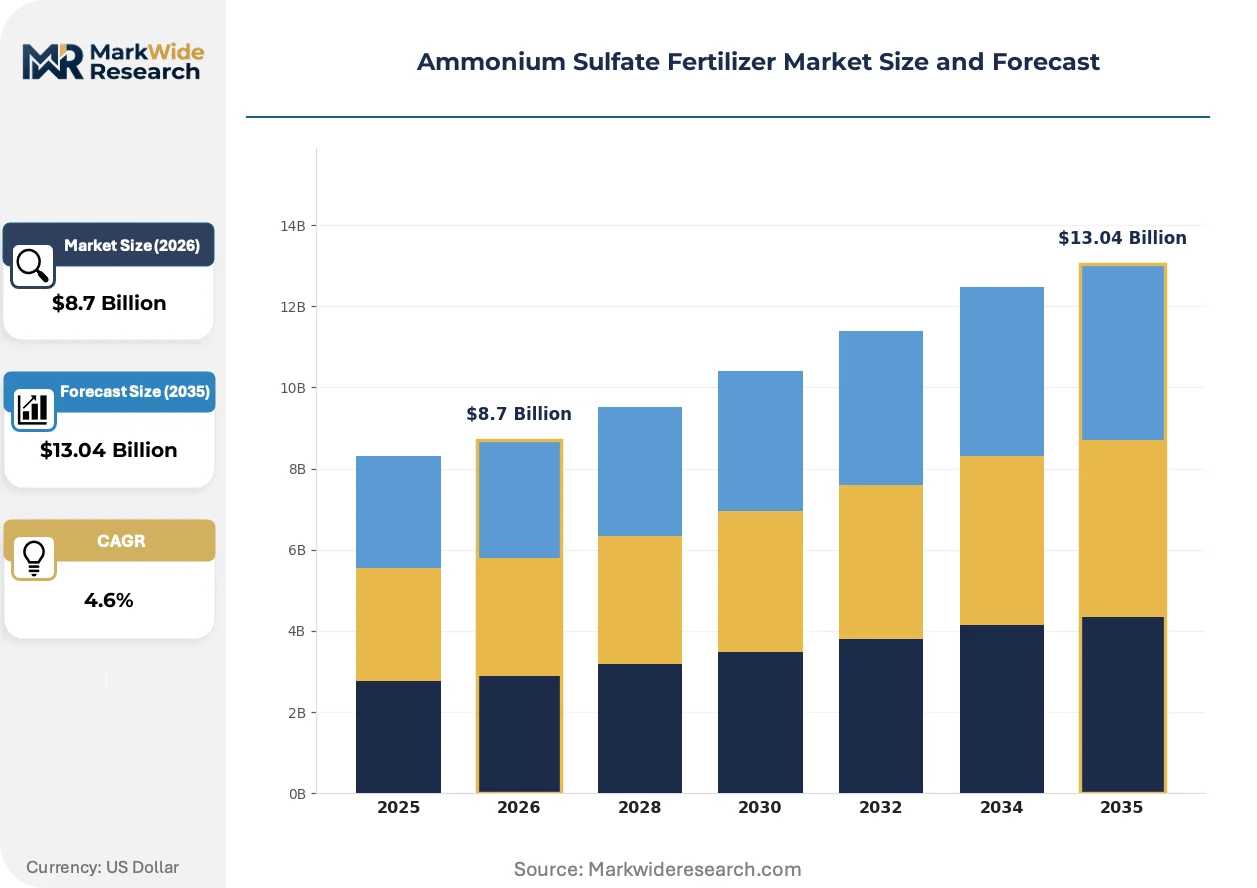
Market Dynamics
China's MEE emission caps on caprolactam co-production facilities are constraining sulfate supply elasticity while specialty crop producers in Southeast Asia expand sulfur-deficient soil correction programs. This regulatory tightening intersects with agronomic advisory service expansion to redraw competitive boundaries in fertilizer distribution.
Growth Catalysts
- Southeast Asia specialty crop expansion:Durian and oil palm producers in Indonesia and Vietnam are expanding sulfate-based fertilization programs to address chronically sulfur-deficient volcanic soils. Agronomists trained in micronutrient deficiency diagnosis command premium placement fees.
- Brazil's Cerrado agricultural frontier:Intensive soybean-corn rotations deplete soil sulfur reserves at rates exceeding natural deposition. Mechanized spreader compatibility drives granular formulation preference among large-scale operators.
- REACH registration compliance:European importers face elevated documentation costs that tilt procurement toward domestic manufacturers with established ECHA dossiers. Merchant producers at Rotterdam and Antwerp port hubs capture redirected demand.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings directly compress merchant ammonium sulfate margins. Producers without captive ammonia supply exposure face margin compression during feedstock spikes.
- Caprolactam co-production concentration:A significant share of global sulfate supply originates as a byproduct of nylon precursor manufacturing. China's MEE emission caps constrain output elasticity from these integrated facilities.
- Substitution by elemental sulfur:Bulk sulfur pastilles offer lower per-unit sulfur cost for soil amendment in non-nitrogen-critical applications. Pastille applicator technology improvements compress the addressable market for sulfate forms.
Strategic Opportunities
- Precision fertigation liquid formulations:Drip and micro-sprinkler systems in California's Central Valley and Spain's Almería greenhouse belts enable sulfur timing aligned with critical crop uptake windows. Liquid variants capture value through application labor reduction.
- Controlled-release coated products:Polymer and sulfur-coated granules command premium positioning among high-value specialty crops requiring synchronized nutrient release. Certification schemes for sustainable agriculture validate price premiums.
- Carbon border adjustment positioning:EU CBAM implementation creates compliance documentation requirements that favor European producers with verified low-carbon production pathways. Early certification investments lock in procurement relationships.
Industry Challenges
- Agronomic diagnostic skill scarcity:Field-level sulfur deficiency diagnosis requires trained personnel capable of distinguishing sulfur from nitrogen symptomology. Distribution networks compete for limited certified crop advisors.
- Legacy blending equipment incompatibility:Existing fertilizer compounding infrastructure in developing markets often lacks corrosion-resistant materials for sulfate handling. Retrofit capex requirements delay market entry timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Sulfate Fertilizer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Coated End Use Industry: Agriculture, Horticulture, Landscaping, Turf Management Application Method: Broadcast, Soil Application, Fertigation, Foliar Application Packaging Type: Bags, Bulk, Totes, Drums |
| Companies Covered | BASF, Evonik Industries AG, LANXESS, AdvanSix, Sumitomo Chemical Co., Ltd., OCI Global, Domo Chemicals, Nutrien Ltd., China Petrochemical Development Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Sulfate Fertilizer Market Emerging Trajectories
Granular and liquid formulation pathways are diverging as application technology and crop systems specialize. Digital soil analytics integration, regulatory carbon accounting, and precision agriculture equipment are simultaneously reshaping product development priorities and channel economics.
Controlled-release coating technology is bifurcating the premium product tier. Polymer-encapsulated and sulfur-matrix coatings extend nutrient availability across 6-12 week windows for high-value horticultural crops. Greenhouse operators in the Netherlands and California's Salinas Valley are adopting these formulations at pace premiums of 40-60% above standard granules. The technology is bifurcating market segmentation between commodity bulk applications and precision-managed specialty systems.
REACH registration requirements under ECHA oversight are elevating compliance documentation burdens for imported ammonium sulfate. Third-party testing and dossier maintenance costs now exceed €50,000 annually for non-European suppliers. Merchant producers with established European manufacturing footprints capture procurement share from importers facing extended certification timelines.
Buying committees at large-scale agricultural cooperatives are consolidating sulfur procurement decisions with nitrogen and phosphorus sourcing. Procurement centralization at Brazilian cooperatives and US Midwest grain elevators compresses distributor margins while favoring suppliers offering multi-nutrient bundles and soil testing services. This pattern is most visible in Brazil's Mato Grosso state and Iowa's corn-soybean belt.
Ammonium Sulfate Fertilizer Market Segmentation
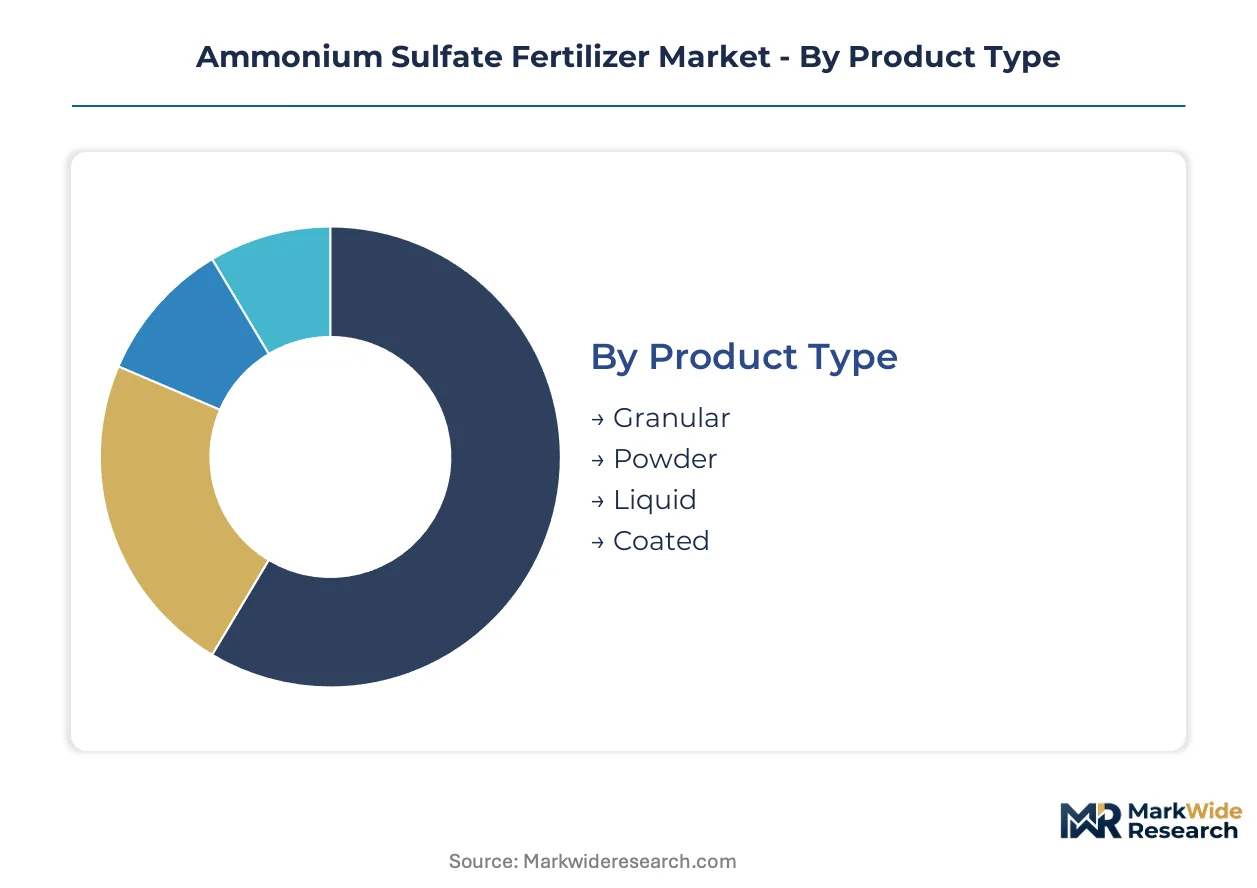
Ammonium sulfate fertilizer markets fragment across physical form, end-use intensity, and application infrastructure. Margin capture varies sharply by segment — granular formulations command volume premiums in mechanized agriculture while liquid variants extract value through precision delivery systems.
Product Type:
Margin pools concentrate in value-added formulations where handling characteristics and nutrient control justify price premiums over commodity grades.
- Granular:Spherical particles sized 2-4mm enable uniform spread patterns via pneumatic and spinner spreaders. Brazil's Mato Grosso soybean operators specify granular for sulfur replenishment in no-till systems where soil disturbance is minimized.
- Liquid:Aqueous solutions containing dissolved ammonium sulfate enable injection through drip irrigation manifolds. California Central Valley nut orchards rotate liquid sulfur applications with nitrogen fertigation to synchronize peak uptake periods.
- Powder:Fine crystalline material serves blending operations where rapid dissolution in tank mixes is required. Southeast Asian compound fertilizer manufacturers specify powder for NPK formulation lines.
- Coated:Polymer or sulfur-matrix encapsulation extends nutrient release across 6-12 week windows. Dutch greenhouse vegetable producers pay 40-60% premiums for controlled-release sulfur in substrate cultivation.
Granular holds installed capacity. Coated is rotating up the share rankings.
End Use Industry:
Application intensity and sulfur deficiency severity determine value extraction across crop systems.
- Agriculture:Field crop producers in sulfur-depleted regions apply ammonium sulfate as primary sulfur carrier. Iowa corn-soybean rotations and Brazilian Cerrado operations drive bulk procurement volumes.
- Horticulture:High-value fruit and vegetable systems require precise sulfur timing for quality parameters. Spanish Almería greenhouse belts specify liquid formulations for soilless substrate management.
- Landscaping:Turf establishment and ornamental maintenance programs use sulfate for chlorosis prevention in alkaline soils. US municipal golf course contracts specify coated products for reduced application frequency.
- Turf Management:Professional sports field maintenance demands rapid green-up response and wear recovery. Premier League football grounds in England source granular sulfate for autumn renovation programs.
Agriculture commands volume leadership. Horticulture is climbing the fastest on value per hectare metrics.
Application Method:
Equipment compatibility and labor efficiency reshape procurement specifications across farm scales.
- Broadcast:Surface spreading via spinner or pneumatic equipment suits pre-plant sulfur incorporation. Australian wheatbelt operators broadcast granular sulfate ahead of seeding rains.
- Soil Application:Banding or knifing places sulfur in root proximity for immediate crop access. German sugar beet growers band sulfate at 15cm depth to match taproot development zones.
- Fertigation:Injection through irrigation infrastructure enables split applications matching crop phenology. Israeli desert agriculture relies on fertigation for sulfur in reclaimed water systems.
- Foliar Application:Aerial or ground sprayer delivery corrects acute deficiencies during critical growth stages. French viticulture applies foliar sulfate at veraison for aromatic compound development.
Broadcast retains equipment ubiquity. Fertigation is gaining share fastest where irrigation infrastructure exists.
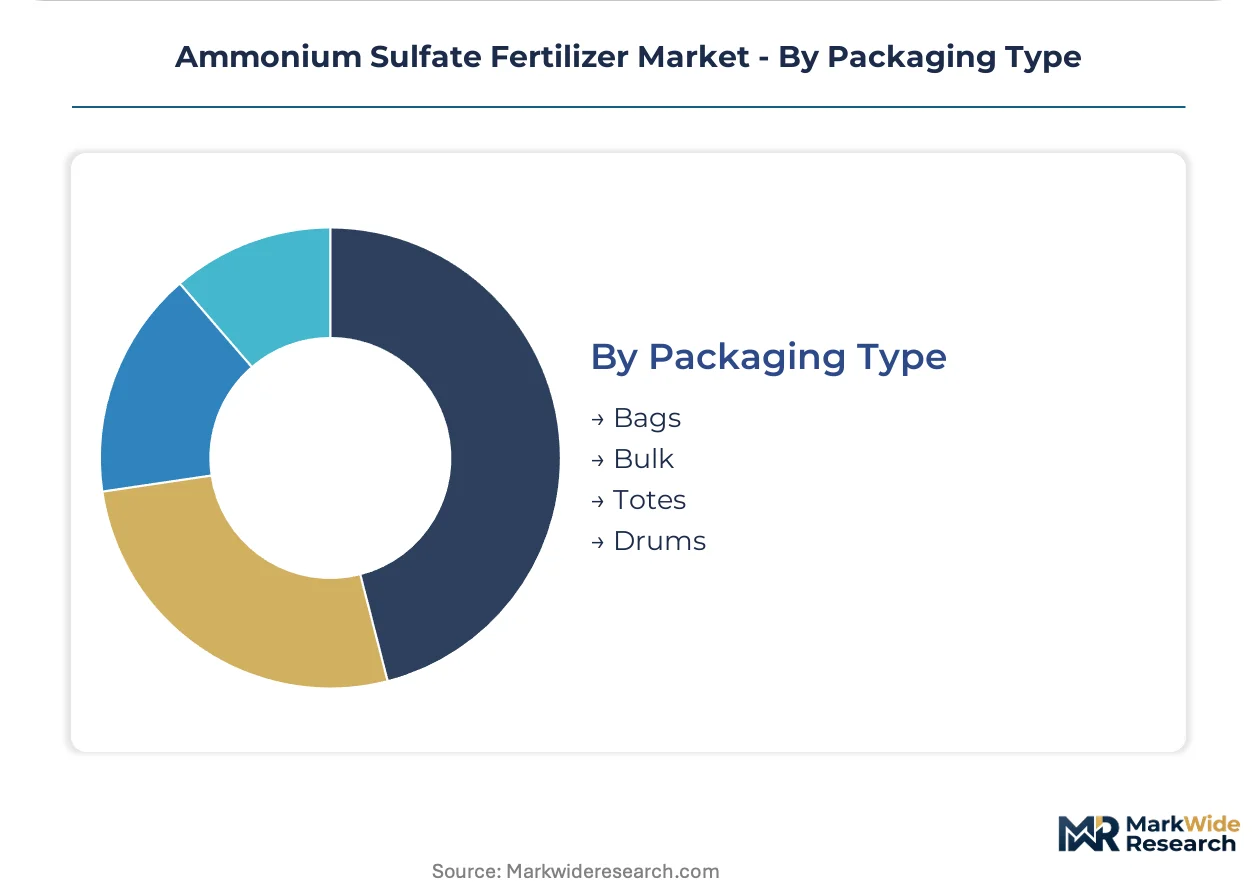
Packaging Type:
Logistics economics and handling infrastructure determine format selection across distribution channels.
- Bags:25-50kg woven polypropylene units serve smallholder and retail garden segments. Vietnamese rice cooperatives procure bagged material for member distribution networks.
- Bulk:Pneumatic tanker and hopper car delivery minimizes per-ton handling costs. US Midwest grain elevators receive bulk sulfate for on-farm blending operations.
- Totes:Intermediate bulk containers bridge bulk and bagged economics for mid-scale operations. Mexican vegetable packers specify totes for sulfur storage at remote packing shed locations.
- Drums:Sealed steel or plastic containers preserve liquid formulation integrity. California organic certifiers require drum packaging to prevent cross-contamination in liquid handling.
Bulk dominates tonnage throughput. Totes are expanding most quickly in specialty crop distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the ammonium sulfate fertilizer market concentrates in European port hubs while Brazilian inland logistics erode margin capture for imported material. Rotterdam and Antwerp terminals command sulfur procurement premiums through integrated ammonia access. Chinese coastal manufacturers face emission compliance costs that compress export competitiveness against Middle Eastern merchant supply.
United States
Midwest grain elevators consolidate sulfur procurement with nitrogen and phosphorus sourcing at cooperative scale. The EPA regulates ammonium sulfate under FIFRA fertilizer material frameworks with state-level nutrient management plan overlays. Iowa's corn-soybean belt drives bulk granular demand through mechanized spreader infrastructure.
Brazil
Mato Grosso soybean operators specify granular formulations for no-till sulfur replenishment where soil disturbance is minimized. ANVISA coordinates with agricultural ministry standards for fertilizer contaminant thresholds. The Cerrado agricultural frontier depletes soil sulfur reserves faster than natural deposition, concentrating demand in frontier expansion zones.
China
Caprolactam co-production facilities supply merchant sulfate as nylon precursor manufacturing byproduct. The MEE enforces emission caps on these integrated plants that constrain output elasticity. Shandong Peninsula chemical clusters face compliance retrofit costs that reshape export supply availability.
Germany
Sugar beet growers band sulfate at 15cm depth to match taproot development zones with precision placement. REACH registration requirements under ECHA oversight elevate documentation burdens for imported material. The Rhine-Ruhr industrial corridor anchors domestic manufacturing with established ECHA dossiers.
Netherlands
Greenhouse vegetable producers in Westland pay 40-60% premiums for controlled-release coated sulfur in substrate cultivation. The EU Green Deal carbon border adjustment mechanisms create compliance documentation requirements favoring verified low-carbon production pathways. Rotterdam port terminals capture redirected demand from importers facing extended certification timelines.
Ammonium Sulfate Fertilizer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the ammonium sulfate fertilizer market. Integrated chemical conglomerates with caprolactam or acrylonitrile co-production assets command feedstock cost advantages while specialty fertilizer houses extract premium positioning through agronomic advisory bundling. Three archetypes dominate: diversified chemical majors with captive ammonia supply, merchant sulfate specialists positioned at port hubs, and regional compounders serving localized blending demand. Competitive moves concentrate on backward integration into ammonia sourcing and geographic expansion through distribution partnership networks.
Among diversified chemical majors, BASF and Evonik Industries AG exemplify integrated production archetypes with co-product sulfate streams from polymer precursor manufacturing. Nutrien Ltd. occupies a position representing North American integrated mining and production scale. OCI Global anchors the merchant specialist tier with ammonia and sulfate capacity positioned at European port terminals.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries AG |
| LANXESS |
| AdvanSix |
| Sumitomo Chemical Co., Ltd. |
| OCI Global |
| Domo Chemicals |
| Nutrien Ltd. |
| China Petrochemical Development Corporation |
| Others |
Supply Flow & Price Mechanics
REACH registration requirements under ECHA oversight gate both European market access qualification and price differentiation between domestic and imported ammonium sulfate tiers. Compliance documentation burdens exceeding €50,000 annually for non-European suppliers simultaneously constrain supply pool eligibility and compress margin capture for merchant importers facing extended certification timelines.
Pricing Analysis
Geographic price spreads widen 15-25% between Rotterdam port hub deliveries and Brazilian inland destinations where logistics erode landed cost competitiveness. Three-tier pricing structure across premium coated, standard granular, and economy powder grades tracks certification level and nutrient release control sophistication. Pricing pressure stems from ammonia feedstock volatility compressing merchant producer margins during natural gas spikes. Large-scale agricultural cooperatives in Brazil's Mato Grosso exhibit highest price sensitivity through consolidated procurement committees, while Dutch greenhouse operators show lowest sensitivity for controlled-release sulfur premiums.
Supply Chain Analysis
Inventory lead times stretch 6-10 weeks for caprolactam co-production sulfate originating from China's Shandong Peninsula chemical clusters under MEE emission compliance constraints. Supply concentrates in China, Germany, and the Netherlands, with merchant capacity anchored at Rotterdam and Antwerp terminals. Raw material dependencies center on merchant ammonia, sulfuric acid, and caprolactam manufacturing byproduct streams. Single-source vulnerability runs through China's integrated nylon precursor facilities where emission caps constrain output elasticity. Distribution runs through agricultural cooperatives and regional compounders serving localized blending demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through procurement committee consolidation at Brazilian cooperatives and US Midwest grain elevators, compressing distributor margins while favoring multi-nutrient bundle suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into captive ammonia supply and agronomic advisory service bundling. BASF's crop science division model demonstrates how digital soil analytics extend advisory reach beyond commodity sales, countering margin compression from procurement centralization. Prioritize certification maintenance under REACH and emerging carbon border adjustment mechanisms to lock in European procurement relationships. For New Entrants and Emerging Players: ECHA fast-track registration for low-carbon production pathways offers procurement entry into EU markets facing extended importer certification timelines. White-space targets include liquid formulation precision fertigation in California's Central Valley and coated controlled-release products for Dutch greenhouse substrate cultivation. Go-to-market through precision agriculture equipment partnerships enables sulfur timing synchronization with critical crop uptake windows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across coated controlled-release manufacturing due to polymer encapsulation technology requirements and certification infrastructure investments. Long-term viability favors merchant sulfate specialists with established port hub positioning and verified low-carbon production pathways. Acquisition target archetype: regional compounders with corrosion-resistant blending infrastructure in Southeast Asian sulfur-deficient markets. Signal to monitor: carbon border adjustment implementation pace and sulfur recovery technology economics restructuring feedstock availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Supply | Captive feedstock production insulates margin compression from natural gas volatility at merchant producers. |
| Controlled-Release Coating Capacity Expansion | Polymer encapsulation technology captures 40-60% price premiums from Dutch greenhouse vegetable operators. |
| Carbon Border Adjustment Certification | Verified low-carbon pathways under EU Green Deal lock in procurement relationships against Middle Eastern merchant supply. |
| Agronomic Advisory Service Bundling | Trained sulfur deficiency diagnosis extends distributor placement fees beyond commodity fertilizer sales. |
| Precision Fertigation Liquid Formulation Development | Drip irrigation compatibility enables sulfur timing synchronization with peak crop uptake in California nut orchards. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from listed chemical producers, ECHA registration dossiers, and agricultural ministry fertilizer consumption statistics. Agronomists at Indonesian durian cooperatives, procurement directors at Brazilian agricultural cooperatives, plant managers at Shandong caprolactam facilities, and distribution channel partners in the US Midwest provided stakeholder perspectives. Bottom-up volume estimates triangulate against top-down value projections from production capacity and trade flow analysis.
Segmentation dimensions modeled include physical form tier, end-use crop system intensity, application infrastructure type, and regional regulatory cluster across the projection horizon. CAGRs derive from regression analysis of historical consumption patterns against sulfur deficiency correction program expansion and crop acreage forecasts. Industry-specific inputs incorporate MEE emission cap compliance timelines, REACH registration renewal schedules, and precision agriculture equipment penetration curves.
Decision-makers should treat outputs as directional under assumptions of continued sulfur-deficient soil expansion in Southeast Asia and Brazil's Cerrado, stable natural gas feedstock pricing, and incremental carbon border adjustment implementation; material deviation in any assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Asia Pacific Controlled Release Fertilizers Market
Fertilizers
Germany Fertilizer Market
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
North America Specialty Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
GCC Fertilizer Market