
 Middle East and Africa Fertilizers Market | 2026-2036
Middle East and Africa Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fertilizers Market Foresight
Multi-source procurement among African distributors is expanding as port infrastructure upgrades in Dar es Salaam and Lagos reduce dependence on single-origin imports. OCP Group leverages integrated phosphate mining and processing assets in Morocco to control upstream supply. SABIC Agri-Nutrients Co. anchors ammonia and urea output through Saudi Arabia's natural gas feedstock advantage. Yara International ASA competes via specialized micronutrient blends tailored to East African soil deficiencies.
Middle East and Africa fertilizers encompass nitrogenous, phosphatic, and potash compounds formulated to replenish soil macronutrients, with urea typically containing 46% nitrogen by weight and phosphate fertilizers derived from beneficiated rock processed through sulfuric acid reaction. Their primary purpose is to correct nutrient depletion in semi-arid and tropical soils where natural organic matter mineralization rates fall below crop removal rates. Urea dominates volume flows across the region due to its high nitrogen concentration and established bulk handling infrastructure, while phosphate holds concentrated margin pools tied to Morocco's sovereign control of global rock reserves. Granulated delivery modes command preference among commercial farming operations in South Africa and Egypt, whereas liquid formulations gain share in hydroponic greenhouse clusters near Addis Ababa and Nairobi.
South Africa's Fertilizer Association enforces product registration and labeling standards that govern import eligibility and domestic blending operations. Egypt's Ministry of Agriculture and Land Reclamation administers subsidy allocation mechanisms that directly determine farmer affordability and national consumption volumes. The country's national pharmaceutical regulator does not oversee this sector; instead, agricultural chemical oversight falls under dedicated crop science authorities. Stakeholders must monitor how Egypt's subsidy reform trajectory and Morocco's phosphate royalty policy evolve, as these fiscal instruments will determine regional pricing benchmarks and investment incentives for new production capacity.
Market Dynamics
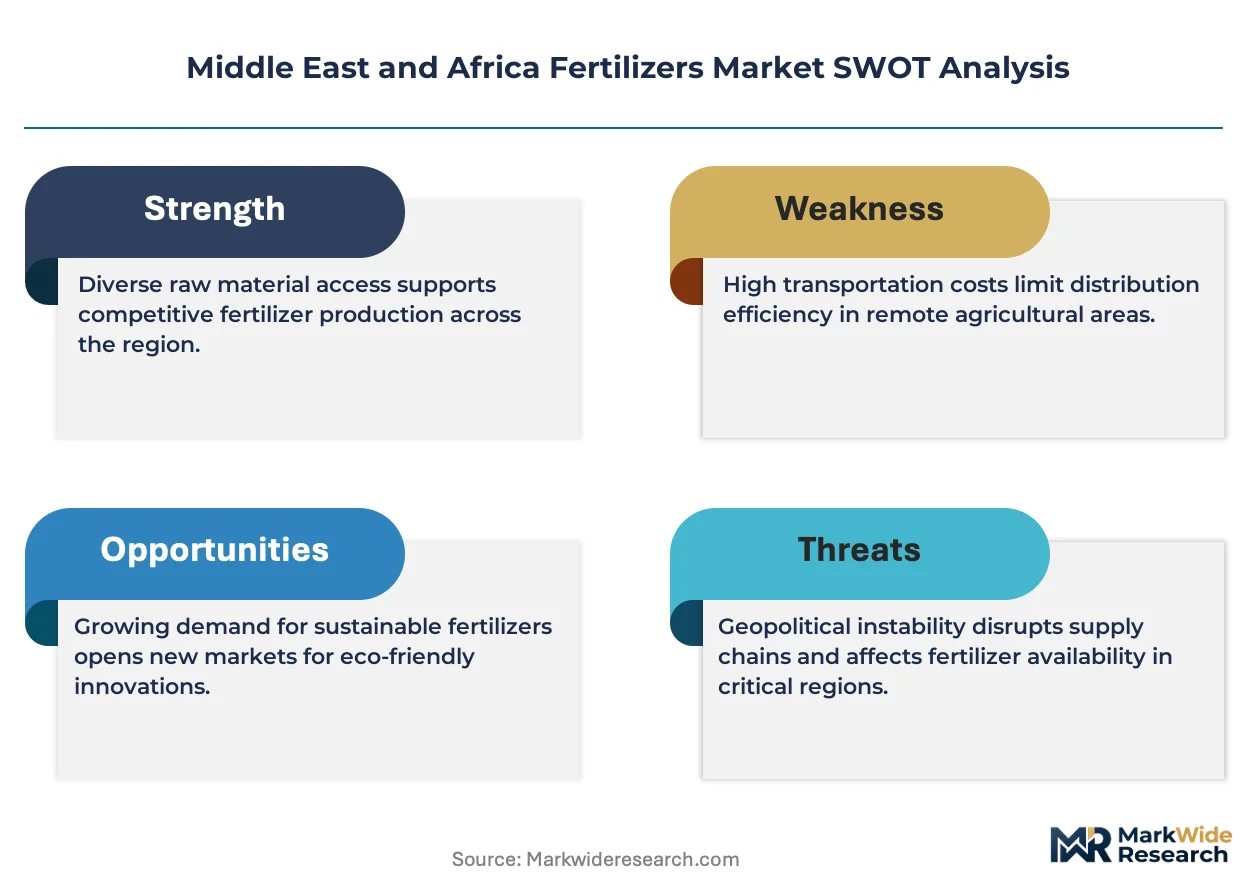
Morocco's sovereign phosphate reserve monopoly and Egypt's wheat subsidy apparatus are locking in divergent pricing architectures across the Middle East and Africa fertilizers landscape. OCP Group's beneficiation investments and Cairo's fiscal allocation mechanisms now determine regional trade flows more than raw commodity cycles.
Growth Catalysts
- Phosphate beneficiation advances:Morocco's OCP Group deploys slurry pipeline infrastructure and advanced flotation circuits that cut processing energy intensity. Captive rock-to-acid integration secures margin capture unavailable to import-dependent blenders.
- Nile Delta vegetable intensification:Egypt's Ministry of Agriculture and Land Reclamation channels subsidized urea and complex fertilizers into delta governorates where triple-cropping rotations deplete soil organic matter faster than natural replenishment.
- East African precision agriculture pilots:Commercial farms in Kenya's Rift Valley and Tanzania's Southern Highlands adopt variable-rate application systems that increase nutrient use efficiency and sustain premium fertilizer offtake volumes.
Market Restraints
- Natural gas feedstock volatility:Ammonia and urea production costs across the Gulf Cooperation Council swing with Henry Hub and TTF benchmark divergence, compressing margins for Saudi and Qatari nitrogen exporters when European storage fills.
- Single-origin phosphate dependence:African blending operations outside Morocco remain tethered to OCP Group rock concentrate, with limited alternative beneficiation capacity in Sub-Saharan Africa to diversify upstream supply.
- Semi-arid soil fixation chemistry:High-pH calcareous soils across Egypt's Western Desert and Sudan's Gezira Scheme immobilize applied phosphorus, forcing farmers to over-apply phosphate fertilizers to achieve agronomic response.
Strategic Opportunities
- Ethiopian hydroponic greenhouse expansion:Liquid fertilizer formulations tailored for closed-loop irrigation systems near Addis Ababa and Hawassa command price premiums over granular commodities in open-field applications.
- South African carbon border alignment:The European Union's Carbon Border Adjustment Mechanism creates compliance service revenue streams for fertilizer traders certifying embedded emissions in ammonia and urea shipments.
- West African port infrastructure modernization:Lagos Apapa and Lekki Deep Sea terminal upgrades enable direct vessel calls that bypass transshipment through European hubs, cutting landed costs for Nigerian distributors.
Industry Challenges
- Soil science agronomist scarcity:Commercial farming operations across Kenya and Tanzania lack sufficient extension personnel trained in site-specific nutrient management, limiting adoption of precision application technologies.
- Subsidy administration complexity:Egypt's Ministry of Agriculture and Land Reclamation struggles with beneficiary verification and leakage control in its smart-card distribution system, distorting intended price signals to wheat farmers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fertilizers Market |
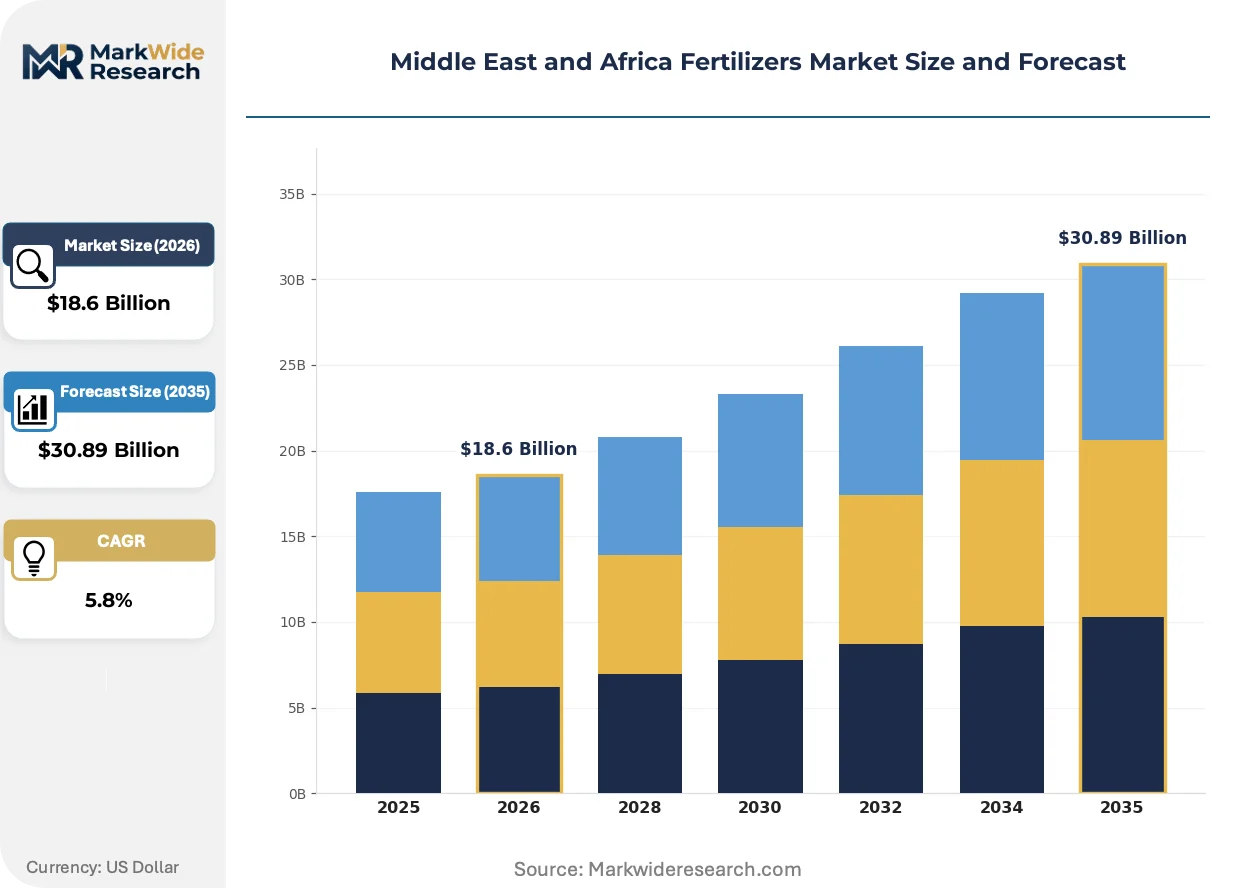
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, Phosphate, Potash Application: Crops, Horticulture, Turf, Soil Amendment End User: Agriculture, Landscape, Hydroponics, Greenhouses Delivery Mode: Bulk, Bagged, Liquid, Granulated |
| Companies Covered | Dangote Group, ICL Group Ltd, Yara International ASA, Kynoch Fertilizer, K+S Aktiengesellschaft, SABIC Agri-Nutrients Co., Foskor, Golden Fertilizer Company Limited, OCP Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fertilizers Market Shifts & Advancements
Digital soil mapping and controlled-release coating chemistries are converging to displace blanket fertilizer recommendations across Middle East and Africa commercial agriculture. These shifts favor suppliers capable of micronutrient customization over bulk commodity traders.
Polymer-coated urea and sulfur-coated formulations are rewriting nitrogen management protocols in Egypt's delta vegetable belts and South Africa's maize triangle. Large-scale farming cooperatives in Gauteng and Free State provinces are adopting these products to reduce split-application labor costs and limit groundwater nitrate loading. The technology is compressing seasonal demand spikes into flatter offtake curves that strain legacy distributor inventory models.
Egypt's subsidy reform trajectory and Morocco's phosphate royalty policy adjustments are forcing traders to recalibrate long-term contract structures. The Ministry of Agriculture and Land Reclamation's phased reduction of wheat farmer support is redirecting procurement toward private-label blends. Importers are responding by diversifying sourcing relationships beyond traditional Gulf Cooperation Council ammonia suppliers.
Aggregated procurement platforms are consolidating fragmented smallholder demand across Nigeria's northern cereal belts and Kenya's highland tea zones. These digital intermediaries bypass legacy distributor networks by pooling orders for direct container shipments from Moroccan and Saudi producers. The model is most visible in Oyo and Kaduna states, where farmer cooperatives now contract quarterly volumes with freight pre-payment rather than spot market purchases.
Middle East and Africa Fertilizers Market Segmentation
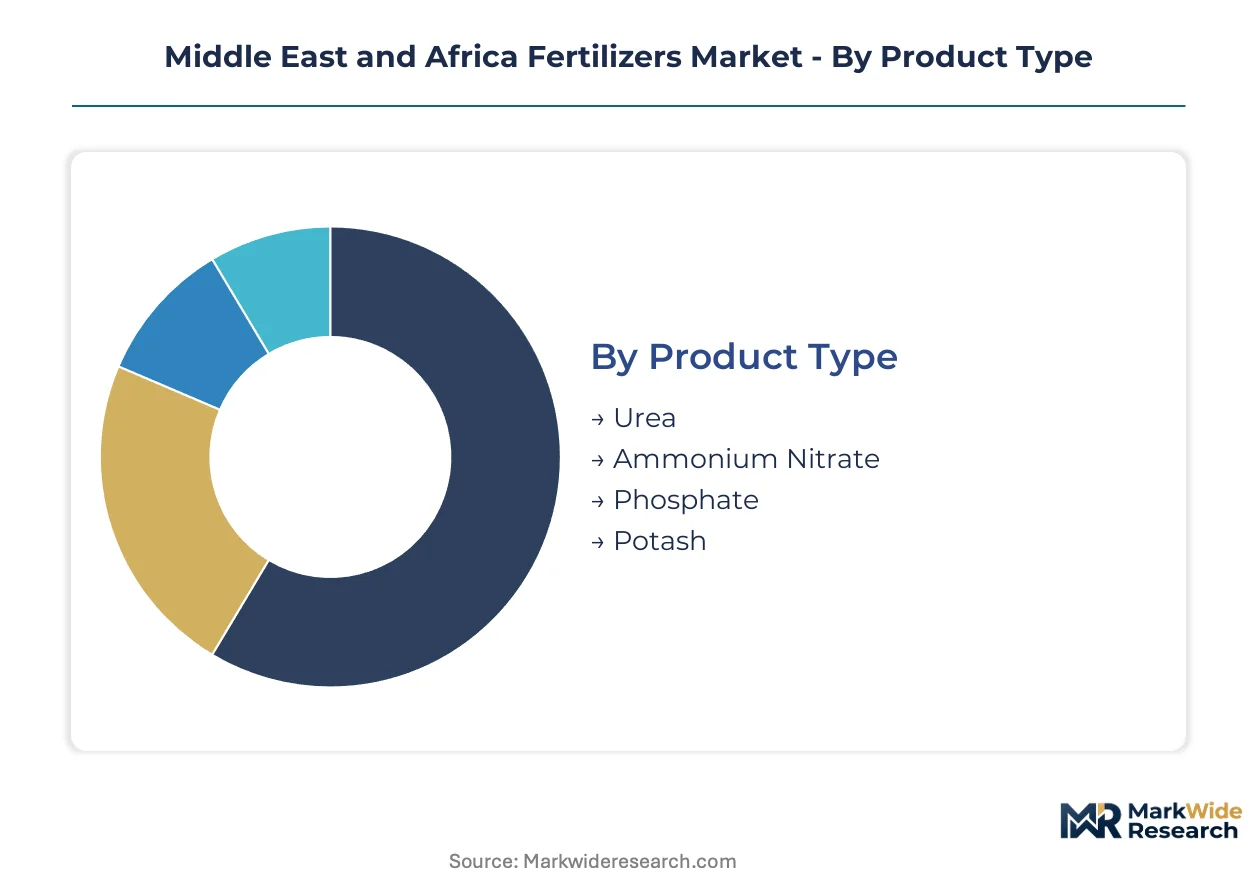
Segmentation in the Middle East and Africa fertilizers market reveals how nutrient chemistry, application method, and delivery logistics intersect with regional agricultural infrastructure. Understanding these divisions exposes where capital investment concentrates and which product formats command premium positioning.
Product Type:
Upgrade cycles in fertilizer procurement follow soil depletion patterns and crop rotation intensities, with farmers replacing basic nitrogen sources with compound formulations as commercial farming expands.
- Urea:Contains 46% nitrogen by weight, making it the most concentrated solid nitrogen fertilizer commercially available. Egyptian wheat farmers in the Nile Delta consume subsidized urea volumes that dwarf other regional markets, though calcareous soil fixation forces over-application to achieve agronomic response.
- Phosphate:Derived from beneficiated rock processed through sulfuric acid reaction to produce phosphoric acid and downstream fertilizers. Morocco's OCP Group controls upstream supply through captive mining and processing assets, locking African blenders outside Morocco into single-origin dependence.
- Ammonium Nitrate:Dual-nutrient formulation delivering nitrogen in nitrate and ammonium forms for immediate and sustained plant uptake. Security regulations restrict transport and storage across several Middle East jurisdictions, limiting distribution flexibility.
- Potash:Potassium chloride and sulfate compounds correcting soil potassium deficiency in intensive vegetable and fruit production. Near-total import dependence across the region concentrates sourcing decisions on Canadian and Belarusian supply contracts.
Urea sits at the top of the volume ranking, with phosphate climbing the fastest as Moroccan beneficiation capacity expands and compound fertilizer adoption spreads.
Application:
Cost tier differentiation separates commodity grain applications from high-value horticultural inputs, with pricing spreads reflecting nutrient precision requirements and yield sensitivity.
- Crops:Cereal and oilseed production across Egypt's wheat belts, Nigeria's northern guinea savanna, and South Africa's maize triangle. Government subsidy programs in Cairo and Abuja determine affordability and consumption volumes, distorting price signals to farmers.
- Horticulture:Vegetable and fruit cultivation in intensive delta and highland systems. Kenya's Rift Valley and Ethiopia's Awash Valley drive premium fertilizer demand as export-oriented producers adopt precision application technologies.
- Turf:Golf course and sports field maintenance in Gulf Cooperation Council urban centers. Saudi Arabia's Riyadh and UAE's Dubai sustain specialized fertilizer procurement through landscaping contractors serving municipal and private developments.
- Soil Amendment:Corrective applications addressing pH imbalance, salinity, and micronutrient deficiency. Sudan's Gezira Scheme and Egypt's Western Desert rehabilitation projects require bulk gypsum and sulfur inputs alongside macronutrient fertilizers.
Crops anchor regional volume flows, with horticulture expanding most quickly as commercial farming and export horticulture intensify across East Africa.
End User:
Customer type fragmentation separates smallholder cooperatives from integrated agribusiness operations, with procurement scale determining supplier access and pricing terms.
- Agriculture:Open-field farming operations ranging from subsistence smallholders to mechanized commercial estates. Nigeria's aggregated procurement platforms are consolidating fragmented northern cereal belt demand into direct container contracts with Moroccan and Saudi producers.
- Landscape:Municipal parks, highway verges, and commercial property grounds maintenance. South Africa's provincial governments and Gulf municipal authorities specify slow-release formulations for labor cost reduction.
- Hydroponics:Soilless cultivation systems in controlled-environment agriculture. Addis Ababa and Hawassa greenhouse clusters command liquid fertilizer premiums tailored for closed-loop irrigation and precise nutrient solution management.
- Greenhouses:Protected cultivation structures for vegetable and flower production. Nairobi and Dar es Salaam peri-urban zones are adopting fertigation-compatible soluble fertilizers as greenhouse acreage expands.
Agriculture dominates absolute consumption, with hydroponics gaining share fastest as Ethiopian and Kenyan controlled-environment agriculture scales.
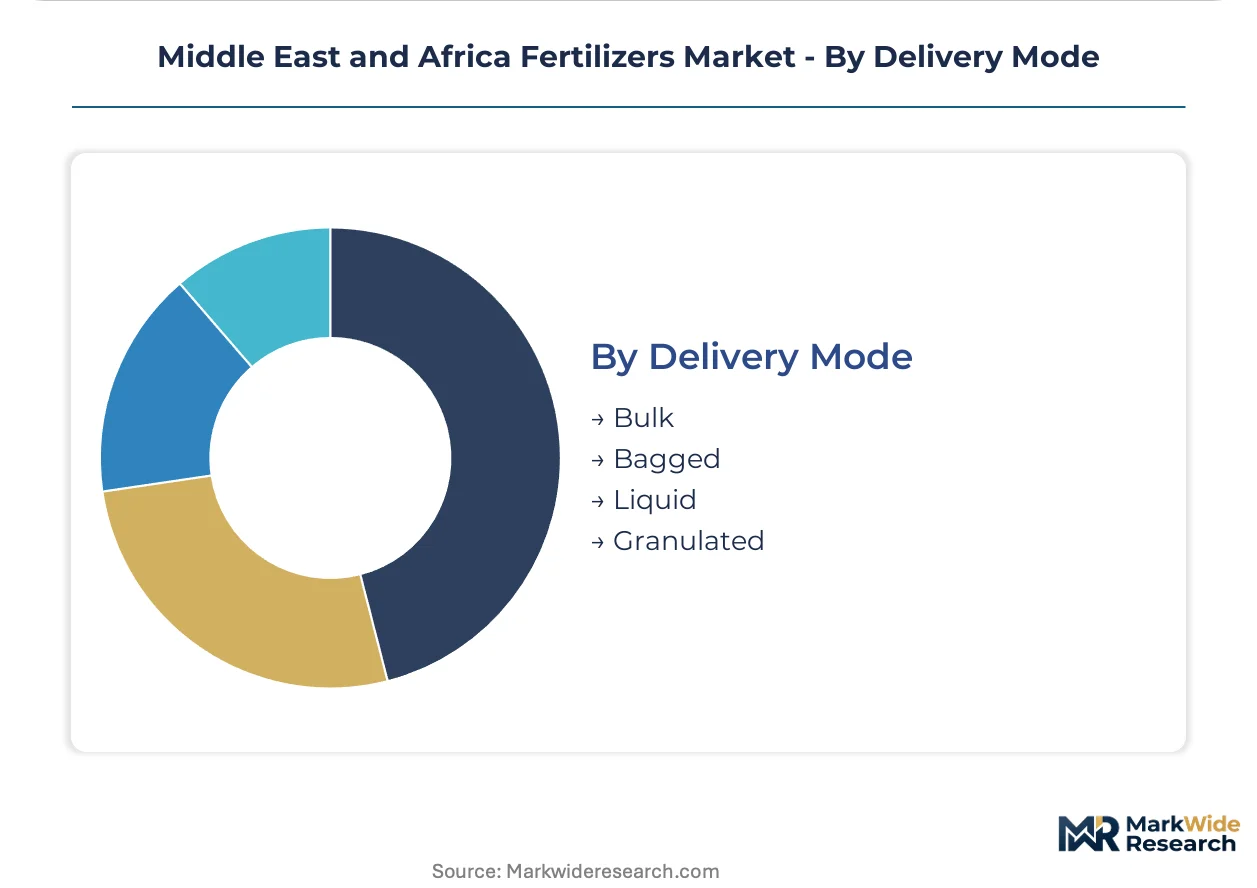
Delivery Mode:
Supply concentration in port infrastructure and bulk handling determines which delivery formats achieve landed cost competitiveness across different geographies.
- Bulk:Unpackaged commodity shipment for domestic blending and direct field application. Lagos Apapa and Lekki Deep Sea terminal upgrades enable direct vessel calls that bypass European transshipment, cutting landed costs for Nigerian distributors.
- Bagged:Standardized packaging in 50kg sacks for smallholder retail distribution. Egypt's smart-card subsidy system requires bagged product traceability, complicating beneficiary verification and leakage control.
- Liquid:Solution and suspension formulations for fertigation and foliar application. Adoption concentrates in South African maize triangles and Gulf greenhouse clusters where precision application equipment is deployed.
- Granulated:Uniform particle size for mechanical spreading and controlled-release coating compatibility. Gauteng and Free State farming cooperatives favor polymer-coated granules to reduce split-application labor costs.
Bulk shipment handles the greatest tonnage, with liquid formulations showing the steepest expansion trajectory as fertigation infrastructure spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fertilizer production placement across the Middle East and Africa, as natural gas feedstock advantages in the Gulf Cooperation Council and phosphate reserve sovereignty in Morocco create divergent cost-of-compliance regimes that attract capacity investment away from import-dependent markets.
Saudi Arabia
SABIC Agri-Nutrients Co. anchors ammonia and urea output through captive natural gas supply from the Kingdom's hydrocarbon infrastructure. The Saudi Food and Drug Authority (SFDA) governs agricultural chemical registration and import protocols. Jubail Industrial City concentrates nitrogen fertilizer production where integrated petrochemical complexes achieve feedstock-to-fertilizer conversion efficiencies unavailable to standalone processors.
Morocco
OCP Group's beneficiation investments have locked in upstream phosphate concentrate supply for regional blending operations. The country's mining royalty framework directly determines rock pricing benchmarks for export-dependent African compounders. Khouribga and Youssoufia mining clusters feed slurry pipeline infrastructure that cuts transport energy intensity versus traditional rail shipment.
Egypt
Nile Delta wheat farmers consume subsidized urea volumes that sustain the region's heaviest nutrient application rates per hectare. The Ministry of Agriculture and Land Reclamation administers smart-card distribution mechanisms that determine farmer affordability and national procurement volumes. Kafr El Sheikh and Dakahlia governorates concentrate intensive triple-cropping rotations that deplete soil organic matter faster than natural replenishment cycles.
South Africa
Gauteng and Free State farming cooperatives are adopting polymer-coated granules to reduce split-application labor costs in maize production. The country's Fertilizer Association enforces product registration and labeling standards that govern import eligibility and domestic blending operations. Richards Bay bulk handling terminals enable direct vessel calls that bypass European transshipment for nitrogen commodity imports.
Nigeria
Dangote Group's domestic production capacity is displacing historical dependence on Moroccan and Saudi imports for northern cereal belt farmers. The country's national agricultural chemical regulator oversees fertilizer quality standards and import certification requirements. Lagos Apapa and Lekki Deep Sea terminal upgrades enable direct container contracts between farmer cooperatives and external producers, cutting landed costs versus legacy distributor networks.
Middle East and Africa Fertilizers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision-formulation specialization and digital distribution platforms to bypass legacy supply chains. The market structures around sovereign resource control, with phosphate rock monopolists and natural gas-anchored nitrogen producers commanding upstream margin capture. Three archetypes dominate: integrated mining-to-acid operators, regional blenders dependent on imported intermediates, and precision-agriculture specialists offering micronutrient customization. Competitive moves concentrate on backward integration into captive phosphate supply and forward integration into farmer-facing digital procurement platforms.
Among integrated phosphate operators, OCP Group and Foskor exemplify the mining-to-fertilizer archetype that controls beneficiation capacity and regional concentrate pricing. SABIC Agri-Nutrients Co. anchors the nitrogen-specialist tier where natural gas feedstock integration determines cost competitiveness against import-dependent blenders. Yara International ASA occupies the precision-formulation position, competing via specialized micronutrient blends rather than bulk commodity volume.
| Leading Market Players |
|---|
| Dangote Group |
| ICL Group Ltd |
| Yara International ASA |
| Kynoch Fertilizer |
| K+S Aktiengesellschaft |
| SABIC Agri-Nutrients Co. |
| Foskor |
| Golden Fertilizer Company Limited |
| OCP Group |
| Others |
Supply & Pricing Matrix
Egyptian wheat farmers' smart-card procurement preferences are compressing distributor margins and forcing supply chain reconfiguration toward direct government contracting. This demand-side shift is amplifying price volatility for private-label blenders while cementing OCP Group's rock-to-acid pricing power across North African compound operations.
Pricing Analysis
Natural gas feedstock pass-through from Saudi Arabia's Jubail complexes sets regional urea benchmarks that Moroccan phosphate producers cannot match on nitrogen compounds. Three-tier pricing structure across polymer-coated premium, standard granular, and bulk commodity levels separates precision agriculture adopters in Kenya's Rift Valley from subsistence smallholders in Nigeria's northern belts. Cost compression in standard-grade urea is intensifying because Egyptian subsidy reforms redirect volumes toward domestic blenders. Smallholder cooperatives aggregated through digital platforms exhibit highest price sensitivity, while Gulf greenhouse operators accept premium liquid formulation pricing.
Supply Chain Analysis
Specialized chemical process engineers and bulk handling technicians concentrate in Morocco's Khouribga mining corridor and Saudi Arabia's Jubail Industrial City, constraining expansion timelines for greenfield beneficiation or ammonia capacity elsewhere. Upstream supply draws from Moroccan phosphate rock, Qatari and Saudi natural gas feedstock, and Belarusian potash contracts. Single-source phosphate dependence creates structural vulnerability for Sub-Saharan African blenders lacking alternative rock concentrate suppliers. Distribution runs through upgraded Lagos Lekki Deep Sea terminals and Dar es Salaam port infrastructure that enables direct vessel calls bypassing European transshipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where micronutrient customization and controlled-release coatings command widening premiums over commodity nitrogen. The demand shift toward precision-formulation specifications favors suppliers with agronomy-extension capabilities over bulk traders.
For Market Incumbents: Anticipate margin compression in standard urea as Egyptian subsidy reforms redirect procurement toward domestic blenders and digital aggregation platforms consolidate Nigerian smallholder demand. Defensive consolidation should prioritize backward integration into captive phosphate supply through long-term OCP Group concentrate offtakes, while channel control investments in farmer-facing procurement platforms protect volume access against emerging digital intermediaries. For New Entrants and Emerging Players: The price-point gap between premium polymer-coated formulations and economy bulk urea offers entry space for mid-tier compounders serving East African commercial farms. White-space targets concentrate in Ethiopia's hydroponic greenhouse clusters demanding liquid fertilizer customization and South Africa's carbon-border certification services for EU-bound ammonia shipments. A go-to-market angle anchored in site-specific soil testing and variable-rate prescription services bypasses legacy distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-agriculture specialists offering micronutrient customization and digital soil-mapping capabilities rather than commodity nitrogen producers facing feedstock volatility. Long-term viability over a multi-year horizon favors acquisition targets with integrated phosphate mining assets or established farmer-data platforms. The signal to watch is Egyptian subsidy reform trajectory, where accelerated smart-card phase-out would redirect procurement volumes and reshape regional pricing benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | OCP Group's Khouribga slurry pipeline infrastructure secures margin capture unavailable to import-dependent blenders. |
| Long-term Supply Agreement | SABIC Agri-Nutrients' captive natural gas contracts anchor cost competitiveness against European nitrogen exporters. |
| Joint Venture for Regional Blending | Dangote Group's Nigerian production capacity displaces historical import dependence for northern cereal belt procurement. |
| Green Manufacturing Transition | Carbon Border Adjustment Mechanism compliance services create revenue streams for certifying embedded ammonia emissions. |
| Platform Integration | Aggregated procurement platforms in Oyo and Kaduna states bypass legacy distributor networks through direct container contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fertilizer procurement managers at Egyptian agricultural cooperatives, Moroccan mining engineers at OCP Group beneficiation facilities, Kenyan commercial farm agronomists, and Nigerian digital platform operators with secondary validation. Secondary sources included customs and trade data from regional port authorities, Fertilizer Association of South Africa registration filings, SEC disclosures from listed agricultural chemical producers, and Ministry of Agriculture and Land Reclamation subsidy allocation records. Bottom-up volume modeling and top-down macroeconomic triangulation anchored market size estimates.
Historical reference periods spanning pre-subsidy-reform and post-infrastructure-upgrade phases established baseline consumption patterns across the projection horizon. Segmentation dimensions modeled encompassed nutrient chemistry tiers, application method differentiation, delivery mode logistics, and end-user procurement scale. CAGRs were derived from trend extrapolation adjusted for policy intervention timing and infrastructure completion schedules. Forecast inputs incorporated natural gas benchmark volatility scenarios and phosphate royalty policy adjustment trajectories.
Caveats apply where Egyptian subsidy reform acceleration, Moroccan mining royalty recalibration, or Gulf Cooperation Council feedstock contract renegotiations could materially shift the outlook. Forecasts reflect assumptions around infrastructure upgrade completion and digital platform adoption curves without certainty of execution timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Southeast Asia Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Potassium Thiosulfate Fertilizer Market