
 CBD Plant Nutrients Market | 2026-2036
CBD Plant Nutrients Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Plant Nutrients Market Intelligence
Modular nutrient kits that bundle vegetative base feeds with flowering-stage boosters is broadening buyer choice across the cultivation cycle. Advanced Nutrients leverages its pH-perfect technology to anchor premium positioning among hydroponic operators. FoxFarm Soil & Fertilizer Company competes through organic-certified formulations that dominate soil-based segments. General Hydroponics sustains R&D intensity in chelated mineral systems for controlled-environment agriculture.
CBD plant nutrients comprise formulated inputs delivering nitrogen, phosphorus, potassium, and micronutrients in bioavailable forms, with chelation using EDTA or humic acid carriers to maintain solubility across pH ranges from 5.5 to 6.5 for optimal root uptake in hemp cultivation. Liquid nutrients command the largest volume share among delivery methods due to dosing precision in automated irrigation systems, while micronutrient blends represent the fastest-expanding product type as cultivators target cannabinoid potency through targeted boron and manganese supplementation during flowering. Soil amendment applications retain stable demand from outdoor hemp operators transitioning from commodity row crops.
USDA organic certification requirements and state-level hemp cultivation licensing under the 2018 Farm Bill shape product formulation standards and channel access across the United States. EPA registration for foliar-applied micronutrients and state agriculture department testing protocols for heavy metal content constrain market entry for non-compliant suppliers. Stakeholders must monitor evolving FDA guidance on hemp-derived product labeling to anticipate downstream specification changes that will cascade into nutrient formulation requirements.
Market Dynamics
State-level hemp licensing frameworks under the 2018 Farm Bill are concentrating demand among commercial controlled-environment operators who require precision nutrition protocols tailored to cannabinoid-specific phenology stages.
Growth Catalysts
- USDA Organic Certification:The USDA organic seal commands price premiums in dispensary and wellness retail channels, pulling craft cultivators toward certified-input supply chains and reformulating base nutrient blends to exclude synthetic chelating agents.
- Controlled-Environment Agriculture:Indoor and greenhouse hemp operations in Colorado, Oregon, and California deploy automated fertigation systems that demand liquid nutrient formulations with precise EC and pH stability across dosing cycles.
- Dual-Use Hemp Licensing:State agriculture departments in Kentucky and New York are expanding fiber-and-CBD dual-crop permits, creating parallel demand streams for vegetative-stage nitrogen management and flowering-stage micronutrient loading.
Market Restraints
- Input Cost Volatility:Phosphate rock and potassium chloride prices fluctuate with energy markets, compressing margin on base NPK formulations and forcing reformulation toward lower-analysis blends.
- Regulatory Friction:EPA registration timelines for novel foliar micronutrients extend 18-24 months, blocking rapid product iteration for boron and manganese flowering boosters targeted at craft operators.
- Technical Limitation:EDTA chelation breaks down above pH 6.8 in hard water regions, requiring expensive humic acid substitutes or acid injection systems that raise capital barriers for small-scale cultivators.
Strategic Opportunities
- Soil Amendment Pivot:Outdoor hemp operators transitioning from commodity corn and soy in Kentucky and Tennessee represent underpenetrated demand for slow-release organic nitrogen and mycorrhizal inoculant bundles.
- Distribution Innovation:Direct-to-grower subscription models bypass traditional hydroponic retail channels, capturing recurring revenue through seasonal kit shipments aligned with phenological calendars.
- Technology Convergence:Integration of IoT soil sensors with cloud-based nutrient calculators enables real-time recipe adjustment, locking in supplier relationships through data-dependent platform stickiness.
Industry Challenges
- Formulation Chemistry Expertise Gap:The intersection of plant physiology, hydroponic system engineering, and regulatory compliance requires hybrid skill sets scarce in regional agriculture extension programs.
- Heavy Metal Testing Burden:State agriculture departments mandate batch-level testing for arsenic, cadmium, and lead, extending certification timelines and raising working capital requirements for inventory holding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Plant Nutrients Market |
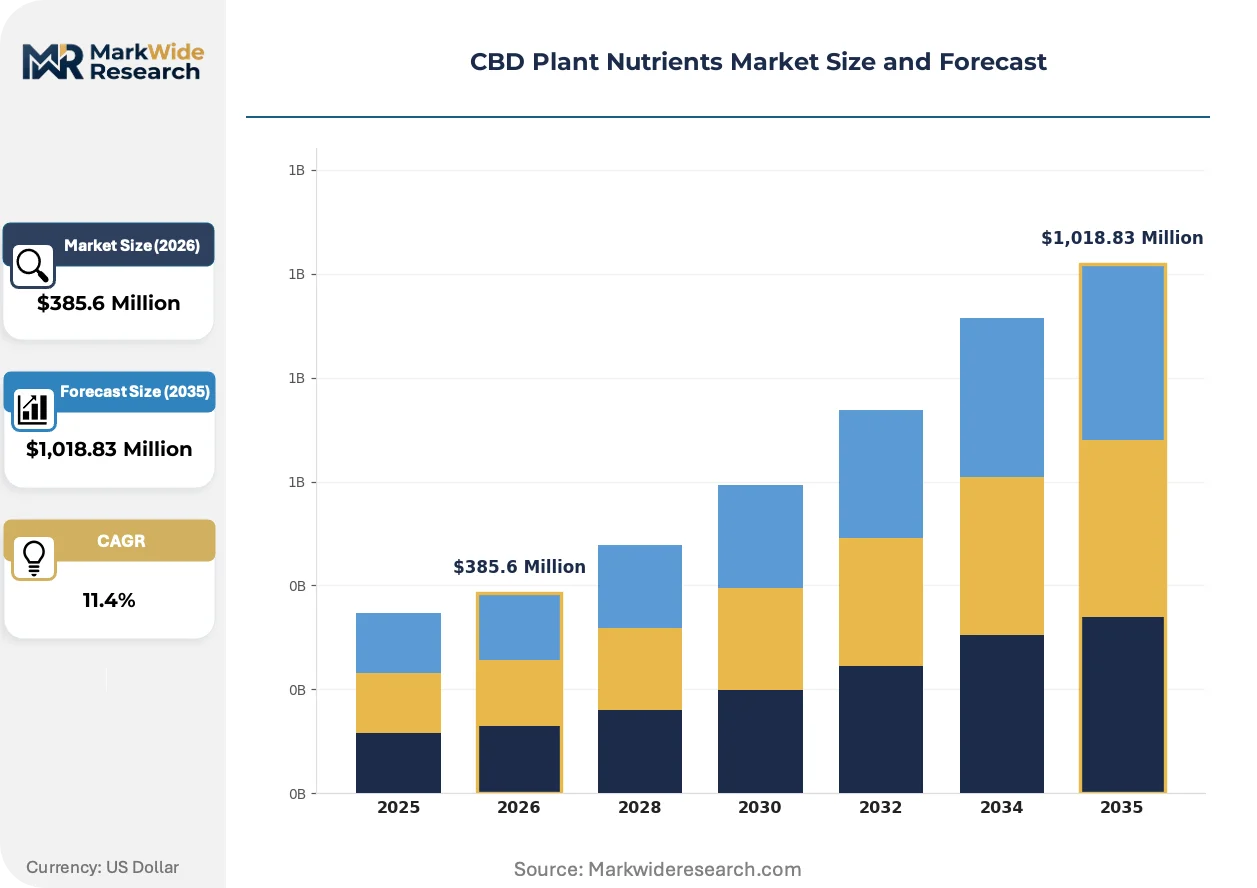
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen Fertilizers, Phosphorus Fertilizers, Potassium Fertilizers, Micronutrient Blends, Chelated Minerals Application: Seedling Growth, Vegetative Stage, Flowering Stage, Harvest Preparation, Soil Amendment Delivery Method: Liquid Nutrients, Granular Fertilizers, Slow Release Pellets, Foliar Sprays, Hydroponic Solutions End User: Commercial Growers, Indoor Cultivators, Greenhouse Operators, Research Institutions, Specialized Farmers |
| Companies Covered | Advanced Nutrients, General Hydroponics, FoxFarm Soil & Fertilizer Company, Botanicare, BioBizz, Green Planet Nutrients, EuroChem Group, Nutrien Ltd., The Mosaic Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Plant Nutrients Market Strategic Shifts & Innovations
Precision agriculture technologies and bioactive carrier systems are compressing the gap between commodity fertilizer inputs and crop-specific cannabinoid optimization protocols.
Biostimulant-infused nutrient carriers combining humic acid, seaweed extract, and beneficial bacterial consortia are decentralizing formulation expertise away from centralized chemical manufacturers toward regional blending operations with direct cultivator relationships. Mid-scale greenhouse operators in Oregon and Colorado adopt these systems fastest, drawn by reduced shipping costs and customizable micronutrient ratios. The technology is decentralizing supply chain power from multinational fertilizer conglomerates toward state-licensed compounding facilities.
EPA's evolving stance on hemp as a specialty crop under FIFRA is forcing registration pathway clarification for plant growth regulators and micronutrient foliars previously categorized under industrial hemp exemptions. Manufacturers now face bifurcated compliance costs between state-level hemp programs and federal pesticide registration tracks. The regulatory uncertainty most affects liquid flowering boosters containing plant hormone analogs, with Colorado Department of Agriculture issuing interim guidance ahead of federal rulemaking.
Craft cultivators are consolidating procurement through cooperative buying groups that aggregate volume across ten to twenty license holders, displacing individual account relationships with distributor sales representatives. These cooperatives negotiate direct manufacturer pricing and custom formulation runs previously reserved for thousand-gallon commercial accounts. The buying-pattern shift concentrates most visibly in California's Emerald Triangle, where legacy operators pool resources through county agricultural alliances.
CBD Plant Nutrients Market Segmentation
Nutrient formulation choices directly constrain cannabinoid yield consistency and regulatory compliance pathways. Segment boundaries in this market reflect capital deployment patterns across controlled-environment infrastructure and the technical sophistication of cultivation operations.
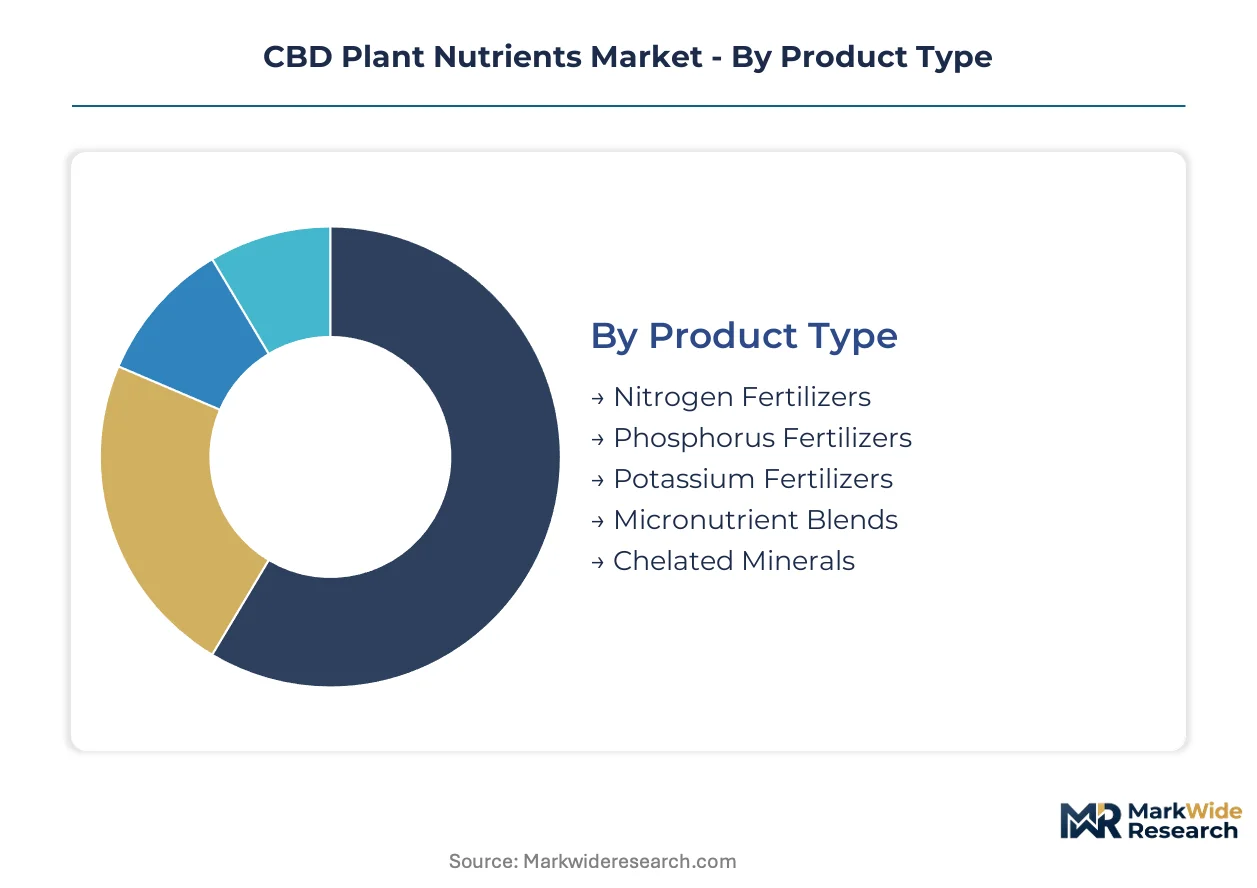
Product Type:
Capital intensity varies sharply across formulation categories, with chelation chemistry and micronutrient precision demanding specialized blending equipment.
- Micronutrient Blends:Boron, manganese, and zinc formulations target flowering-stage cannabinoid potency through targeted phenology protocols. Demand concentrates among craft operators in Colorado and California seeking USDA organic certification pathways that exclude synthetic chelating agents.
- Chelated Minerals:EDTA and humic acid carriers maintain mineral solubility across pH ranges from 5.5 to 6.5, enabling consistent root uptake in automated hydroponic systems. Kentucky and Tennessee outdoor operators transitioning from commodity row crops drive adoption of humic-based alternatives as hard water compatibility becomes critical.
- Nitrogen Fertilizers:Base vegetative formulations anchor input costs for commercial controlled-environment facilities.
- Phosphorus Fertilizers:Flowering-stage phosphorus loading protocols support resin gland development in high-CBD cultivars.
- Potassium Fertilizers:Stress-response and water regulation functions dominate late-stage application timing.
Most installed capacity flows through Nitrogen Fertilizers. Expansion is steepest in Micronutrient Blends.
Application:
Operational sequencing across phenology stages determines labor allocation and fertigation automation requirements.
- Flowering Stage:Micronutrient loading protocols during weeks 3-6 of bloom directly influence cannabinoid concentration profiles. Oregon greenhouse operators deploy precision boron supplementation to optimize CBDa synthesis rates.
- Vegetative Stage:Nitrogen management protocols establish biomass foundation for subsequent flowering performance. California's Emerald Triangle cultivators emphasize organic nitrogen sources to meet dispensary channel certification requirements.
- Seedling Growth:Reduced-EC formulations prevent root burn in propagation environments.
- Harvest Preparation:Flushing protocols remove residual mineral content prior to biomass processing.
- Soil Amendment:Slow-release organic inputs serve Kentucky and Tennessee outdoor operators transitioning from corn and soy rotations.
Revenue concentration sits with Flowering Stage applications. Technical innovation is accelerating fastest in Vegetative Stage nitrogen optimization.
Delivery Method:
Automation compatibility and dosing precision separate premium positioning from commodity alternatives.
- Liquid Nutrients:Automated fertigation systems in Colorado and California indoor facilities demand precise EC and pH stability across dosing cycles. pH-perfect technologies reduce manual monitoring labor while maintaining chelation integrity.
- Hydroponic Solutions:Recirculating deep water culture and nutrient film technique systems require mineral formulations with low precipitation risk. Oregon mid-scale greenhouse operators favor these systems for water use efficiency compliance.
- Granular Fertilizers:Mechanical spreading compatibility supports outdoor hemp acreage in Kentucky.
- Slow Release Pellets:Reduced application frequency appeals to labor-constrained operations.
- Foliar Sprays:Rapid micronutrient correction bypasses root uptake limitations during critical flowering windows.
Volume leadership belongs to Liquid Nutrients. Platform stickiness is building fastest around Hydroponic Solutions with integrated sensor calibration.
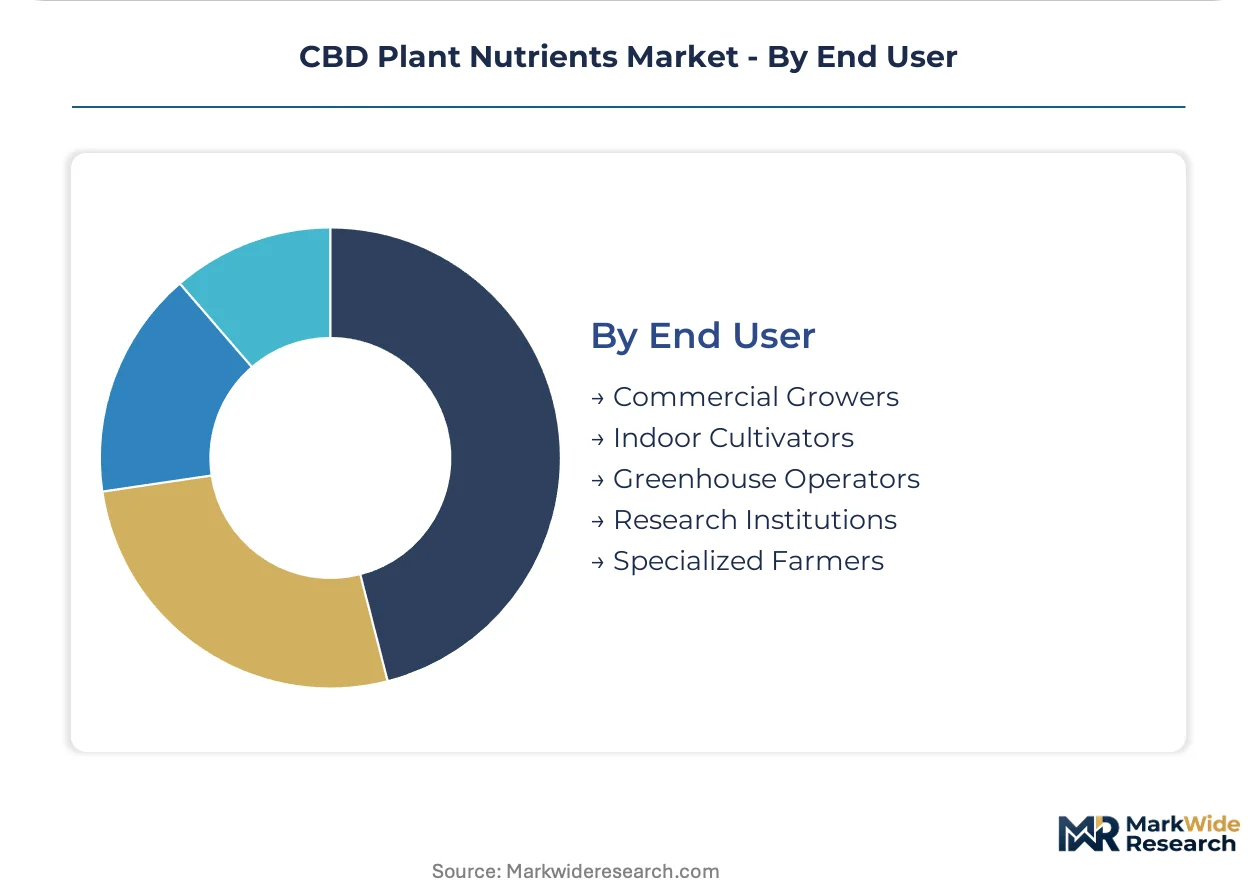
End User:
Scale thresholds and regulatory exposure create distinct procurement patterns across operator categories.
- Commercial Growers:State-licensed controlled-environment facilities in Colorado, Oregon, and California aggregate volume for direct manufacturer negotiations. Automated fertigation infrastructure demands consistent formulation quality and bulk logistics efficiency.
- Indoor Cultivators:Retrofitted warehouse operations prioritize space-efficient nutrient storage and pH stability in closed-loop systems. California's legacy operators in Humboldt and Mendocino counties drive demand for organic-certified input bundles.
- Greenhouse Operators:Hybrid climate control environments balance natural light supplementation with precision nutrition protocols.
- Research Institutions:University hemp programs in Kentucky and New York require analytical-grade formulations for controlled studies.
- Specialized Farmers:Fiber-and-CBD dual-crop permit holders manage divergent nutrient timing for stalk and flower harvests.
Procurement volume concentrates with Commercial Growers. Cooperative buying consolidation is advancing fastest among Indoor Cultivators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CBD plant nutrients industry traces its commercial origins to California's Emerald Triangle, where legacy cannabis cultivators pioneered precision hydroponic nutrition protocols during the medical marijuana era. These craft operators refined micronutrient timing for cannabinoid optimization, establishing formulation standards that subsequently migrated to state-licensed hemp programs following the 2018 Farm Bill.
United States
State-level hemp licensing frameworks concentrate demand among controlled-environment operators requiring precision nutrition protocols. The USDA organic certification pathway pulls craft cultivators toward certified-input supply chains, excluding synthetic chelating agents. Colorado's Front Range corridor anchors commercial greenhouse infrastructure, where automated fertigation systems demand liquid formulations with precise EC and pH stability.
Canada
Health Canada regulates hemp cultivation under the Cannabis Act, creating parallel compliance tracks for CBD and industrial fiber streams. Prairie provinces Manitoba and Saskatchewan host outdoor acreage transitioning from commodity grains toward dual-use hemp permits. British Columbia's Okanagan Valley clusters craft indoor operations sourcing organic-certified micronutrient blends from regional compounding facilities.
Germany
The EU's Novel Food regulation constrains CBD product placement, upstreaming formulation requirements into nutrient specification standards for compliant biomass. Bavaria's agricultural research stations pilot precision fertigation for greenhouse hemp under ECHA guidance on fertilizer product safety. North Rhine-Westphalia's chemical manufacturing base supplies chelated mineral formulations to Dutch and Danish greenhouse operators.
Netherlands
REACH compliance requirements shape chelation chemistry choices for exporters serving EU hemp programs. The Westland greenhouse cluster integrates Dutch horticultural automation expertise with cannabinoid-specific phenology protocols. Wageningen University research programs validate micronutrient loading schedules for high-CBD cultivars in controlled environments.
Australia
The TGA's down-scheduling of low-dose CBD products accelerates licensed cultivation expansion across Victoria and Queensland. State agriculture departments mandate heavy metal testing protocols that constrain imported nutrient sourcing. The Riverina region in New South Wales trials outdoor hemp rotations following rice and wheat, driving demand for slow-release organic nitrogen amendments.
CBD Plant Nutrients Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation sophistication and certification compliance. The vendor base stratifies into three tiers: multinational fertilizer conglomerates with mineral supply advantages, specialized hydroponic formulators with pH-stability IP, and regional organic-certified blenders with direct cultivator relationships. Consolidation pressure concentrates among mid-scale operators seeking scale economies in chelated mineral production. Competitive moves center on backward integration into humic acid sourcing and technology licensing for IoT-enabled dosing platforms.
Within the specialized hydroponic tier, Advanced Nutrients, General Hydroponics, and FoxFarm Soil & Fertilizer Company exemplify divergent positioning archetypes. Advanced Nutrients occupies the premium-technology position through pH-perfect formulation systems. General Hydroponics anchors the R&D-intensive segment with chelated mineral expertise. FoxFarm represents the organic-certified soil-based alternative. These three entities collectively illustrate how formulation philosophy—synthetic precision versus organic compliance—segments competitive territory.
| Leading Market Players |
|---|
| Advanced Nutrients |
| General Hydroponics |
| FoxFarm Soil & Fertilizer Company |
| Botanicare |
| BioBizz |
| Green Planet Nutrients |
| EuroChem Group |
| Nutrien Ltd. |
| The Mosaic Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap blenders in Oregon and Colorado anchor supply discipline through direct cultivator relationships that bypass distributor markups, compressing working capital cycles and enabling price premiums for organic-certified formulations. Their ownership structure insulates pricing from quarterly earnings pressure while concentrating procurement leverage over humic acid and seaweed extract suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pH-perfect synthetic formulations from organic-certified blends and commodity NPK bases. Price differentiation rests on USDA organic certification status and automated fertigation compatibility. Cost compression in economy-tier nitrogen fertilizers is intensifying because phosphate rock and potassium chloride feedstock volatility forces reformulation toward lower-analysis blends. Craft operators in California's Emerald Triangle exhibit lowest price sensitivity due to dispensary channel premiums, while Kentucky outdoor transition farmers from commodity row crops drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Denver, Portland, and Sacramento operate hub-and-spoke patterns that consolidate shipments to county-level agricultural alliances. Manufacturing concentrates in the United States, Canada, and the Netherlands, with chelated mineral expertise clustering around North Rhine-Westphalia's chemical base. Raw material dependencies draw from Moroccan phosphate rock, Canadian potash, and Indonesian seaweed extract. Single-source vulnerability in EDTA chelating agent supply creates exposure to pharmaceutical industry demand spikes. Distribution runs through direct-to-grower subscription channels that displace traditional hydroponic retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CBD plant nutrients market compounds steadily as state-level hemp licensing frameworks under the 2018 Farm Bill institutionalize recurring demand from controlled-environment operators.
For Market Incumbents: Deploy pH-stability IP licensing to lock in platform stickiness among automated fertigation operators. Defensive consolidation moves center on backward integration into humic acid sourcing and acquisition of regional organic-certified blenders. Threat from EPA registration timeline extensions for novel foliar micronutrients blocks rapid product iteration, favoring incumbents with existing compliant portfolios. For New Entrants and Emerging Players: Direct-to-grower subscription platforms offer the most penetrable route, bypassing established hydroponic retail channels. White-space targets include Kentucky and Tennessee outdoor operators transitioning from corn and soy, plus mid-scale greenhouse cooperatives in Oregon seeking customizable micronutrient ratios. Go-to-market angle emphasizes IoT sensor integration with cloud-based nutrient calculators. For Investors and Strategic Acquirers: Specialized hydroponic formulators with chelated mineral expertise are the most active acquirer in this space, consolidating regional organic-certified blenders to capture craft operator relationships. Long-term viability frames this as a 5-10 year regulatory compliance play where formulation chemistry expertise gaps create durable moats. Signal to watch: FDA guidance finalization on hemp-derived product labeling that cascades into nutrient specification changes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Humic Acid Sourcing | Captures supply security for organic-certified formulations serving Colorado craft operators. |
| IoT Sensor Platform Integration | Locks supplier relationships through data-dependent stickiness among California automated fertigation users. |
| USDA Organic Certification Investment | Opens dispensary channel premiums for Emerald Triangle cultivators seeking compliant input chains. |
| Direct-to-Grower Subscription Launch | Bypasses distributor markups while capturing recurring revenue aligned with phenological calendars. |
| Regional Compounding Facility Acquisition | Consolidates state-licensed blending capacity near Kentucky dual-crop permit holders. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with commercial greenhouse operations managers, state agriculture department licensing officials, organic certification auditors, and hydroponic retail channel buyers with secondary validation against USDA hemp program filings, state-level cultivation license databases, EPA pesticide registration records, and controlled-environment agriculture trade association reports. Bottom-up cultivation facility counts and top-down nutrient input cost models were triangulated to anchor volume estimates.
Segment-weighting applied product type, application stage, delivery method, and end-user scale dimensions across the modeling period. CAGRs were derived from installed base expansion in automated fertigation systems and penetration rates for micronutrient blends among craft operators. Industry-specific inputs included state licensing velocity under the 2018 Farm Bill and organic certification conversion timelines.
The model assumes a particular technology adoption path; alternative pathways for biostimulant-infused nutrient carriers would alter the outlook. Forecasts reflect assumptions about EPA registration clarity and FDA labeling guidance finalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Global Soil Wetting Agents Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market