
 Irrigation Pumps Market | 2026-2036
Irrigation Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Irrigation Pumps Market Outlook
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote monitoring platforms as hardware margins compress. Grundfos leverages its digital service ecosystem to capture recurring revenue from farm cooperatives. Xylem anchors its position through vertical integration into pump controls and variable frequency drives. Kirloskar Brothers Limited dominates India's replacement cycle with extensive rural distribution networks.
Irrigation pumps are electromechanical devices engineered to lift, pressurize, and distribute water for crop production, typically operating at flow rates from 5 to 500 cubic meters per hour and heads up to 300 meters depending on topography and crop requirements. Submersible pumps lead product type demand due to higher efficiency in deep-well extraction and lower surface footprint constraints. Solar power source installations represent the fastest-expanding segment as photovoltaic costs decline and rural electrification gaps persist. Fixed installation types retain the largest volume share in large-scale agricultural projects where permanent infrastructure justifies capital deployment.
The US Department of Energy enforces minimum efficiency standards under its pump energy conservation program, while India's Bureau of Indian Standards mandates ISI certification for agricultural pump sets to reduce electricity subsidies and groundwater overextraction. China's Ministry of Ecology and Environment monitors pump-related energy consumption under dual carbon goals, pressuring manufacturers toward higher-efficiency motor designs. Stakeholders must weigh solar-diesel hybrid configurations against grid-tied electric systems as tariff structures and carbon accounting rules continue diverging across major agricultural economies.
Market Dynamics
Submersible electric systems are virtualizing groundwater extraction infrastructure across the Indo-Gangetic Plain, compressing replacement cycles as India's Bureau of Indian Standards tightens motor efficiency norms and farm cooperatives demand predictive maintenance integration.
Growth Catalysts
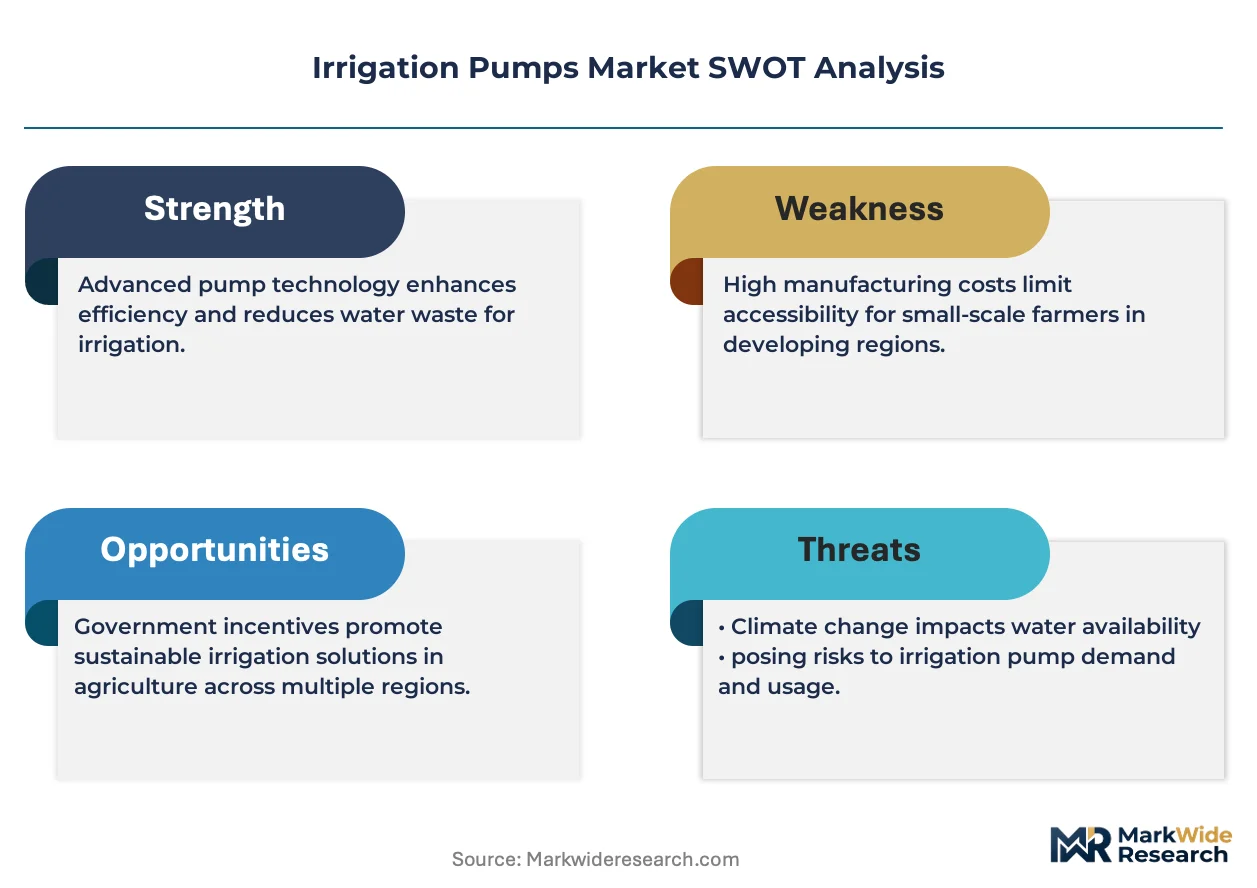
- India's BIS Efficiency Mandates:Tightened ISI certification for agricultural pump sets reduces electricity subsidies and accelerates replacement of legacy motor designs.
- Photovoltaic Cost Decline:Solar power source installations expand fastest where rural electrification gaps persist and diesel price volatility erodes operating margins.
- Deep-well Extraction Requirements:Submersible pumps capture demand in arid zones where surface footprint constraints and higher hydraulic efficiency justify capital deployment.
Market Restraints
- Copper and Rare Earth Input Volatility:Permanent magnet motor production depends on concentrated Chinese rare earth processing, exposing manufacturers to supply disruption.
- Groundwater Overextraction Regulations:India's Central Ground Water Authority restricts pump deployment in critical blocks, capping addressable market in Punjab and Haryana.
- Grid-tied Tariff Structure Divergence:Inconsistent agricultural electricity pricing across Indian states distorts total cost of ownership calculations for electric versus solar-diesel hybrid systems.
Strategic Opportunities
- Remote Monitoring Platform Integration:Grundfos and Xylem are virtualizing service delivery through digital ecosystems that capture recurring revenue from predictive maintenance contracts.
- African Electrification Gaps:Solar-powered submersible systems address irrigation needs in Nigeria and Kenya where grid extension lags agricultural mechanization timelines.
- Variable Frequency Drive Convergence:Pump-motor-VFD integration enables demand-responsive flow control, reducing energy consumption in large-scale canal-fed projects.
Industry Challenges
- Field Technician Shortage:Submersible pump installation and diagnostics require specialized electrical-mechanical skills scarce in rural distribution networks.
- Legacy Control System Integration:Smart pump controllers face interoperability friction with existing irrigation automation infrastructure in mature agricultural regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irrigation Pumps Market |
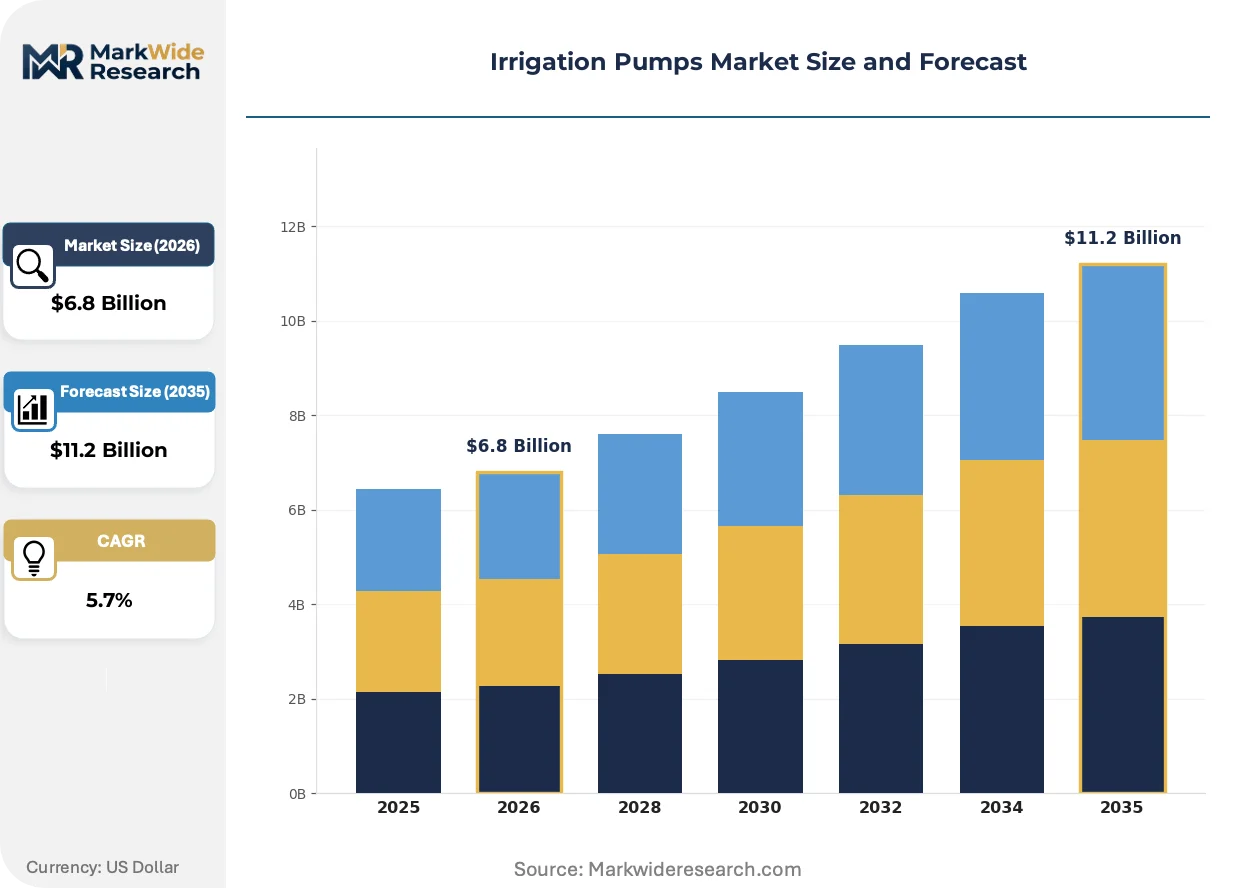
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Centrifugal, Positive Displacement, Diaphragm Application: Agricultural, Landscape, Industrial, Residential Power Source: Electric, Diesel, Solar, Gasoline Installation Type: Portable, Fixed, Subsurface, Surface |
| Companies Covered | Grundfos, Xylem, Flowserve Corporation, Franklin Electric, WILO SE, Sulzer Ltd, EBARA International Corporation, Kirloskar Brothers Limited, Davey Water, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irrigation Pumps Market Strategic Shifts
Digitalization is virtualizing hardware-centric business models across the irrigation pumps sector, compressing margins on standalone equipment while expanding addressable revenue through software-enabled service layers and energy optimization platforms.
Variable frequency drive integration is virtualizing fixed-speed pump operation, enabling real-time flow modulation based on soil moisture sensor feedback. Large-scale farm cooperatives in California's Central Valley and Australia's Murray-Darling Basin are retrofitting existing installations with VFD-controlled submersible systems. This technology is virtualizing traditional throttle-valve energy waste, cutting electricity consumption by enabling precise hydraulic matching to crop growth stages.
China's Ministry of Ecology and Environment enforces pump-related energy consumption monitoring under dual carbon goals, pressuring domestic manufacturers toward IE4 and IE5 motor efficiency classes. The regulation compresses export competitiveness of lower-tier Chinese producers. European OEMs sourcing from Chinese motor suppliers now require third-party efficiency verification, adding compliance cost layers to supply contracts.
Aftermarket service unbundling is fragmenting traditional equipment-plus-maintenance bundles into discrete predictive monitoring subscriptions and on-demand repair networks. Farm cooperatives in India's Maharashtra and Gujarat states now procure pump hardware through rural distribution while sourcing diagnostics through cellular-enabled remote monitoring platforms. This bifurcation is most visible where electricity subsidy reform creates pressure for verifiable energy consumption data.
Irrigation Pumps Market Segmentation
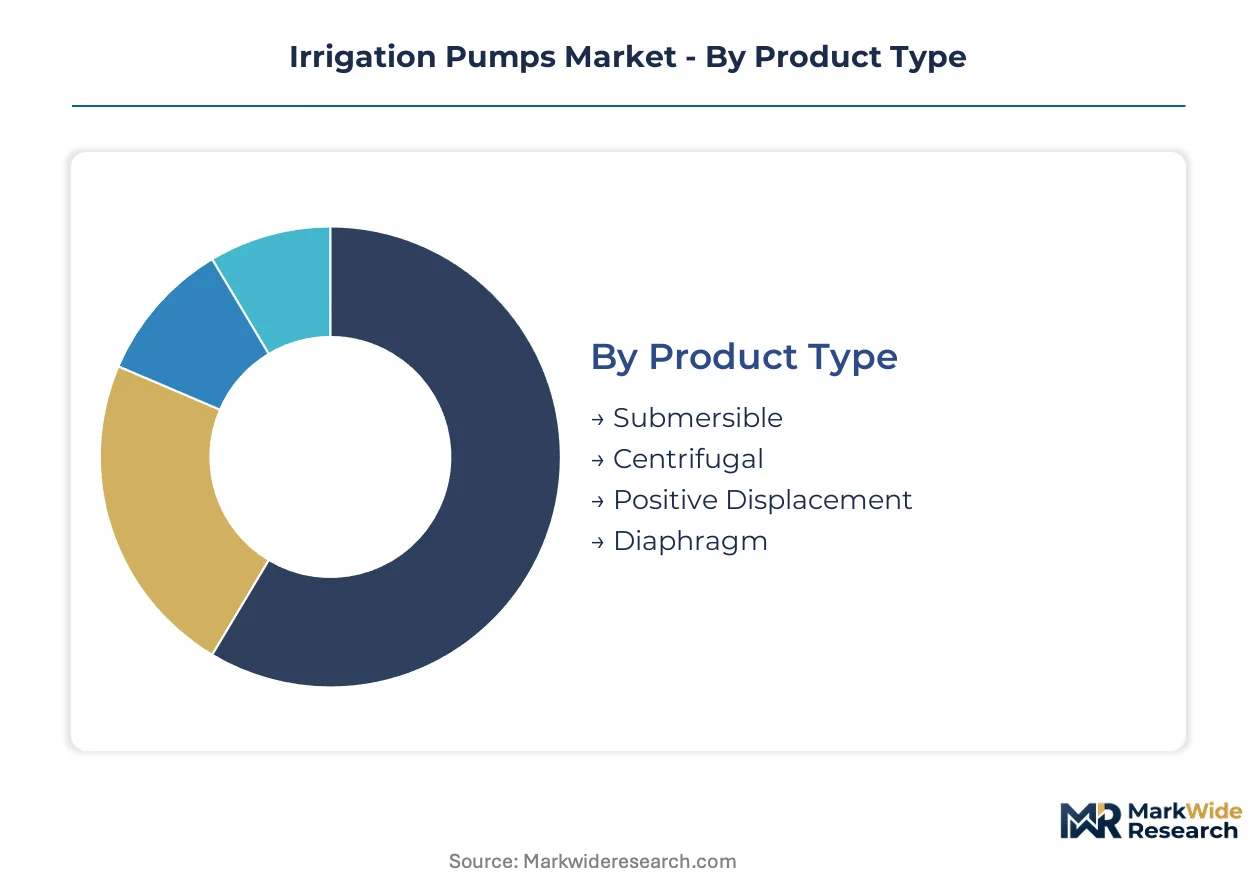
Irrigation pump procurement decisions diverge sharply across deployment contexts. Deep-well extraction demands submersible efficiency. Grid-connected farms prioritize electric reliability. Off-grid operations weigh solar capital against diesel volatility. Each dimension reshapes vendor positioning and margin structure.
Product Type:
Cost tier differentiation separates capital-intensive submersible systems from accessible surface alternatives. Permanent infrastructure investments concentrate in deep aquifer regions.
- Submersible:Motor-and-pump assemblies operate fully immersed, eliminating suction lift limitations and surface footprint constraints. Arid zone cooperatives in Rajasthan and Gujarat prioritize these for borewell depths exceeding 100 meters where hydraulic efficiency determines operating economics.
- Centrifugal:Impeller-driven systems generate moderate pressure through rotational energy transfer, dominating canal-fed surface irrigation networks. India's Indo-Gangetic Plain replacement cycles concentrate here as BIS efficiency mandates accelerate motor upgrades.
- Positive Displacement:Reciprocating or rotary mechanisms deliver precise flow volumes against high backpressure. Industrial greenhouse operations and fertigation systems specify these for chemical compatibility and metering accuracy.
- Diaphragm:Flexible membrane separation isolates pumped fluid from mechanical components, suiting low-flow chemical dosing and abrasive water sources. Smallholder drip irrigation in Kenya and Nigeria deploys these for solar-powered micro-systems.
Submersible systems command the established base. The steepest expansion runs through centrifugal replacements tied to efficiency regulation.
Application:
Customer type determines specification rigor and procurement channel. Agricultural buyers prioritize total cost of ownership. Landscape and residential segments emphasize plug-and-play simplicity.
- Agricultural:Large-scale mechanized irrigation demands flow rates from 50 to 500 cubic meters per hour, with head requirements scaling to topography. California's Central Valley and Australia's Murray-Darling Basin cooperatives drive VFD retrofit demand for energy optimization.
- Landscape:Golf courses, municipal parks, and commercial grounds require intermittent operation with aesthetic noise constraints. Texas Hill Country and Florida retirement communities specify these for reclaimed water distribution.
- Industrial:Cooling towers, dust suppression, and process water recycling impose continuous-duty cycles with corrosion-resistant metallurgy. Mining operations in Chile's Atacama and Western Australia's Pilbara specify hardened configurations.
- Residential:Domestic wells and garden irrigation operate at fractional agricultural scale, prioritizing compact footprint and single-phase electrical compatibility. Suburban expansion in Arizona and Nevada sustains replacement demand.
Agricultural applications anchor volume concentration. Landscape and residential segments gain share fastest through amenity irrigation expansion.
Power Source:
Volume distribution reflects electrification infrastructure maturity and fuel price volatility exposure. Grid reliability and tariff structure determine electric system economics.
- Electric:Grid-tied induction and permanent magnet motors dominate established agricultural regions with stable supply. India's subsidized agricultural tariffs and China's dual carbon monitoring accelerate IE4 and IE5 efficiency class adoption.
- Diesel:Compression-ignition engines retain relevance where grid extension lags or backup redundancy matters. Nigerian and Ethiopian commercial farms specify these for dry-season reliability despite fuel price volatility.
- Solar:Photovoltaic-powered DC or AC submersible systems eliminate fuel logistics and grid dependency. East African smallholders and Indian PM-KUSUM beneficiaries drive steepest adoption curves as module costs decline.
- Gasoline:Portable two-stroke or four-stroke engines serve emergency dewatering and temporary irrigation. Southeast Asian rice paddy preparation and Bangladesh flood recession agriculture sustain niche demand.
Electric systems retain volume leadership. Solar configurations expand most quickly across electrification-deficient regions.
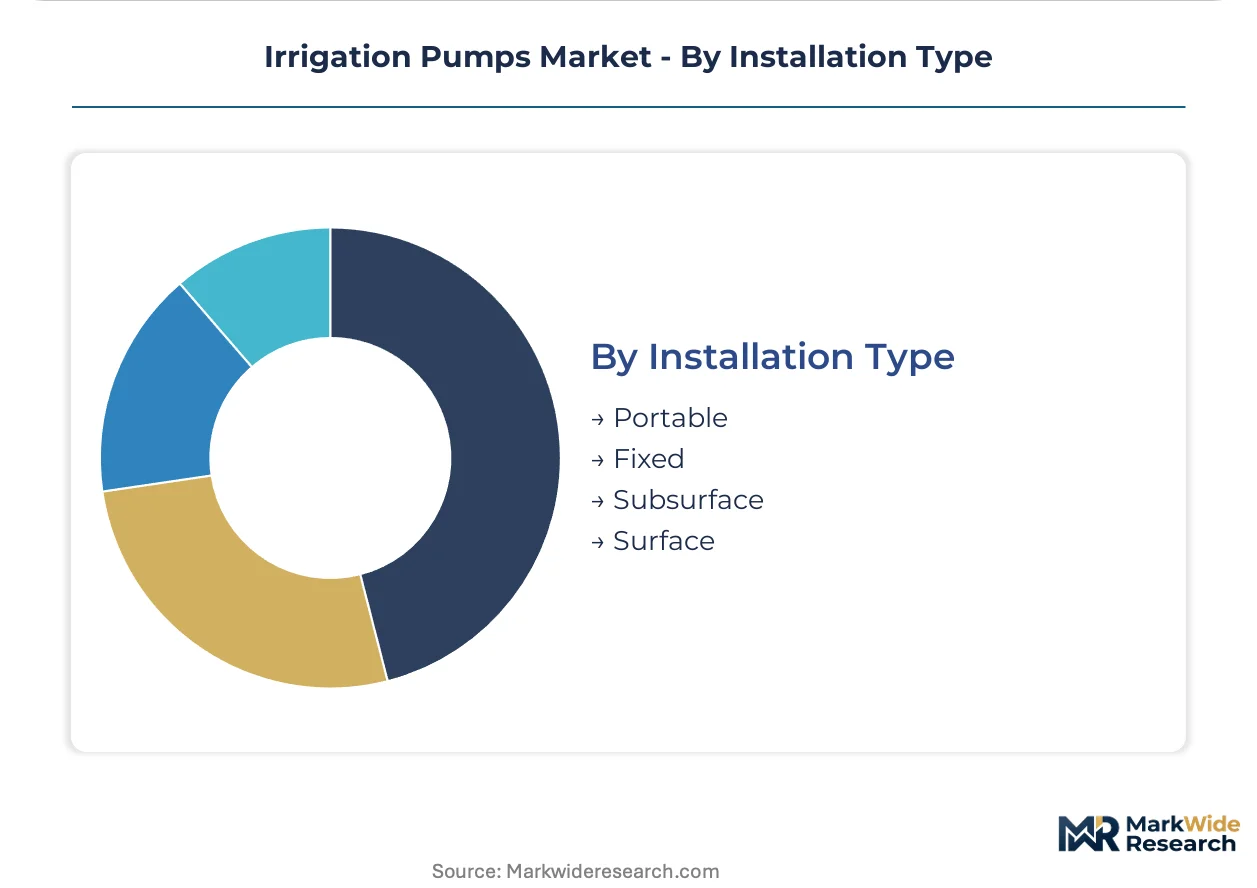
Installation Type:
Margin structure varies with mobility requirements and foundation complexity. Permanent installations justify control system integration. Portable units compete on acquisition cost.
- Portable:Trailer-mounted or skid-based systems relocate between fields and water sources. Australian dryland grain operations and Brazilian soybean expansion zones specify these for seasonal water access.
- Fixed:Permanent concrete foundations and dedicated electrical infrastructure maximize efficiency and automation integration. Large-scale Indian canal projects and US Bureau of Reclamation contracts standardize these configurations.
- Subsurface:Buried discharge lines and wellhead assemblies minimize surface disruption and theft exposure. Israeli kibbutzim and Saudi Arabian pivot irrigation deploy these for security and climate protection.
- Surface:Above-ground suction and discharge piping simplifies maintenance access and relocation. Vietnamese Mekong Delta rice intensification and Indonesian palm oil nurseries favor these for flood-prone terrain.
Fixed installations dominate capital deployment. Portable systems climb fastest where land tenure uncertainty or seasonal water access prevails.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for irrigation pumps concentrates in China, Denmark, and Germany, with final assembly gravitating toward proximity to agricultural demand centers. Component sourcing for high-efficiency motors and variable frequency drives clusters in East Asia and Western Europe. Installation and service networks expand fastest where groundwater extraction intensifies and rural electrification programs accelerate mechanized irrigation.
United States
California's Central Valley and the High Plains Aquifer region drive submersible pump demand for deep-well extraction in drought-stressed watersheds. The Department of Energy enforces minimum efficiency standards under its pump energy conservation program, tightening compliance costs for legacy motor designs. Nebraska's Platte River Valley and Texas's Panhandle concentrate large-scale cooperative procurement of VFD-retrofitted systems.
India
The Indo-Gangetic Plain replacement cycle accelerates as farm cooperatives expand mechanized coverage and electricity subsidy reform pressures verifiable energy consumption. The Bureau of Indian Standards mandates ISI certification for agricultural pump sets, phasing out inefficient motor designs. Punjab and Haryana face deployment restrictions from the Central Ground Water Authority in critical blocks, capping addressable market expansion.
China
The Ministry of Ecology and Environment monitors pump-related energy consumption under dual carbon goals, pressuring domestic manufacturers toward IE4 and IE5 motor efficiency classes. Shandong and Jiangsu provinces anchor production clusters for permanent magnet motor components. The North China Plain concentrates demand for grid-tied electric systems where agricultural electrification infrastructure matures.
Germany
Rhineland-Palatinate and Bavaria host precision engineering clusters for high-efficiency pump-motor integration and smart control systems. The EU Green Deal and F-Gas Regulation shape energy efficiency mandates for agricultural equipment imports. German OEMs source motor components from Chinese suppliers with third-party efficiency verification requirements adding compliance cost layers.
Brazil
The Cerrado expansion zone and southern soybean belt drive portable pump demand where seasonal water access and land tenure uncertainty favor mobile infrastructure. ANVISA regulates equipment safety standards for agricultural machinery importation. Mato Grosso and Rio Grande do Sul concentrate large-scale farm cooperative procurement of diesel-electric hybrid systems for dry-season reliability.
Irrigation Pumps Market Competitive Environment
Full-line system integrators and specialized component suppliers split the market between bundled solutions and modular procurement paths. The vendor base stratifies across three tiers: premium OEMs with captive digital service ecosystems, mid-tier regional fabricators with distribution density advantages, and value-oriented assemblers competing on acquisition cost. Consolidation pressure runs through predictive maintenance platform acquisition and backward integration into motor manufacturing. Geographic expansion into African electrification-deficient markets and strategic partnerships for solar-diesel hybrid system development represent dominant competitive vectors.
Within the premium OEM tier, Grundfos anchors Danish pump engineering heritage through its digital service ecosystem, while Xylem occupies a position exemplifying North American water technology integration. Kirloskar Brothers Limited represents the regional fabricator archetype with extensive Indian rural distribution networks. These three companies illustrate the strategic divergence between software-enabled recurring revenue capture and hardware-margin defense through channel density.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| Flowserve Corporation |
| Franklin Electric |
| WILO SE |
| Sulzer Ltd |
| EBARA International Corporation |
| Kirloskar Brothers Limited |
| Davey Water |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu provinces anchor permanent magnet motor production clusters, concentrating upstream capacity for high-efficiency pump assemblies. This geographic concentration grants component suppliers pricing leverage over downstream OEMs, while India's Bureau of Indian Standards efficiency mandates compress margins on legacy motor designs and accelerate pass-through cost pressures.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now drive lifetime value capture as hardware margins compress across standard pump configurations. Three-tier pricing structure across premium, standard, and economy levels separates IE5-certified permanent magnet systems from IE3 induction motors and unbranded replacement units. Pricing pressure stems from photovoltaic module cost declines that enable solar-powered alternatives to undercut grid-tied electric systems on total cost of ownership. Smallholder cooperatives in East Africa exhibit highest price sensitivity, while large-scale canal-fed projects in Australia and California prioritize energy efficiency over acquisition cost.
Supply Chain Analysis
Copper winding wire and rare earth permanent magnets feed from concentrated Chinese processing facilities, exposing manufacturers to commodity volatility and export restriction risk. Component sourcing clusters in China, Denmark, and Germany, with final assembly gravitating toward proximity to Indo-Gangetic Plain and North China Plain demand centers. Single-source vulnerability concentrates in neodymium magnet supply from Chinese rare earth refiners. Distribution runs through rural dealership networks in India, OEM-direct channels in North America, and government procurement frameworks in African electrification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-powered submersible systems represent early-cycle expansion as rural electrification gaps and declining photovoltaic costs converge to displace diesel alternatives across Sub-Saharan Africa and South Asia.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into variable frequency drive manufacturing and predictive maintenance platform development. Grundfos-style digital service ecosystems defend against hardware margin erosion from Chinese value-oriented assemblers. Captive control over motor-controller integration preserves specification authority in efficiency-regulated procurement channels.
For New Entrants and Emerging Players: Pursue white-space opportunity in Nigerian and Kenyan solar-powered submersible segments where grid extension lags agricultural mechanization timelines. Portable pump configurations for Brazilian Cerrado seasonal water access offer penetrable entry points against fixed-installation incumbents. Partnership with rural microfinance institutions enables pay-as-you-go distribution models unreachable by established OEM credit terms.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because predictive maintenance platform adoption transforms capital equipment into subscription-based service relationships. Acquisition targets cluster around regional fabricators with dense Indian rural distribution and cellular-enabled remote monitoring capabilities. Watch for inflection in India's electricity subsidy reform pace, which accelerates verifiable energy consumption data demand and smart controller penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VFD Manufacturing | Captures margin from pump-motor-controller convergence demanded by Australia's Murray-Darling Basin cooperatives. |
| Predictive Maintenance Platform Acquisition | Replicates Grundfos digital service ecosystem for recurring revenue from Indian farm cooperative procurement. |
| Solar-Diesel Hybrid System Development | Addresses Nigerian dry-season reliability requirements while positioning for photovoltaic cost decline tailwinds. |
| Rural Distribution Network Expansion | Mirrors Kirloskar Brothers Limited channel density for India's BIS-mandated replacement cycle capture. |
| IE5 Motor Efficiency Certification Investment | Secures eligibility for China's dual carbon-monitored procurement and European Green Deal-compliant export channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, Bureau of Indian Standards certification registries, and agricultural electrification program disclosures. Interviews with pump OEM procurement directors, Indian rural dealership operators, East African farm cooperative managers, and utility planning officers informed demand-side validation. Top-down triangulation against customs export flows and bottom-up build from state-level agricultural pump subsidy disbursements cross-checked volume estimates.
Forecast inputs span product type segmentation by submersible, centrifugal, positive displacement, and diaphragm configurations; power source splits across electric, diesel, solar, and gasoline; and installation type differentiation between portable, fixed, subsurface, and surface deployments. CAGRs derive from regression against agricultural mechanization indices, groundwater extraction licensing trajectories, and photovoltaic cost decline curves. Modeled variables include India's BIS efficiency mandate compliance timelines and China's dual carbon monitoring enforcement intensity.
Sensitivities concentrate around rare earth export restriction severity, Indian electricity subsidy reform pace, and African rural electrification program funding continuity. Cross-checking against International Energy Agency agricultural energy consumption benchmarks and national groundwater extraction licensing data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Farm Equipment and Irrigations
Hose Reel Irrigation Machine Market
Farm Equipment and Irrigations
Tractor Rental Market
Farm Equipment and Irrigations
Asia Pacific Irrigation Valves Market
Farm Equipment and Irrigations
Irrigation Controllers Market
Farm Equipment and Irrigations
Zero Turn Mowers Market
Farm Equipment and Irrigations
Golf Irrigation Market
Farm Equipment and Irrigations
Global Center Pivot Irrigation Systems Market
Farm Equipment and Irrigations
Europe Irrigation Valves Market
Farm Equipment and Irrigations
Ride-On Mower Market
Farm Equipment and Irrigations
Global Irrigation Automation Market
Farm Equipment and Irrigations
Soaker Hose Irrigation System Market
Farm Equipment and Irrigations
Drip Irrigation Market
Farm Equipment and Irrigations
Grass Trimmer Market
Farm Equipment and Irrigations
Rain Barrels Market
Farm Equipment and Irrigations
Agriculture Logistics Market
Farm Equipment and Irrigations
Brazil Agricultural Irrigation Machinery Market